
 Global Bio-Based PET Market | 2026-2036
Global Bio-Based PET Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bio-Based PET Market Foresight
Conventional fossil-derived PET is pivoting toward bio-ethylene integration as MEG feedstock costs realign with sugarcane and corn starch economics. Indorama Ventures leverages integrated PTA-Bio-PET complexes across Thai and Brazilian sites to anchor regional supply. Toyota Tsusho competes through offtake partnerships with Brazilian ethanol refiners, securing upstream bio-ethylene access. Braskem specializes in I'm green polyethylene bridging, extending polymer expertise into adjacent bio-based polyester development.
Bio-based polyethylene terephthalate substitutes petroleum-derived terephthalic acid with plant-sourced monoethylene glycol while retaining identical molecular weight and crystallinity for existing blow-molding equipment. The material serves primarily to decarbonize rigid packaging and synthetic textile supply chains without retrofitting downstream machinery. High-Viscosity PET dominates beverage container applications where intrinsic viscosity above 0.80 dL/g ensures carbonation retention and mechanical durability. Food Packaging trails as the fastest-growing application segment, driven by EU single-use plastic directives and retailer sustainability mandates requiring demonstrable bio-content thresholds. Modified PET variants incorporating comonomers like isophthalic acid occupy premium automotive and electronics niches where dimensional stability under thermal cycling commands price premiums.
The EU Green Deal and REACH bio-based content verification frameworks compel suppliers to demonstrate mass-balance chain of custody through certified feedstock accounting. FDA food-contact notifications and Japan's METI bioplastics labeling guidelines shape market access requirements for bottle-grade and film-grade resins respectively. Stakeholders must monitor feedstock crop yield volatility and polymerization catalyst efficiency gains to calibrate capacity commitments against offtake contract structures.
Market Dynamics
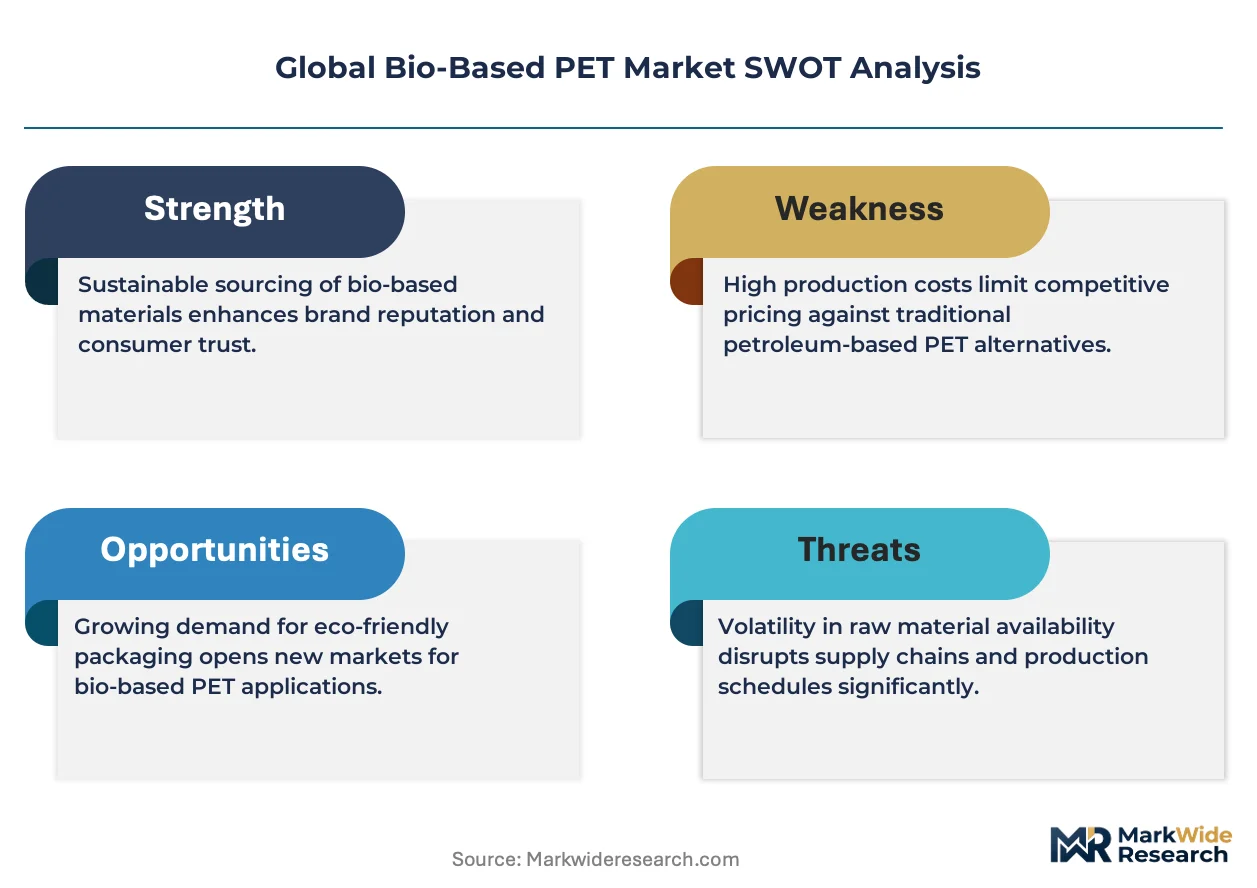
Mass-balance certification requirements under EU REACH and Japan's METI bioplastics labeling frameworks are forcing feedstock accounting transparency through every polymerization stage, compressing margins for non-integrated converters while rewarding captive bio-ethylene producers.
Growth Catalysts
- EU Green Deal packaging directives:Mandatory bio-content thresholds for single-use containers are pulling bottle-grade resin through German and French beverage bottling corridors.
- Sugarcane ethanol economics:Brazilian bio-ethylene feedstock costs have realigned with fossil MEG pricing, enabling cost-parity production of plant-sourced monoethylene glycol.
- Textile cluster demand:East Asian synthetic fiber manufacturers are scaling procurement of certified bio-PET chip to meet retailer sustainability mandates.
Market Restraints
- Feedstock crop volatility:Sugarcane yield fluctuations in São Paulo state and corn starch price swings across the US Midwest directly compress polymerization margins.
- Catalyst efficiency limitations:Current titanium-based polymerization catalysts achieve lower throughput with bio-ethylene feedstock versus fossil-derived equivalents, constraining nameplate capacity utilization.
- PTA supply concentration:Purified terephthalic acid remains petroleum-derived, creating a 70% fossil dependency floor that limits total bio-content claims.
Strategic Opportunities
- Indian packaging conversion:The country's FSSAI food-contact notification pathway and DGFT import tariff structures favor early movers establishing bottle-grade resin compounding.
- Automotive modified PET:Comonomer-incorporated variants with isophthalic acid are penetrating thermal management applications in electric vehicle battery housings.
- Blockchain feedstock tracking:Distributed ledger verification is emerging as a channel innovation to document mass-balance chain of custody for EU customs clearance.
Industry Challenges
- Certification timeline compression:REACH bio-based content verification and FDA food-contact notification cycles now exceed 18 months, delaying commercial offtake execution.
- Polymerization scale-up capex:Continuous solid-state polymerization lines for high-intrinsic-viscosity resin require capital commitments that strain mid-cap balance sheets.
- Legacy equipment compatibility:Existing blow-molding machinery tolerances vary across Thai, Brazilian, and German installed bases, complicating resin specification standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bio-Based PET Market |
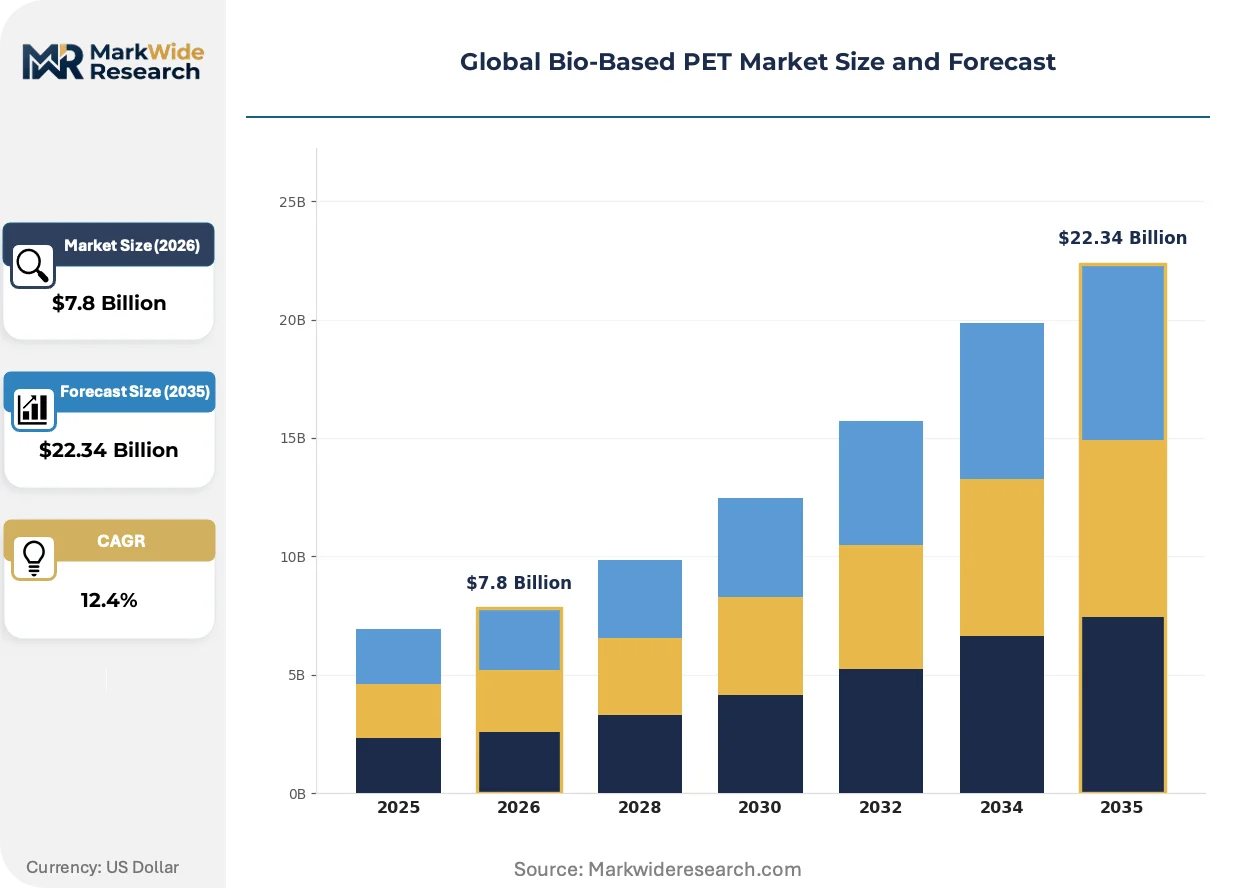
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $22.34 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Viscosity PET, Low-Viscosity PET, Modified PET, Blended PET, Copolymer PET Application: Beverage Containers, Food Packaging, Textile Fibers, Automotive Components, Consumer Electronics Housing End User: Beverage Manufacturers, Textile Producers, Automotive Suppliers, Electronics Assemblers, Packaging Companies Manufacturing Stage: Polymer Synthesis, Pelletizing, Film Extrusion, Bottle Molding, Fiber Spinning |
| Companies Covered | Indorama Ventures Public Company Limited, Toyota Tsusho Corporation, Toray Industries Inc., Teijin Limited, Braskem, Plastipak Holdings Inc., NatureWorks LLC, M&G Chemicals, Gevo Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bio-Based PET Market Shifts & Advancements
Bio-based PET technology trajectories are converging on feedstock diversification and certification automation, with polymer producers racing to secure upstream ethanol offtake while downstream buyers demand granular carbon accounting.
Enzymatic depolymerization is expanding into closed-loop recycling streams for post-consumer bottle flake. European textile brands are adopting this technology to achieve circularity claims without virgin fossil input. The process is compressing reliance on mechanical recycling infrastructure by enabling molecular-level purification of contaminated feedstock.
Japan's METI bioplastics labeling guidelines now mandate third-party verification of biomass carbon ratios for film-grade resins entering consumer packaging. This policy shift is forcing Japanese converters to segregate production lines and maintain batch-level documentation. Food packaging applications are responding by consolidating procurement around pre-certified resin suppliers.
Retailer sustainability scorecards are reshaping procurement patterns across North American beverage bottling corridors. Major retail chains now require documented bio-content percentages exceeding 30% for private-label water and soft drink containers. This specification is visible most acutely in California and New York state procurement contracts, where compliance deadlines compress supplier qualification windows to under 12 months.
Global Bio-Based PET Market Segmentation
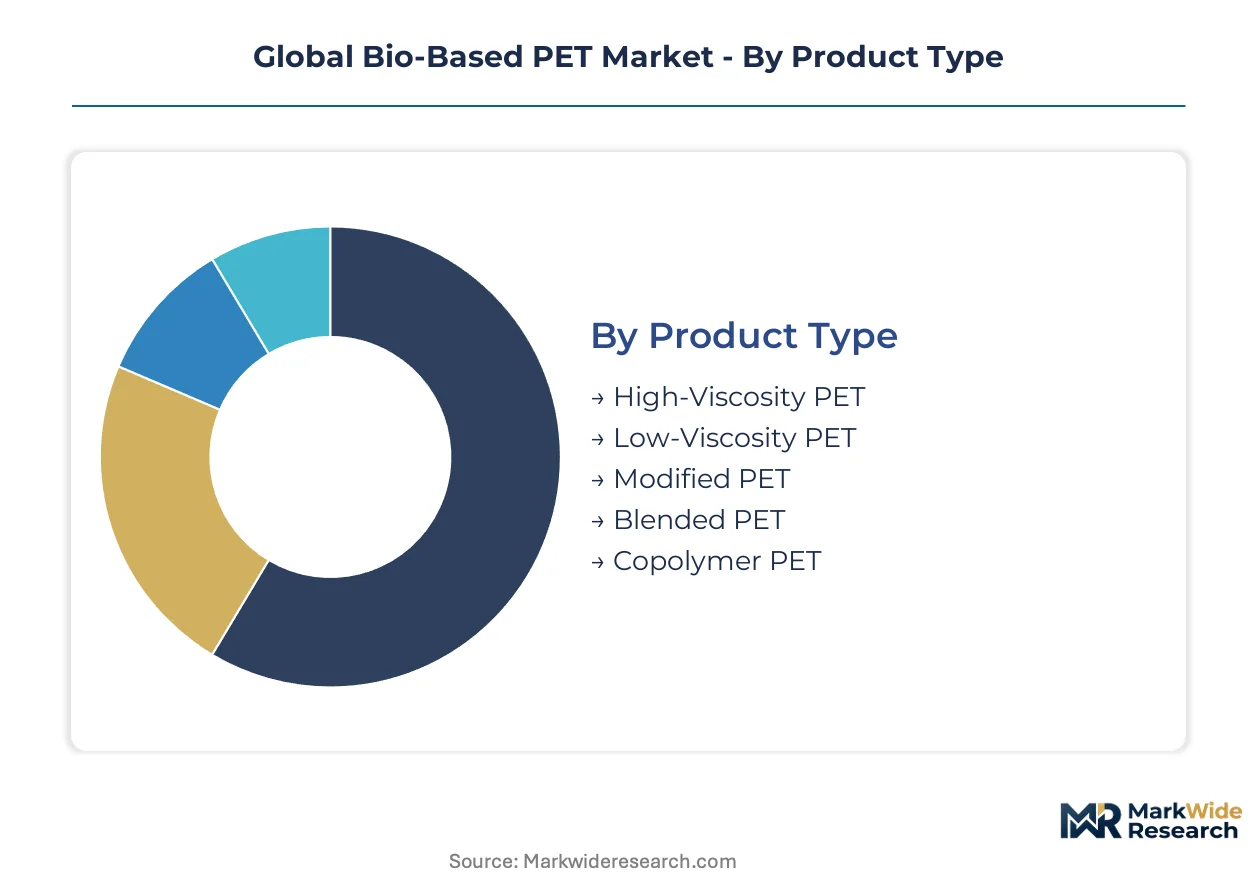
Bio-based PET segmentation tracks viscosity grades, conversion pathways, and end-use specifications that determine equipment compatibility and certification requirements. Technical differentiation across these axes dictates procurement patterns and margin structures for resin suppliers and converters alike.
Product Type:
Viscosity and molecular architecture define processing windows and end-use eligibility for bio-based PET resins.
- High-Viscosity PET:Intrinsic viscosity exceeds 0.80 dL/g through extended solid-state polymerization, delivering carbonation retention for beverage containers in Germany and Brazil. EU Green Deal packaging directives are pulling this grade through certified bottling corridors.
- Modified PET:Isophthalic acid or cyclohexane dimethanol comonomers disrupt crystallinity for thermal cycling resistance in electric vehicle battery housings. Automotive suppliers in Japan and South Korea are qualifying these grades under METI bioplastics labeling frameworks.
- Low-Viscosity PET:Faster injection molding cycles suit thin-wall food trays and disposable containers where barrier requirements are modest.
- Blended PET:Mechanical mixtures with recycled flake or other biopolymers balance cost and sustainability claims for non-food packaging.
- Copolymer PET:Random copolymerization with diethylene glycol improves clarity and processability for premium cosmetic bottles.
High-Viscosity PET leads on scale; Modified PET leads on momentum.
Application:
End-use specifications cascade from barrier requirements, thermal stability needs, and regulatory contact approvals.
- Food Packaging:Single-use trays, films, and containers require FDA food-contact notifications and EU REACH bio-based content verification. Retailer sustainability mandates in California and New York are compressing supplier qualification windows below 12 months.
- Beverage Containers:Bottle-grade resin demands mass-balance chain of custody documentation for EU customs clearance. German and French bottling corridors are scaling procurement as bio-content thresholds harden under packaging waste directives.
- Textile Fibers:Synthetic fiber manufacturers in East Asian clusters are securing certified bio-PET chip to meet brand sustainability scorecards.
- Automotive Components:Under-hood applications specify dimensional stability across thermal cycling ranges.
- Consumer Electronics Housing:Flame-retardant grades with UL94 ratings serve laptop and smartphone chassis markets.
Beverage Containers dominate volume; Food Packaging climbs the fastest.
End User:
Procurement sophistication varies from commodity resin tenders to co-development partnerships with certified feedstock guarantees.
- Beverage Manufacturers:Coca-Cola system bottlers and private-label water producers specify 30%+ bio-content minimums. Their procurement teams audit mass-balance documentation through every polymerization stage.
- Textile Producers:East Asian synthetic fiber mills are consolidating procurement around pre-certified resin suppliers to satisfy retailer sustainability mandates.
- Automotive Suppliers:Tier-1 thermal management component manufacturers qualify modified PET grades for electric vehicle platforms.
- Electronics Assemblers:OEMs and contract manufacturers specify flame-retardant grades with documented carbon footprints.
- Packaging Companies:converters balance equipment compatibility across legacy blow-molding machinery tolerances in Thai, Brazilian, and German installed bases.
Beverage Manufacturers anchor demand scale; Textile Producers are gaining share fastest.
Manufacturing Stage:
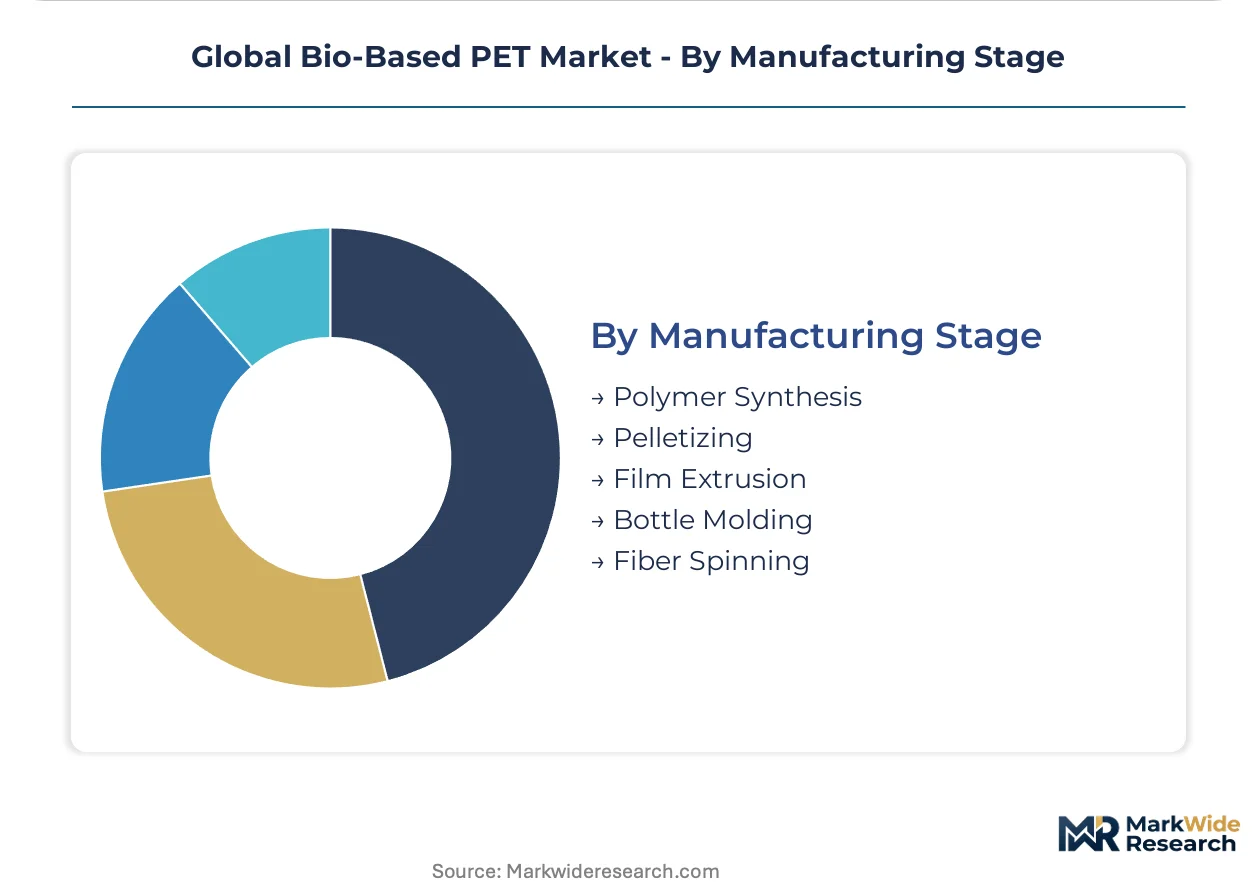
Each conversion step imposes distinct capital intensity and certification requirements on bio-based PET value chains.
- Polymer Synthesis:Continuous melt-phase polymerization with titanium-based catalysts achieves lower throughput with bio-ethylene feedstock versus fossil equivalents, constraining nameplate capacity utilization at integrated Thai and Brazilian complexes.
- Bottle Molding:Stretch blow-molding equipment across German, Brazilian, and Thai installed bases requires resin viscosity standardization that complicates multi-source procurement.
- Pelletizing:Underwater pellet systems produce uniform chip for downstream fiber spinning and sheet extrusion.
- Film Extrusion:Cast and biaxially oriented lines serve food packaging applications with thickness control critical for barrier performance.
- Fiber Spinning:Melt spinning of textile-grade chip requires precise intrinsic viscosity control for tenacity and dye uptake.
Polymer Synthesis commands the highest capital commitment; Bottle Molding shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian synthetic fiber clusters anchor global bio-based PET procurement, with German beverage bottling corridors and Brazilian ethanol refineries forming complementary demand poles across three continents.
Germany
Beverage bottlers in Bavaria and North Rhine-Westphalia are scaling procurement of bottle-grade resin to meet EU Green Deal packaging waste directives. ECHA REACH bio-based content verification frameworks compel mass-balance documentation through every polymerization stage. The Rhine-Main packaging corridor concentrates stretch blow-molding capacity for carbonated soft drink containers.
Brazil
São Paulo state ethanol refineries supply cost-competitive bio-ethylene feedstock that has realigned with fossil MEG pricing. ANVISA food-contact regulations shape resin qualification timelines for domestic beverage manufacturers. The Campinas petrochemical cluster hosts integrated PTA-Bio-PET complexes serving Latin American export markets.
Japan
Automotive suppliers in Aichi Prefecture qualify modified PET grades for electric vehicle thermal management applications. METI bioplastics labeling guidelines mandate third-party verification of biomass carbon ratios for film-grade resins. The Chubu-Nagoya industrial zone concentrates comonomer-incorporated resin development for under-hood components.
United States
California and New York state procurement contracts now require documented bio-content percentages exceeding 30% for private-label beverage containers. FDA food-contact notification cycles influence resin supplier qualification windows. The Southeast packaging conversion belt stretches from Georgia to the Carolinas with legacy blow-molding equipment requiring viscosity standardization.
India
Maharashtra and Gujarat textile mills are consolidating procurement of certified bio-PET chip to satisfy export-oriented retailer sustainability mandates. FSSAI food-contact notification pathways and DGFT import tariff structures favor early movers establishing bottle-grade resin compounding. The Mumbai-Pune industrial corridor anchors synthetic fiber spinning capacity for global apparel brands.
Global Bio-Based PET Market Competitive Landscape
Global majors compete with regional champions across integrated feedstock-to-resin value chains, producing a tiered structure where captive bio-ethylene producers command margin premiums over non-integrated converters. Strategic archetypes cluster around Thai-Brazilian integrated complexes, Japanese automotive material specialists, and Brazilian ethanol-to-ethylene bridge players. Capacity expansion and strategic partnerships dominate competitive moves as stakeholders secure upstream offtake and downstream qualification.
Within the integrated petrochemical tier, Indorama Ventures Public Company Limited and Braskem exemplify regional anchoring strategies through Thai and Brazilian site networks. Toyota Tsusho Corporation occupies a position bridging ethanol refinery partnerships with polymer distribution. These three entities represent distinct geographic and vertical positioning archetypes without overlapping core territories.
| Leading Market Players |
|---|
| Indorama Ventures Public Company Limited |
| Toyota Tsusho Corporation |
| Toray Industries Inc. |
| Teijin Limited |
| Braskem |
| Plastipak Holdings Inc. |
| NatureWorks LLC |
| M&G Chemicals |
| Gevo Inc. |
| Others |
Supply & Pricing Matrix
Continuous solid-state polymerization technology adoption simultaneously compresses production costs and concentrates supply among integrated Thai and Brazilian complexes capable of high-intrinsic-viscosity resin output. This dual effect reshapes margin distribution across converters and captive bio-ethylene producers.
Pricing Analysis
Input-cost pass-through from sugarcane ethanol and corn starch feedstocks governs contract-based long-term offtake structures. Price differentiation rests on mass-balance certification grade and volume scale, with certified bottle-grade resin commanding premiums over uncertified equivalents. Pricing pressure stems from catalyst efficiency limitations constraining throughput at bio-ethylene integrated sites. Small-scale converters exhibit highest price sensitivity; multinational beverage manufacturers with dedicated procurement teams demonstrate lowest sensitivity due to sustainability mandate compliance requirements.
Supply Chain Analysis
Regional distribution centers in Thailand, Brazil, and Germany anchor hub-and-spoke patterns serving beverage bottling corridors and textile clusters. Raw material dependencies center on São Paulo state sugarcane ethanol, US Midwest corn starch, and petroleum-derived purified terephthalic acid from Korean and Taiwanese aromatics complexes. Single-source vulnerability concentrates in bio-ethylene supply from Brazilian ethanol refiners. Distribution runs through certified resin suppliers maintaining batch-level mass-balance documentation for EU customs clearance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Bio-Based PET Market functions as a regulatory compounder where EU Green Deal packaging waste directives mandate bio-content thresholds that pull demand through certified supply channels.
For Market Incumbents: Deepen backward integration into Brazilian ethanol refinery offtake to secure feedstock cost parity against fossil MEG fluctuations. Expand high-viscosity capacity at Thai complexes to capture German and French beverage bottler procurement. Defend against specialty chemical entrants by accelerating FDA food-contact notification cycles below 18-month industry averages. For New Entrants and Emerging Players: Indian packaging converters represent the most penetrable buyer archetype given FSSAI notification pathways and DGFT tariff structures favoring early movers. Target Maharashtra and Gujarat textile mills consolidating procurement around pre-certified chip suppliers. Penetrate through blockchain-enabled mass-balance verification as a channel innovation for EU customs documentation. For Investors and Strategic Acquirers: Valuations sit cheapest among non-integrated mid-cap converters lacking captive bio-ethylene access. Long-term viability favors integrated petrochemical players with Thai-Brazilian site networks and established mass-balance certification infrastructure. Monitor METI bioplastics labeling guideline enforcement in Japan as an inflection indicator for automotive modified PET qualification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive bio-ethylene access from Brazilian ethanol refiners insulates margin compression from sugarcane yield volatility. |
| Capacity Expansion | High-viscosity solid-state polymerization lines in Thailand capture EU Green Deal-driven German bottler procurement. |
| Long-term Supply Agreement | Multi-year offtake contracts with Coca-Cola system bottlers lock in 30% bio-content minimum specifications. |
| Joint Venture | Ethanol refinery partnerships in São Paulo state secure upstream feedstock for cost-parity MEG production. |
| Green Certification Program | REACH bio-based content verification and FDA food-contact notifications accelerate commercial offtake execution timelines. |
Research Methodology
Coverage spans East Asian textile clusters, German beverage bottling corridors, Brazilian ethanol refining regions, and North American packaging conversion belts, with primary inputs from each. The analysis combines interviews with polymer plant managers, procurement leads at beverage OEMs, synthetic fiber technical directors, and distribution channel partners with secondary validation from customs trade data, SEC petrochemical filings, and ECHA REACH registration databases. Bottom-up resin capacity modeling and top-down end-use demand triangulation anchor volume estimates.
Granularity-level framing models viscosity grades, application segments, and manufacturing stages at country-specific resolution across the projection horizon. CAGRs derive from segment-level growth rate synthesis calibrated against feedstock crop yield assumptions and polymerization catalyst efficiency trajectories. Industry-specific forecast inputs include sugarcane ethanol pricing correlations and EU packaging directive implementation timelines.
Underlying measurement precision varies by segment; beverage container and food packaging applications carry tighter precision than emerging automotive modified PET niches. Forecasts reflect assumptions about regulatory enforcement consistency and bio-ethylene feedstock cost parity maintenance. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Canada Bioplastics Market
Bioplastics
Europe Bioplastics Market
Bioplastics
Brazil Bioplastics Market
Bioplastics
Biopolymers Market
Bioplastics
Starch-Based Plastics Market
Bioplastics
Biobased Biodegradable Plastics Market
Bioplastics
Bio-Based Succinic Acid Derivatives for Plasticizers Market
Bioplastics
North America Bioplastics Market
Bioplastics
Polylactic Acid (PLA) Straws Market
Bioplastics
Middle East and Africa Polylactic Acid (PLA) Market
Bioplastics
Biopolymer Films Market
Bioplastics
US Bioplastics Market
Bioplastics
Cellulose Plastics Market
Bioplastics
Biodegradable Microbeads Market
Bioplastics
Southeast Asia Bio-PET Market
Bioplastics
Biodegradable Superabsorbent Materials Market