
 Global Bio-Polylactic Acid (PLA) Market | 2026-2036
Global Bio-Polylactic Acid (PLA) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bio-Polylactic Acid (PLA) Market Foresight
ISO 17088 certification for compostable plastics is reorganizing supplier eligibility across the Global Bio-Polylactic Acid (PLA) Market. NatureWorks LLC leverages its Nebraska manufacturing complex to dominate North American resin supply. TotalEnergies Corbion anchors European production through its Thai and French operations. Zhejiang Hisun Biomaterials competes on fermentation-derived lactide cost structures in Asia.
Bio-Polylactic Acid is an aliphatic polyester synthesized from lactic acid monomers via ring-opening polymerization of lactide, with a glass transition temperature near 60°C and melting point around 175°C, engineered primarily for thermoplastic processing in packaging and durable goods. The end use industry segmentation shows packaging commanding the largest volume pull due to food-contact film and thermoformed tray applications, while textile fibers represent the fastest-expanding margin pool as spin-dyeing technology improves PLA dye uptake. Pellet and film forms currently absorb the majority of resin offtake, though injection molding granules are gaining specification in automotive interior components.
The European Commission's REACH framework and the EU Packaging and Packaging Waste Regulation constrain petroleum-based plastic substitution timelines, while the U.S. FDA maintains food-contact notification requirements that gate PLA entry into beverage and fresh-produce packaging. China's GB standards for biodegradable plastics and its dual carbon goals are accelerating domestic lactide capacity licensing decisions. Stakeholders must track regulatory divergence between compostability certification regimes and carbon accounting methodologies to align capital deployment with enforceable demand triggers.
Market Dynamics
ISO 17088 certification requirements are reorganizing supplier eligibility across the Bio-Polylactic Acid value chain, forcing resin producers to retrofit fermentation and polymerization assets ahead of 2030 compliance deadlines in Germany and France.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Tightening material compliance timelines are pulling forward conversion line investments for thermoformed trays and food-contact films.
- Spin-dyeing technology improvements:Enhanced PLA dye uptake is unlocking specification in textile fiber applications previously served by petroleum-based polyesters.
- Thai lactide production clusters:Feedstock proximity to cassava starch supply is compressing monomer logistics costs for European and Asian resin offtake.
Market Restraints
- Corn starch input cost volatility:Feedstock price swings in the US Midwest propagate directly into NatureWorks LLC's Nebraska manufacturing economics.
- Supply concentration in Thai-French corridors:TotalEnergies Corbion's dual-site dependency creates single-source exposure for European brand owners.
- Technical limitation in high-temperature thermoforming:PLA's 175°C melting point restricts specification in hot-fill beverage packaging above 85°C.
Strategic Opportunities
- Underpenetrated automotive interior components:Injection molding granules are gaining specification in dashboard trim and seatback panels as OEMs pursue cabin carbon reduction targets.
- China's dual carbon goals:Domestic lactide capacity licensing is accelerating under GB standards for biodegradable plastics, opening import substitution potential.
- Compostability certification convergence:Alignment between ISO 17088 and ASTM D6400 is reducing duplicative testing costs for multinational packaging converters.
Industry Challenges
- Fermentation process engineering talent scarcity:Industrial microbiology and lactide purification expertise concentrates in Nebraska and Bangkok corridors, constraining greenfield project staffing.
- Capex intensity for polymerization reactor trains:Ring-opening polymerization vessels require stainless-steel construction and nitrogen blanketing systems that extend payback timelines.
- REACH registration timeline compression:ECHA dossier preparation for novel lactide copolymers is outpacing internal regulatory affairs capacity at mid-scale resin producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bio-Polylactic Acid (PLA) Market |
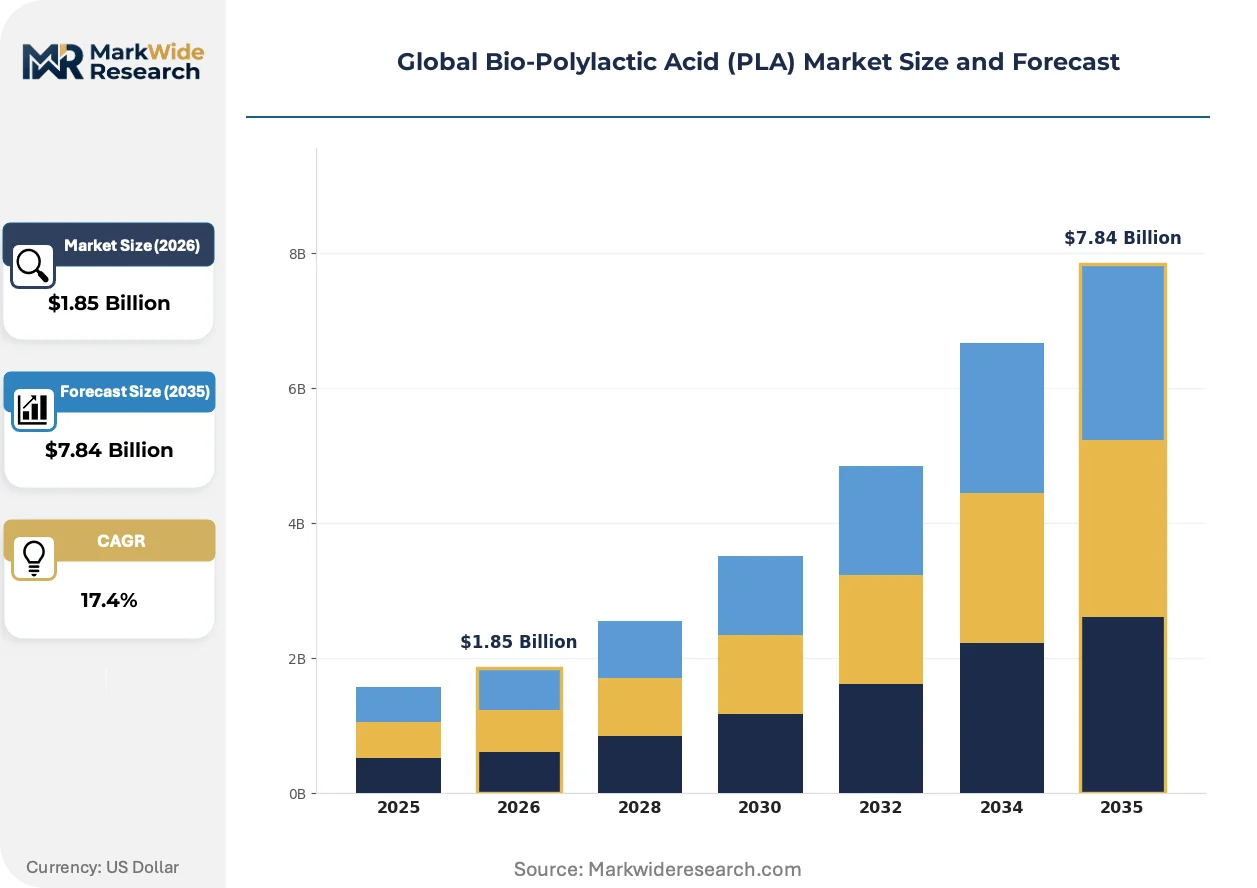
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
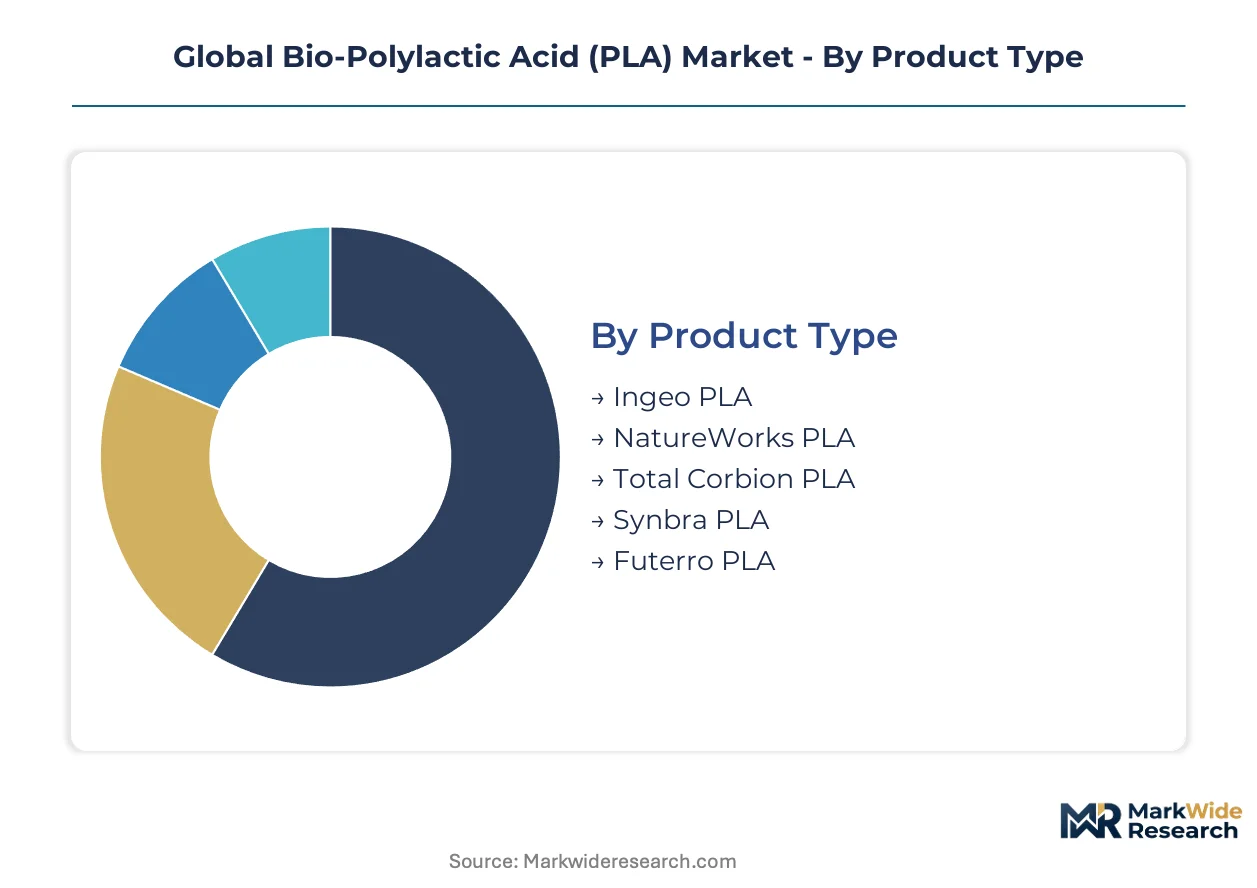
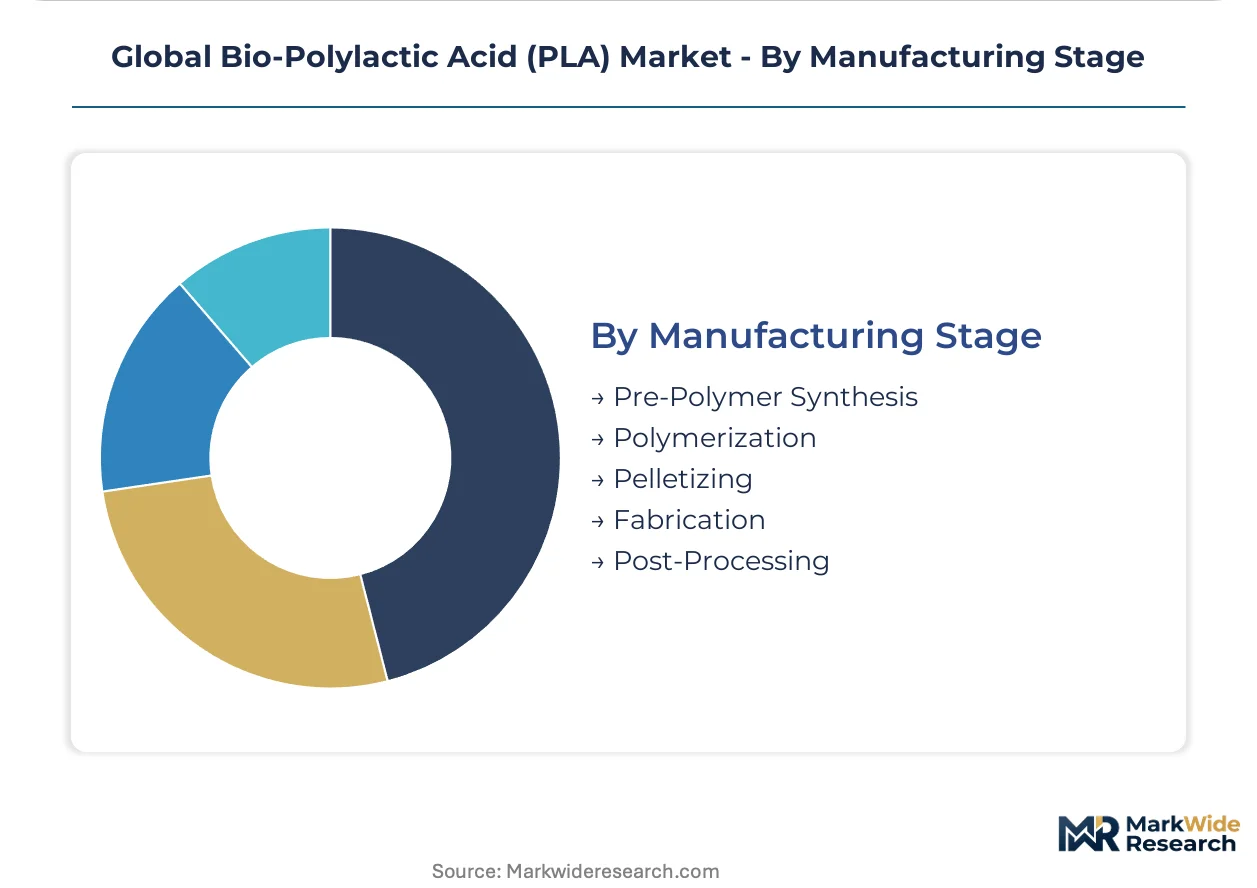
| Segmentation | Product Type: Ingeo PLA, NatureWorks PLA, Total Corbion PLA, Synbra PLA, Futerro PLA End Use Industry: Packaging, Textile Fibers, Agriculture, Automotive Components, Electronics Housing Form: Pellets, Films, Fibers, Sheets, Injection Molding Granules Manufacturing Stage: Pre-Polymer Synthesis, Polymerization, Pelletizing, Fabrication, Post-Processing |
| Companies Covered | NatureWorks LLC, TotalEnergies Corbion, BASF SE, Futerro, Zhejiang Hisun Biomaterials, Mitsubishi Chemical Corporation, COFCO Biotechnology, Toray Industries, Jiangxi Keyuan Bio-Material, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bio-Polylactic Acid (PLA) Market Shifts & Advancements
Ring-opening polymerization catalyst advances and fermentation yield improvements are compressing production economics while regulatory certification regimes are hardening material eligibility standards.
High-purity lactide production via continuous fermentation is decomposing batch-process cost structures that have dominated PLA manufacturing since commercialization. Packaging converters in Germany are adopting the output for thermoformed tray specification at accelerating rates. The technology is decomposing incumbent suppliers' yield advantages and redistributing margin capture toward fermentation-integrated producers.
REACH framework amendments are tightening substance registration requirements for lactic acid derivatives entering EU food-contact applications. Industrial consequence includes extended dossier preparation timelines and third-party testing cost inflation. Fresh-produce packaging specifications in France and Italy are most affected, with brand owners accelerating supplier qualification to secure 2026 compliance positions.
Brand-owner sustainability scorecards are mandating compostability certification as a gate criterion for resin supplier selection. Direct contracting between food multinationals and Thai-French lactide producers is displacing distributor-mediated procurement in European supply chains. The shift is most visible in German retail private-label packaging, where ISO 17088 compliance documentation now accompanies every pellet delivery.
Global Bio-Polylactic Acid (PLA) Market Segmentation
Segmentation in the Global Bio-Polylactic Acid (PLA) Market reveals how resin specifications, processing forms, and end-use certifications channel value capture differently across supply tiers. Understanding these divisions exposes where fermentation-integrated producers hold cost advantages and where specification premiums concentrate.
Product Type:
Channel distribution for PLA resins splits between direct mill contracts for high-volume packaging converters and distributor-mediated procurement for smaller textile and agricultural compounders.
- Ingeo PLA:NatureWorks LLC's flagship resin dominates North American food-contact film supply through ISO 17088-certified Nebraska production. German retail private-label packaging specifications now mandate this grade for thermoformed tray compliance ahead of E.U. Packaging and Packaging Waste Regulation deadlines.
- NatureWorks PLA:Corn-starch-derived lactide from U.S. Midwest feedstock supplies injection molding granules for automotive interior components. Dashboard trim specifications at German OEMs are displacing petroleum-based ABS in cabin carbon reduction programs.
- Total Corbion PLA:Thai-French corridor production anchors European thermoforming demand through TotalEnergies Corbion's Rayong and Grandpuits operations.
- Synbra PLA:Netherlands-based fermentation focuses on expanded polylactic bead applications for protective packaging.
- Futerro PLA:Belgian-Chinese joint venture capacity targets Asian textile fiber spin-dyeing specifications under China's GB biodegradable standards.
By volume, Ingeo PLA leads. By growth pace, Total Corbion PLA is climbing the fastest on EU regulatory pull.
End Use Industry:
Margin structure across end uses inverts conventional polymer patterns: packaging commands volume while textile fibers capture expanding premiums through dye-uptake technology advances.
- Packaging:Thermoformed trays and food-contact films absorb the majority of resin offtake. French and Italian fresh-produce brand owners are accelerating supplier qualification to secure REACH-compliant positions for 2026 food-contact notification requirements.
- Textile Fibers:Spin-dyeing technology improvements are unlocking PLA specification in apparel previously served by petroleum-based polyesters. German technical textile producers are piloting lactide-based filament for automotive seat fabric.
- Agriculture:Mulch film and controlled-release fertilizer coatings drive seasonal demand clusters in China's Shandong province.
- Automotive Components:Injection-molded dashboard trim and seatback panels are gaining specification as OEMs pursue cabin carbon reduction targets.
- Electronics Housing:Limited penetration due to PLA's 60°C glass transition temperature constraining thermal management applications.
Packaging captures the largest revenue pool. Textile fibers are expanding most quickly as dye-uptake specifications mature.
Form:
Processing form determines logistics economics: pellets and films move through bulk rail and containerized ocean freight, while fibers and sheets require specialized temperature-controlled handling.
- Pellets:Standard extrusion-grade resin dominates thermoforming line feedstock. German packaging converters are expanding pellet silo capacity ahead of single-use plastic bans.
- Films:Biaxially oriented PLA film specifications for flexible food packaging are tightening thickness tolerances to compete with oriented polypropylene.
- Fibers:Staple and filament grades for textile spin-dyeing applications.
- Sheets:Thermoforming feedstock for rigid tray production.
- Injection Molding Granules:Automotive interior component specifications are gaining traction in German OEM supply chains.
Pellets and films together lead by tonnage. Injection molding granules are gaining share fastest on automotive qualification timelines.
Manufacturing Stage:
Value capture concentrates upstream: fermentation-integrated producers retaining lactide and polymerization stages capture margin that toll compounders at pelletizing and fabrication stages cannot access.
- Pre-Polymer Synthesis:Lactic acid fermentation and crude lactide production. Thai cassava starch corridors compress monomer logistics costs for European offtake.
- Polymerization:Ring-opening polymerization of high-purity lactide. Stainless-steel reactor trains with nitrogen blanketing systems represent the capex-intensive bottleneck.
- Pelletizing:Extrusion and cutting to standard pellet dimensions.
- Fabrication:Film casting, sheet extrusion, and fiber spinning by downstream converters.
- Post-Processing:Thermoforming, injection molding, and surface treatment for end-use specifications.
Polymerization commands the highest margin concentration. Pre-polymer synthesis is expanding most quickly on continuous fermentation technology deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging converters and brand owners in Germany, Thailand, the United States, China, and France are driving the majority of resin procurement decisions. These buyer archetypes concentrate where regulatory deadlines for single-use plastic phase-outs intersect with established fermentation and polymerization infrastructure.
Germany
Thermoformed tray demand from retail private-label packaging anchors resin offtake. The EU Packaging and Packaging Waste Regulation mandates recyclability compliance by 2030. The Grandpuits industrial cluster southeast of Paris supplies German converters through cross-border rail logistics.
Thailand
Cassava starch feedstock proximity compresses lactide production economics for Asian and European export markets. The country's national industrial standards regulator enforces biodegradable plastic certification under GB-equivalent protocols. The Rayong petrochemical corridor hosts integrated fermentation-to-polymerization complexes serving brand owners in France and Germany.
United States
Food-contact film specifications from beverage and fresh-produce packagers pull Nebraska-manufactured resin through domestic distribution networks. The FDA maintains notification requirements for PLA entry into food-contact applications. The Midwest corn belt supplies fermentation feedstock to manufacturing complexes in Nebraska.
China
Domestic lactide capacity licensing accelerates under GB standards for biodegradable plastics and dual carbon goals. The Ministry of Ecology and Environment enforces biodegradable plastic deployment timelines in major municipalities. The Shandong province agriculture cluster consumes mulch film and controlled-release fertilizer coatings seasonally.
France
Fresh-produce packaging brand owners accelerate supplier qualification to secure REACH-compliant positions for 2026 food-contact requirements. ECHA dossier preparation timelines constrain novel lactide copolymer registration. The Grandpuits refining complex conversion hosts polymerization trains supplying German retail packaging specifications.
Global Bio-Polylactic Acid (PLA) Market Competitive Landscape
Player mix skews toward fermentation-integrated resin producers with captive lactide supply. The structure concentrates around three to four vertically positioned suppliers controlling upstream monomer and downstream polymerization stages. Strategic archetypes include Midwest corn-belt integrated producers, Thai-French corridor dual-site operators, and Asian fermentation cost competitors. Capacity expansion and compostability certification alignment represent the dominant competitive moves reshaping supplier eligibility.
Within the integrated producer tier, NatureWorks LLC and TotalEnergies Corbion exemplify divergent geographic anchoring strategies. NatureWorks LLC occupies a position tied to U.S. Midwest feedstock corridors. TotalEnergies Corbion represents the Thai-French dual-site model serving European regulatory demand. Zhejiang Hisun Biomaterials sits within the Asian fermentation-specialist archetype competing on lactide cost structures.
| Leading Market Players |
|---|
| NatureWorks LLC |
| TotalEnergies Corbion |
| BASF SE |
| Futerro |
| Zhejiang Hisun Biomaterials |
| Mitsubishi Chemical Corporation |
| COFCO Biotechnology |
| Toray Industries |
| Jiangxi Keyuan Bio-Material |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts with Thai-French corridor producers lock in lactide supply access and price visibility for German packaging converters facing EU Packaging and Packaging Waste Regulation deadlines. These agreements tie resin pricing to corn starch and cassava feedstock indices while securing volume commitments against single-use plastic substitution timelines.
Pricing Analysis
Cost-plus contracts with corn starch indexation dominate NatureWorks LLC's Nebraska supply agreements and TotalEnergies Corbion's Thai-French corridor arrangements. Price differentiation rests on ISO 17088 certification tier and volume scale, with certified pellet grades commanding premiums over uncertified alternatives. Pricing pressure stems from fermentation yield improvements compressing lactide production economics. Small-scale textile compounders exhibit highest price sensitivity, while automotive OEMs prioritize specification certainty over unit cost.
Supply Chain Analysis
Container availability on Asia-Europe trade lanes constrains lactide monomer movement from Rayong to Grandpuits polymerization trains. Supply concentrates in Thailand, the United States, and France, with fermentation-integrated producers controlling upstream lactide and downstream polymerization stages. Raw material dependencies center on corn starch from the US Midwest and cassava starch from Thai agricultural zones. Single-source vulnerability runs through TotalEnergies Corbion's dual-site concentration for European brand owners. Distribution runs through direct mill contracts for high-volume converters and distributor-mediated channels for smaller compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against petroleum-based polypropylene and polyethylene terephthalate incumbents. Brand-owner sustainability mandates are accelerating material switching timelines that PLA producers must capture before incumbent resin suppliers reformulate.
For Market Incumbents: Fortify backward integration into fermentation-integrated lactide production to defend margin capture against toll compounders. Expand Grandpuits polymerization capacity to anchor EU regulatory demand. Secure ISO 17088 certification alignment ahead of German recyclability mandates to lock out uncertified competitors.
For New Entrants and Emerging Players: Anchor in China's domestic lactide capacity licensing wave under GB biodegradable standards and dual carbon goals. Target Shandong province agriculture clusters for seasonal mulch film demand. Pursue direct contracting with food multinationals to bypass distributor-mediated European procurement.
For Investors and Strategic Acquirers: Fermentation-integrated mid-scale specialists with captive Thai cassava supply offer acquisition exposure to cost-compressed lactide economics. Long-term viability hinges on compostability certification convergence reducing duplicative testing burdens. Watch for ECHA REACH registration timeline compression as an inflection signal for regulatory capacity constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lactide Production | Captures margin concentration currently held by Thai-French corridor fermentation specialists. |
| ISO 17088 Certification Investment | Secures supplier eligibility for German retail private-label packaging ahead of 2030 mandates. |
| Long-term Supply Agreement with Automotive OEMs | Locks in injection molding granule offtake for dashboard trim and seatback panel specifications. |
| Joint Venture for Continuous Fermentation Technology | Decomposes batch-process cost structures that have dominated PLA manufacturing since commercialization. |
| Capacity Expansion in Grandpuits Industrial Cluster | Positions polymerization trains to serve cross-border German thermoforming demand via rail logistics. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary source validation. Interview subjects included fermentation plant managers at Thai cassava starch facilities, procurement leads at German packaging converters, technical R&D directors at polymerization operations, and regulatory affairs specialists navigating ECHA REACH dossier preparation. Secondary sources encompassed customs and trade flow data, SEC filings from publicly traded resin producers, EU regulatory filings under the Packaging and Packaging Waste Regulation, and industry association reports from European bioplastics associations. Bottom-up capacity and demand modeling was cross-checked against top-down macroeconomic triangulation.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product grade tier, end-use industry, processing form, and regional production hub. CAGRs were derived from regression analysis against feedstock cost indices and regulatory enforcement timelines. Industry-specific inputs included fermentation yield improvement curves and compostability certification adoption rates among multinational brand owners.
Decision-makers should treat outputs as directional under assumptions of sustained EU regulatory enforcement and Thai feedstock supply stability; material deviation would warrant model refresh. Specific risks include corn starch price volatility propagating through Nebraska manufacturing economics and REACH registration timeline slippage constraining novel copolymer commercialization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Biodegradable Superabsorbent Materials Market
Bioplastics
Global Bioplastic Composites Market
Bioplastics
Starch-Based Plastics Market
Bioplastics
Biopolymers Market
Bioplastics
Southeast Asia Bio-PET Market
Bioplastics
Global Bio-Based PET Market
Bioplastics
Biodegradable Insulated Panel Market
Bioplastics
Biodegradable Disposable Tableware Market
Bioplastics
China Bioplastics Market
Bioplastics
Cellulose Bioplastic Market
Bioplastics
Starch-Based Bioplastics Market
Bioplastics
Bio-Based Succinic Acid Derivatives for Plasticizers Market
Bioplastics
Middle East and Africa Polylactic Acid (PLA) Market
Bioplastics
Global Bioresorbable (Resorbable) Polymers Market
Bioplastics
Global Bioplastic Market
Bioplastics
Biodegradable Microbeads Market