
 Asia-Pacific Paints and Coatings Additives Market | 2026-2036
Asia-Pacific Paints and Coatings Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Paints and Coatings Additives Market Outlook
Waterborne formulation technology is reconfiguring additive selection criteria across the Asia-Pacific coatings supply chain. BASF SE anchors its regional position through backward integration into dispersant intermediates. Evonik Industries AG specializes in silicone-based surface modifiers for high-performance architectural finishes. Dow extends its formulation reach through rheology modifier portfolios tailored to tropical humidity conditions.
Asia-Pacific paints and coatings additives comprise functional chemical compounds—typically organic or organometallic substances at 0.1–5.0 wt% loading—that modify viscosity stability, pigment distribution, film formation, or substrate adhesion during coating application and cure. These additives serve to prevent manufacturing defects, extend pot life, and achieve regulatory-compliant finished film properties across liquid, powder, and radiation-cured systems. Dispersants command substantial volume share due to universal pigment stabilization requirements across all formulation types, while rheology modifiers capture disproportionate value in premium water-based architectural segments where sag resistance and spatter control determine specification wins. UV-curing formulations represent the fastest-expanding formulation category as electronics and wood coatings manufacturers in South Korea and Taiwan adopt low-energy cure cycles to reduce thermal substrate damage.
China's MEE enforces progressively lower VOC limits under evolving GB standards, redirecting solvent-based capacity investments toward waterborne and powder coating additive platforms. Japan's METI coordinates with JIS standard committees to establish performance benchmarks for low-carbon coating systems in automotive OEM supply chains. India's BIS certification requirements for architectural coating raw materials are tightening import quality gates. Stakeholders must monitor regulatory divergence between national standards regimes when allocating R&D budgets across multi-country formulation portfolios.
Market Dynamics
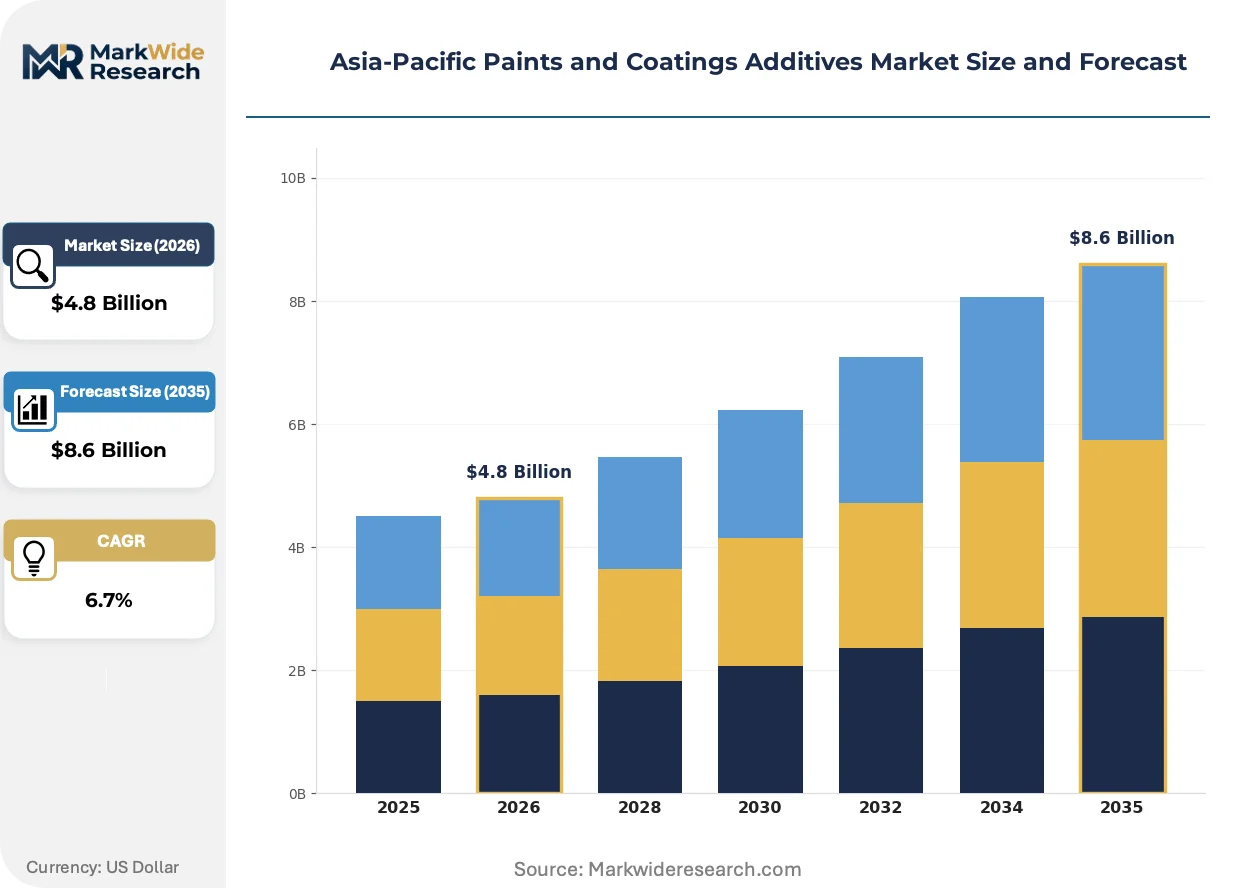
Waterborne formulation conversion is fragmenting additive specifications across Asia-Pacific coatings supply chains, forcing suppliers to revalidate product portfolios against divergent national VOC regimes while construction procurement concentrates in India's western corridor and Southeast Asian industrial zones.
Growth Catalysts
- GB Standards Stringency:China's MEE enforcement of progressively lower VOC limits under evolving GB standards redirects solvent-based capacity investments toward waterborne and powder coating additive platforms.
- Construction Procurement Expansion:Southeast Asian infrastructure build-out is expanding formulation volumes for water-based dispersants and rheology modifiers in commercial and residential architectural coatings.
- UV-Curing Electronics Adoption:Electronics and wood coatings manufacturers in South Korea and Taiwan are adopting low-energy cure cycles to reduce thermal substrate damage, accelerating photoinitiator and oligomer additive demand.
Market Restraints
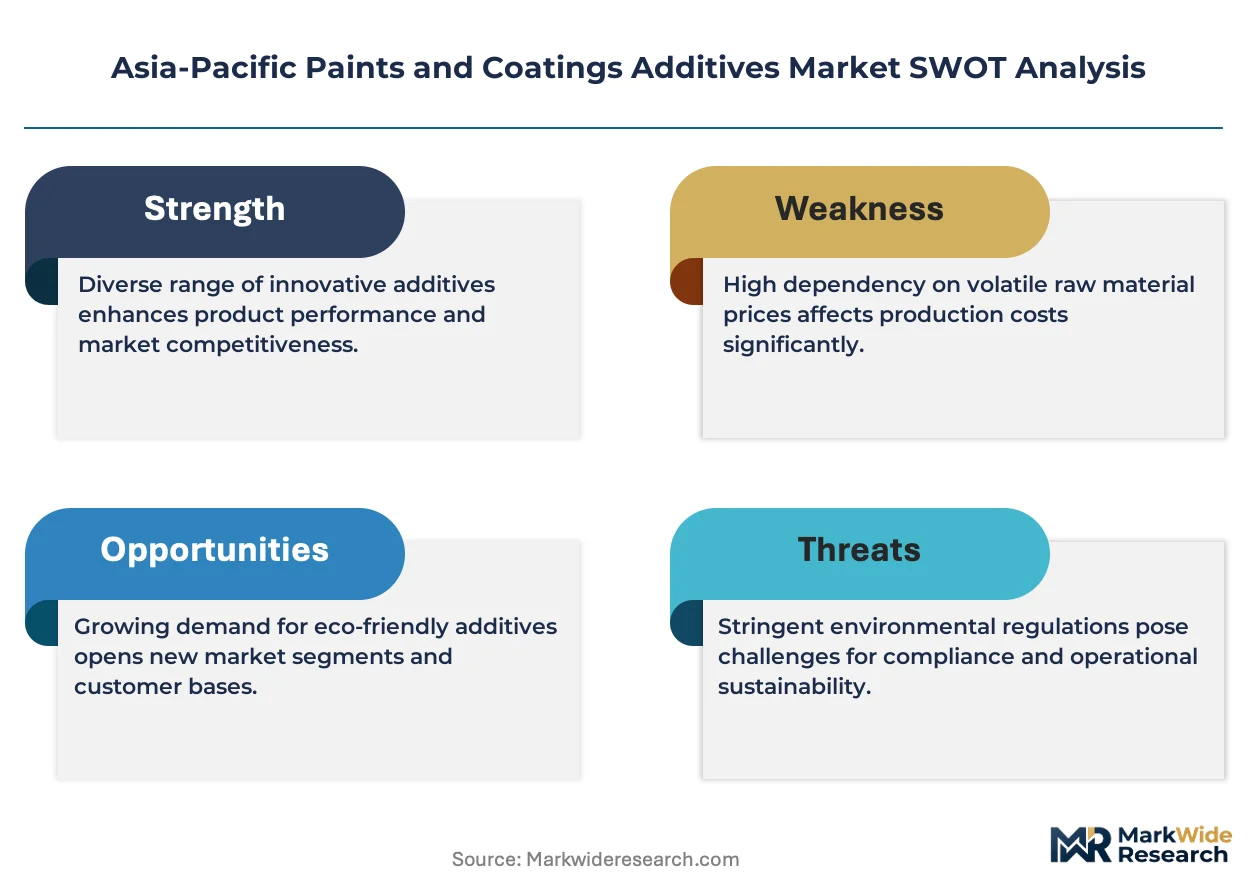
- Petrochemical Feedstock Volatility:Acrylic acid and solvent intermediate prices fluctuate with naphtha and propylene chain dynamics, compressing margin visibility for dispersant and rheology modifier producers.
- Import Quality Gate Tightening:India's BIS certification requirements for architectural coating raw materials are extending qualification timelines for foreign additive suppliers.
- Silicone Intermediate Concentration:Silicone-based surface modifier supply concentrates among a limited set of organosilicon producers, creating allocation risk during semiconductor demand surges.
Strategic Opportunities
- Vietnam Industrial Corridor Penetration:Northern Vietnam's emerging electronics manufacturing clusters present underdeveloped demand for conformal coating additives serving PCB protection applications.
- JIS Low-Carbon Automotive Benchmarks:Japan's METI coordination with JIS standard committees to establish performance benchmarks for low-carbon coating systems creates specification pull for bio-based additive platforms.
- Digital Formulation Platforms:AI-assisted additive selection tools are compressing trial-and-error cycles, enabling remote technical service penetration into tier-two and tier-three coatings producers.
Industry Challenges
- Formulation Chemist Scarcity:Waterborne system expertise gaps persist across Southeast Asian technical service teams, slowing customer conversion from solvent-based legacy specifications.
- Multi-Country Registration Burden:Divergent BIS, GB, and JIS compliance pathways force additive suppliers to maintain parallel qualification dossiers, inflating regulatory affairs overhead.
- Tropical Stability Validation:Rheology modifiers and biocides require extended humidity-chamber testing for tropical Asia-Pacific conditions, extending product launch timelines versus temperate-market equivalents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Paints and Coatings Additives Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Modifiers, Dispersants, Stabilizers, Rheology Modifiers End User: Construction, Automotive, Industrial, Wood Coatings Formulation Type: Water-Based, Solvent-Based, Powder Coatings, UV-Curing Functionality: Anti-Foaming Agents, Preservatives, Colorants, Adhesion Promoters |
| Companies Covered | Dow, BASF SE, Evonik Industries AG, Altana, Ashland, Elementis PLC, Solvay, Arkema SA, BYK-Chemie GmbH, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Paints and Coatings Additives Market Strategic Shifts
Digital twin technologies are compressing additive development cycles across Asia-Pacific coatings laboratories, while regulatory divergence between China's GB standards and India's BIS frameworks is forcing modular formulation architectures.
Bio-based dispersant intermediates derived from lignin and tannin feedstocks are virtualizing petroleum-derived surfactant positions in premium architectural segments. Japanese and South Korean coatings producers are integrating these platforms into JIS-compliant low-carbon systems. The technology is virtualizing traditional petrochemical supply relationships by enabling regional biomass supply chain capture.
China's MEE enforcement of dual carbon goals is tightening GB 30981 and related VOC emission standards for industrial coatings, forcing reformulation of automotive and marine protective systems. Domestic coatings producers are accelerating waterborne epoxy and polyurethane additive procurement to maintain facility operating permits. The policy pressure concentrates most intensely on Yangtze River Delta manufacturing clusters where MEE inspection frequency has intensified.
Specification authority is migrating from coatings producers to architectural project developers and automotive OEMs, compressing additive supplier direct relationships. Large-scale construction procurement in India's western corridor now routes through EPC contractors with pre-approved material lists, displacing traditional distributor technical selling. The pattern is most visible in Maharashtra and Gujarat where Reliance-Adani infrastructure projects consolidate specification decisions at the developer level.
Asia-Pacific Paints and Coatings Additives Market Segmentation
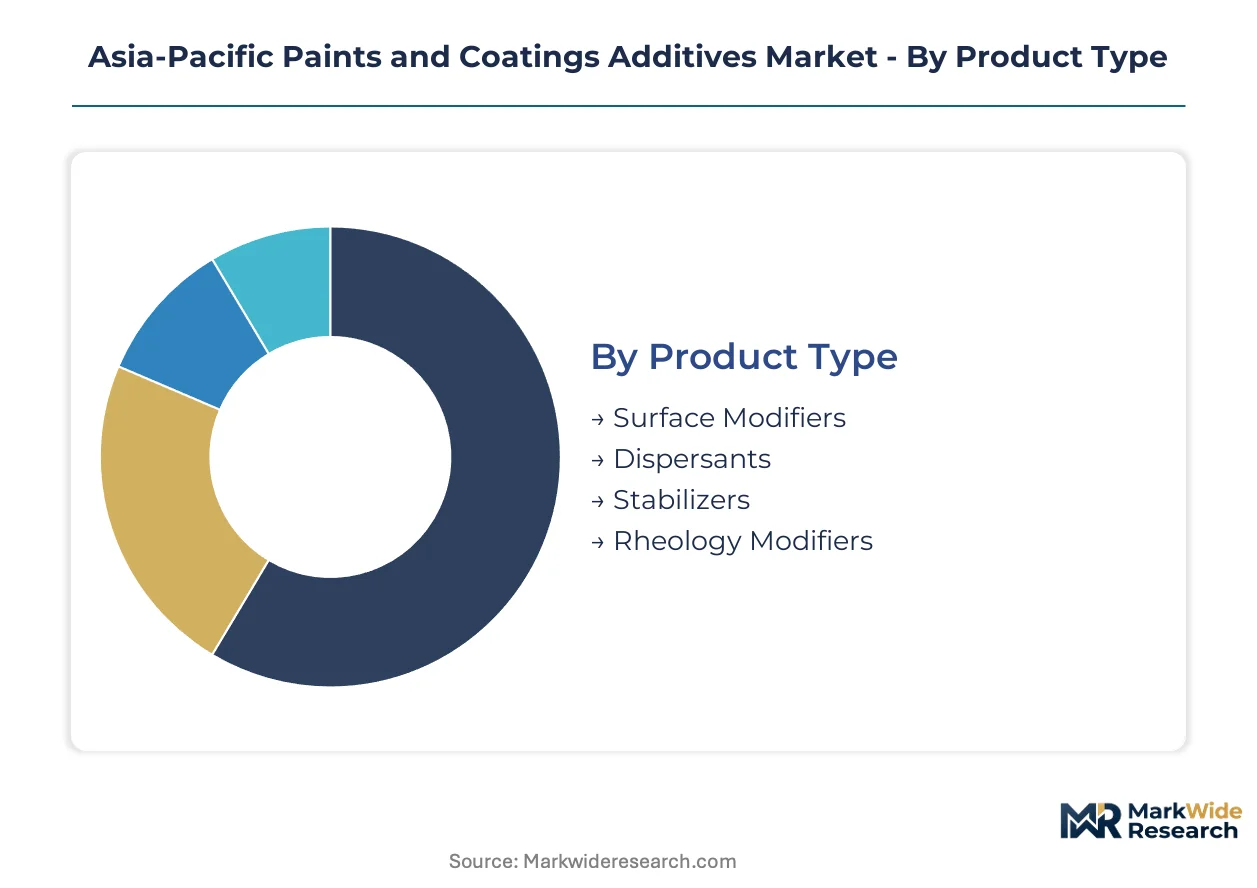
Additive selection in Asia-Pacific coatings markets follows formulation chemistry, end-use performance requirements, and regulatory compliance pathways. Segment boundaries blur as waterborne conversion forces multi-functional additive architectures across construction, automotive, and industrial applications.
Product Type:
Cost tier determines specification authority across additive categories, with premium segments capturing disproportionate value in architectural and automotive finishes.
- Surface Modifiers:Silicone-based and fluorinated chemistries reduce surface tension for substrate wetting and leveling control. Demand concentrates in South Korean electronics conformal coatings and Japanese automotive OEM clearcoats where scratch resistance determines specification wins. MEE inspection intensity in Yangtze River Delta clusters is redirecting solvent-based modifier procurement toward water-compatible silicone polyethers.
- Dispersants:Polyacrylate and polyurethane anchor block copolymers stabilize pigment particle distribution across waterborne and solvent systems. India's western industrial corridor from Gujarat through Maharashtra is expanding procurement volumes for titanium dioxide and organic pigment dispersion in architectural emulsions. BIS certification timelines are extending qualification cycles for imported dispersant platforms.
- Stabilizers:Hindered amine light stabilizers and UV absorbers protect coating films from photodegradation in tropical high-UV conditions.
- Rheology Modifiers:Associative thickeners and clay-based systems control sag resistance and spatter in spray-applied architectural coatings.
Dispersants command the established base. The steepest expansion runs through surface modifiers.
End User:
Application intensity varies sharply across end-use sectors, with construction procurement consolidating through EPC contractor pre-approved lists while automotive specifications migrate to OEM direct control.
- Construction:Architectural coatings for commercial and residential buildings drive volume demand for dispersants, rheology modifiers, and biocides. Southeast Asian infrastructure build-out in Vietnam, Indonesia, and Philippines is accelerating waterborne additive procurement for interior and exterior emulsion paints. Reliance-Adani project consolidation in Maharashtra and Gujarat is displacing traditional distributor technical selling with developer-level specification authority.
- Automotive:OEM clearcoats, basecoats, and electrodeposition primers require high-performance surface modifiers, adhesion promoters, and UV stabilizers. China's GB standards on VOC emissions are tightening solvent-based coating specifications and redirecting investment toward waterborne epoxy and polyurethane additive platforms in Yangtze River Delta manufacturing clusters.
- Industrial:Protective coatings for marine, oil and gas, and chemical processing infrastructure demand corrosion-resistant additive packages.
- Wood Coatings:Furniture and flooring finishes in South Korea and Taiwan are adopting UV-curing systems to reduce thermal substrate damage.
Construction captures the volume base. Automotive delivers the steepest value expansion.
Formulation Type:
Volume distribution reflects regulatory pressure intensity, with waterborne platforms gaining share fastest where MEE enforcement concentrates.
- Water-Based:Acrylic, polyurethane, and epoxy dispersions rely on dispersants, rheology modifiers, and coalescing aids for film formation. China's dual carbon goals and GB 30981 enforcement are accelerating domestic procurement of waterborne-compatible additives to maintain facility operating permits. Humidity-chamber validation requirements for tropical Asia-Pacific conditions extend product launch timelines versus temperate-market equivalents.
- Solvent-Based:Alkyd, urethane, and epoxy systems retain share in marine protective and automotive refinish segments where performance specifications exceed waterborne capabilities.
- Powder Coatings:Zero-VOC thermoset systems for architectural aluminum and industrial equipment depend on flow control and degassing additives.
- UV-Curing:Photoinitiator and oligomer formulations for electronics and wood coatings enable low-energy cure cycles. Electronics manufacturers in South Korea and Taiwan are adopting these systems to reduce thermal substrate damage on temperature-sensitive components.
Solvent-based formulations retain the installed base. UV-curing climbs the fastest.
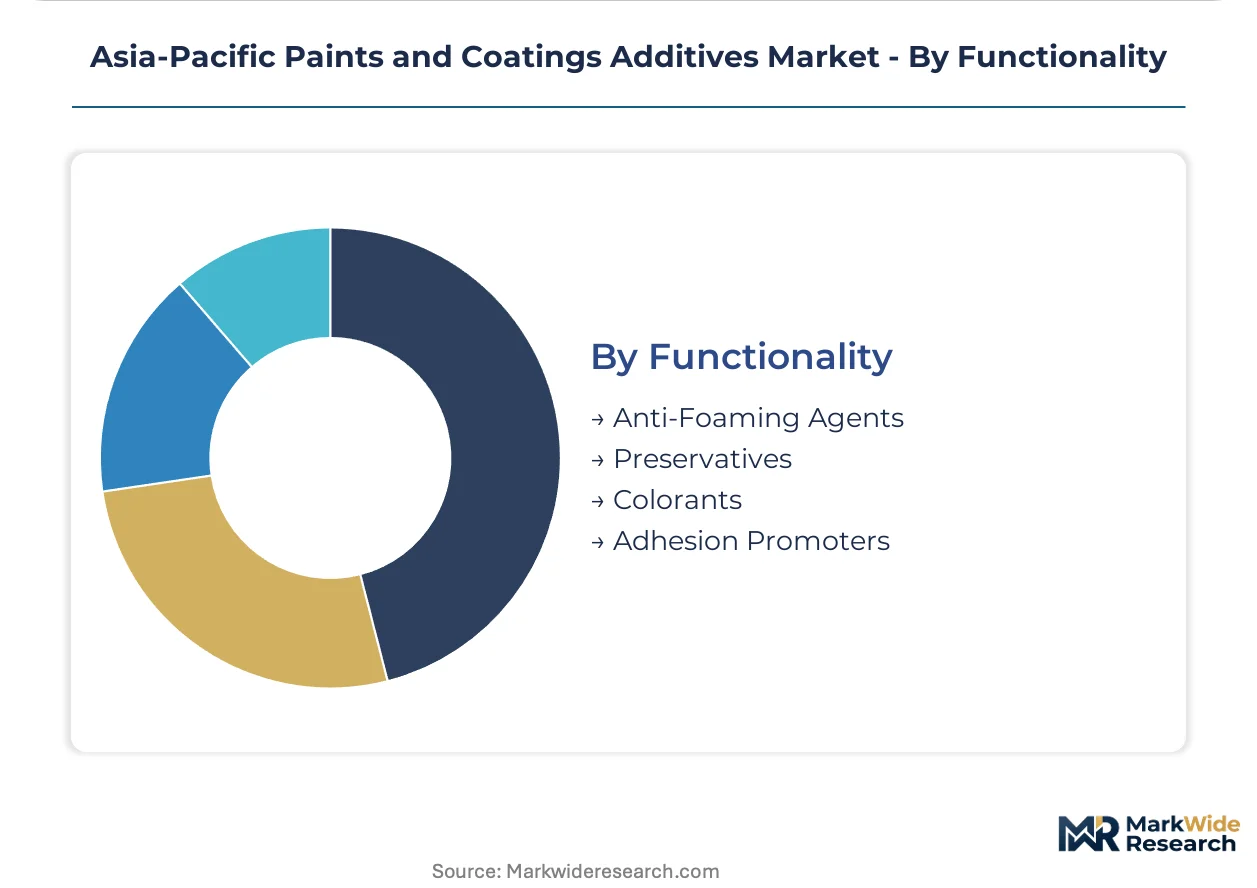
Functionality:
Margin concentration aligns with performance-critical functions where formulation failure costs exceed additive expenditure.
- Anti-Foaming Agents:Silicone and mineral oil defoamers prevent air entrainment during high-speed dispersion and application. Waterborne architectural production in Southeast Asia requires tropical-stability validated grades where humidity-chamber testing extends qualification timelines.
- Preservatives:Isothiazolinone and formaldehyde-releasing biocides protect waterborne coatings from microbial degradation in-can and in-film. India's BIS certification requirements for architectural coating raw materials are tightening import quality gates and extending foreign supplier registration burdens.
- Colorants:Pigment dispersions and tinting systems enable point-of-sale color matching.
- Adhesion Promoters:Silane and titanate coupling agents improve substrate bonding for metal, plastic, and composite surfaces. Automotive OEM specifications in Japan's METI-coordinated JIS frameworks are establishing performance benchmarks for low-carbon coating systems with bio-based additive platforms.
Anti-foaming agents command the established base. Adhesion promoters are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports waterborne additive formulations to Southeast Asian coatings producers as MEE enforcement tightens domestic VOC standards. Japanese specialty chemical firms supply surface modifiers to South Korean electronics clusters. India's western industrial corridor imports dispersant intermediates from European suppliers.
China
Yangtze River Delta manufacturing clusters are accelerating waterborne epoxy and polyurethane additive procurement. MEE inspection frequency has intensified under GB 30981 and dual carbon enforcement. Shanghai and Jiangsu province coatings producers are reformulating automotive and marine protective systems to maintain facility operating permits.
India
Reliance-Adani infrastructure projects in Maharashtra and Gujarat are consolidating specification authority at the developer level. BIS certification requirements for architectural coating raw materials are extending qualification timelines for imported dispersant platforms. Mumbai-Pune industrial corridor demand concentrates on titanium dioxide and organic pigment dispersion in architectural emulsions.
Japan
METI coordinates with JIS standard committees to establish performance benchmarks for low-carbon coating systems. Automotive OEM supply chains in Kanto and Kansai regions are integrating bio-based additive platforms into clearcoat specifications. Nagoya manufacturing clusters are specifying silicone-based surface modifiers for scratch-resistant finishes.
South Korea
Electronics manufacturers in Seoul Capital Area and Busan-Ulsan are adopting UV-curing systems to reduce thermal substrate damage. Photoinitiator and oligomer additive demand is accelerating for PCB protection applications. Gyeonggi-do semiconductor packaging facilities are driving conformal coating additive procurement.
Vietnam
Northern Vietnam's emerging electronics manufacturing clusters present underdeveloped demand for conformal coating additives. Bac Ninh and Hai Phong industrial zones are attracting PCB assembly investment from Taiwanese and South Korean capital. Local coatings formulators lack technical service depth for waterborne system conversion.
Asia-Pacific Paints and Coatings Additives Market Competitive Environment
On the supply side, the industry is structured around three distinct capability tiers. Integrated petrochemical majors control dispersant intermediate supply through backward integration into acrylic acid and solvent chains. Specialty chemical houses dominate silicone-based surface modifiers and rheology modifier portfolios. Regional distributors and local compounders fill formulation service gaps in tier-two and tier-three coatings markets. Competitive moves concentrate on capacity expansion in waterborne-compatible additive platforms and strategic partnerships with tropical-stability validation laboratories.
Among integrated chemical majors, BASF SE and Dow exemplify the scale-driven archetype with regional formulation reach. Evonik Industries AG occupies a specialist position within the silicone-based surface modifier segment. These three anchors represent divergent strategic postures: backward-integrated intermediate control versus high-performance architectural specialization versus tropical-humidity rheology expertise.
| Leading Market Players |
|---|
| Dow |
| BASF SE |
| Evonik Industries AG |
| Altana |
| Ashland |
| Elementis PLC |
| Solvay |
| Arkema SA |
| BYK-Chemie GmbH |
| Others |
Value Chain & Pricing Dynamics
Silicone intermediate concentration among organosilicon producers in China, Japan, and South Korea determines both premium tier spreads for surface modifiers and the regionalized supply chain architecture for Asia-Pacific coatings additives. This single-source dependency for high-performance architectural finishes forces additive suppliers to maintain captive supply relationships or absorb allocation risk during semiconductor demand surges, compressing margin visibility across waterborne formulation conversions.
Pricing Analysis
Waterborne-compatible additive platforms command a technology-generation pricing gap against legacy solvent-based equivalents, with premium rheology modifiers and dispersants capturing value in tropical-stability validated grades. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified automotive grades from BIS-compliant architectural emulsions and unqualified economy tiers. Pricing pressure stems from acrylic acid and propylene chain volatility feeding naphtha-linked feedstock costs. Volume-scale buyers in India's western industrial corridor exhibit highest price sensitivity, while Japanese automotive OEMs prioritize certification-grade performance over unit cost.
Supply Chain Analysis
Upstream acrylic acid and solvent intermediates draw from petrochemical complexes concentrated in China, South Korea, and Japan, with naphtha and propylene chain dynamics feeding additive production cost structures. Dispersant anchor block copolymers, silicone polyethers, and photoinitiator oligomers constitute critical input dependencies. Single-source vulnerability concentrates in organosilicon surface modifiers where semiconductor demand surges trigger allocation constraints. Distribution runs through EPC contractor pre-approved material lists in construction, bypassing traditional distributor technical selling in Maharashtra and Gujarat infrastructure corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. BIS, GB, and JIS compliance pathways create switching costs that protect qualified suppliers from unregistered competitors across multi-country formulation portfolios.
For Market Incumbents: Harden specification authority through backward integration into dispersant intermediates and tropical-stability validation laboratory partnerships. Capacity addition in Vietnam's northern industrial zones captures emerging electronics conformal coating demand before local formulators develop waterborne technical service depth. Certification investment in JIS low-carbon automotive benchmarks protects against bio-based additive platform substitution.
For New Entrants and Emerging Players: Pursue underdeveloped demand in Vietnam's Bac Ninh and Hai Phong electronics clusters where PCB protection applications lack conformal coating additive supply. Digital formulation platforms offering AI-assisted additive selection compress trial-and-error cycles for tier-two and tier-three coatings producers lacking in-house formulation chemists. Remote technical service penetration enables market entry without establishing regional laboratory infrastructure.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialty chemical houses with silicone-based surface modifier expertise over integrated petrochemical majors facing feedstock margin compression. Long-term viability centers on regulatory affairs capabilities spanning BIS, GB, and JIS parallel qualification dossiers. Acquisition targets should demonstrate tropical humidity validation infrastructure and established EPC contractor relationships. Watch MEE inspection frequency in Yangtze River Delta clusters as inflection indicator for waterborne additive procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dispersant Intermediates | BASF SE's captive acrylic acid supply secures margin stability against naphtha volatility in Yangtze River Delta manufacturing. |
| Tropical Stability Validation Laboratory Partnership | Extended humidity-chamber testing capacity accelerates product launch timelines for Southeast Asian waterborne architectural emulsions. |
| Digital Formulation Platform Deployment | AI-assisted additive selection compresses technical service cycles for tier-two coatings producers in Vietnam and Indonesia. |
| JIS Low-Carbon Certification Investment | METI-coordinated performance benchmarks create specification pull for bio-based additive platforms in Kanto automotive OEM supply chains. |
| Northern Vietnam Industrial Corridor Expansion | Bac Ninh and Hai Phong electronics clusters present first-mover advantage for conformal coating additive technical service penetration. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs and trade data, ACC and Cefic chemical industry reports, and SEC 10-K filings from listed specialty chemical firms. Primary interviews engaged plant managers at coatings manufacturing facilities, procurement leads at downstream automotive OEMs, distribution channel partners across India and Southeast Asia, and technical R&D directors at additive suppliers. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators and regional construction procurement databases.
Forecast inputs considered formulation type conversion rates, regulatory enforcement intensity across MEE and BIS jurisdictions, and end-use sector growth patterns across the analysis window. Segmentation dimensions modeled include product type tier, end-use industry concentration, formulation chemistry platform, and regional regulatory cluster. CAGRs derived from historical volume trajectories adjusted for policy-driven substitution effects and tropical climate validation requirements.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese domestic additive producers or accelerated GB standard enforcement beyond Yangtze River Delta clusters would shift outcomes. Cross-checking against EPC contractor pre-approved material list disclosures and MEE inspection frequency reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Alkyd Coatings Market
Paints & Coatings
South America Paints and Coatings Additives Market
Paints & Coatings
GCC Paints and Coatings Market
Paints & Coatings
Qatar Paints and Coatings Market
Paints & Coatings
North America Paints and Coatings Market
Paints & Coatings
Fluorescent Paint Market
Paints & Coatings
Bituminous Paints Market
Paints & Coatings
Low VOC Paints and Coatings Market
Paints & Coatings
Asia-Pacific Architectural Coatings Market
Paints & Coatings
Decorative Paints Market
Paints & Coatings
Bio-Based and Low VOC Paints Market
Paints & Coatings
India Architectural Coatings Market
Paints & Coatings
Paint Cans Market
Paints & Coatings
Polyurethane Resins Paints and Coatings Market
Paints & Coatings
Mosquito-Repellent Paints Market
Paints & Coatings
United Arab Emirates (UAE) Paints and Coatings Market