
 Bio-Based and Low VOC Paints Market | 2026-2036
Bio-Based and Low VOC Paints Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Based and Low VOC Paints Market Intelligence
The bundling of primers and topcoats into certified low-VOC systems is shifting buyer preference from single-can purchases. The Sherwin-Williams Company leverages its extensive retail network to promote these integrated solutions directly to contractors. Akzo Nobel N.V. differentiates with its focus on high-purity bio-based formulations targeting architects specifying for green building projects. PPG Industries, Inc. competes on performance for industrial coatings, ensuring its low-VOC products meet stringent durability standards.
Bio-based and low-VOC paints are formulations using renewable resources like plant oils and containing volatile organic compounds below 50 grams per liter. Their primary purpose is to reduce air pollution while delivering protective and decorative surface finishes. The residential application segment leads in volume, driven by contractor and consumer demand for healthier indoor air quality. Latex product types represent the largest category, favored by DIY consumers and professionals for their ease of use and low odor.
Regulations like the US EPA's National Volatile Organic Compound Emission Standards and the EU's ECHA directives under REACH set strict limits on paint composition. In parallel, China's MEE enforces environmental protection laws that mandate lower VOC content in architectural and industrial coatings. Future competitive advantage will depend on achieving higher bio-based content without compromising paint durability, adhesion, or color stability.
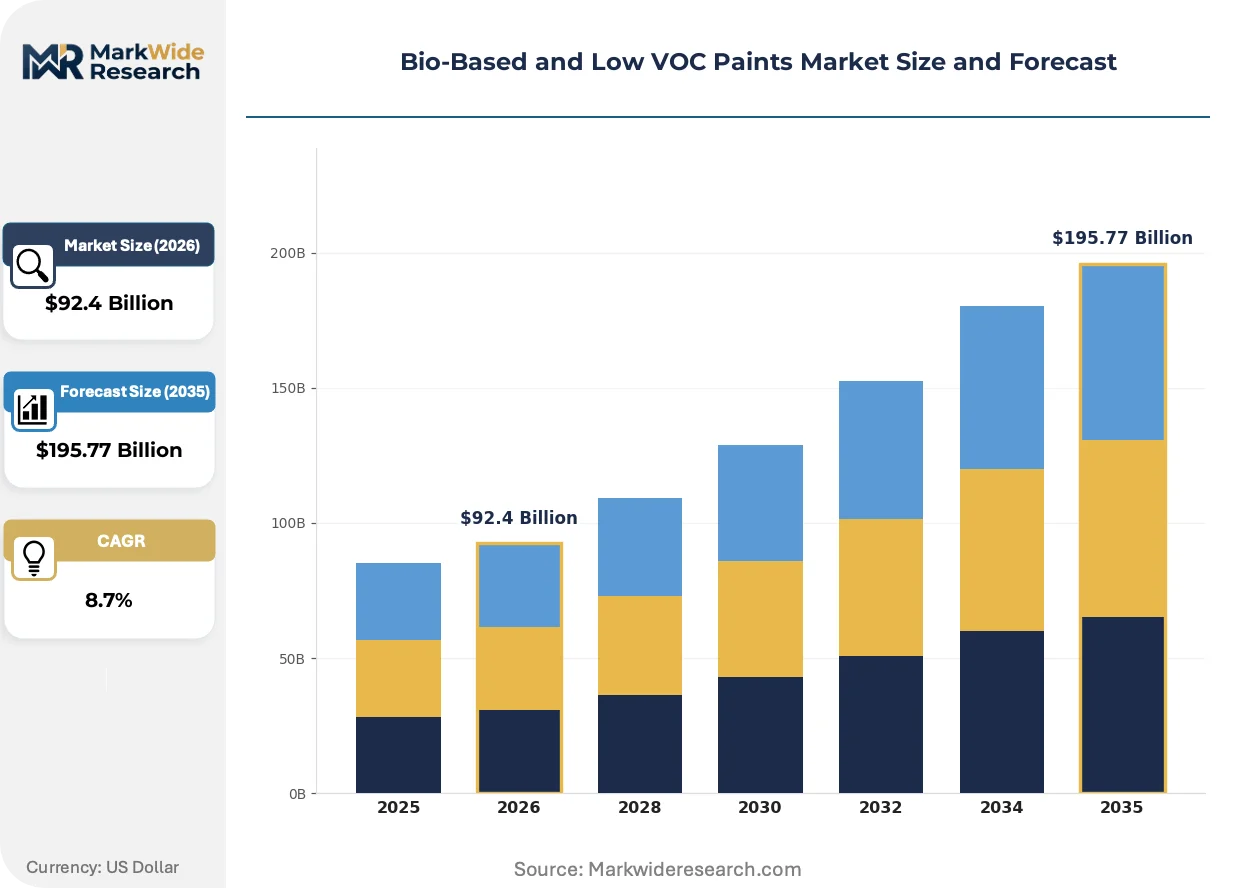
Market Dynamics
The central structural force shaping the market is the dual pressure from stringent global regulations limiting VOC emissions and end-user demand for high-performance coatings. This creates a technical and commercial imperative to innovate bio-based formulations that do not compromise durability.
Growth Catalysts
- EU Green Deal:This policy framework incentivizes the renovation of buildings with sustainable materials, directly increasing the specification of low-VOC and bio-based paints in both new construction and retrofitting projects across member states.
- Residential Health Concerns:Demand from homeowners and contractors for products that improve indoor air quality is a primary catalyst, particularly in the residential segment, where low-odor and non-toxic paint formulations are heavily marketed.
- Chinese Environmental Mandates:Environmental protection laws enforced by China's MEE set strict limits on VOC content in architectural and industrial coatings, compelling both domestic and international manufacturers to reformulate products for this major market.
Market Restraints
- Feedstock Price Volatility:The cost of key bio-based inputs, such as plant oils and starches, is subject to agricultural market fluctuations, creating price instability compared to more predictable petrochemical-derived raw materials.
- Performance Parity Challenges:High bio-content paints can exhibit limitations in durability, adhesion, and color stability, particularly in demanding industrial or exterior applications, when compared to traditional high-performance coatings.
- Regulatory Compliance Costs:The expense and time required to test and certify products against a fragmented landscape of green building standards and eco-labels across different jurisdictions can be a significant barrier for smaller manufacturers.
Strategic Opportunities
- Functional Additives from Bio-Sources:There is a significant opportunity in developing novel, high-performance additives like rheology modifiers and surfactants from bio-based feedstocks, creating a key point of differentiation beyond just the base resin.
- Marine and Protective Coatings:Penetrating the marine coatings segment with bio-based anti-fouling solutions that comply with strict environmental regulations, such as those from the IMO, represents a high-value growth avenue.
- Digital Specification Platforms:Integrating bio-based paint data into Building Information Modeling (BIM) software allows for earlier specification by architects, embedding these products into green building projects from the design phase.
Industry Challenges
- Supply Chain Transparency:Verifying the origin and sustainability credentials of bio-based raw materials throughout a complex global supply chain is a persistent operational challenge, crucial for substantiating marketing claims and meeting certification requirements.
- Consumer Education on Performance:Overcoming lingering perceptions among some end-users that bio-based and low-VOC paints are inherently less durable or offer a poorer finish than traditional solvent-based options requires significant marketing and educational efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Based and Low VOC Paints Market |
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $195.77 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Alkyd, Latex, Epoxy Application: Residential, Commercial, Industrial, Automotive End User: Contractors, DIY Consumers, Manufacturers, Architects Distribution Channel: Retail, Wholesale, E-commerce, Direct Sales |
| Companies Covered | BASF SE, The Sherwin-Williams Company, Akzo Nobel N.V., Benjamin Moore & Co., PPG Industries, Inc., Auro Pflanzenchemie AG, Axalta Coating Systems, LLC, Asian Paints Limited, Nippon Paint Holdings Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Based and Low VOC Paints Market Strategic Shifts & Innovations
The market's evolution is defined by the fusion of advanced material science with digital tools that streamline specification. This combination is enabling the creation of coatings that meet both stringent environmental and performance criteria, shifting the competitive landscape from price to certified value.
Advanced Bio-Resin Development
Novel bio-resins derived from non-food feedstocks like algae and agricultural waste form the next frontier of paint formulation. These materials are being adopted by manufacturers targeting high-end architectural projects where sustainability is a primary design goal. The development of these high-purity binders is converging with the need for coatings that satisfy circular economy principles by reducing reliance on virgin petrochemicals and improving end-of-life options.
Regulatory Tightening in North America
The US EPA's National Volatile Organic Compound Emission Standards continue to place downward pressure on the permissible VOC content in architectural and industrial maintenance coatings. This regulation directly compels manufacturers to innovate and shift production toward water-based latex and acrylic technologies. The architectural coatings segment, in particular, is accelerating its transition to zero-VOC formulations to maintain compliance and appeal to environmentally conscious consumers.
System-Based Specification
A distinct behavioral shift is occurring as specifiers and large contractors move from purchasing individual products to adopting complete, manufacturer-certified coating systems. This change disrupts the traditional distributor channel, which was built on component sales, and favors integrated suppliers who can provide warrantied primer-plus-topcoat solutions. This trend is most advanced in North American and European commercial construction, where green building programs like LEED and BREEAM reward a systemic approach to materials.
Bio-Based and Low VOC Paints Market Segmentation
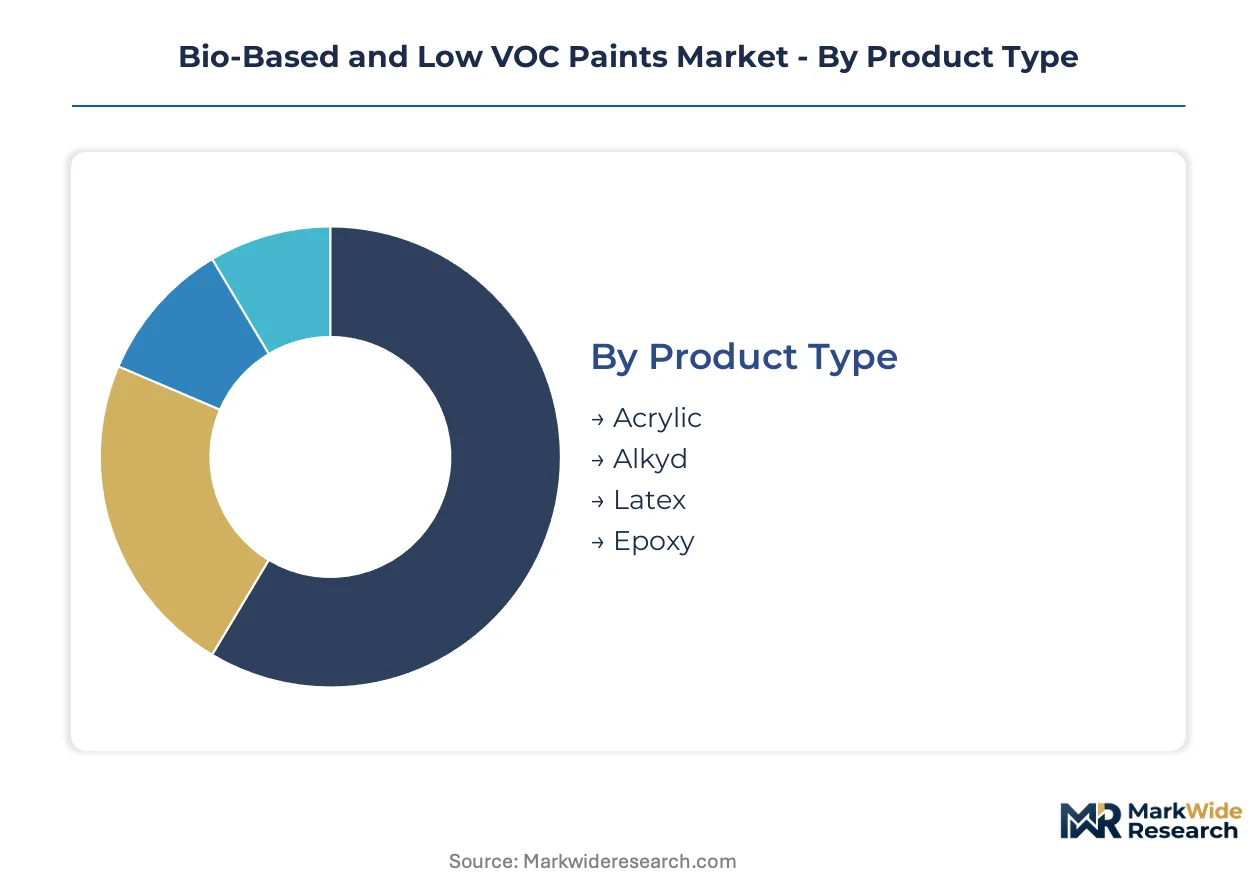
The Bio-Based and Low VOC Paints Market segments reflect distinct material compositions, application requirements, and end-user purchasing behaviors. Understanding these categorizations helps manufacturers align product development with specific demand pockets and regulatory compliance needs. Each segment presents unique challenges and opportunities for market participants.
Product Type:
Supply concentration for bio-based and low VOC paints largely centers on established polymer chemistries that have been reformulated to meet new environmental standards. Manufacturers prioritize these types for their proven performance and adaptability.
- Latex:These water-based formulations feature acrylic or vinyl polymers, offering low odor, quick drying times, and easy cleanup. DIY consumers and professional contractors in the residential segment favor latex products for their user-friendliness and compliance with indoor air quality standards.
- Acrylic:Acrylic paints utilize acrylic polymers, providing excellent durability, color retention, and weather resistance, making them suitable for both interior and exterior applications. Architectural projects in Europe increasingly specify acrylic formulations due to their performance characteristics and low VOC content.
- Alkyd:Alkyd paints are oil-based, traditionally known for their hard, durable finish and good adhesion, though often higher in VOCs. Reformulated low-VOC alkyds now offer improved environmental profiles while retaining durability for industrial maintenance applications.
- Epoxy:Epoxy coatings consist of an epoxide resin and a polyamine hardener, forming a tough, chemical-resistant finish for demanding industrial environments. These specialized systems are critical for protective coatings in manufacturing facilities.
Latex absorbs the bulk of installed capacity; Acrylic is expanding most quickly.
Application:
Demand for bio-based and low VOC paints is primarily driven by specific end-use environments where health and environmental considerations are paramount, influencing material selection and product innovation.
- Residential:This segment includes paints for homes and apartments, focusing on interior air quality, low odor, and aesthetic appeal for homeowners and remodelers. New housing projects in Germany prioritize these coatings to meet stringent green building certifications.
- Industrial:Industrial applications encompass protective coatings for manufacturing plants, infrastructure, and heavy machinery, requiring high durability, chemical resistance, and specific performance standards. Chinese environmental mandates compel manufacturers to supply low-VOC industrial coatings for factories.
- Commercial:Commercial applications cover offices, retail spaces, and public buildings, where durability, maintenance, and occupant well-being are key considerations. Green building programs like LEED in North America encourage low-VOC paint use in new commercial constructions.
- Automotive:Automotive coatings protect vehicle bodies and components, demanding high gloss, chip resistance, and color stability. Reformulated bio-based products are gaining traction in this segment, driven by sustainability targets from major car manufacturers.
The residential segment drives significant volume, while industrial applications present a strong growth trajectory.
End User:
The purchasing decisions for bio-based and low VOC paints are shaped by the specific needs, expertise, and priorities of various professional and individual buyers. Each end user type has distinct procurement patterns and product preferences.
- Contractors:Professional painters and construction firms purchase in bulk for various projects, prioritizing ease of application, consistent performance, and cost-effectiveness. These buyers often specify complete coating systems from major suppliers like Sherwin-Williams.
- DIY Consumers:Individual homeowners undertake painting projects themselves, seeking user-friendly, low-odor products with easy cleanup. Retail channels cater to these consumers with readily available latex formulations.
- Manufacturers:Industrial manufacturers integrate paints into their production processes for finishing products or maintaining facilities. Their focus is on adhesion, durability, and compliance with specific industry standards.
- Architects:Architects specify materials during the design phase of green building projects, prioritizing certified sustainable and healthy building products. Akzo Nobel N.V. targets architects with its high-purity bio-based formulations.
Contractors influence substantial purchasing decisions, with architects increasingly shaping product specification.
Distribution Channel:
The channels through which bio-based and low VOC paints reach end-users vary significantly, impacting market accessibility, pricing, and customer engagement. Each channel serves different customer bases and sales volumes.
- Retail:This channel includes large home improvement stores and specialized paint shops, catering primarily to DIY consumers and small contractors. Sherwin-Williams leverages its extensive retail network to promote integrated solutions.
- Wholesale:Wholesalers supply larger quantities to professional contractors, construction companies, and industrial clients, often offering bulk pricing and specialized product lines. This channel is crucial for high-volume project sales.
- E-commerce:Online platforms provide convenience and a wider selection, appealing to both DIY consumers and smaller contractors seeking specific products or competitive pricing. Digital specification platforms are also emerging here.
- Direct Sales:Manufacturers engage in direct sales for large industrial clients, government projects, or specialized applications, offering custom formulations and technical support. PPG Industries, Inc. often uses direct sales for its industrial coatings.
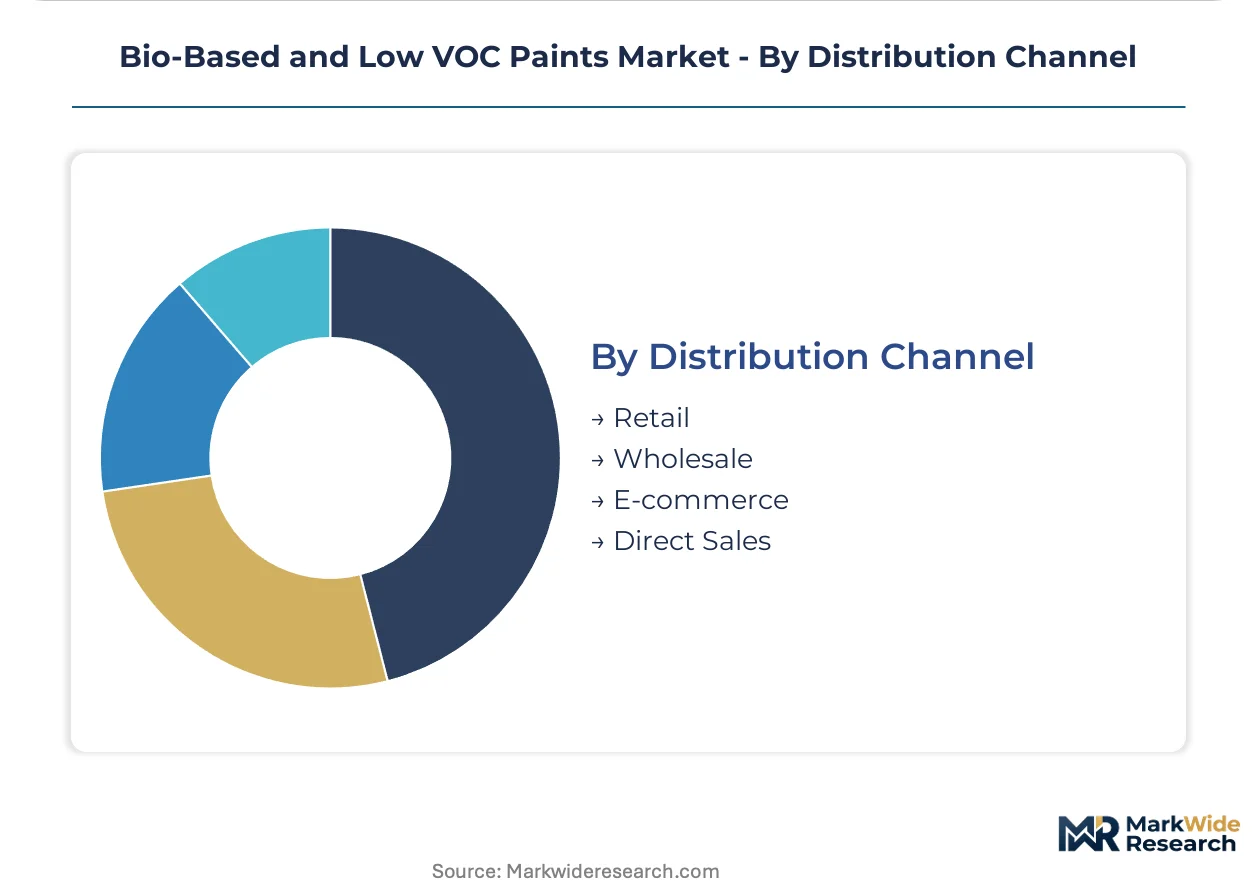
Retail channels provide broad consumer access, while direct sales secure large-scale project commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal, acting as a policy-driven economic zone, significantly drives demand for bio-based and low VOC paints across its member states. This framework incentivizes sustainable construction and renovation, creating specific market concentrations. Global regulatory pressures and consumer health concerns also shape regional market dynamics.
Germany
Germany exhibits strong demand for bio-based and low VOC paints due to stringent green building certification standards. The EU Green Deal further incentivizes sustainable building materials across new construction and retrofitting projects. In Bavaria, architects increasingly specify these coatings for high-performance, environmentally friendly architectural projects.
China
China's market expansion is driven by robust environmental protection laws from the MEE, mandating lower VOC content. This compels manufacturers to reformulate products for both architectural and industrial coatings. Manufacturing hubs within the Yangtze River Delta actively adopt low-VOC industrial coatings for facility maintenance.
United States
United States demand stems from residential health concerns and the preference for healthier indoor air quality. The US EPA's National Volatile Organic Compound Emission Standards place downward pressure on VOC content. California, a leader in green building initiatives, sees accelerated adoption of zero-VOC architectural formulations.
France
French market growth is influenced by green building programs and increasing public procurement of sustainable materials. EU ECHA directives under REACH set strict limits on paint composition, impacting product availability. The Île-de-France region demonstrates strong adoption in commercial and public infrastructure projects.
India
India experiences rising demand from rapid urbanization and a significant construction boom. Evolving national environmental standards and local green building codes increasingly encourage low-VOC paint use. Maharashtra's large-scale residential developments increasingly specify healthier paint options for new housing.
Bio-Based and Low VOC Paints Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the bio-based and low VOC paints market, creating a dynamic competitive environment. The market structure features a tiered landscape, with large integrated chemical companies holding significant sway alongside agile, specialized formulators. Strategic archetypes encompass global coatings manufacturers, regional market leaders, and innovative bio-material developers. Companies primarily focus on portfolio diversification and strategic partnerships to enhance their product offerings and expand market presence.
Scale-driven global players, such as The Sherwin-Williams Company, exemplify extensive retail networks and integrated coating solutions. Akzo Nobel N.V. represents a focus on high-purity bio-based formulations, specifically targeting architects involved in green building projects. PPG Industries, Inc. anchors the segment focused on performance-driven industrial coatings, ensuring its low-VOC products meet stringent durability standards for demanding applications. These companies leverage their established market positions to drive system-based specification, influencing procurement patterns across commercial and residential sectors. Their broad product portfolios and robust distribution channels reinforce their leadership in the global market.
| Leading Market Players |
|---|
| BASF SE |
| The Sherwin-Williams Company |
| Akzo Nobel N.V. |
| Benjamin Moore & Co. |
| PPG Industries, Inc. |
| Auro Pflanzenchemie AG |
| Axalta Coating Systems, LLC |
| Asian Paints Limited |
| Nippon Paint Holdings Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Vertical integration into bio-based raw material processing anchors major paint manufacturers' supply positions, directly influencing their ability to control input costs and exert pricing power across the market.
Pricing Analysis
Premium pricing for short lead times characterizes specialized bio-based paint formulations. Contract-based long-term offtake agreements dominate for large commercial and industrial projects. Pricing stratifies across performance tiers, with certified green building products commanding a premium due to strict LEED and BREEAM compliance and volume scale. Pricing pressure intensifies for standard architectural coatings due to increased competition from water-based latex technologies; DIY consumers exhibit high price sensitivity, while architects prioritize certified value.
Supply Chain Analysis
Logistics and freight costs significantly impact the final price of bio-based and low-VOC paints, particularly for international shipments of specialized raw materials. Supply concentration for plant oils and starches primarily centers in agricultural regions, with key manufacturing hubs for finished products located in Germany, China, and the United States. Raw material supply relies on agricultural market stability, introducing feedstock price volatility as a structural risk. Distribution runs through extensive retail networks for DIY consumers and wholesale channels for contractors, with direct sales securing large industrial commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bio-based and low VOC paints market is undergoing a technology-transition phase, with advanced bio-resins displacing traditional petrochemical-derived binders. This shift demands strategic adjustments across all market participants to capitalize on evolving environmental mandates and consumer preferences.
For Market Incumbents:Deploy significant R&D investment into novel bio-resins from non-food feedstocks to achieve higher bio-based content without compromising performance. Strengthen control over distribution channels, particularly retail networks, to promote integrated low-VOC coating systems directly to contractors and DIY consumers. This strategy counters threats from regulatory tightening by the US EPA and EU ECHA directives. Focus on system-based specification to differentiate from commodity offerings.
For New Entrants and Emerging Players:A price-point gap exists in specialized applications requiring high-performance, bio-based solutions. Target the marine coatings segment with IMO-compliant anti-fouling formulations, or focus on developing novel functional additives from bio-sources. Architects specifying for green building projects represent a highly penetrable segment, valuing certified sustainable materials. Leverage digital specification platforms to integrate product data early into BIM software, gaining visibility from the design phase.
For Investors and Strategic Acquirers:Exit pathways concentrate in specialized formulators with proprietary bio-resin technology or advanced functional additive portfolios. The long-term viability of this market remains strong for companies achieving higher bio-based content without compromising durability. Acquisition targets should possess robust intellectual property in sustainable chemistry and clear paths to scalability. A key signal to watch is the successful commercialization of bio-resins derived from non-food feedstocks like algae, indicating a shift towards circular economy principles.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Bio-Resin R&D | Develops higher bio-content formulations, meeting stringent EU Green Deal standards and reducing petrochemical reliance. |
| Expand System-Based Product Offerings | Shifts buyer preference from single-can purchases, favoring integrated suppliers like Sherwin-Williams in commercial construction. |
| Penetrate Marine Coatings Segment | Addresses strict IMO environmental regulations, opening a high-value growth avenue for specialized bio-based solutions. |
| Integrate into Digital Specification Platforms | Embeds products into green building projects from the design phase, influencing architects and large contractors. |
| Secure Long-Term Bio-Feedstock Contracts | Mitigates feedstock price volatility, ensuring stable input costs for manufacturers of bio-based paints. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing foundational market insights. This analysis combined primary interviews with industry stakeholders, including R&D directors, procurement leads for commercial projects, architects specifying green building materials, and professional contractors. Secondary validation drew from US EPA reports, EU ECHA directives, China's MEE environmental laws, and various green building certification standards. A rigorous bottom-up and top-down triangulation approach ensured data accuracy and consistency.
Data-stream reconciliation integrated historical market performance with projected growth catalysts across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end user, distribution channel, and regional regulatory environment. Compound Annual Growth Rates were derived from historical trends and projected market drivers like the EU Green Deal. Industry-specific forecast inputs included evolving bio-based content targets and tightening VOC emission limits globally.
Inputs from published reports, company disclosures, and expert interviews were available through the study window; gaps in emerging bio-material performance data introduce uncertainty bands. Forecasts reflect assumptions regarding regulatory enforcement and technological advancements, though feedstock price volatility and unexpected regulatory shifts remain risk factors. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Water-Soluble Paints Market
Paints & Coatings
Polyolefin Resin Paints Market
Paints & Coatings
Middle-East and Africa Wood Coatings Market
Paints & Coatings
Nano Paints and Coatings Market
Paints & Coatings
India Automotive Paints and Coatings Market
Paints & Coatings
Cellulose Paints Market
Paints & Coatings
Europe Automotive Paints and Coatings Market
Paints & Coatings
GCC Paints and Coatings Market
Paints & Coatings
South America Paints and Coatings Market
Paints & Coatings
Food Grade Epoxy Paint Market
Paints & Coatings
Global Construction Paints and Coatings Market
Paints & Coatings
Faux Paints and Coatings Market
Paints & Coatings
Anti-Fungal and Anti-Bacterial Paints Market
Paints & Coatings
Global Decorative Coatings Market
Paints & Coatings
Europe Architectural Coatings Market
Paints & Coatings
Faux Finish Coatings Market