
 Alkyd Coatings Market | 2026-2036
Alkyd Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Alkyd Coatings Market Analysis
India is narrowing its alkyd resins deficit through domestic petrochemical capacity additions near Gujarat and Maharashtra. BASF SE leverages backward integration into phthalic anhydride and polyol feedstocks to secure margin stability across Asian supply chains. Akzo Nobel N.V. anchors its position through water-based alkyd technology leadership in European decorative coatings. PPG Industries Inc. competes on automotive refinish specialization, sustaining OEM approval density across North American assembly plants.
Alkyd coatings are thermosetting polyester resins formed by polycondensation of polyhydric alcohols with polybasic acids and fatty acid modifiers, typically cured through oxidative crosslinking at ambient temperatures to form durable, glossy films with excellent adhesion to metal and wood substrates. Their primary commercial purpose centers on protective and decorative finishing across infrastructure, transportation equipment, and consumer goods where cost-performance balance outweighs premium polymer alternatives. Solvent-based alkyds still occupy the largest volume share in industrial maintenance and marine applications, yet water-based formulations are recording the fastest growth as VOC regulations tighten and emulsion polymerization advances close the performance gap. High-performance grades command concentrated margin pools in aerospace and specialty transportation end uses where thermal resistance and chemical durability justify formulation premiums.
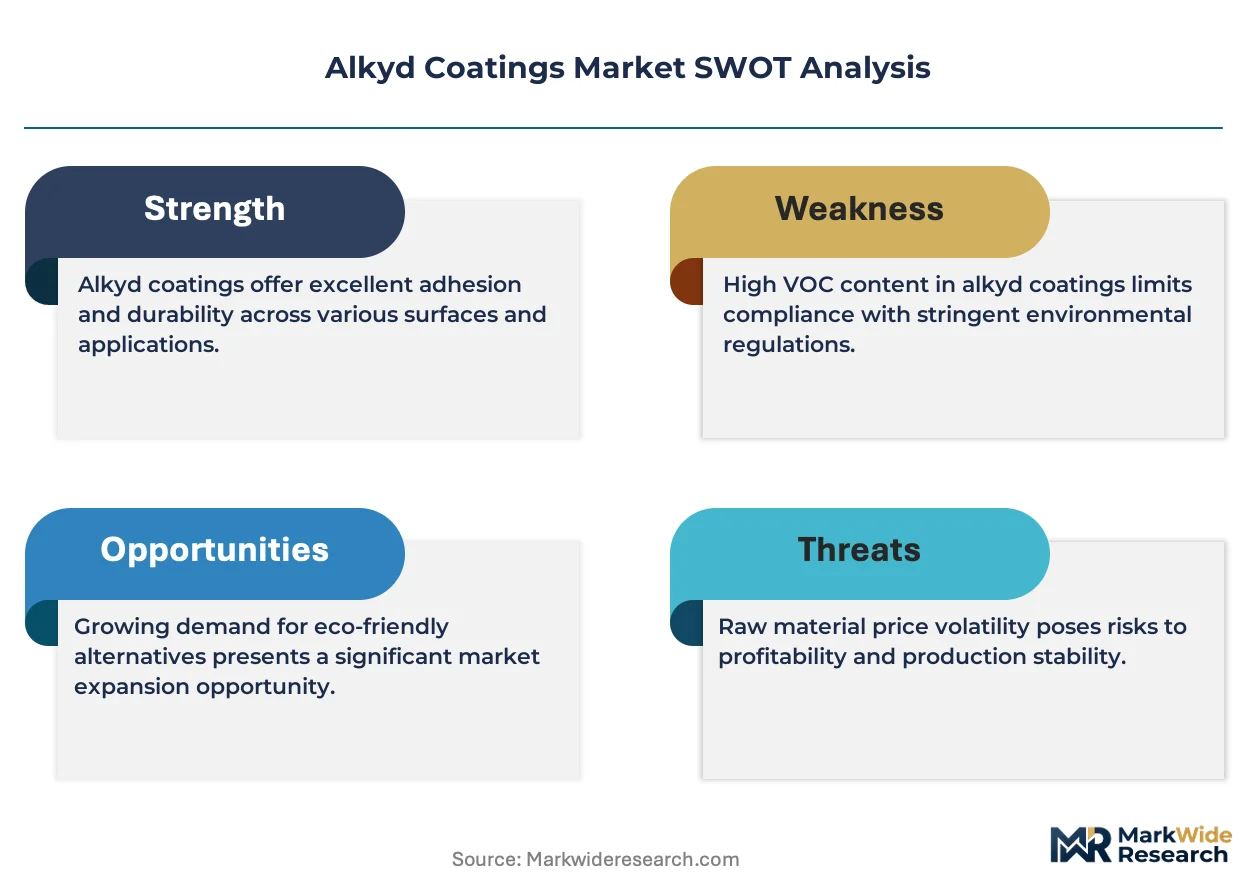
EPA VOC regulations and REACH substance restrictions are reshaping product portfolios, pushing manufacturers toward exempt-solvent and water-reducible systems to maintain market access in regulated jurisdictions. China's MEE enforcement of GB standards on industrial coating emissions is accelerating local reformulation investment, while India's BIS certification requirements for architectural coatings are raising quality barriers for imported products. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned R&D allocation.
Market Dynamics
China's MEE enforcement of GB emission standards is forcing solvent-based alkyd manufacturers into accelerated reformulation cycles, compressing margins while water-based alternatives scale through emulsion polymerization advances.
Growth Catalysts
- Commercial refurbishment cycles:Aging infrastructure across North American and European commercial building stock is generating sustained maintenance coating demand. Building owners prioritize alkyd systems for their balance of durability and cost efficiency in high-traffic interior spaces.
- REACH substance restrictions:ECHA's tightening controls on hazardous air pollutants are redirecting industrial maintenance procurement toward exempt-solvent and water-reducible alkyd formulations. This regulatory pressure is expanding addressable market for compliant coating producers.
- Marine protective specifications:Shipyard maintenance protocols in Japan and South Korea specify alkyd-based primers for ballast tanks and deck structures. Corrosion resistance requirements in saltwater environments sustain premium-grade consumption.
Market Restraints
- Phthalic anhydride cost volatility:Feedstock price swings tied to ortho-xylene supply disruptions constrain resin producer margin stability. Asian petrochemical capacity expansions have not fully eliminated input cost transmission risks.
- Polyurethane substitution in automotive:OEM clearcoat specifications increasingly favor two-component polyurethane systems for superior scratch resistance and UV durability. Alkyd automotive refinish share faces structural compression in premium vehicle segments.
- Solvent-based formulation lock-in:Industrial maintenance contractors in Russia and Middle Eastern markets resist water-based alkyd adoption due to ambient cure performance concerns in high-humidity conditions.
Strategic Opportunities
- India infrastructure build-out:National highway expansion and urban metro construction are accelerating protective coating consumption. Domestic alkyd resin capacity additions near Gujarat reduce import dependency for project contractors.
- UV-curable alkyd hybridization:Convergence of traditional oxidative cure with photoinitiator activation enables faster line speeds in furniture and flooring applications. European decorative coating specialists are piloting these systems for parquet finishing.
- BIS certification barriers:India's mandatory quality standards for architectural coatings are raising compliance costs for imported products. Local formulation expertise becomes a defendable competitive position.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in emulsion polymerization for water-based alkyds concentrates among aging technical workforces in Western Europe and Japan. Knowledge transfer gaps threaten reformulation timelines.
- Legacy equipment retrofit costs:Converting solvent-based production lines to handle water-reducible systems requires tank cleaning infrastructure and humidity-controlled storage. Capital intensity delays conversion decisions for mid-scale coating manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alkyd Coatings Market |
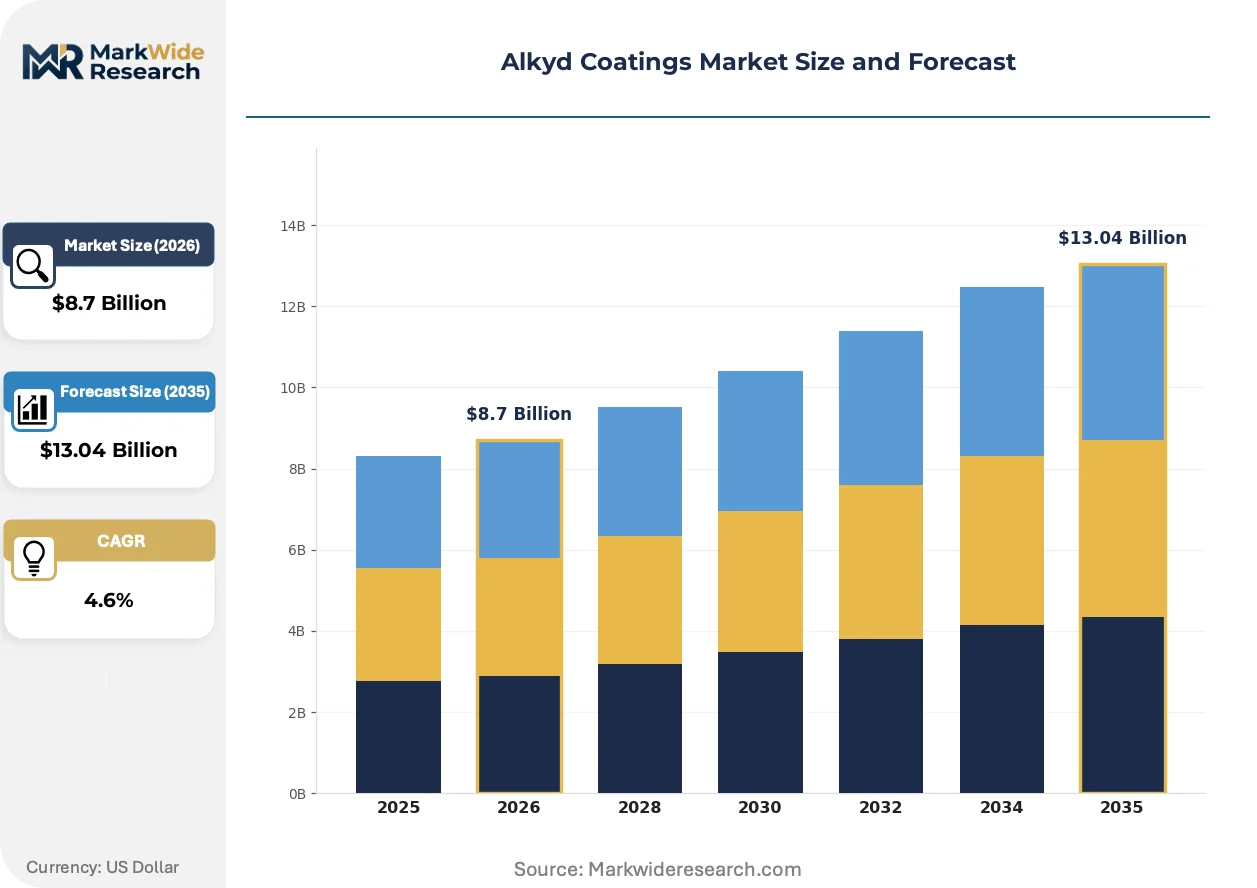
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, High Solids, Powder Coatings Application: Industrial, Automotive, Architectural, Marine End User: Construction, Transportation, Furniture, Aerospace Grade: Standard, High Performance, Eco-Friendly, Specialty |
| Companies Covered | BASF SE, Axalta Coating Systems LLC, Akzo Nobel N.V., Kansai Paint Co Ltd, Jotun A/S, PPG Industries Inc., Nippon Paint Holdings Co Ltd, Hempel A/S, The Sherwin-Williams Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alkyd Coatings Market Emerging Trajectories
Digital formulation tools and predictive curing models are compressing product development cycles while regulatory convergence across major economies is standardizing compliance requirements for coating producers.
Hybrid alkyd-acrylic emulsion technology is virtualizing the performance gap between water-based and solvent-based systems in metal substrate applications. Industrial maintenance contractors in Germany and the Netherlands are adopting these formulations for machinery refinishing. The technology is virtualizing traditional solvent-based specification dominance in corrosion protection segments.
EPA VOC regulations under the National Emission Standards for Hazardous Air Pollutants are mandating coating reformulation across fabricated metal product manufacturing. Compliance deadlines in 2025-2027 are accelerating R&D investment in exempt-solvent systems. Architectural and industrial maintenance segments in California and the Northeast are experiencing the most acute product portfolio pressure.
Specification authority is migrating from general contractors to facility engineering departments with lifecycle cost modeling capabilities. Industrial buyers in the US power generation and chemical processing sectors now require coating performance warranties tied to predictive maintenance data. This shift concentrates procurement decisions among technically sophisticated end-users in the Gulf Coast refining corridor.
Alkyd Coatings Market Segmentation
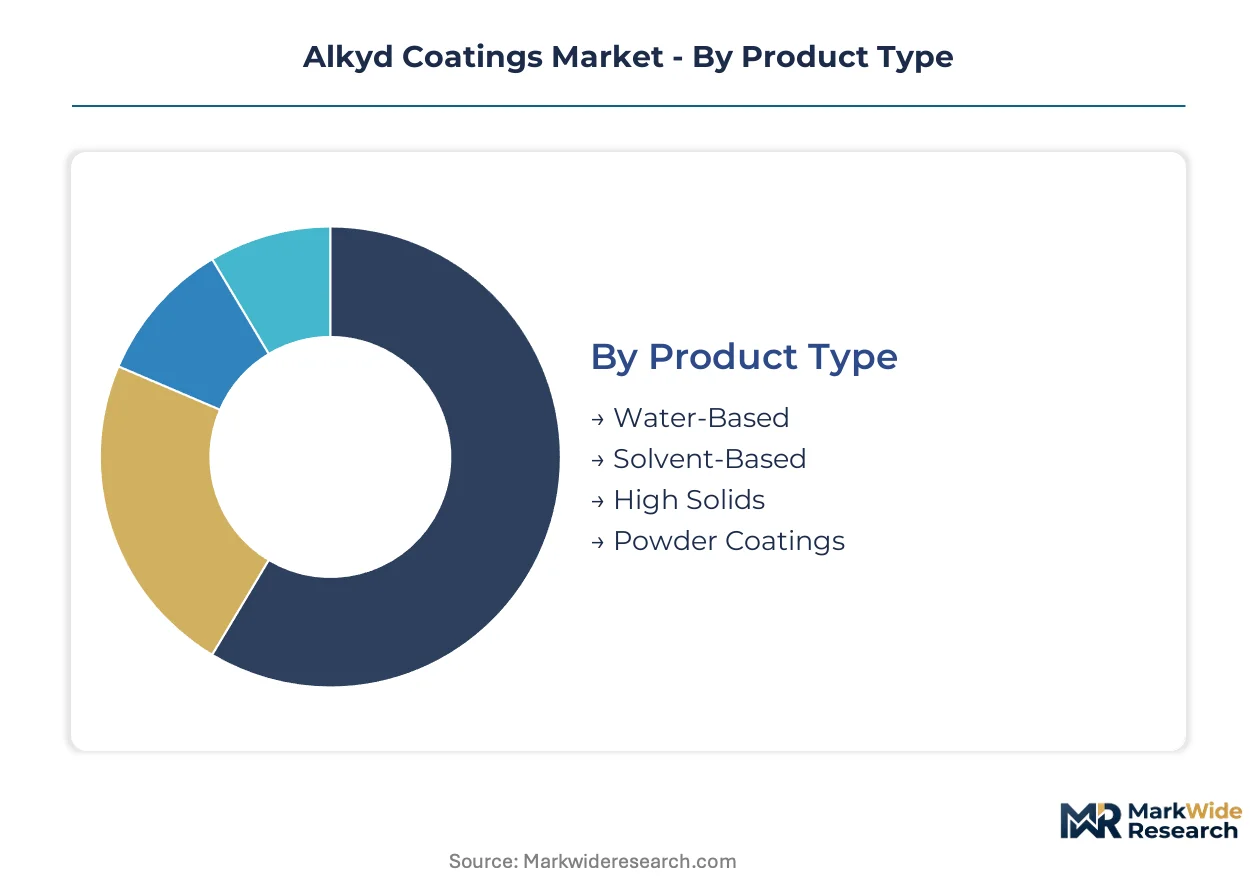
Alkyd coatings serve divergent performance requirements across protective, decorative, and functional applications. Segmentation reveals how formulation chemistry, end-use durability demands, and regulatory exposure create distinct margin architectures and competitive battlegrounds.
Product Type:
Cost tier determines reformulation urgency and capital allocation priorities across manufacturing bases.
- Solvent-Based:Conventional systems rely on mineral spirits or xylene carriers with oxidative cure mechanisms. Industrial maintenance contractors in Russia and the Middle East specify these formulations for ambient cure reliability in high-humidity environments, though MEE enforcement in China is compressing their addressable market.
- Water-Based:Emulsion polymerization advances have closed the adhesion gap on metal substrates. German and Dutch machinery refinishing operations are adopting hybrid alkyd-acrylic emulsions for corrosion protection, with EPA VOC deadlines accelerating R&D investment among US producers.
- High Solids:Reduced solvent content meets exempt-solvent thresholds under REACH restrictions while preserving flow characteristics. European aerospace applicators favor these systems for hangar floor coatings where ventilation constraints limit conventional solvent use.
- Powder Coatings:Thermosetting variants require elevated cure temperatures limiting substrate compatibility. Automotive underhood components and metal furniture frames constitute primary demand concentration.
Solvent-based formulations hold installed capacity. Water-based systems are rotating up the share rankings.
Application:
Application context dictates specification authority and procurement channel structure.
- Industrial:Protective coatings for manufacturing equipment, storage tanks, and processing infrastructure. US power generation and Gulf Coast refining facilities now require performance warranties tied to predictive maintenance data, concentrating procurement among technically sophisticated buyers.
- Architectural:Decorative and protective finishes for commercial building interiors and exteriors. India's BIS certification requirements for imported architectural coatings are raising compliance barriers and defending local formulation expertise.
- Automotive:Refinish clearcoats and OEM primers where scratch resistance and UV durability determine specification. Polyurethane substitution is compressing alkyd share in premium vehicle segments.
- Marine:Ballast tank primers and deck structures in saltwater environments. Japanese and South Korean shipyard maintenance protocols specify alkyd-based systems for corrosion resistance.
Industrial applications anchor volume concentration. Marine specifications are climbing the fastest on specification premiumization.
End User:
Customer type shapes technical service intensity and distribution channel configuration.
- Construction:Infrastructure and building projects drive protective coating consumption. India's national highway expansion and urban metro construction are accelerating demand, with domestic resin capacity additions near Gujarat reducing import dependency.
- Transportation:Rail, commercial vehicle, and ship maintenance operations. Specifications prioritize rapid return-to-service and field applicability under variable ambient conditions.
- Furniture:Wood finishing for residential and commercial interiors. European parquet flooring specialists are piloting UV-curable alkyd hybrids for accelerated line speeds.
- Aerospace:Thermal resistance and chemical durability requirements justify formulation premiums. Specialty grades command concentrated margin pools in this segment.
Construction dominates procurement volume. Aerospace represents the steepest expansion trajectory on performance premium capture.
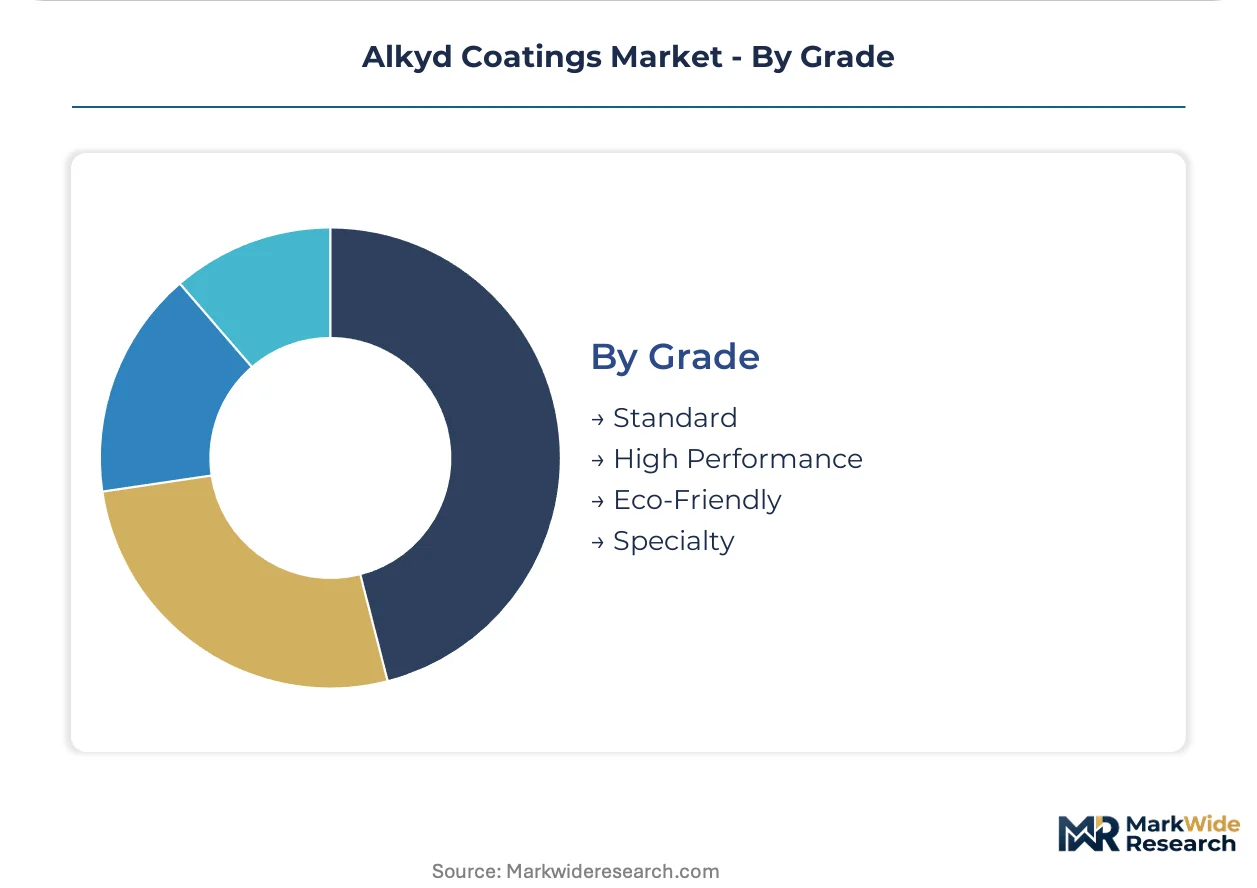
Grade:
Maturity level determines competitive intensity and differentiation latitude.
- Standard:Commodity formulations for general-purpose protective and decorative applications. Price competition intensifies as Asian petrochemical capacity expansions transmit feedstock cost volatility.
- High Performance:Enhanced thermal resistance, chemical durability, and extended service life specifications. These grades sustain margin pools where lifecycle cost modeling dominates procurement decisions.
- Eco-Friendly:Low-VOC and bio-based content variants responding to regulatory pressure. ECHA's tightening hazardous air pollutant controls and EPA NESHAP compliance deadlines are redirecting procurement toward these formulations.
- Specialty:Custom-engineered systems for extreme service conditions or substrate compatibility requirements. Formulation chemist scarcity in emulsion polymerization threatens supply security for water-based specialty grades.
Standard grades hold production scale. Eco-friendly formulations are rotating up the share rankings on regulatory convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China and India deploy alkyd coatings predominantly for industrial maintenance and infrastructure protection, whereas the United States and Germany concentrate consumption in automotive refinish and architectural refurbishment applications with stricter VOC compliance thresholds.
China
Industrial maintenance and marine protective coatings dominate consumption as port infrastructure expansion accelerates along the eastern seaboard. MEE enforcement of GB emission standards is compressing solvent-based formulation margins and forcing accelerated water-based reformulation cycles. Resin production clusters in Shandong and Jiangsu provinces are scaling emulsion polymerization capacity to serve domestic coating manufacturers.
United States
Automotive refinish clearcoats and commercial building refurbishment sustain demand concentration in the Midwest and Southeast manufacturing corridors. EPA NESHAP compliance deadlines through 2027 are mandating exempt-solvent system adoption across fabricated metal product manufacturing. Gulf Coast refining and power generation facilities in Texas and Louisiana now require performance warranties tied to predictive maintenance data.
India
National highway expansion and urban metro construction are accelerating protective coating procurement for infrastructure steel structures. BIS certification requirements for imported architectural coatings are raising compliance barriers and defending domestic formulation expertise. Domestic alkyd resin capacity additions near Gujarat and Maharashtra are narrowing import dependency for project contractors.
Germany
Machinery refinishing operations in the Ruhr industrial basin and Bavarian manufacturing zones specify hybrid alkyd-acrylic emulsions for corrosion protection. REACH substance restrictions on hazardous air pollutants are redirecting procurement toward water-reducible and exempt-solvent formulations. Stuttgart and Munich aerospace clusters sustain premium-grade consumption for thermal-resistant hangar floor coatings.
Japan
Shipyard maintenance protocols in Nagasaki and Kure specify alkyd-based primers for ballast tanks and deck structures in saltwater environments. METI industrial standards are tightening VOC thresholds for marine coating applications. Osaka and Yokohama industrial coating distributors are consolidating technical service capabilities around lifecycle cost modeling for refinery and chemical processing clients.
Alkyd Coatings Market Vendor Landscape
Capability concentration sits with specialty formulation chemists in Western Europe and Japan; scale advantage sits with integrated petrochemical producers commanding backward integration into phthalic anhydride and polyol feedstocks. The vendor base stratifies across three tiers: multinational coating specialists with OEM approval density, regional resin producers with domestic supply chain control, and niche applicators serving single-industry end uses. Dominant competitive moves include capacity expansion near Gujarat and Maharashtra to serve Indian infrastructure demand, and technology licensing partnerships to transfer emulsion polymerization expertise across jurisdictions.
Among European-integrated multinationals, BASF SE and Akzo Nobel N.V. occupy positions exemplifying feedstock control and water-based technology leadership respectively. PPG Industries Inc. anchors the North American automotive refinish specialization tier. These three represent distinct strategic archetypes: petrochemical backward integration, regulatory-compliant formulation R&D, and OEM certification density in transportation end uses.
| Leading Market Players |
|---|
| BASF SE |
| Axalta Coating Systems LLC |
| Akzo Nobel N.V. |
| Kansai Paint Co Ltd |
| Jotun A/S |
| PPG Industries Inc. |
| Nippon Paint Holdings Co Ltd |
| Hempel A/S |
| The Sherwin-Williams Company |
| Others |
Supply Flow & Price Mechanics
Shanghai-Rotterdam container freight corridors transmit ortho-xylene cost volatility into European alkyd resin quotations, compressing margins for non-integrated formulators while rewarding backward-integrated producers with captive phthalic anhydride supply. This logistics-cost asymmetry stratifies pricing power across supply chain tiers, with feedstock-advantaged multinationals commanding premium-grade spreads and import-dependent regional blenders competing on volume discounts in commodity architectural segments.
Pricing Analysis
Geographic price spreads between Asian export hubs and European inland markets reflect feedstock integration differentials and regulatory compliance cost layering. Three-tier pricing structure across high-performance, standard, and economy grades separates aerospace specification premiums from commodity architectural volumes. Pricing pressure stems from phthalic anhydride cost volatility transmitted through ortho-xylene supply disruptions. Construction contractors in India's highway expansion programs exhibit highest price sensitivity, while Gulf Coast refining facilities accepting performance-warranty terms demonstrate lowest.
Supply Chain Analysis
Extended payment terms from state-owned infrastructure contractors in India and China strain working capital for mid-scale resin producers, accelerating consolidation toward balance-sheet-strong multinationals. Supply concentrates in China, India, and Germany, with Shandong and Jiangsu province clusters dominating emulsion polymerization capacity. Feedstock dependencies center on ortho-xylene, phthalic anhydride, and polyol streams. Single-source vulnerability in Asian petrochemical feedstock channels threatens margin stability. Distribution runs through technical service-intensive direct sales for industrial maintenance and project-contractor channels for infrastructure applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Alkyd coatings function as a service-attach business where predictive maintenance warranties and application technical support expand faster than resin volume, rewarding formulation expertise over commodity production scale.
For Market Incumbents: Entrench through backward integration into phthalic anhydride and polyol feedstocks to neutralize ortho-xylene cost volatility, while accelerating water-based emulsion polymerization R&D to preempt REACH and EPA compliance deadlines. Polyurethane substitution in automotive clearcoats demands defensive specialization in refinish application technical service. Capacity additions near Gujarat defend Indian infrastructure procurement share against import competition.
For New Entrants and Emerging Players: Pursue BIS certification-compliant architectural formulation in India, where domestic resin capacity additions reduce import dependency and compliance barriers defend local expertise. UV-curable alkyd hybridization for European parquet flooring offers penetrable white-space with faster line-speed value propositions. Partner with German or Dutch machinery refinishing distributors for corrosion-protection specification entry.
For Investors and Strategic Acquirers: Carve-out targets emerge from petrochemical conglomerates with non-core coating resin divisions lacking water-based formulation capabilities. Long-term viability hinges on regulatory-compliant technology ownership and geographic proximity to infrastructure demand clusters. Watch EPA NESHAP compliance deadline adherence as inflection indicator for US market access retention.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phthalic Anhydride | Captive feedstock supply neutralizes ortho-xylene price volatility for BASF and Asian petrochemical majors. |
| Water-Based Emulsion Polymerization Scale-Up | REACH and MEE compliance deadlines force solvent-based line conversions among European and Chinese producers. |
| BIS Certification Investment | Quality barriers defend domestic Indian formulators against imported architectural coating competition. |
| UV-Curable Alkyd Hybrid Development | European parquet specialists adopt photoinitiator-activated systems for accelerated furniture finishing line speeds. |
| Gujarat-Maharashtra Capacity Expansion | Domestic resin supply reduces import dependency for Indian national highway and metro construction contractors. |
Methodological Framework
Cross-validation between primary interviews with plant managers, procurement leads at downstream OEMs, coating distribution channel partners, and technical R&D directors anchors the qualitative findings against customs trade data, ACC and Cefic industry reports, SEC 10-K filings, and national emission standard enforcement disclosures. Bottom-up volume modeling triangulates with top-down value chain analysis across feedstock, resin synthesis, formulation, and application tiers.
Calibration against historical capacity utilization rates and regulatory compliance cost trajectories shapes the projection framework across the analysis window. Segmentation dimensions include formulation chemistry tier, end-use industry vertical, substrate application method, and regional regulatory cluster. CAGRs derive from demand elasticity modeling against infrastructure investment cycles and automotive production forecasts. Feedstock price transmission coefficients and emulsion polymerization adoption curves constitute industry-specific forecast inputs.
Sensitivities concentrate around MEE enforcement intensity in China, EPA NESHAP compliance deadline adherence, and ortho-xylene supply disruption frequency. Forecasts reflect documented assumptions on regulatory convergence timing and petrochemical capacity expansion realization. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Middle East and Africa Floor Coatings Market
Paints & Coatings
Saudi Arabia Architectural Paints Market
Paints & Coatings
Paints and Coatings Market
Paints & Coatings
Global Thinners and Paint Strippers Market
Paints & Coatings
Asia-Pacific Paints and Coatings Market
Paints & Coatings
Qatar Paints and Coatings Market
Paints & Coatings
Global Decorative Coatings Market
Paints & Coatings
Road Marking Paints and Coatings Market
Paints & Coatings
Paint Curing Lamp Market
Paints & Coatings
Water-Borne Latex Paints Market
Paints & Coatings
Middle East & Africa Corrosion Protection Coating Market
Paints & Coatings
Cellulose Paints Market
Paints & Coatings
Global Aerosol Paints Market
Paints & Coatings
Epoxy Paint Thinner Market
Paints & Coatings
Resins in Paints and Coatings Market
Paints & Coatings
Europe Paints and Coatings Market