
 Decorative Paints Market | 2026-2036
Decorative Paints Market Size, Share, and Industry Trends Forecast 2026-2036
Decorative Paints Market Analysis
India's western manufacturing corridor is narrowing the supply gap for decorative coatings serving both domestic consumption and regional export. Sherwin-Williams Company leverages its North American retail network to sustain brand visibility in the professional painter segment. AkzoNobel N.V. anchors its European position through specialized color-matching technology and architectural specification relationships. Asian Paints Ltd. dominates India's decorative segment with extensive distribution control reaching tier-three towns.
Decorative paints encompass pigmented liquid coatings formulated with binders, solvents, and additives that cure to form protective and aesthetic films on interior and exterior substrates, typically applied at dry film thicknesses of 25–75 microns for residential surfaces. Their primary commercial purpose is to provide weather resistance, substrate protection, and color customization for buildings and structures. Water-based acrylic formulations lead volume in residential applications due to faster drying and lower odor profiles, while oil-based alkyd systems retain share in trim and high-durability commercial finishes where hardness and gloss retention command premium positioning. The matte finish category occupies the largest share of interior residential specification, though satin and eggshell variants are gaining traction in commercial spaces requiring washability without full gloss reflectance.
EPA regulations on volatile organic compound emissions restrict solvent-based paint sales in the United States, while REACH registration requirements in Europe impose chemical disclosure and substitution obligations on coating manufacturers. India's BIS certification mandates product quality benchmarks for imported and domestically produced decorative coatings. China's MEE enforcement of air quality standards in the Yangtze River Delta has shuttered non-compliant coating facilities and consolidated production among larger enterprises. Stakeholders must monitor evolving low-carbon building codes and bio-based binder technologies that will determine formulation roadmaps and capital allocation priorities.
Market Dynamics
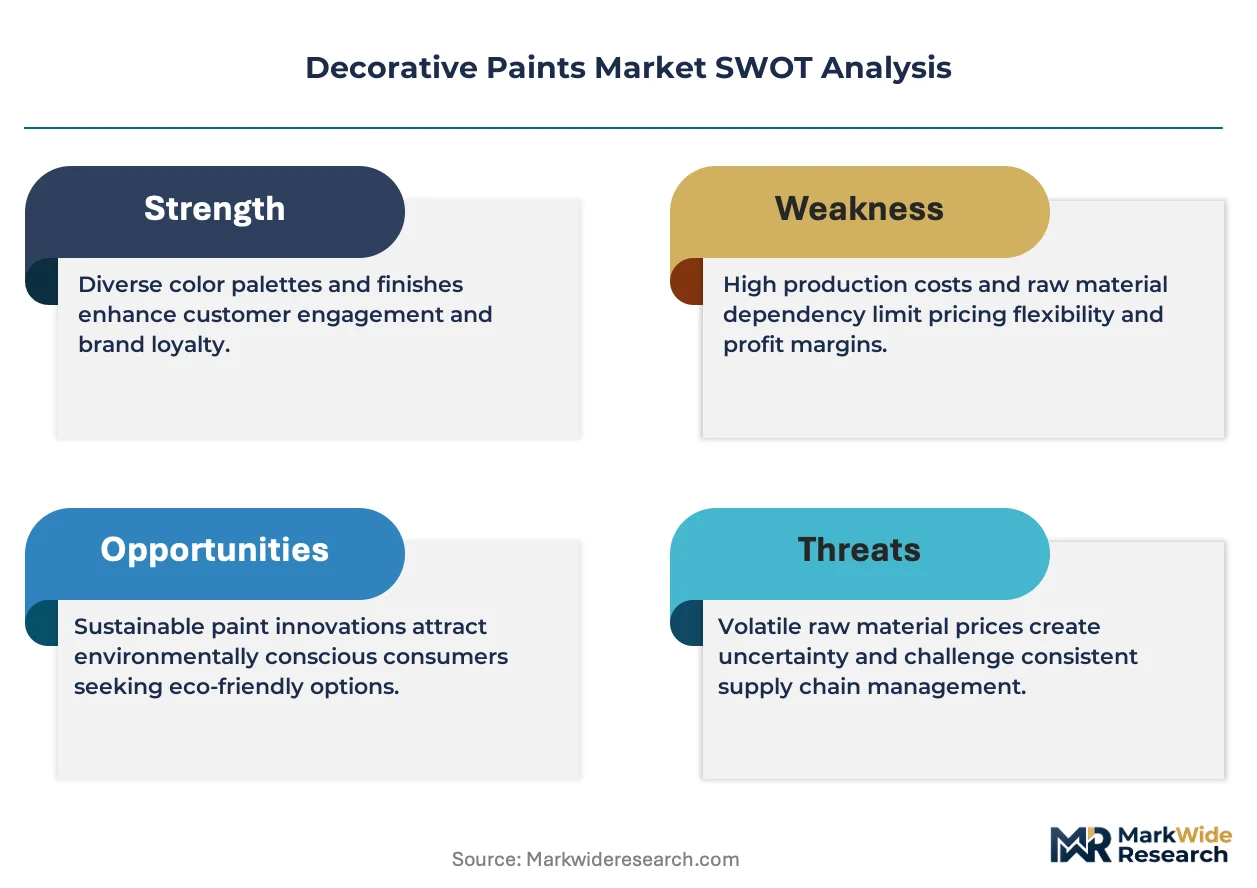
Water-based chemistry migration is compressing solvent-based capacity across major manufacturing basins, forcing reformulation investments and facility retooling decisions that will determine competitive positioning through the forecast window.
Growth Catalysts
- Low-VOC mandates:EPA emission restrictions in the United States redirect residential specification toward compliant water-based acrylic systems, expanding addressable volume for certified suppliers.
- Suburban renovation cycles:India's tier-two and tier-three towns are entering active repainting phases as housing stock matures, pulling premium interior finishes into markets previously served by economy grades.
- Color-matching digitization:Spectrophotometer-based tinting systems reduce waste and enable same-day fulfillment, compressing project timelines for professional applicator segments.
Market Restraints
- Titanium dioxide volatility:Pigment input costs swing with mining output from South African and Chinese ore processors, compressing margin predictability for mid-tier producers.
- Alkyd capacity concentration:Solvent-based manufacturing clusters in China's Shandong province face MEE air quality enforcement, creating supply uncertainty for trim and high-durability commercial grades.
- Curing time limitations:Water-based exterior formulations require extended dry windows in high-humidity climates, restricting application season length in coastal Indian and Southeast Asian markets.
Strategic Opportunities
- Bio-based binder development:Plant-derived alkyd alternatives from European specialty chemical suppliers open premium positioning for sustainability-specified architectural projects.
- Professional painter channel digitization:Mobile-enabled direct ordering platforms bypass traditional distributor markups, capturing margin and purchase data in India's fragmented contractor base.
- EU Green Deal alignment:CSRD disclosure requirements and embodied carbon tracking for construction materials create specification pull for verified low-carbon coating systems in commercial newbuild.
Industry Challenges
- REACH substitution timelines:ECHA candidate list reviews force rapid reformulation of legacy biocide and solvent packages, compressing R&D-to-registration cycles.
- Skilled applicator scarcity:Spray equipment operation and substrate preparation expertise gaps in emerging markets elevate defect rates and warranty claims for premium system sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decorative Paints Market |
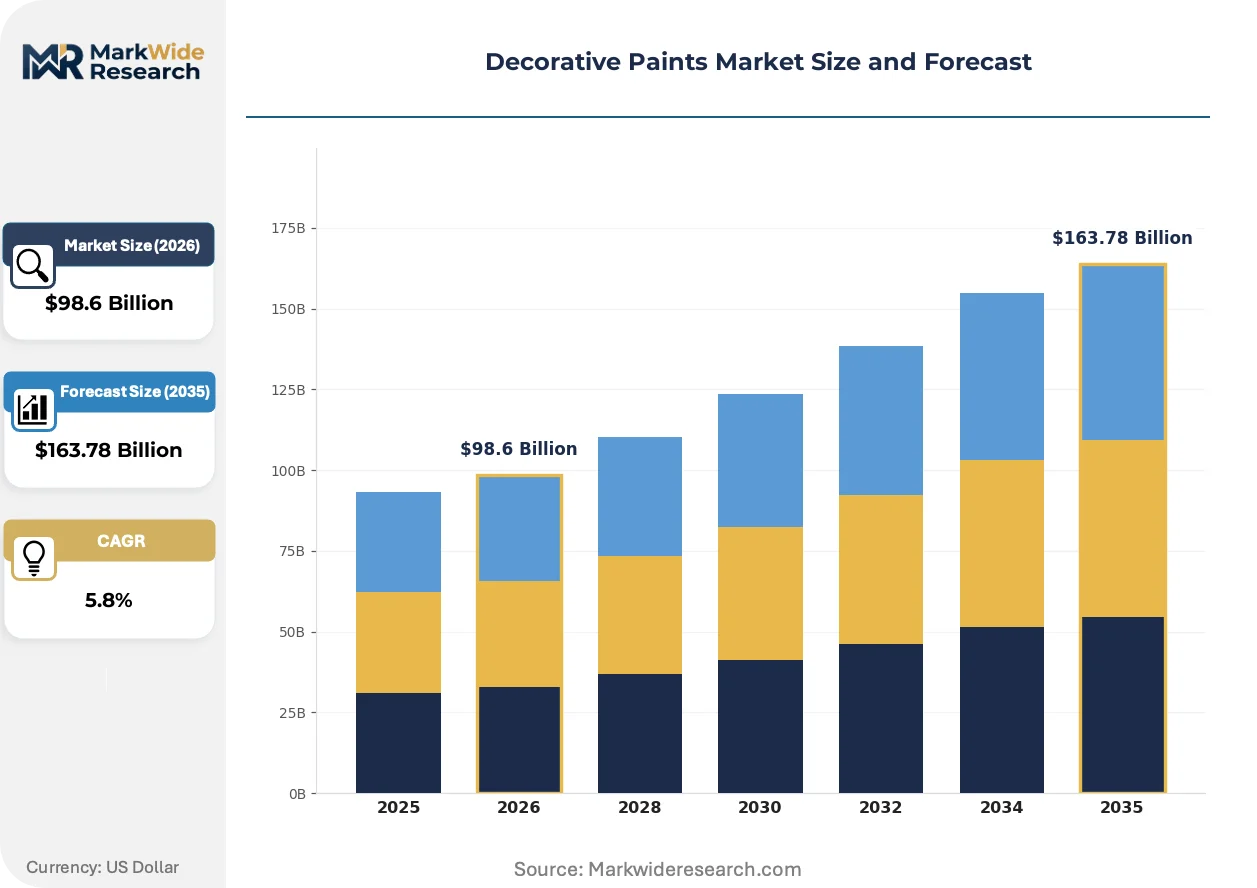
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $163.78 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Latex, Oil-based, Water-based Application: Residential, Commercial, Industrial, Automotive Finish Type: Matte, Gloss, Satin, Eggshell Distribution Channel: Retail, Online, Wholesale, Direct Sales |
| Companies Covered | Sherwin-Williams Company, PPG Industries Inc., AkzoNobel N.V., Nippon Paint Holdings Co., Ltd., Asian Paints Ltd., BASF SE, RPM International Inc., Jotun Group, Axalta Coating Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decorative Paints Market Emerging Trajectories
Formulation science and specification workflows are converging around environmental performance metrics, compressing traditional quality-price hierarchies and enabling new entry paths for technology-backed suppliers.
Spectrophotometric color matching is digitizing the specification-to-application workflow, enabling real-time formula retrieval from cloud databases. Large residential developers in China's tier-one cities now mandate digital color confirmation prior to bulk orders, eliminating batch-to-batch visual variance disputes. This compression of the approval cycle is digitizing inventory management for distributor networks, reducing working capital requirements and obsoleting physical color card libraries.
REACH authorization procedures are tightening biocide and solvent substance approvals, forcing disclosure of full supply chain chemistry. European coating manufacturers face substitution deadlines for chromate corrosion inhibitors and certain isothiazolinone preservatives, redirecting R&D spend toward in-can stabilization alternatives. The decorative segment's DIY retail channel absorbs compliance cost pass-through most visibly, with professional specification markets demanding documentary evidence for green building certification submissions.
Direct contractor engagement models are displacing traditional distributor relationships in high-velocity renovation markets. Professional painting crews in India's western corridor now source materials through mobile platforms offering credit terms and same-day delivery, bypassing multi-tier distribution. This channel compression concentrates purchase data with platform operators, enabling predictive inventory positioning that reduces stockout frequency during monsoon-season application windows.
Decorative Paints Market Segmentation
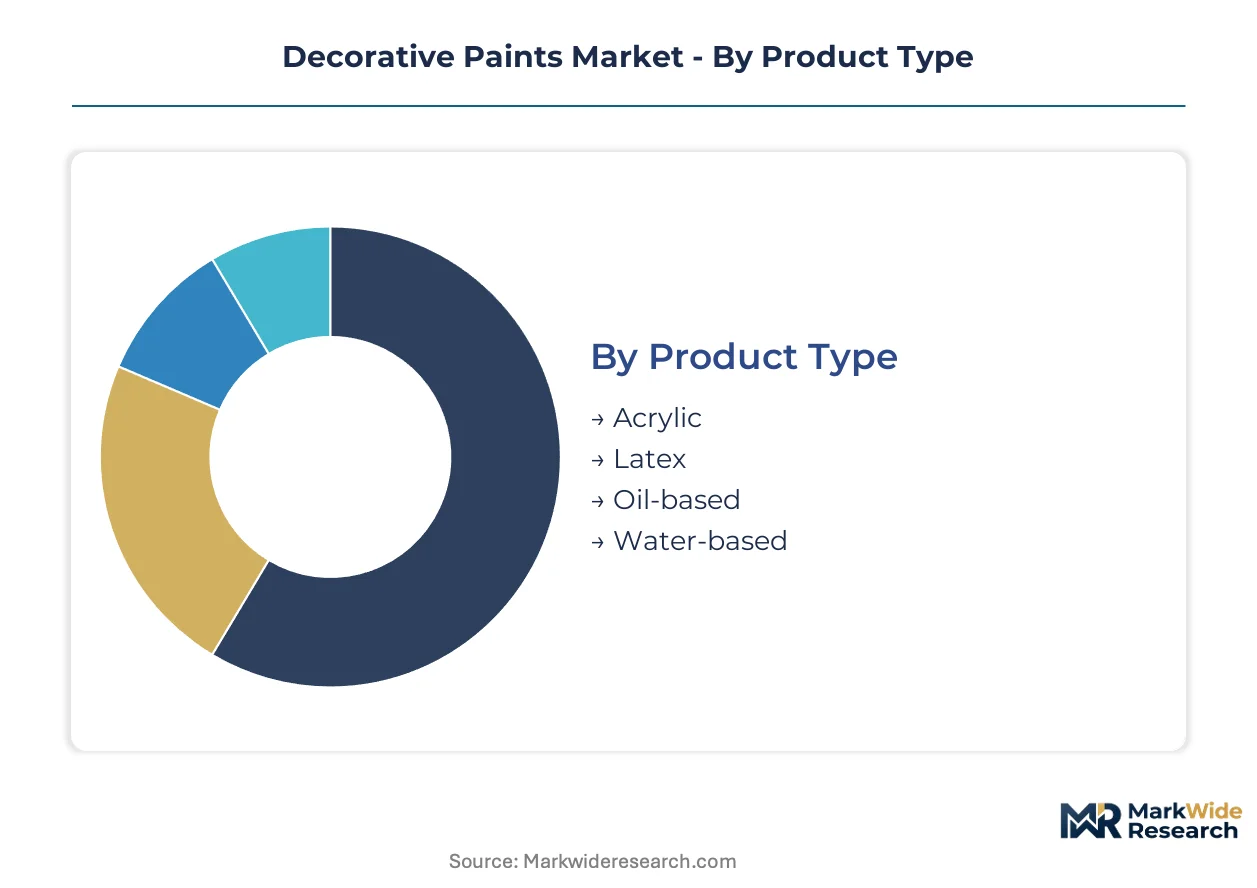
Segmentation in decorative paints reveals divergent reformulation cycles and channel economics across chemistry types and end-use specifications. Understanding turnover velocity by segment enables capital allocation toward faster-rotating inventory positions and longer-duration specification relationships.
Product Type:
Cycle times vary sharply across chemistries, with water-based systems turning inventory fastest due to shorter shelf lives and regulatory-driven specification shifts, while oil-based alkyds move slowly through professional contractor stockpiles.
- Water-based:Acrylic and vinyl-acrylic emulsions dominate residential interior specification, curing through coalescence rather than solvent evaporation. Demand concentrates in China's tier-one cities and India's western corridor, where low-VOC mandates from EPA and MEE enforcement eliminate solvent-based alternatives from new construction tenders.
- Acrylic:Pure acrylic binders deliver superior exterior durability and UV resistance, commanding premium positioning in coastal and high-humidity climates. Specification concentrates in commercial newbuild across Southeast Asia, where extended monsoon seasons demand hydrophobic film formation and chalking resistance.
- Latex:Vinyl-acrylic copolymers serve economy residential segments with adequate washability at lower binder cost. Demand clusters in India's tier-three towns entering first renovation cycles.
- Oil-based:Alkyd systems retain share in trim, cabinetry, and high-traffic commercial floors where hardness and gloss retention justify solvent handling costs. Supply uncertainty from Shandong province MEE enforcement compresses availability for North American import-dependent contractors.
Water-based dominates installed base. Acrylic is where expansion concentrates.
Application:
Margin structures diverge across end-use segments, with industrial specifications demanding certified performance documentation and residential markets absorbing price sensitivity through distributor-promoted economy tiers.
- Residential:Single-family and multi-family housing drives volume through renovation-triggered repurchase cycles. Demand concentrates in suburban India and China's tier-two cities, where housing stock maturation overlaps with rising premium interior finish specification.
- Commercial:Office, retail, and hospitality newbuild requires washability, stain resistance, and accelerated curing to compress construction schedules. Specification concentrates in EU Green Deal-aligned projects demanding embodied carbon disclosure and CSRD-compliant supply chain documentation.
- Industrial:Factory and warehouse coatings prioritize chemical resistance and rapid return-to-service. Procurement shifts toward direct manufacturer relationships bypassing distributor markups for volume accounts.
- Automotive:Refinish and OEM touch-up applications demand color-matching precision and chip resistance. Digitization of spectrophotometer-based tinting systems compresses approval cycles for collision repair networks.
Residential commands volume share. Commercial is climbing the fastest on sustainability specification.
Finish Type:
Sheen selection maps directly to functional requirements and substrate positioning, with matte absorbing imperfections on older walls while gloss delivers durability on trim and high-contact surfaces.
- Matte:Flat finishes minimize surface preparation requirements and conceal substrate irregularities on ceilings and aging plaster. Specification dominates residential interiors across Europe and India, where renovation economics favor minimal prep labor.
- Satin:Low-luster sheen balances washability with subdued reflectance, gaining specification in commercial spaces requiring periodic cleaning without full gloss glare. Demand accelerates in healthcare and education verticals.
- Eggshell:Slightly higher sheen than satin delivers improved scrub resistance for residential living areas and corridors. Preference concentrates in North American mid-market housing where durability expectations exceed matte performance.
- Gloss:High-reflectance films provide moisture resistance and easy cleaning on trim, doors, and cabinetry. Oil-based alkyd gloss retains professional painter preference for flow and leveling despite water-based migration.
Matte dominates installed base. Satin is gaining share fastest on commercial washability requirements.
Distribution Channel:
Channel economics are compressing traditional multi-tier structures, with mobile-enabled direct platforms capturing contractor purchase data and inventory positioning advantages.
- Retail:Big-box and specialty paint stores serve DIY consumers and small contractors with immediate pickup and color-matching services. Foot traffic concentrates in North American suburban corridors where homeowner renovation cycles drive impulse premium upgrades.
- Online:E-commerce platforms aggregate economy and mid-tier SKUs for delivery to residential and small commercial accounts. Growth concentrates in India's fragmented contractor base, where credit-enabled mobile ordering bypasses distributor working capital constraints.
- Wholesale:Distributor networks maintain bulk inventory for professional painting crews and general contractors. Concentration persists in tier-two and tier-three Indian towns where physical credit relationships and same-day availability outweigh platform convenience.
- Direct Sales:Manufacturer-to-contractor relationships capture large project specification and volume pricing. Procurement is shifting toward data-enabled inventory management for monsoon-season application windows.
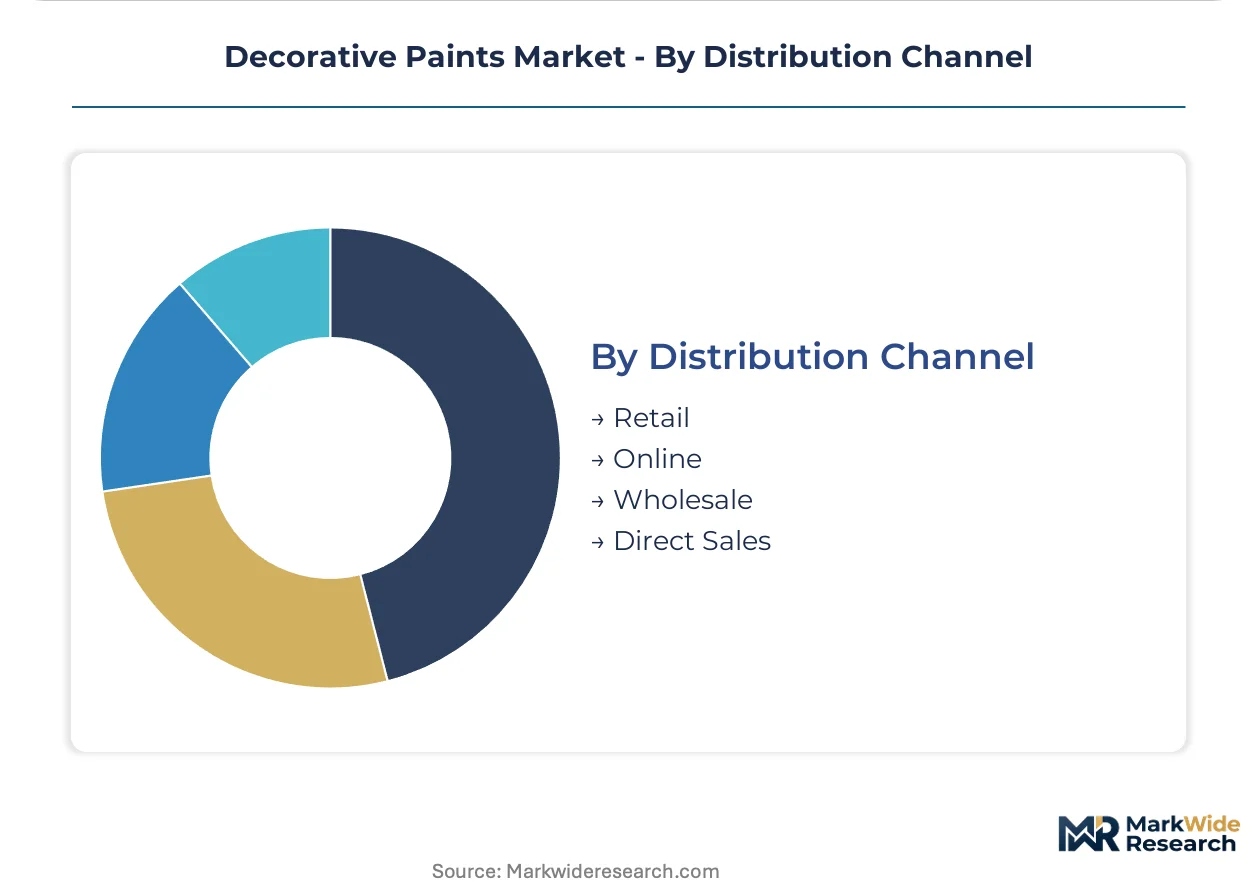
Retail dominates installed base. Online is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Decorative paint consumption patterns diverge sharply by geography, with developed markets prioritizing low-carbon specification and renovation-grade premium finishes while emerging economies concentrate on new construction volume and first-cycle repainting demand.
United States
Residential renovation activity drives specification toward water-based acrylic systems compliant with EPA volatile organic compound emission restrictions. Professional painting crews dominate procurement, with color-matching digitization compressing project approval timelines. Supply concentrates in the Midwest and Southeast manufacturing corridors serving suburban housing markets.
Germany
Commercial newbuild and heritage restoration create dual demand streams for sustainable coating systems aligned with EU Green Deal embodied carbon tracking. REACH authorization procedures force rapid biocide substitution, redirecting formulation investments toward in-can stabilization alternatives. Production clusters in North Rhine-Westphalia supply certified systems across the European Union.
China
Tier-one cities generate overlapping demand from new construction and accelerated repainting cycles, while MEE air quality enforcement in the Yangtze River Delta consolidates production among compliant large-scale manufacturers. Digital color confirmation mandates from large residential developers compress inventory cycles for distributor networks.
India
Tier-two and tier-three towns enter active renovation phases as housing stock matures, pulling premium interior finishes into markets previously served by economy grades. BIS certification mandates quality benchmarks for both imported and domestically produced coatings. Manufacturing concentrates in Gujarat and Maharashtra serving western corridor consumption and regional export.
Brazil
Urban residential construction in São Paulo and Rio de Janeiro sustains volume demand for economy and mid-tier water-based systems. ANVISA regulatory frameworks govern chemical disclosure for architectural coatings. Distribution runs through multi-tier wholesale networks serving informal contractor segments in expanding metropolitan peripheries.
Decorative Paints Market Vendor Landscape
Capability concentration sits with specialized coating formulators possessing color-matching technology and specification relationships; scale advantage sits with integrated chemical conglomerates controlling binder supply chains. The market structures around three tiers: global diversified coatings groups, regional decorative specialists with distribution depth, and commodity manufacturers serving price-sensitive construction markets. Dominant competitive moves include direct contractor platform development bypassing traditional distribution, and backward integration into titanium dioxide and acrylic binder production to secure margin against input volatility.
Within the global diversified tier, Sherwin-Williams Company and PPG Industries Inc. exemplify North American scale advantages anchored in retail network density and professional painter channel relationships. AkzoNobel N.V. represents the European specialist archetype with specification-driven positioning in architectural color systems. Asian Paints Ltd. occupies a distinctive position as a distribution-integrated operator controlling tier-three town penetration in high-velocity emerging markets.
| Leading Market Players |
|---|
| Sherwin-Williams Company |
| PPG Industries Inc. |
| AkzoNobel N.V. |
| Nippon Paint Holdings Co., Ltd. |
| Asian Paints Ltd. |
| BASF SE |
| RPM International Inc. |
| Jotun Group |
| Axalta Coating Systems |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta freight corridor carries titanium dioxide and acrylic binder shipments from Shandong and Jiangsu manufacturing clusters to coastal export terminals, with its container rates compressing margin structures for water-based emulsion producers while amplifying price differentiation between certified low-VOC formulations and uncertified economy grades.
Pricing Analysis
Geographic price spreads between China's tier-one cities and India's tier-three towns exceed the cost-of-delivery differential, reflecting brand premium capture and certification-grade stratification. Three-tier pricing structure across premium, standard, and economy levels dominates, with quality grade and volume scale as primary differentiation drivers. Pricing pressure stems from titanium dioxide volatility originating in South African ore processing, compressing mid-tier producer margins. Economy residential segments in India's western corridor exhibit highest price sensitivity, while EU commercial newbuild specification demonstrates lowest sensitivity due to embodied carbon compliance requirements.
Supply Chain Analysis
Contract manufacturing concentration sits with BASF SE and RPM International Inc. operating captive emulsion facilities, while Asian Paints Ltd. and AkzoNobel N.V. maintain in-house binder production. Geographic supply concentration centers on China, India, and Germany, with raw material dependencies on titanium dioxide from South Africa and China, acrylic monomers from Saudi petrochemical complexes, and bio-based alkyd precursors from European specialty suppliers. Single-source vulnerability runs through Shandong province alkyd capacity facing MEE air quality enforcement. Distribution runs through mobile-enabled direct platforms in India's western corridor and traditional wholesale networks in tier-two towns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The decorative paints market enters cyclical recovery as suburban renovation cycles across India's tier-two and tier-three towns accelerate premium interior finish specification, following housing stock maturation patterns observed in China's tier-one cities during prior recovery phases.
For Market Incumbents: Build specification moats through color-matching digitization and direct contractor platform control. Sherwin-Williams Company and Asian Paints Ltd. demonstrate defensive positioning by capturing purchase data and inventory positioning advantages in monsoon-season application windows. Capacity addition in Gujarat and Maharashtra manufacturing corridors secures supply certainty against Shandong province MEE enforcement disruptions. Certification investment in EU Green Deal alignment and CSRD disclosure documentation captures commercial newbuild specification pull. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, where washability requirements exceed matte performance capabilities of local economy suppliers but full sustainability certification remains undemanded. Bio-based binder development for heritage restoration projects in Germany offers technology-backed differentiation without competing against established distribution depth. Go-to-market through spectrophotometer-based tinting system partnerships bypasses physical color card library investments. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with non-core decorative coatings divisions lacking specification relationships or color-matching technology. Long-term viability hinges on water-based chemistry migration completion and regulatory compliance cost absorption capacity. Watch titanium dioxide mining output from South African ore processors as inflection indicator for margin compression severity across mid-tier producers. Quarterly review of MEE enforcement actions in Shandong province and ECHA candidate list biocide substitution timelines is advised to detect supply disruption signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Dioxide | Captive ore processing from South African suppliers secures margin against pigment input volatility. |
| Direct Contractor Platform Development | Mobile-enabled ordering in India's western corridor captures purchase data and inventory positioning advantages. |
| Bio-based Binder R&D Partnership | European specialty chemical collaboration opens premium positioning for EU Green Deal-aligned commercial projects. |
| Spectrophotometer Tinting System Deployment | Cloud-based color confirmation eliminates batch variance disputes and compresses project approval timelines. |
| CSRD Compliance Documentation Investment | Embodied carbon tracking certification captures specification pull from EU commercial newbuild procurement. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC 10-K filings, ACC and Cefic industry reports, and ECHA registration databases. Primary interviews engaged plant managers at emulsion manufacturing facilities, procurement leads at downstream residential developers, distribution channel partners in India's tier-two towns, and technical R&D directors overseeing water-based formulation migration. Bottom-up volume modeling from country-level consumption patterns triangulates against top-down value estimates derived from manufacturer revenue disclosures and trade flow analysis.
Forecast inputs include chemistry-type segmentation by water-based acrylic, vinyl-acrylic latex, and oil-based alkyd systems; application splits across residential renovation, commercial newbuild, and industrial maintenance; finish-type specification by matte, satin, eggshell, and gloss sheen requirements; and distribution channel dynamics spanning retail, online, wholesale, and direct sales. CAGRs derive from regression analysis of historical consumption against housing stock maturation curves, regulatory compliance deadlines, and pigment input cost trajectories. Industry-specific inputs incorporate MEE air quality enforcement timelines in China's Yangtze River Delta and BIS certification implementation phases across India's western manufacturing corridor.
Practitioners should monitor titanium dioxide mining output disruptions, REACH authorization substitution deadlines, and monsoon-season logistics bottlenecks for early signals of forecast revision. Assumptions underlying projections reflect current regulatory enforcement intensity and housing renovation cycle momentum. Quarterly review of ECHA candidate list reviews, Shandong province MEE inspection schedules, and South African ore processor export volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Europe Paints and Coatings Market
Paints & Coatings
Europe Architectural Coatings Market
Paints & Coatings
Refinish Paint Market
Paints & Coatings
Global Construction Paints and Coatings Market
Paints & Coatings
Paint Mixing Market
Paints & Coatings
Faux Finish Coatings Market
Paints & Coatings
Global Wood Coatings Market
Paints & Coatings
Road Marking Paints and Coatings Market
Paints & Coatings
Paints and Coatings Market
Paints & Coatings
Low VOC Paint Market
Paints & Coatings
India Paints and Coatings Market
Paints & Coatings
Floor Paints Market
Paints & Coatings
Paints and Coatings Additives Market
Paints & Coatings
United Arab Emirates (UAE) Paints and Coatings Market
Paints & Coatings
ASEAN Paints and Coatings Market
Paints & Coatings
Water Color Market