
 Asia-Pacific Architectural Coatings Market | 2026-2036
Asia-Pacific Architectural Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Architectural Coatings Market Outlook
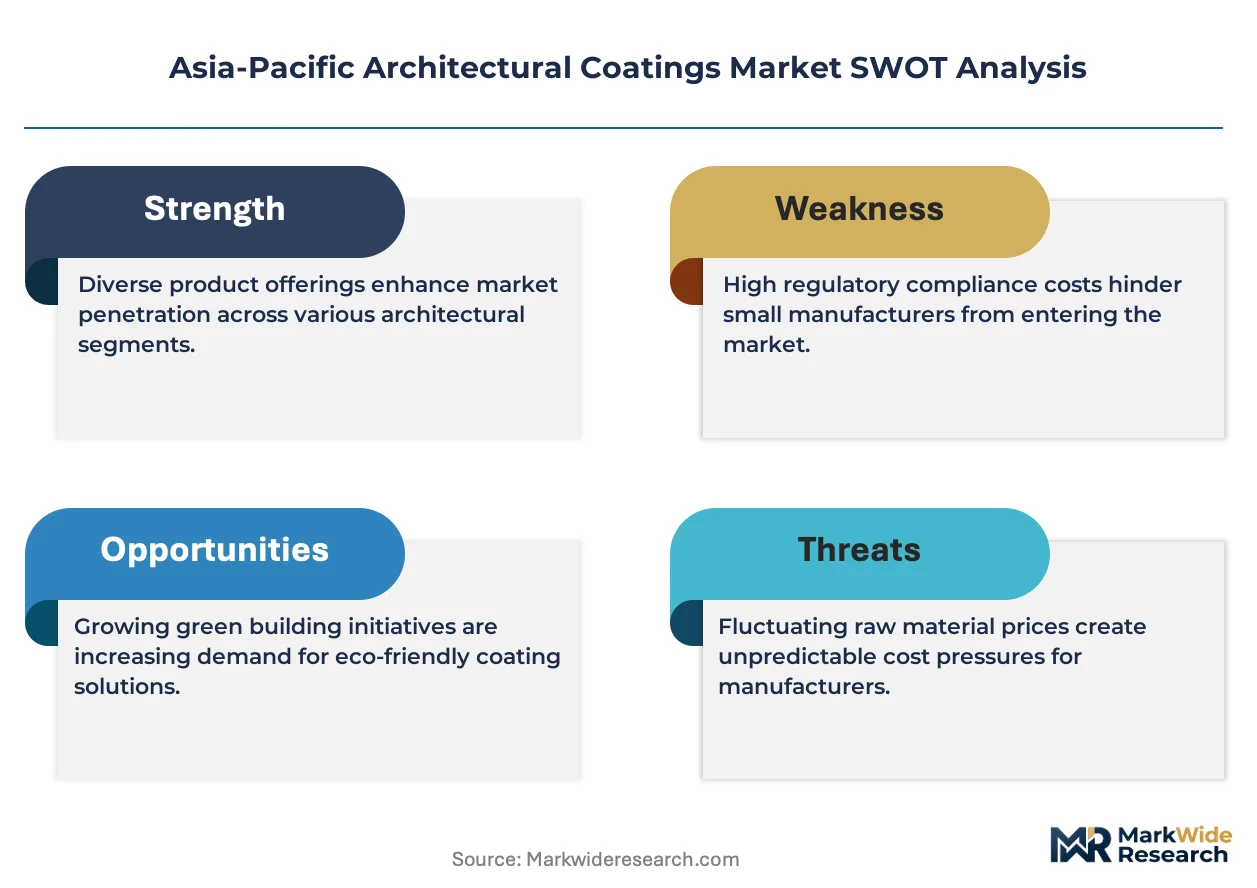
Waterborne emulsion technology is narrowing the performance gap with solvent-borne predecessors across tropical humidity cycles. Asian Paints leverages its distribution depth across tier-two Indian cities to sustain volume leadership in decorative emulsions. Kansai Paint Co., Ltd. anchors its position through captive resin production in Japan and Thailand. PPG Industries Inc. competes on specification-grade commercial coatings for aviation-linked infrastructure projects across the region.
Asia-Pacific architectural coatings comprise film-forming liquid or powder systems applied to building exteriors and interiors for protection, decoration, or substrate preservation, typically formulated with binders such as acrylic, alkyd, or polyurethane resins at solids contents ranging from thirty to sixty percent by volume. Their primary commercial purpose is extending building envelope service life while meeting aesthetic and regulatory requirements across diverse climatic zones. Waterborne formulations now lead volume in residential applications across Southeast Asia, where humidity resistance and faster recoat windows determine contractor preference. Specialty coatings represent the fastest-expanding margin pool, driven by antimicrobial and self-cleaning functionalities in healthcare and premium commercial buildings. Solvent-borne systems retain share in industrial infrastructure segments where chemical resistance and substrate adhesion on weathered steel remain non-negotiable.
China's MEE enforces progressively stricter VOC limits on architectural coatings in urban clusters, forcing domestic producers toward waterborne conversion or facility relocation. India's BIS certification mandates for lead and chromium content in decorative paints reshape import compliance and local formulation standards. Japan's JIS standards for exterior durability create a premium tier accessible primarily to technology leaders with proven tropical and temperate track records. Stakeholders must monitor regulatory divergence between national VOC frameworks and evolving green building certification requirements to align product pipelines with enforcement timelines.
Market Dynamics
China's MEE emissions standards are forcing wholesale reformulation across the region's largest production base, compressing solvent-borne capacity while waterborne lines absorb disproportionate capital allocation. This regulatory compression cascades through resin supply chains and distribution networks from Shanghai to Bangkok.
Growth Catalysts
- India's Pradhan Mantri Awas Yojana housing scheme:Government-subsidized urban construction across Mumbai-Delhi-NCR corridors sustains consistent decorative coatings volume. Tier-two city expansion extends addressable market depth beyond traditional metro concentration.
- Waterborne acrylic emulsion technology:Humidity-resistant formulations now match solvent-borne recoat windows in tropical Southeast Asian climates. Contractor preference shifts decisively toward low-VOC systems for residential repaint cycles.
- Japan's JIS exterior durability certification:Premium-tier specification creates margin expansion opportunity for proven tropical-temperate track records. Technology leaders capture specification-grade commercial and infrastructure projects.
Market Restraints
- Petrochemical feedstock volatility:Acrylic acid and titanium dioxide input costs oscillate with regional refinery capacity constraints. Formulators lack pricing power to pass through full raw material swings in competitive Southeast Asian markets.
- Captive resin supply concentration:Japanese and Thai integrated producers control critical waterborne polymer capacity. Non-integrated competitors face supply security risk during demand surges.
- Substrate adhesion limitations on weathered steel:Solvent-borne alkyd systems retain non-negotiable share in industrial infrastructure maintenance. Waterborne chemistry cannot yet displace these applications without performance compromise.
Strategic Opportunities
- Vietnam and Philippines urban corridor underpenetration:Decorative coatings consumption per capita trails Thailand and Malaysia by substantial margins. Distribution infrastructure investment in Ho Chi Minh City and Cebu unlocks first-mover positioning.
- Antimicrobial functionality in healthcare construction:Hospital and clinic specifications increasingly mandate self-sanitizing surface coatings. Product development pipelines can capture premium pricing in institutional segments.
- China's dual carbon goals:National decarbonization mandates accelerate green building certification adoption. Coatings qualifying for LEED and local equivalents gain specification advantage in commercial developments.
Industry Challenges
- Waterborne formulation chemist scarcity:Regional talent pools lack depth in humidity-stable emulsion design. Technical service teams struggle to support rapid product rollout across dispersed Southeast Asian markets.
- BIS lead and chromium certification timelines:India's mandatory testing protocols create six-to-nine month product registration delays. Import-dependent suppliers face working capital compression during compliance windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Architectural Coatings Market |
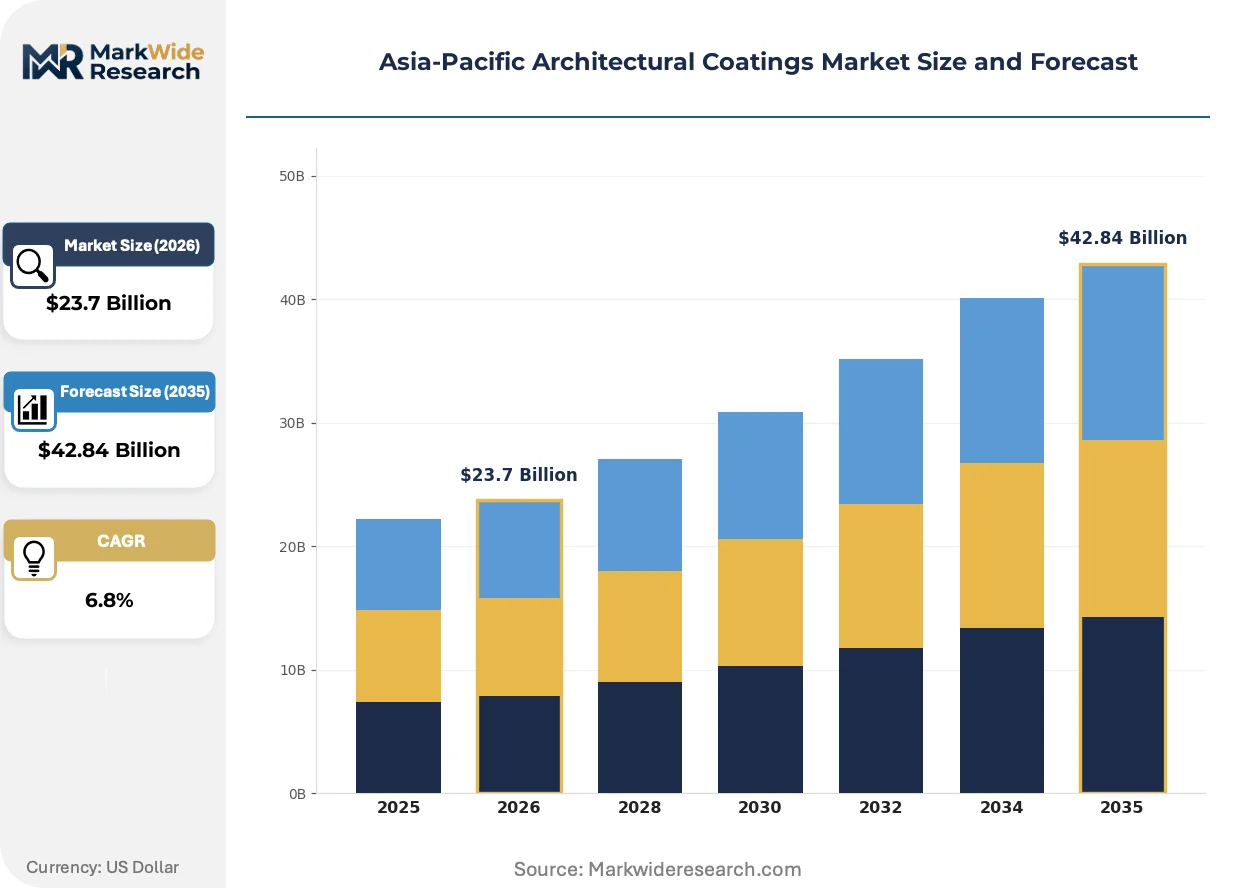
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsion Paints, Oil-Based Paints, Water-Based Primers, Specialty Coatings Application: Residential, Commercial, Industrial, Infrastructure End User: Contractors, Homeowners, Architects, Retailers Formulation: Solvent-Borne, Waterborne, Powder Coatings, UV-Curable |
| Companies Covered | Akzo Nobel N.V., Asian Paints, Jotun, Kansai Paint Co., Ltd., Berger Paints India Limited, Nippon Paint Holdings Co., Ltd., PPG Industries Inc., The Sherwin-Williams Company, BASF Coatings GmbH, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Architectural Coatings Market Strategic Shifts
Digital color matching and predictive maintenance platforms are compressing traditional specification workflows between architects, contractors, and coatings suppliers. Technology investment now concentrates on reducing field application failure rates and accelerating project handover documentation.
Self-cleaning photocatalytic titanium dioxide surface treatments are virtualizing traditional maintenance cycles for high-rise commercial facades. Premium developers in Singapore and Sydney specify these systems for reduced lifecycle cleaning costs. The technology is virtualizing the five-year recoat assumption that has structured maintenance budgeting for decades.
China's MEE progressively tightens VOC limits on architectural coatings in urban clusters, forcing domestic producers toward waterborne conversion or facility relocation to less regulated zones. Enforcement variance between provincial authorities creates compliance complexity for national distribution strategies. Guangdong and Jiangsu manufacturers face the most aggressive implementation timelines.
Specification influence is migrating from general contractors to facade consultants and sustainability officers who control green building certification points. Procurement authority fragments across project stakeholders with divergent performance priorities. This pattern is most visible in Australia's commercial development sector where NABERS ratings drive coating selection criteria.
Asia-Pacific Architectural Coatings Market Segmentation
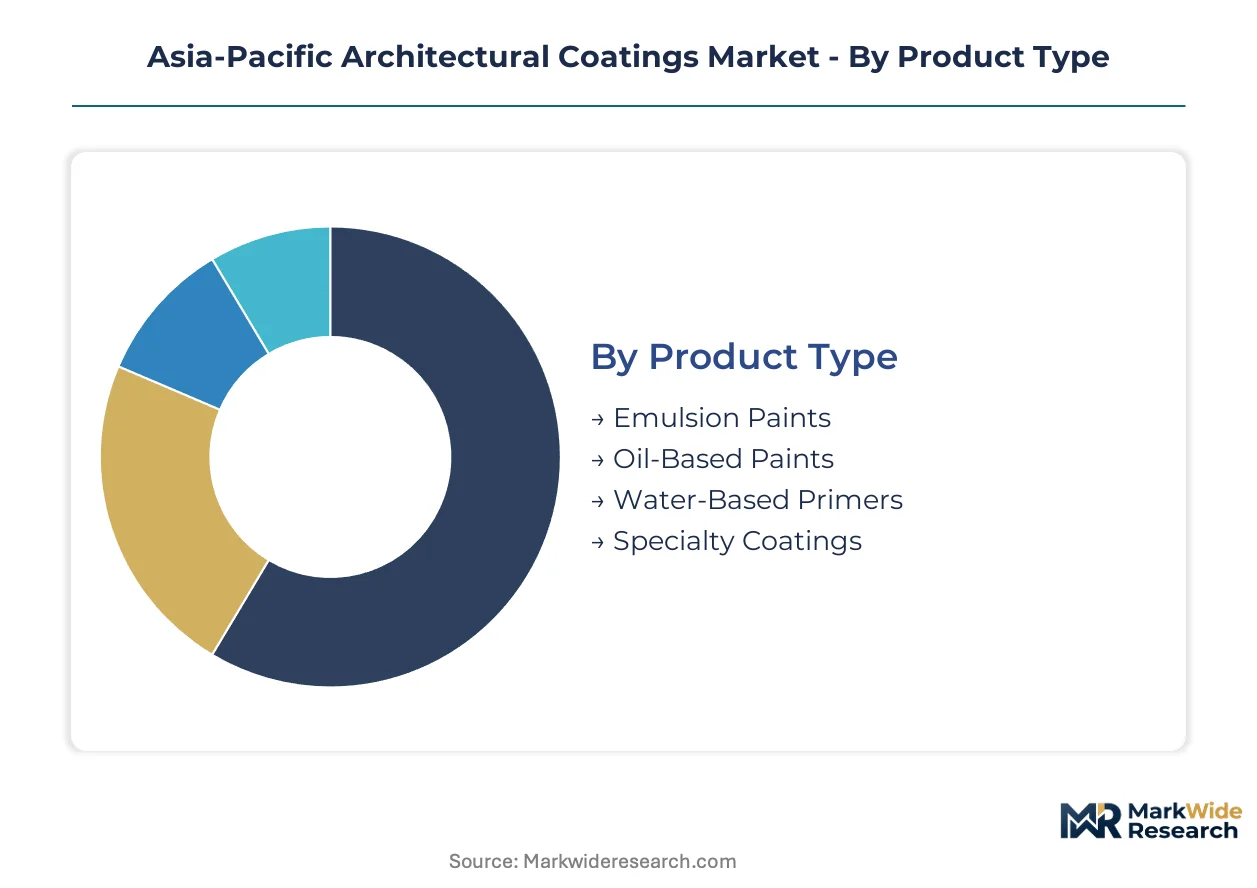
Architectural coatings segmentation in Asia-Pacific reflects divergent technical service requirements across formulation chemistries and application environments. Specification complexity varies sharply between decorative residential projects and infrastructure-grade protective systems. Understanding segment boundaries enables suppliers to align R&D investment with margin structures and regulatory exposure.
Product Type:
After-sales technical service intensity separates premium decorative segments from commodity trade sales, with formulation stability in tropical humidity cycles driving repeat specification.
- Emulsion Paints:Acrylic and styrene-acrylic latex binders formulated at 40-55% volume solids for interior and exterior decorative applications. Demand concentrates in India's tier-two urban corridors under Pradhan Mantri Awas Yojana schemes, where contractor preference for low-VOC, fast-recoat systems accelerates waterborne conversion. Humidity-resistant grade specifications now match solvent-borne performance windows in Southeast Asian climates.
- Specialty Coatings:Functional systems incorporating antimicrobial additives, photocatalytic self-cleaning surfaces, or elastomeric waterproofing membranes. Singapore and Sydney premium commercial developers specify these for reduced lifecycle maintenance costs and green building certification points. Healthcare construction across the region increasingly mandates self-sanitizing surface properties.
- Oil-Based Paints:Alkyd resin systems retaining share in metal substrate applications where adhesion to weathered steel remains critical.
- Water-Based Primers:Penetrating sealers and blocking coats applied to porous substrates before topcoat application.
By volume, emulsion paints lead across residential construction corridors. By growth pace, specialty coatings are expanding most quickly on healthcare and premium commercial specifications.
Application:
Project scale and specification authority concentration determine margin capture, with fragmented procurement in residential repaint contrasting centralized facade consultant influence in commercial developments.
- Residential:Decorative interior and exterior coatings applied to single-family homes, apartments, and government housing schemes. Mumbai-Delhi-NCR urban corridors sustain consistent volume through subsidized construction programs. Tier-two Indian cities extend addressable market depth beyond traditional metro concentration.
- Commercial:High-rise facades, office interiors, and retail environments where sustainability officers and facade consultants control specification. Australia's NABERS ratings and China's green building certifications drive coating selection criteria toward low-VOC and durability-proven systems.
- Industrial:Protective coatings for manufacturing facilities, warehouses, and process equipment exposed to chemical or thermal stress.
- Infrastructure:Bridges, tunnels, and transportation assets requiring long-cycle maintenance protection on weathered steel and concrete substrates.
Residential applications dominate current volume absorption. Commercial segment climbs the fastest on certification-linked specification premiums.
End User:
Technical specification knowledge and purchasing authority fragmentation shape channel strategy, with professional contractors demanding field service support while retail homeowners prioritize color matching convenience.
- Contractors:Professional applicators executing repaint and new construction projects across residential and commercial segments. Southeast Asian contractors increasingly specify waterborne systems based on recoat window performance in tropical humidity.
- Architects:Design professionals controlling aesthetic and performance specifications in commercial and premium residential developments. Digital color matching platforms compress specification workflows between architects and suppliers.
- Homeowners:DIY purchasers in retail channels selecting decorative emulsions for interior refresh projects.
- Retailers:Distributors and trade outlets stocking inventory for contractor and consumer pickup.
Contractors represent the largest volume channel. Architects command the steepest expansion trajectory on commercial project specification influence migration.
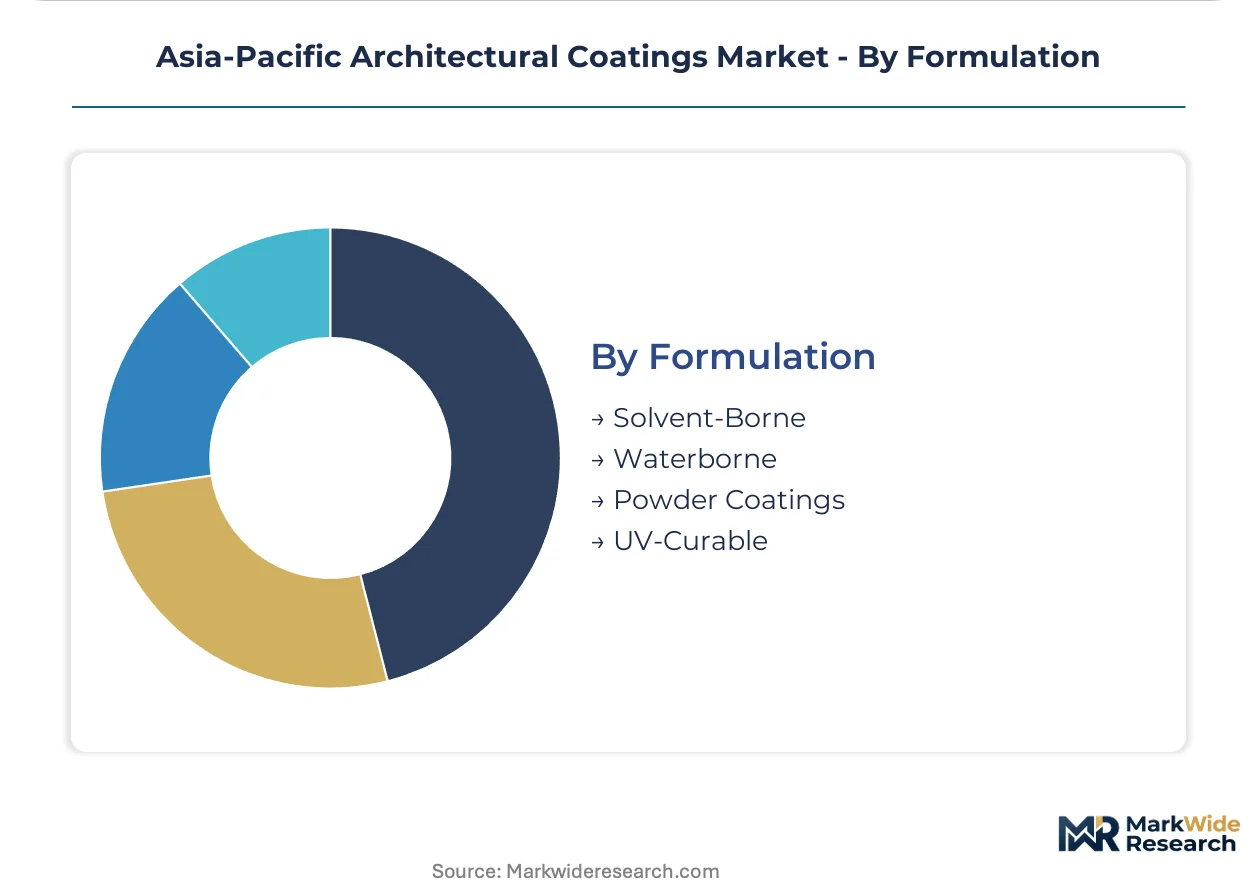
Formulation:
Regulatory enforcement variance across national jurisdictions accelerates technology transition, with waterborne capacity absorbing disproportionate capital allocation as solvent-borne faces progressive compression.
- Waterborne:Acrylic, polyurethane, and hybrid emulsion systems with VOC content below regulatory thresholds. China's MEE emissions standards force wholesale reformulation across the region's largest production base. Captive resin supply in Japan and Thailand creates supply security advantages for integrated producers.
- Solvent-Borne:Alkyd and polyurethane systems retaining non-negotiable share where chemical resistance and substrate adhesion on weathered steel remain performance requirements. Industrial infrastructure maintenance segments resist waterborne displacement.
- Powder Coatings:Thermosetting resin systems applied as dry powder and cured thermally, limited primarily to metal substrate applications.
- UV-Curable:Rapid-cure systems activated by ultraviolet radiation, niche-deployed in specialized industrial finishing applications.
Waterborne formulations lead by volume across residential and commercial segments. UV-curable systems gain share fastest on manufacturing throughput efficiency requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan exports high-performance resin intermediates to Thailand and Vietnam, where local formulators blend waterborne emulsions for Southeast Asian construction markets. This trade corridor shapes technology transfer patterns and captive supply advantages across the region.
China
Guangdong and Jiangsu manufacturers face the most aggressive MEE emissions implementation timelines, forcing waterborne conversion or facility relocation. Dual carbon goals accelerate green building certification adoption in Shanghai and Beijing commercial developments. Pearl River Delta production clusters absorb disproportionate capital allocation for low-VOC capacity expansion.
India
Pradhan Mantri Awas Yojana housing schemes sustain decorative coatings volume across Mumbai-Delhi-NCR urban corridors. BIS lead and chromium certification mandates reshape import compliance and local formulation standards. Tier-two cities including Pune, Ahmedabad, and Lucknow extend addressable market depth beyond traditional metro concentration.
Japan
JIS exterior durability standards create premium-tier specification opportunities for proven tropical-temperate track records. METI industrial policy supports resin technology development for humidity-stable emulsion systems. Kanto and Kansai production bases supply captive polymer capacity to Southeast Asian affiliates.
Vietnam
Decorative coatings consumption per capita trails Thailand and Malaysia by substantial margins, creating first-mover positioning potential. Ho Chi Minh City and Hanoi construction booms absorb imported emulsion intermediates from regional suppliers. Distribution infrastructure investment accelerates as foreign formulators establish local blending operations.
Australia
NABERS ratings drive coating selection criteria toward low-VOC and durability-proven systems in commercial developments. Sydney and Melbourne facade consultants control specification authority for high-rise premium projects. Self-cleaning photocatalytic surface treatments gain specification share for reduced lifecycle maintenance costs.
Asia-Pacific Architectural Coatings Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement authority in residential repaint versus concentrated specification influence in commercial developments. The vendor base spans integrated resin producers, regional formulators with distribution depth, and global specification-grade suppliers. Three archetypes dominate: captive resin-integrated Japanese conglomerates, Indian subcontinent distributors with tier-two city penetration, and North American specification players targeting aviation-linked infrastructure. Dominant competitive moves include backward integration into waterborne polymer supply and geographic expansion through distribution infrastructure investment in underpenetrated Southeast Asian corridors.
Among Japan-based integrated producers, Kansai Paint Co., Ltd. and Nippon Paint Holdings Co., Ltd. occupy positions anchored by captive resin production in Thailand and domestic technology leadership. Asian Paints exemplifies the distribution-depth archetype across Indian tier-two markets. PPG Industries Inc. represents specification-grade positioning for commercial and infrastructure projects.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| Asian Paints |
| Jotun |
| Kansai Paint Co., Ltd. |
| Berger Paints India Limited |
| Nippon Paint Holdings Co., Ltd. |
| PPG Industries Inc. |
| The Sherwin-Williams Company |
| BASF Coatings GmbH |
| Others |
Value Chain & Pricing Dynamics
Captive resin production in Japan and Thailand concentrates margin capture at the polymer supply tier, forcing non-integrated formulators to absorb titanium dioxide and acrylic acid volatility without commensurate pricing power. This upstream control pattern shapes competitive returns across Southeast Asian distribution networks.
Pricing Analysis
Waterborne emulsion technology commands premium positioning against legacy solvent-borne systems, with next-generation antimicrobial and self-cleaning formulations extracting additional margin tiers. Pricing stratifies across JIS-certified premium, BIS-compliant standard, and unbranded economy levels based on certification grade and after-sales technical service bundling. Cost compression in commodity decorative segments is intensifying because petrochemical feedstock swings outpace contractor pricing power in competitive Indian and Vietnamese markets. Government housing scheme contractors exhibit highest price sensitivity, while Australian facade consultants controlling NABERS-linked specifications show lowest.
Supply Chain Analysis
Extended payment terms from Japanese resin suppliers to Thai and Vietnamese formulators compress working capital cycles for non-integrated competitors. Geographic supply concentration centers on China for titanium dioxide intermediates, Japan and Thailand for waterborne polymer resins, and India for decorative emulsion blending. Raw material dependencies rest on acrylic acid from regional refinery complexes, imported rutile ore for pigment manufacture, and specialty additives for antimicrobial functionality. Single-source vulnerability runs through captive resin supply controlled by integrated Japanese producers. Distribution runs through tier-two city stockists in India, project-specification channels in Australia, and contractor-direct relationships across Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waterborne technology substitution threatens solvent-borne incumbents in decorative segments, while photocatalytic self-cleaning surfaces virtualize traditional maintenance revenue streams for protective coatings suppliers.
For Market Incumbents: Insulate core decorative volume through backward integration into waterborne polymer production or exclusive resin supply agreements with Japanese technology partners. Defend specification-grade positioning in Australian commercial developments by accelerating JIS durability certification acquisition before green building mandates tighten. Prioritize captive supply security over price competition in Southeast Asian humidity-resistant emulsion segments.
For New Entrants and Emerging Players: Establish a beachhead in Vietnam's Ho Chi Minh City construction corridor where decorative coatings consumption per capita trails regional benchmarks and distribution infrastructure remains underdeveloped. Target Philippine healthcare construction specifications for antimicrobial functionality premiums, leveraging regulatory lag against established suppliers. Deploy contractor-direct technical service teams rather than retail channel dependence to overcome Asian Paints' tier-two city stockist depth.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional formulators in Southeast Asia lacking captive resin supply but possessing established contractor relationships. Five-to-ten year viability hinges on waterborne conversion capital deployment timing relative to MEE enforcement acceleration in China. Monitor BIS certification backlog duration as signal for import-dependent supplier distress and consolidation opportunity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Waterborne Polymer Production | Captive resin supply insulates margin compression from acrylic acid volatility and Japanese supplier concentration. |
| JIS Exterior Durability Certification Investment | Premium-tier specification access in Australian NABERS-linked commercial developments commands pricing power. |
| Antimicrobial Product Development Pipeline | Healthcare construction mandates across Singapore and Sydney create defendable premium positioning. |
| Tier-Two Distribution Infrastructure Expansion | Pune and Ahmedabad stockist networks capture Pradhan Mantri Awas Yojana volume beyond metro saturation. |
| Photocatalytic Self-Cleaning Surface Launch | Virtualized maintenance cycles for high-rise facades disrupt traditional five-year recoat assumptions. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, combining contractor specification interviews, resin producer technical director discussions, and facade consultant workflow analysis with secondary validation. Secondary sources included China MEE enforcement documentation, India BIS certification timelines, Japan METI industrial policy filings, and customs trade data for acrylic acid and titanium dioxide flows. Plant managers at Thai emulsion facilities, procurement leads at Australian commercial developers, and distribution channel partners in Indian tier-two cities provided operational ground-truth. Bottom-up volume builds across formulation segments triangulated against top-down production capacity assessments.
Calibration against historical regulatory enforcement variance and technology substitution patterns anchored the analytical framework. Segmentation modeling spanned formulation chemistry, application environment, and certification tier across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating housing scheme construction schedules and green building adoption trajectories. Industry-specific inputs included MEE implementation timeline scenarios and JIS certification success rates for tropical durability claims.
Sensitivities concentrate around MEE enforcement acceleration in Guangdong and Jiangsu, BIS certification timeline extensions for import-dependent suppliers, and waterborne formulation chemist availability constraints. Forecasts reflect documented assumptions on regulatory trajectory and technology performance convergence. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Road Marking Paint Market
Paints & Coatings
Morocco Paints and Coatings Market
Paints & Coatings
Automotive Coatings Market
Paints & Coatings
South America Paints and Coatings Market
Paints & Coatings
Asia-Pacific Paint Thinner Market
Paints & Coatings
Industrial Paint Booth Market
Paints & Coatings
Refinish Paint Market
Paints & Coatings
Anti-Fungal and Anti-Bacterial Paints Market
Paints & Coatings
Architectural Coatings Market
Paints & Coatings
Europe Paints and Coatings Additives Market
Paints & Coatings
Global Decorative Paints and Coatings Market
Paints & Coatings
Canvas Primer Market
Paints & Coatings
Global Construction Paints and Coatings Market
Paints & Coatings
Polyurethane Resins Paints and Coatings Market
Paints & Coatings
Paint Defoamers Market
Paints & Coatings
Europe Architectural Coatings Market