
 Organic Farming Market | 2026-2036
Organic Farming Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Farming Market Analysis
USDA Organic certification is redrawing competitive boundaries across the value chain, as compliance costs and three-year transition periods filter out conventional operators lacking balance-sheet depth. Organic Valley (CROPP Cooperative) leverages its farmer-owned cooperative structure to sustain premium milk pooling across the Upper Midwest. SunOpta Inc. anchors North American organic ingredient supply through its vertically integrated grain and fruit processing platforms. Nature's Path Foods Inc. differentiates via family-controlled brand equity and zero-synthetic-additive formulations that command shelf-space loyalty.
Organic farming denotes agricultural production systems that exclude synthetic pesticides, genetically modified organisms, and petroleum-based fertilizers, relying instead on composting, biological pest control, and mechanical weed management to maintain soil fertility and ecosystem balance. The practice delivers certified food and fiber outputs to commercial buyers bound by third-party audit protocols for residue limits and traceability. Crop type segmentation shows vegetables and fruits capturing disproportionate value per hectare due to shorter rotation cycles and direct-to-retail freshness premiums, while cereal grains dominate volume throughput as livestock feed demand scales. Certification segmentation reveals structural tension between USDA Organic and EU Organic equivalence agreements, where divergent livestock stocking rates and permitted inputs create arbitrage complexity for cross-border traders.
EPA regulates pesticide tolerance thresholds under the Federal Insecticide, Fungicide, and Rodenticide Act, while the USDA National Organic Program administers accreditation and enforcement of certifying agents; the EU Green Deal tightens these frames through binding pesticide reduction targets and expanded buffer-zone mandates. Regulatory fragmentation between jurisdictions elevates compliance costs for multi-certification holders but simultaneously deepens moats against uncertified competitors. Stakeholders must monitor evolving equivalence negotiations and domestic subsidy reallocation as conventional-to-organic transition incentives reshape land-use economics and input supplier pricing power.
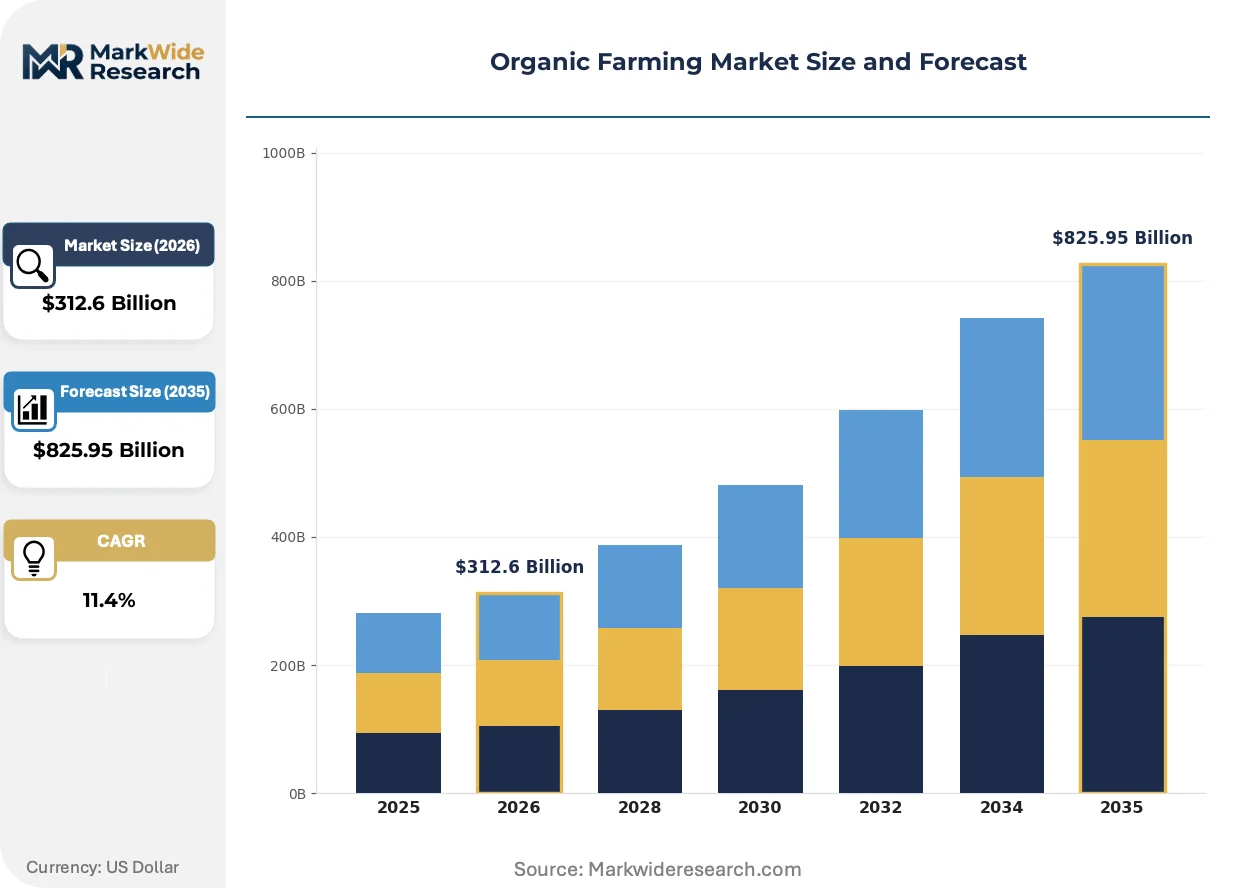
Market Dynamics
Certification equivalence friction between USDA Organic and EU Organic standards is compressing cross-border arbitrage margins and forcing operators to choose single-jurisdiction specialization over multi-market scale.
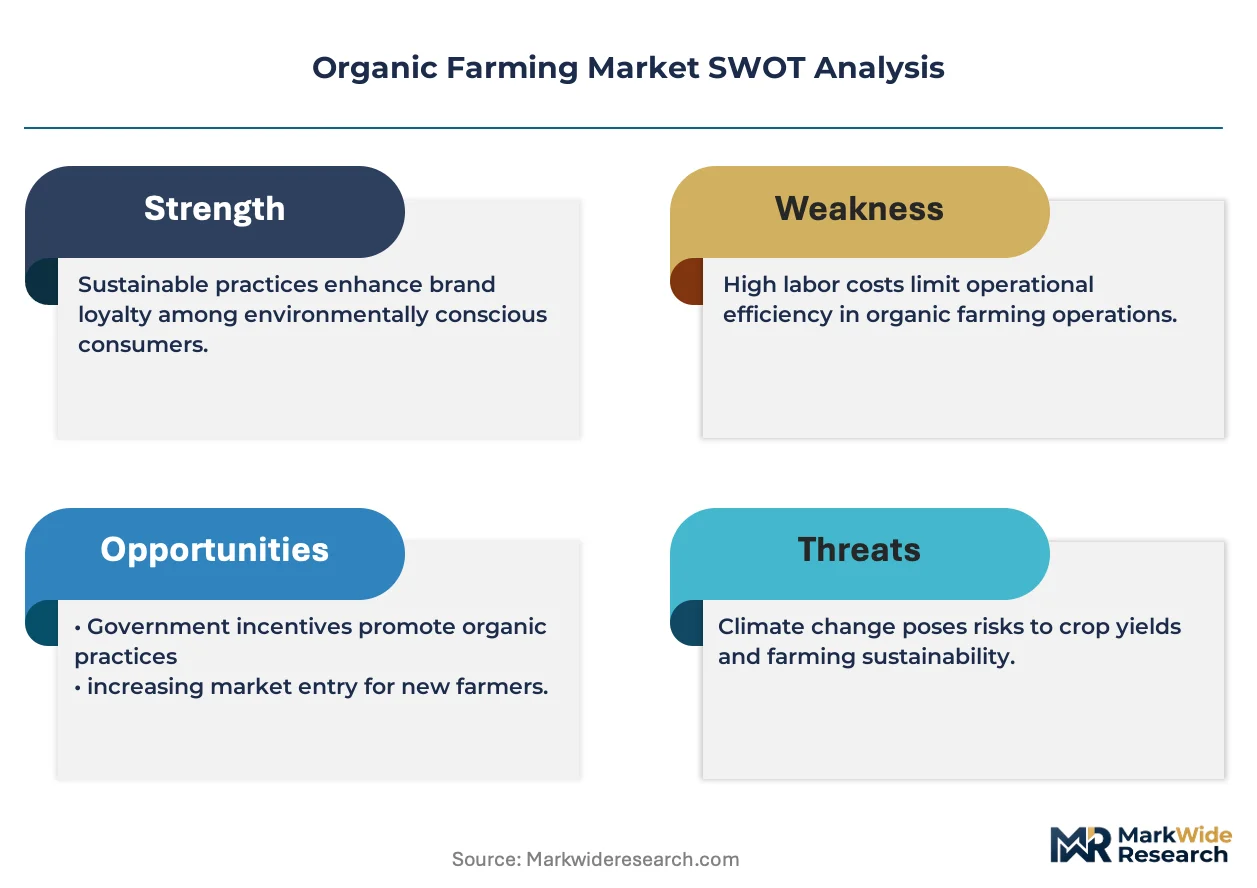
Growth Catalysts
- EU Green Deal Farm to Fork targets:Binding pesticide reduction mandates accelerate input substitution toward biological crop protection, expanding addressable market for compliant suppliers.
- Private-label normalization:German discounters Aldi and Lidl have embedded organic basket penetration into mainstream retail economics, hardening consumer willingness to pay certification premiums.
- Vertically integrated processing platforms:Grain and fruit processors with captive organic supply chains capture margin that would otherwise leak to commodity traders.
Market Restraints
- Three-year transition lock-up:USDA Organic certification requires thirty-six months of synthetic-free cultivation before harvest eligibility, freezing working capital and filtering out thinly capitalized conventional operators.
- Input cost volatility:Biological pest control and compost-based fertility systems face price instability from weather-dependent supply of manure and botanical extracts.
- Equivalence agreement gaps:Divergent livestock stocking rates and permitted inputs between USDA Organic and EU Organic create compliance complexity that elevates multi-certification costs.
Strategic Opportunities
- Buffer-zone mandate expansion:EU Green Deal proposals for widened chemical-free perimeters around organic parcels create demand for adjacent land conversion services.
- Direct-to-retail freshness premiums:Shorter rotation vegetables and fruits command disproportionate value per hectare through bypassing wholesale aggregation layers.
- Livestock feed demand scaling:Organic cereal grains face structural demand pull from dairy and poultry operations seeking residue-free feed inputs.
Industry Challenges
- Certifying agent capacity constraints:USDA National Organic Program accreditation bottlenecks delay audit scheduling and extend time-to-market for transitioning farms.
- Traceability system integration:Third-party audit protocols for residue limits require digitized chain-of-custody documentation that legacy farm management software cannot support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Farming Market |
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $825.95 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Crop Type: Cereal Grains, Fruits, Vegetables, Pulses Certification: USDA Organic, EU Organic, ACO, JAS Distribution Channel: Retail Stores, Farmers' Markets, Online Sales, Wholesalers Technology: Hydroponics, Permaculture, Crop Rotation, Organic Fertilizers |
| Companies Covered | Cal-Organic Farms, Organic Valley (CROPP Cooperative), SunOpta Inc., Nature’s Path Foods Inc., Picks Organic Farm, Organic Farmers Co., The Indian Organic Farmers Producer Company Limited, Camson Bio Technologies Limited, ZUWA Organic Farms Pvt Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Farming Market Emerging Trajectories
Biological crop protection formulations and precision composting systems are compressing the yield gap against synthetic-dependent conventional agriculture while hardening compliance documentation standards.
RNA interference biopesticides are displacing botanical extract sprays in high-value fruit and vegetable operations. Large-scale organic vegetable producers in California and Spain are adopting these targeted pest suppression tools at accelerating pace. The technology is displacing calendar-based spraying regimens with phenology-triggered applications that reduce input volume and residue risk.
EU Green Deal pesticide reduction targets are tightening residue tolerance thresholds and expanding mandatory buffer zones between organic and conventional parcels. The industrial consequence is land-use reconfiguration around organic clusters rather than dispersed mixed farming. Vegetable and fruit growers in the Netherlands and northern Italy are responding by consolidating organic parcels into contiguous blocks to minimize perimeter exposure.
Retail procurement is consolidating around vertically integrated suppliers with captive organic grain and fruit processing capacity. Grocery chains in Germany and France are displacing spot-market purchasing with multi-year offtake agreements that bundle traceability guarantees. This pattern is most visible in dairy and infant formula supply chains where residue documentation requirements are most stringent.
Organic Farming Market Segmentation
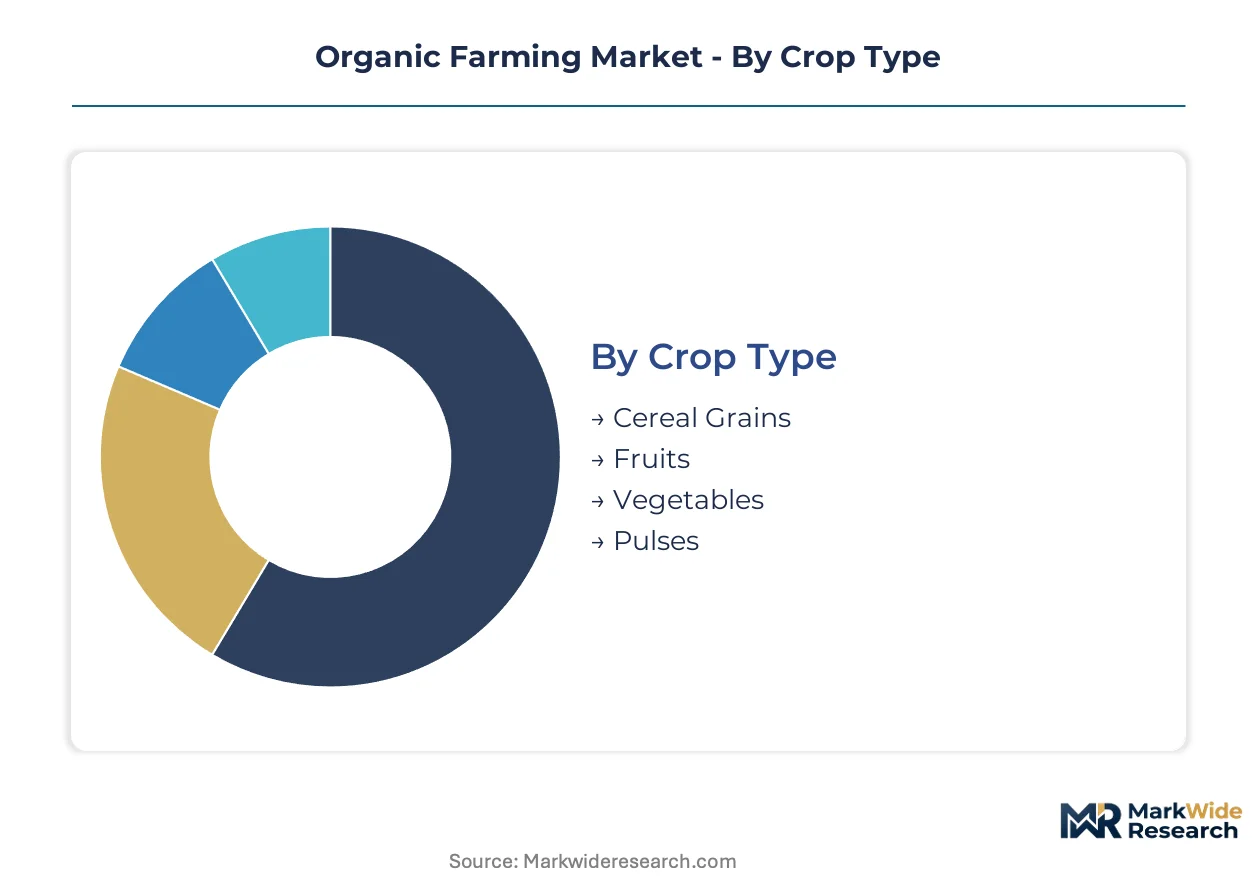
Segmentation in organic farming reveals how certification standards, crop economics, and channel access fragment producer strategies. Distinct margin profiles and compliance burdens across each dimension determine which operators can scale versus remain niche.
Crop Type:
Channel penetration varies sharply by crop type, with vegetables and fruits commanding direct-to-retail premiums while grains flow through bulk commodity channels.
- Vegetables:Short rotation cycles enable multiple harvests annually, supporting freshness-based pricing in supermarket produce aisles. Leafy greens and brassicas concentrate demand in Germany and the Netherlands where discounters have normalized organic basket penetration.
- Fruits:Tree crops and berries generate the highest value per hectare through direct retail relationships, though frost vulnerability and multi-year establishment periods tie up capital. Spanish citrus and Italian stone fruit clusters supply year-round European demand.
- Cereal Grains:Volume throughput dominates as livestock feed demand scales, with organic corn and wheat flowing to dairy and poultry operations seeking residue-free inputs.
- Pulses:Nitrogen-fixing legumes support rotational fertility management while capturing premium protein markets in plant-based food formulations.
By volume, cereal grains lead. By growth pace, vegetables are ahead.
Certification:
Cost tiers stratify sharply across certification schemes, with multi-standard compliance elevating overhead for exporters while single-standard operators capture domestic efficiency.
- USDA Organic:The National Organic Program's three-year transition lock-up and synthetic-free cultivation mandates filter out thinly capitalized conventional operators. Compliance documentation requirements favor large-scale grain and dairy producers with dedicated administrative capacity.
- EU Organic:Farm to Fork strategy pesticide reduction targets and expanding buffer-zone mandates deepen moats against uncertified competitors. German and French retail procurement increasingly demands EU Organic equivalence for cross-border supply security.
- ACO:Australian Certified Organic governs export-oriented production from Queensland and Victoria, with equivalence negotiations determining access to Asian premium markets.
- JAS:Japanese Agricultural Standards certification enables access to high-value retail channels in Tokyo and Osaka, though stringent residue thresholds limit eligible supplier pools.
USDA Organic holds the broadest geographic footprint. EU Organic is gaining regulatory momentum fastest.
Distribution Channel:
Customer type determines channel selection, with institutional buyers favoring wholesale aggregation while quality-sensitive consumers pay freshness premiums at direct outlets.
- Retail Stores:Supermarket chains and discounters in Germany, France, and the United States have embedded organic penetration into mainstream economics through private-label expansion and multi-year offtake agreements.
- Farmers' Markets:Direct producer-consumer relationships capture maximum margin for small-scale vegetable and fruit operators, particularly in California and Italian regional clusters.
- Online Sales:Subscription box models and e-commerce platforms aggregate dispersed demand for specialty items like heirloom grains and botanical inputs.
- Wholesalers:Bulk aggregation layers remain essential for cereal grains and processing-grade commodities where traceability documentation is standardized rather than customized.
Retail stores dominate value capture. Online sales are expanding most quickly.
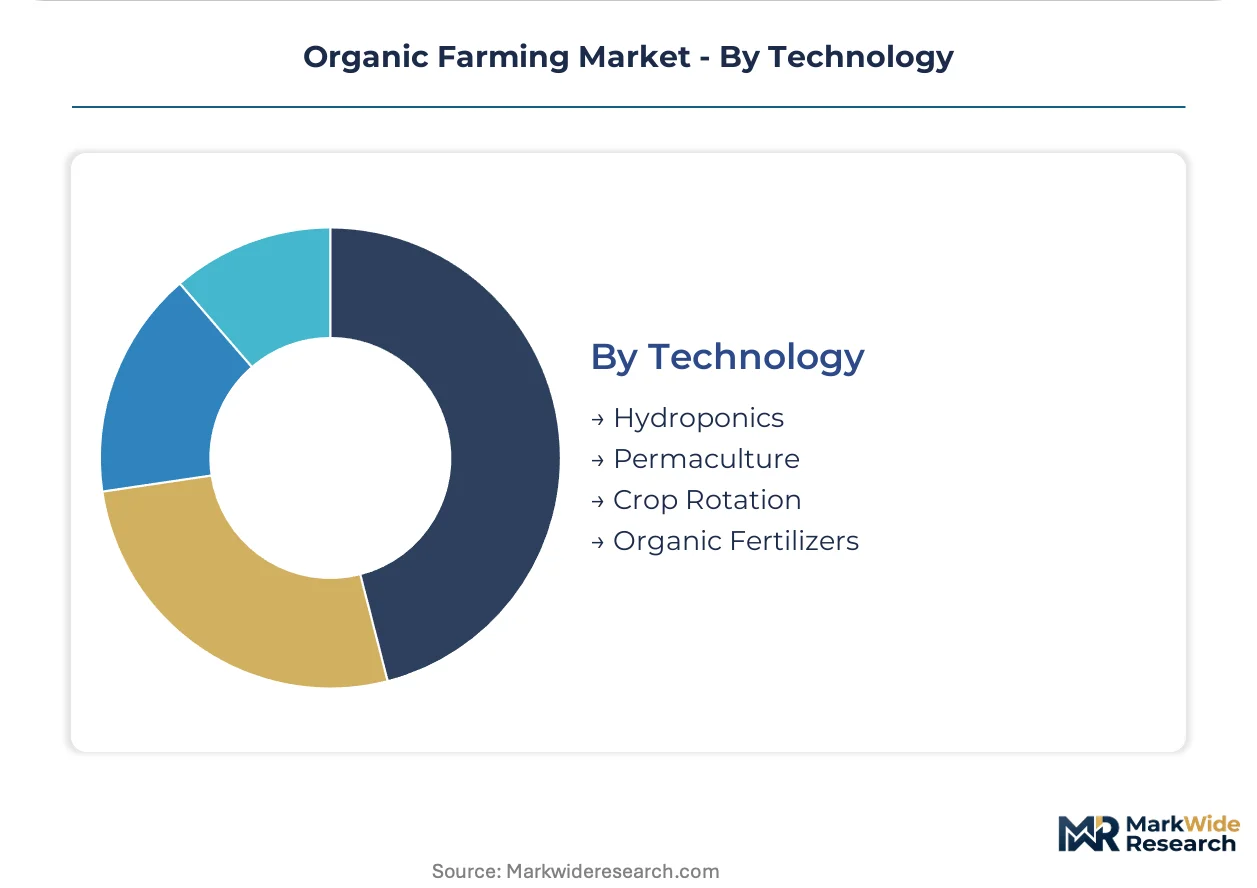
Technology:
Supply concentration clusters around input availability, with biological pest control and compost sourcing determining viable production geographies.
- Hydroponics:Soilless cultivation systems enable organic certification in controlled environments, concentrating in Dutch greenhouse clusters and California Central Valley operations where land scarcity elevates vertical production economics.
- Permaculture:Integrated food-forest designs capture premium markets for diversified smallholdings, though scalability constraints limit output volumes.
- Crop Rotation:Mechanical weed suppression and nitrogen-fixing sequences remain foundational to soil fertility management across temperate grain belts.
- Organic Fertilizers:Compost-based and manure-derived inputs face weather-dependent supply volatility, driving consolidation around large-scale composting facilities in proximity to livestock operations.
Crop rotation anchors volume production. Hydroponics is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's Farm to Fork pesticide reduction targets are accelerating land conversion incentives across multiple jurisdictions. Germany's discounter-driven organic basket penetration and the United States' USDA transition subsidies are reshaping producer economics. France, Spain, and India are deploying distinct regulatory frameworks to capture premium export positioning.
Germany
Aldi and Lidl have normalized organic penetration in mainstream retail, hardening consumer willingness to pay certification premiums. The EU Organic regulation's buffer-zone mandates are forcing land-use reconfiguration around contiguous organic blocks. Bavarian vegetable clusters are consolidating parcels to minimize perimeter chemical exposure.
United States
USDA Organic's three-year transition lock-up is filtering out thinly capitalized conventional operators. The National Organic Program's accreditation bottlenecks are extending time-to-market for transitioning farms. California Central Valley producers are adopting RNA interference biopesticides in high-value fruit operations.
France
Retail procurement is consolidating around vertically integrated suppliers with captive traceability documentation. The EU Green Deal's binding pesticide reduction targets are tightening residue tolerance thresholds. Provence-Alpes-Côte d'Azur stone fruit growers are responding with phenology-triggered application systems.
Spain
Citrus and vegetable exports to Northern Europe are driving demand for EU Organic equivalence certification. The country's national agricultural regulator is aligning domestic standards with Farm to Fork strategy mandates. Valencia and Murcia clusters are expanding greenhouse hydroponics for year-round supply security.
India
Export-oriented production from Maharashtra and Karnataka is scaling to serve Middle East and European premium markets. The Agricultural and Processed Food Products Export Development Authority is streamlining organic certification for cross-border trade. Gujarat's cotton and pulse belts are converting under domestic transition incentive programs.
Organic Farming Market Vendor Landscape
Listed leaders compete with private specialists across certification depth and channel access. The vendor base stratifies between farmer-owned cooperatives with premium pooling power and vertically integrated processors with captive supply chains. Two archetypes dominate: cooperative structures that aggregate smallholder output, and integrated platforms that control grain and fruit processing. Competitive moves center on multi-year offtake agreements with retail chains and backward integration into composting and biological input production.
Within the cooperative tier, Organic Valley (CROPP Cooperative) and Organic Farmers Co. exemplify farmer-owned structures that sustain premium milk and produce pooling across dispersed geographies. Among integrated processors, SunOpta Inc. anchors North American organic ingredient supply through in-house grain and fruit processing platforms. Nature's Path Foods Inc. occupies a position in family-controlled brand equity, differentiating via zero-synthetic-additive formulations that command shelf-space loyalty in retail channels.
| Leading Market Players |
|---|
| Cal-Organic Farms |
| Organic Valley (CROPP Cooperative) |
| SunOpta Inc. |
| Nature's Path Foods Inc. |
| Picks Organic Farm |
| Organic Farmers Co. |
| The Indian Organic Farmers Producer Company Limited |
| Camson Bio Technologies Limited |
| ZUWA Organic Farms Pvt Ltd |
| Others |
Supply Flow & Price Mechanics
Ninety-day organic certification transition timelines compress working capital cycles and amplify price premiums for harvest-ready inventory. This lead-time compression concentrates pricing power with vertically integrated processors who control grain and fruit processing platforms, while thinly capitalized conventional operators face margin erosion from input cost volatility.
Pricing Analysis
Certification level creates the primary spread, with USDA Organic and EU Organic equivalence tiers commanding distinct premium bands over uncertified conventional supply. Three-tier pricing structure across premium, standard, and economy levels reflects compliance depth, with multi-certification holders capturing highest tiers through reduced arbitrage friction. Pricing pressure stems from biological input cost volatility as weather-dependent manure and botanical extract supplies fluctuate. Retail grocery chains exhibit lowest price sensitivity, while wholesale commodity buyers face margin compression from spot-market exposure.
Supply Chain Analysis
Strategic stockpile preferences dominate biological input procurement, with compost and manure inventories held against weather-dependent supply interruptions. Geographic supply concentration clusters in the United States, Germany, and Spain, where EU Green Deal buffer-zone mandates are forcing land-use reconfiguration. Raw material dependencies center on livestock manure, botanical pest extracts, and certified organic seed stocks. Single-source vulnerability runs through concentrated composting facility networks near dairy operations. Distribution runs through vertically integrated processors with captive organic grain and fruit handling capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating around German discounters Aldi and Lidl, whose normalized organic basket penetration has shifted procurement leverage from fragmented spot-market purchasing toward multi-year offtake agreements.
For Market Incumbents: Secure backward integration into composting and biological input production to insulate margins from weather-dependent supply volatility. Deepen multi-year offtake agreements with retail chains to lock in volume commitments before EU Green Deal buffer-zone mandates expand compliance costs. Certification investment in dual USDA-EU equivalence protects against cross-border arbitrage compression. For New Entrants and Emerging Players: USDA Organic fast-track programs for transitioning conventional operators present entry vectors in cereal grain segments where livestock feed demand scales. White-space concentrates in direct-to-retail freshness premiums for short-rotation vegetables, particularly in California and Italian regional clusters bypassing wholesale aggregation. Go-to-market leverage rests on phenology-triggered RNA interference biopesticide adoption reducing residue risk documentation burdens. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates with underutilized organic processing assets stranded by conventional portfolio prioritization. Long-term viability favors vertically integrated platforms with captive supply chains over cooperative structures dependent on premium pooling economics. Watch EU-US equivalence negotiation progress as inflection signal for cross-border arbitrage margin restoration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biological Input Production | In-house composting and botanical extract processing insulates margins from weather-driven supply volatility. |
| Multi-Year Retail Offtake Agreements | German discounters Aldi and Lidl are displacing spot-market purchasing with bundled traceability guarantees. |
| Dual Certification Investment | USDA-EU equivalence compliance deepens moats against single-standard competitors facing arbitrage friction. |
| RNA Interference Biopesticide Adoption | Phenology-triggered applications reduce input volume and residue risk in California high-value fruit operations. |
| Contiguous Organic Parcel Consolidation | EU Green Deal buffer-zone mandates force land-use reconfiguration around consolidated blocks in Bavarian vegetable clusters. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with organic certification officers, grain procurement managers at retail chains, biological input suppliers, and farm operations directors; alongside secondary validation through USDA National Organic Program accreditation records, EU Farm to Fork strategy documentation, and customs trade data for organic commodity flows. Bottom-up farm-level production estimates and top-down retail channel value capture were triangulated for convergence.
Across the analysis window, projections were derived from modeled segmentation across crop type, certification scheme, distribution channel, and production technology dimensions. CAGRs were computed from annualized growth trajectories fitted to historical transition rates and policy-mandated conversion incentives. Forecast inputs incorporated EU pesticide reduction target compliance timelines and USDA transition subsidy allocation patterns.
The analysis sits within stated boundaries; outcomes outside sustained certification premium retention or equivalence agreement stability would require recalibration. Forecasts reflect documented assumptions around input cost trajectories and retail procurement consolidation pace. Regulatory fragmentation risk and biological supply weather volatility represent primary revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Limestone for Agriculture Market
Agriculture and Agri Products
Animal Feed and Pet Food Market
Agriculture and Agri Products
Greenhouse Horticulture Market
Agriculture and Agri Products
Ginseng Market
Agriculture and Agri Products
United States Compound Feed Market
Agriculture and Agri Products
Henequen Market
Agriculture and Agri Products
Europe Eggs Market
Agriculture and Agri Products
Asia-Pacific Compound Feed Market
Agriculture and Agri Products
Brazil Compound Feed Market
Agriculture and Agri Products
Lucerne Market
Agriculture and Agri Products
Brazil Cashew Market
Agriculture and Agri Products
Prunus Africana Market
Agriculture and Agri Products
Tarragon Market
Agriculture and Agri Products
United Kingdom Poultry Meat Market
Agriculture and Agri Products
Livestock and Meat Market
Agriculture and Agri Products
Clover Leaf Oil Market