
 Africa Fertilizers Market | 2026-2036
Africa Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Fertilizers Market Outlook
A widening capital-intensity divergence between integrated phosphate producers and import-dependent blenders is unwinding competitive stability across the continent. OCP Group leverages captive phosphate rock reserves in Morocco to sustain cost leadership in upstream phosphate fertilizers. Yara International ASA anchors its position through ammonia manufacturing scale and deep-water port logistics that reduce landed costs for East African buyers. Kynoch Fertilizer competes via localized blending capacity in South Africa, allowing rapid formulation shifts for regional soil profiles.
Africa fertilizers encompass nitrogen, phosphorus, and potassium compounds formulated to correct soil nutrient deficits, with urea typically containing 46% nitrogen by weight and phosphate fertilizers derived from beneficiated rock phosphate processed through acidulation. These inputs restore depleted macronutrients in tropical soils that have endured decades of extractive cropping without replenishment. Urea dominates product type volumes due to its high nitrogen concentration and established import infrastructure, while phosphate fertilizers command margin premiums in West African markets where lateritic soils exhibit severe phosphorus fixation. Potassium fertilizers represent the fastest-growing product category as precision agriculture spreads among commercial farming operations in Zambia and Tanzania.
Nigeria's fertilizer quality regulator enforces minimum nutrient content standards for imported products, while South Africa's Department of Agriculture mandates registration and labeling compliance through its fertilizer control framework. The African Union's fertilizer financing mechanisms are reshaping how governments procure bulk supplies and distribute through cooperative channels. Stakeholders must monitor how carbon border adjustments in European export markets could redirect Moroccan and Algerian fertilizer flows toward intra-African trade corridors.
Market Dynamics
Capital-intensity divergence between integrated phosphate producers and import-dependent blenders is unwinding competitive stability across Africa's fertilizer landscape. Moroccan captive rock reserves versus East African ammonia importers exemplifies this structural tension.
Growth Catalysts
- CAADP subsidy frameworks:The African Union's Comprehensive Africa Agriculture Development Programme is reshaping government procurement and cooperative distribution channels across member states.
- Commercial farming expansion:Large-scale maize and sorghum operations in Nigeria's northern grain belt require sustained nutrient replenishment, concentrating demand pull.
- Precision agriculture diffusion:Variable-rate application technology spreads among Zambian and Tanzanian commercial growers, elevating potassium fertilizer uptake.
Market Restraints
- Natural gas price volatility:Ammonia synthesis depends on natural gas feedstock, exposing nitrogen fertilizer costs to global energy market swings.
- Phosphate rock concentration:Moroccan and Algerian producers control upstream phosphate reserves, creating supply security risks for import-dependent blenders.
- Lateritic phosphorus fixation:West African soils chemically bind applied phosphorus, reducing agronomic efficiency and requiring higher application rates.
Strategic Opportunities
- Intra-African trade corridor development:Carbon border adjustments in European export markets could redirect Moroccan and Algerian fertilizer flows toward regional buyers.
- Localized blending capacity:Rapid formulation shifts for regional soil profiles remain underdeveloped outside South Africa's established infrastructure.
- Cooperative distribution channels:Government bulk procurement through farmer cooperatives offers channel innovation potential in Ethiopia and Kenya.
Industry Challenges
- Soil science expertise scarcity:Agronomists capable of prescribing balanced NPK formulations for tropical soil conditions remain concentrated in research institutions.
- Port and inland logistics bottlenecks:Deep-water port access and last-mile distribution require sustained capital deployment in East African markets.
- Quality enforcement fragmentation:Nigeria's minimum nutrient standards and South Africa's registration frameworks create compliance complexity for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Fertilizers Market |
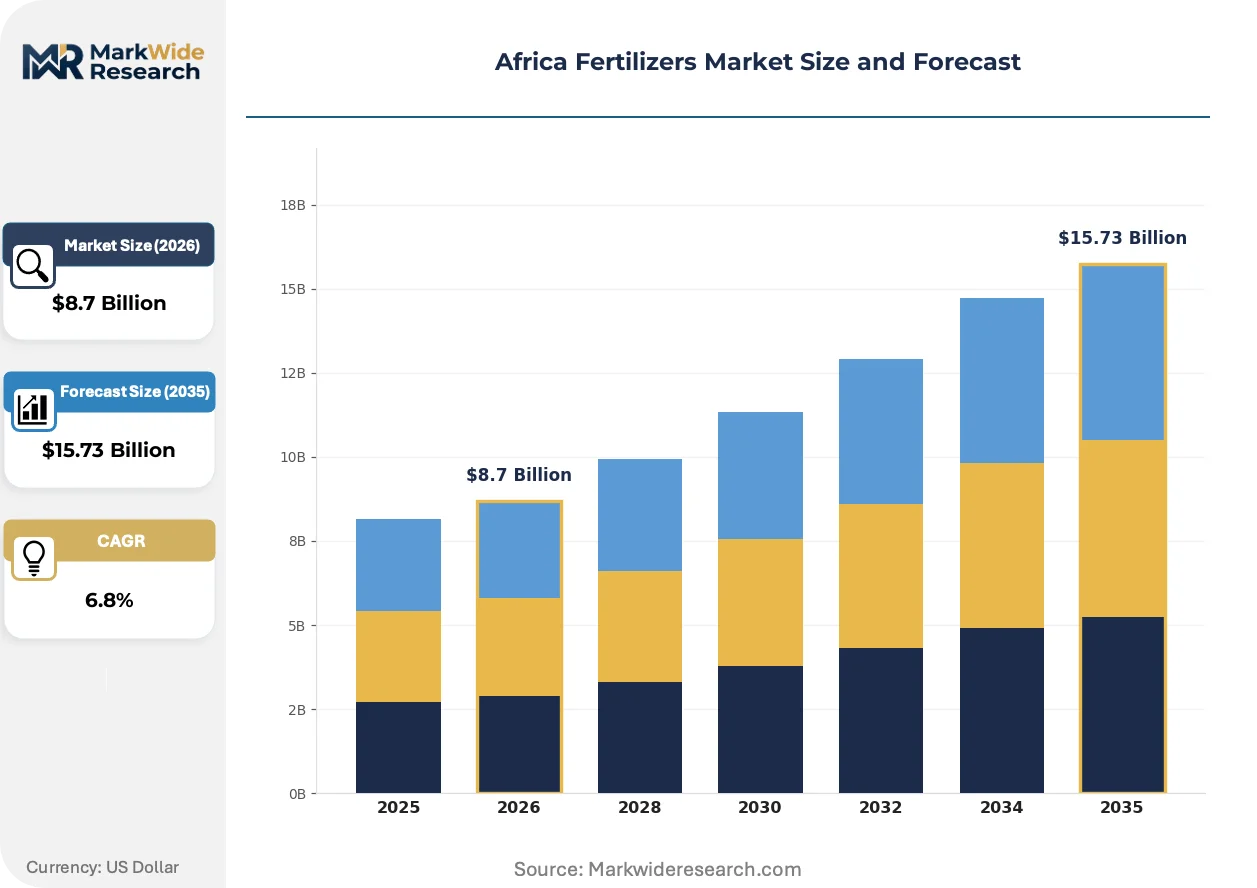
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urea, Ammonium Nitrate, Potassium Fertilizers, Phosphate Fertilizers End Use Industry: Agriculture, Horticulture, Commercial Farming, Organic Farming Application: Crops, Vegetables, Fruits, Lawns Distribution Channel: Direct Sales, Retail Outlets, Online, Cooperatives |
| Companies Covered | ICL Group Ltd, Haifa Group, OCP Group, Omnia Fertilizer, Kynoch Fertilizer, Yara International ASA, K+S Aktiengesellschaft, SABIC Agri-Nutrients Co., Foskor, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Fertilizers Market Strategic Shifts
Digital soil mapping and controlled-release formulations are reshaping how African growers match nutrient inputs to specific field conditions. These innovations promise to reduce waste while improving yield response curves.
Controlled-release urea coatings is bifurcating the nitrogen product landscape. Commercial farming operations in Kenya and Ethiopia adopt polymer-sulfur coated variants to reduce volatilization losses. This technology is bifurcating price tiers between commodity urea and premium stabilized formulations.
REACH-equivalent substance registration requirements are tightening as African regulators harmonize with European chemical safety protocols. Nigeria's fertilizer quality regulator now enforces minimum nutrient content verification for all imported products. West African blenders face reformulation costs to meet emerging contaminant thresholds.
Cooperative bulk purchasing displaces individual farm-level procurement in Nigeria's grain belt. Farmer organizations aggregate demand to access government-subsidized import volumes previously reserved for state channels. This aggregation pattern concentrates buyer power while compressing blender margins.
Africa Fertilizers Market Segmentation
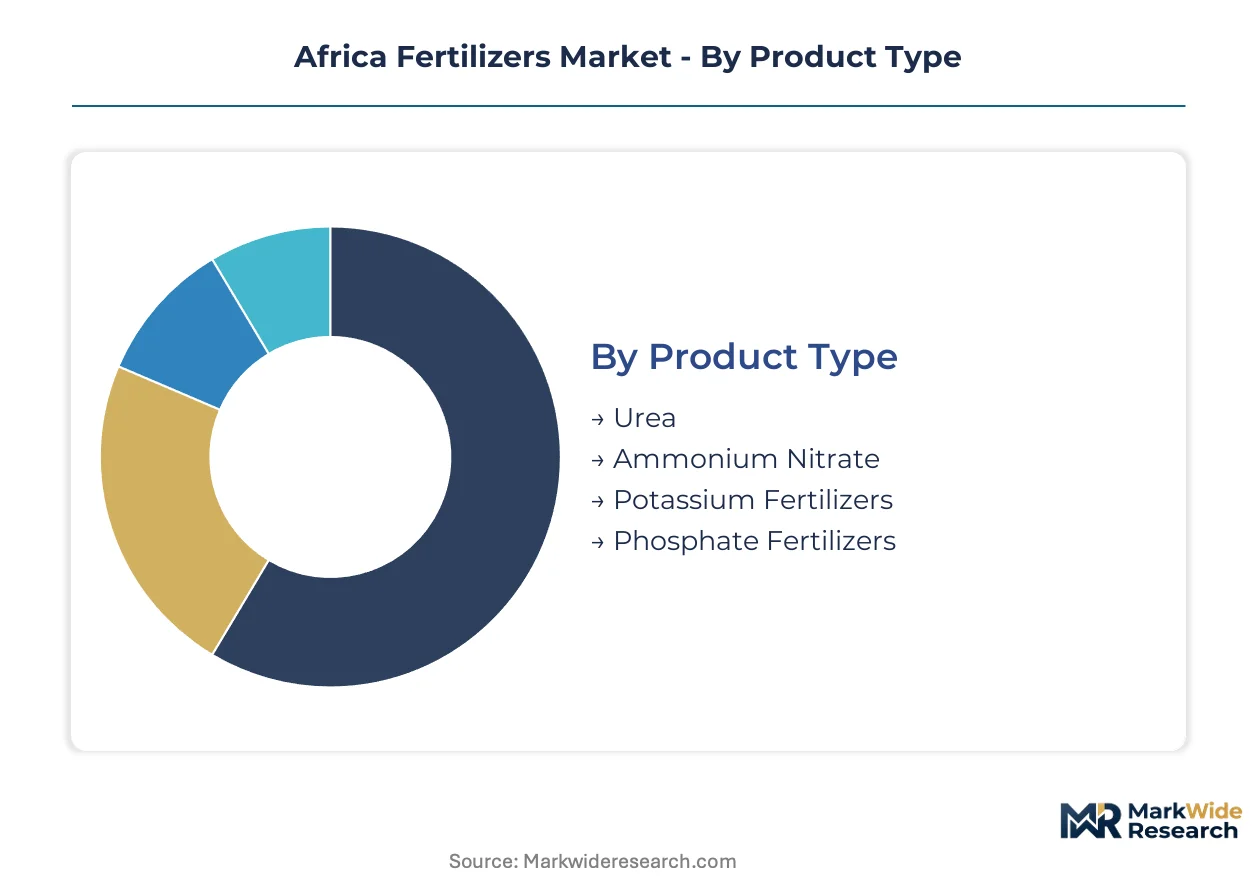
Fertilizer segmentation in Africa reveals how nutrient chemistry, crop economics, and channel infrastructure interact to determine commercial viability. Understanding these divides exposes where substitution pressures and margin compression concentrate most acutely.
Product Type:
Substitution pressure runs strongest against commodity nitrogen where polymer-coated alternatives erode traditional urea economics.
- Urea:Contains 46% nitrogen by weight, the highest concentration of any solid fertilizer. Demand concentrates in Nigeria's northern grain belt where maize and sorghum producers prioritize cost-per-unit-nitrogen over application flexibility. Volatilization losses in tropical heat constrain agronomic efficiency.
- Phosphate Fertilizers:Derived from acidulated phosphate rock, these compounds address severe phosphorus fixation in West African lateritic soils. Moroccan captive reserves supply upstream material while blenders in Senegal and Ghana formulate region-specific grades. Premium pricing reflects beneficiation complexity and transport distance from mine mouth.
- Potassium Fertilizers:Muriate of potash and sulfate of potash formulations gain traction in Zambia and Tanzania where precision agriculture enables variable-rate application. Soil testing penetration drives prescription accuracy.
- Ammonium Nitrate:Dual-nutrient composition delivers nitrogen plus calcium in water-soluble form. Security restrictions on explosive precursor classification limit distribution flexibility in East African markets.
Urea anchors the volume base while potassium fertilizers gain share at the steepest rate.
End Use Industry:
Cost tier divergence separates subsidized smallholder channels from commercial operations paying import-parity prices.
- Agriculture:Encompasses subsistence and semi-commercial cereal production across the Sahel and East African highlands. CAADP subsidy frameworks determine effective demand through government procurement volumes.
- Commercial Farming:Large-scale operations in Kenya's Rift Valley and Ethiopia's Awash Valley purchase direct from importers or blenders. Credit terms and formulation customization drive supplier selection.
- Horticulture:Export-oriented flower and vegetable producers in Kenya and Tanzania require water-soluble specialty grades. Phytosanitary certification requirements in European export markets dictate input quality standards.
- Organic Farming:Certified operations in South Africa's Western Cape and Uganda's Mount Elgon region restrict synthetic input use. Biofertilizer and compost derivatives compete for nutrient budget allocation.
Traditional agriculture commands absolute volume while commercial farming expands most quickly as land consolidation accelerates.
Application:
Application method and timing requirements create distinct formulation specifications across crop categories.
- Crops:Maize, sorghum, millet, and wheat dominate tonnage. Basal dressing at planting and top-dressing at tillering stages generate seasonal demand spikes synchronized with rainfall patterns.
- Vegetables:Tomato, onion, and cabbage production in peri-urban zones around Lagos, Nairobi, and Addis Ababa requires micronutrient-inclusive NPK blends. Drip irrigation compatibility determines water-solubility specifications.
- Fruits:Citrus in Egypt's Nile Delta and banana plantations in Cameroon apply fertigation systems. Controlled-release formulations reduce labor costs in remote orchards.
- Lawns:Golf courses and estate landscaping in South Africa's Gauteng and Nigeria's Abuja represent a niche premium segment. Slow-release nitrogen prevents burn on high-visibility turf.
Staple crops absorb the bulk of volume while vegetables climb the fastest on commercial intensification.
Distribution Channel:
Channel configuration determines working capital intensity and price realization for suppliers.
- Cooperatives:Farmer organizations in Ethiopia's Oromia region and Kenya's grain belt aggregate demand to access government-subsidized import allocations. Bulk purchasing compresses blender margins while concentrating buyer power.
- Direct Sales:Large estates and commercial farms negotiate annual supply contracts with Moroccan phosphate exporters or regional blenders. Volume commitments secure preferential pricing and guaranteed offtake.
- Retail Outlets:Agro-dealer networks in Nigeria's Kano and Kaduna states provide last-mile access for smallholders. Working capital constraints limit inventory depth during planting season surges.
- Online:E-commerce platforms in South Africa and Kenya aggregate input orders with mechanization and seed purchases. Logistics partnerships with last-mile couriers remain underdeveloped outside major urban corridors.
Cooperative channels dominate volume throughput while direct sales capture margin at the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Africa's fertilizer trade flows reflect a stark import dependency, with Morocco and Algeria anchoring phosphate exports while East African markets absorb nitrogen and potassium shipments through Mombasa and Dar es Salaam ports. The continent's regional divisions trace soil chemistry, subsidy regimes, and port access rather than political boundaries.
Nigeria
Maize and sorghum producers in the northern grain belt drive sustained urea consumption through government-backed cooperative channels. The fertilizer quality regulator enforces minimum nutrient content verification for all imported products, tightening compliance burdens on blenders. Kano and Kaduna states host agro-dealer networks that manage last-mile distribution during compressed planting windows.
Kenya
Commercial farming operations in the Rift Valley purchase direct from importers, prioritizing credit terms and formulation customization over subsidized alternatives. The Agriculture and Food Authority administers registration and labeling compliance through national fertilizer control frameworks. Nairobi-based logistics providers coordinate deep-water port access with inland trucking to Ethiopian and Ugandan buyers.
Ethiopia
Large-scale operations in the Awash Valley negotiate annual supply contracts, securing guaranteed offtake through volume commitments. The Ethiopian Agricultural Transformation Agency shapes cooperative distribution channels that aggregate smallholder demand. Oromia region farmer organizations access government-subsidized import allocations previously reserved for state procurement.
Morocco
OCP Group leverages captive phosphate rock reserves to sustain cost leadership in upstream phosphate fertilizer production for regional export. The national phosphates office coordinates beneficiation capacity expansion targeting West African lateritic soil markets. Casablanca-Jorf Lasfar industrial corridor processes acidulated phosphate rock for shipment to Senegalese and Ghanaian blenders.
South Africa
Kynoch Fertilizer competes through localized blending capacity that enables rapid formulation shifts for regional soil profiles. The Department of Agriculture mandates registration and labeling compliance through its fertilizer control framework. Gauteng province golf courses and estate landscaping represent a niche premium segment for slow-release nitrogen formulations.
Africa Fertilizers Market Competitive Environment
Concentration sits with integrated phosphate producers holding captive rock reserves, while nitrogen and potassium segments fragment across import-dependent blenders and trading houses. Moroccan upstream dominance contrasts with East African ammonia importers exposed to natural gas price volatility. Two strategic archetypes define competitive positioning: vertically integrated phosphate miners with beneficiation assets, and regional blenders with formulation flexibility and cooperative channel access. Capacity expansion in Moroccan beneficiation and South African blending infrastructure represent the dominant competitive moves reshaping supply security.
Among integrated phosphate specialists, OCP Group exemplifies the captive-reserve archetype through Moroccan upstream control. Yara International ASA occupies a position among ammonia manufacturing scale players with deep-water port logistics reducing landed costs for East African buyers. Kynoch Fertilizer represents the localized blending tier, anchoring rapid formulation capability for regional soil profiles outside South Africa's established infrastructure.
| Leading Market Players |
|---|
| ICL Group Ltd |
| Haifa Group |
| OCP Group |
| Omnia Fertilizer |
| Kynoch Fertilizer |
| Yara International ASA |
| K+S Aktiengesellschaft |
| SABIC Agri-Nutrients Co. |
| Foskor |
| Others |
Value Chain & Pricing Dynamics
Captive beneficiation capacity at Jorf Lasfar anchors cost leadership for Moroccan phosphate exporters while constraining price floors for nitrogen importers exposed to volatile natural gas feedstock costs. Scale economies in upstream rock processing cascade through West African markets, compressing blender margins in Senegal and Ghana while sustaining premium realization for specialized formulations.
Pricing Analysis
Commercial farming operations anchor contract-based long-term offtake pricing, with annual volume commitments securing preferential terms over spot-market procurement. Price differentiation hinges on formulation customization depth and cooperative channel access, with direct sales to large estates commanding premiums over subsidized smallholder tiers. Cost compression in commodity urea intensifies as polymer-coated alternatives displace standard grades among Kenyan and Ethiopian growers. Smallholder cooperatives exhibit highest price sensitivity, while export-oriented horticulture operations in Tanzania prioritize quality certification over unit economics.
Supply Chain Analysis
Morocco and Algeria anchor upstream phosphate fertilizer production, while Nigeria and Kenya concentrate nitrogen blending and distribution infrastructure. Raw material dependencies center on phosphate rock beneficiation, ammonia synthesis feedstock, and potash extraction from Belarusian and Canadian sources. Single-source vulnerability concentrates in Moroccan captive reserves, exposing import-dependent blenders to supply security disruptions. Distribution runs through cooperative bulk purchasing channels in Ethiopia's Oromia region and agro-dealer networks in Nigeria's northern states, with deep-water port access at Mombasa and Dar es Salaam conditioning East African landed costs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Africa's fertilizer market presents a defensive-moat story anchored in regulatory entrenchment: CAADP subsidy frameworks and national quality verification regimes create switching costs that protect incumbent positions against unqualified imports.
For Market Incumbents: Consolidate cooperative channel relationships in Nigeria's grain belt and Ethiopia's Awash Valley to defend against emerging regional blenders with localized formulation capability. Prioritize backward integration into ammonia manufacturing or captive phosphate sourcing to mitigate natural gas price volatility exposure. Secure CAADP-aligned procurement contracts before subsidy framework revisions redirect government allocations. For New Entrants and Emerging Players: Differentiate on precision agriculture-enabled potassium formulations for Zambian and Tanzanian commercial growers where soil testing penetration remains nascent. Target localized blending capacity in East African markets outside South Africa's established infrastructure, leveraging rapid NPK customization for lateritic soil conditions. Pursue cooperative distribution partnerships to access government-subsidized import allocations previously reserved for incumbent channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated phosphate producers with captive rock reserves and long-term offtake contracts with West African governments. Five-to-ten year viability favors beneficiaries of intra-African trade corridor development as carbon border adjustments redirect Moroccan and Algerian flows from European markets. Monitor Nigerian fertilizer quality regulator enforcement intensity as signal for compliance-cost inflection affecting import-dependent blender economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonia Manufacturing | Reduces exposure to natural gas price volatility for nitrogen fertilizer producers. |
| Localized Blending Capacity Expansion | Enables rapid formulation shifts for West African lateritic soil profiles. |
| Cooperative Distribution Channel Partnerships | Unlocks access to CAADP-subsidized procurement volumes in Ethiopia and Kenya. |
| Controlled-Release Formulation Development | Captures premium pricing from Kenyan and Ethiopian commercial farming operations. |
| Intra-African Trade Corridor Positioning | Anticipates redirection of Moroccan phosphate flows from European export markets. |
Study Parameters
A standing panel of fertilizer procurement officers at commercial farming operations, blending plant managers, and cooperative distribution coordinators provided ongoing calibration against secondary validation from customs records, African Union CAADP implementation reports, and national fertilizer control framework filings. Primary interviews with agronomists at research institutions and port logistics operators at Mombasa and Dar es Salaam supplemented demand-side and infrastructure assessments. Bottom-up volume modeling triangulated against top-down macroeconomic projections across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including trade flow databases and national agricultural input surveys. The analytical framework modeled segmentation across product type, end-use industry, application method, and distribution channel throughout the forecast period. CAGRs derived from regression analysis of historical consumption patterns and projected acreage expansion under CAADP targets, with natural gas price scenarios and phosphate rock supply assumptions as key industry-specific inputs.
Forecasts assume regulatory continuity in Nigerian quality verification regimes and South African registration frameworks; material policy shifts would require re-modeling. Specific risks include CAADP subsidy framework revisions, carbon border adjustment implementation timing in European markets, and phosphate rock supply disruptions from concentrated Moroccan production. Recalibration cycles align with material shifts in subsidy allocation patterns and intra-African trade corridor development milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
China Specialty Fertilizer Market
Fertilizers
Fertilizer Applicators Market
Fertilizers
Polymer Coated Urea Market
Fertilizers
United States Specialty Fertilizer Market
Fertilizers
Nitro Compound Fertilizers Market
Fertilizers
United States Fertilizers Market
Fertilizers
Enhanced Efficiency Fertilizer Market
Fertilizers
Humate Fertilizer Market
Fertilizers
North America Specialty Fertilizer Market
Fertilizers
India Fertilizers Market
Fertilizers
Russia Specialty Fertilizer Market
Fertilizers
Thailand Fertilizers Market
Fertilizers
Diammonium Hydrogen Phosphate (DAP) Market
Fertilizers
China Micronutrient Fertilizer Market
Fertilizers
India Specialty Fertilizer Market
Fertilizers
Global Phosphatic Fertilizers Market