
 Baby Food and Infant Formula Market | 2026-2036
Baby Food and Infant Formula Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Food and Infant Formula Market Intelligence
Precision fermentation and enzymatic processing is narrowing the gap between conventional dairy-based formulas and bioactive-equivalent alternatives. Nestlé S.A. leverages its pharmaceutical-grade manufacturing infrastructure to sustain regulatory compliance across multiple jurisdictions. Danone S.A. anchors its competitive position through specialized medical nutrition segments for infants with metabolic disorders. Abbott Laboratories differentiates via extensive clinical research partnerships that validate proprietary nutrient blends.
Baby food and infant formula comprises nutritionally complete or complementary feeding products designed for children from birth through toddlerhood, typically formulated to deliver precise macronutrient ratios, essential fatty acids, and micronutrient profiles that mirror or supplement human milk composition. These products serve the fundamental commercial purpose of providing safe, standardized nutrition during developmental windows when dietary adequacy directly influences cognitive and physical growth trajectories. Formula products command the largest value pool due to premium pricing on hypoallergenic and specialized variants, while organic ingredient-type offerings represent the fastest-expanding margin segment as certification requirements filter out commoditized competitors. Online stores as a distribution channel are displacing traditional supermarket dominance in direct-to-subscription models, though pharmacies retain structural importance in markets where formula classification as quasi-medical products triggers reimbursement or prescription-adjacent purchasing behavior.
The FDA enforces infant formula quality and nutrient specifications under the Federal Food, Drug, and Cosmetic Act, while the EMA coordinates member-state oversight through harmonized compositional standards and notification procedures. China's SAMR operates a stringent formula registration system requiring clinical evidence and on-site manufacturing audits that have eliminated numerous foreign brands from shelf access. Stakeholders must monitor divergence between regional microbiome research agendas and resulting probiotic strain approval lists, as these scientific boundaries will determine which product portfolios achieve multi-jurisdiction commercial viability without costly reformulation.
Market Dynamics
China's SAMR formula registration system operates as the dominant structural filter, eliminating subscale foreign entrants while concentrating shelf access among manufacturers with pharmaceutical-grade compliance infrastructure and clinical evidence portfolios.
Growth Catalysts
- Dual-income household expansion:Working parents in urban China and the United States prioritize convenience-driven feeding solutions that reduce preparation time without compromising nutritional completeness.
- GB standards evolution:China's tightening national food safety standards on infant formula composition create competitive moats for compliant manufacturers while filtering commoditized imports from lower-tier domestic producers.
- Precision fermentation maturation:Enzymatic processing advances enable bioactive-equivalent lipid and protein structures that narrow functional gaps with human milk oligosaccharides.
Market Restraints
- Input cost volatility:Organic dairy and specialty oil feedstocks face agricultural supply shocks that compress margin structures for certified product lines.
- Regulatory friction:Divergent probiotic strain approval lists between FDA, EMA, and NMPA jurisdictions force portfolio fragmentation and reformulation costs.
- Technical limitation:Current microbiome replication science cannot yet synthesize the full spectrum of human milk glycans at commercial scale.
Strategic Opportunities
- Direct-to-subscription channel emergence:Online stores displace traditional supermarket dominance through recurring revenue models that capture lifetime customer value.
- Medical nutrition specialization:Metabolic disorder formulations for infants represent underserved segments with reimbursement-adjacent pricing power.
- Urban India penetration:Middle-class density in Mumbai, Delhi, and Bangalore creates addressable demand for fortified and organic positioning.
Industry Challenges
- Pharmaceutical-grade talent scarcity:Formulation scientists with cross-training in pediatric nutrition and regulatory dossier preparation command premium compensation and limited supply.
- SAMR audit timeline compression:On-site manufacturing inspections and clinical evidence reviews extend product launch cycles beyond typical working capital planning horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Food and Infant Formula Market |
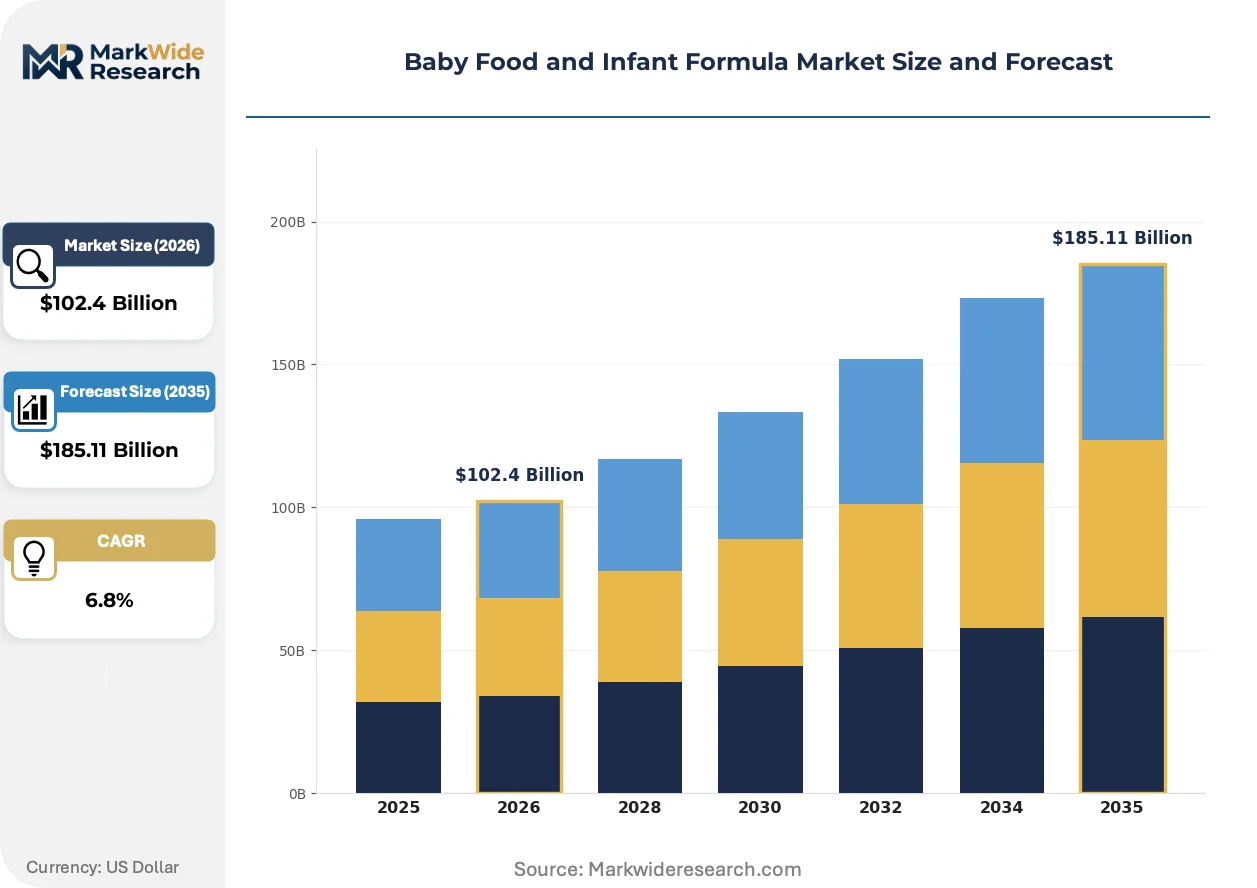
| Market Size in 2026 | $102.4 Billion |
| Market Size in 2035 | $185.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Puree, Cereal, Snacks, Formula Ingredient Type: Organic, Non-Organic, Fortified, Gluten-Free Distribution Channel: Supermarkets, Online Stores, Pharmacies, Specialty Retailers Package Size: Single Serve, Family Pack, Bulk, Variety Pack |
| Companies Covered | Nestlé S.A., Danone S.A., Abbott Laboratories, Reckitt Benckiser Group, The Kraft Heinz Company, FrieslandCampina, The Hain Celestial Group, Hero Group, Perrigo Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Food and Infant Formula Market Strategic Shifts & Innovations
Biotechnology convergence with pediatric nutrition science is compressing development cycles for next-generation formulations while regulatory harmonization efforts fragment across major jurisdictions.
Precision fermentation platforms for human milk oligosaccharide synthesis are rendering obsolete conventional corn syrup and plant-based fat blends in premium formula positioning. Urban Chinese parents with household incomes exceeding tier-one city medians adopt these bioactive-equivalent products at rates outpacing manufacturer capacity expansion. The technology is compressing R&D amortization periods while elevating technical barriers to formulation parity.
China's SAMR infant formula registration system now mandates on-site manufacturing audits and domestic clinical trials that foreign entrants without local production assets cannot satisfy. This policy architecture eliminates brand portfolios dependent on pure import models while privileging manufacturers with captive Chinese manufacturing infrastructure. European and North American producers with pre-existing pharmaceutical plant networks capture disproportionate registration success rates.
Subscription-based replenishment models displace traditional retail purchasing among millennial parents in the United States and United Kingdom. Direct-to-consumer platforms capture recurring revenue through algorithmic dosing reminders and pediatrician partnership content. This channel rotation concentrates customer data ownership with manufacturers while reducing price transparency and comparison shopping frequency.
Baby Food and Infant Formula Market Segmentation
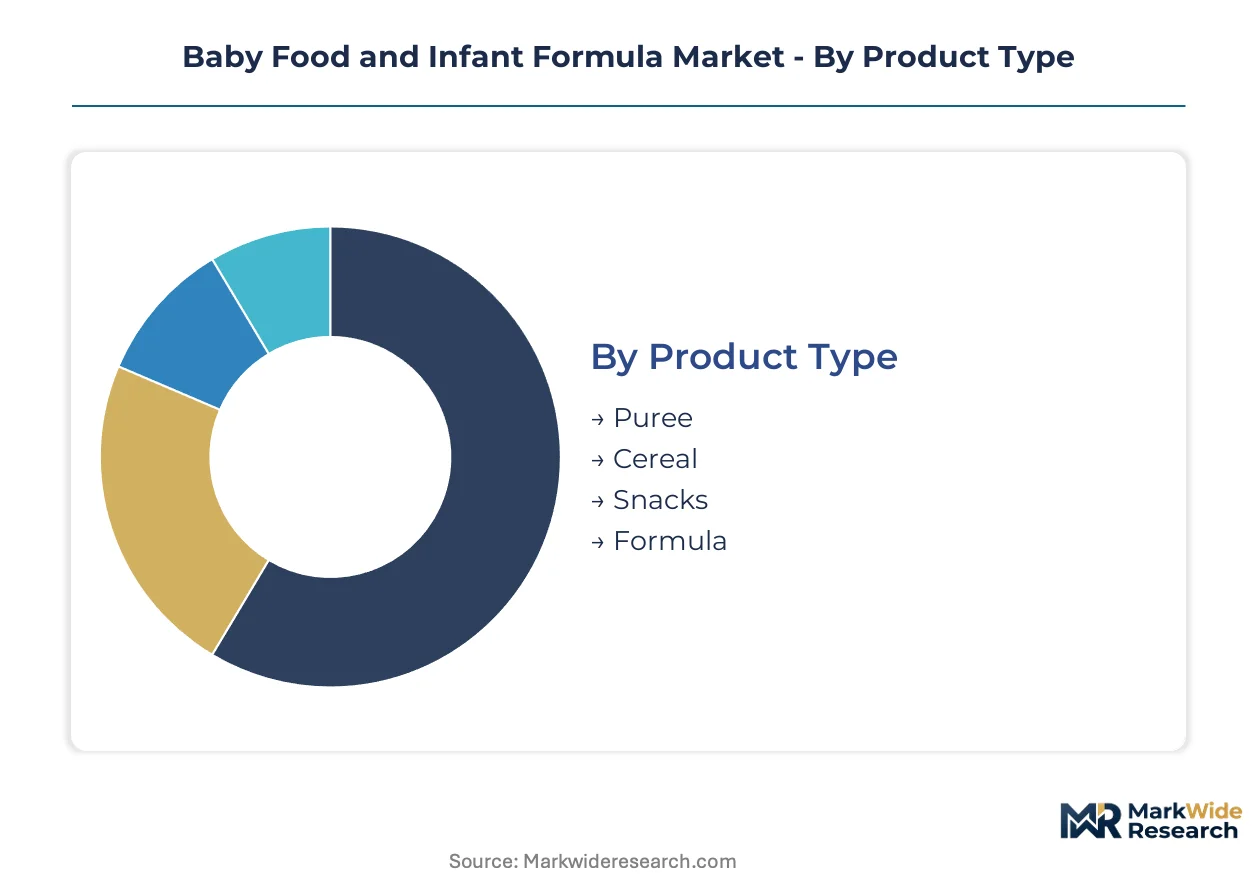
Segmentation in baby food and infant formula reveals distinct margin architectures and channel requirements. Product type determines formulation complexity and regulatory burden, while ingredient type drives certification costs and pricing power. Distribution channel selection shapes customer acquisition economics and lifetime value capture.
Product Type:
After-sales intensity varies sharply across product types, with formula requiring clinical support and feeding guidance while purees demand minimal post-purchase engagement.
- Formula:Nutritionally complete breast milk substitutes with precise macronutrient ratios, essential fatty acids, and micronutrient profiles. Demand concentrates among dual-income households in urban China where SAMR registration requirements filter non-compliant imports. Working parents prioritize convenience without compromising developmental nutrition.
- Puree:Single-ingredient or blended fruit and vegetable preparations for complementary feeding stages. Adoption accelerates in United States metropolitan markets where millennial parents favor clean-label transparency and transparent sourcing claims over conventional jarred alternatives.
- Cereal:Iron-fortified grain-based first foods designed for developmental readiness. Rice and oat variants dominate initial feeding transitions.
- Snacks:Finger foods and puffs for toddler self-feeding development. Puff formats with dissolvable textures capture shelf space in specialty retailers.
Formula holds the largest share; momentum sits with puree as clean-label positioning gains traction.
Ingredient Type:
Cost tier stratification separates certified organic at premium price points from fortified conventional offerings at mid-market positioning.
- Organic:Products certified to USDA, EU organic, or China organic standards with prohibited synthetic inputs. Urban Chinese parents in tier-one cities adopt organic positioning at rates outpacing domestic supply capacity, creating import dependency.
- Fortified:Conventional base ingredients with added iron, zinc, vitamins A and D, or DHA for developmental support. Medicaid and WIC reimbursement programs in United States sustain volume concentration despite lower per-unit margins.
- Non-Organic:Standard agricultural inputs without certification premiums. Price-sensitive segments in lower-tier Chinese cities and rural India sustain residual demand.
- Gluten-Free:Celiac-safe formulations using rice, quinoa, or certified oat bases. Medical necessity drives prescription-adjacent purchasing through pharmacy channels in European markets.
Fortified products anchor volume; organic certification commands the steepest expansion trajectory.
Distribution Channel:
Channel maturity separates established supermarket dominance from emerging direct-to-subscription models capturing recurring revenue.
- Online Stores:Direct-to-consumer platforms with algorithmic replenishment and pediatrician partnership content. Subscription models in United States and United Kingdom displace price comparison by locking in recurring purchase patterns.
- Supermarkets:Mass-market retail with high foot traffic and promotional intensity. Shelf space allocation in Walmart, Carrefour, and Tesco networks determines brand visibility for entry-level positioning.
- Pharmacies:Quasi-medical classification triggers prescription-adjacent purchasing and reimbursement eligibility. Boots and CVS formats in United Kingdom and United States retain structural importance for specialized formulas.
- Specialty Retailers:Boutique formats targeting affluent parents with curated organic and premium assortments. Buy Buy Baby and independent natural grocers concentrate in high-income zip codes.
Supermarkets retain the largest share; online stores are expanding most quickly through subscription lock-in.
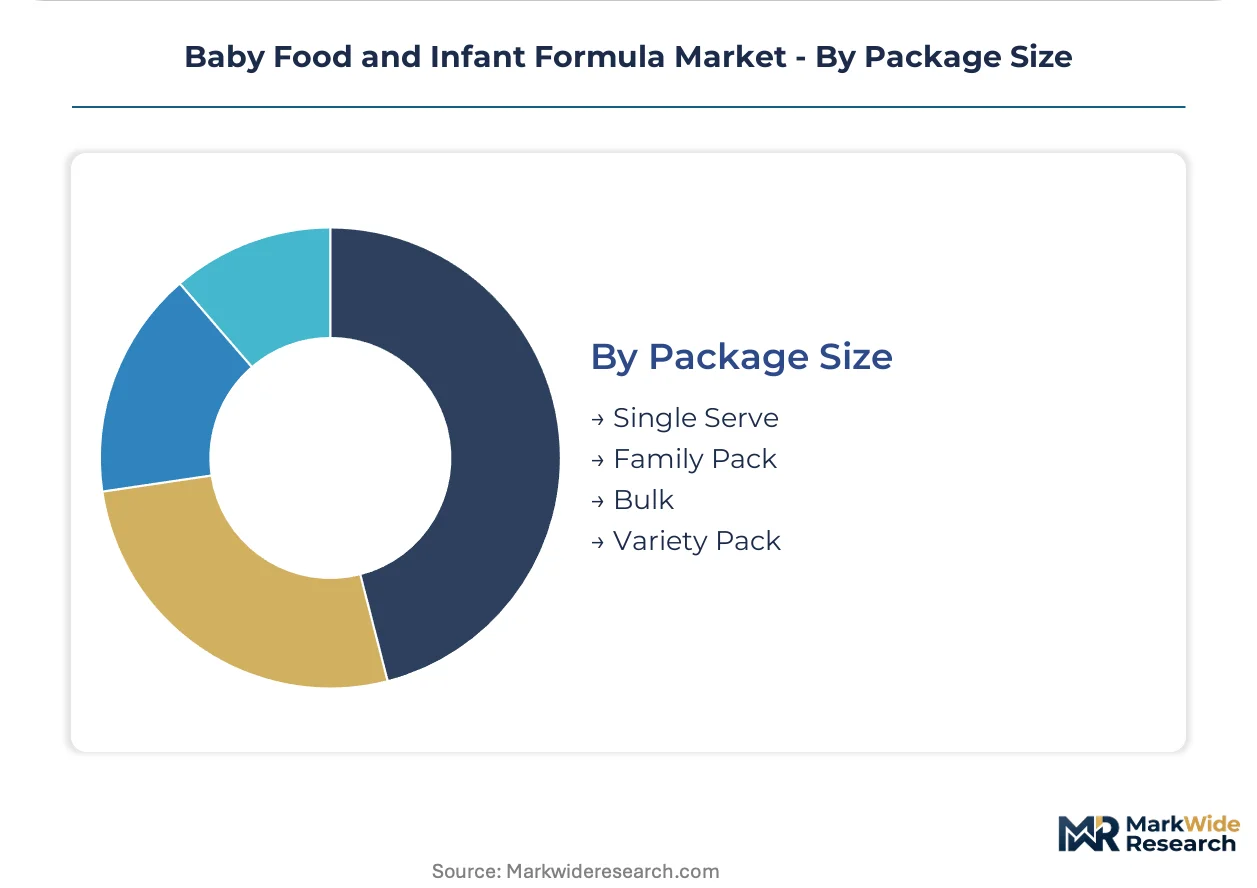
Package Size:
Volume economics favor family pack and bulk formats while single serve captures trial and travel occasions.
- Family Pack:Multi-serving containers designed for household consumption over 7-14 day windows. Cost-per-gram efficiency appeals to budget-conscious parents in United States suburban markets.
- Single Serve:Portion-controlled pouches and ready-to-feed bottles for travel and daycare compliance. On-the-go feeding requirements in Japanese and South Korean urban centers sustain premium pricing.
- Bulk:Institutional sizing for childcare facilities and multi-child households. Food service distributors in United States and Canada manage this channel with limited brand visibility.
- Variety Pack:Assorted flavors or formats for palate development and trial reduction. Gift-oriented purchasing in Chinese holiday seasons drives seasonal volume spikes.
Family pack holds the largest share; single serve formats gain share fastest through convenience positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency characterizes the trade balance across major consuming markets, with finished formula products flowing from manufacturing-strong jurisdictions toward demand-concentrated urban centers. Regulatory divergence on registration requirements and ingredient approvals shapes cross-border commercial viability.
United States
Dual-income households in metropolitan corridors sustain premium formula consumption despite WIC program concentration in fortified conventional tiers. The FDA enforces infant formula quality specifications under the Federal Food, Drug, and Cosmetic Act with stringent nutrient mandate compliance. Manufacturing clusters in Illinois and Michigan anchor domestic production capacity serving pharmacy and supermarket channels.
China
Urban middle-class parents in tier-one cities drive organic and bioactive-equivalent formula adoption at rates exceeding domestic supply capacity. SAMR operates a stringent registration system requiring on-site manufacturing audits and domestic clinical trials that filter pure-import brands. Production assets in Jiangsu and Zhejiang provinces concentrate among multinational manufacturers with pharmaceutical-grade compliance infrastructure.
Germany
Organic certification demand from environmentally conscious parents supports premium pricing on EU-standard products. The EMA coordinates member-state oversight through harmonized compositional standards and notification procedures. Industrial concentration in Bavaria and Baden-Württemberg hosts formulation facilities serving both domestic pharmacy channels and export markets.
India
Middle-class density in Mumbai, Delhi, and Bangalore creates addressable demand for fortified and organic positioning as breastfeeding duration shortens among working mothers. FSSAI regulates infant food standards with evolving safety specifications that foreign entrants navigate through joint venture structures. Maharashtra and Karnataka sub-regions concentrate modern retail expansion where online stores displace traditional distribution.
Australia
Chinese cross-border e-commerce demand for clean-label organic products sustains export-oriented production at premium price points. TGA oversees therapeutic goods classification that affects specialized formula distribution through pharmacy networks. Manufacturing in Victoria and New South Wales supplies direct-to-consumer platforms with algorithmic replenishment models.
Baby Food and Infant Formula Market Key Industry Players
On the supply side, the industry is consolidating around pharmaceutical-grade compliance infrastructure as regulatory barriers eliminate subscale participants. Tiered competitive positioning separates multinational manufacturers with captive clinical research capabilities from regional processors dependent on contract formulation. Three archetypes dominate: diversified nutrition conglomerates with cross-category R&D amortization, specialized pediatric medical nutrition operators, and private-label contract manufacturers serving retail channel consolidation. Competitive moves concentrate on SAMR registration acquisition and precision fermentation technology licensing.
Within the diversified nutrition tier, Nestlé S.A., Danone S.A., and Abbott Laboratories occupy positions defined by manufacturing asset depth and multi-jurisdiction regulatory dossier capabilities. These Switzerland-based, France-based, and United States-based entities exemplify the pharmaceutical-grade compliance archetype required for China's registration system. Their positioning reflects accumulated clinical evidence portfolios and on-site audit readiness rather than discrete product-level differentiation.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Danone S.A. |
| Abbott Laboratories |
| Reckitt Benckiser Group |
| The Kraft Heinz Company |
| FrieslandCampina |
| The Hain Celestial Group |
| Hero Group |
| Perrigo Company |
| Others |
Cost & Logistics Intelligence
Jiangsu and Zhejiang provinces anchor global infant formula manufacturing capacity, with pharmaceutical-grade plant networks concentrating among multinationals that leverage this supply density to sustain premium pricing power in SAMR-regulated channels. Input cost volatility in organic dairy and specialty oil feedstocks compresses margin structures for certified product lines, forcing tiered pricing stratification that separates bioactive-equivalent formulations from conventional alternatives.
Pricing Analysis
Urban dual-income households anchor pricing power for manufacturers with SAMR registration credentials, with three-tier pricing structure across premium, standard, and economy levels reflecting certification grade and bioactive content differentiation. Price differentiation stems from organic certification tier and pharmaceutical-grade manufacturing compliance, with pricing pressure intensifying in conventional tiers due to agricultural supply shocks in specialty oil feedstocks. WIC-dependent buyers in the United States exhibit highest price sensitivity, while tier-one Chinese parents purchasing bioactive-equivalent formulas show lowest elasticity.
Supply Chain Analysis
Contract manufacturing concentration rests with pharmaceutical-grade facilities in Switzerland, France, and the Netherlands serving multinational brand portfolios with cross-jurisdiction compliance capabilities. Raw material dependencies center on organic dairy from Australia and New Zealand, human milk oligosaccharide precursors from precision fermentation platforms, and specialty lipid structures from enzymatic processing operations. Single-source vulnerability in SAMR-registered production assets creates supply chain risk, as on-site audit requirements eliminate pure-import alternatives. Distribution runs through direct-to-subscription platforms displacing supermarket dominance in United States and United Kingdom markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in medical nutrition specialization and precision fermentation technology licensing, as divergent probiotic strain approvals between FDA, EMA, and NMPA jurisdictions create niche formulation requirements that subscale players can exploit.
For Market Incumbents: Insulate registered formulation portfolios by deepening captive manufacturing in Jiangsu and Zhejiang provinces to satisfy SAMR on-site audit mandates, while licensing precision fermentation technology to narrow functional gaps with human milk oligosaccharides before substitute platforms achieve scale. Threat concentration sits with contract manufacturers acquiring clinical evidence capabilities that erode dossier-based competitive moats.
For New Entrants and Emerging Players: Metabolic disorder formulations for infants with reimbursement-adjacent pricing power represent the most penetrable entry point, with urban India penetration in Mumbai, Delhi, and Bangalore offering secondary white-space expansion as breastfeeding duration shortens among working mothers. Go-to-market execution should prioritize pharmacy channel partnerships where quasi-medical classification triggers prescription-adjacent purchasing behavior.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory compliance infrastructure play because SAMR registration acquisition timelines extend beyond typical working capital planning horizons, concentrating value capture among entities with pharmaceutical-grade manufacturing assets and clinical evidence portfolios. Acquisition target archetype: specialized pediatric medical nutrition operators with metabolic disorder formulation expertise. Signal to watch is divergence between regional microbiome research agendas and resulting probiotic strain approval list harmonization efforts.
| Strategic Initiative | Industry Significance |
|---|---|
| SAMR Registration Acquisition | On-site manufacturing audits in Jiangsu province unlock shelf access in tier-one Chinese cities. |
| Precision Fermentation Licensing | Human milk oligosaccharide synthesis platforms narrow functional gaps with breast milk composition. |
| Medical Nutrition Specialization | Metabolic disorder formulations command reimbursement-adjacent pricing in pharmacy channels. |
| Direct-to-Subscription Launch | Algorithmic replenishment models capture lifetime customer value while reducing price transparency. |
| Backward Integration into Organic Dairy | Captive supply of certified feedstocks insulates margin compression from agricultural volatility. |
Research Approach
Operator-level perspectives from infant formula brand managers, SAMR regulatory affairs consultants, pharmacy procurement directors, and precision fermentation R&D leads anchored the qualitative base, triangulated against FDA enforcement actions, SAMR registration databases, EU organic certification records, and Nielsen retail audit data across supermarket and online channels. Bottom-up volume modeling from product-type and ingredient-type segments converged with top-down macroeconomic drivers to establish forecast boundaries.
Scenario-bracketing framed analytical approach across the projection horizon, with segmentation dimensions spanning product type, ingredient certification tier, distribution channel, and regional regulatory cluster. CAGRs derived from elasticity-adjusted adoption curves for bioactive-equivalent formulations and urban household income trajectories in tier-one Chinese cities, incorporating SAMR audit timeline compression effects on working capital requirements.
Practitioners should monitor GB standards evolution and precision fermentation capacity expansion for early signals of competitive repositioning, as forecasts reflect assumptions on regulatory harmonization progress and microbiome replication science advancement. Quarterly review of SAMR registration approval rates and organic dairy feedstock pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Growing Up Formula Market
Baby Food and Infant Formula
Global DHA Algae Oil for Infant Formula Market
Baby Food and Infant Formula
Goat Milk Formula Market
Baby Food and Infant Formula
Baby Infant Formula Market
Baby Food and Infant Formula
Infant Nutrition Market
Baby Food and Infant Formula
North America Baby Food and Infant Formula Market
Baby Food and Infant Formula
Canada Baby Food Market
Baby Food and Infant Formula
Organic Baby Food Market
Baby Food and Infant Formula
Asia-Pacific Prebiotics for Infant Formula Market
Baby Food and Infant Formula
Baby Food Testing Market
Baby Food and Infant Formula
Hypo Anti Allergic Baby Food Market
Baby Food and Infant Formula
Middle East and Africa Baby Food Market
Baby Food and Infant Formula
Indonesia Infant Nutrition Market
Baby Food and Infant Formula
Infant Formula Ingredients Market
Baby Food and Infant Formula
India Baby Food Market
Baby Food and Infant Formula
Baby Juice Market