
 Canned Baby Food Market | 2026-2036
Canned Baby Food Market Size, Share, and Industry Trends Forecast 2026-2036
Canned Baby Food Market Analysis
China is fragmenting as new domestic entrants challenge established multinationals in canned baby food manufacturing. Nestlé leverages its dairy supply chain to sustain cost advantages across Asian retail channels. HiPP anchors its position through organic certification depth that competitors struggle to replicate. Abbott Laboratories differentiates via clinical nutrition credibility extending from its pharmaceutical heritage.
Canned baby food comprises thermally processed, shelf-stable purees of vegetables, fruits, meats, or combinations, hermetically sealed in metal or glass containers after commercial sterilization at temperatures exceeding 100°C to eliminate pathogens and enzymes. The product category serves caregivers requiring convenient, long-duration infant nutrition without refrigeration dependency. Vegetable purees command margin pools due to ingredient cost stability and perceived nutritional density among health-conscious parents. Pouch packaging is displacing traditional tins among urban consumers prioritizing portability and reduced serving waste. Online retail channels are capturing volume from supermarkets as subscription models lock in recurring purchases.
The FDA governs infant formula and food labeling under the Federal Food, Drug, and Cosmetic Act, while the USDA administers organic certification standards that premium brands pursue for price positioning. China's SAMR enforces GB national food safety standards for infant complementary foods, creating compliance barriers for imported products. EFSA's scientific opinions on infant nutrition guide European member state regulations and shape reformulation investments. Stakeholders must monitor tightening heavy metal limits in agricultural inputs and the pace of biodegradable packaging mandates.
Market Dynamics
Dual-income household expansion across Asia and North America is compressing meal preparation windows for infant feeding, converting time-constrained parents toward shelf-stable, ready-to-serve nutrition formats that eliminate refrigeration logistics and preparation labor.
Growth Catalysts
- China's SAMR enforcement of GB 10769 standards:Stricter infant food safety protocols are filtering out informal domestic producers, consolidating volume toward certified manufacturers capable of traceable supply chains and laboratory verification.
- Pouch packaging technology:Flexible spouted pouches reduce serving waste and enable single-hand feeding, attracting urban parents in dense metropolitan transit corridors.
- Vegetable puree demand concentration:Health-conscious caregivers perceive higher micronutrient density in vegetable-forward formulations, sustaining premium price acceptance despite ingredient cost stability.
Market Restraints
- Heavy metal bioaccumulation in agricultural inputs:Arsenic and cadmium uptake in rice paddies and root vegetables forces costly pre-screening and geographic sourcing diversification.
- Glass and aluminum supply concentration:Container manufacturing clusters in specific industrial zones create vulnerability to energy price shocks and logistics bottlenecks.
- Fresh and frozen baby food substitution:Cold-chain infrastructure expansion in developed markets enables competitor formats promising superior sensory and nutritional preservation.
Strategic Opportunities
- India's FSSAI modernization:Harmonized infant food standards under Food Safety and Standards Authority of India regulations create compliance pathways for organized players to capture share from unorganized cottage producers.
- Subscription commerce integration:Direct-to-consumer recurring delivery models lock in purchase frequency and reduce customer acquisition costs through predictable replenishment cycles.
- Biodegradable packaging mandates:EU Green Deal packaging sustainability requirements accelerate R&D investment in compostable barrier films and bio-based spout materials.
Industry Challenges
- Clinical nutrition expertise scarcity:Formulation science requiring pediatric dietetic credentials and food safety microbiology creates recruitment bottlenecks in R&D functions.
- Retort processing capex intensity:Commercial sterilization equipment and aseptic filling lines demand substantial capital deployment with extended depreciation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canned Baby Food Market |
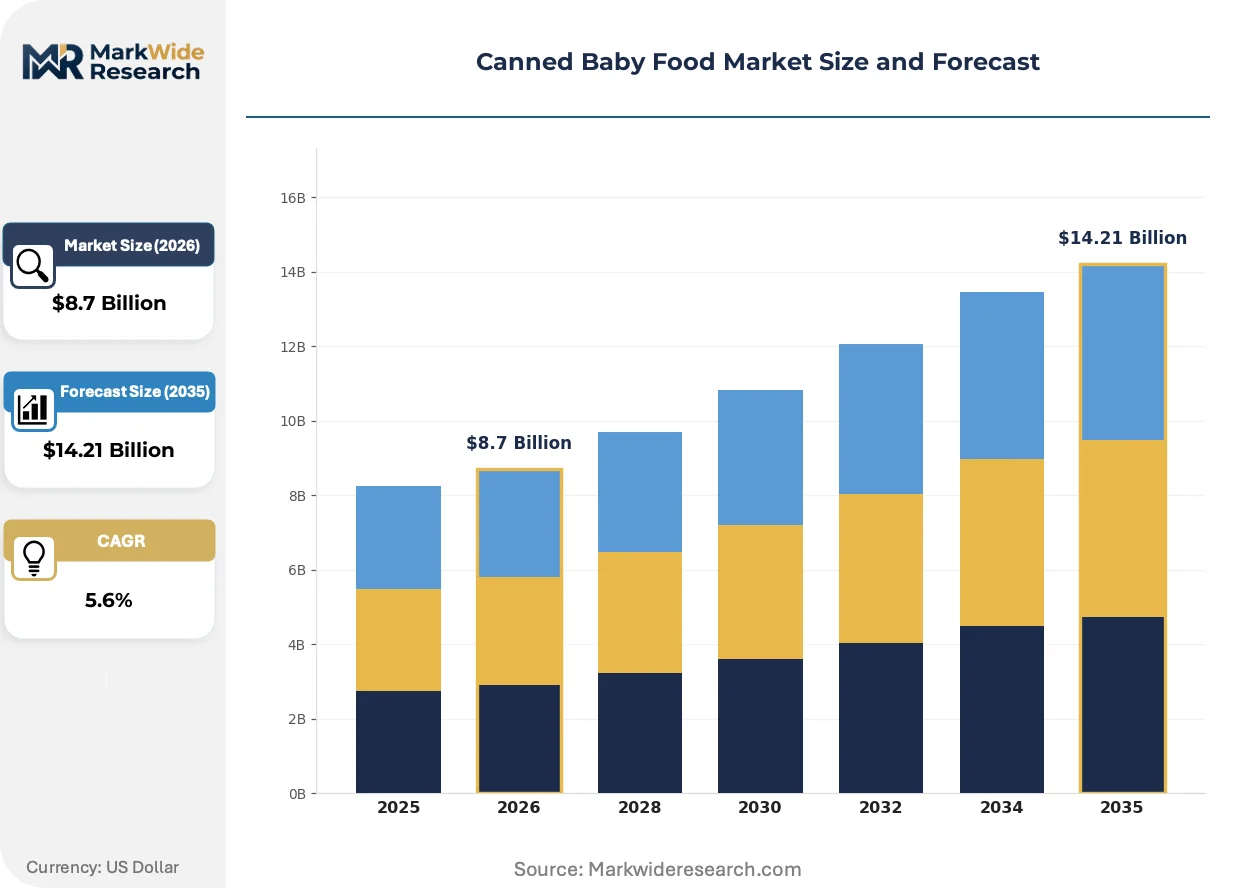
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Purees, Fruit Purees, Meat Purees, Mixed Flavor Packaging Type: Tins, Pouches, Jars, Glass Containers Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Food Stores Age Group: Infants, Toddlers, Newborns, Young Children |
| Companies Covered | The Hain Celestial Group, HiPP, Nestlé, Bubs Australia Limited, Reckitt Benckiser Group plc, Abbott Laboratories, The Kraft Heinz Company, Beech-Nut, Danone S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canned Baby Food Market Emerging Trajectories
Refrigeration-independent infant nutrition is experiencing format and channel transformation as convenience engineering intersects with safety verification demands and sustainability pressures across manufacturing and distribution.
High-pressure processing is collapsing the traditional trade-off between shelf stability and nutrient retention. This non-thermal pasteurization technology preserves heat-sensitive vitamins in fruit and vegetable matrices. Premium organic brands are piloting HPP-treated refrigerated lines with 45-60 day shelf life. The technology is collapsing retort sterilization's monopoly on pathogen elimination for premium-positioned products.
EFSA's scientific opinions on aluminum migration from packaging materials are tightening acceptable daily intake thresholds for infant consumers. European manufacturers face reformulation or packaging substrate switching to comply with evolving safety assessments. Glass container demand is accelerating in Germany, France, and Benelux markets where parental risk perception elevates material purity over convenience.
Subscription-based replenishment is restructuring purchase behavior among millennial and Generation Z parents. Automated recurring orders through proprietary apps and third-party platforms displace supermarket impulse purchasing. This shift concentrates most visibly in coastal Chinese cities and Pacific Northwest US metropolitan areas where digital commerce penetration and dual-income household density coincide.
Canned Baby Food Market Segmentation
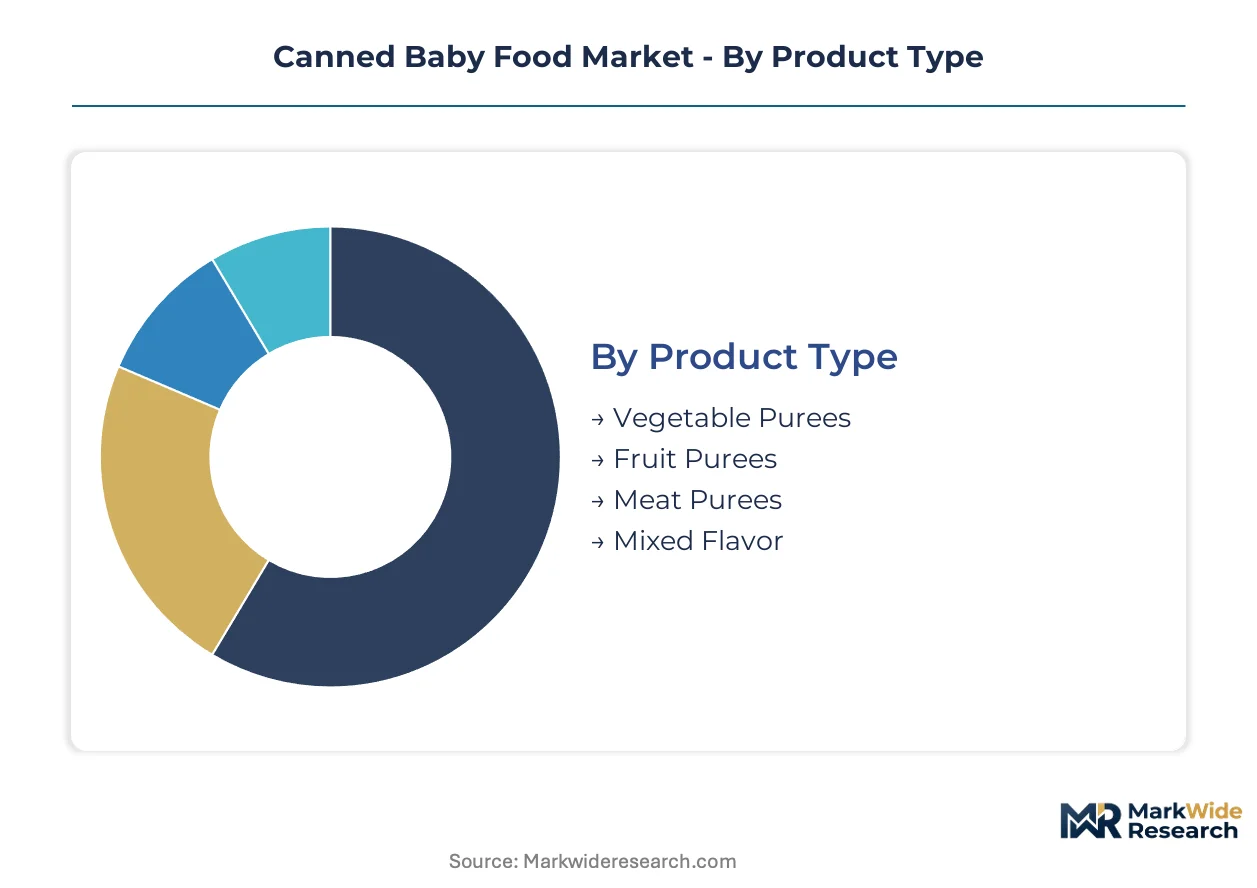
Segmentation in canned baby food reveals how convenience engineering, safety verification, and feeding-stage requirements reshape purchasing patterns across caregiver demographics. Each dimension exposes distinct margin pools and inventory velocity profiles that manufacturers must align against.
Product Type:
Vegetable purees turn inventory fastest due to health-conscious parent preference and year-round ingredient availability, while meat purees move slowest given sourcing complexity and shorter production cycles.
- Vegetable Purees:Thermally processed blends of carrots, peas, sweet potatoes, and squash deliver perceived micronutrient density. Demand concentrates in coastal Chinese cities and Pacific Northwest US metropolitan areas where organic certification commands price premiums. Dual-income households with compressed meal preparation windows drive repeat purchase frequency.
- Fruit Purees:Shelf-stable apple, pear, and banana formulations balance palatability acceptance with thermal processing requirements. Urban parents in dense transit corridors favor single-serve portability. EFSA's evolving aluminum migration thresholds are pushing European manufacturers toward glass substrate alternatives.
- Meat Purees:Chicken, beef, and turkey purees provide protein-forward infant nutrition with extended retort processing requirements.
- Mixed Flavor:Combination formulations merge vegetable, fruit, and protein matrices for complete-meal positioning.
Vegetable purees anchor the volume base while mixed flavor formulations gain share at the steepest rate.
Packaging Type:
Cost tiers stratify sharply: pouches command manufacturing premiums against commodity tin formats, while glass containers occupy the purity-positioned apex with highest per-unit production expense.
- Tins:Traditional metal cans dominate emerging market penetration due to established supply chains and lowest unit economics. India's FSSAI modernization is consolidating volume toward organized producers capable of traceable tin sourcing.
- Pouches:Flexible spouted films enable single-hand feeding and reduced serving waste. Parents in Shanghai, Seoul, and San Francisco metro areas prioritize this format for transit-compatible convenience. Biodegradable barrier films under EU Green Deal mandates are accelerating R&D investment.
- Jars:Wide-mouth glass or plastic containers serve portion-control preferences in European retail channels.
- Glass Containers:Hermetically sealed glass jars address parental risk perception around material purity. Germany, France, and Benelux markets show strongest uptake following EFSA safety opinion tightening.
Tins retain the broadest geographic footprint while pouches capture the fastest-expanding urban customer segments.
Distribution Channel:
Volume concentrates through supermarket chains, yet margin profiles favor direct-to-consumer models with locked replenishment cycles and reduced slotting fee exposure.
- Supermarkets:Mass retail chains maintain shelf-space dominance for impulse and planned purchasing. Walmart, Carrefour, and Aeon networks across the US, France, and Japan enforce stringent supplier qualification protocols.
- Online Retail:Subscription commerce and third-party platforms displace physical impulse buying. Automated recurring orders concentrate in China's coastal cities where digital penetration and dual-income density coincide. Customer acquisition costs compress through predictable replenishment.
- Convenience Stores:Small-format retail captures emergency replenishment and travel-oriented purchasing.
- Health Food Stores:Specialty channels curate organic and allergen-free assortments for premium-positioned segments.
Supermarkets anchor transaction volume while online retail climbs the fastest among millennial and Generation Z parent cohorts.
Age Group:
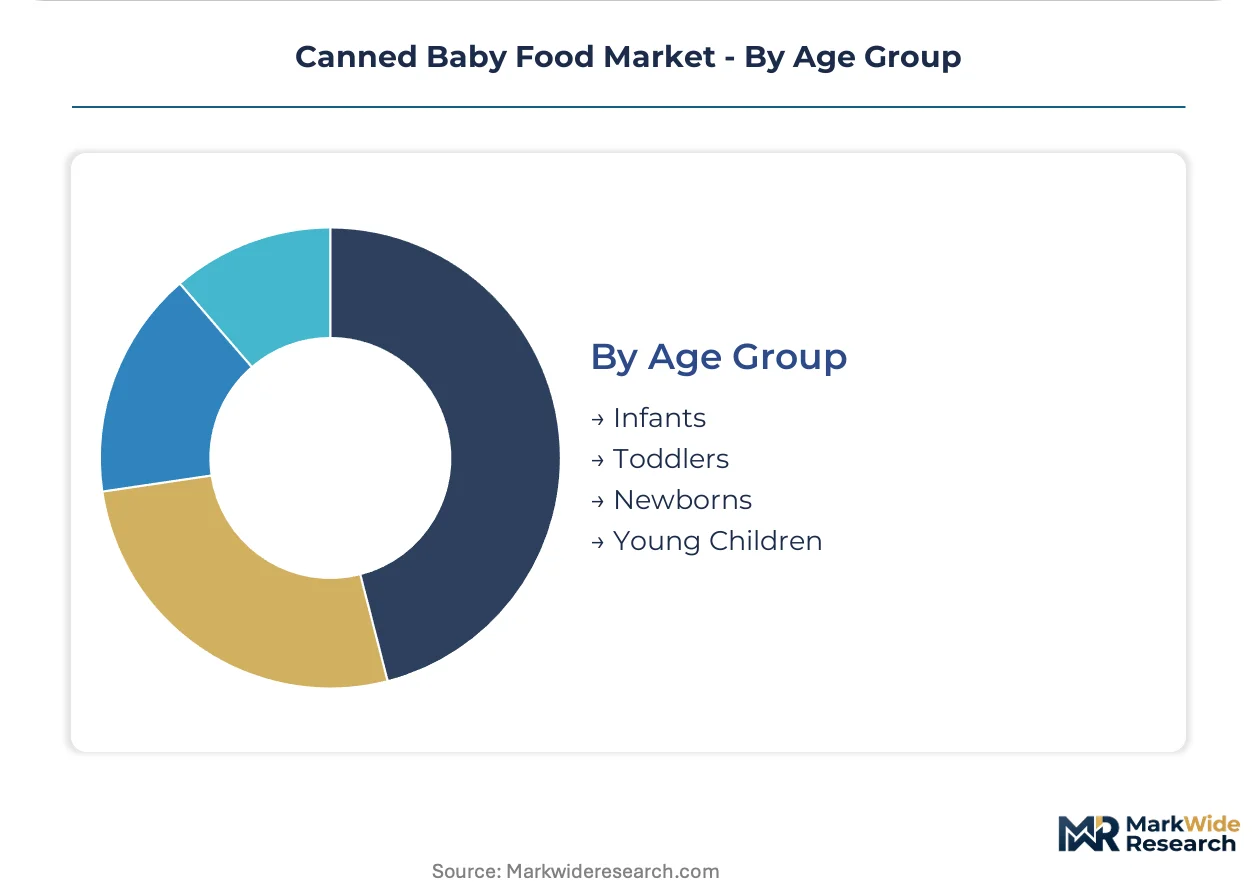
Feeding-stage progression dictates formulation complexity, texture graduation, and portion scaling across the infant-to-toddler transition window.
- Infants:Smooth, single-ingredient purees serve 4-6 month introduction phases with lowest allergen profiles. China's SAMR GB 10769 enforcement filters out informal producers lacking laboratory verification.
- Toddlers:Chunkier textures and diversified flavor profiles accommodate developing chewing capabilities. Parents in Tokyo, London, and New York metro areas seek vegetable-forward options with reduced added sugars.
- Newborns:Breast milk or formula alternatives dominate this pre-solid stage with minimal canned food penetration.
- Young Children:Complete-meal formats with protein and grain integration serve 2-4 year nutritional requirements.
Infant-stage products anchor the revenue base while toddler formulations expand most quickly as feeding windows lengthen and texture variety demands intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR's GB 10769 enforcement in China is filtering informal producers from certified supply chains, consolidating infant food manufacturing toward traceable laboratory verification systems. Dual-income household density in Shanghai, Beijing, and Shenzhen is compressing meal preparation windows and accelerating pouch-format adoption. India's FSSAI modernization is harmonizing standards to displace unorganized cottage production.
United States
Dual-income household expansion across Pacific Northwest metropolitan corridors is converting time-constrained parents toward subscription-based replenishment models. FDA infant formula and food labeling requirements under the Federal Food, Drug, and Cosmetic Act enforce stringent compositional standards. Walmart's supplier qualification protocols in Bentonville, Arkansas anchor mass retail distribution infrastructure.
China
Middle-class parental shift toward branded shelf-stable nutrition is concentrating demand in coastal tier-one cities. SAMR enforcement of GB national food safety standards for infant complementary foods creates compliance barriers for imported products. Manufacturing clusters in Yangtze River Delta cities are scaling traceable supply chain verification systems to meet laboratory testing mandates.
Germany
Parental risk perception around material purity is elevating glass container demand over convenience-oriented formats. EFSA scientific opinions on aluminum migration from packaging materials are tightening acceptable daily intake thresholds. Manufacturing concentration in Bavaria is accelerating substrate switching toward hermetically sealed glass jars.
India
FSSAI modernization under harmonized infant food standards is creating compliance pathways for organized manufacturers. Food Safety and Standards Authority of India regulations are consolidating volume away from unorganized cottage producers. Industrial corridors in Maharashtra and Gujarat are scaling tin-format production for emerging market penetration.
Japan
Urban parents in Tokyo and Osaka metro areas are seeking vegetable-forward toddler formulations with reduced added sugars. METI oversight of food manufacturing standards ensures rigorous safety verification protocols. Kanto region distribution networks are integrating pouch-format lines for transit-compatible convenience.
Canned Baby Food Market Vendor Landscape
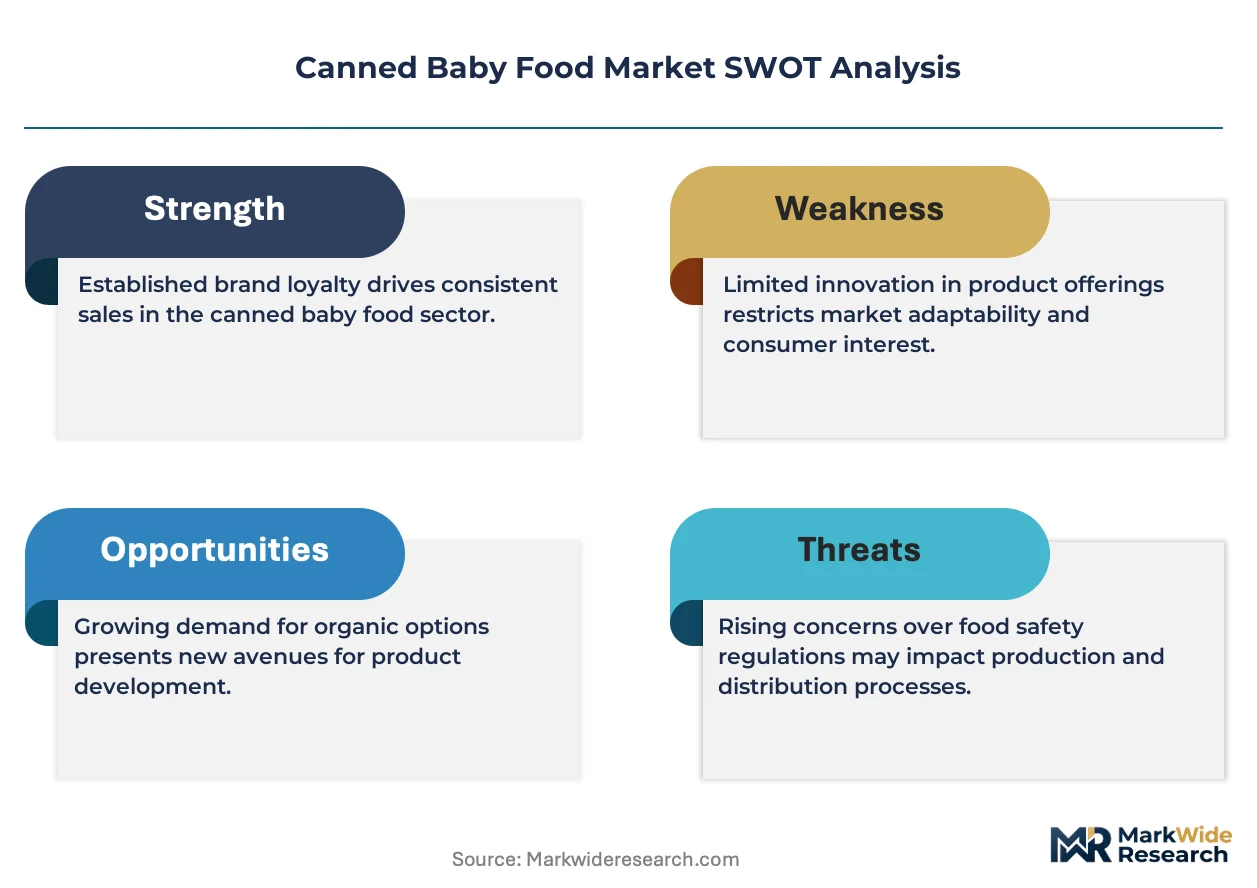
Capability concentration sits with organic certification specialists; scale advantage sits with diversified nutrition conglomerates. The manufacturer base organizes around three strategic archetypes: dairy supply chain integrators leveraging captive ingredient sourcing, clinical nutrition credentialed pharmaceutical heritage players, and organic certification depth specialists. Competitive moves center on pouch packaging technology licensing and subscription commerce platform integration.
Within the organic certification tier, HiPP exemplifies European purity-positioning archetypes through hereditary organic farming credentials. Nestlé S.A. occupies the scale-driven multinational position, leveraging dairy supply chain integration across Asian retail channels. Abbott Laboratories anchors the clinical nutrition segment, extending pharmaceutical heritage into pediatric dietetic formulation credibility.
| Leading Market Players |
|---|
| The Hain Celestial Group |
| HiPP |
| Nestlé |
| Bubs Australia Limited |
| Reckitt Benckiser Group plc |
| Abbott Laboratories |
| The Kraft Heinz Company |
| Beech-Nut |
| Danone S.A. |
| Others |
Supply Flow & Price Mechanics
China's Yangtze River Delta manufacturing clusters concentrate retort sterilization equipment and aseptic filling capacity, anchoring margin pools with downstream brand owners in Shanghai and Shenzhen who command premium shelf positioning against tin-format commodity producers.
Pricing Analysis
Coastal Chinese cities exhibit 30-40% price premiums over inland provinces for identical organic-certified SKUs. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth and packaging substrate, with glass-jar organic lines capturing the top tier. Pricing pressure stems from fresh and frozen baby food substitution as cold-chain infrastructure expands in Pacific Northwest US metropolitan corridors. Mass-market tin formats face the highest price sensitivity among rural Indian households, while subscription-locked urban parents in Seoul and San Francisco show lowest elasticity.
Supply Chain Analysis
Export-control regimes on advanced barrier-film polymers from Germany and Japan constrain pouch-format manufacturing scale-up in emerging markets. Supply concentrates in China for aluminum sheet and glass container production, with Italy and Spain contributing specialized organic ingredient sourcing. Raw material dependencies include rice-based starches, vegetable purees, and hermetic sealing compounds. Single-source vulnerability in aluminum smelting clusters creates energy-price shock exposure. Distribution runs through supermarket chains for impulse volume, with direct-to-consumer platforms capturing recurring replenishment cycles in digitally penetrated metros.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-pressure processing disruption collapses the shelf-stability-versus-nutrition trade-off, with EFSA's evolving aluminum migration thresholds accelerating substrate switching investments across European manufacturing.
For Market Incumbents: Build regulatory compliance moats through SAMR GB 10769 laboratory verification systems and EFSA-aligned packaging substrate portfolios. Nestlé's dairy supply chain integration across Asian retail channels demonstrates captive ingredient sourcing leverage against emerging domestic Chinese entrants. Accelerate biodegradable barrier film R&D to preempt EU Green Deal mandates. For New Entrants and Emerging Players: Establish a beachhead in India's FSSAI-modernizing organized segment before tin-format consolidation completes. Target Maharashtra and Gujarat industrial corridors where unorganized cottage producers lack traceable supply chains. Deploy subscription-commerce platforms with automated replenishment to bypass supermarket slotting fee barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed organic certification specialists lacking clinical nutrition credibility. Five-to-ten-year viability hinges on HPP technology licensing portfolios and pouch-format manufacturing scale. Watch EFSA aluminum migration threshold tightening as the signal forcing glass-container capex acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| HPP Technology Licensing | Non-thermal pasteurization preserves heat-sensitive vitamins in premium vegetable purees. |
| Biodegradable Packaging Transition | EU Green Deal mandates accelerate compostable barrier film and bio-based spout R&D. |
| Subscription Platform Integration | Automated replenishment locks purchase frequency in Shanghai and San Francisco metros. |
| Organic Certification Depth Investment | Hereditary farming credentials differentiate HiPP against commodity tin producers. |
| Clinical Nutrition R&D Expansion | Pediatric dietetic formulation credibility extends Abbott's pharmaceutical heritage into infant feeding. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across the canned baby food value chain, including category buyers at Walmart and Carrefour, brand managers at organic certification specialists, retort processing equipment engineers, and pediatric dietetic formulation scientists. Secondary validation drew from FDA Federal Food Drug and Cosmetic Act filings, SAMR GB standard enforcement records, EFSA scientific opinions on aluminum migration, Nielsen retail audit data, and customs records of vegetable puree ingredient flows. Bottom-up SKU-level volume aggregation was triangulated against top-down macroeconomic demand modeling.
Calibration anchored historical volume trajectories against dual-income household expansion rates and digital commerce penetration indices across the analysis window. Segmentation dimensions modeled include product type, packaging substrate, distribution channel, and feeding-stage age group, with regional regulatory clusters treated as distinct demand environments. CAGRs were derived from fitted growth curves incorporating pouch-format adoption rates, subscription-commerce share capture, and organic certification premium persistence. Forecast inputs included SAMR enforcement intensity projections and EU Green Deal packaging mandate timelines.
Stress conditions across aluminum price volatility, heavy metal bioaccumulation in rice paddies, and fresh-food substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement pacing and technology adoption S-curves. Material shifts in EFSA aluminum migration thresholds or India's FSSAI modernization acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Wet Cat Food Market
Baby Food and Infant Formula
Japan Baby Food and Infant Formula Market
Baby Food and Infant Formula
Global DHA Algae Oil for Infant Formula Market
Baby Food and Infant Formula
Asia Pacific Organic Baby Food Market
Baby Food and Infant Formula
Canned Pet Food Market
Baby Food and Infant Formula
Europe Baby Food Market
Baby Food and Infant Formula
Omega 3 Ingredients for Infant Food Market
Baby Food and Infant Formula
South America Baby Food Market
Baby Food and Infant Formula
Hydrolyzed Formula Milk Powder Market
Baby Food and Infant Formula
United States Baby Food and Infant Formula Market
Baby Food and Infant Formula
Hypo Anti Allergic Baby Food Market
Baby Food and Infant Formula
India Baby Food Market
Baby Food and Infant Formula
North America Baby Food and Infant Formula Market
Baby Food and Infant Formula
Baby Formula Ingredients Market
Baby Food and Infant Formula
Baby Formula Market
Baby Food and Infant Formula
A2 Infant Formula Market