
 North America Baby Food and Infant Formula Market | 2026-2036
North America Baby Food and Infant Formula Market Size, Share, and Industry Trends Forecast 2026-2036
North America Baby Food and Infant Formula Market Intelligence
The North America baby food and infant formula market is repositioning around a stark split between premium organic lines and conventional commodity offerings. Nestlé S.A. leverages its Gerber subsidiary to dominate shelf-stable purees and cereal segments across mass retail channels. Danone S.A. anchors its competitive stance through specialized medical nutrition and hypoallergenic formulations. Abbott Laboratories sustains hospital and pharmacy distribution strength with its science-backed powdered and ready-to-feed portfolios.
Baby food and infant formula encompasses nutritionally complete products manufactured for consumption by children under thirty-six months, typically formulated with specified protein, fat, carbohydrate, vitamin, and mineral profiles subject to compositional standards. These products serve the essential commercial purpose of substituting or complementing breast milk during early childhood development. Organic baby food commands premium shelf positioning and margin expansion as parental willingness-to-pay rises for certified clean-label options. Pouch packaging is displacing glass jars as the fastest-growing format, driven by convenience-seeking behaviors and on-the-go feeding occasions. Supermarkets retain volume leadership, though online retailers capture disproportionate growth in subscription-based replenishment models.
The FDA regulates infant formula under the Federal Food, Drug, and Cosmetic Act with stringent pre-market notification and nutrient requirements, while USDA organic certification governs label claims for natural-positioned products. Health Canada and PMRA coordinate cross-border ingredient approvals that affect North American supply fluidity. Stakeholders must monitor evolving state-level clean-label legislation and potential harmonization pressures between FDA and CFIA standards as organic share expands.
Market Dynamics
The FDA's updated infant formula enforcement discretion policy is compressing import pathways while simultaneously accelerating domestic production investments across the United States and Canada. This regulatory recalibration is forcing manufacturers to reconfigure supply chains around stricter pre-market notification requirements and nutrient compliance verification.
Growth Catalysts
- Organic certification standards:USDA organic label requirements create pricing power and margin expansion for certified clean-label producers. Millennial parents in California, Texas, and New York demonstrate sustained willingness-to-pay premiums.
- Pouch packaging technology:Flexible film and spout innovations enable on-the-go feeding convenience. Urban working parents adopt single-serve formats for daycare and travel occasions.
- Hypoallergenic formulation science:Extensively hydrolyzed protein research addresses cow's milk protein allergy prevalence. Pediatric allergists recommend specialized formulas as first-line interventions.
Market Restraints
- Dairy commodity volatility:Whey and lactose input costs fluctuate with global dairy futures markets. Formula manufacturers absorb margin compression or pass through retail price adjustments.
- Domestic production concentration:Three facilities supply the majority of U.S. powdered infant formula volume. Single-site contamination events trigger nationwide shortage cascades.
- Breastfeeding duration extension:WHO guidelines and hospital initiatives extend exclusive breastfeeding recommendations. Commercial formula faces demand headwinds in the zero-to-six-month segment.
Strategic Opportunities
- Subscription replenishment channels:Direct-to-consumer platforms capture recurring revenue with personalized nutrition algorithms. First-time parents in metropolitan markets show high trial-to-subscription conversion.
- Toddler nutritional extension:Twelve-to-thirty-six-month formulations bridge the gap between infant formula and cow's milk. Growth and immunity positioning targets developmental milestone marketing.
- Cross-border Canadian retail:Health Canada PMRA approvals enable U.S. manufacturer shelf presence in Toronto and Vancouver. Regulatory harmonization discussions reduce dual-registration burdens.
Industry Challenges
- Specialized manufacturing talent scarcity:Food-grade dairy processing engineers with infant nutrition experience command premium compensation. Retention pressures intensify as facility automation investments require hybrid skill sets.
- Legacy ERP integration friction:Lot-level traceability mandates clash with decades-old manufacturing execution systems. Real-time ingredient genealogy tracking requires substantial middleware investment.
- Clinical trial recruitment bottlenecks:Pediatric nutrition studies face IRB approval delays and parental consent hesitancy. Novel ingredient substantiation timelines extend beyond product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Baby Food and Infant Formula Market |
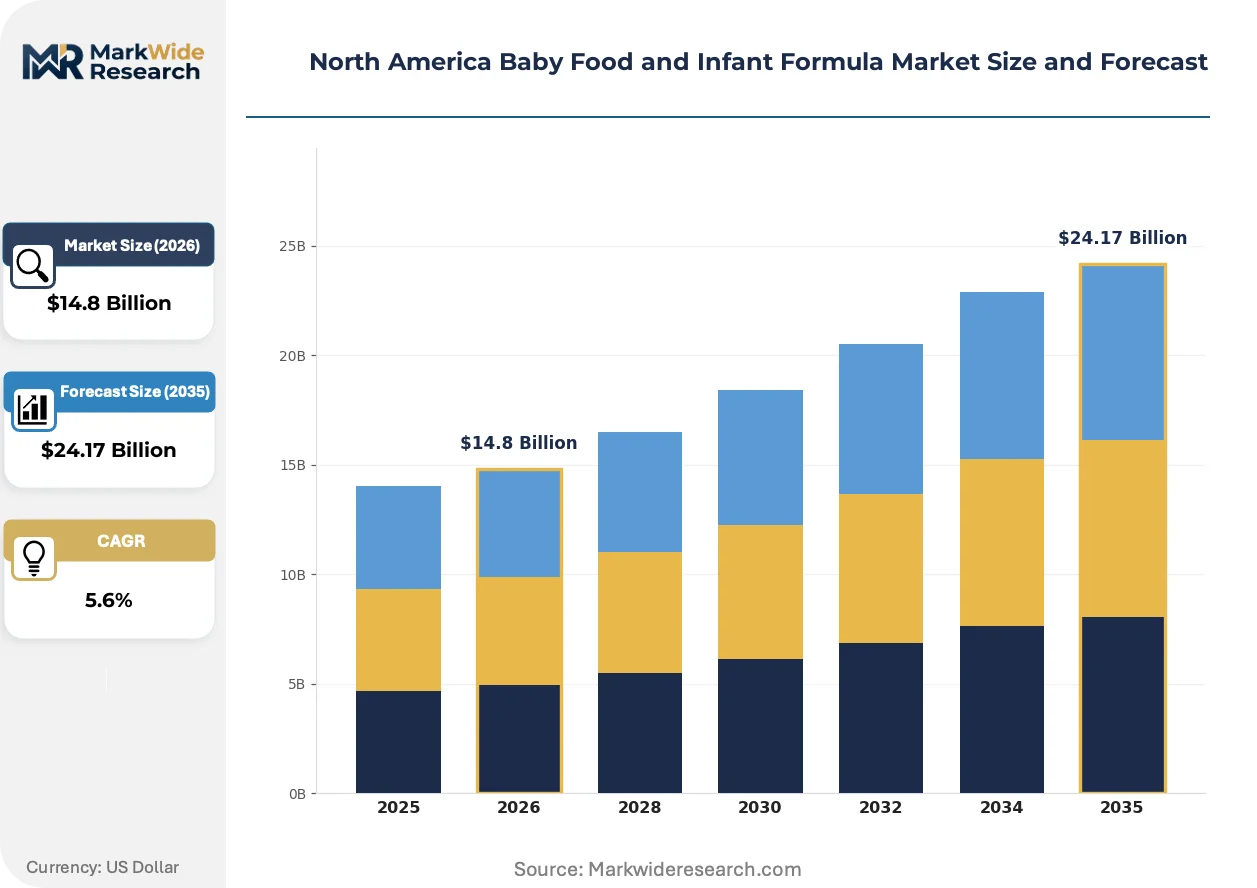
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.17 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Baby Food, Cereal, Puree, Snacks Distribution Channel: Supermarkets, Online Retailers, Pharmacies, Specialty Stores Packaging Type: Glass Jars, Pouches, Tetra Packs, Cans Formulation: Ready-to-Feed, Powdered, Concentrated, Additive-Free |
| Companies Covered | Reckitt Benckiser Group, The Kraft Heinz Company, Nestlé S.A., Beech-Nut Nutrition Corporation, The Hain Celestial Group Inc, Danone S.A., Gerber Products Company, Hipp GmbH & Co. Vertrieb KG, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Baby Food and Infant Formula Market Strategic Shifts & Innovations
Clean-label ingredient transparency is converging with digital traceability platforms to reshape how parents evaluate and purchase infant nutrition. Three interconnected developments are compressing traditional formulation and distribution models.
Precision fermentation-derived proteins are converging with traditional dairy processing infrastructure to create hybrid infant formula bases. Biotech startups in California and Illinois partner with established dairy cooperatives to scale lactoferrin and alpha-lactalbumin production. This convergence is blurring the boundary between conventional and alternative protein positioning in premium formula segments.
Health Canada and the FDA are coordinating cross-border ingredient pre-approval pathways through mutual recognition pilot programs. Dual-registration requirements previously forced twelve-to-eighteen month market entry delays for novel bioactive compounds. Specialized medical nutrition manufacturers with existing hospital formulary relationships capture first-mover positioning in this streamlined environment.
Urban millennial parents are consolidating purchase decisions around subscription-based replenishment platforms with pediatrician-integrated nutrition guidance. Mass retail shelf space loses traffic as telehealth-enabled formula recommendations drive direct-to-consumer trial. This behavioral pivot concentrates most visibly in California, New York, and Texas metropolitan corridors where digital-native parenting communities cluster.
North America Baby Food and Infant Formula Market Segmentation
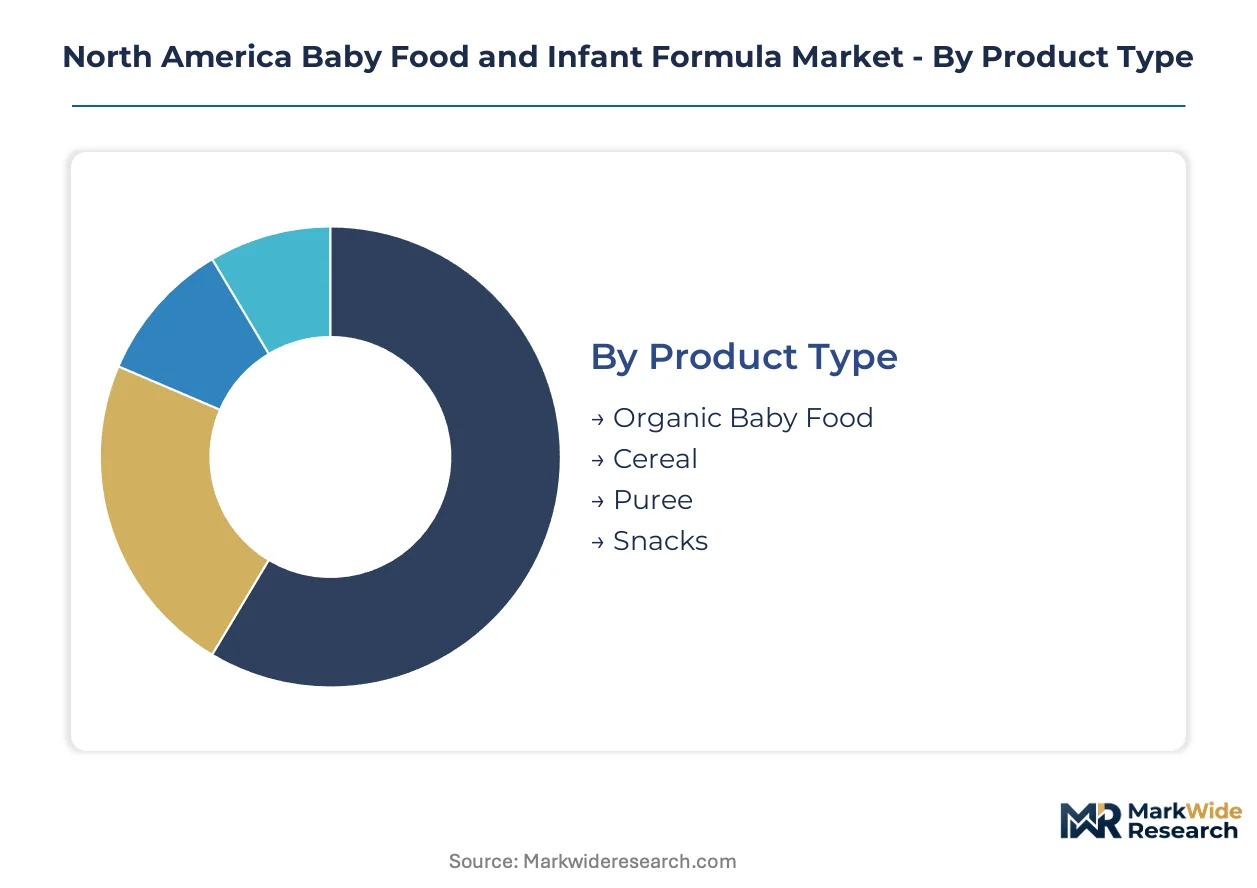
Segmentation in the North America baby food and infant formula market reveals how parental priorities fragment across convenience, safety perception, and nutritional philosophy. Manufacturers must configure portfolio depth and channel strategy around distinct buyer archetypes rather than demographic aggregates.
Product Type:
Parents differentiate primarily by certification status and ingredient transparency, with willingness-to-pay scaling steeply toward verified clean-label positioning.
- Organic Baby Food:USDA-certified products command shelf premiums through prohibited synthetic pesticide and fertilizer standards. California and New York urban parents sustain double-digit price acceptance for certified supply chains.
- Cereal:Iron-fortified grain formulations serve as traditional first solids for infants four-to-six months. Texas and Midwest volume concentrates in mass retail channels where pediatrician recommendation drives trial.
- Puree:Single-ingredient and combination fruit-vegetable blends target texture introduction stages.
- Snacks:Puffed grain and teething biscuit formats extend brand relationships into toddler years.
Volume sits with Cereal; growth tilts toward Organic Baby Food.
Distribution Channel:
Channel selection reflects purchase urgency, subscription appetite, and trust in professional guidance.
- Supermarkets:Mass retail chains retain dominant shelf space and promotional velocity across standard formula and jarred food segments. Weekly shopping trip integration sustains replenishment frequency for price-sensitive households.
- Online Retailers:Direct-to-consumer platforms capture subscription-based recurring revenue with personalized nutrition algorithms. First-time parents in metropolitan markets show high trial-to-subscription conversion.
- Pharmacies:Hospital discharge bundles and pediatrician recommendations drive specialized formula trial.
- Specialty Stores:Premium organic boutiques serve clean-label enthusiasts seeking curated assortment.
Supermarkets anchor current volume; online channels expand most quickly.
Packaging Type:
Format innovation centers on feeding occasion flexibility and parental mobility requirements.
- Pouches:Flexible film and spout designs enable one-handed feeding without refrigeration. Urban working parents adopt single-serve formats for daycare and travel occasions across California, Texas, and New York corridors.
- Glass Jars:Traditional rigid containers retain trust among preservative-averse buyers seeking visible product integrity. Midwest and older demographic segments sustain modest volume despite format decline.
- Tetra Packs:Aseptic carton technology extends ambient shelf stability for liquid formulas.
- Cans:Metal packaging dominates powdered formula bulk formats with moisture protection.
Glass Jars retain legacy volume; Pouches gain share fastest.
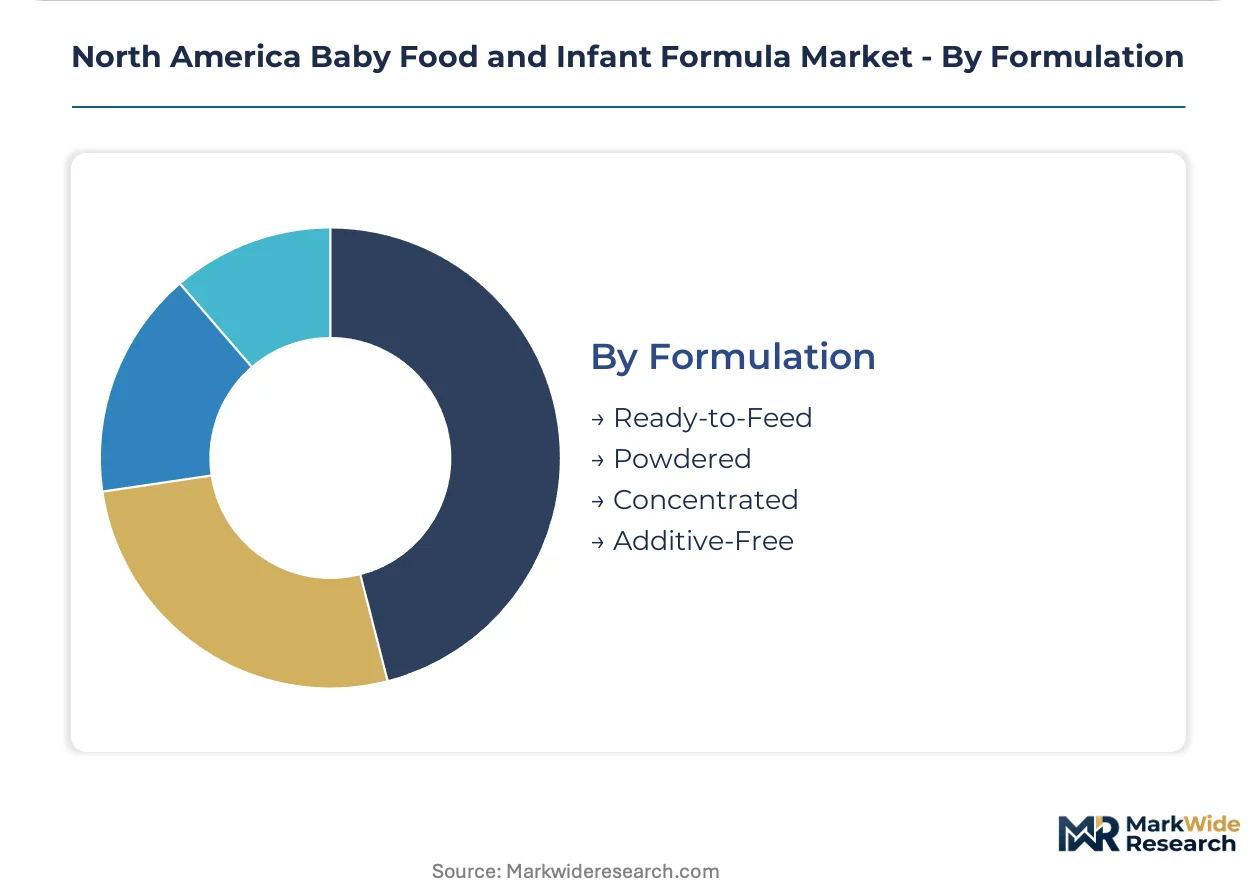
Formulation:
Preparation time and storage constraints segment buyers between convenience premium and cost optimization.
- Ready-to-Feed:Sterile liquid products eliminate mixing errors and bacterial contamination risk. Hospital nurseries and overnight feeding occasions sustain premium pricing.
- Powdered:Concentrated dry blends offer lowest per-ounce cost with extended pantry stability. Volume concentrates in households with multiple children and budget-conscious segments.
- Concentrated:Liquid concentrates require dilution but reduce storage bulk versus ready-to-feed.
- Additive-Free:Exclusion of artificial colors, flavors, and preservatives targets clean-label positioning.
Powdered formulations dominate volume; Additive-Free climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's urban corridors anchor North American demand for premium organic infant nutrition, with Los Angeles and San Francisco metros driving clean-label trial rates above national averages.
United States
Millennial parents in Texas and New York sustain double-digit willingness-to-pay premiums for USDA-certified organic lines. FDA enforcement discretion policies compress import pathways while accelerating domestic production investments across Midwest dairy processing zones. Chicago and Minneapolis-St. Paul industrial clusters concentrate powdered formula manufacturing capacity subject to stringent pre-market notification requirements.
Canada
Health Canada coordinates cross-border ingredient approvals with FDA through mutual recognition pilot programs, reducing dual-registration burdens for specialized medical nutrition. Toronto and Vancouver retail corridors capture disproportionate subscription-based replenishment growth among urban first-time parents. PMRA regulatory harmonization discussions accelerate novel bioactive compound market entry timelines.
Mexico
Monterrey and Mexico City distribution hubs channel mass-market formula volumes through supermarket chains serving price-sensitive households with multiple children. COFEPRIS regulatory alignment pressures intensify as manufacturers seek streamlined North American supply chain configuration. Querétaro industrial corridor attracts dairy processing investments targeting export qualification standards.
North America Baby Food and Infant Formula Market Key Industry Players
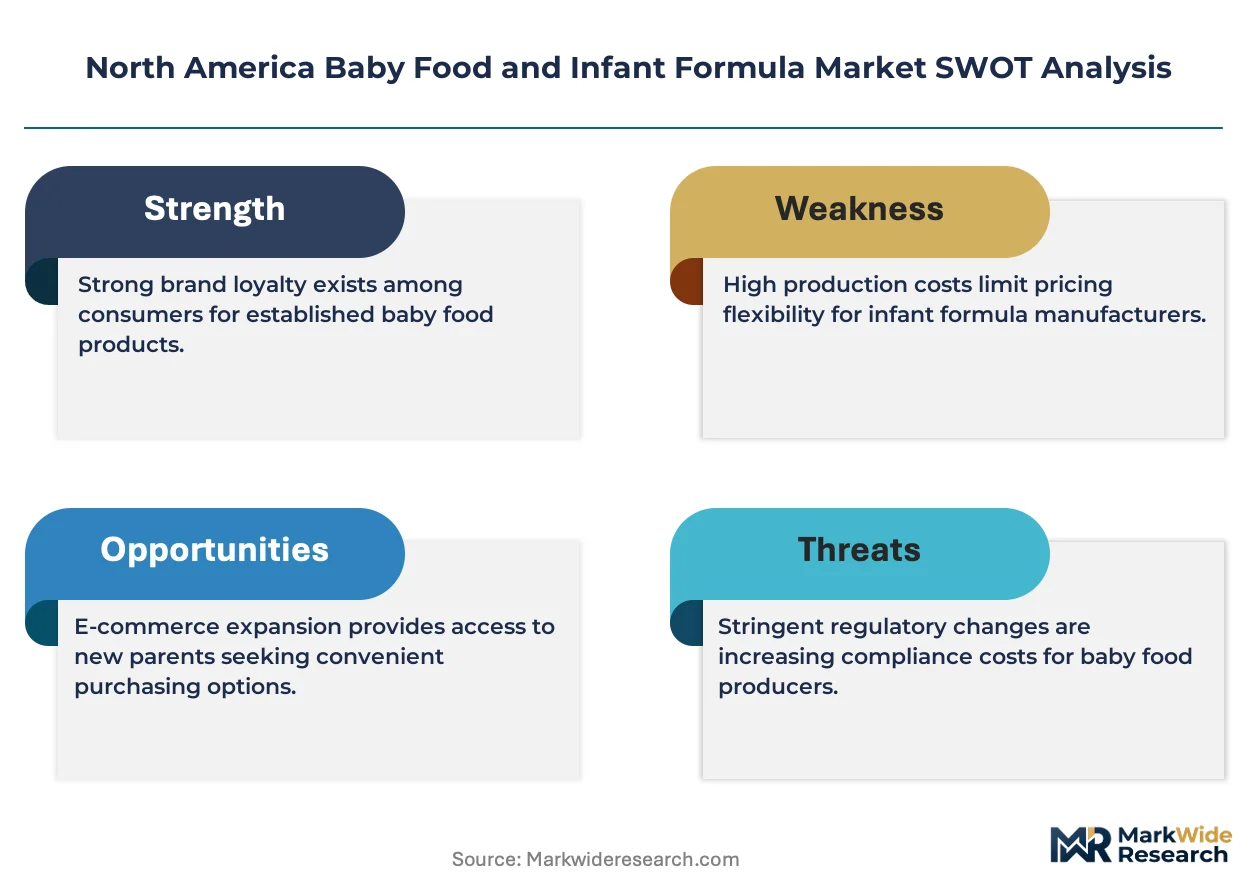
Premium-margin players sit above commodity-margin players across certification and formulation complexity, with organic-certified and hypoallergenic portfolios commanding shelf positioning advantages. Three multinational nutrition conglomerates retain dominant volume share through hospital formulary relationships and mass retail distribution density. Strategic archetypes include science-backed medical nutrition specialists, mass-market brand licensors, and organic-certified premium challengers. Competitive moves concentrate on subscription platform acquisition and precision fermentation partnership structures.
Among diversified nutrition conglomerates, Nestlé S.A. and Danone S.A. occupy positions spanning conventional and premium-tier portfolios, while Abbott Laboratories anchors the medical nutrition specialist archetype through hospital and pharmacy channel strength. Reckitt Benckiser Group and The Kraft Heinz Company exemplify brand-licensing and mass-market distribution approaches, with The Hain Celestial Group Inc representing organic-certified challenger positioning. These entities collectively illustrate the market's tiered structure across formulation science, certification status, and channel access depth.
| Leading Market Players |
|---|
| Reckitt Benckiser Group |
| The Kraft Heinz Company |
| Nestlé S.A. |
| Beech-Nut Nutrition Corporation |
| The Hain Celestial Group Inc |
| Danone S.A. |
| Gerber Products Company |
| Hipp GmbH & Co. Vertrieb KG |
| Abbott Laboratories |
| Others |
Cost & Logistics Intelligence
Food-grade dairy processing engineers with infant nutrition expertise concentrate in Midwest industrial corridors, and their scarcity premium feeds directly into spreads between commodity and certified-organic price tiers. Labor-cost differentials between conventional and specialized manufacturing widen the gap parents encounter at retail.
Pricing Analysis
Outcome-based pricing anchors premium tiers to pediatric health metrics and developmental milestone claims rather than input costs alone. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and formulation complexity. Cost compression in economy powdered formulas is intensifying because dairy commodity volatility passes through to shelf prices. First-time parents in metropolitan markets show lowest price sensitivity; households with multiple children in suburban and rural segments exhibit highest elasticity.
Supply Chain Analysis
Regional distribution centers in Chicago, Minneapolis-St. Paul, and Toronto anchor hub-and-spoke patterns serving supermarket and pharmacy channels. Manufacturing concentrates in the United States, Canada, and Mexico under FDA, Health Canada, and COFEPRIS oversight respectively. Whey protein concentrates, lactose, and vegetable oils constitute critical input dependencies. Single-source vulnerability concentrates in three Midwest powdered formula facilities. Distribution runs through mass retail chains with growing direct-to-consumer bypass.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America baby food and infant formula market functions as a cost-of-compliance story where FDA pre-market notification requirements erect substantial barrier-to-entry moats favoring incumbents with established regulatory affairs infrastructure.
For Market Incumbents: Anchor hospital formulary relationships through specialized medical nutrition portfolios while accelerating precision fermentation partnerships to secure alternative protein supply. Consolidate subscription platform capabilities to defend against direct-to-consumer disintermediation. Vertical integration into organic dairy sourcing insulates margin from commodity volatility. For New Entrants and Emerging Players: Subscription-fatigued urban millennial parents represent an underserved buyer archetype seeking telehealth-integrated guidance without platform lock-in. White-space sits in toddler nutritional extension formats bridging formula and cow's milk. Target Health Canada PMRA streamlined approval pathways for novel bioactive compounds. Go-to-market through pediatrician recommendation networks bypasses mass retail slotting barriers. For Investors and Strategic Acquirers: Re-rating potential sits with organic-certified challengers given USDA label scarcity and sustained willingness-to-pay premiums in California, Texas, and New York corridors. Long-term viability favors manufacturers with dual FDA-Health Canada registration capabilities and hospital channel entrenchedness. Watch FDA enforcement discretion policy evolution as inflection signal for import pathway compression or expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Biotech startups in California partner with dairy cooperatives to scale lactoferrin production. |
| Subscription Platform Acquisition | Direct-to-consumer replenishment captures recurring revenue from metropolitan first-time parents. |
| Organic Certification Investment | USDA label requirements create pricing power and margin expansion in premium segments. |
| Cross-Border Registration Streamlining | Health Canada FDA mutual recognition reduces dual-registration burdens for novel ingredients. |
| Toddler Nutritional Extension Launch | Twelve-to-thirty-six-month formulations bridge gap between infant formula and cow's milk. |
Research Approach
Trade databases, regulatory filings, and retail audit data formed the secondary backbone of this analysis. Primary interviews with infant nutrition R&D directors, FDA regulatory affairs specialists, hospital formulary managers, and supermarket category buyers complemented documentary sources. Bottom-up and top-down triangulation validated volume estimates across product type, distribution channel, packaging format, and formulation segments.
Bottom-up modeling built forecasts from facility-level production capacity and channel shipment data, while top-down approaches cross-checked against demographic birth cohort projections and breastfeeding duration trends. Segmentation dimensions included certification status, preparation format, packaging technology, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating input cost trajectories and parental willingness-to-pay elasticity estimates.
Revisions become necessary when FDA enforcement discretion policy shifts, major facility contamination events, or dairy commodity price spikes materialize across the analysis window. Forecasts reflect documented assumptions around regulatory stability and birth rate trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Middle East and Africa Organic Baby Food Market
Baby Food and Infant Formula
Europe Organic Baby Food Market
Baby Food and Infant Formula
Infant Formula Milk Powder with A2 Beta-Casein Market
Baby Food and Infant Formula
Functional Milk Replacers Market
Baby Food and Infant Formula
Kids Food and Beverages Market
Baby Food and Infant Formula
Wet Cat Food Market
Baby Food and Infant Formula
Global DHA Algae Oil for Infant Formula Market
Baby Food and Infant Formula
Second Stage Organic Infant Formula Market
Baby Food and Infant Formula
Europe Baby Food and Infant Formula Market
Baby Food and Infant Formula
Middle East and Africa Baby Food Market
Baby Food and Infant Formula
Middle-Aged and Elderly Milk Powder Market
Baby Food and Infant Formula
Infant Food Compliance Ready Fertility Input Market
Baby Food and Infant Formula
Baby Cereal-Based Complementary Food Market
Baby Food and Infant Formula
North America Organic Baby Food Market
Baby Food and Infant Formula
United States Baby Food and Infant Formula Market
Baby Food and Infant Formula
Baby Juice Market