
 Mammography Detectors Market | 2026-2036
Mammography Detectors Market Size, Share, and Industry Trends Forecast 2026-2036
Mammography Detectors Market Analytics
Radiation physicist and biomedical engineer talent is bifurcating between legacy analog service networks and digital detector deployment teams, constraining how quickly health systems convert screening fleets. Siemens Healthineers leverages in-house semiconductor fabrication to control flat-panel supply chains for European hospital networks. Hologic, Inc. dominates North American breast imaging through dense field service infrastructure that sustains long-term detector maintenance contracts. Canon Medical Systems Corporation specializes in solid-state detector architectures that anchor its position in Japanese diagnostic centers.
Mammography detectors are imaging sensors that convert X-ray photons into electrical signals, typically employing amorphous selenium or cesium iodide scintillator layers on thin-film transistor arrays to achieve spatial resolution below 100 micrometers for microcalcification detection. Their primary purpose is enabling early-stage breast cancer identification through high-contrast digital image acquisition. Digital detectors command the dominant value share as hospitals phase out screen-film cassettes, while digital breast tomosynthesis technology represents the fastest-expanding segment due to its superior lesion characterization through three-dimensional slice reconstruction. Flat-panel installations occupy the largest deployment base, though mobile units are gaining traction in rural screening programs where fixed system capital requirements limit access.
The FDA enforces stringent quality standards under the Mammography Quality Standards Act that dictate detector performance benchmarks and facility accreditation requirements for US screening centers. EMA harmonized medical device regulations through the MDR framework, which imposes clinical evidence thresholds on digital breast tomosynthesis systems entering European markets. Japan's PMDA maintains distinct pharmaceutical and medical device approval pathways that shape how detector manufacturers structure regulatory submissions for solid-state technologies. Stakeholders must monitor how evolving AI-assisted diagnostic classifications across FDA, EMA, and PMDA jurisdictions reshape detector software integration requirements and service revenue models.
Market Dynamics
The FDA's updated quality standards for digital breast tomosynthesis are compressing replacement cycles across hospital radiology departments, forcing facilities toward solid-state detector architectures before analog systems reach end-of-life.
Growth Catalysts
- MDR Clinical Evidence Thresholds:EMA's Medical Device Regulation mandates rigorous clinical validation for digital breast tomosynthesis systems entering European markets, accelerating hospital upgrades to compliant detector platforms.
- Amorphous Selenium Deposition:Advances in vacuum deposition techniques for direct-conversion layers are improving detective quantum efficiency in premium flat-panel installations across German diagnostic networks.
- Rural Screening Access Gaps:Mobile mammography units equipped with portable solid-state detectors are penetrating underserved regions in the United States where fixed system capital requirements previously excluded populations.
Market Restraints
- Cesium Iodide Crystal Supply Concentration:Scintillator material production clusters in East Asian manufacturing zones, exposing detector fabricators to single-source vulnerability and input cost volatility.
- FDA Accreditation Friction:Mammography Quality Standards Act facility certification timelines extend 12-18 months for digital breast tomosynthesis conversions, delaying revenue recognition for equipment vendors.
- Thin-Film Transistor Array Technical Ceiling:Amorphous silicon backplane electron mobility limits frame rates for high-resolution tomosynthesis slice reconstruction, constraining temporal resolution improvements.
Strategic Opportunities
- AI-Assisted Diagnostic Classifications:FDA software-as-a-medical-device pathways for lesion detection algorithms are creating integrated detector-analytics bundles that command service contract premiums.
- Japanese Diagnostic Center Modernization:PMDA streamlined approval pathways for solid-state technologies are accelerating replacement demand in Japan's aging installed base of screen-film systems.
- Photon-Counting Detector Convergence:Direct conversion cadmium zinc telluride sensors combined with spectral imaging protocols are opening premium positioning for next-generation breast tissue characterization.
Industry Challenges
- Radiation Physicist Talent Scarcity:Health systems struggle to recruit biomedical engineers certified for both legacy analog service networks and digital detector deployment teams, constraining fleet conversion velocity.
- Legacy PACS Integration Complexity:Hospital IT departments face DICOM conformance validation burdens when connecting new solid-state detectors to aging picture archiving infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mammography Detectors Market |
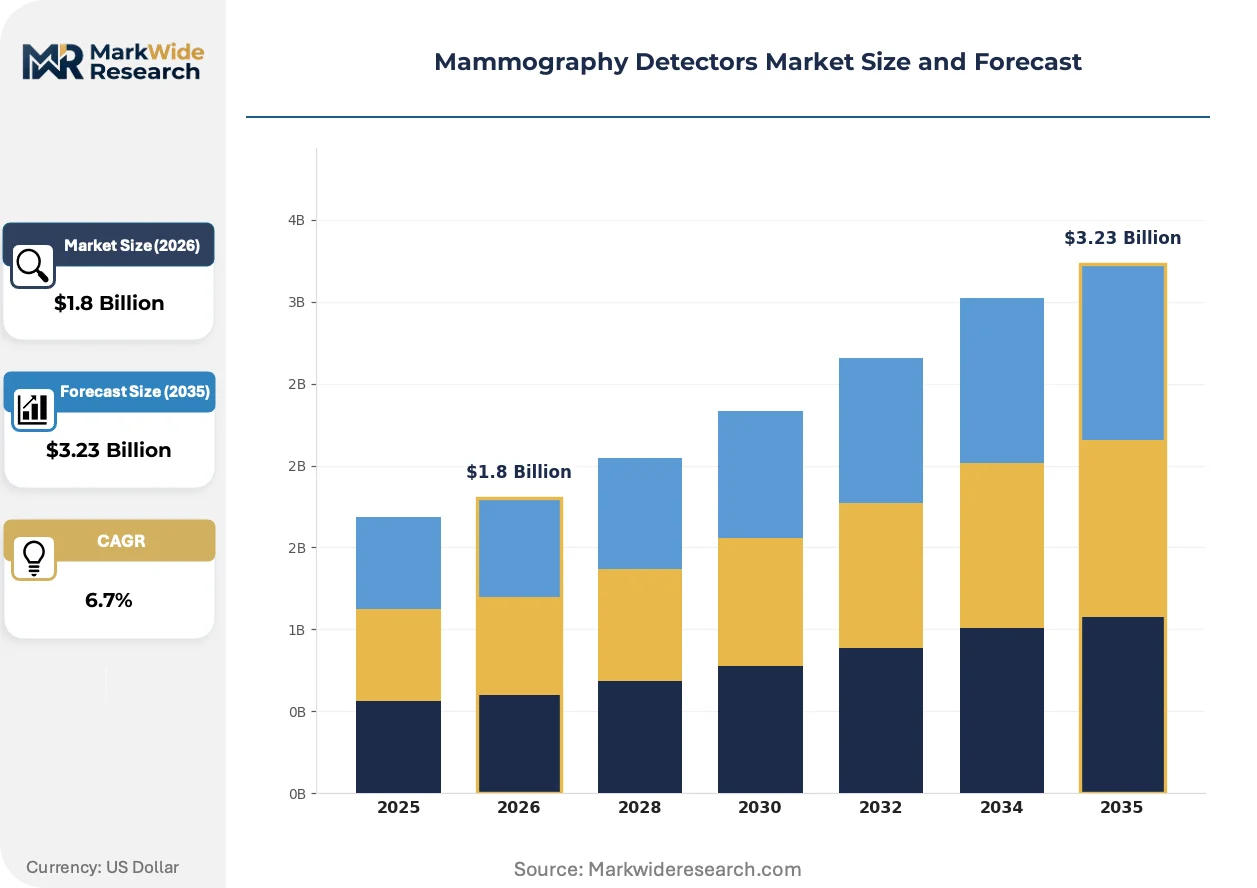
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Detectors, Digital Detectors, Computed Radiography, Solid-State Detectors Technology: Screen-Film, Flat Panel, Computed Radiography Systems, Digital Breast Tomosynthesis End User: Hospitals, Clinics, Diagnostic Centers, Research Institutions Installation: On-premises, Cloud-based, Mobile Units, Fixed Systems |
| Companies Covered | Hologic, Inc., Siemens Healthineers, FUJIFILM Holdings Corporation, GE Healthcare, Koninklijke Philips NV, Analogic Corporation, Varex Imaging, Canon Medical Systems Corporation, Teledyne DALSA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mammography Detectors Market Evolving Landscape
Detector architecture is pivoting from indirect scintillator-based conversion toward direct photon-counting semiconductors, reshaping competitive positioning around spectral imaging capabilities and software integration depth.
Amorphous selenium direct-conversion layers achieve higher detective quantum efficiency than cesium iodide scintillator-TFT sandwiches by eliminating light diffusion between absorption and signal readout. Academic medical centers in Germany and the United States are prioritizing selenium deposition platforms for microcalcification detection protocols. This technology is supplanting indirect-conversion architectures in premium flat-panel segment procurement specifications.
EMA's Medical Device Regulation imposes post-market surveillance obligations and clinical evidence thresholds that extend regulatory timelines for digital breast tomosynthesis system approvals. Manufacturers must maintain notified body relationships across multiple European member states to sustain market access. Breast imaging departments in France and Italy are consolidating vendor selections to partners with established MDR technical documentation capabilities.
Service contract unbundling is separating detector hardware warranties from software maintenance and AI algorithm update subscriptions. Independent service organizations are capturing replacement parts and calibration revenue previously retained by original equipment manufacturers. This pattern is most pronounced in United States hospital systems seeking operational expenditure flexibility over capital-intensive long-term agreements.
Mammography Detectors Market Segmentation
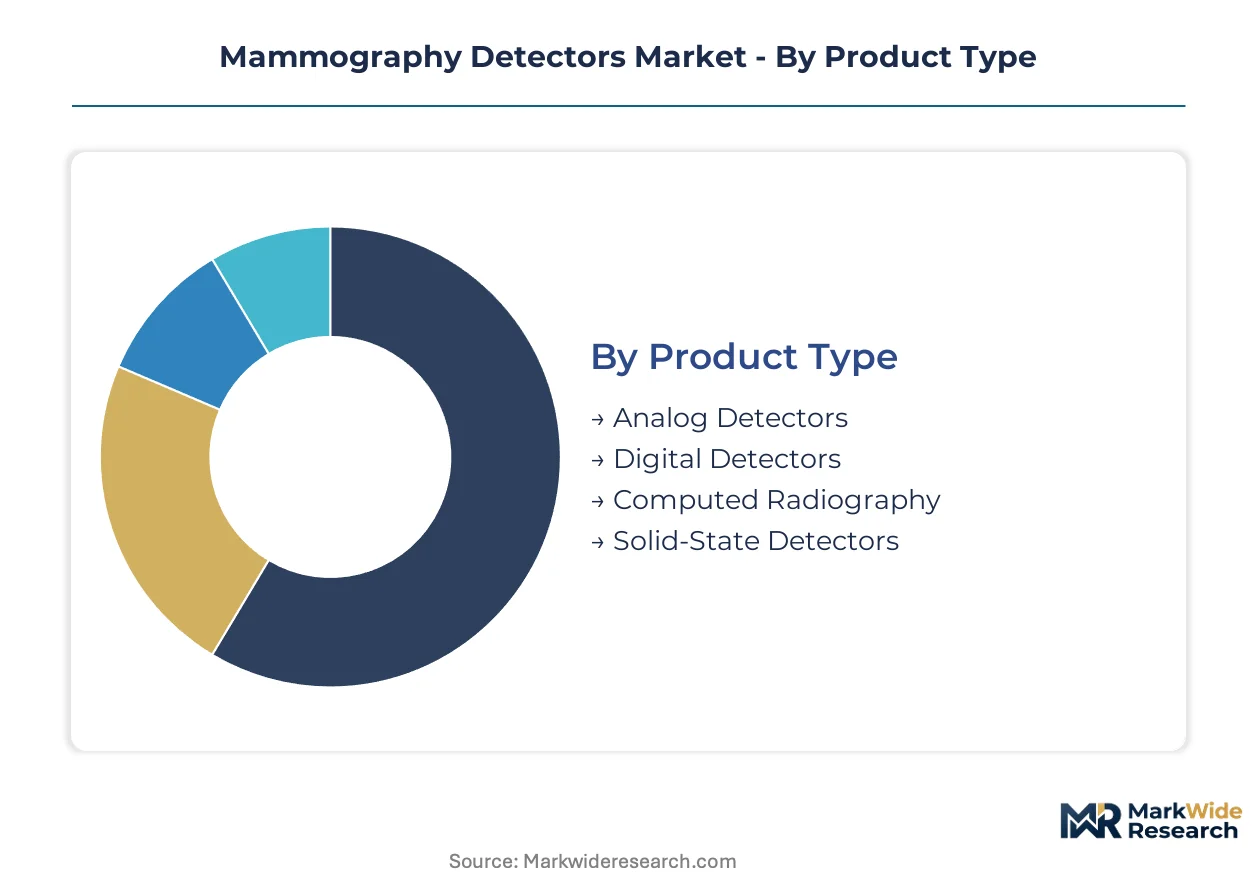
Segmentation reveals how detector procurement priorities diverge across clinical settings and infrastructure constraints. Margin pools concentrate in premium digital architectures serving high-volume screening networks, while cost-sensitive segments sustain analog and computed radiography demand in resource-limited environments.
Product Type:
Margin concentration sits in solid-state and premium digital platforms where replacement cycles compress under regulatory pressure.
- Digital Detectors:Amorphous selenium or cesium iodide scintillator layers on thin-film transistor arrays deliver spatial resolution below 100 micrometers. Hospital radiology departments in Germany and the United States prioritize these platforms for microcalcification detection protocols under FDA and EMA quality mandates.
- Solid-State Detectors:Direct-conversion architectures using cadmium zinc telluride or advanced selenium deposition eliminate intermediate light conversion stages. Academic medical centers in Japan's diagnostic networks are accelerating procurement as PMDA streamlines approval pathways for next-generation breast tissue characterization.
- Analog Detectors:Legacy screen-film cassettes persist in rural screening programs where capital constraints delay digital conversion.
- Computed Radiography:Photostimulable phosphor plates offer intermediate digital transition for facilities balancing image quality against upgrade costs.
Digital detectors hold installed capacity. Solid-state detectors are rotating up the share rankings.
Technology:
Volume concentration follows flat-panel deployments, though tomosynthesis commands accelerating replacement premiums.
- Digital Breast Tomosynthesis:Three-dimensional slice reconstruction through multiple low-dose projection angles enables superior lesion characterization. The FDA's updated quality standards are compressing replacement cycles across United States hospital radiology departments, forcing facilities toward compliant architectures before analog systems reach end-of-life.
- Flat Panel:Amorphous silicon or selenium backplanes integrated with scintillator or direct-conversion layers anchor the dominant deployment base. German diagnostic networks concentrate demand for premium installations with advanced vacuum deposition techniques improving detective quantum efficiency.
- Screen-Film:Conventional analog radiography persists in Japan's aging installed base and emerging market screening programs.
- Computed Radiography Systems:Cassette-based digital transition technology serves mid-tier facilities in France and Italy consolidating vendor selections under EMA MDR technical documentation requirements.
Flat panel technology holds installed capacity. Digital breast tomosynthesis is climbing the fastest.
End User:
Customer-type differentiation separates high-volume screening mandates from specialized research applications.
- Hospitals:Integrated radiology departments with dense field service infrastructure sustain long-term detector maintenance contracts and fleet standardization. North American health systems prioritize vendor partnerships with established FDA accreditation support capabilities.
- Diagnostic Centers:Dedicated breast imaging facilities concentrate throughput and demand premium spatial resolution for microcalcification protocols. Japanese diagnostic centers are modernizing aging screen-film systems through PMDA-streamlined solid-state approval pathways.
- Clinics:Outpatient settings balance equipment utilization rates against capital recovery timelines in competitive referral markets.
- Research Institutions:Academic medical centers pilot photon-counting detector convergence and spectral imaging protocols for next-generation tissue characterization.
Hospitals hold installed capacity. Diagnostic centers are gaining share fastest.
Installation:
Deployment architecture determines capital structure and operational flexibility for screening network planners.
- Fixed Systems:Permanent installations in dedicated mammography suites anchor high-volume screening programs with premium flat-panel configurations. German and United States hospital networks concentrate procurement for centralized breast imaging departments.
- Mobile Units:Portable solid-state detectors mounted on specialized vehicles penetrate underserved United States regions where fixed system capital requirements previously excluded rural populations. These units require robust calibration protocols and independent service organization support for replacement parts revenue.
- On-premises:Local hardware and PACS integration dominates hospital IT architectures facing DICOM conformance validation burdens with aging picture archiving infrastructure.
- Cloud-based:Remote image storage and AI-assisted diagnostic algorithm updates are emerging in service contract unbundling patterns separating hardware warranties from software maintenance subscriptions.
Fixed systems hold installed capacity. Mobile units are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German diagnostic networks concentrate procurement for premium flat-panel installations, while United States hospital systems prioritize FDA-compliant digital breast tomosynthesis upgrades. Japanese centers modernize aging screen-film infrastructure through streamlined PMDA pathways. Mobile units penetrate rural United States regions where fixed capital requirements previously excluded populations.
United States
Hospital radiology departments drive detector replacement cycles under FDA Mammography Quality Standards Act mandates. The FDA's updated digital breast tomosynthesis quality standards compress upgrade timelines before analog systems reach end-of-life. Mobile mammography units equipped with portable solid-state detectors expand screening access across underserved rural counties in Texas and the Mountain West.
Germany
Academic medical centers prioritize amorphous selenium deposition platforms for microcalcification detection protocols. EMA Medical Device Regulation mandates rigorous clinical validation, accelerating hospital procurement of compliant detector architectures. Bavarian diagnostic networks concentrate demand for premium flat-panel installations with advanced vacuum deposition techniques improving detective quantum efficiency.
Japan
Diagnostic centers modernize aging installed bases of screen-film systems through PMDA-streamlined approval pathways for solid-state technologies. METI industrial policy supports domestic semiconductor fabrication for next-generation breast tissue characterization. Tokyo and Osaka metropolitan clusters anchor procurement for direct-conversion cadmium zinc telluride sensor platforms.
France
Breast imaging departments consolidate vendor selections under EMA MDR technical documentation requirements for post-market surveillance obligations. ANSM national pharmaceutical regulator enforces clinical evidence thresholds on digital breast tomosynthesis system approvals. Île-de-France hospital networks standardize on partners with established notified body relationships across multiple European member states.
United Kingdom
NHS screening programs drive fleet standardization across integrated radiology departments with dense field service infrastructure. MHRA medical device regulations align with EMA MDR frameworks for clinical validation requirements. London and Southeast England diagnostic centers concentrate procurement for premium spatial resolution platforms serving high-volume breast imaging mandates.
Mammography Detectors Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in detector fabrication and field service deployment. Siemens Healthineers leverages in-house semiconductor fabrication to control flat-panel supply chains for European hospital networks. Hologic, Inc. dominates North American breast imaging through dense field service infrastructure sustaining long-term maintenance contracts. Three archetypes define competitive positioning: vertically integrated semiconductor fabricators, regional field service specialists, and software-analytics integrators. Dominant competitive moves include strategic partnerships for AI-assisted diagnostic bundles and geographic expansion through mobile unit service networks.
Among North American imaging specialists, Hologic, Inc. and Analogic Corporation exemplify the field service-intensive archetype, while Siemens Healthineers anchors the integrated fabrication tier with captive semiconductor production capabilities. Canon Medical Systems Corporation occupies a specialist position in solid-state detector architectures serving Japanese diagnostic center modernization programs. These three companies represent distinct strategic vectors: service contract density, upstream supply control, and premium technology specialization.
| Leading Market Players |
|---|
| Hologic, Inc. |
| Siemens Healthineers |
| FUJIFILM Holdings Corporation |
| GE Healthcare |
| Koninklijke Philips NV |
| Analogic Corporation |
| Varex Imaging |
| Canon Medical Systems Corporation |
| Teledyne DALSA |
| Others |
Value Network & Pricing Analysis
Ninety-day cesium iodide crystal inventory cycles concentrate pricing power with East Asian scintillator fabricators, compressing margin flexibility for detector assemblers in Germany and the United States while amplifying cost pass-through to hospital radiology departments under FDA quality mandates.
Pricing Analysis
Long-term detector maintenance contracts dominate procurement structures, though service contract unbundling is fragmenting revenue streams. Pricing stratifies across premium flat-panel installations with amorphous selenium deposition, standard TFT-array configurations, and economy-tier computed radiography transitions. Cost compression in standard digital detectors intensifies as independent service organizations capture replacement parts revenue previously retained by original equipment manufacturers. Academic medical centers in Germany exhibit least price sensitivity for premium spatial resolution, while rural United States screening programs face acute capital constraints.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for thin-film transistor array substrates sourced from Taiwanese and South Korean semiconductor foundries. Scintillator material production draws from Japanese and Chinese chemical processing clusters, with cesium iodide crystal growth tethered to single-source vulnerability in East Asian manufacturing zones. Tariff exposure on semiconductor components threatens detector fabricator margins. Distribution runs through original equipment manufacturer field service networks and emerging independent service organization channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity opens as service contract unbundling separates hardware warranties from AI algorithm subscriptions, creating niche entry points for specialized calibration and replacement parts providers.
For Market Incumbents: Secure captive semiconductor fabrication capacity for amorphous selenium deposition to defend against supply disruption from East Asian scintillator concentration. Lock hospital system partnerships through bundled detector-analytics offerings before independent service organizations capture maintenance revenue. FDA accreditation friction represents the critical threat window requiring preemptive field service infrastructure investment. For New Entrants and Emerging Players: PMDA streamlined approval pathways for solid-state technologies offer fastest regulatory traction for cadmium zinc telluride sensor platforms targeting Japanese diagnostic center modernization. Mobile mammography unit deployment in underserved United States rural counties presents the most penetrable white-space. Lead with independent service organization partnerships for calibration protocol delivery to bypass incumbent field service density. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified imaging conglomerates with underoptimized breast imaging detector divisions lacking AI software integration depth. Five-to-ten-year viability hinges on spectral imaging protocol convergence. Watch photon-counting detector regulatory clearance velocity as inflection indicator for premium positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | EMA notified body relationships secure European hospital network access under post-market surveillance obligations. |
| AI Software Companion Development | FDA software-as-a-medical-device pathways enable integrated detector-analytics bundles commanding service premiums. |
| Mobile Unit Service Network Expansion | Portable solid-state detector deployment penetrates rural United States counties excluded by fixed capital requirements. |
| Backward Integration into Selenium Deposition | In-house vacuum deposition techniques improve detective quantum efficiency for German academic medical center procurement. |
| Hospital System Partnership Consolidation | Dense field service infrastructure sustains long-term maintenance contracts against independent service organization encroachment. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with radiation physicists, biomedical engineers, hospital purchasing committee members, and GPO contracts managers; and secondary validation against FDA 510(k) filings, EMA MDR technical documentation, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up detector shipment triangulation converged with top-down screening program capacity modeling.
Across the projection horizon, the analytical framework modeled volume and value outputs through segmentation by detector architecture, technology platform, end-user setting, and installation type. CAGRs derived from replacement cycle compression analysis under evolving quality standards. Forecast inputs incorporated PMDA approval pathway timelines and rural screening access gap closure rates.
Underlying assumptions cover regulatory timeline stability and semiconductor input cost trajectories, with deviation risk concentrated in cesium iodide supply disruption and AI diagnostic classification velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Picture Archiving Communications System Market
Medical Imaging
Ultrasound Image Processing Software Market
Medical Imaging
Gallium-68 Market
Medical Imaging
Asia-Pacific Fluoroscopy Market
Medical Imaging
Europe Nuclear Imaging Market
Medical Imaging
Global Technetium-99M Market
Medical Imaging
United Kingdom Magnetic Resonance Imaging Market
Medical Imaging
Medical Holography Market
Medical Imaging
Portable Ultrasound Bladder Scanner Market
Medical Imaging
Medical X-Ray Market
Medical Imaging
Global Digital Radiography Market
Medical Imaging
Global Ultrasound Imaging Devices Market
Medical Imaging
Diagnostic Ultrasound Market
Medical Imaging
Mammography Market
Medical Imaging
Forensic Imaging Market
Medical Imaging
Remanufactured Medical Imaging Devices Market