
 Cone Beam CT Scanner Market | 2026-2036
Cone Beam CT Scanner Market Size, Share, and Industry Trends Forecast 2026-2036
Cone Beam CT Scanner Market Intelligence
Radiology technologist training pipelines is bifurcating the competitive landscape into vendors with embedded education ecosystems versus hardware-only suppliers. Planmeca leverages its Helsinki-based training academy to lock in Nordic dental clinic loyalty. Carestream Health anchors North American hospital procurement through bundled service contracts that span hardware and PACS integration. Vatech competes aggressively on price in Southeast Asian imaging center tenders while maintaining CE-marked quality documentation.
A cone beam CT scanner acquires volumetric anatomical datasets through a cone-shaped X-ray beam rotating around the patient, typically delivering sub-millimeter isotropic resolution at radiation doses lower than conventional multislice CT. Its primary purpose centers on three-dimensional hard-tissue visualization for preoperative planning and intraoperative navigation across dental, orthopedic, and interventional specialties. Dental product type installations dominate unit volumes globally, though orthopedic applications command higher per-system pricing due to extended field-of-view requirements and weight-bearing mechanical engineering. Low-dose technology is gaining fastest among end users, driven by pediatric eligibility expansion and ALARA compliance mandates that elevate reimbursement scrutiny on radiation metrics.
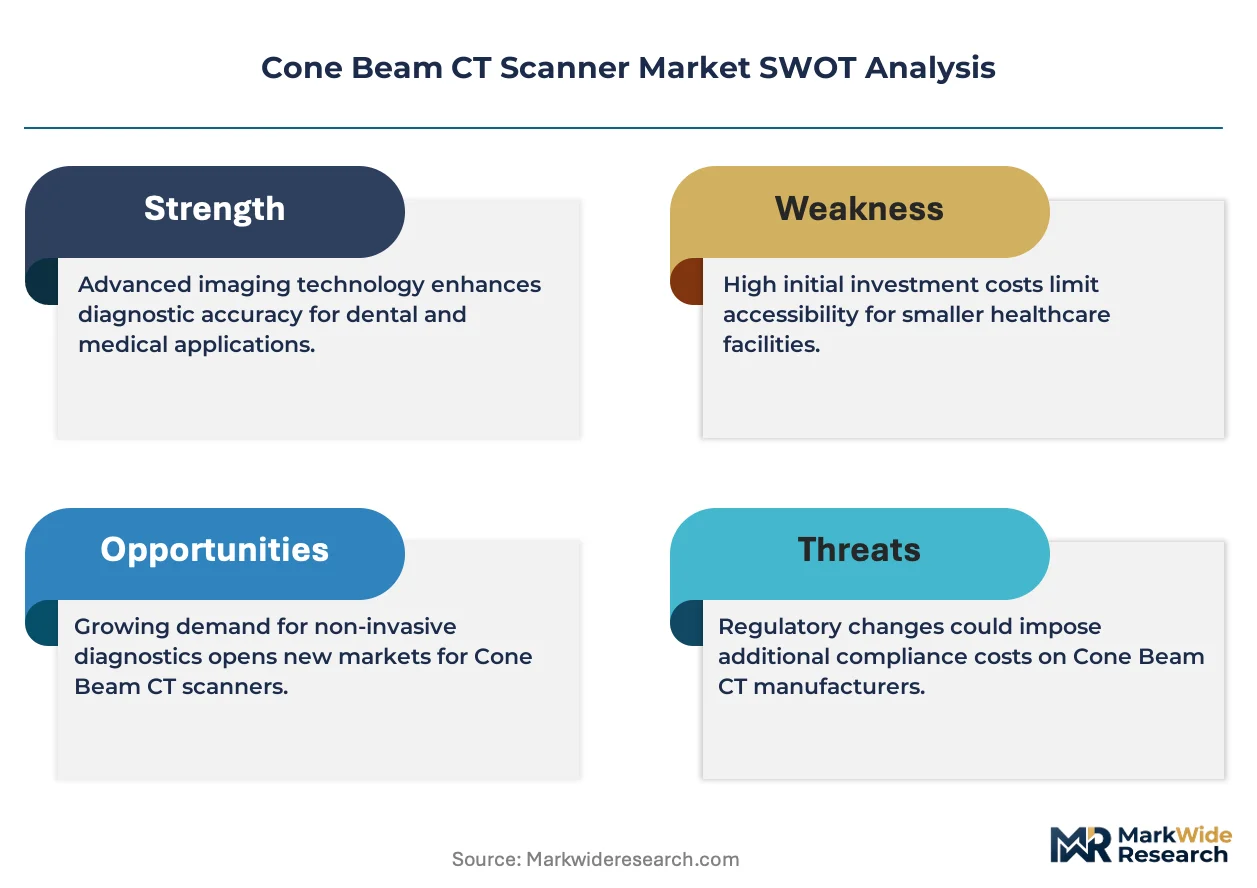
FDA 510(k) premarket notification requirements and EU MDR technical documentation standards govern software algorithm validation, particularly for AI-enhanced image reconstruction modules that now accompany premium system configurations. Japan's PMDA enforces distinct clinical performance benchmarks for imported devices, creating a dual-track compliance burden for manufacturers seeking access across Atlantic and Pacific regulatory zones. Stakeholders must monitor evolving cybersecurity guidance from FDA and post-market surveillance obligations under EU MDR Article 83, as connected imaging platforms face escalating threat surface exposure and liability frameworks.
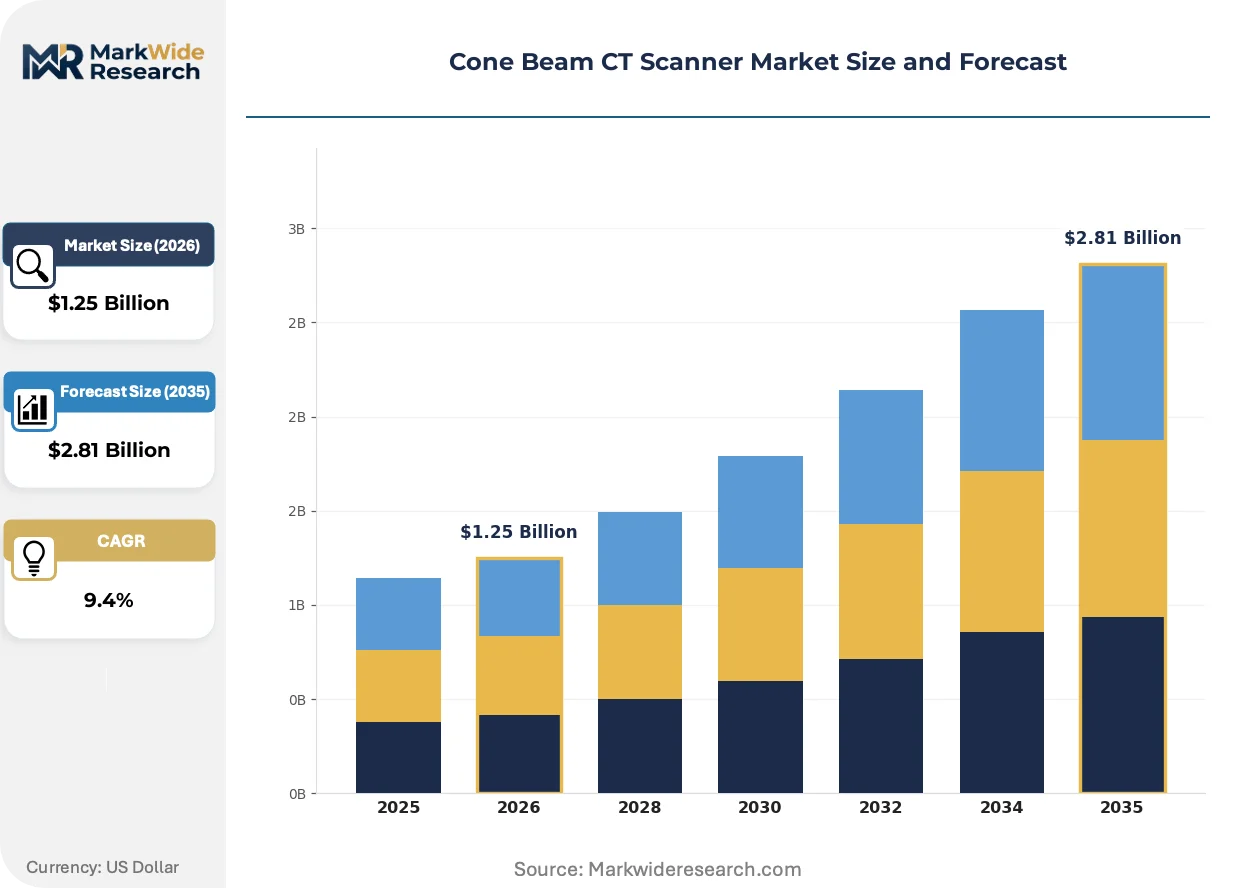
Market Dynamics
AI-integrated reconstruction algorithms are forcing a compliance recalibration across manufacturing pipelines as FDA 510(k) pathways and EU MDR technical documentation standards tighten validation protocols for software-enabled imaging systems.
Growth Catalysts
- ALARA compliance mandates:Pediatric eligibility expansion for low-dose protocols is pulling replacement demand from German and Japanese dental clinics seeking dose audit documentation for reimbursement.
- Metropolitan hospital networks:South Korea's capital-region health systems are consolidating procurement around connected imaging platforms that integrate with electronic health record architectures.
- Implantology workflow digitization:Preoperative planning software compatibility is becoming a non-negotiable specification in tier-1 Indian imaging center tenders.
Market Restraints
- Dual-track compliance burden:Japan's PMDA clinical performance benchmarks for imported devices impose redundant testing costs on manufacturers already certified under EU MDR or FDA pathways.
- Extended field-of-view engineering:Orthopedic system configurations require specialized mechanical components that concentrate supply among a limited base of precision-machining suppliers.
- Conventional multislice CT substitution:Hospital radiology departments in budget-constrained environments default to established CT modalities for overlapping anatomical coverage.
Strategic Opportunities
- EU MDR Article 83 post-market surveillance:Cybersecurity validation services represent an adjacent revenue stream for vendors with embedded software engineering capabilities.
- Weight-bearing mechanical engineering:Convergence with intraoperative navigation systems is opening orthopedic ambulatory surgery center penetration beyond traditional hospital settings.
- PACS integration bundling:North American hospital procurement committees are unbundling hardware-only contracts, creating entry points for full-stack service providers.
Industry Challenges
- Radiology technologist AI literacy:Training pipelines for reconstruction algorithm interpretation lag behind deployment timelines, creating workflow friction in high-throughput clinics.
- CE-marked quality documentation:Southeast Asian price-competitive tenders demand simultaneous cost compression and regulatory file maintenance, straining quality management resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cone Beam CT Scanner Market |
| Market Size in 2026 | $1.25 Billion |
| Market Size in 2035 | $2.81 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dental, Orthopedic, Oncology, Cardiology End User: Hospitals, Imaging Centers, Dental Clinics, Research Institutes Technology: 2D, 3D, Dual-Modality, Low-Dose Application: Diagnosis, Treatment Planning, Surgical Navigation, Implantology |
| Companies Covered | Planmeca, Carestream Health, Dentsply Sirona, Vatech, CurveBeam AI, J. Morita Corporation, Cefla Medical Equipment, Asahi Roentgen, Genoray, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cone Beam CT Scanner Market Strategic Shifts & Innovations
Reconstruction software architectures are actively fragmenting competitive positioning between vendors with captive algorithm development and those dependent on licensed third-party modules.
Photon-counting detector layers are bifurcating the premium system tier from conventional flat-panel configurations. Nordic dental clinic chains are prioritizing these platforms for implantology workflows despite extended procurement cycles. The technology is bifurcating vendor ecosystems into those with semiconductor foundry partnerships and hardware-assemblers without direct sensor supply.
EU MDR software validation requirements are extending technical documentation obligations to AI-enhanced image reconstruction modules. Manufacturers must now submit algorithm performance benchmarking against reference datasets previously exempt from 510(k) pathways. Premium system configurations face the steepest compliance cost escalation as notified bodies expand scrutiny of machine-learning training data provenance.
After-sales service unbundling is compressing switching cycles among imaging center chains previously locked into decade-long maintenance agreements. German and Japanese dental clinics now negotiate separate algorithm update subscriptions from hardware service contracts. This pattern concentrates in metropolitan markets where multiple vendors maintain localized technical support infrastructure.
Cone Beam CT Scanner Market Segmentation
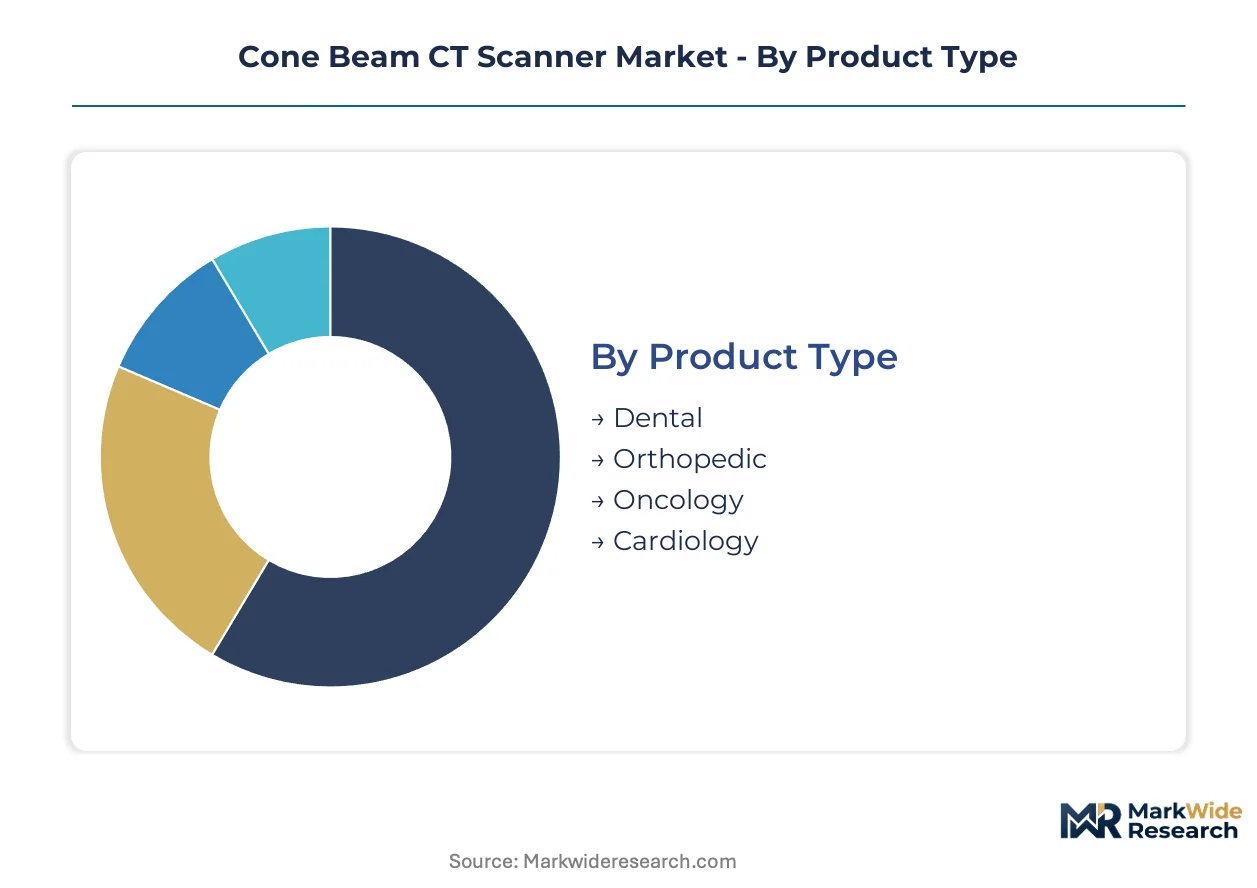
Cone beam CT scanner procurement patterns diverge sharply across clinical settings, with hardware specifications and software ecosystems calibrated to distinct reimbursement pathways and workflow integration requirements. Understanding these segment boundaries clarifies where vendors can compress cost structures versus where premium positioning sustains margin.
Product Type:
Dental systems dominate domestic installation volumes across Germany and Japan, while orthopedic configurations drive export-led revenue concentration toward North American hospital networks.
- Dental:Systems deliver sub-millimeter isotropic resolution optimized for maxillofacial hard-tissue visualization, with German and Japanese clinics prioritizing low-dose protocols for pediatric eligibility expansion. ALARA compliance mandates are accelerating replacement cycles as dose audit documentation becomes prerequisite for reimbursement.
- Orthopedic:Extended field-of-view engineering enables weight-bearing mechanical configurations that command premium pricing. Demand concentrates in South Korean metropolitan hospital networks where intraoperative navigation integration drives procurement specifications.
- Oncology:Specialized configurations support radiation therapy planning workflows with enhanced soft-tissue contrast algorithms. Research institutes in tier-1 Indian imaging center chains are piloting adoption for head-and-neck tumor delineation.
- Cardiology:Emerging segment addressing electrophysiology ablation guidance with cardiac-gated acquisition protocols. Regulatory validation under FDA 510(k) pathways remains incomplete for most vendor portfolios.
Dental commands the established base. The steepest expansion runs through orthopedic applications.
End User:
Customer type determines service contract structure, with hospital procurement favoring bundled PACS integration while imaging centers negotiate unbundled algorithm subscriptions.
- Hospitals:Capital procurement committees prioritize connected imaging platforms that integrate with electronic health record architectures. South Korean capital-region health systems are consolidating vendor relationships around full-stack service providers.
- Imaging Centers:Tier-1 Indian chains demand preoperative planning software compatibility as non-negotiable tender specifications. After-sales service unbundling is compressing switching cycles previously locked into decade-long maintenance agreements.
- Dental Clinics:Nordic chains leverage embedded education ecosystems to lock in vendor loyalty. German and Japanese clinics now negotiate separate algorithm update subscriptions from hardware service contracts.
- Research Institutes:Academic medical centers pilot photon-counting detector layers for implantology workflow validation. Extended procurement cycles accompany semiconductor foundry partnership requirements.
Hospitals anchor volume procurement. Imaging centers are climbing the fastest on digitization-driven replacement demand.
Technology:
Technology tier stratifies across detector architecture maturity, with flat-panel configurations serving cost-sensitive segments and photon-counting layers commanding premium positioning.
- 3D:Volumetric reconstruction algorithms represent the clinical standard for preoperative planning across dental and orthopedic specialties. EU MDR software validation requirements are extending technical documentation obligations to AI-enhanced modules previously exempt from 510(k) pathways.
- Low-Dose:Pediatric eligibility expansion is pulling replacement demand from German and Japanese dental clinics seeking dose audit documentation. ALARA compliance mandates elevate reimbursement scrutiny on radiation metrics.
- 2D:Legacy configurations persist in budget-constrained Southeast Asian imaging center tenders. Vatech competes aggressively on price while maintaining CE-marked quality documentation.
- Dual-Modality:Convergence with intraoperative navigation systems is opening orthopedic ambulatory surgery center penetration beyond traditional hospital settings. Weight-bearing mechanical engineering requirements concentrate supply among limited precision-machining suppliers.
3D technology holds the installed base. Low-dose protocols are gaining share fastest on regulatory compliance tailwinds.
Application:
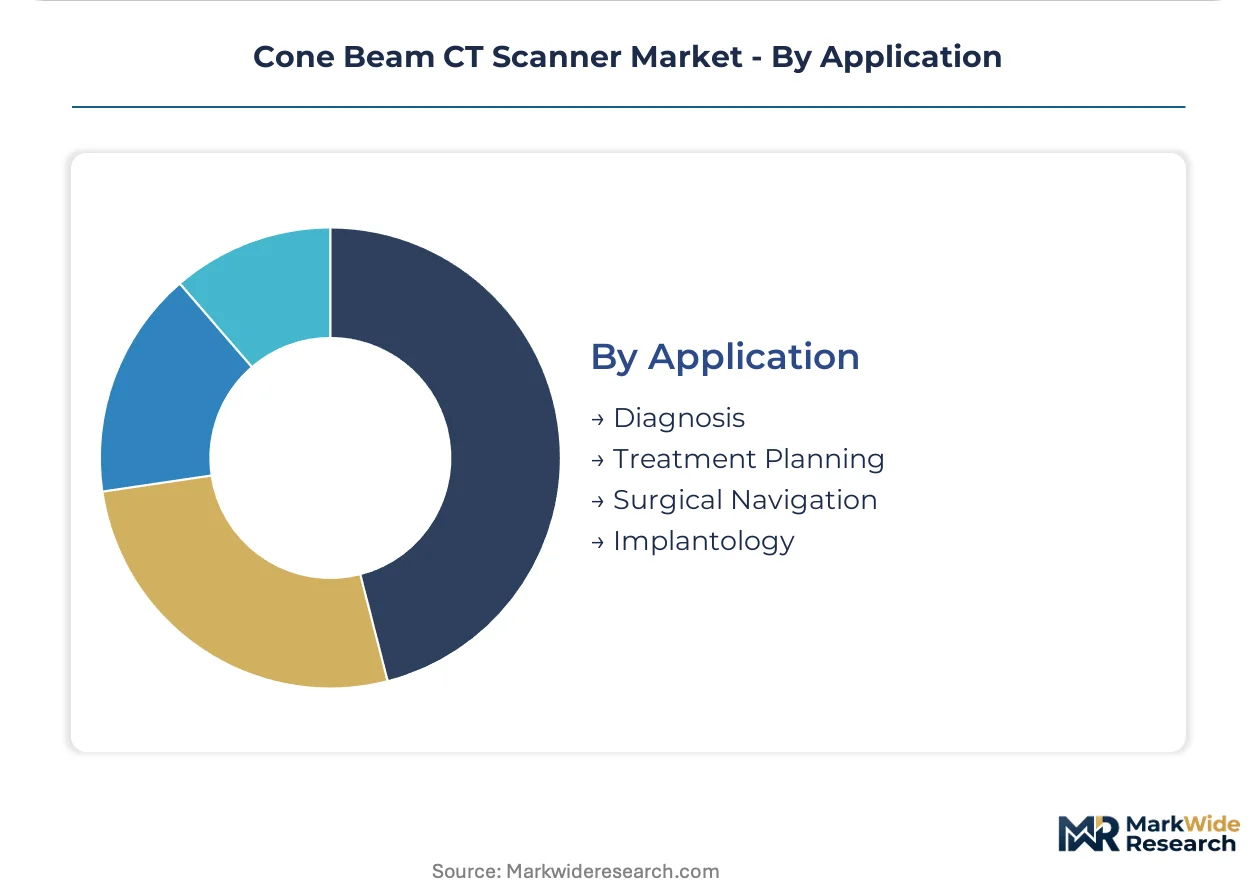
Application scope determines software licensing architecture, with diagnosis workflows requiring basic reconstruction packages and surgical navigation demanding real-time tracking integration.
- Implantology:Preoperative planning software compatibility is becoming non-negotiable in tier-1 Indian imaging center tenders. Nordic dental clinic chains prioritize photon-counting platforms despite extended procurement cycles.
- Treatment Planning:AI-integrated reconstruction algorithms are forcing compliance recalibration across manufacturing pipelines as FDA 510(k) and EU MDR tighten validation protocols. Premium system configurations face steepest documentation cost escalation.
- Diagnosis:Conventional multislice CT substitution pressure concentrates in budget-constrained hospital radiology departments with overlapping anatomical coverage requirements.
- Surgical Navigation:Real-time tracking integration demands specialized mechanical engineering that concentrates supply among vendors with captive algorithm development versus licensed third-party module dependence.
Implantology anchors the revenue base. Treatment planning applications are expanding most quickly on AI-enhanced reconstruction adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese dental clinics where low-dose protocol mandates justify premium procurement, while Indian tier-1 imaging centers compress vendor margins through aggressive tender competition. This asymmetry shapes divergent go-to-market architectures across the installed base.
United States
Hospital procurement committees in the United States prioritize connected imaging platforms integrating with electronic health record architectures. FDA 510(k) premarket notification requirements govern software algorithm validation for AI-enhanced reconstruction modules. Carestream Health anchors North American hospital procurement through bundled service contracts spanning hardware and PACS integration.
Germany
German dental clinics are expanding adoption of low-dose systems for implantology workflows driven by ALARA compliance mandates. EU MDR technical documentation standards tighten software validation requirements for AI-integrated reconstruction algorithms. Planmeca leverages its Helsinki-based training academy to lock in Nordic dental clinic loyalty across the broader German-speaking region.
Japan
Japanese dental clinics seek dose audit documentation for reimbursement under pediatric eligibility expansion for low-dose protocols. PMDA enforces distinct clinical performance benchmarks for imported devices, creating a dual-track compliance burden for manufacturers. Metropolitan hospital networks in the capital region consolidate procurement around full-stack service providers.
India
Tier-1 Indian imaging center chains demand preoperative planning software compatibility as non-negotiable tender specifications. The country's national medical device regulator maintains quality documentation requirements alongside cost compression pressures. Vatech competes aggressively on price in Southeast Asian tenders while maintaining CE-marked quality documentation.
South Korea
South Korea's metropolitan hospital networks concentrate demand for connected imaging platforms with electronic health record integration. MFDS maintains cybersecurity guidance for connected imaging platforms facing escalating threat surface exposure. The Seoul Capital Area health systems are consolidating vendor relationships around full-stack service providers.
Cone Beam CT Scanner Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the cone beam CT scanner market. Premium-tier vendors with captive algorithm development and semiconductor foundry partnerships command pricing power in Nordic and North American markets. Cost-optimized suppliers with licensed third-party modules and hardware-assembly models penetrate Southeast Asian tenders. Two dominant competitive moves are reshaping positioning: after-sales service unbundling that compresses switching cycles, and embedded education ecosystems that lock in clinic loyalty.
Among Nordic and North American premium-tier vendors, Planmeca and Carestream Health exemplify contrasting geographic anchoring strategies. Planmeca occupies a position within the embedded education ecosystem archetype, leveraging training infrastructure to sustain clinic relationships. Carestream Health represents the bundled service contract model, anchoring hospital procurement through full-stack hardware and software integration. Vatech sits within the cost-competitive tier, maintaining CE-marked quality documentation while penetrating price-sensitive tenders.
| Leading Market Players |
|---|
| Planmeca |
| Carestream Health |
| Dentsply Sirona |
| Vatech |
| CurveBeam AI |
| J. Morita Corporation |
| Cefla Medical Equipment |
| Asahi Roentgen |
| Genoray |
| Others |
Cost & Logistics Intelligence
Detector fabrication scale economies in South Korea and Japan concentrate premium-tier supply among semiconductor foundry partners, compressing cost floors for flat-panel configurations while elevating entry barriers for photon-counting architectures. This concentration bifurcates vendor tiers between captive sensor developers and hardware-assemblers dependent on licensed detector supply.
Pricing Analysis
The customization-premium spread separates configured-to-order orthopedic systems from standard dental configurations. Three-tier pricing structure across premium, standard, and economy levels reflects detector architecture maturity and software ecosystem depth. Price differentiation hinges on AI-enhanced reconstruction licensing and after-sales service bundling. Cost compression in Southeast Asian tenders is intensifying because Vatech and Genoray compete aggressively on CE-marked hardware without algorithm subscriptions. Imaging centers in India and Vietnam exhibit highest price sensitivity; Nordic dental chains anchored by Planmeca's education ecosystem demonstrate lowest.
Supply Chain Analysis
Germany and Japan anchor precision-machining capacity for weight-bearing mechanical components, while South Korea and Taiwan feed flat-panel detector substrate supply. Cone beam CT scanner production draws from rare-earth phosphor deposits concentrated in Chinese processing facilities, precision ball-bearing supply from German and Japanese specialty manufacturers, and semiconductor-grade silicon from South Korean foundries. Single-source vulnerability concentrates in extended field-of-view mechanical engineering where orthopedic configurations require captive machining partnerships. Distribution runs through hospital procurement committees in North America and tier-1 imaging center chains in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection in cone beam CT scanner procurement is accelerating as PACS integration and algorithm subscription unbundling transform hardware vendors into recurring-revenue service providers. Interoperability with electronic health record architectures now determines contract renewal rates.
For Market Incumbents: Secure embedded education ecosystem lock-in through training academy expansion in Nordic and German-speaking regions. Deepen backward integration into semiconductor foundry partnerships for photon-counting detector supply. Conventional multislice CT substitution in budget-constrained hospital radiology departments represents the priority threat; vertical integration into AI-enhanced reconstruction algorithm development is the defensive lever.
For New Entrants and Emerging Players: Cybersecurity validation services for EU MDR Article 83 compliance represent the most penetrable service-layer gap where incumbents under-serve. Target orthopedic ambulatory surgery centers in South Korea and North America with weight-bearing mechanical configurations bundled with intraoperative navigation integration. White-space entry runs through unbundled algorithm subscription models in metropolitan hospital networks seeking to separate hardware procurement from software update cycles.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vendors with captive algorithm development and semiconductor foundry partnerships over hardware-assemblers dependent on licensed third-party modules. Long-term viability across the analysis window hinges on software-enabled recurring revenue attachment rates. Acquisition target archetype: mid-tier vendors with CE-marked quality documentation and established Southeast Asian distribution seeking algorithm development capability. Signal to watch: photon-counting detector layer adoption rates in Nordic dental clinic chains as inflection indicator for premium-tier demand shift.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Integrated Reconstruction Development | FDA 510(k) and EU MDR validation requirements favor vendors with captive algorithm engineering. |
| Photon-Counting Detector Partnership | Semiconductor foundry alliances in South Korea and Taiwan secure premium-tier supply positioning. |
| PACS Integration Bundling | North American hospital procurement committees prioritize full-stack service providers over hardware-only vendors. |
| Embedded Education Ecosystem Expansion | Planmeca's Helsinki-based training academy demonstrates loyalty-lock mechanics in Nordic dental chains. |
| Cybersecurity Validation Service Launch | EU MDR Article 83 post-market surveillance obligations create adjacent revenue for software-capable vendors. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with hospital procurement committee members, dental clinic practice managers, biomedical engineers, GPO contracts managers, and radiology technologist training directors. Secondary validation incorporated FDA 510(k) premarket notification databases, EU MDR technical documentation filings, hospital procurement contract registries, and GPO pricing benchmark reports. Bottom-up installation data triangulated against top-down vendor revenue segmentation across product type, end user, and technology tier.
Across the analysis window, volume and value outputs reflect segmentation modeling by detector architecture maturity, software ecosystem integration depth, field-of-view specification, and regional regulatory cluster. CAGRs were derived from replacement cycle analysis, pediatric eligibility expansion trajectories, and ALARA compliance mandate adoption curves. Forecast inputs incorporated dose audit documentation requirements in Germany and Japan, tender specification evolution in Indian tier-1 imaging centers, and cybersecurity guidance enforcement in South Korea.
Underlying assumptions cover stable regulatory enforcement timelines for FDA and EU MDR software validation, with deviation risk concentrated in PMDA benchmark harmonization delays and photon-counting detector yield ramp schedules. Forecasts reflect these conditions with explicit acknowledgment that tariff exposure on precision-machined components or rare-earth phosphor supply disruption could revise trajectory. Recalibration cycles align with material shifts in reimbursement scrutiny on radiation metrics and post-market surveillance obligation enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Preclinical Brain Imaging Market
Medical Imaging
North America Digital Pathology Market
Medical Imaging
Global Digital Radiography Market
Medical Imaging
Argentina Diagnostic Imaging Equipment Market
Medical Imaging
South Korea Mammography Market
Medical Imaging
Open System MRI Market
Medical Imaging
AI in Diagnostic Imaging Market
Medical Imaging
Advanced Computed Tomography (CT) Scanner Market
Medical Imaging
Surgical Imaging Robots Market
Medical Imaging
Spain Mammography Market
Medical Imaging
UK Digital Radiology Market
Medical Imaging
X-Ray Devices Market
Medical Imaging
India Mammography Market
Medical Imaging
Global Medical Image Management Market
Medical Imaging
Medical Digital Imaging Devices Market
Medical Imaging
Italy Computed Tomography Market