
 Radiographic Film Processor Market | 2026-2036
Radiographic Film Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Radiographic Film Processor Market Analytics
Digital radiography integration is rewriting how radiographic film processors fit into clinical workflows, forcing manufacturers to bridge analog chemistry with digital output compatibility. Carestream Health leverages its installed base of legacy processors to sustain recurring revenue from consumables and service contracts. Fujifilm Holdings Corporation anchors its position through backward integration into proprietary film chemistry and digital sensor development. Konica Minolta competes by specializing in compact tabletop units tailored for high-volume dental and veterinary practices.
A radiographic film processor is an electromechanical device that develops fixed medical or industrial X-ray films through controlled immersion in developer, fixer, and wash solutions maintained at precise temperature and agitation parameters, producing diagnostic images for clinical interpretation. Automatic processors dominate hospital procurement due to throughput requirements and labor cost containment, while manual processors retain niche demand in research labs and low-budget veterinary settings where film volume does not justify capital expenditure. Hybrid systems represent the fastest-growing technology segment as facilities phase out pure analog rooms without committing to full digital detector replacement.
FDA 21 CFR Part 820 quality system regulations and ISO 13485 medical device standards govern processor manufacturing, installation, and servicing across the United States, while CE marking under the EU MDR shapes market access for European-bound equipment. The EPA regulates silver recovery and fixer effluent discharge from wet chemistry operations, adding compliance cost layers that favor digital displacement. Stakeholders must monitor regulatory divergence between jurisdictions that accelerate digital mandates versus those that grandfather analog equipment in rural or cost-constrained healthcare networks.
Market Dynamics
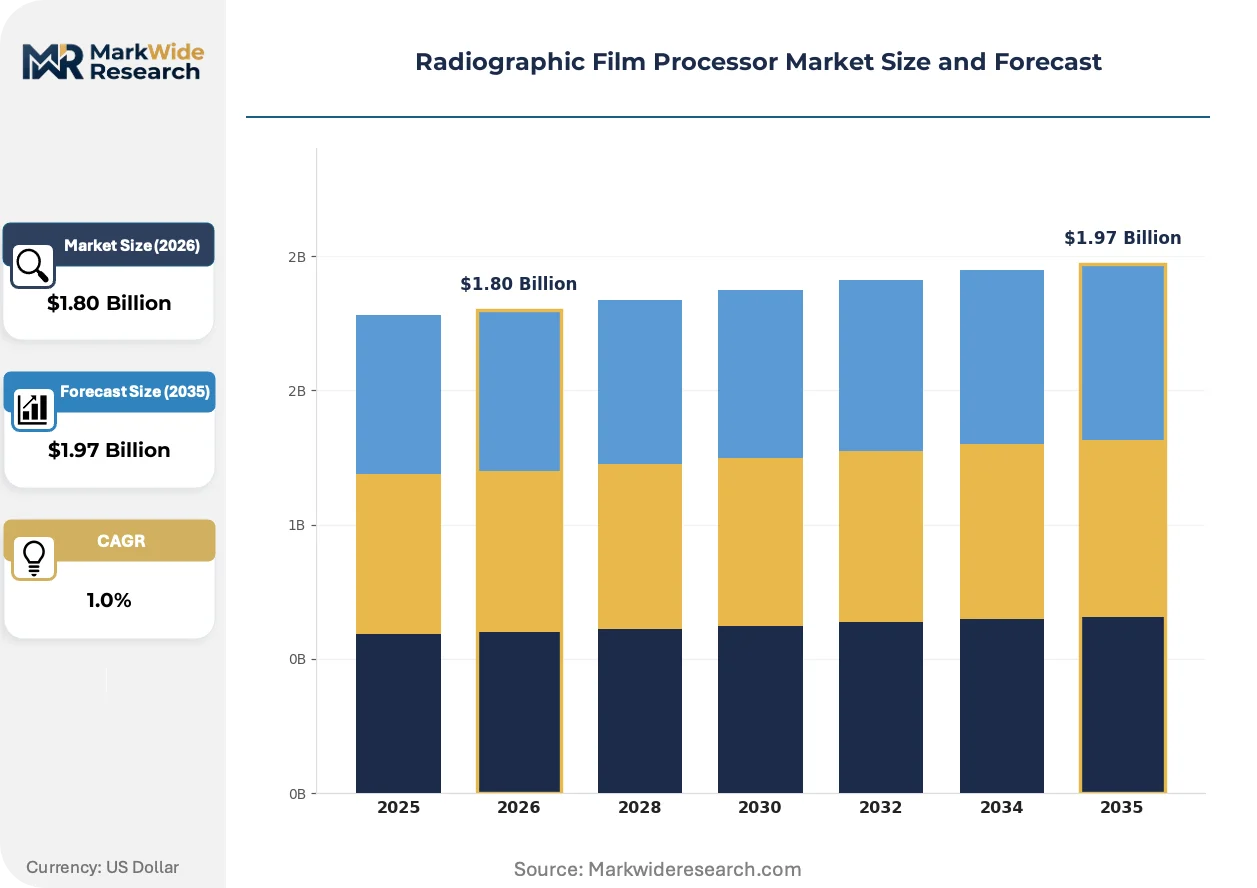
The transition from analog wet-chemistry processing to digital radiography is compressing installed-base economics while forcing incumbent manufacturers to defend recurring revenue streams from consumables and service contracts through hybrid system architectures.
Growth Catalysts
- Hybrid Processing Adoption:Dental clinics in the United States are deploying dual-capability units that process conventional film while interfacing with digital sensors, preserving capital investment during phased technology transitions.
- FDA 21 CFR Part 820:Stringent quality system validation requirements for analog-to-digital transitions are locking in established suppliers with compliant manufacturing infrastructure and documented service histories.
- Rural Hospital Infrastructure:Cost-constrained healthcare networks in the American Midwest and Mountain West maintain legacy film rooms for trauma and surgical backup where digital detector replacement capital is unavailable.
Market Restraints
- Silver Price Volatility:Fixer chemistry containing recoverable silver faces input cost swings that squeeze processor consumable margins and complicate long-term service contract pricing.
- EPA Effluent Regulation:Wet-chemistry discharge standards for developer and fixer waste are adding compliance layers that accelerate facility decisions to abandon analog processing entirely.
- Digital Detector Substitution:Flat-panel digital radiography systems are eliminating film processing steps in high-volume hospital radiology departments where throughput economics favor full digital conversion.
Strategic Opportunities
- Veterinary Practice Expansion:Small-animal and equine clinics in Texas and Florida represent underpenetrated demand for compact tabletop processors where imaging volume does not justify digital capital expenditure.
- ISO 13485 Certification Services:Manufacturers can monetize quality system expertise by offering validation consulting to clinics navigating dual analog-digital compliance during technology transitions.
- Refurbishment Channel Development:Certified pre-owned processor programs targeting budget-constrained outpatient imaging centers create aftermarket revenue without new unit production.
Industry Challenges
- Field Service Technician Scarcity:Wet-chemistry processor maintenance requires specialized knowledge of temperature control systems and chemical replenishment protocols that retiring technicians possess but new entrants lack.
- Legacy Integration Complexity:Hybrid systems must interface with existing PACS infrastructure and film digitizers, creating interoperability testing burdens that extend installation timelines and strain technical support resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiographic Film Processor Market |
| Market Size in 2026 | $1.80 Billion |
| Market Size in 2035 | $1.97 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Processors, Manual Processors, Film Developer, Cleaner Solutions End User: Hospitals, Diagnostic Centers, Research Labs, Clinics Technology: Digital Radiography, Analog Imaging, Computed Radiography, Hybrid Systems Application: Orthopedics, Cardiology, Dental Imaging, Veterinary Use |
| Companies Covered | Carestream Health, Fujifilm Holdings Corporation, Konica Minolta, Agfa-Gevaert N.V., PROTEC, AFP Manufacturing, Zimed Healthcare Ltd, Euroteck, HEXAGON INTERNATIONAL(GB) LIMITED, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiographic Film Processor Market Evolving Landscape
Digital convergence is fragmenting the traditional processor value chain, with hardware commoditization pushing competitive differentiation toward software integration, predictive maintenance capabilities, and chemistry formulation control.
Computed radiography scanning technology is digitizing analog film workflows without requiring full detector replacement. Mid-sized orthopedic practices are adopting CR plates and readers as an intermediate step, preserving existing X-ray generators while eliminating wet chemistry. This hybrid architecture is digitizing image capture while extending the economic life of capital equipment that would otherwise face premature obsolescence.
EPA silver recovery mandates are tightening effluent discharge thresholds for fixer solutions used in wet-chemistry processing. Metal recovery systems must now achieve higher extraction efficiency before waste stream disposal, adding capital cost to analog operations. Hospital networks in California and New York are responding by accelerating digital conversion timelines to bypass ongoing compliance burden.
Service contract unbundling is separating hardware maintenance from chemistry supply agreements that processors historically bundled. Independent service organizations are capturing repair work that original manufacturers once monopolized, while chemical suppliers compete directly on replenishment pricing. This disaggregation is most visible in the American Southeast, where multi-site dental groups negotiate chemistry procurement separately from equipment service.
Radiographic Film Processor Market Segmentation
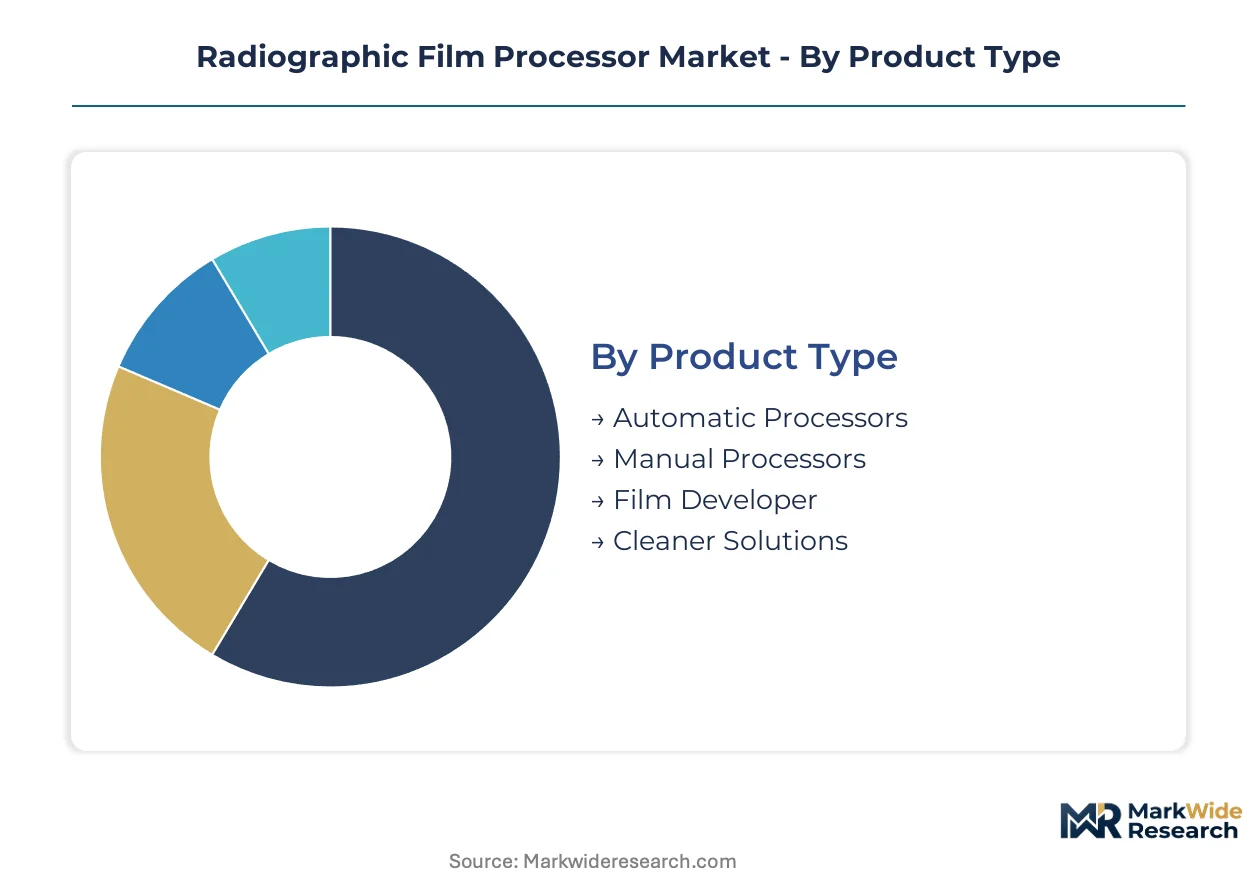
Radiographic film processor segmentation reveals how service intensity, capital constraints, and technology transition timelines fragment procurement patterns across clinical settings. Each dimension carries distinct aftermarket economics that reshape vendor go-to-market priorities.
Product Type:
After-sales-service intensity varies sharply across processor categories, with automatic units demanding continuous chemical replenishment contracts and field calibration visits that manual systems rarely require.
- Automatic Processors:These electromechanical systems integrate temperature-controlled developer tanks, fixer baths, and wash cycles with automated film transport mechanisms. Hospital radiology departments in the United States concentrate procurement here, driven by throughput requirements exceeding 200 films daily and Joint Commission pressure to standardize image quality.
- Manual Processors:Basic tank-and-dip configurations without mechanical transport rely on operator timing for development cycles. Research laboratories at universities in Massachusetts and California retain demand for these units where film volume stays below 20 exposures weekly and experimental protocols require developer formulation flexibility.
- Film Developer:Concentrated hydroquinone-based chemistry supplied in bulk replenishment tanks or ready-to-mix pouches.
- Cleaner Solutions:Proprietary formulations for removing silver buildup and chemical residues from transport rollers and tanks.
Automatic processors hold the largest share; momentum sits with hybrid-capable automatic units that bridge analog chemistry with digital output interfaces.
End User:
Capital availability and imaging volume thresholds segment end-user procurement, with hospitals amortizing equipment over decade-long depreciation schedules while clinics prioritize lease-to-own arrangements.
- Hospitals:Multi-modality imaging departments with centralized sterile processing and dedicated biomedical engineering staff. Academic medical centers in Chicago and Houston maintain legacy film rooms for trauma backup where digital detector replacement capital competes with emergency department expansion budgets.
- Diagnostic Centers:Outpatient imaging chains with high-throughput screening mandates and lean cost structures. Independent diagnostic facilities in Florida and Arizona favor refurbished automatic processors with unbundled service contracts to preserve margin on Medicare-reimbursed chest X-ray volumes.
- Research Labs:University and pharmaceutical testing facilities with non-diagnostic imaging needs.
- Clinics:Single-specialty and primary care practices with sporadic imaging demand.
Hospitals dominate installed base value; diagnostic centers are expanding most quickly through consolidation-driven equipment standardization programs.
Technology:
Technology architecture determines whether processors function as standalone endpoints or integration nodes within broader imaging ecosystems, reshaping vendor R&D allocation between hardware and software competencies.
- Digital Radiography:Flat-panel detector systems that bypass film entirely, capturing X-ray photons directly into electronic signals. Hospital networks in California and New York are accelerating displacement of wet-chemistry infrastructure here, compelled by EPA effluent regulations and radiologist preference for immediate image availability.
- Analog Imaging:Conventional silver-halide film exposed in cassette-based systems requiring full chemical processing. Rural critical access hospitals in Montana and Wyoming sustain demand for pure analog processors where USDA rural development grants prioritize facility operations over capital equipment replacement.
- Computed Radiography:Photostimulable phosphor plates scanned by laser readers to produce digital images without wet chemistry.
- Hybrid Systems:Dual-capability units processing conventional film while interfacing with digital sensors and PACS networks.
Hybrid systems hold the largest share among processor-requiring technologies; computed radiography is climbing the fastest as orthopedic practices seek intermediate digitization without generator replacement.
Application:
Clinical application dictates film size, throughput, and image quality requirements that cascade into processor specification decisions and chemistry consumption rates.
- Dental Imaging:Intraoral and panoramic film formats requiring compact tabletop processors with rapid cycle times. Private dental practices in Texas and Florida drive procurement volume here, with group practice consolidation creating multi-site service contract opportunities for regional distributors.
- Veterinary Use:Equine and small-animal imaging with cassette sizes matching human orthopedics but lower daily volume. Mixed-animal practices in Kentucky and Colorado represent underpenetrated demand where imaging revenue supplements primary care services.
- Orthopedics:Long-bone and joint imaging with high-resolution requirements for fracture line visualization.
- Cardiology:Chest and cardiac catheterization imaging with rapid turnaround needs for procedural guidance.
Dental imaging holds the largest share; veterinary use is gaining share fastest as pet insurance penetration lifts imaging utilization in companion animal practices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export automatic processors to hospital networks in the United States, sustaining transatlantic trade flows even as digital conversion accelerates in destination markets.
United States
Hospital networks in the American Midwest and Mountain West maintain legacy film infrastructure for trauma backup and surgical suites. FDA 21 CFR Part 820 quality system regulations govern analog-to-digital transition validation, favoring established suppliers with compliant manufacturing histories. Critical access hospitals in Montana and Wyoming leverage USDA rural development grants to sustain wet-chemistry operations.
Germany
Precision engineering clusters in Bavaria and Baden-Württemberg produce high-throughput automatic processors for export markets. CE marking under the EU MDR shapes domestic market access requirements, while REACH chemical regulations constrain developer and fixer formulation chemistry. Stuttgart-based engineering firms supply refurbishment services extending processor lifecycle economics.
Japan
Aging healthcare infrastructure in rural prefectures sustains demand for compact tabletop units alongside metropolitan digital conversion. PMDA medical device standards and METI industrial policy coordinate phased analog retirement timelines. Osaka-based manufacturers concentrate on hybrid system development bridging film chemistry with digital PACS integration.
China
County-level hospitals in western provinces retain analog processing capacity where digital detector capital remains constrained. NMPA medical device registration and GB standards govern domestic manufacturing quality, while MEE environmental regulations tighten silver recovery mandates for fixer effluent. Yangtze River Delta production clusters serve both domestic replacement demand and Southeast Asian export markets.
India
Tier-2 and Tier-3 city diagnostic centers balance cost constraints against incremental digital upgrade pathways. CDSCO medical device rules and BIS standards regulate imported processor quality, while state-level pollution control boards enforce effluent discharge limits on wet-chemistry operations. Maharashtra and Gujarat imaging chains drive procurement volume through consolidation-driven equipment standardization.
Radiographic Film Processor Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: diversified imaging conglomerates with backward integration into film chemistry, specialized electromechanical fabricators focused on compact tabletop units, and independent service organizations capturing aftermarket repair and chemistry supply. Competitive dynamics center on M&A activity targeting regional distribution networks and strategic partnerships bridging analog hardware with digital PACS software integration.
Within the diversified imaging tier, Carestream Health and Fujifilm Holdings Corporation exemplify conglomerate structures leveraging captive film chemistry supply and digital sensor development. Konica Minolta occupies a position among compact tabletop specialists targeting high-volume dental and veterinary practices. Agfa-Gevaert N.V. anchors the European manufacturing base with heritage chemical processing expertise.
| Leading Market Players |
|---|
| Carestream Health |
| Fujifilm Holdings Corporation |
| Konica Minolta |
| Agfa-Gevaert N.V. |
| PROTEC |
| AFP Manufacturing |
| Zimed Healthcare Ltd |
| Euroteck |
| HEXAGON INTERNATIONAL(GB) LIMITED |
| Others |
Value Network & Pricing Analysis
Overcapacity in German precision-engineering clusters is compressing margins for automatic processor exports while forcing incumbent suppliers toward hybrid system premiums and unbundled service contracts to defend profitability.
Pricing Analysis
The technology-generation pricing gap between pure analog, hybrid-capable, and full digital radiography systems spans three distinct tiers. Automatic processors with hybrid interfaces command premium positioning against legacy analog units, while manual tank systems occupy economy positioning for research and low-volume veterinary settings. Price differentiation hinges on FDA 21 CFR Part 820 certification tier and after-sales service bundling intensity. Cost compression in economy-tier manual processors is intensifying because independent service organizations capture repair work previously monopolized by original manufacturers. Diagnostic centers in Florida and Arizona exhibit highest price sensitivity through refurbished procurement and chemistry unbundling, while academic medical centers in Chicago and Houston show lowest sensitivity due to Joint Commission compliance requirements.
Supply Chain Analysis
Upstream feedstock concentration for hydroquinone developer chemistry and silver-bearing fixer solutions centers on chemical manufacturing clusters in Germany, Japan, and the United States. Processor electromechanical components draw from precision metal fabrication in Bavaria and Baden-Württemberg, while digital interface modules source from semiconductor foundries in Taiwan and South Korea. Single-source vulnerability sits with proprietary film chemistry formulations where backward integration by Fujifilm and Carestream locks out third-party substitution. Distribution runs through hospital GPO contracts, dental group purchasing networks, and independent imaging equipment distributors serving outpatient diagnostic chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital radiography disruption is compressing the analog processor installed base faster than replacement revenue from hybrid systems can offset, creating a narrow window for repositioning around service-intensive niches before full detector substitution accelerates under EPA effluent mandates.
For Market Incumbents: Insulate recurring revenue streams by deepening captive chemistry supply agreements and predictive maintenance software integration for hybrid system installed bases. Defend against independent service organization encroachment through exclusive spare parts control and field technician certification programs. Prioritize ISO 13485 validation consulting services as a margin-preserving lever during customer analog-to-digital transitions. For New Entrants and Emerging Players: Build out compact tabletop processor lines targeting veterinary practices in Texas and Florida where imaging volume thresholds do not justify digital capital expenditure. Penetrate the small-animal and equine clinic segment through lease-to-own arrangements and unbundled chemistry procurement options. Establish regional distribution partnerships with agricultural supply cooperatives serving mixed-animal practices in Kentucky and Colorado. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across refurbished processor programs and aftermarket service platforms as new unit production economics deteriorate. Five-to-ten year viability favors acquisition targets with installed-base service contracts and proprietary chemistry supply relationships rather than hardware manufacturing capacity. Monitor EPA silver recovery mandate enforcement intensity in California and New York as the signal for digital conversion acceleration timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid System Certification | FDA 21 CFR Part 820 validation locks in established suppliers with compliant manufacturing infrastructure. |
| Refurbishment Channel Development | Certified pre-owned programs capture budget-constrained diagnostic center demand without new production. |
| Chemistry Supply Integration | Backward integration into proprietary developer and fixer formulations sustains consumable recurring revenue. |
| Predictive Maintenance Software | Remote monitoring capabilities differentiate service contracts and reduce field technician dispatch costs. |
| Veterinary Distribution Partnership | Agricultural supply cooperative relationships penetrate underpenetrated small-animal and equine clinic segments. |
Research Methodology
Initial hypotheses were tested against primary input from biomedical engineering directors, hospital purchasing committee members, dental clinic operations managers, and independent service organization technicians and refined through secondary validation against FDA 510(k) filings, EPA effluent compliance databases, hospital GPO contract repositories, and medical device import-export customs records. Bottom-up triangulation across installed base estimates and top-down cross-check against manufacturer revenue disclosures anchored volume and value outputs.
Demand-supply-balance framing structured the analytical approach across the projection horizon, modeling segmentation dimensions spanning automatic-manual-hybrid product architecture, hospital-diagnostic center-clinic end-user tiers, and dental-veterinary-orthopedic application verticals. CAGRs were derived from replacement cycle analysis and technology substitution elasticity estimates, incorporating EPA regulatory timeline assumptions and silver price volatility scenarios as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified imaging conglomerates into pure digital radiography would shift outcomes through accelerated installed base attrition. Cross-checking against hospital capital expenditure survey data and dental group practice consolidation announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
X-Ray Devices Market
Medical Imaging
Argentina Mammography Market
Medical Imaging
Global Orthopedic Imaging Equipment Market
Medical Imaging
Global Medical Cameras Market
Medical Imaging
Diagnostic Imaging Market
Medical Imaging
Precision Cancer Imaging Market
Medical Imaging
Spain Digital X-Ray Market
Medical Imaging
Perfusion Radiology Market
Medical Imaging
South America Mammography Market
Medical Imaging
Africa Magnetic Resonance Imaging (MRI) Market
Medical Imaging
United Kingdom Mammography Market
Medical Imaging
3D Medical and Surgical Imaging Platform Market
Medical Imaging
Europe Mobile Tomography Market
Medical Imaging
Carotid Ultrasound Imaging Market
Medical Imaging
Global Electroretinography Market
Medical Imaging
Coronary Heart Disease Diagnostic Imaging Market