
 Germany Digital Radiology Market | 2026-2036
Germany Digital Radiology Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Digital Radiology Market Insights
A shortage of radiology technologists trained in computational imaging protocols is redrawing competitive dynamics across Germany. Siemens Healthineers leverages its Erlangen manufacturing base to anchor domestic supply chains for high-field MRI systems. Philips sustains R&D intensity in AI-powered diagnostic software through its Hamburg operations. GE Healthcare competes on service density, maintaining field engineering teams that cover university hospitals in North Rhine-Westphalia and Baden-Württemberg.
Digital radiology encompasses the acquisition, processing, storage, and transmission of diagnostic images using electronic detectors and PACS infrastructure, with modern systems achieving spatial resolution below 150 micrometers and dose reduction of 40-60% versus analog film. CT scanners lead product type revenue due to replacement cycles in Germany's aging installed base of Somatom and Brilliance platforms. Artificial Intelligence within the technology dimension captures the fastest expansion as algorithms gain CE marking under MDR for lesion detection and workflow triage. Hospitals dominate end user demand, though outpatient facilities represent a margin pool where teleradiology networks reduce per-study overhead.
MDR conformity requirements enforced by BfArM and notified bodies extend approval timelines and elevate clinical evidence burdens for new digital radiology platforms. The German Digital Healthcare Act (DVG) creates reimbursement pathways for AI-assisted diagnosis, directly shaping software vendor go-to-market priorities. KBA safety standards for mobile C-arm systems and DIN technical specifications for image quality assurance further segment product development roadmaps. Stakeholders must monitor how BfArM guidance on software as a medical device evolves alongside EU AI Act risk classification for autonomous diagnostic algorithms.
Market Dynamics
The Medical Device Regulation (MDR) is compressing product launch timelines while simultaneously elevating clinical evidence requirements for AI-enabled imaging platforms across German hospital networks.
Growth Catalysts
- MDR Conformity Pathways:The German Digital Healthcare Act (DVG) establishes reimbursement codes for AI-assisted diagnostic workflows, accelerating hospital procurement decisions for CE-marked algorithms.
- Bavaria Medical Technology Corridor:Munich-Stuttgart clusters concentrate university hospital demand, creating dense reference sites that validate new imaging platforms for national rollout.
- Detector Technology Maturation:Solid-state photon-counting CT detectors achieve sub-150-micrometer spatial resolution while reducing radiation exposure by 40-60% versus legacy analog systems.
Market Restraints
- Notified Body Bottlenecks:BfArM oversight capacity constraints extend MDR approval timelines by 12-18 months for software-as-medical-device classifications.
- Rare Earth Magnet Supply:High-field MRI superconducting magnets depend on niobium-titanium supply chains concentrated in Chinese processing facilities.
- Technician Labor Scarcity:German radiology technologist training programs graduate insufficient candidates proficient in computational imaging protocols and PACS administration.
Strategic Opportunities
- Outpatient Teleradiology Networks:Ambulatory imaging centers in North Rhine-Westphalia seek remote diagnostic partnerships to reduce per-study overhead without capital-intensive equipment purchases.
- EU AI Act Risk Classification:Autonomous lesion detection algorithms face elevated compliance scrutiny, creating first-mover advantages for vendors with established BfArM rapport.
- Mobile C-Arm Integration:KBA safety standards for surgical imaging systems open retrofit markets for hybrid OR installations in aging hospital infrastructure.
Industry Challenges
- Legacy PACS Interoperability:Hospital IT departments struggle to integrate AI diagnostic layers with decade-old vendor-neutral archive architectures from multiple incumbent suppliers.
- Computational Imaging Skill Gaps:Radiology departments lack sufficient staff trained in algorithm validation, bias detection, and explainable AI documentation for clinical governance committees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Digital Radiology Market |
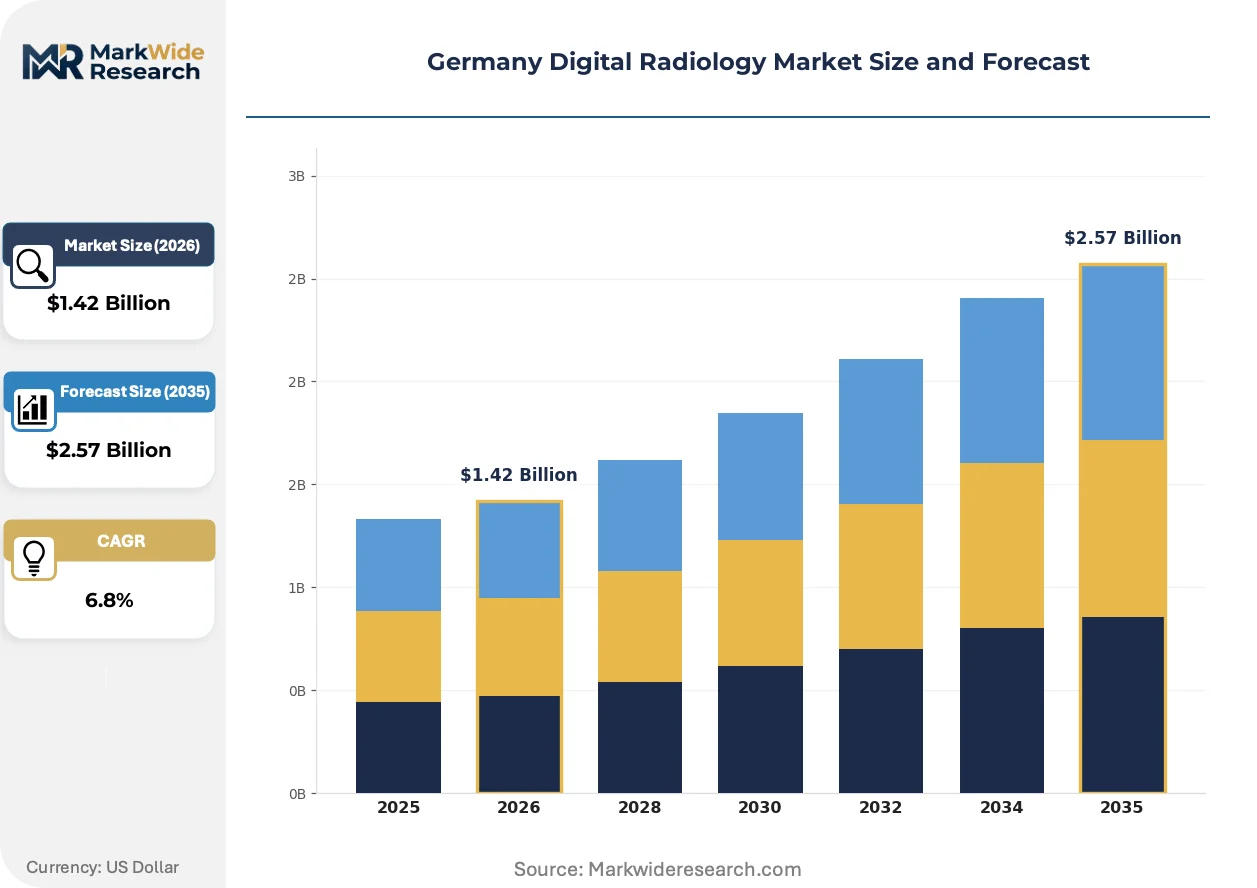
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
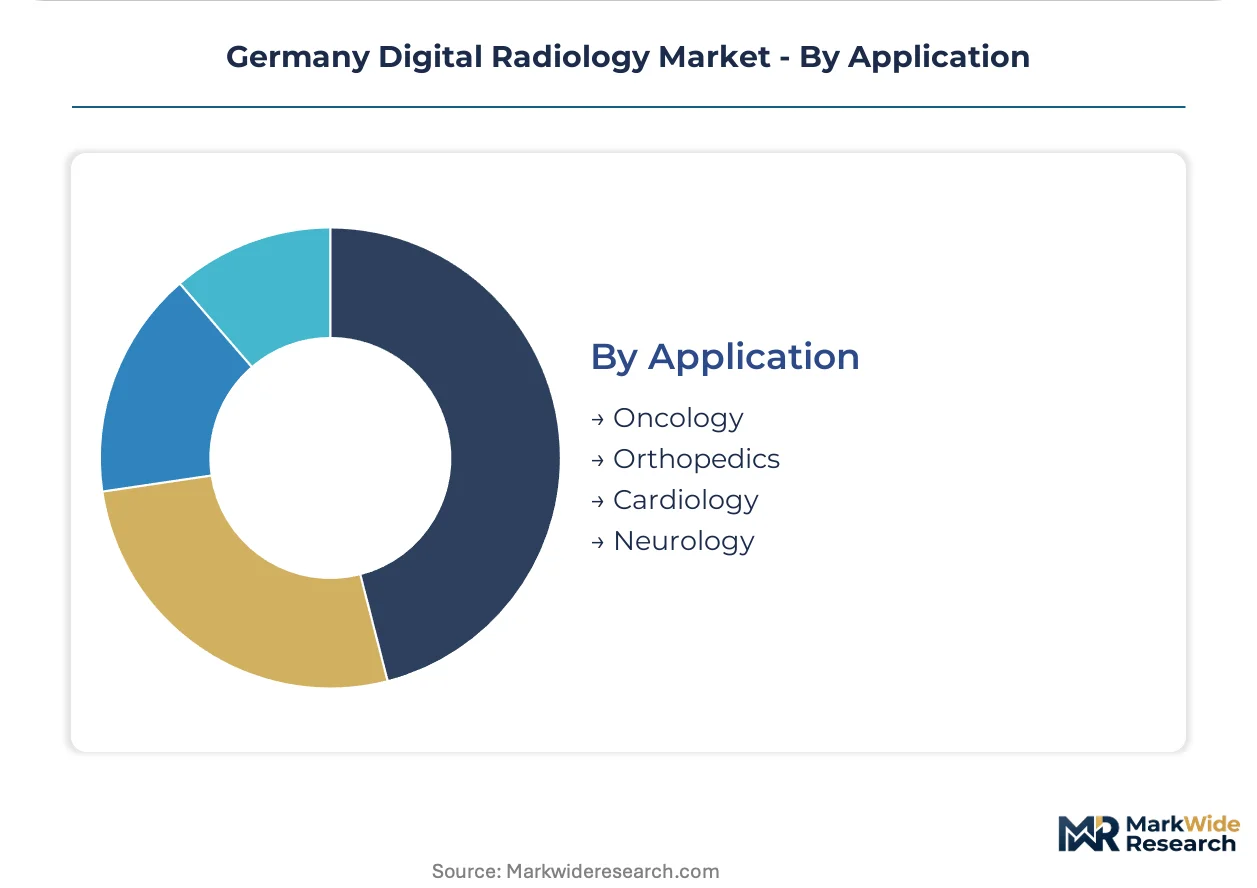
| Segmentation | Product Type: X-ray Systems, CT Scanners, MRI Machines, Ultrasound Devices Technology: Computational Imaging, Artificial Intelligence, Cloud Computing, DICOM End User: Hospitals, Diagnostic Centers, Research Institutions, Outpatient Facilities Application: Oncology, Orthopedics, Cardiology, Neurology |
| Companies Covered | FUJIFILM, Carestream Health, Siemens Healthineers, Shimadzu Corporation, Agfa Healthcare, GE Healthcare, Canon, Hologic, Koninklijke Philips, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Digital Radiology Market Trends and Innovations
Artificial intelligence deployment is fragmenting across distinct use cases rather than consolidating into general-purpose platforms, with workflow triage and lesion detection diverging into separate vendor specializations.
Photon-counting CT detector technology is bifurcating the installed base upgrade cycle. Siemens Healthineers accelerates field replacement of energy-integrating detectors in German university hospitals. Cardiac and pediatric imaging segments capture disproportionate benefit from spectral resolution improvements, compressing competitive differentiation around dose optimization metrics.
The EU AI Act's risk-based classification framework is reshaping software development roadmaps for autonomous diagnostic algorithms. German notified bodies now require algorithmic bias audits and post-market performance monitoring for high-risk applications. Radiology AI vendors are restructuring quality management systems to satisfy both MDR technical documentation and AI Act conformity assessment.
Hospital procurement committees are unbundling equipment acquisition from service contracts and AI software subscriptions. Large academic medical centers in Baden-Württemberg negotiate direct algorithm licensing with startup developers, bypassing traditional OEM distribution channels. This disintermediation concentrates in regions with established digital health innovation hubs and receptive IT governance structures.
Germany Digital Radiology Market Segmentation
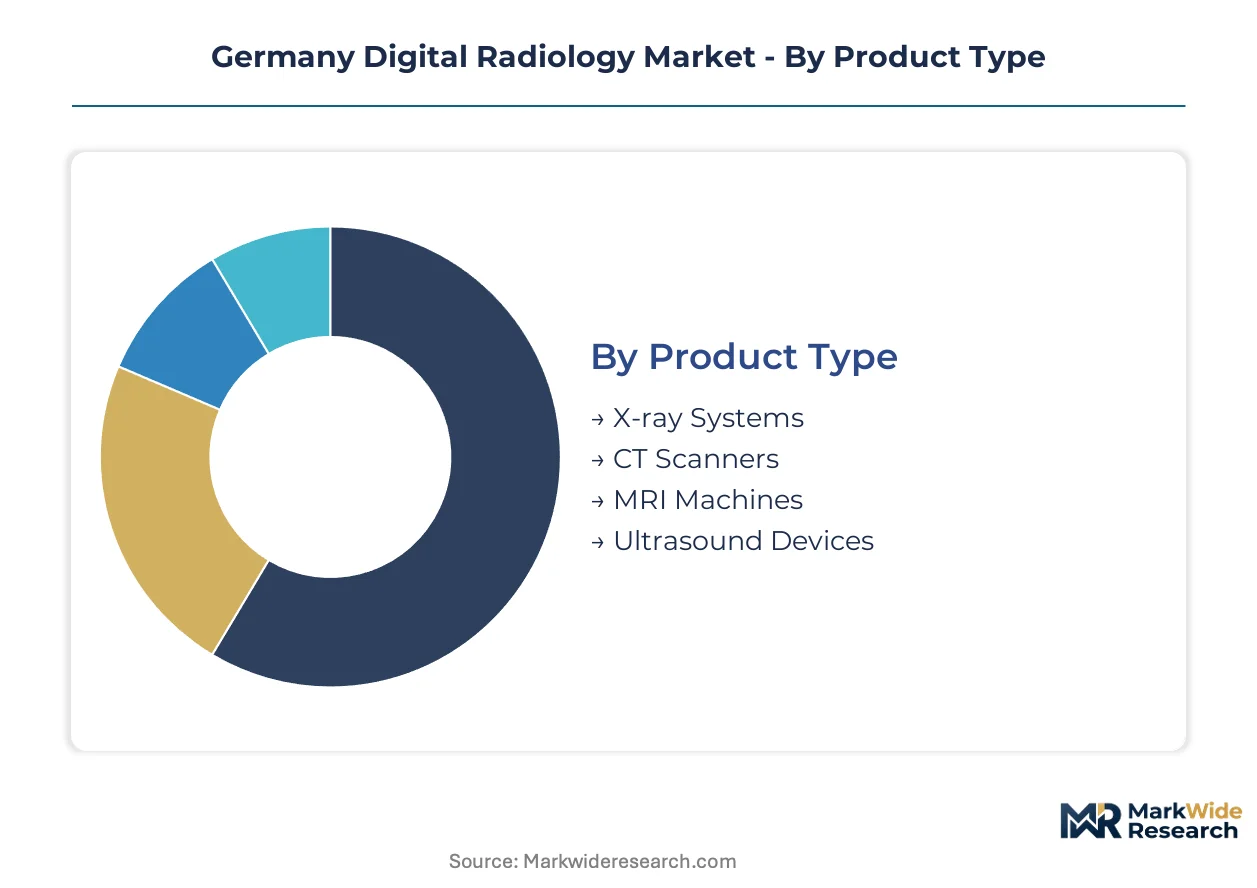
Segmentation in Germany's digital radiology market reveals how procurement priorities diverge across clinical settings and technological maturity levels. Understanding these divides exposes where capital concentrates versus where margin pools form in outpatient and research environments.
Product Type:
Domestic demand for replacement cycles dominates CT and MRI procurement, while X-ray and ultrasound platforms retain stronger export orientation toward Central European hospital networks.
- CT Scanners:Energy-integrating and photon-counting detector platforms achieve sub-150-micrometer spatial resolution with 40-60% dose reduction versus analog film. German university hospitals in Bavaria's Munich-Stuttgart corridor accelerate replacement of aging Somatom and Brilliance installed bases to capture spectral resolution improvements for cardiac and pediatric protocols.
- MRI Machines:High-field superconducting systems with niobium-titanium magnets enable advanced neurovascular and musculoskeletal imaging. Siemens Healthineers anchors domestic supply chains through its Erlangen manufacturing base, though magnet processing dependencies in Chinese facilities create supply vulnerability.
- X-ray Systems:Digital radiography and fluoroscopy platforms with flat-panel detectors serve general radiology and surgical guidance.
- Ultrasound Devices:Portable and cart-based systems with DICOM connectivity support point-of-care and obstetric applications.
CT Scanners holds the largest share; momentum sits with MRI Machines as high-field platforms penetrate orthopedic and cardiac segments.
Technology:
Cost tiers separate validated clinical algorithms from experimental cloud deployments, with reimbursement pathways under DVG concentrating investment in CE-marked AI workflows.
- Artificial Intelligence:Lesion detection and workflow triage algorithms gain BfArM conformity assessment under MDR and EU AI Act risk classification. The German Digital Healthcare Act creates direct reimbursement codes for AI-assisted diagnosis, accelerating hospital procurement of validated platforms while post-market performance monitoring requirements elevate vendor quality management burdens.
- Computational Imaging:Iterative reconstruction and spectral processing protocols reduce acquisition times and radiation exposure. Bavarian university hospitals deploy these techniques for quantitative imaging biomarkers in oncology trials, creating reference site density that validates platforms for national rollout.
- Cloud Computing:Teleradiology networks and vendor-neutral archive extensions enable remote diagnostic partnerships.
- DICOM:Interoperability standards govern image exchange between PACS, RIS, and EMR systems in multi-vendor environments.
Artificial Intelligence commands the premium tier; Computational Imaging expands most quickly as reconstruction protocols mature for clinical validation.
End User:
Customer type determines capital intensity versus operational expenditure models, with academic medical centers disintermediating OEM channels for direct algorithm licensing.
- Hospitals:University and community hospitals concentrate demand for integrated imaging platforms with AI diagnostic layers. Procurement committees in Baden-Württemberg unbundle equipment acquisition from service contracts, negotiating direct software subscriptions that bypass traditional distribution channels.
- Diagnostic Centers:Ambulatory imaging facilities in North Rhine-Westphalia seek teleradiology partnerships to reduce per-study overhead without capital-intensive equipment purchases, creating margin pools for remote diagnostic networks.
- Research Institutions:Academic consortia require imaging platforms with open APIs for algorithm development and clinical trial integration.
- Outpatient Facilities:Physician offices and specialized clinics prioritize compact systems with simplified workflow automation.
Hospitals dominate volume; Diagnostic Centers represent the steepest expansion trajectory as teleradiology networks proliferate.
Application:
Clinical use case maturity varies by reimbursement density and AI validation completeness, with oncology and cardiology leading algorithmic deployment.
- Oncology:Tumor detection, staging, and treatment response monitoring drive demand for quantitative imaging biomarkers. Photon-counting CT spectral resolution enables tissue characterization that supports precision oncology protocols in German comprehensive cancer centers.
- Cardiology:Coronary CT angiography and cardiac MRI stress testing require sub-millimeter spatial resolution and motion correction algorithms. Dose optimization metrics compress competitive differentiation as pediatric and repeat-examination protocols demand strict ALARA compliance.
- Orthopedics:Musculoskeletal MRI and weight-bearing CT support surgical planning and implant assessment.
- Neurology:Advanced neuroimaging protocols for stroke, dementia, and functional mapping utilize high-field MRI platforms.
Oncology holds the largest share; Cardiology gains share fastest as spectral CT resolution enables non-invasive coronary assessment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BfArM oversight of MDR conformity assessments anchors procurement dynamics across German hospital networks, with regional variation in installed base age and AI adoption intensity creating divergent upgrade cycles.
Bavaria
University hospitals in Munich and Erlangen drive photon-counting CT replacement demand through cardiac and pediatric imaging protocols. The German Digital Healthcare Act reimburses AI-assisted diagnosis, accelerating algorithm procurement in comprehensive cancer centers. Siemens Healthineers maintains manufacturing and R&D concentration in Erlangen, anchoring domestic supply chains for high-field MRI platforms.
North Rhine-Westphalia
Community hospitals and ambulatory imaging centers seek teleradiology partnerships to reduce per-study overhead without capital-intensive equipment purchases. KBA safety standards for mobile C-arm systems shape hybrid OR retrofit markets in aging hospital infrastructure. Cologne and Düsseldorf medical technology clusters concentrate field engineering service density for multi-vendor PACS environments.
Baden-Württemberg
Academic medical centers in Stuttgart and Heidelberg unbundle equipment acquisition from service contracts, negotiating direct AI software subscriptions that bypass traditional OEM distribution channels. DIN technical specifications for image quality assurance segment product development roadmaps for quantitative imaging biomarkers. The Stuttgart-Tübingen innovation corridor validates new platforms for national rollout through dense reference site networks.
Hamburg
Philips sustains R&D intensity in AI-powered diagnostic software through its Hamburg operations, leveraging port city logistics for Central European distribution. Outpatient facilities prioritize compact systems with simplified workflow automation for point-of-care applications. The city's digital health startup ecosystem enables direct algorithm licensing relationships between developers and procurement committees.
Lower Saxony
Regional hospital networks face legacy PACS interoperability challenges when integrating AI diagnostic layers with decade-old vendor-neutral archive architectures. Technician training programs at Hannover Medical School address computational imaging skill gaps in algorithm validation and explainable AI documentation. Wolfsburg and Braunschweig industrial zones supply precision manufacturing components for detector assemblies.
Germany Digital Radiology Market Competitive Landscape
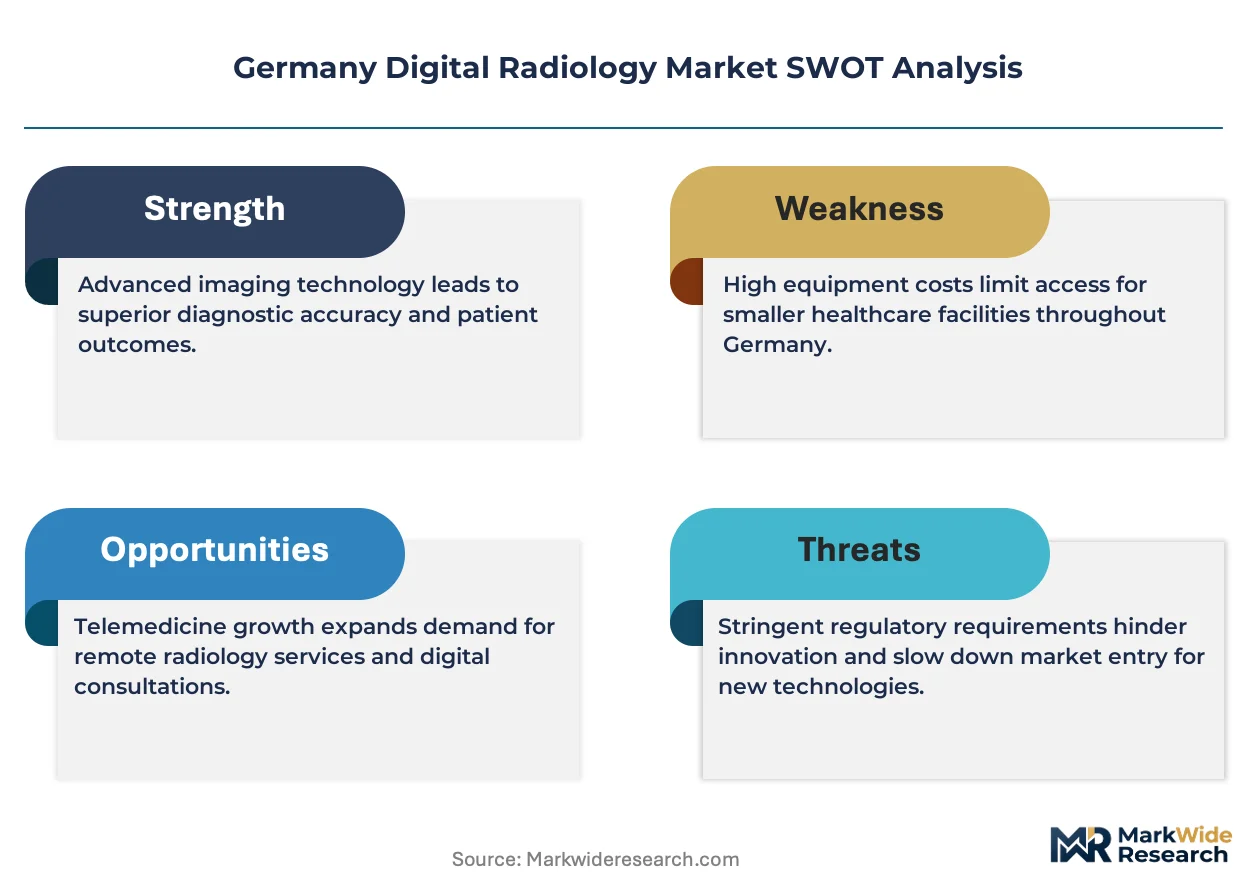
Technology leadership and cost leadership are held by different player archetypes across the German digital radiology market. Consolidation around integrated imaging platforms with AI diagnostic layers has created a tiered structure where full-system OEMs, specialized software developers, and regional service providers occupy distinct competitive positions. Strategic moves concentrate on direct algorithm licensing partnerships and unbundled service contract negotiations that bypass traditional distribution channels.
Within the integrated-system tier, Siemens Healthineers and Koninklijke Philips exemplify archetypes combining hardware manufacturing with AI software development, while GE Healthcare occupies a position emphasizing service density and field engineering coverage. These three anchors represent contrasting approaches to MDR conformity burden management and BfArM rapport cultivation.
| Leading Market Players |
|---|
| FUJIFILM |
| Carestream Health |
| Siemens Healthineers |
| Shimadzu Corporation |
| Agfa Healthcare |
| GE Healthcare |
| Canon |
| Hologic |
| Koninklijke Philips |
| Others |
Pricing and Supply Chain Analysis
MDR conformity assessment pathways gate both supplier qualification and price differentiation simultaneously in Germany's digital radiology sector, compressing margins for vendors lacking BfArM rapport while enabling premium positioning for CE-marked AI algorithms with established clinical evidence packages.
Pricing Analysis
Bavarian university hospitals pay 15-25% premiums over North Rhine-Westphalia community hospitals for equivalent CT platforms due to bundled AI software subscriptions and dedicated field engineering coverage. Pricing stratifies across premium, standard, and economy tiers based on detector generation and algorithm validation completeness. Cost compression in the standard tier intensifies as Chinese component suppliers enter flat-panel detector assembly. Outpatient diagnostic centers exhibit highest price sensitivity, deferring upgrades until DVG reimbursement codes mature.
Supply Chain Analysis
Niobium-titanium superconducting wire processing in Chinese facilities creates single-source vulnerability for high-field MRI magnet production, forcing German OEMs to maintain 6-9 month strategic inventories. Detector assemblies draw from Japanese sensor substrates, German precision machining, and Taiwanese semiconductor packaging. Distribution runs through Erlangen and Hamburg logistics hubs serving Central European hospital networks directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where MDR regulatory entrenchment and hospital switching costs protect incumbent positions against software-only challengers lacking hardware-service integration.
For Market Incumbents: Secure BfArM rapport through early engagement on software-as-medical-device classifications before EU AI Act risk tiers finalize. Deepen backward integration into photon-counting detector crystal growth to offset rare earth processing concentration in Chinese facilities. Defend against teleradiology networks disintermediating equipment sales by embedding AI diagnostics into long-term service contracts with penalty clauses for early termination.
For New Entrants and Emerging Players: Anchor in North Rhine-Westphalia outpatient diagnostic centers where capital constraints prevent direct equipment purchases and teleradiology partnerships offer lowest-friction market entry. Target algorithm licensing direct to Baden-Württemberg academic medical centers with unbundled procurement committees bypassing traditional OEM channels. Lead with workflow triage applications requiring lighter clinical evidence burdens than autonomous lesion detection.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed teleradiology networks possessing dense radiologist panels but lacking AI diagnostic layers. Five-to-ten year viability hinges on DVG reimbursement expansion beyond pilot codes to routine AI-assisted diagnosis. Monitor BfArM guidance on post-market performance monitoring as inflection indicator for quality management system investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Conformity Pathway Acceleration | Early BfArM engagement compresses approval timelines by 8-12 months for AI algorithms seeking CE marking. |
| Photon-Counting Detector Backward Integration | In-house cadmium-zinc-telluride crystal growth reduces dependency on Japanese sensor substrate suppliers. |
| Teleradiology Network Partnership | Remote diagnostic alliances with North Rhine-Westphalia outpatient centers capture margin pools without capital equipment exposure. |
| Direct Algorithm Licensing Model | Unbundled software subscriptions bypass OEM distribution channels in Baden-Württemberg academic medical centers. |
| Computational Imaging Training Program | Hannover Medical School partnerships address technician scarcity in PACS administration and algorithm validation protocols. |
Research Methodology
Operator-level perspectives from hospital procurement committee chairs, biomedical engineering directors, radiology department heads, and GPO contracts managers anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation against BfArM device registrations, hospital procurement databases, and DIN technical specification releases. Bottom-up installed base modeling and top-down reimbursement flow analysis provided triangulation across independent estimation approaches.
Sensitivity analysis tested forecast robustness across MDR approval timeline scenarios and DVG reimbursement expansion assumptions over the projection horizon. Segmentation dimensions modeled include product type, technology maturity tier, end-user capital intensity, and clinical application reimbursement density. CAGRs derived from replacement cycle analysis of aging Somatom and Brilliance platforms cross-referenced with AI algorithm adoption curves in Bavarian reference sites.
Decision-makers should treat outputs as directional under base assumptions of stable BfArM oversight capacity and continued DVG reimbursement pathway expansion; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as EU AI Act risk classification implementation timelines and rare earth magnet supply chain configurations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Imaging Agents Market
Medical Imaging
US Magnetic Resonance Angiography Market
Medical Imaging
Mobile Gamma Cameras Market
Medical Imaging
Healthcare Cloud Picture Archiving and Communications System Market
Medical Imaging
Middle East and Africa Clinical Trial Imaging Market
Medical Imaging
North America Open System MRI Market
Medical Imaging
Hand-Held X-Rays Market
Medical Imaging
Argentina Diagnostic Imaging Equipment Market
Medical Imaging
US Imaging Services Market
Medical Imaging
Europe Open System MRI Market
Medical Imaging
Wireless Intraoral Camera Market
Medical Imaging
Mobile Tomography Market
Medical Imaging
Global Nuclear Imaging Equipment Market
Medical Imaging
Vascular Imaging Systems Market
Medical Imaging
Global Confocal Microscope Market
Medical Imaging
Cardiology PACS Market