
 Ammunition Handling Systems Market | 2026-2036
Ammunition Handling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Ammunition Handling Systems Market Analysis
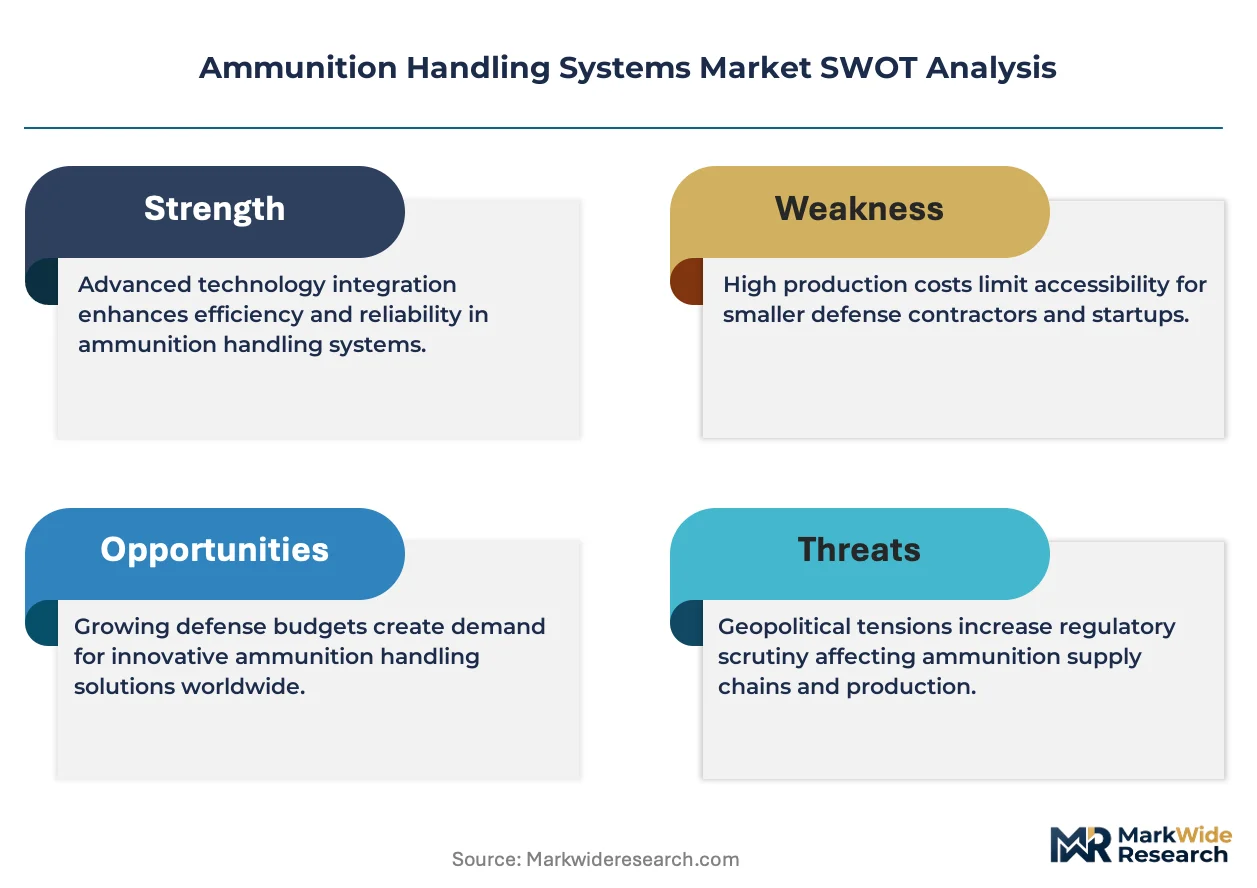
Polymer composite feed chutes is consolidating around legacy aluminum linkless ammunition tracks in medium-caliber naval and ground turrets, cutting weight by roughly one-third while maintaining cyclic-rate tolerance above 650 rounds per minute. General Dynamics Corporation leverages captive metallurgy and composite molding capabilities across its Ordnance and Tactical Systems division to anchor naval gun supply chains. BAE Systems sustains transatlantic production footprints for chain gun ammunition handling across both US and UK land and maritime programs. Curtiss-Wright Corporation differentiates through embedded diagnostics in electromechanical feeder drives, extending predictive maintenance intervals for remote operational theaters.
Ammunition handling systems comprise mechanical, electromechanical, and hydraulic subassemblies engineered to store, transport, index, and feed munitions into weapon platforms at specified cyclic rates, operating across temperature extremes from minus 51 to plus 71 degrees Celsius per MIL-STD-810. Automated Systems occupy the dominant revenue position due to integration demands in remote weapon stations and self-propelled howitzer autoloaders, where manual intervention compromises crew survivability. Electric technology segments are gaining fastest within naval close-in weapon systems, displacing legacy hydraulic drive trains that demand flammable fluid reservoirs and intensive shipboard maintenance protocols. Manual Systems retain niche relevance in training environments and certain law enforcement applications where cost constraints override throughput requirements, though margin pools remain thin relative to militarized automated configurations.
US Army Armament Research, Development and Engineering Center (ARDEC) test protocols, NATO STANAG 4385 ammunition interface standards, and the US Department of Defense MIL-STD-461 electromagnetic compatibility requirements collectively shape product qualification timelines and platform integration costs for suppliers seeking program access. The EU Green Deal's fluorinated gas restrictions are beginning to constrain pneumatic system refrigerants and propellant gas choices in European-sourced handling mechanisms, forcing redesigns of certain actuation circuits. Stakeholders must monitor evolving MOSA mandate enforcement thresholds and determine whether to absorb certification costs for modular interoperability or specialize in proprietary platform captive supply arrangements that risk exclusion from future competitive awards.
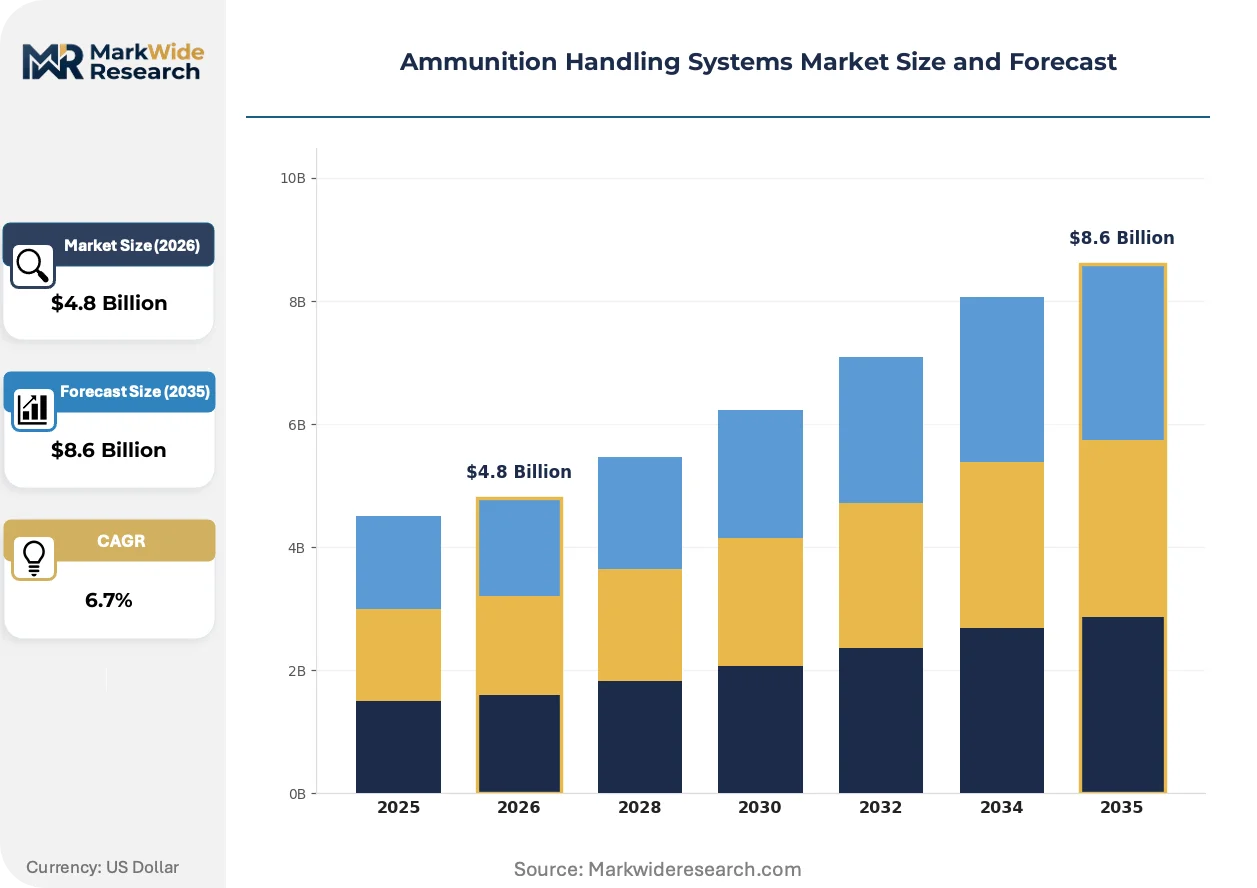
Market Dynamics
Modular open systems architecture mandates from the US Department of Defense are forcing ammunition handling suppliers to abandon proprietary interfaces in favor of interoperable electromechanical subassemblies that integrate across multiple armored vehicle platforms.
Growth Catalysts
- STANAG 4385 standardization:NATO ammunition interface protocols are accelerating cross-border procurement of linkless feed systems for coalition armored vehicle fleets, reducing platform-specific engineering costs.
- Naval gun modernization:US Navy DDG(X) and Constellation-class frigate programs are driving demand for automated naval ammunition handling with cyclic rates exceeding 650 rounds per minute in close-in weapon systems.
- Titanium aluminide alloys:Next-generation metallurgy is enabling lighter rotating feed mechanisms that withstand sustained thermal stress in self-propelled howitzer autoloaders.
Market Restraints
- Aluminum-lithium billet scarcity:Aerospace-grade alloy supply concentration in Russian and Chinese smelters creates input cost volatility for lightweight ammunition track manufacturers.
- EU F-Gas Regulation constraints:Fluorinated gas restrictions are forcing redesign of pneumatic actuation circuits in European-sourced handling systems, extending qualification timelines by 18-24 months.
- Hydraulic legacy lock-in:Existing naval close-in weapon systems with flammable fluid reservoirs impose technical limitations on electrification retrofits due to shipboard space and power constraints.
Strategic Opportunities
- Poland and Baltic states:NATO eastern flank armored vehicle procurement is creating white space for automated ammunition handling integration in K2 Black Panther and future indigenous platforms.
- Remote weapon station convergence:Unmanned turret architectures are converging sensor fusion with ammunition handling diagnostics, enabling predictive maintenance contracts as a revenue stream.
- Australian LAND 400 Phase 3:Boxer CRV and future infantry fighting vehicle programs represent underpenetrated demand for medium-caliber automated feed mechanisms in Asia-Pacific.
Industry Challenges
- MIL-STD-461 certification timelines:Electromagnetic compatibility testing for electromechanical feeder drives creates program entry barriers, with qualification cycles extending platform integration schedules.
- Legacy M113 hydraulic system integration:Cold War-era armored personnel carrier fleets require ammunition handling retrofits compatible with existing hydraulic infrastructure, complicating automation upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ammunition Handling Systems Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Systems, Manual Systems, Semi-Automated Systems, Mobile Systems Application: Combat Operations, Storage Facilities, Training Environments, Manufacturing End User: Military, Law Enforcement, Private Security, Civilian Technology: Hydraulic, Pneumatic, Electric, Mechanical |
| Companies Covered | General Dynamics Corporation, BAE Systems, Curtiss-Wright Corporation, Meggitt Defense Systems, Moog Inc., Dillon Aero, Nobles Worldwide, McNally Industries, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ammunition Handling Systems Market Emerging Trajectories
Digital thread integration across ammunition handling subassemblies is compressing development cycles while enabling real-time performance telemetry from operational theaters back to engineering teams.
Polymer composite feed chutes are unifying structural and thermal performance requirements previously served by separate aluminum and steel components. US Army next-generation combat vehicle programs are adopting these linkless tracks for medium-caliber turrets. This materials convergence is unifying supplier qualification pathways across naval and ground platforms that previously demanded distinct metallurgical certifications.
EU Green Deal fluorinated gas restrictions are forcing ammunition handling manufacturers to eliminate pneumatic refrigerants and propellant gases from European-sourced actuation circuits. Industrial consequence includes accelerated investment in all-electric feeder drive architectures. Naval close-in weapon systems in European shipyards are responding with shipboard power distribution upgrades to support higher electromechanical loads.
Platform-as-a-service procurement models are displacing traditional hardware-plus-spares contracting in NATO armored vehicle programs. Defense ministries are unbundling ammunition handling system ownership from vehicle acquisition, shifting toward performance-based logistics contracts. This behavioral shift is most visible in British Army Boxer and Ajax program structures, where availability guarantees now dominate supplier selection criteria over unit acquisition cost.
Ammunition Handling Systems Market Segmentation
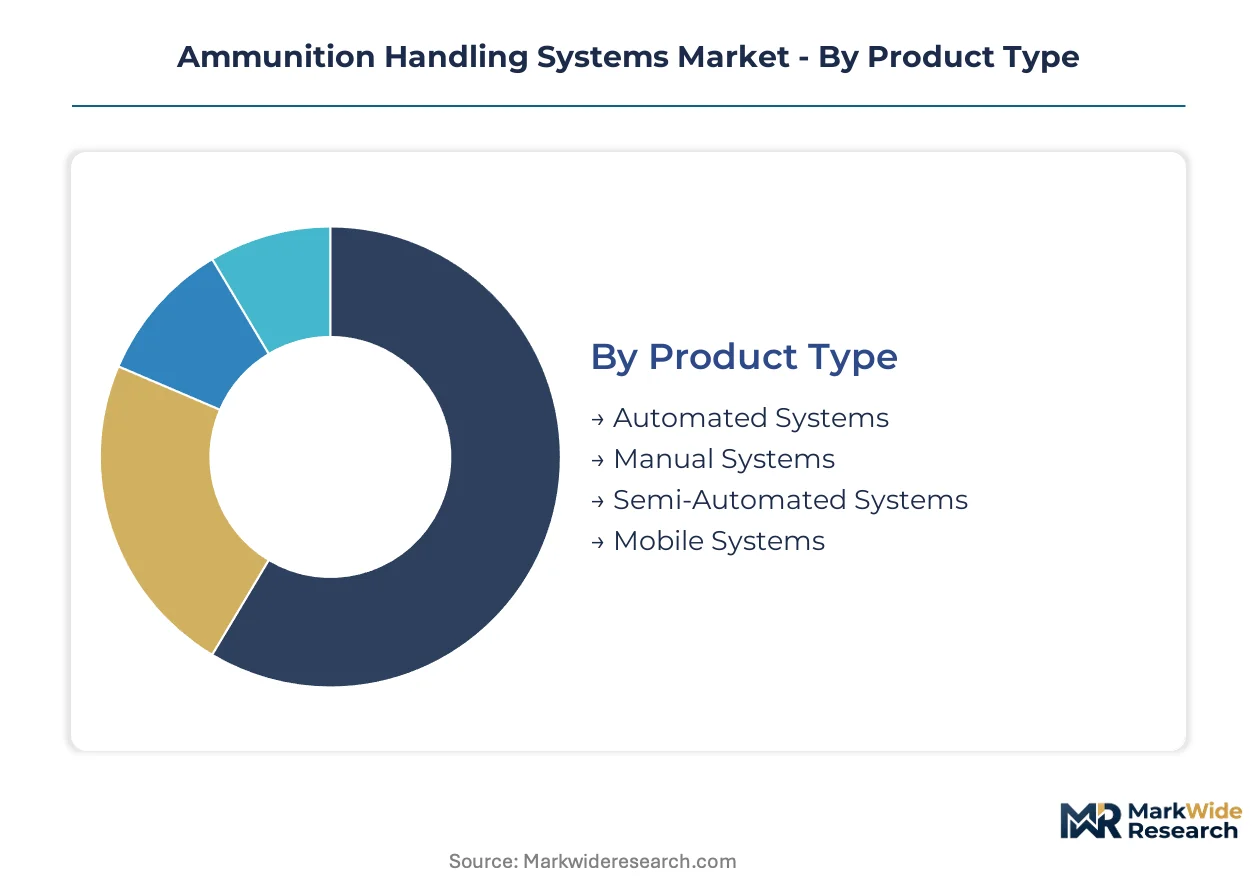
Ammunition handling systems fragment across mechanical complexity tiers, each carrying distinct qualification burdens and platform integration timelines. Procurement patterns diverge sharply between NATO armored vehicle programs demanding MOSA-compliant electromechanical architectures and legacy fleet retrofits constrained by existing hydraulic infrastructure.
Product Type:
Standardization pressures from US Department of Defense modular mandates compress customization margins at the high-complexity end, while cost floors protect simpler configurations from commoditization.
- Automated Systems:Electromechanical and hydraulic subassemblies engineered for remote weapon stations and self-propelled howitzer autoloaders, eliminating crew exposure during sustained fire missions. NATO eastern flank armored vehicle procurement in Poland and the Baltic states concentrates procurement for K2 Black Panther integration.
- Manual Systems:Hand-operated feed mechanisms retaining relevance in training environments and law enforcement applications where throughput requirements remain modest. Margin pools remain thin relative to militarized automated configurations due to limited technical differentiation.
- Semi-Automated Systems:Hybrid architectures blending operator oversight with mechanized ammunition transport, common in legacy platform upgrades.
- Mobile Systems:Self-contained units designed for expeditionary deployment across dispersed operational theaters.
Leading the category by volume: Automated Systems. Expanding most quickly: Automated Systems in naval close-in weapon systems.
Application:
Operational tempo and crew survivability requirements create tiered demand patterns across mission profiles.
- Combat Operations:High-cyclic-rate configurations for active engagement scenarios, prioritizing reliability under thermal stress and electromagnetic interference per MIL-STD-461.
- Storage Facilities:Automated inventory management and climate-controlled ammunition preservation systems.
- Training Environments:Cost-optimized manual and semi-automated systems where live-fire frequency remains controlled.
- Manufacturing:Production-line ammunition handling for assembly and quality assurance processes.
Combat Operations commands the largest procurement budgets. Storage Facilities automation is climbing the fastest as depots modernize.
End User:
Budget cycles and threat perception separate institutional buyers from commercial actors.
- Military:Dominant revenue concentration across Army modernization programs, naval gun system upgrades, and next-generation combat vehicle development. US Department of Defense MOSA mandates reshape supplier qualification pathways.
- Law Enforcement:Specialized tactical units procure compact automated systems for armored response vehicles.
- Private Security:Limited penetration constrained by export control regulations and cost thresholds.
- Civilian:Niche applications in competitive shooting sports and collector markets.
Military end users anchor procurement volume. Law Enforcement represents the steepest expansion trajectory among non-military segments.
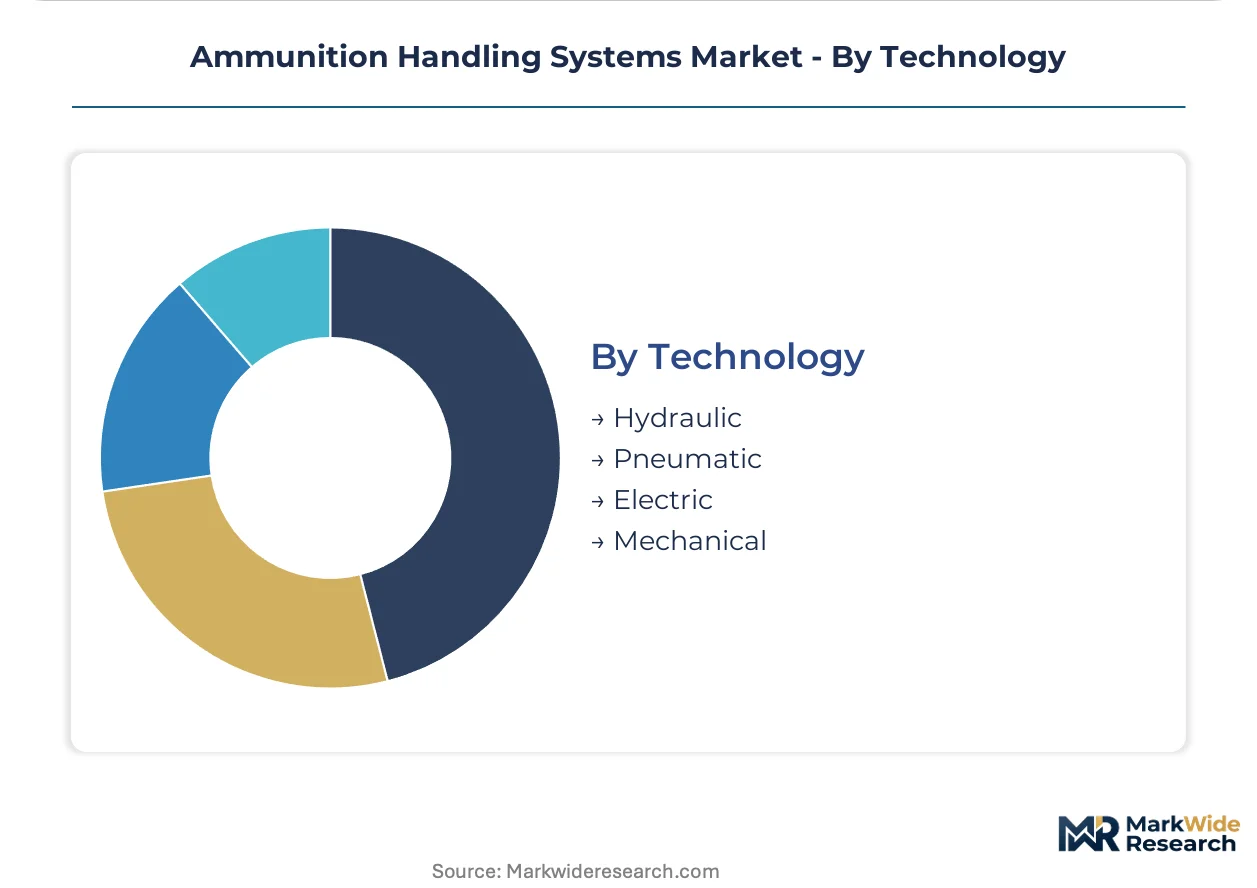
Technology:
Energy density and maintenance burden drive platform-level technology selection.
- Electric:Electromechanical feeder drives with embedded diagnostics extending predictive maintenance intervals, gaining fastest within naval close-in weapon systems as shipyards upgrade power distribution infrastructure.
- Hydraulic:Legacy drive trains with flammable fluid reservoirs imposing technical limitations on electrification retrofits due to shipboard space constraints.
- Pneumatic:Actuation circuits facing redesign pressure from EU F-Gas Regulation restrictions on fluorinated refrigerants and propellant gases.
- Mechanical:Link-based and linkless feed tracks in aluminum, steel, and emerging polymer composites.
Electric technology leads new platform integration. Hydraulic retains installed base dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement for ammunition handling systems concentrates in NATO-aligned defense budgets, with modernization programs across ground and naval platforms driving regional demand patterns. National qualification protocols and platform-specific integration requirements fragment supply relationships despite standardization pressures.
United States
Army next-generation combat vehicle programs and naval gun system upgrades anchor procurement volume. The Department of Defense's modular open systems approach mandates reshape supplier qualification pathways, forcing interoperability across armored vehicle platforms. General Dynamics and Curtiss-Wright maintain captive production capabilities across multiple states.
United Kingdom
British Army Boxer and Ajax program structures prioritize availability guarantees over unit acquisition cost, shifting toward performance-based logistics contracts. BAE Systems sustains transatlantic production footprints for chain gun ammunition handling across land and maritime programs. Industrial concentration clusters around defense hubs in the Midlands and South West.
Germany
Rheinmetall and Krauss-Maffei Wegmann integration demands drive automated feed mechanism development for Leopard and future indigenous platforms. EU Green Deal fluorinated gas restrictions force redesign of pneumatic actuation circuits in European-sourced handling systems. Manufacturing capabilities concentrate in Bavaria and North Rhine-Westphalia.
Poland
NATO eastern flank armored vehicle procurement creates white space for automated ammunition handling integration in K2 Black Panther and future indigenous platforms. National defense spending acceleration outpaces domestic supplier capacity, opening import channels. Industrial development clusters around Poznan and Warsaw defense corridors.
Australia
LAND 400 Phase 3 Boxer CRV and future infantry fighting vehicle programs represent underpenetrated demand for medium-caliber automated feed mechanisms in Asia-Pacific. Defense export control alignment with US technology transfer protocols simplifies supplier entry. Capability development concentrates in Victoria and South Australia shipyard and vehicle integration facilities.
Ammunition Handling Systems Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated defense primes commanding naval and ground platform programs while component specialists capture subsystem retrofit opportunities. Market structure tilts toward consolidated supply relationships at the platform level, fragmenting into specialized niche positions for diagnostics and materials technologies. Strategic archetypes include captive metallurgy divisions of major primes, electromechanical subsystem specialists, and regional maintenance-overhaul-repair providers. Dominant competitive moves encompass backward integration into alloy supply chains and technology licensing arrangements for modular interoperability compliance.
Among US-based integrated defense contractors, General Dynamics Corporation, BAE Systems, and Curtiss-Wright Corporation exemplify divergent positioning archetypes. General Dynamics occupies a position anchored in captive metallurgy and composite molding capabilities across ordnance and tactical systems divisions. BAE Systems represents transatlantic production footprint sustainability across coalition program requirements. Curtiss-Wright sits within the electromechanical diagnostics specialization tier, with embedded feeder drive technologies extending predictive maintenance intervals for expeditionary operational theaters.
| Leading Market Players |
|---|
| General Dynamics Corporation |
| BAE Systems |
| Curtiss-Wright Corporation |
| Meggitt Defense Systems |
| Moog Inc. |
| Dillon Aero |
| Nobles Worldwide |
| McNally Industries |
| Thales Group |
| Others |
Supply Flow & Price Mechanics
US Department of Defense program offices and NATO national procurement agencies concentrate buyer power, locking contract structures around performance-based availability guarantees rather than per-unit hardware transactions. This buyer concentration forces suppliers to absorb qualification cost burdens upfront while competing on lifecycle service metrics.
Pricing Analysis
Volume-military contracts anchor revenue pools while aftermarket diagnostics and predictive maintenance subscriptions expand margin contribution. Three-tier pricing structure across MIL-SPEC certified, NATO STANAG compliant, and commercial-off-the-shelf configurations reflects qualification burden differentiation. Cost compression in polymer composite feed chute manufacturing is intensifying because General Dynamics and BAE Systems have brought metallurgy and molding capabilities in-house. Law enforcement and training segment buyers exhibit highest price sensitivity, whereas naval close-in weapon system integrators prioritize cyclic-rate reliability over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle prime contractor demand from General Dynamics, BAE Systems, and Rheinmetall, while specialized subsystem vendors serve retrofit and foreign military sale programs through defense trade intermediaries. Manufacturing concentration rests on the United States, Germany, and the United Kingdom for final integration, with titanium aluminide alloy feedstock drawing from aerospace-grade suppliers in Japan and the United States. Aluminum-lithium billet scarcity from Russian and Chinese smelter concentration creates single-source vulnerability for lightweight ammunition track producers. Distribution runs through captive prime contractor supply chains and authorized foreign military sale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Modular open systems architecture mandates are compressing proprietary platform margins, forcing subscale suppliers toward consolidation or exit. Only integrated primes and specialized diagnostics developers will capture sustainable positions.
For Market Incumbents: Hedge against MOSA-driven commoditization by deepening captive control over titanium aluminide and polymer composite supply chains. Accelerate embedded sensor development for predictive maintenance contracts, as platform-as-a-service procurement displaces hardware-centric revenue models in British Army and Australian LAND 400 programs. For New Entrants and Emerging Players: Launch via subsystem retrofit partnerships targeting Poland's K2 Black Panther integration and Baltic states' armored vehicle modernization. Poland's domestic supplier capacity gap creates immediate white space for automated feed mechanism integration. Position around EU F-Gas Regulation compliance as incumbent pneumatic system redesigns extend qualification timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor electromechanical diagnostics specialists with embedded software capabilities in the United Kingdom and Australia. Long-term viability hinges on platform-as-a-service contract capture rather than spot hardware sales. Monitor MOSA mandate enforcement thresholds as the critical inflection signal for proprietary system obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Captive titanium aluminide production insulates General Dynamics from aerospace-grade billet scarcity. |
| Embedded Diagnostics Development | Curtiss-Wright's predictive maintenance software extends service contract capture in expeditionary theaters. |
| MOSA Compliance Certification | Modular interoperability investment preserves supplier eligibility for US Army next-generation combat vehicle awards. |
| Platform-as-a-Service Contracting | Availability guarantees in British Army Boxer programs displace traditional hardware-plus-spares procurement. |
| EU F-Gas Regulation Redesign | All-electric feeder architectures position European suppliers ahead of pneumatic system phase-out deadlines. |
Methodological Framework
Multi-period observation of NATO procurement award patterns, US Army modernization program milestones, and naval gun system upgrade schedules anchored the trend analysis, supplemented by interviews with program managers at defense primes, subsystem engineering directors, military procurement officers, and aftermarket service heads. Secondary validation drew from US Department of Defense contract announcements, NATO STANAG documentation, EU Green Deal regulatory filings, and MIL-STD qualification records. Bottom-up platform integration cost modeling and top-down defense budget allocation analysis were triangulated against supplier revenue disclosures.
Segment-weighting across automated, manual, semi-automated, and mobile system architectures combined with technology-tier splits between electric, hydraulic, pneumatic, and mechanical drive trains shaped the analytical framework. End-user weighting reflected military versus law enforcement versus civilian procurement concentration. CAGRs were derived from platform delivery schedules and modernization cycle phasing across the analysis window. Forecast inputs incorporated titanium aluminide alloy adoption curves and polymer composite replacement rates for legacy aluminum tracks.
Program delay risk, alloy supply disruption, and MOSA mandate acceleration are the dominant revision risks to baseline projections. Forecasts reflect documented assumptions regarding NATO eastern flank procurement pacing and naval shipbuilding schedules. Periodic stress-testing of base assumptions against actual contract award timing and qualification timeline extensions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Turret System Market
Weapons and Ammunition
Global E Bomb Market
Weapons and Ammunition
Small Caliber Ammunition Market
Weapons and Ammunition
Missile Launching Systems Market
Weapons and Ammunition
Global Artillery Systems Market
Weapons and Ammunition
Cruise Missile Market
Weapons and Ammunition
Weapons Release System Market
Weapons and Ammunition
Military Fuze Market
Weapons and Ammunition
Man-Portable Anti-Armor Weapons Market
Weapons and Ammunition
France Nuclear Bombs and Missiles Market
Weapons and Ammunition
Electromagnetic Weapons Market
Weapons and Ammunition
Weapon Mounts Market
Weapons and Ammunition
North America Ammunition Market
Weapons and Ammunition
Military Airborne Laser Market
Weapons and Ammunition
Mortar Artillery System Market
Weapons and Ammunition
Guns and Accessories Market