
 Asia-Pacific Natural Gas Market | 2026-2036
Asia-Pacific Natural Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Natural Gas Market Outlook
China's dual carbon goals is decoupling legacy coal infrastructure from new gas-fired power licensing, raising capital requirements for entrants without integrated upstream assets. China National Petroleum Corporation leverages its Tarim Basin pipeline network to sustain supply security across western provinces. Oil and Natural Gas Corporation anchors India's domestic production profile through its Krishna-Godavari deepwater blocks. Korea Gas Corporation operates the world's largest LNG import terminal complex at Incheon, controlling seasonal arbitrage flows across Northeast Asia.
Asia-Pacific natural gas consists primarily of methane with energy content ranging from 37-39 megajoules per cubic meter, extracted through conventional drilling, hydraulic fracturing of shale formations, or recovered as associated gas from oil production, then distributed for combustion in power turbines, industrial furnaces, and compressed vehicle engines. Liquefied Natural Gas dominates value flows through the region's import-dependent economies, while Compressed Natural Gas gains structural share in transportation applications where fleet operators seek fuel cost predictability. Power Generation absorbs the largest volume share as grid operators balance renewable intermittency, though Industrial Heating commands margin concentration through long-term bilateral contracts with price escalation clauses.
China's National Energy Administration enforces shale gas production quotas under the 14th Five-Year Plan, while India's Petroleum and Natural Gas Regulatory Board mandates city gas distribution network buildouts under amended PNG regulations. Japan's METI reviews long-term LNG procurement contracts through its Strategic Energy Plan, reshaping contract duration standards across Asian buyers. Stakeholders must weigh exposure to spot-indexed versus oil-linked pricing as contract renegotiation cycles accelerate and new Qatar-Australia supply volumes enter the Pacific basin.
Market Dynamics
Asia-Pacific natural gas markets face structural recalibration as China's dual carbon goals force coal-to-gas switching at scale while LNG import dependency across Northeast Asia locks in long-term contract renegotiation cycles. Pipeline infrastructure investments in Central Asia and shale extraction innovations in Sichuan Basin are redrawing supply geography.
Growth Catalysts
- Coal retirement mandates:Southeast Asian power utilities accelerate gas-fired capacity additions under national energy transition frameworks. Vietnam's PDP8 and Indonesia's RUPTL explicitly schedule coal plant phase-outs.
- City gas distribution buildouts:India's Petroleum and Natural Gas Regulatory Board mandates PNG network expansion to 300+ districts. Industrial corridors in Gujarat and Maharashtra convert process heat systems from fuel oil.
- Small-scale LNG infrastructure:Bunkering terminals at Singapore Port and Port of Busan enable maritime fuel switching. Island economies in Indonesia and Philippines access previously stranded gas reserves.
Market Restraints
- Upstream supply concentration:Qatar and Australia control over sixty percent of Asia-Pacific LNG contract volumes. Buyer concentration risk elevates during supply disruption events.
- Henry Hub-TTF price volatility transmission:Spot-indexed procurement exposes Japanese and Korean utilities to Atlantic basin price spikes. Hedging costs compress utility margins.
- Pipeline geopolitics:Myanmar-to-China pipeline flows face intermittent disruption. Central Asian transit routes through Uzbekistan and Kazakhstan require diplomatic maintenance.
Strategic Opportunities
- Biomethane injection mandates:Japan's METI Green Transformation framework requires gas utilities to blend renewable natural gas. Agricultural waste feedstock in Thailand and Vietnam offers stranded supply.
- Hydrogen-ready turbine retrofits:GE and Siemens equipment installed across South Korea and Taiwan permits 30% hydrogen co-firing. Utility engineering procurement shifts toward future-proof specifications.
- Compressed natural gas logistics:Heavy trucking fleets in India's Golden Quadrilateral corridor adopt CNG for fuel cost predictability. Station infrastructure buildout lags vehicle conversion rates.
Industry Challenges
- Deepwater drilling talent scarcity:Krishna-Godavari Basin operations require subsea engineering specialists. Indian technical institutes produce insufficient offshore rig personnel.
- Liquefaction train construction timelines:Australian greenfield projects face 18-24 month commissioning delays. Labor mobility restrictions and environmental approval bottlenecks extend capital deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Natural Gas Market |
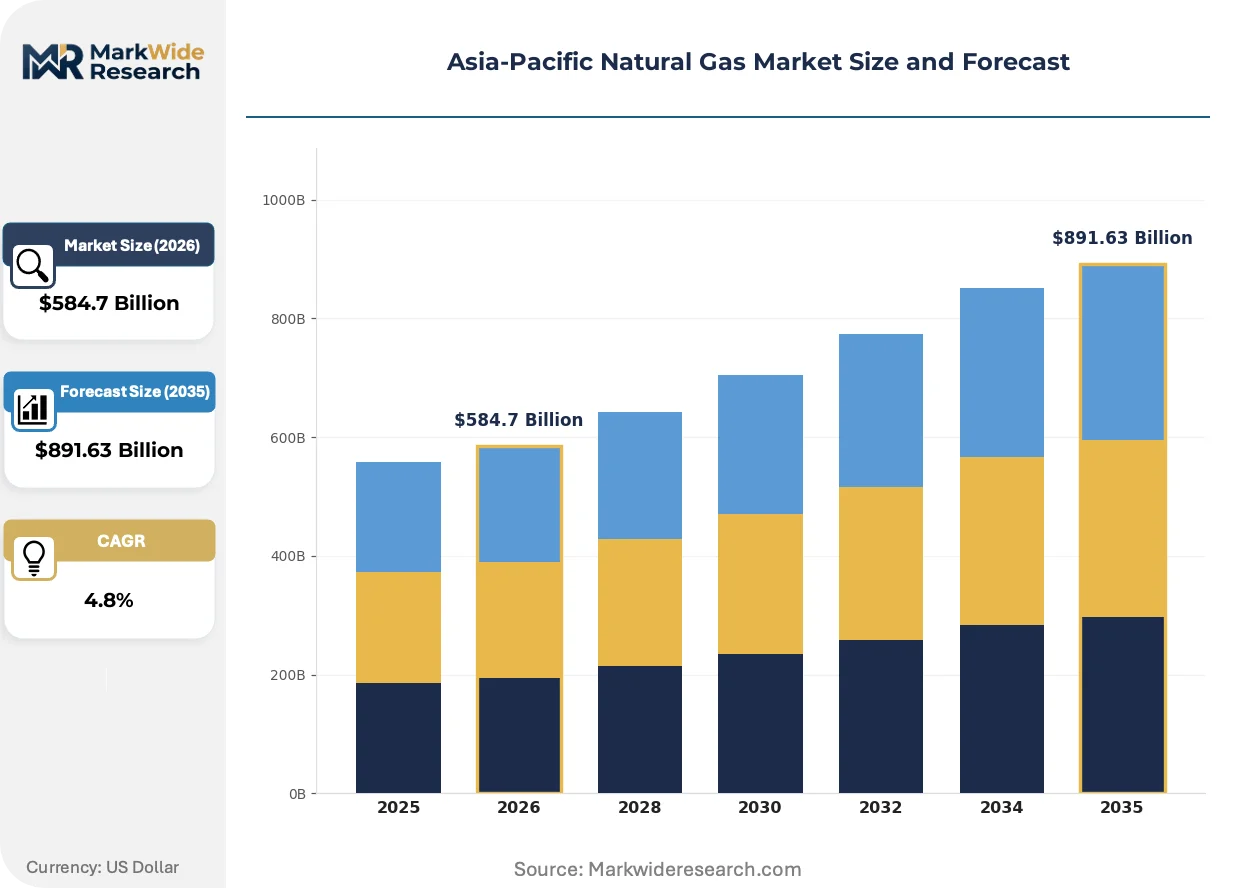
| Market Size in 2026 | $584.7 Billion |
| Market Size in 2035 | $891.63 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquefied Natural Gas, Compressed Natural Gas, Virtual Pipeline, Regasified LNG Application: Power Generation, Industrial Heating, Residential Heating, Transportation Delivery Mode: Pipelines, Shipping, Trucks, Rail End User: Utilities, Manufacturing, Transportation Sector, Commercial |
| Companies Covered | China National Petroleum Corporation, China Petroleum & Chemical Corporation, Oil and Natural Gas Corporation, Chevron Corporation, GAIL Limited, Korea Gas Corporation, Mitsubishi Corporation, Tokyo Gas Co. Ltd, ENN Energy Holdings Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Natural Gas Market Strategic Shifts
Digital twin deployment across LNG regasification terminals and AI-driven demand forecasting are compressing procurement decision cycles. Technology convergence between gas infrastructure and renewable integration systems is reshaping capital allocation priorities.
Hydrogen blending infrastructure is expanding into existing natural gas pipeline networks. Japanese utilities at Tokyo Gas and Osaka Gas pilot 10% hydrogen injection at city gate stations. Korean steelmakers at POSCO retrofit blast furnace injectors for hydrogen-natural gas mixtures. This dual-fuel capability is expanding into long-term infrastructure planning as governments harden decarbonization targets.
China's National Energy Administration enforces shale gas production quotas under the 14th Five-Year Plan. Sichuan Basin operators deploy extended-reach horizontal drilling to access previously uneconomic formations. Tarim Basin pipeline network expansions redirect western production toward coastal demand centers, reducing LNG import dependency in Jiangsu and Zhejiang provinces.
Spot-indexed procurement contracts displace traditional oil-linked pricing in Japanese and Korean utility portfolios. JERA and KOGAS renegotiate long-term Qatar supply agreements to incorporate DES pricing components. This contract structure rotation concentrates among buyers with storage flexibility at Incheon and Futtsu terminals, compressing margins for oil-linked contract holders.
Asia-Pacific Natural Gas Market Segmentation
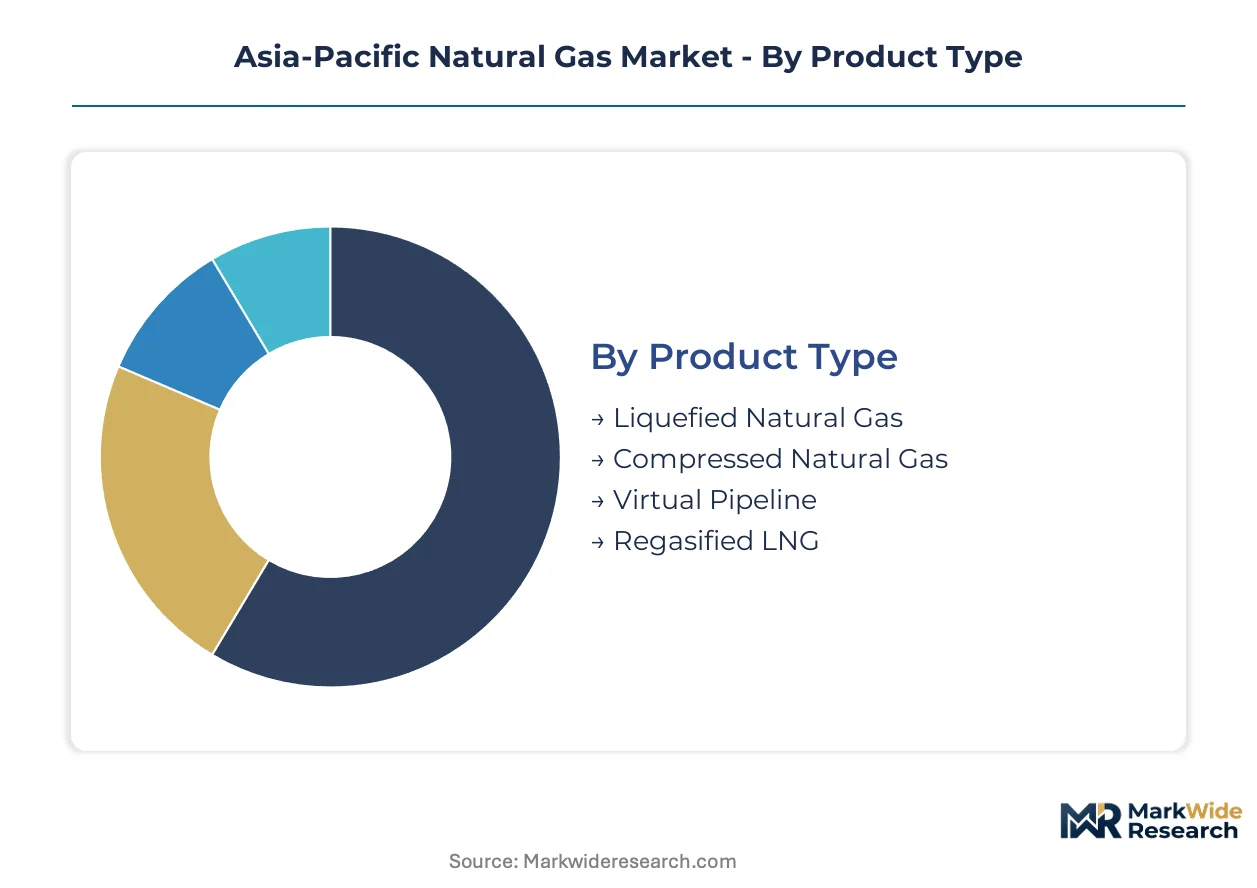
Asia-Pacific natural gas markets fragment across four structural dimensions that determine capital deployment cycles and margin capture. Product type differentiation separates infrastructure-heavy LNG investments from distributed CNG networks. Application segmentation reveals where coal displacement creates the steepest demand ramps.
Product Type:
Standardization dominates at the commodity level, yet delivery specifications fragment sharply across cryogenic liquefaction, compression thresholds, and regasification protocols.
- Liquefied Natural Gas:Cryogenically cooled to minus 162 degrees Celsius for maritime transport across Asia-Pacific basin routes. Demand concentrates at Korean and Japanese utility import terminals where coal retirement schedules force baseload power substitution.
- Compressed Natural Gas:Pressurized to 200-250 bar for distributed vehicle fueling and industrial feedstock. India's Golden Quadrilateral highway corridor drives fleet conversion as diesel price volatility erodes operator margins.
- Virtual Pipeline:Truck-mounted tube trailers deliver stranded gas to off-grid industrial zones. Indonesian archipelago operations and Philippine island manufacturing clusters absorb supply where physical pipeline economics fail.
- Regasified LNG:Returns cryogenic liquid to gaseous state at coastal import terminals. Chinese Jiangsu and Zhejiang province distribution networks prioritize this supply mode over distant domestic production.
Most installed capacity flows through Liquefied Natural Gas. Expansion is steepest in Compressed Natural Gas.
Application:
Volume concentration tilts toward baseload power substitution, while margin capture favors industrial process heat under long-term bilateral contracting.
- Power Generation:Combined-cycle gas turbines balance renewable intermittency across Southeast Asian grids. Vietnam's PDP8 implementation and Indonesia's RUPTL scheduling accelerate coal-to-gas capacity additions.
- Industrial Heating:Process heat for cement, chemicals, and steel production commands premium pricing through take-or-pay structures. Gujarat and Maharashtra manufacturing corridors convert fuel oil systems under India's city gas distribution mandates.
- Residential Heating:Urban pipeline networks in northern China and Korea deliver space heating fuel. Seasonal demand spikes strain storage capacity at Incheon and Tianjin terminals.
- Transportation:Heavy-duty trucking and maritime bunkering adopt gas-for-oil substitution. Singapore Port and Busan terminal infrastructure enables marine fuel switching under IMO compliance timelines.
Power Generation absorbs the largest volume flows. Industrial Heating commands the strongest margin expansion trajectory.
Delivery Mode:
Geographic constraints and infrastructure legacy determine modal selection, with pipeline economics favoring continental demand centers while maritime routes serve archipelago markets.
- Pipelines:Central Asian transit routes through Uzbekistan and Kazakhstan feed China's western provinces. Tarim Basin network expansions reduce coastal LNG import dependency.
- Shipping:Qatari and Australian LNG carriers dominate Asia-Pacific contract volumes. JERA and KOGAS renegotiate long-term supply agreements toward DES pricing components.
- Trucks:Tube trailer fleets serve CNG station networks and virtual pipeline operations. India's 300-district city gas buildout mandates compress logistics scaling.
- Rail:Limited deployment for bulk LNG container movement across China and India rail corridors. Regulatory harmonization for cryogenic cargo remains incomplete.
Shipping handles the majority of international volume. Trucks are gaining share fastest in last-mile distribution.
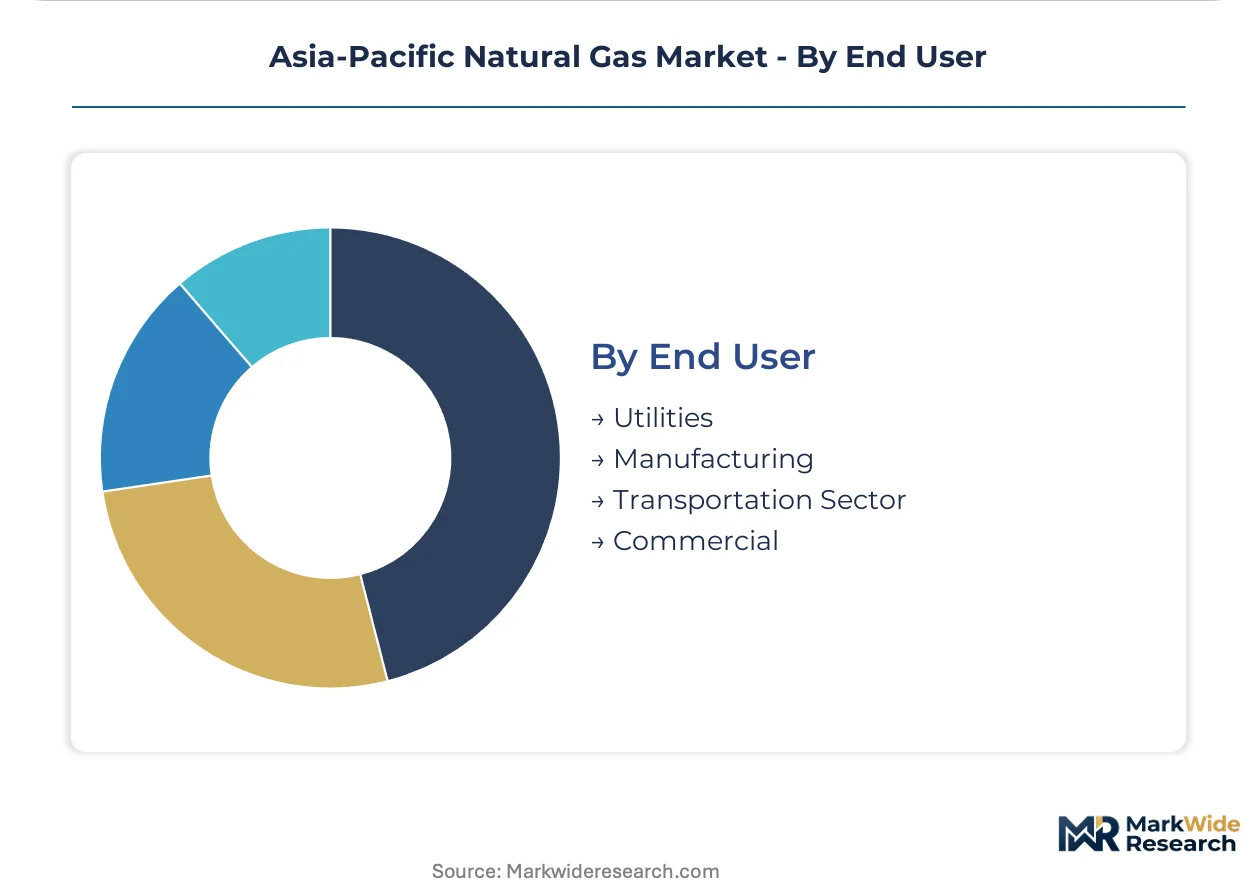
End User:
Procurement sophistication varies sharply across regulated utilities, price-sensitive manufacturers, and fragmented commercial accounts.
- Utilities:Grid operators in Japan, Korea, and Taiwan manage seasonal arbitrage through storage-flexible terminal access. Spot-indexed contract exposure elevates hedging costs during Atlantic basin price spikes.
- Manufacturing:Steel, cement, and chemical producers negotiate long-term bilateral contracts with oil-linked escalation clauses. Process heat reliability requirements override spot market participation.
- Transportation Sector:Fleet operators prioritize fuel cost predictability over energy density. CNG logistics infrastructure buildout lags vehicle conversion rates across India's industrial corridors.
- Commercial:Hotels, hospitals, and retail chains adopt gas-fired distributed generation. City gate station access determines economic viability in secondary urban markets.
Utilities control the largest procurement volumes. Manufacturing contracts deliver the most stable margin structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Subsea engineering specialists and pipeline construction crews concentrate along Australia's northwest shelf and China's Sichuan Basin, anchoring regional upstream capability. These talent clusters sustain extraction and infrastructure deployment across the Asia-Pacific basin.
China
Sichuan Basin shale operators and Tarim Basin pipeline engineers drive domestic production scaling. The National Energy Administration enforces shale gas quotas under the 14th Five-Year Plan. Jiangsu and Zhejiang province distribution networks prioritize regasified LNG over distant domestic supply.
India
Krishna-Godavari deepwater blocks and Gujarat industrial corridors anchor demand expansion. The Petroleum and Natural Gas Regulatory Board mandates city gas distribution to 300-plus districts under amended PNG regulations. Maharashtra manufacturing hubs convert fuel oil process heat systems to natural gas.
Japan
Utility procurement teams at JERA and Tokyo Gas manage seasonal arbitrage through storage-flexible terminal access. METI reviews long-term LNG contracts through its Strategic Energy Plan, reshaping duration standards. Osaka Gas pilots hydrogen injection at city gate stations under Green Transformation frameworks.
South Korea
Korea Gas Corporation operates the world's largest LNG import terminal complex at Incheon, controlling seasonal flows across Northeast Asia. KOGAS renegotiates Qatar supply agreements toward DES pricing components. POSCO steelmakers retrofit blast furnace injectors for hydrogen-natural gas mixtures.
Australia
Northwest Shelf liquefaction trains and Queensland coal seam gas fields anchor export capacity. Greenfield projects face 18-24 month commissioning delays from labor mobility restrictions. Gladstone terminal infrastructure redirects Pacific basin flows toward Japanese and Korean utility buyers.
Asia-Pacific Natural Gas Market Competitive Environment
The competitive structure tilts toward state-backed integrated oil and gas companies with captive upstream assets and pipeline networks. These national champions command procurement preference in domestic markets while competing for long-term supply contracts abroad. Three archetypes dominate: upstream-integrated national oil companies, utility-affiliated LNG importers with terminal access, and city gas distributors with localized network control. Competitive moves concentrate on pipeline network expansion and long-term contract renegotiation toward spot-indexed pricing.
Among Chinese state-backed operators, China National Petroleum Corporation and China Petroleum & Chemical Corporation exemplify the upstream-integrated archetype with basin-level production quotas and coastal distribution reach. Oil and Natural Gas Corporation represents Indian deepwater capability through its Krishna-Godavari block positions. Korea Gas Corporation occupies a distinctive position as a utility-scale importer with terminal infrastructure leverage across Northeast Asian spot markets.
| Leading Market Players |
|---|
| China National Petroleum Corporation |
| China Petroleum & Chemical Corporation |
| Oil and Natural Gas Corporation |
| Chevron Corporation |
| GAIL Limited |
| Korea Gas Corporation |
| Mitsubishi Corporation |
| Tokyo Gas Co. Ltd |
| ENN Energy Holdings Limited |
| Others |
Value Chain & Pricing Dynamics
Subsea engineering specialists concentrated along Australia's northwest shelf and China's Sichuan Basin command wage premiums that widen pricing spreads between integrated LNG supply contracts and spot-indexed procurement. Labor-cost differentials between these talent clusters and emerging basins in India and Southeast Asia translate directly into contract-tier stratification.
Pricing Analysis
Bundled long-term offtake agreements with integrated shipping and regasification services dominate utility procurement, while unbundled spot-indexed contracts expose buyers to Henry Hub-TTF volatility transmission. Three-tier pricing structure across premium, standard, and economy levels separates oil-linked Japanese utility contracts from DES-indexed Korean agreements and spot-exposed Southeast Asian buyers. Pricing pressure stems from Qatar-Australia supply volume expansion compressing contract premiums. Manufacturing buyers in India's industrial corridors exhibit highest price sensitivity, while Japanese utilities with storage-flexible terminal access at Futtsu show lowest sensitivity.
Supply Chain Analysis
Reverse-logistics flows for LNG carrier repositioning and regasification terminal turnaround cycles create seasonal supply bottlenecks that constrain spot market liquidity. Upstream supply concentrates in Qatar, Australia, and the United States. Feedstock dependencies include shale gas feedstock, liquefaction train capacity, and specialized cryogenic shipping. Single-source vulnerability elevates during Strait of Malacca transit disruptions. Distribution runs through long-term bilateral contracts with utility offtakers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Qatar's low-cost liquefaction capacity against Japan's high import-dependency pricing creates sustained margin capture opportunities for integrated traders.
For Market Incumbents: Extend pipeline network control through Central Asian transit route consolidation and Tarim Basin expansion. Defend against spot-indexed contract displacement by locking in manufacturing offtakers in Gujarat and Maharashtra under long-term bilateral structures. Prioritize hydrogen-ready infrastructure certification to preempt regulatory obsolescence under Japan's METI Green Transformation framework. For New Entrants and Emerging Players: Virtual pipeline logistics platforms offer the most penetrable entry vector for Indonesian archipelago and Philippine island markets where physical pipeline economics fail. Target CNG station infrastructure buildout across India's Golden Quadrilateral corridor where vehicle conversion rates outpace fueling capacity. Deploy asset-light tube trailer fleet models with localized city gas distribution partnerships. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale city gas distributors with district-level PNG network concessions but without integrated upstream supply. Long-term viability hinges on regulatory capture through amended PNG regulation compliance and biomass injection mandate positioning. Monitor Japan-Korea contract renegotiation cycles toward DES pricing components as inflection signal for spot-indexed market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Australian greenfield liquefaction trains expand Pacific basin supply availability for Northeast Asian utility buyers. |
| Long-term Supply Agreement | JERA and KOGAS renegotiate Qatar contracts toward DES pricing components, reshaping regional contract standards. |
| Backward Integration | China National Petroleum Corporation leverages Tarim Basin pipeline networks to reduce coastal LNG import dependency. |
| Green Certification Program | Japanese utilities pilot 10% hydrogen injection at city gate stations under METI Green Transformation biomethane mandates. |
| Technology Licensing | GE and Siemens hydrogen-ready turbine retrofits enable 30% hydrogen co-firing across South Korean and Taiwanese installations. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from utility planning officers at JERA and Korea Gas Corporation, EPC contractors on Australian greenfield projects, LNG shipping operators, and city gas distribution regulators at India's Petroleum and Natural Gas Regulatory Board. Secondary validation drew from EIA data, IEA regional gas reports, FERC export filings, and project development databases tracking liquefaction train commissioning. Bottom-up demand modeling across end-use segments triangulated against top-down supply capacity assessments.
Segment-weighting approaches applied differential growth assumptions across power generation, industrial heating, residential, and transportation applications. The analytical framework incorporated fuel source differentiation, project scale tiers, regulatory framework clusters, and regional grid interconnection status throughout the projection horizon. CAGRs derived from production quota enforcement trajectories under China's 14th Five-Year Plan and India's PNG network buildout mandates. Forecast inputs included shale extraction innovation rates and small-scale LNG infrastructure deployment timelines.
Supply disruption events, contract renegotiation cycle acceleration, and hydrogen blending infrastructure cost curves are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding Qatar-Australia supply volume timing and Central Asian pipeline diplomatic stability. Practitioners should monitor spot-indexed contract penetration rates and biomethane injection mandate enforcement for early signals of structural pricing regime shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Sand Screen Sales Market
Oil & Gas
United States Oil and Gas Market
Oil & Gas
Russian Federation Oil and Gas Upstream Market
Oil & Gas
Well Stimulation Vessels Market
Oil & Gas
Oil Breather Tank Market
Oil & Gas
Hydraulic Fracturing Market
Oil & Gas
Unconventional Gas Market
Oil & Gas
North Sea Oilfield Equipment Market
Oil & Gas
Process Simulation Software in Oil and Gas Market
Oil & Gas
North America Oil and Gas Electric Submersible Pump Market
Oil & Gas
Asia-Pacific Oilfield Services Market
Oil & Gas
Deepwater and Ultra-Deepwater Exploration and Production Market
Oil & Gas
Russian Federation Oil and Gas Midstream Market
Oil & Gas
Offshore Drilling Fluid Market
Oil & Gas
Oil and Gas Hose Assemblies Market
Oil & Gas
Kuwait & Iraq Oilfield Chemicals Market