
 Process Simulation Software in Oil and Gas Market | 2026-2036
Process Simulation Software in Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Process Simulation Software in Oil and Gas Market Outlook
The EU Green Deal is rebalancing capital allocation across European refining complexes, forcing operators to retire legacy assets or retrofit with simulation-backed optimization suites. Aspen Technology leverages its steady-state simulation heritage to anchor long-term contracts with integrated refiners. Honeywell competes through its unified control-and-simulation architecture that extends hardware-software bundling into downstream projects.
Process simulation software in oil and gas refers to computational platforms that model thermodynamic behavior, mass transfer, and reaction kinetics across hydrocarbon processing equipment using equation-oriented or sequential modular solvers. These tools enable engineers to predict unit performance, optimize energy integration, and validate safety envelopes before physical commissioning. Steady-state simulation dominates current license revenue due to its entrenched role in front-end engineering design, while dynamic simulation is displacing traditional operator training systems as real-time digital twin adoption accelerates. Cloud-based deployment is capturing the fastest expansion among deployment models, though on-premise installations sustain margin pools in national oil companies with restricted data sovereignty policies.
The EPA enforces methane performance standards that compel upstream operators to document leak detection and repair protocols through validated process models. OSHA process safety management rules mandate hazard analysis documentation that simulation software generates for covered petrochemical facilities. Stakeholders must weigh cloud migration timelines against cybersecurity frameworks as regulatory evidence requirements harden.
Market Dynamics
Digital twin deployment across Gulf Coast petrochemical corridors is compressing commissioning cycles and forcing incumbent vendors to bundle real-time optimization with legacy steady-state licenses. This convergence of operational technology and information technology is restructuring contract terms and technical support models.
Growth Catalysts
- EPA Methane Performance Standards:Upstream operators must document leak detection protocols through validated process models, creating mandatory software procurement cycles.
- Carbon capture retrofits:Amine-based post-combustion capture projects require rigorous thermodynamic simulation to optimize energy penalty and solvent regeneration.
- US Gulf Coast ethylene expansion:Petrochemical capacity additions in Texas and Louisiana are generating concentrated demand for front-end engineering design licenses.
Market Restraints
- High-performance computing costs:Cloud-based dynamic simulation workloads incur substantial GPU rental expenses that constrain mid-size engineering contractors.
- Data sovereignty restrictions:National oil companies in Saudi Arabia and Russia mandate on-premise deployment, fragmenting vendor cloud strategies.
- Legacy workforce dependency:Retirement of FORTRAN-era chemical engineers is eroding institutional knowledge required to validate complex equation-oriented models.
Strategic Opportunities
- India refinery upgrades:Reliance Industries and Indian Oil Corporation are expanding digital twin pilots under the country's dual carbon reduction commitments.
- Electrolyzer-integrated hydrogen hubs:Green hydrogen production facilities require novel simulation of alkaline and PEM cell thermal management alongside downstream ammonia synthesis.
- EU F-Gas Regulation compliance:Refrigerant transition mandates for LNG liquefaction trains are creating demand for alternative thermodynamic property packages.
Industry Challenges
- Cyber-physical security integration:Real-time digital twins connecting plant historians to cloud solvers expand attack surfaces requiring IEC 62443 certification timelines.
- Multiphysics model reconciliation:Coupling computational fluid dynamics with process simulation introduces convergence failures that delay project milestones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Process Simulation Software in Oil and Gas Market |
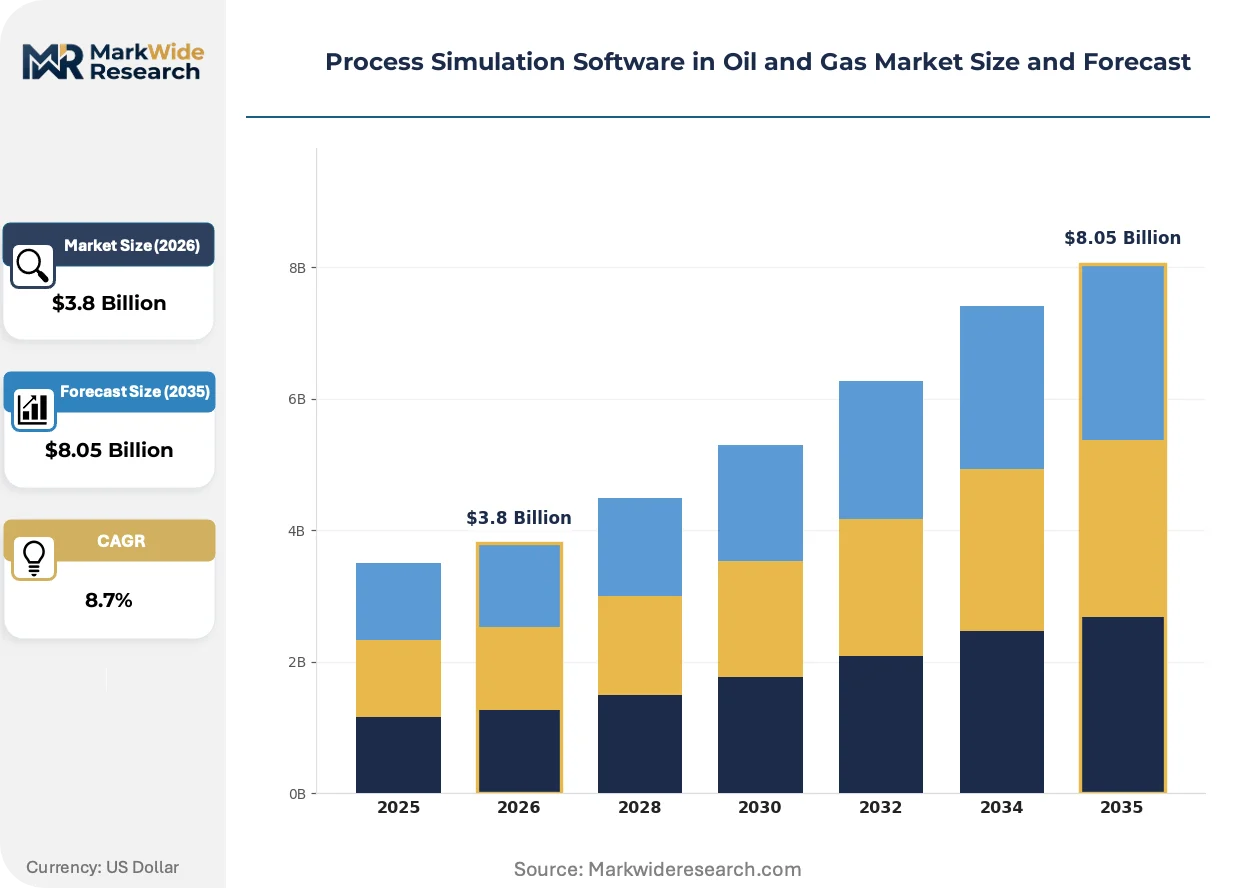
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Software Type: Process Modeling, Dynamic Simulation, Steady-State Simulation, Design Software Application: Upstream, Midstream, Downstream, Refining User Type: Engineers, Researchers, Analysts, Technicians Deployment Model: On-Premise, Cloud-Based, Hybrid, Standalone |
| Companies Covered | Aspen Technology, Honeywell, AVEVA, Siemens, Schneider Electric, Schlumberger, KBC Advanced Technologies, Emerson Electric, ANSYS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Process Simulation Software in Oil and Gas Market Strategic Shifts
Artificial intelligence is penetrating process simulation workflows through surrogate modeling and automated parameter estimation. This shift is compressing the traditional trade-off between model fidelity and computational speed.
Machine learning surrogate models trained on high-fidelity simulation outputs are automating real-time optimization loops that previously required manual engineer intervention. Integrated operators at Baytown and Beaumont complexes are deploying these reduced-order models for predictive control. The technology is automating setpoint adjustments across distillation columns and reactor trains without human-in-the-loop validation.
The EU AI Act's risk classification framework is imposing documentation burdens on simulation software used for safety-critical process control. Vendors must now maintain algorithmic transparency logs for models influencing emergency shutdown logic. Downstream facilities in Rotterdam and Antwerp are demanding compliance roadmaps before renewing enterprise licenses.
Subscription pricing for cloud-hosted simulation seats is displacing perpetual license procurement among independent engineering firms. Wood Group and McDermott are consolidating vendor relationships around usage-based models with burst capacity for peak proposal cycles. This shift concentrates most visibly in Houston and London, where contract engineering headcount fluctuates with LNG project sanctioning waves.
Process Simulation Software in Oil and Gas Market Segmentation
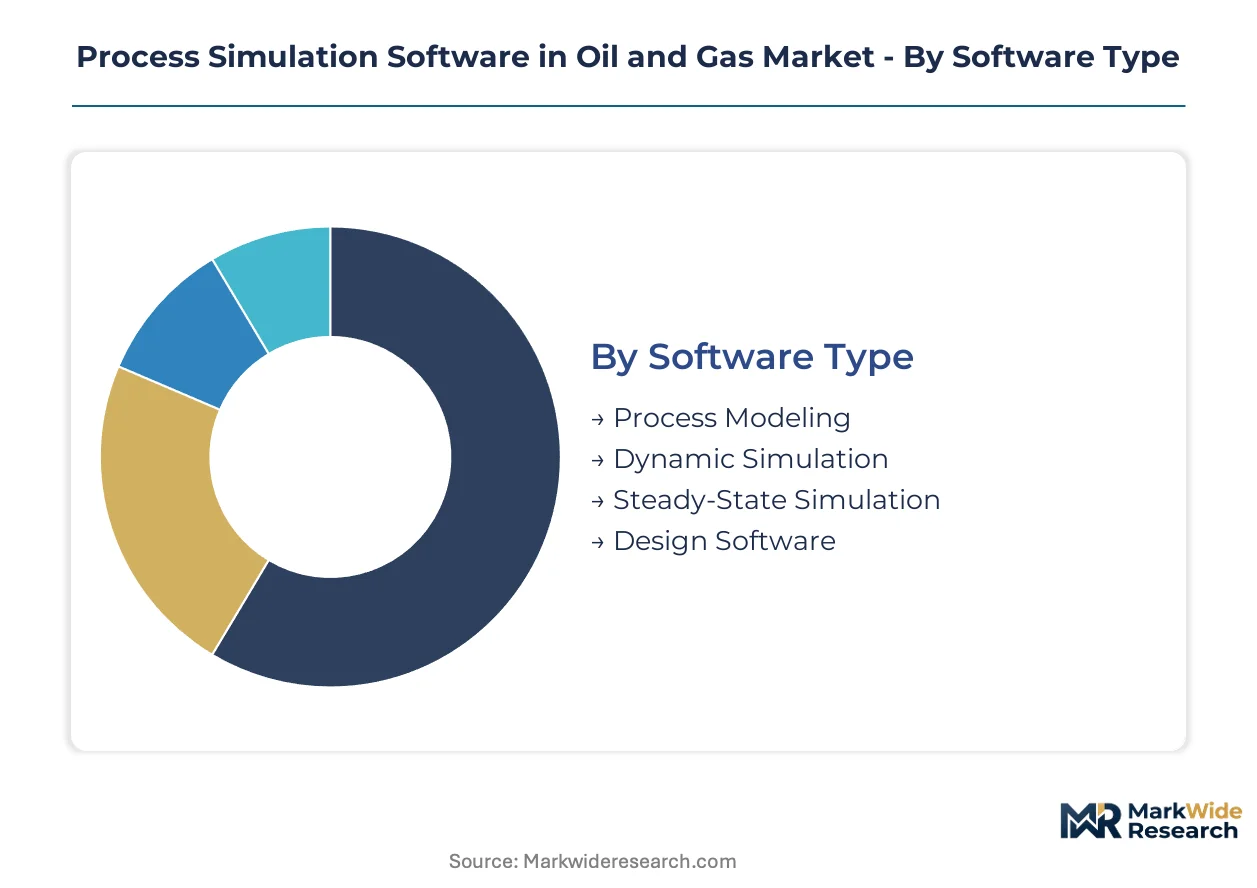
Process simulation software segments reflect divergent computational architectures and deployment constraints across hydrocarbon value chains. License structures, hardware requirements, and regulatory evidence standards vary sharply by software type and deployment model.
Software Type:
Technical sophistication and solver methodology distinguish commercial positioning across this axis.
- Steady-State Simulation:Equation-oriented and sequential modular solvers calculate mass and energy balances at fixed operating points. Front-end engineering design contracts in the US Gulf Coast petrochemical corridor sustain entrenched demand for yield optimization and heat integration studies.
- Dynamic Simulation:Time-dependent differential equation solvers model transient behaviors including startup sequences and emergency scenarios. Real-time digital twin deployments across Baytown and Beaumont complexes are displacing traditional operator training systems as integrated operators bundle predictive control with legacy licenses.
- Process Modeling:Thermodynamic property packages and reaction kinetic frameworks enable custom unit operation development.
- Design Software:Equipment sizing and cost estimation modules bridge process simulation with capital project workflows.
Steady-state simulation leads on scale; dynamic simulation leads on momentum.
Application:
Value chain position dictates model complexity and regulatory exposure.
- Downstream:Refinery-wide material balance reconciliation and product blending optimization require rigorous thermodynamic validation. EU Green Deal efficiency mandates and F-Gas Regulation compliance deadlines are accelerating procurement cycles across Rotterdam and Antwerp facilities.
- Refining:Catalytic reformer and hydrocracker kinetic modeling demands specialized reactor modules with proprietary catalyst deactivation algorithms. Reliance Industries and Indian Oil Corporation are expanding digital twin pilots under India's dual carbon reduction commitments.
- Upstream:Subsurface flow assurance and surface facility debottlenecking utilize compositional reservoir coupling.
- Midstream:Pipeline hydraulics and storage terminal vapor recovery modeling address methane performance documentation.
Refining commands the deepest license values; downstream is expanding most quickly.
User Type:
Workflow integration and interface complexity segment procurement authority.
- Engineers:Process design and optimization specialists consume the majority of perpetual license seats. Wood Group and McDermott are consolidating vendor relationships around subscription models with burst capacity for peak proposal cycles in Houston and London.
- Researchers:Novel process development and pilot plant validation require equation-oriented flexibility and custom property package access.
- Analysts:Economic evaluation and scenario planning utilize simplified interfaces with Monte Carlo sensitivity tools.
- Technicians:Control room operators access reduced-order models through embedded human-machine interface dashboards.
Engineers anchor seat volume; researchers show the steepest expansion trajectory.
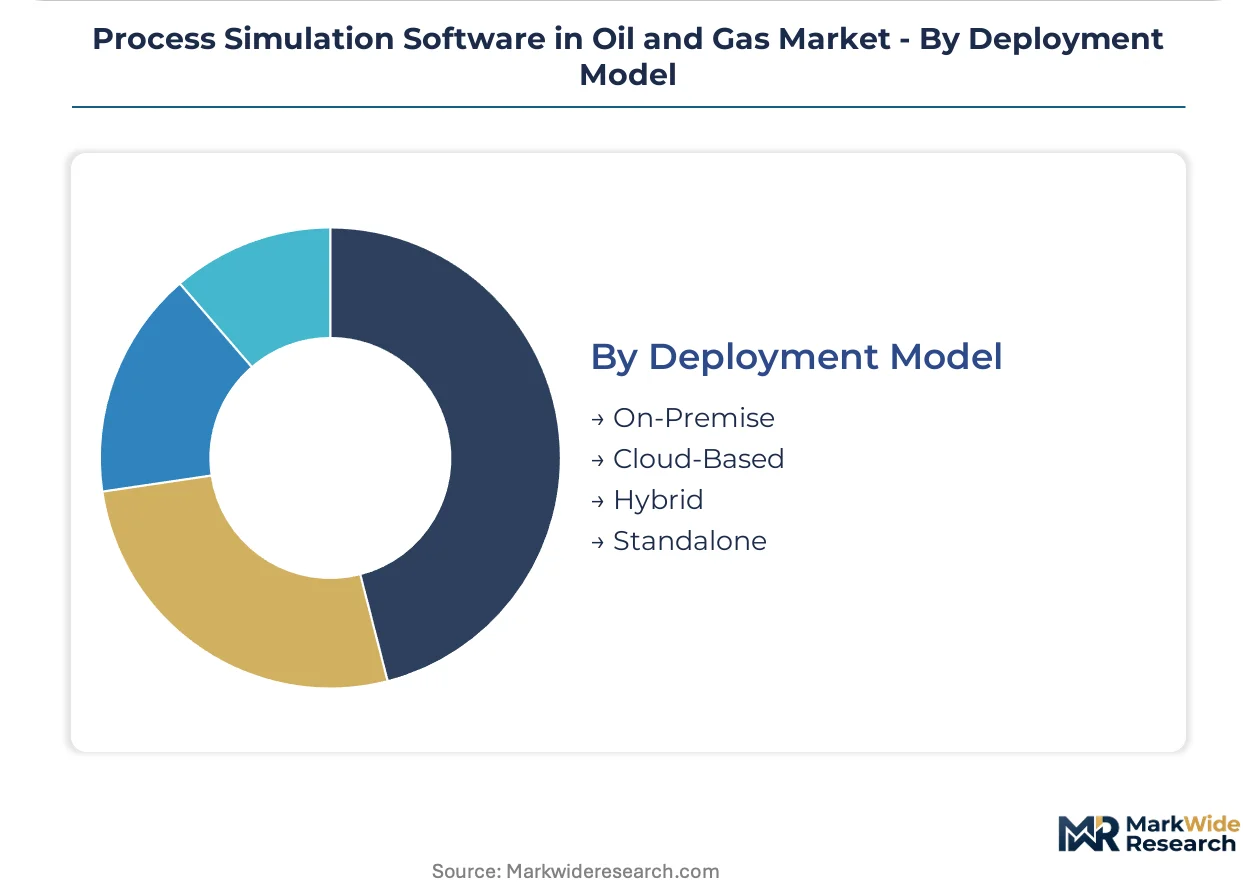
Deployment Model:
Data sovereignty requirements and computational intensity shape infrastructure decisions.
- Cloud-Based:GPU-accelerated dynamic simulation and machine learning surrogate training offload capital expenditure to operational budgets. Independent engineering firms are displacing perpetual procurement with usage-based models, though IEC 62443 certification timelines constrain real-time digital twin adoption.
- On-Premise:Air-gapped installations satisfy national oil company data sovereignty mandates in Saudi Arabia and Russia. Margin pools persist where restricted export control regulations govern thermodynamic property database access.
- Hybrid:Steady-state model development on-premise couples with cloud-based optimization for sensitivity studies.
- Standalone:Single-workstation licenses serve specialty engineering contractors with intermittent project workloads.
On-premise retains the installed base; cloud-based is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Process simulation software originated in United States chemical engineering departments during the 1960s, with commercialization following the rise of integrated refining complexes along the Gulf Coast. The technology spread to European petrochemical centers and subsequently to Asian manufacturing hubs as digitalization mandates intensified.
United States
The EPA's methane performance standards and OSHA process safety management rules compel upstream and downstream operators to document hazard analyses through validated simulation models. Texas and Louisiana host the densest concentration of petrochemical capacity expansions, where Baytown and Beaumont complexes deploy real-time digital twins for predictive control across distillation trains.
Germany
REACH compliance and the EU Green Deal's efficiency mandates are accelerating procurement cycles across Rhine-Ruhr refining clusters. BASF and Bayer legacy sites in Ludwigshafen and Leverkusen retrofit steady-state licenses with dynamic simulation for carbon capture integration and energy optimization studies.
Saudi Arabia
SABIC's expansion of specialty chemicals capacity and the kingdom's downstream diversification drive demand for rigorous thermodynamic modeling. Data sovereignty restrictions mandate on-premise deployment across Jubail and Yanbu industrial cities, fragmenting vendor cloud strategies while preserving margin pools for air-gapped installations.
India
Reliance Industries and Indian Oil Corporation anchor digital twin pilots under the country's dual carbon reduction commitments. The Petroleum and Natural Gas Regulatory Board's tightening emissions standards push refiners in Gujarat and Maharashtra toward simulation-backed optimization suites for catalytic reformer and hydrocracker units.
China
MIIT's smart manufacturing initiatives and the national dual carbon goals are restructuring procurement authority at Sinopec and PetroChina facilities. Yangtze River Delta and Pearl River Delta petrochemical corridors concentrate demand for front-end engineering design licenses as ethylene capacity additions proceed.
Process Simulation Software in Oil and Gas Market Competitive Environment
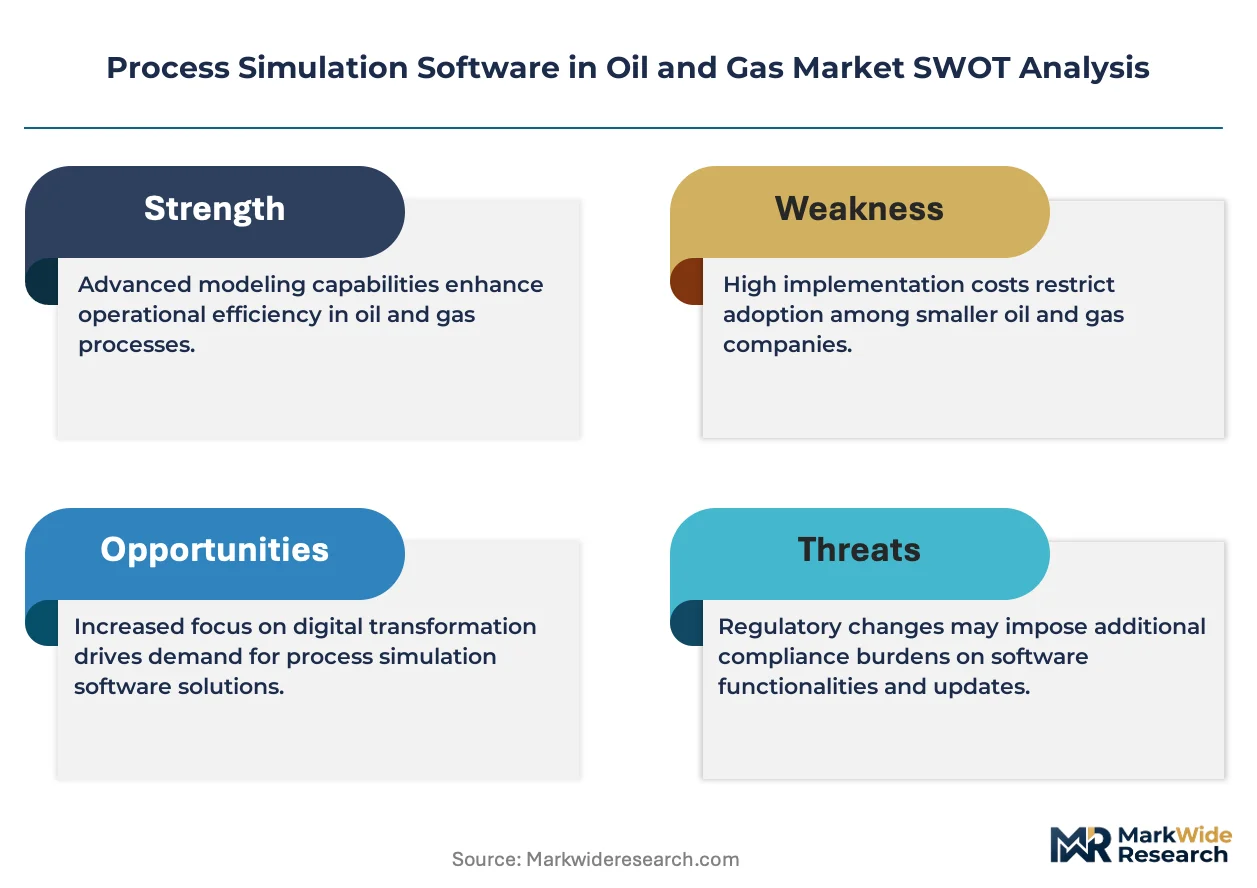
Capital-heavy engineering conglomerates compete with asset-light software specialists for license revenue across hydrocarbon processing workflows. The vendor base consolidates around three tiers: diversified automation suppliers bundling hardware-software stacks, pure-play simulation houses defending equation-oriented solver heritage, and emerging cloud-native platforms attacking mid-market engineering contractors. Strategic differentiation centers on M&A activity absorbing specialized reactor modeling boutiques and capacity expansion into GPU-accelerated dynamic simulation infrastructure.
Within the diversified automation tier, Honeywell and Siemens exemplify hardware-software bundling strategies that extend control system footprints into downstream optimization contracts. Aspen Technology occupies a position as the pure-play archetype, leveraging steady-state heritage to anchor long-term refinery relationships. AVEVA represents the cloud-transition vector, consolidating subscription pricing models among independent engineering firms in Houston and London.
| Leading Market Players |
|---|
| Aspen Technology |
| Honeywell |
| AVEVA |
| Siemens |
| Schneider Electric |
| Schlumberger |
| KBC Advanced Technologies |
| Emerson Electric |
| ANSYS |
| Others |
Value Chain & Pricing Dynamics
License-tier bifurcation between perpetual enterprise seats and subscription-based cloud access manifests in divergent margin structures and vendor support architectures across the hydrocarbon processing software value chain. Aspen Technology and Honeywell extract premium pricing from integrated refiners through bundled hardware-software stacks, while AVEVA and emerging cloud-native platforms compete for engineering contractor volume through usage-based models that shift capital expenditure to operational budgets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments procurement authority by organizational scale and deployment complexity. Premium tiers command higher valuations through IEC 62443 certification documentation and dedicated technical account management, while standard licenses target mid-size engineering firms with burst capacity for proposal cycles. Price differentiation hinges on GPU-accelerated solver access and thermodynamic property database breadth. Cost compression in the standard tier intensifies as cloud-native entrants undercut incumbent perpetual license maintenance fees. National oil companies in Saudi Arabia and Russia exhibit lowest price sensitivity due to data sovereignty mandates that preserve on-premise margin pools.
Supply Chain Analysis
Refurbishment flows for legacy FORTRAN-era solver modules and equation-oriented model libraries sustain secondary market activity among retiring chemical engineering specialists. Software development concentrates in the United States, Germany, and India, with Houston, Ludwigshafen, and Bangalore hosting primary R&D centers for thermodynamic property package development. Raw material dependencies span high-performance computing infrastructure from NVIDIA and AMD, cloud hosting capacity from AWS and Azure, and specialized chemical engineering talent pipelines. Single-source vulnerability in GPU supply chains threatens dynamic simulation deployment timelines. Distribution runs through direct enterprise sales teams for integrated operators and channel partners for independent engineering contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Process simulation software procurement functions as a geographic-arbitrage play where engineering labor cost differentials between Houston and Bangalore enable Indian service providers to undercut Western digital twin implementation quotes by 40-60 percent.
For Market Incumbents: To counter cloud-native platforms attacking the mid-market engineering contractor segment, Aspen Technology and Honeywell should deepen backward integration into GPU-accelerated infrastructure and anchor long-term contracts with carbon capture retrofit mandates across EU refining clusters. Certification investment in EU AI Act algorithmic transparency documentation for safety-critical control applications preserves premium positioning in Rotterdam and Antwerp facilities. For New Entrants and Emerging Players: Cloud-based subscription routes offer the most penetrable entry vector for independent engineering firms in Houston and London seeking burst capacity during LNG project sanctioning waves. Target mid-size contractors currently locked out of perpetual license economics by concentrating on steady-state simulation for front-end engineering design proposals. Go-to-market execution should emphasize usage-based pricing with seamless migration paths from legacy Aspen HYSYS and Honeywell UniSim installations. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized reactor modeling boutiques possessing proprietary catalyst deactivation algorithms for hydrocracker and catalytic reformer units. Long-term viability over a decade horizon depends on machine learning surrogate model capabilities that compress the fidelity-speed trade-off in real-time optimization loops. Watch for EPA methane performance standard enforcement intensity as an inflection indicator for mandatory upstream software procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| GPU-Accelerated Dynamic Simulation Infrastructure | NVIDIA partnerships enable real-time digital twin deployment across Baytown and Beaumont complexes. |
| EU AI Act Compliance Certification | Algorithmic transparency documentation secures license renewals at Rotterdam and Antwerp downstream facilities. |
| Carbon Capture Retrofit Integration | Amine-based post-combustion simulation modules anchor long-term contracts with BASF Ludwigshafen operations. |
| Machine Learning Surrogate Model Development | Reduced-order models automate setpoint adjustments without human-in-the-loop validation at integrated operator sites. |
| Cloud-Native Platform Expansion | Subscription pricing displaces perpetual procurement among Wood Group and McDermott engineering contractors. |
Study Parameters
Bottom-up refinery operator and engineering contractor modeling reconciled against top-down software vendor license tracking forms the analytical core of this study. Primary interviews with process simulation directors, IT procurement officers at national oil companies, EPC project managers, and chemical engineering department heads combined with secondary validation from SEC 10-K filings, EPA enforcement databases, EU ETS transaction registries, and hyperscaler capex disclosures. Triangulation across these sources ensures segmentation integrity for steady-state versus dynamic simulation deployment patterns.
Historical trendline analysis of license revenue trajectories from 2016 through 2026 established baseline growth coefficients across the projection horizon. The forecast framework models segmentation dimensions including software type, deployment model, user archetype, and regional regulatory cluster. CAGRs derive from regression analysis against petrochemical capacity addition pipelines and carbon capture project sanctioning waves. Industry-specific inputs include ethylene cracker commissioning schedules and EU F-Gas Regulation compliance deadlines.
The model assumes a particular technology adoption path; alternative pathways for machine learning surrogate models displacing traditional equation-oriented solvers would alter the outlook. Forecasts reflect assumptions regarding EPA methane rule enforcement continuity and EU Green Deal capital allocation stability. Practitioners should monitor LNG project FID timing and GPU supply chain constraints for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Africa Oilfield Services Market
Oil & Gas
Wellhead Equipment Market
Oil & Gas
Subsea Well Access System Market
Oil & Gas
LNG Storage Tank Market
Oil & Gas
Europe Wireline Logging Services Market
Oil & Gas
Smart Oilfield Market
Oil & Gas
Oriented Perforating System Market
Oil & Gas
Russia Oil and Gas EPC Market
Oil & Gas
Natural Gas Market
Oil & Gas
Kazakhstan Oil and Gas Midstream Market
Oil & Gas
Bunker Liners Market
Oil & Gas
United States Oil and Gas Pipeline Maintenance, Repair, Overhaul (MRO) Market
Oil & Gas
Kuwait Oil and Gas Upstream Market
Oil & Gas
Ecuador Wireline Logging Services Market
Oil & Gas
Casing Centralizer Market
Oil & Gas
Blockchain in Oil and Gas Market