
 Asia-Pacific Oilfield Services Market | 2026-2036
Asia-Pacific Oilfield Services Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Oilfield Services Market Outlook
China's dual carbon goals is realigning capital allocation across the Asia-Pacific oilfield services sector, elevating project-level emissions scrutiny and tightening contractor qualification thresholds. Schlumberger Ltd leverages its integrated drilling portfolio to anchor deepwater campaigns in Australian and Malaysian waters. Baker Hughes Co differentiates through turbomachinery and digital asset solutions that sustain margin in gas-weighted basins.
Asia-Pacific oilfield services encompass the technical provision of drilling, completion, production optimization, and intervention activities for hydrocarbon extraction, typically executed under reservoir pressure ratings exceeding 10,000 psi and temperatures surpassing 150°C to ensure well integrity in challenging formations. Drilling services dominate value capture given rig-day rates and consumables intensity, while Completion commands premium pricing in high-pressure high-temperature offshore environments where metallurgical specifications escalate. Production services, particularly artificial lift and enhanced oil recovery, represent the fastest-expanding technology category as operators target recovery factors above 35% in mature Southeast Asian fields.
China's MEE enforces methane intensity standards that shape contractor selection and equipment specification, while Australia's NOPSEMA mandates well-control certification that filters market access for international service providers. Japan's METI coordinates technology partnerships that channel domestic engineering capability into regional subsea projects. Stakeholders must monitor how divergent carbon-accounting rules across Beijing, Canberra, and Jakarta reshape the cost structure of integrated service contracts.
Market Dynamics
Capital reallocation under China's dual carbon goals is compressing conventional drilling timelines while accelerating gas-field development and emissions-reduction technology deployment across the Asia-Pacific oilfield services sector. National oil companies now embed carbon intensity thresholds directly into tender specifications, reshaping contractor qualification and equipment procurement patterns.
Growth Catalysts
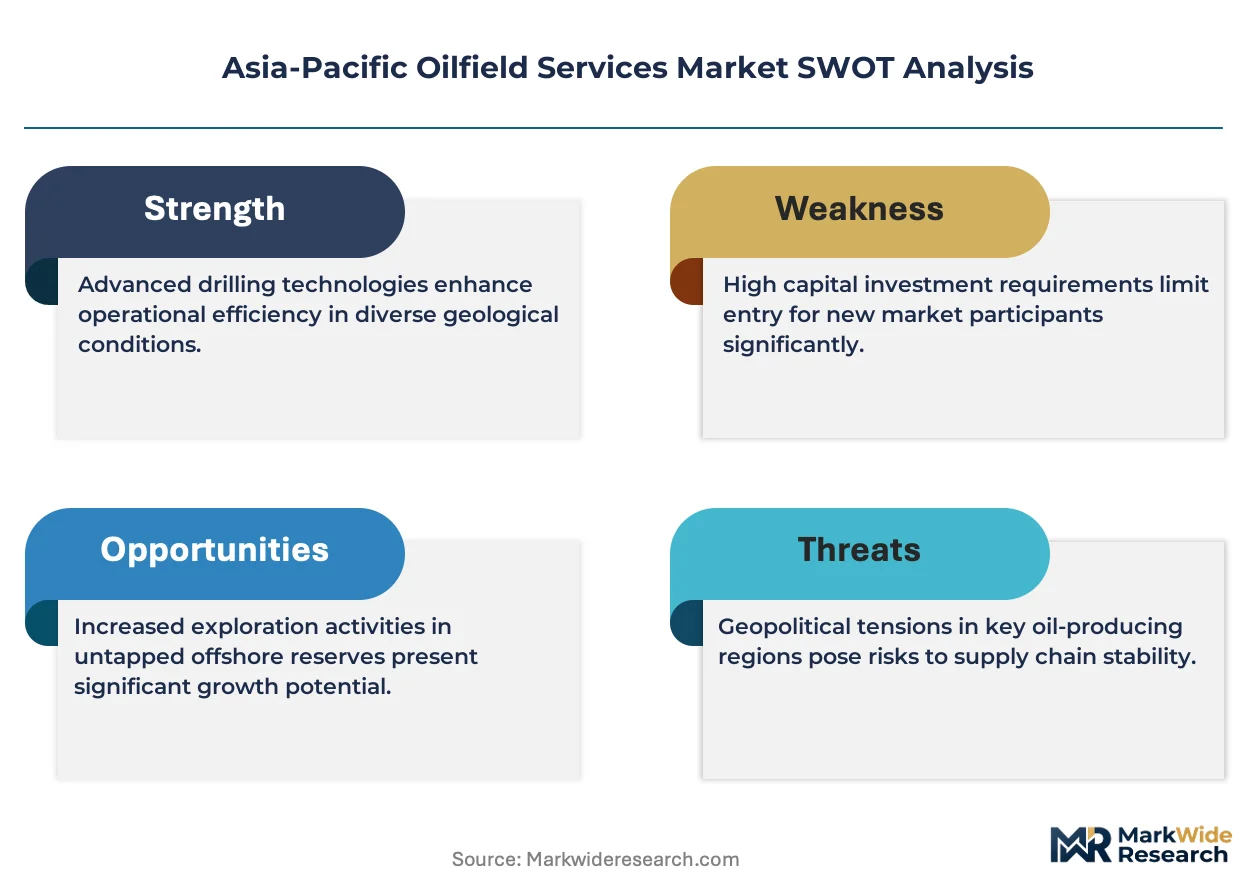
- Offshore exploration mandates:Australia's NOPSEMA and Malaysia's Petronas have expanded deepwater licensing rounds, driving demand for high-pressure high-temperature drilling packages in the Browse and Sabah basins.
- Methane intensity frameworks:China's MEE enforcement of fugitive emission standards is compelling operators to retrofit existing infrastructure with leak detection systems and electrified compression.
- Mature-field rejuvenation:Indonesia's Pertamina and Thailand's PTTEP are deploying chemical enhanced oil recovery in declining sandstone reservoirs, opening service contracts for polymer flooding and reservoir surveillance.
Market Restraints
- Specialized steel alloy costs:Nickel and molybdenum price volatility directly impacts blowout preventer manufacturing margins, with forgings sourced predominantly from Japanese and Korean mills.
- Rig fleet concentration:Premium jack-up availability clusters in Singapore and UAE shipyards, creating bottleneck risk for Southeast Asian campaign scheduling.
- Dual-use technology controls:Export licensing friction around directional drilling software and downhole telemetry systems delays equipment deployment in certain national waters.
Strategic Opportunities
- Decommissioning liability markets:Australia's Bass Strait and Malaysia's Dulang field are entering plug-and-abandonment phases, creating demand for P&A specialists and subsea cutting technologies.
- Carbon capture integration:Japan's METI-funded CCUS hubs in Tomakomai and Victoria's CarbonNet project require reservoir characterization and monitoring services from oilfield contractors.
- Digital twin convergence:Real-time drilling analytics fused with predictive maintenance platforms are enabling performance-based contracting models in Australian offshore developments.
Industry Challenges
- Deepwater metallurgical certification:Qualifying sour-service materials for HPHT wells exceeding 175°C and 15,000 psi requires 18-24 month testing protocols at accredited facilities.
- Cross-border crew mobility:Visa processing delays and divergent safety certification reciprocity between Australia, Indonesia, and Vietnam disrupt project staffing timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Oilfield Services Market |
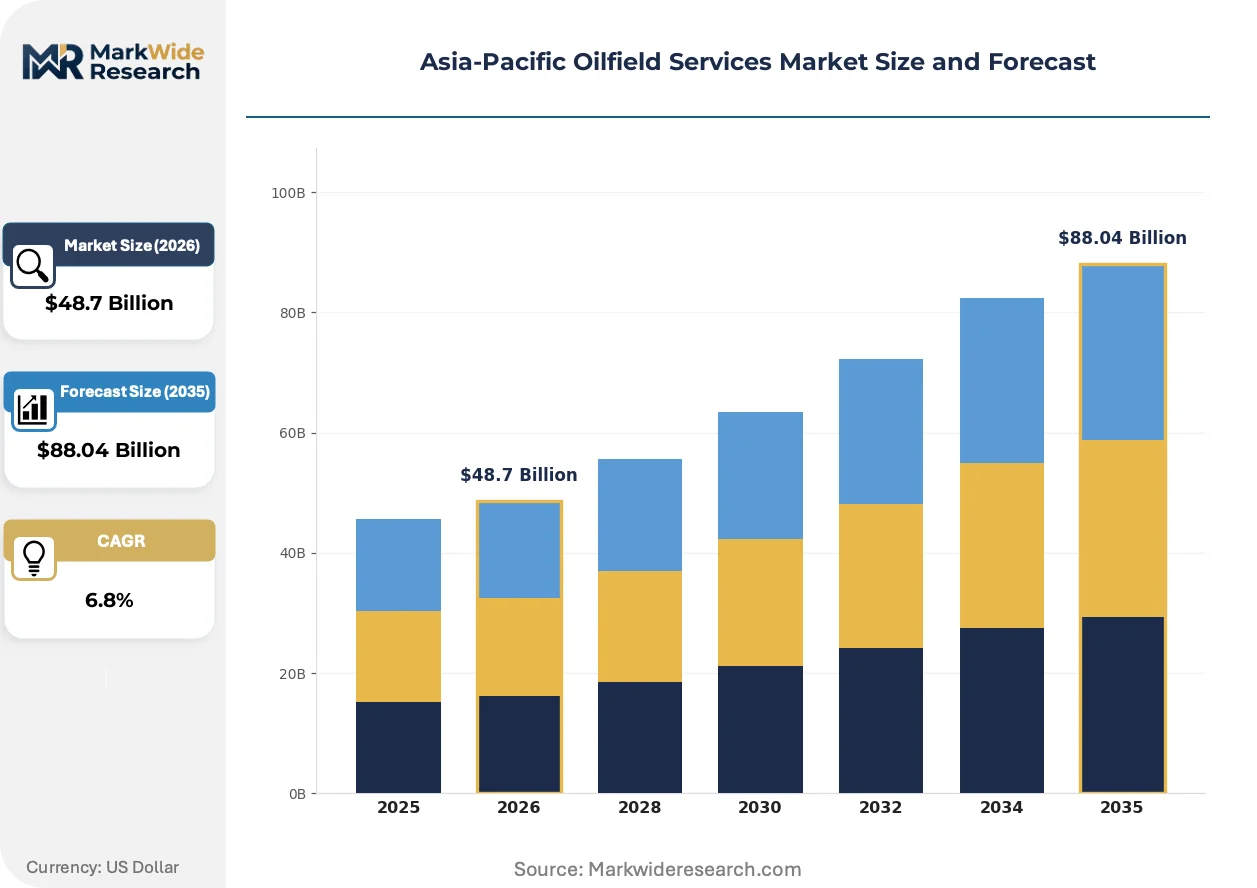
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Drilling, Completion, Production, Workover Technology: Automated Systems, Sensor Technologies, Enhanced Oil Recovery, Artificial Lift End User: Exploration Companies, Production Firms, Service Providers, Contractors Application: Onshore Operations, Offshore Activities, Shale Development, Mature Fields |
| Companies Covered | Schlumberger Ltd, Baker Hughes Co, Halliburton Co, National Oilwell Varco Inc, Weatherford International plc, Petrofac Limited, Superior Energy Services Inc, Expro Group, Archer Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Oilfield Services Market Strategic Shifts
Digital automation and emissions accountability are converging to redefine service delivery models across Asia-Pacific hydrocarbon basins. Contractors now compete on carbon-adjusted efficiency metrics rather than day-rate pricing alone.
Managed pressure drilling systems are modularizing across Australian and Malaysian deepwater campaigns, allowing operators to reconfigure pressure boundaries without pulling full strings. National oil companies in the region are adopting these systems for narrow-margin drilling in depleted reservoirs. The technology is modularizing service company offerings into rental-based, task-specific packages rather than integrated rig contracts.
Australia's Safeguard Mechanism reforms and Singapore's carbon tax escalation are forcing Scope 1 emissions disclosure across supply chains. Service providers must now submit verified carbon inventories to qualify for major tenders. Offshore drilling contractors in the Timor Sea and North West Shelf are responding by electrifying rig power systems and procuring renewable-backed shore power.
Integrated service contracts are fragmenting into discrete, performance-measured work packages as operator procurement teams seek granular accountability. National oil companies in Indonesia and Thailand are unbundling drilling, completions, and intervention scopes that were previously sole-sourced. This pattern is most visible in Pertamina's recent tender restructuring, where directional drilling, logging-while-drilling, and cementing services now attract separate vendor selection.
Asia-Pacific Oilfield Services Market Segmentation
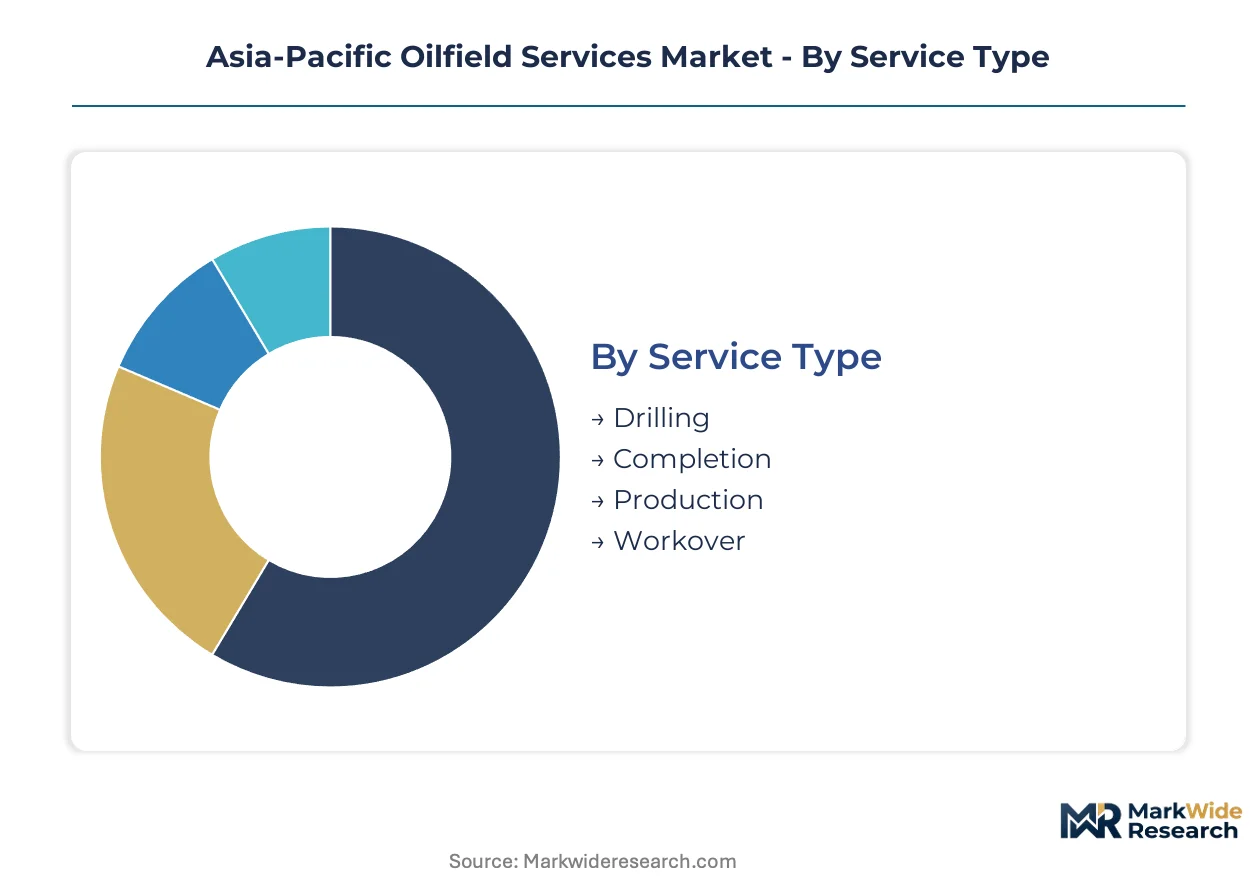
Service differentiation in Asia-Pacific oilfield services tracks reservoir complexity and carbon intensity mandates. Buyers segment procurement by pressure-temperature ratings, emissions accountability, and integration depth required for campaign execution.
Service Type:
Operator procurement teams differentiate vendors by equipment intensity and consumables cadence rather than labor hours alone.
- Drilling:Rig-day rates and consumables intensity anchor revenue capture, with high-pressure high-temperature packages commanding premium positioning in Australian and Malaysian deepwater basins. Demand concentrates where national oil companies expand Browse and Sabah basin licensing rounds.
- Completion:Metallurgical specifications escalate pricing in offshore environments exceeding 150°C and 10,000 psi, with sour-service materials requiring 18-24 month certification protocols. Australian North West Shelf developments drive specification tightening.
- Production:Artificial lift and enhanced oil recovery systems target recovery factors above 35% in Indonesia's and Thailand's mature sandstone reservoirs.
- Workover:Intervention campaigns for well integrity restoration and recompletion sustain contractor utilization in Vietnam's and Australia's aging asset base.
Drilling leads volumes today; Completion is gaining share fastest.
Technology:
Carbon-adjusted efficiency metrics now shape technology procurement more than day-rate pricing alone.
- Automated Systems:Managed pressure drilling modularization allows pressure boundary reconfiguration without pulling full strings, narrowing margins in depleted reservoirs. Australia's Safeguard Mechanism reforms accelerate electrified rig power adoption.
- Sensor Technologies:Real-time drilling analytics fused with predictive maintenance enable performance-based contracting in Timor Sea developments. Leak detection retrofits respond to China's MEE methane intensity enforcement.
- Enhanced Oil Recovery:Chemical flooding and polymer injection open service contracts for Pertamina and PTTEP field rejuvenation programs.
- Artificial Lift:Electric submersible pumps and gas lift systems sustain production from declining Southeast Asian brownfields.
Sensor Technologies leads volumes today; Automated Systems is climbing the fastest.
End User:
Risk allocation preferences determine whether operators outsource integrated campaigns or unbundle discrete work packages.
- Exploration Companies:Early-phase operators prioritize directional drilling and logging-while-drilling services for frontier basin appraisal, with procurement unbundling accelerating across Indonesian and Thai tender structures.
- Production Firms:Established operators driving Indonesia's Pertamina and Thailand's PTTEP chemical enhanced oil recovery deployment.
- Service Providers:Subcontractor networks supplying specialized crews and equipment for cross-border campaign staffing.
- Contractors:Integrated service companies anchoring deepwater drilling packages in Australian and Malaysian waters.
Production Firms lead volumes today; Exploration Companies is expanding most quickly.
Application:
Reservoir depletion stage and water depth dictate equipment specification and regulatory compliance burden.
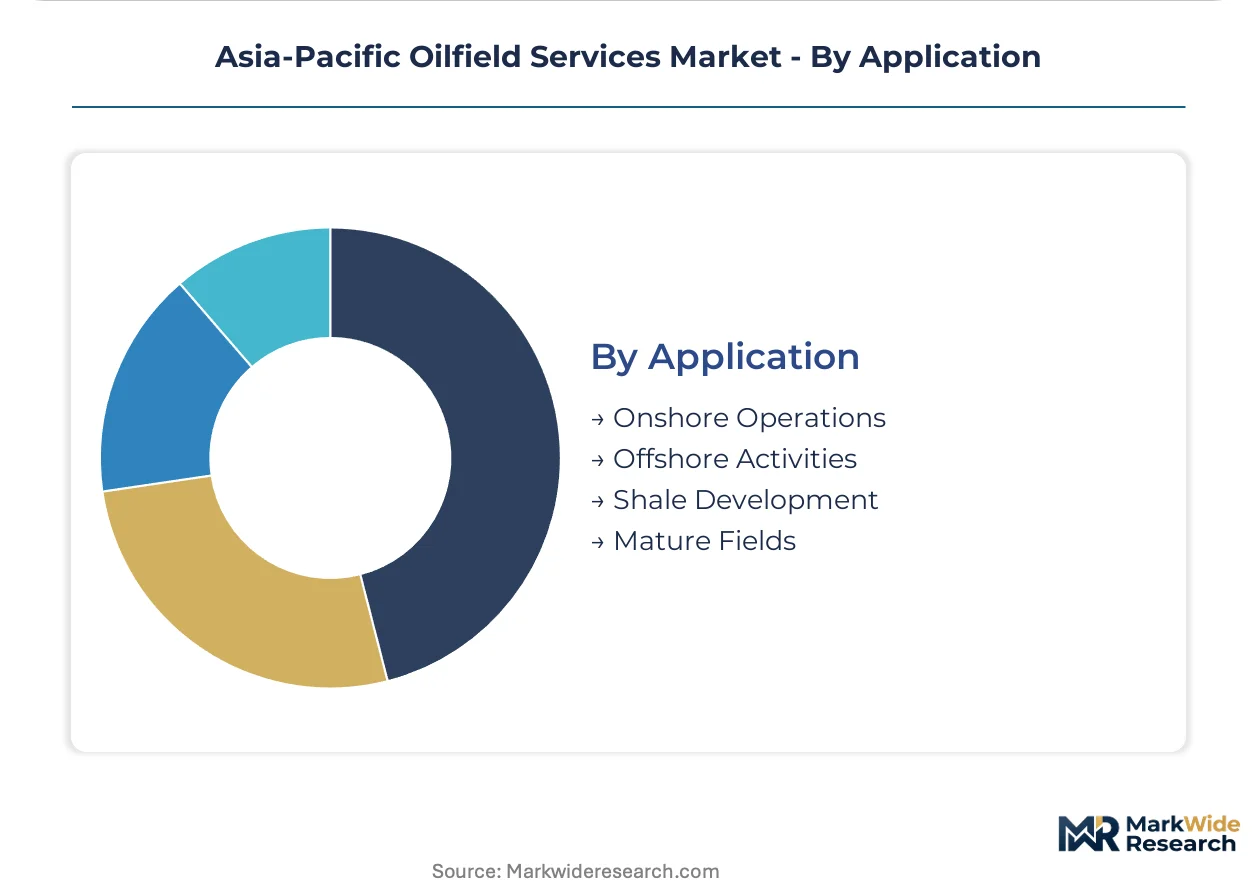
- Onshore Operations:Conventional drilling and workover services in China and Indonesia's mature sedimentary basins, with capital reallocation compressing conventional timelines under dual carbon goals.
- Offshore Activities:Deepwater HPHT drilling packages in Australia's Browse basin and Malaysia's Sabah waters, where NOPSEMA and Petronas licensing expansion drives specification escalation.
- Shale Development:Hydraulic fracturing and horizontal completion services, limited in Asia-Pacific relative to North American scale but emerging in China's Sichuan basin.
- Mature Fields:Rejuvenation programs across Southeast Asia's declining sandstone reservoirs, where recovery factor targets above 35% stimulate chemical flooding and reservoir surveillance demand.
Onshore Operations lead volumes today; Offshore Activities is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized engineering talent pools in Perth, Kuala Lumpur, and Singapore anchor the Asia-Pacific oilfield services geography, concentrating deepwater expertise and subsea fabrication capability in these coastal clusters.
China
Sichuan basin shale development and offshore gas-field expansion in the South China Sea drive service demand for horizontal drilling and completion packages. China's MEE enforces methane intensity standards that filter contractor selection and equipment procurement. Tianjin and Shenzhen host fabrication yards where domestic contractors assemble high-pressure blowout preventers for regional deployment.
Australia
Browse basin deepwater licensing and Bass Strait decommissioning programs sustain demand for HPHT drilling and plug-and-abandonment specialists. Australia's NOPSEMA mandates well-control certification that restricts market access for uncredentialed international providers. Perth anchors the regional headquarters of major integrated service companies managing North West Shelf campaigns.
Malaysia
Petronas-expanded Sabah basin licensing rounds and mature-field rejuvenation in Peninsular Malaysia drive tender activity for drilling and enhanced oil recovery services. Malaysia's national oil company embeds local content requirements that shape subcontractor selection. Kuala Lumpur concentrates regional procurement decision-making and engineering support for offshore campaigns.
Indonesia
Pertamina's chemical flooding programs in Sumatra and Java target recovery factors above 35% in declining sandstone reservoirs. Indonesia's upstream regulator mandates domestic utilization certificates that influence service provider structuring. Batam island hosts supply bases supporting cross-border mobilization to Vietnamese and Thai waters.
Thailand
PTTEP's polymer injection campaigns in the Gulf of Thailand and onshore mature fields sustain production optimization service contracts. Thailand's Board of Investment offers tax incentives for oilfield technology localization that redirect capital allocation. Rayong province clusters manufacturing and maintenance facilities serving regional offshore operations.
Asia-Pacific Oilfield Services Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the Asia-Pacific oilfield services sector, creating a tiered structure where integrated portfolio breadth anchors premium positioning. The market consolidates around three strategic archetypes: full-service international contractors, regional specialists with national oil company relationships, and technology-focused niche providers. Competitive moves center on modular service unbundling to capture unilateral procurement mandates and carbon-adjusted efficiency guarantees that meet tightening tender specifications.
Among Houston-based integrated contractors, Schlumberger Ltd and Baker Hughes Co exemplify the full-service archetype with portfolios spanning drilling through production optimization. Halliburton Co occupies a comparable position anchoring completion and intervention capabilities in Australian and Southeast Asian waters. These entities represent the scale-driven tier where integrated project delivery and reservoir characterization expertise filter access to high-specification offshore campaigns.
| Leading Market Players |
|---|
| Schlumberger Ltd |
| Baker Hughes Co |
| Halliburton Co |
| National Oilwell Varco Inc |
| Weatherford International plc |
| Petrofac Limited |
| Superior Energy Services Inc |
| Expro Group |
| Archer Limited |
| Others |
Value Chain & Pricing Dynamics
Nickel and molybdenum price volatility on the London Metal Exchange cascades through forged alloy supply chains into tiered contractor pricing across HPHT drilling packages. Buyers in Australian and Malaysian deepwater basins now face carbon-adjusted rate premiums that embed Scope 1 emissions compliance costs into day-rate structures.
Pricing Analysis
Bundled integrated service contracts are fragmenting into discrete unbundled work packages across Indonesian and Thai tender structures. Three-tier pricing structure across premium HPHT, standard offshore, and economy onshore levels reflects metallurgical certification grade and after-sales service bundling. Cost compression in standard-tier drilling packages is intensifying because national oil companies unbundle procurement scopes. Exploration companies exhibit highest price sensitivity; integrated contractors anchoring Browse basin campaigns show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and Korean steel mills supplying sour-service alloy forgings for blowout preventer manufacturing. Geographic supply concentration clusters in Singapore, UAE, and South Korean shipyards for premium jack-up rig fabrication. Raw material dependencies draw from nickel, molybdenum, and high-grade chromium steel feedstock. Tariff exposure around directional drilling software export licensing creates deployment delays. Distribution runs through Batam island supply bases and Perth logistics hubs serving regional offshore campaigns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where capital is reallocating toward gas-field development and emissions-reduction technologies that demand premium contractor specifications.
For Market Incumbents: Deploy modular service unbundling to capture Pertamina's discrete procurement mandates while anchoring integrated Browse basin positions. Backward integration into blowout preventer forging supply reduces Japanese mill dependency. Invest in MEE-compliant methane detection certification to defend against emerging digital-native competitors. For New Entrants and Emerging Players: Enter via Bass Strait plug-and-abandonment specialization where decommissioning liability markets lack incumbent density. Target Australia's carbon capture integration projects requiring reservoir characterization services. Lead with electrified rig power retrofits as the go-to-market wedge against legacy diesel fleets. For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists holding Petronas and PTTEP relationships in Malaysian and Thai waters. Five-to-ten year viability hinges on gas-weighted basin exposure and CCUS service capability buildout. Monitor China's dual carbon enforcement intensity as the inflection signal for conventional drilling compression timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Service Unbundling | Captures Pertamina's discrete procurement mandates while maintaining HPHT premium positioning. |
| Backward Integration into Forging Supply | Reduces Japanese mill dependency and stabilizes blowout preventer margin exposure. |
| Electrified Rig Power Retrofit | Aligns with Australia's Safeguard Mechanism reforms and Singapore carbon tax escalation. |
| CCUS Service Capability Buildout | Positions contractors for METI-funded Tomakomai and Victoria CarbonNet project demand. |
| Decommissioning Liability Specialization | Captures Bass Strait and Dulang field plug-and-abandonment contract flows. |
Study Parameters
Coverage spans China, Australia, Malaysia, Indonesia, and Thailand, with primary inputs from each market cluster combining interviews with drilling contractors, national oil company procurement leads, subsea fabrication yard managers, and regulatory compliance officers. Secondary validation draws from NOPSEMA well-control certification databases, MEE methane intensity enforcement records, Petronas licensing round disclosures, and ASEAN customs trade data. Bottom-up rig fleet utilization models triangulate against top-down capital expenditure tracking across national oil company budgets.
Granularity-level modeling disaggregates service type, technology category, pressure-temperature rating tier, and carbon intensity compliance grade across the projection horizon. Analytical framework approach segments by drilling, completion, production, and workover scopes with end-user risk allocation preferences. CAGRs derive from rig-day rate trajectories, equipment procurement backlogs, and regulatory enforcement intensity indices. Forecast inputs incorporate dual carbon goal capital reallocation timelines and HPHT well count projections in Browse and Sabah basins.
Inputs from national oil company tender disclosures and regulatory certification databases were available through the study window; gaps in real-time contractor carbon inventory verification introduce uncertainty bands around emissions-adjusted pricing assumptions. Forecasts reflect documented assumptions around methane enforcement intensity and metallurgical testing protocol durations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Middle-East and Africa Frac Stack Market
Oil & Gas
Oilwell Spacer Fluids Market
Oil & Gas
United States Natural Gas Market
Oil & Gas
North America Proppants Market
Oil & Gas
Oil and Gas Separator Market
Oil & Gas
Vietnam Oil and Gas Midstream Market
Oil & Gas
APAC Oil and Gas Automation Market
Oil & Gas
Iraq Oil and Gas Market
Oil & Gas
Polycrystalline Diamond Compact (PDC) Drill Bit Market
Oil & Gas
India LNG Bunkering Market
Oil & Gas
Mineral Oil and Mineral Spirit Market
Oil & Gas
Kazakhstan Oil and Gas Market
Oil & Gas
Electric Fracking Market
Oil & Gas
Europe Intelligent Pigging Market
Oil & Gas
Geothermal Drilling Market
Oil & Gas
South America Oil and Gas Hoses and Coupling Market