
 United States Oil and Gas Market | 2026-2036
United States Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
United States Oil and Gas Market Analytics
The Permian Basin is reconfiguring national supply geography as pipeline capacity additions link West Texas to Gulf Coast export terminals. ExxonMobil Corporation leverages its integrated Permian-to-Gulf Coast infrastructure to capture margin across upstream and downstream stages. Chevron Corporation anchors its growth program in the Delaware sub-basin with extended horizontal laterals and centralized water handling. ConocoPhillips competes through capital discipline and portfolio concentration in Alaska and the Lower 48.
United States oil and gas encompasses crude petroleum and natural gas extraction, processing, and transport through onshore and offshore systems operating at pressures from 2,000 to 15,000 psi and temperatures requiring specialized metallurgy. The sector supplies feedstock for power generation, manufacturing, transportation fuels, and petrochemicals. Upstream service categories dominate capital allocation as operators deploy hydraulic fracturing and enhanced oil recovery technologies to offset decline curves in mature fields. Downstream refining segments face structural margin pressure from renewable fuel standards and electrification trends in transportation end-use markets.
EPA methane regulations and the Inflation Reduction Act's waste emissions charge reshape upstream economics by penalizing uncaptured venting and flaring above specified thresholds. FERC certificate policies for interstate natural gas pipelines add procedural complexity to midstream project timelines. OSHA process safety management standards enforce mechanical integrity protocols at refining and petrochemical facilities. Stakeholders must monitor how federal permitting reform proposals and state-level setback rules alter the cost structure of new drilling programs.
Market Dynamics
The Permian Basin's associated gas output is reconfiguring midstream investment flows as ethane extraction capacity races to match Gulf Coast cracker demand. Pipeline buildouts linking West Texas to Corpus Christi and Houston export terminals are compressing regional price differentials while EPA methane rules under the Inflation Reduction Act impose new compliance costs on venting and flaring.
Growth Catalysts
- Petrochemical Feedstock Demand:Gulf Coast ethylene crackers are expanding intake capacity as Permian ethane supply volumes climb. Dow and LyondellBasell facility expansions in Texas are pulling incremental NGL volumes through new fractionation trains.
- FERC Certificate Policies:Interstate natural gas pipeline approvals, though procedurally complex, are clearing backlog for Appalachian and Permian takeaway projects. Certificate issuance timelines are stabilizing after procedural reforms.
- Enhanced Oil Recovery:CO2 injection projects in the Permian and West Texas are extending field life in mature reservoirs. Occidental Petroleum and Kinder Morgan infrastructure partnerships are lowering carbon capture costs for tertiary recovery.
Market Restraints
- Steel Input Volatility:Line pipe and OCTG steel prices fluctuate with tariff exposure and domestic mill capacity. Section 232 exclusions for Canadian and Mexican supply remain contested.
- Midstream Concentration Risk:Permian takeaway capacity is controlled by a limited set of pipeline operators. Bottleneck risk resurfaces when production growth outpaces scheduled expansion in-place dates.
- Renewable Fuel Substitution:California LCFS credits and federal RFS mandates are compressing refining margins for conventional gasoline. Renewable diesel capacity additions in Louisiana and Texas are accelerating fuel-switching.
Strategic Opportunities
- Carbon Capture Infrastructure:45Q tax credits under the Inflation Reduction Act are subsidizing CO2 transport and sequestration projects. The Texas Gulf Coast salt dome formations offer storage geology for captured emissions.
- Hydrogen Hub Development:Appalachian and Gulf Coast regional clean hydrogen hubs are securing DOE funding for blue hydrogen production. Natural gas reforming with CCS is the incumbent pathway competing with electrolysis.
- Permian Delaware Sub-basin:Lea and Eddy counties in New Mexico hold underdeveloped stacked pay zones. Extended lateral drilling and pad development are improving capital efficiency in this geography.
Industry Challenges
- Process Safety Engineering Talent:OSHA PSM compliance and mechanical integrity programs require specialized inspectors and reliability engineers. The aging workforce in refining and petrochemicals is creating knowledge transfer gaps.
- Legacy SCADA Integration:Upstream operators are patching decades-old control systems with modern IoT monitoring. Cybersecurity hardening of OT networks is lagging IT infrastructure upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Oil and Gas Market |
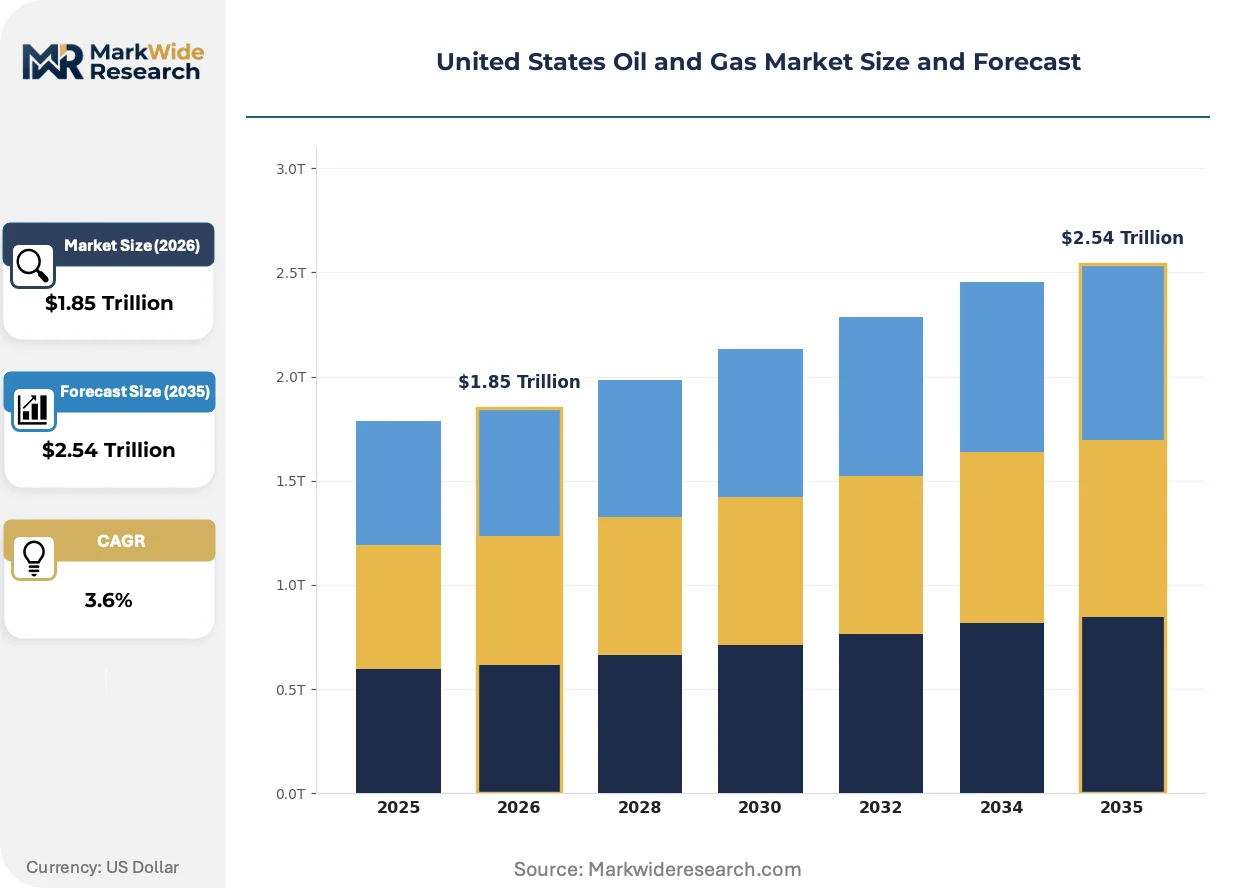
| Market Size in 2026 | $1.85 Trillion |
| Market Size in 2035 | $2.54 Trillion |
| CAGR (2026 – 2036) | 3.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Exploration, Production, Refining, Distribution Service Type: Upstream, Midstream, Downstream, Consulting Technology: Automation, Hydraulic Fracturing, Offshore Drilling, EOR End User: Power Generation, Manufacturing, Transportation, Petrochemicals |
| Companies Covered | ExxonMobil Corporation, Chevron Corporation, ConocoPhillips, Marathon Petroleum Corporation, Phillips 66, Valero Energy Corporation, EOG Resources, Occidental Petroleum, Williams Companies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Oil and Gas Market Evolving Landscape
Digitalization and emissions monitoring are converging to reshape operational economics across the US oil and gas value chain. Operators are deploying sensor networks and automation to reduce labor intensity while satisfying tightening environmental compliance thresholds.
Electrification of drilling rigs and hydraulic fracturing fleets is hybridizing power systems in the Permian and Eagle Ford. Producers such as Chesapeake Energy and EOG Resources are contracting grid power and on-site solar to displace diesel generators. This technology is hybridizing cost structures—reducing fuel logistics while introducing new dependency on utility interconnection timelines and transmission availability.
EPA's waste emissions charge under the Inflation Reduction Act is imposing direct fees on methane venting above specified intensity thresholds. Upstream operators in the Permian and Bakken are accelerating LDAR program deployment and investing in vapor recovery units. Small-to-mid-size independents without integrated gas processing are most affected and are responding by divesting non-core, high-emitting assets or seeking midstream processing partnerships.
Buyers of natural gas for power generation and industrial heat are consolidating procurement through long-term offtake agreements with price collars. Merchant power utilities and data center developers are bypassing traditional spot market exposure and contracting directly with Permian and Haynesville producers. This pattern is most visible in Texas and Louisiana, where ERCOT grid expansion and Gulf Coast industrial demand are concentrating buyer negotiating leverage.
United States Oil and Gas Market Segmentation
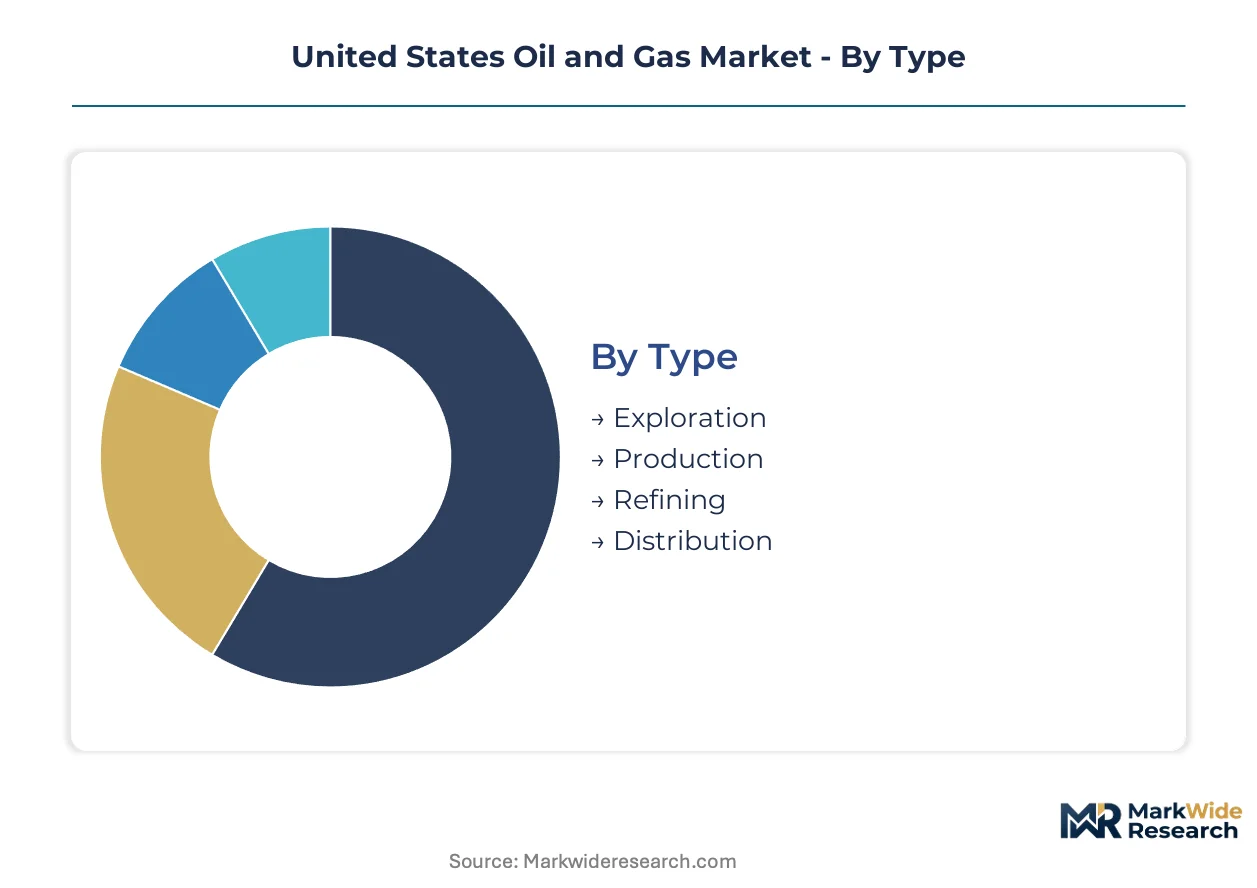
Segmentation in the United States oil and gas market reveals how capital cycles, regulatory exposure, and technology adoption vary across operational stages. Understanding these divisions allows stakeholders to match investment horizons to asset turnover rates and compliance obligations.
Type:
Exploration turns over fastest as seismic programs and lease acquisitions cycle quarterly, while refining assets lock capital for decades with long-dated permitting and construction timelines.
- Exploration:Geophysical surveying and lease acquisition activities precede drilling commitment decisions. Permian and Delaware Basin operators in Texas and New Mexico are accelerating 3D seismic deployment to derisk stacked pay zones before pad development.
- Production:Well completion and hydrocarbon extraction operations span onshore and offshore environments. Associated gas volumes from West Texas oil wells are forcing rapid midstream processing partnerships to avoid EPA methane penalties under IRA waste emissions charges.
- Refining:Crude processing into transportation fuels and petrochemical feedstock operates at fixed locations with extended asset lives. Gulf Coast facilities face margin compression from California LCFS credits and federal renewable fuel standards accelerating fuel substitution.
- Distribution:Product logistics through pipelines, rail, and marine terminals connects production to demand centers. FERC interstate certificate policies add procedural complexity to new pipeline timelines while stabilizing after recent reforms.
Refining dominates installed base by capital employed. Exploration is where expansion concentrates as operators rebuild inventory after years of underinvestment.
Service Type:
Upstream services command premium pricing during drilling upswings, while midstream contracts generate stable fee revenue insulated from commodity volatility.
- Upstream:Drilling, completion, and production services deploy specialized equipment and labor to extract hydrocarbons. Hydraulic fracturing fleets in the Permian are electrifying to reduce diesel logistics costs and satisfy ESG procurement criteria from integrated majors.
- Midstream:Gathering, processing, and transport infrastructure handles raw production before refining. Permian ethane extraction capacity is racing to match Gulf Coast cracker demand as Dow and LyondellBasell expand Texas facilities.
- Downstream:Refining and marketing services convert crude into finished products. Renewable diesel capacity additions in Louisiana and Texas are reshaping traditional fuel margin structures.
- Consulting:Technical advisory and regulatory compliance support spans reservoir engineering to emissions accounting. EPA methane rule implementation is driving demand for LDAR program design and vapor recovery unit optimization.
Midstream dominates installed base through pipeline and processing plant ownership. Upstream is where expansion concentrates as rig counts recover and lateral lengths extend.
Technology:
Automation platforms refresh on 3-5 year software cycles, while offshore drilling assets require 20-year amortization schedules.
- Automation:Digital control systems, sensor networks, and predictive analytics optimize field operations. IoT deployment for emissions monitoring is accelerating under IRA waste emissions charge compliance deadlines.
- Hydraulic Fracturing:High-pressure fluid injection creates reservoir permeability in tight formations. Extended lateral drilling in the Delaware sub-basin is improving capital efficiency per wellbore.
- Offshore Drilling:Deepwater and shelf production systems operate in marine environments with specialized metallurgy. Gulf of Mexico projects face longer development timelines but deliver production profiles spanning decades.
- EOR:Enhanced oil recovery through CO2 injection or thermal methods extends mature field life. Occidental Petroleum and Kinder Morgan partnerships are lowering carbon capture costs for tertiary recovery in the Permian.
Hydraulic fracturing dominates installed base by well count. Automation is where expansion concentrates as operators retrofit legacy SCADA and deploy continuous emissions monitoring.
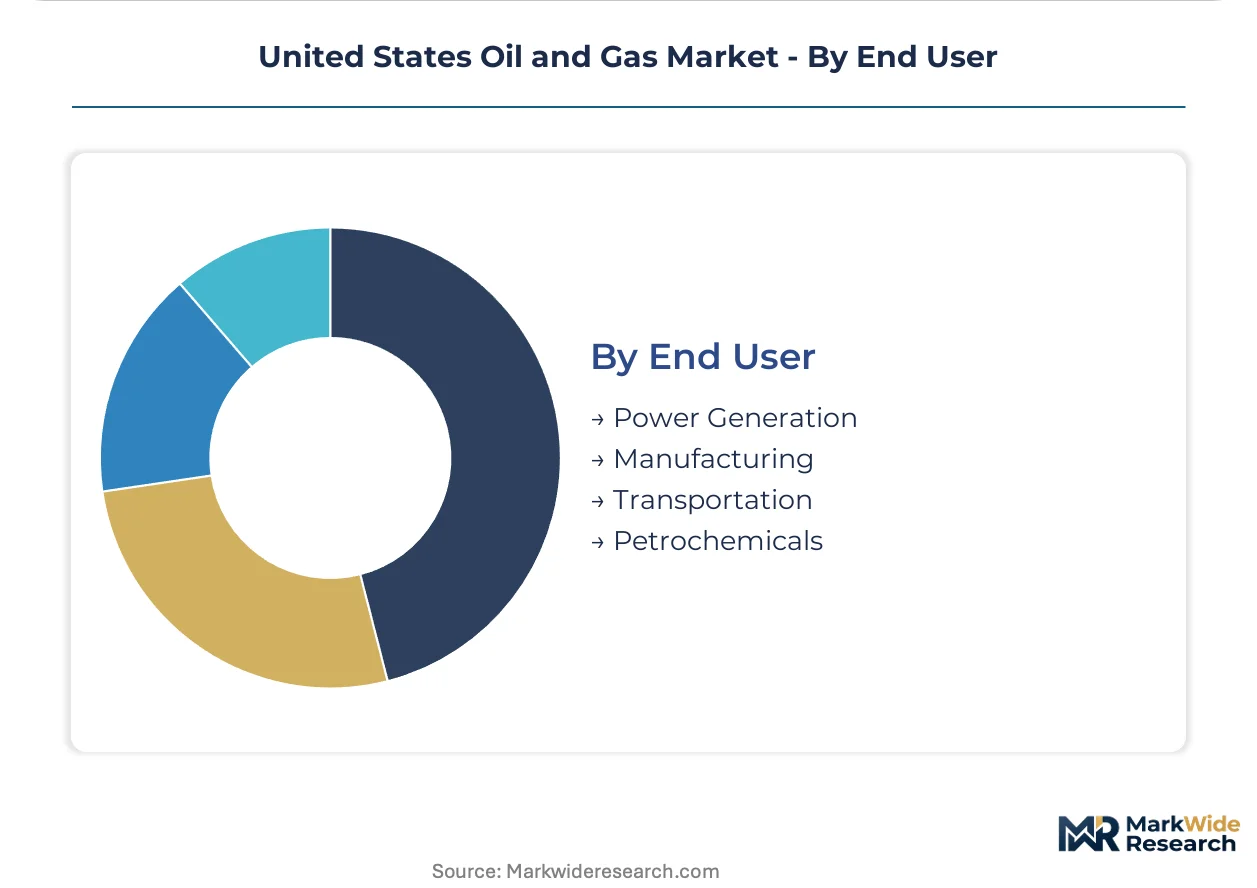
End User:
Transportation fuel demand turns over with vehicle fleet replacement, while petrochemical feedstock contracts run 10-15 years.
- Power Generation:Natural gas-fired turbines and reciprocating engines produce electricity. ERCOT grid expansion in Texas is concentrating buyer negotiating leverage for long-term offtake agreements with Permian and Haynesville producers.
- Manufacturing:Industrial heat and process energy from natural gas and petroleum products. Data center developers are bypassing spot markets to contract directly with producers for baseload supply.
- Transportation:Liquid fuels for road, rail, air, and marine movement. Electrification trends and renewable diesel substitution are compressing conventional gasoline refining margins.
- Petrochemicals:Ethane, propane, and naphtha feedstock for plastics and chemical synthesis. Gulf Coast ethylene crackers are expanding intake capacity as Permian NGL supply volumes climb.
Transportation dominates installed base by volume consumed. Petrochemicals is where expansion concentrates as cracker capacity additions pull incremental NGL through new fractionation trains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin pipeline network anchors national supply geography as takeaway capacity additions link West Texas production to Gulf Coast export terminals. This infrastructure underwrites the concentration of drilling activity and midstream investment across the southwestern United States.
Texas
Houston and Corpus Christi petrochemical complexes drive ethane demand as Permian associated gas volumes climb. EPA methane regulations under the Inflation Reduction Act impose waste emissions charges on venting and flaring above specified thresholds. The Permian Delaware sub-basin in West Texas concentrates extended lateral drilling programs and centralized water handling infrastructure.
New Mexico
Lea and Eddy counties hold underdeveloped stacked pay zones in the Delaware Basin. State-level environmental regulations complement federal IRA compliance requirements for upstream operators. Carlsbad and Hobbs anchor oilfield service clustering and workforce concentration for drilling programs.
Louisiana
Gulf Coast refineries and LNG export terminals pull natural gas from Haynesville and Permian supply basins. FERC certificate policies for interstate pipelines add procedural complexity to midstream project timelines. Lake Charles and Cameron Parish concentrate LNG liquefaction capacity and carbon capture project development.
North Dakota
Bakken crude production generates associated gas volumes requiring processing capacity expansion. EPA methane rules under the Inflation Reduction Act penalize uncaptured venting from older well completions. Williston Basin operators are accelerating LDAR program deployment and vapor recovery unit investment.
Pennsylvania
Appalachian Marcellus and Utica shale production supplies Northeast and Gulf Coast demand centers through interstate pipeline networks. FERC interstate certificate issuance timelines are stabilizing after procedural reforms. Pittsburgh anchors regional headquarters activity for upstream and midstream operators.
United States Oil and Gas Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the services and equipment layers. The United States oil and gas sector exhibits tiered consolidation with integrated majors controlling midstream-to-downstream value chains and independents concentrating in single-basin upstream positions. Three archetypes dominate: Permian-to-Gulf Coast integrated operators, Delaware Basin pure-play producers, and Appalachian gas-focused independents. Competitive moves center on portfolio concentration through asset divestitures and carbon capture infrastructure partnerships.
Among integrated majors, ExxonMobil Corporation and Chevron Corporation exemplify the Permian-to-Gulf Coast platform archetype with control over upstream production, midstream takeaway, and downstream refining capacity. ConocoPhillips occupies a position representing capital discipline and Lower 48 portfolio concentration without integrated downstream exposure. These three companies anchor the competitive structure through their respective strategic postures on vertical integration, basin focus, and capital allocation rigor.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Chevron Corporation |
| ConocoPhillips |
| Marathon Petroleum Corporation |
| Phillips 66 |
| Valero Energy Corporation |
| EOG Resources |
| Occidental Petroleum |
| Williams Companies |
| Others |
Value Network & Pricing Analysis
Permian-to-Gulf Coast pipeline corridors compress regional price differentials while concentrating supply control among integrated operators with captive transport infrastructure. This logistics architecture grants volume shippers pricing leverage over spot-market participants and forces midstream-dependent producers into long-term offtake commitments with embedded price collars.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates hydrocarbon transactions. Premium tier captures Gulf Coast ethane delivered under index-plus contracts with quality guarantees; standard tier reflects Henry Hub-linked natural gas with basis adjustments; economy tier absorbs distressed production from flaring-constrained wells facing EPA waste emissions charges. Price differentiation hinges on transport access and methane intensity certification. Pricing pressure stems from renewable diesel substitution eroding conventional refining margins. Merchant power utilities exhibit highest price sensitivity; integrated petrochemical operators with captive supply show least.
Supply Chain Analysis
Export-control regimes under BIS regulations restrict advanced drilling and subsea technology flows to sanctioned jurisdictions, concentrating equipment sourcing among domestic and allied-nation suppliers. The United States draws line pipe from domestic mills and Canadian exempt sources; OCTG steel feeds from integrated US producers; specialized downhole electronics import from Japan and Western Europe. Single-source vulnerability concentrates in high-pressure pumping equipment. Distribution runs through pipeline gathering systems into fractionation trains, then via marine terminals to export markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as Permian ethane extraction capacity races to match Gulf Coast cracker demand growth. Petrochemical feedstock pull-through from Dow and LyondellBasell facility expansions provides durable offtake visibility absent in prior commodity cycles.
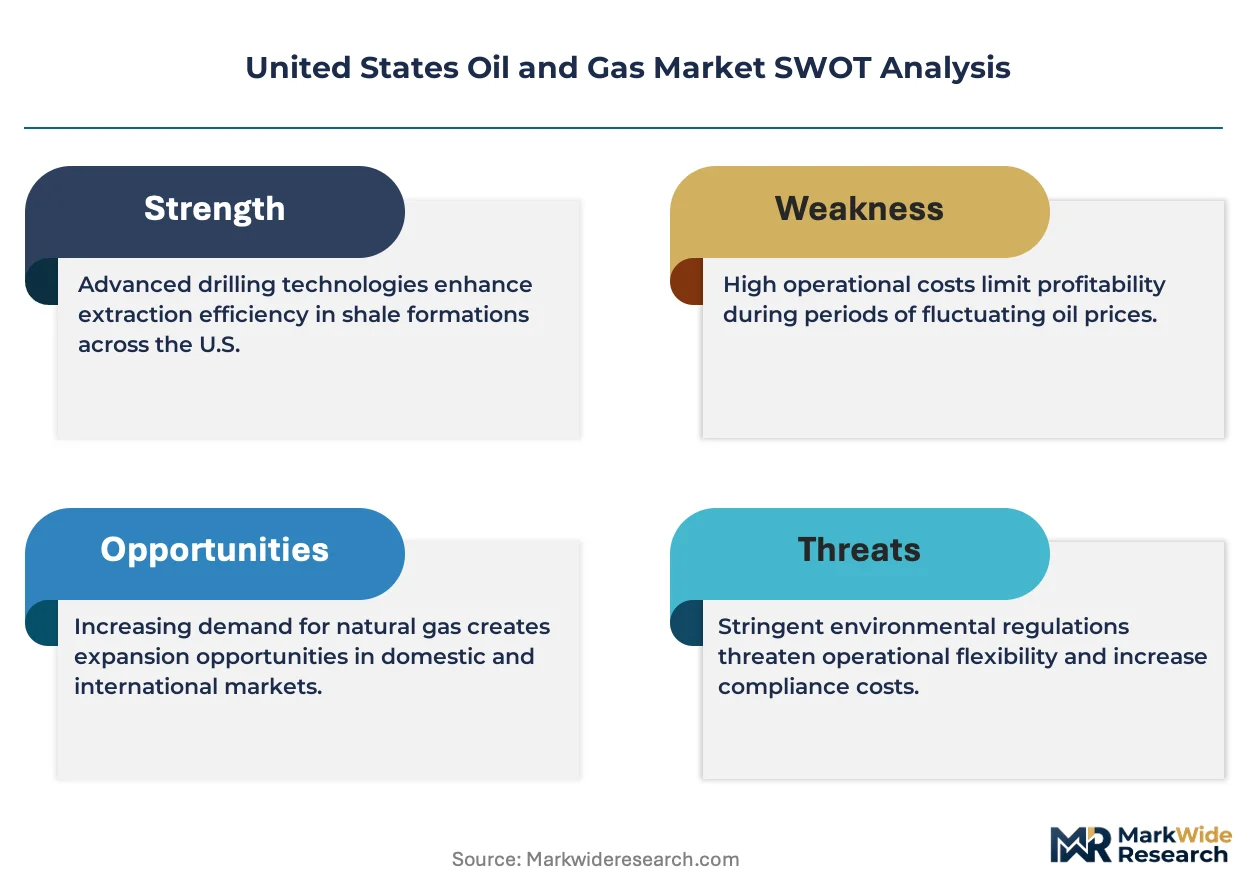
For Market Incumbents: Entrench position through backward integration into carbon capture infrastructure and Delaware Basin water handling systems. EPA methane compliance thresholds threaten non-integrated independents with stranded asset risk. Captive CO2 transport networks and salt dome sequestration partnerships lock in tertiary recovery economics while insulating against 45Q credit competition. For New Entrants and Emerging Players: Build out specialized emissions monitoring and LDAR program management services targeting small-to-mid-size Permian operators lacking in-house environmental compliance teams. Lea and Eddy counties in New Mexico present the most penetrable geography with underdeveloped stacked pay zones and less concentrated leasehold positions. Go-to-market through midstream processing partnerships that bundle methane capture with gas processing contracts. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated majors divesting non-core, high-emitting assets to concentrate capital in Permian-to-Gulf Coast corridors. Long-term viability frames around operators with pipeline access and low methane intensity profiles. Watch FERC certificate issuance velocity as inflection signal—accelerated approvals unlock midstream valuation re-rating; procedural delays compress producer netbacks and trigger consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Infrastructure Partnership | 45Q tax credits subsidize Occidental-Kinder Morgan CO2 transport networks for tertiary recovery economics. |
| Permian Ethane Extraction Capacity Buildout | Dow and LyondellBasell expansions pull incremental NGL through new fractionation trains. |
| Electrified Fracturing Fleet Deployment | Chesapeake and EOG displace diesel generators with grid power and on-site solar. |
| Long-term Power Purchase Agreement | ERCOT data center developers bypass spot markets to contract directly with Haynesville producers. |
| Hydrogen Hub Development | Appalachian and Gulf Coast hubs secure DOE funding for blue hydrogen with CCS pathways. |
Research Methodology
A spread of perspectives from upstream operations executives, midstream project developers, petrochemical procurement leads, and environmental compliance officers converged on the working assumptions. Primary interviews combined with secondary validation through EIA production data, FERC pipeline filings, EPA emissions inventories, and SEC 10-K disclosures. Bottom-up well-level production estimates triangulated against top-down basin supply-demand balances.
Demand-supply-balance framing anchored the analytical framework across the analysis window. Segmentation modeled operational type, service category, technology platform, and end-use application. CAGRs derived from production growth trajectories, capacity expansion schedules, and regulatory compliance cost curves. Forecast inputs incorporated ethane cracker buildout timelines and IRA methane charge implementation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by pure-play carbon capture developers or hydrogen hub consortiums would shift outcomes. Material shifts in FERC certificate policy timelines or EPA enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Europe Oil and Gas Electric Submersible Pump Market
Oil & Gas
Oil and Gas Asset Integrity Management Services Market
Oil & Gas
Norway Oil and Gas Upstream Market
Oil & Gas
Well Intervention Service Market
Oil & Gas
Well Cementing Market
Oil & Gas
Planned LNG Market
Oil & Gas
Europe Oilfield Chemicals Market
Oil & Gas
Middle East and Africa Early Production Facility Market
Oil & Gas
Desalter Market
Oil & Gas
Cuttings Re-Injection Services Market
Oil & Gas
South America Oil and Gas Hoses and Coupling Market
Oil & Gas
Saudi Arabia Drilling Rigs Market
Oil & Gas
Marine Oil Water Separators Market
Oil & Gas
United States Natural Gas Market
Oil & Gas
Europe Coiled Tubing Market
Oil & Gas
Methane Hydrate Extraction Market