
 Russian Federation Oil and Gas Upstream Market | 2026-2036
Russian Federation Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
Russian Federation Oil and Gas Upstream Market Analytics
Advanced horizontal drilling combined with multi-stage hydraulic fracturing is reconfiguring how Russian operators access low-permeability reservoirs in the Bazhenov and Achimov formations. Rosneft Oil Company PJSC leverages its dominance in East Siberia to anchor large-scale greenfield developments. PJSC Gazprom sustains integrated control across the full gas value chain from Yamal to export corridors. Novatek PAO specializes in LNG-optimized upstream configurations that compete for Arctic feedstock allocation.
The Russian Federation Oil and Gas Upstream sector encompasses exploration, production, drilling, and enhanced recovery activities targeting hydrocarbon reserves at depths ranging from 2,000 to 5,000 meters across onshore and offshore geological complexes, with primary purpose being the extraction of crude oil and natural gas for processing into fuels, petrochemical feedstocks, and power generation inputs. Production activity retains the largest value share given mature supergiant fields in West Siberia, while enhanced recovery represents the fastest-expanding segment as operators deploy gas injection and thermal methods to sustain output from depleted reservoirs. Horizontal drilling and 3D seismic technology segments command premium service pricing due to technical complexity and limited specialist contractor availability.
Russia's Ministry of Energy coordinates licensing rounds through the subsoil use framework, while Rosnedra manages geological data and block allocation procedures that determine which operators gain access to frontier acreage. Environmental requirements under Russian Federation nature protection statutes shape drilling waste management standards and offshore spill response obligations in sensitive Arctic ecosystems. Stakeholders must monitor how fiscal mechanism adjustments and technology import substitution mandates reshape capital deployment priorities across the project pipeline.
Market Dynamics
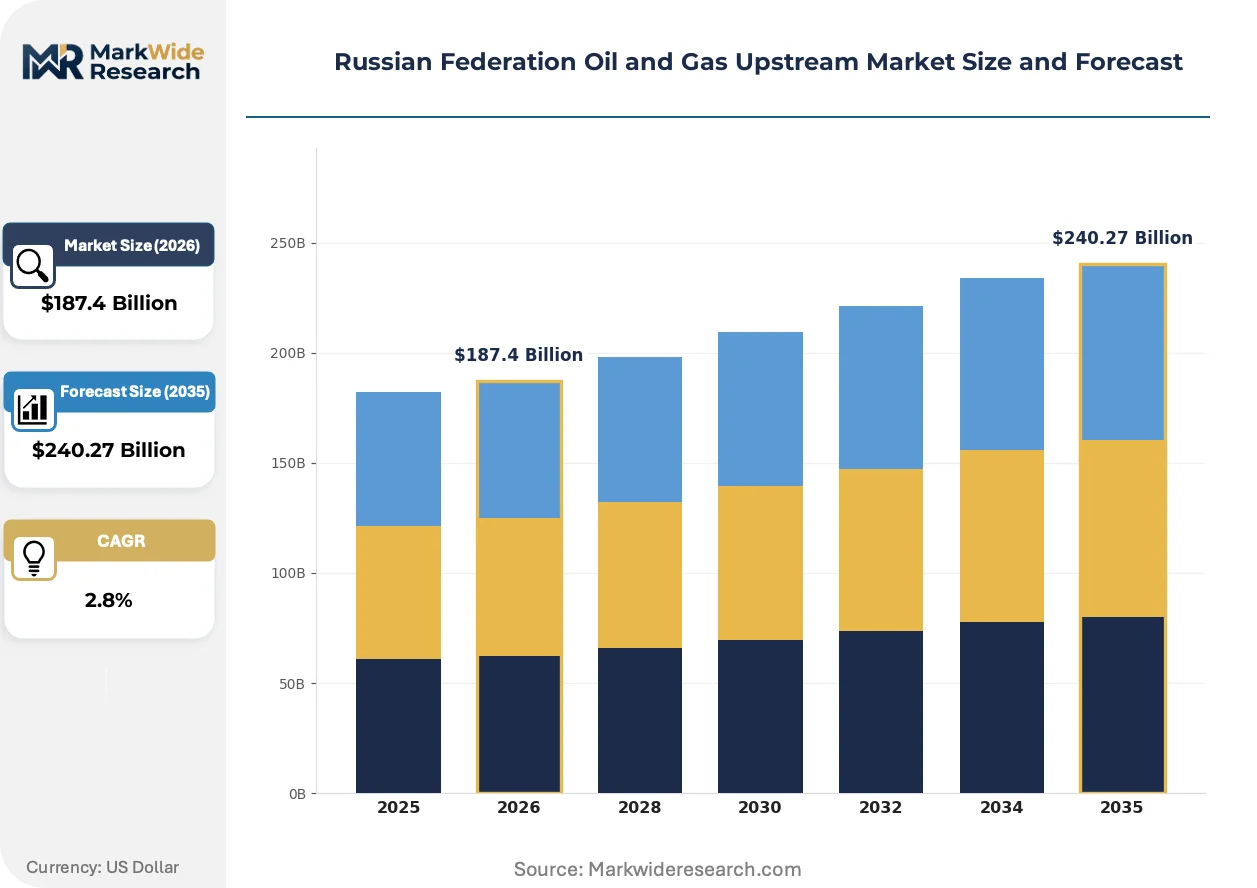
The mineral extraction tax framework and Arctic development incentives are restructuring capital deployment across Russia's upstream sector, pushing operators toward Eastern Siberian greenfields and offshore frontier zones while mature West Siberian assets require intensified recovery investment.
Growth Catalysts
- Arctic offshore licensing:Rosnedra's expanded block allocation in the Barents and Kara Seas unlocks supergiant gas and condensate prospects. Operators gain access to untapped reservoirs with strategic export positioning.
- Enhanced recovery mandates:The Ministry of Energy's production maintenance targets accelerate gas injection and thermal method deployment across depleted West Siberian brownfields. These techniques sustain output from legacy assets.
- Petrochemical feedstock pull:Domestic polymer complexes at Tobolsk and Ust-Luga expand offtake contracts for West Siberian light crude and condensate. This anchors local demand against export volatility.
Market Restraints
- Specialist contractor scarcity:Horizontal drilling and multi-stage fracturing services face limited availability from domestic providers. Import substitution mandates constrain access to advanced foreign equipment.
- Arctic logistics cost structure:Ice-class vessel charter rates and seasonal construction windows inflate development breakevens for offshore projects. Yamal infrastructure saturation compounds access bottlenecks.
- Technology import friction:Sanctions on seismic imaging software and directional drilling tools delay exploration timelines. Operators must certify domestic alternatives under Rosnedra technical standards.
Strategic Opportunities
- Eastern Siberia greenfield development:Vankor and Verkhnechonsk cluster expansions offer low-decline production profiles with pipeline connectivity to the Eastern Siberia-Pacific Ocean system.
- LNG-optimized upstream configurations:Yamal and Gydan peninsula gas fields support modular liquefaction trains with direct access to Asian spot markets. This displaces traditional pipeline-dependent monetization.
- Digital twin convergence:Integration of 3D reservoir modeling with real-time downhole monitoring reduces well intervention frequency. Operators deploy these systems at Krasnoleninskoye and Prirazlomnoye.
Industry Challenges
- Arctic environmental compliance:Spill response obligations under Russian Federation nature protection statutes require dedicated ice-capable containment fleets. Operators must pre-position assets across remote offshore installations.
- Deep drilling talent scarcity:Extended-reach horizontal wells in the Bazhenov formation demand geosteering specialists with unconventional reservoir experience. Training pipelines lag field deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russian Federation Oil and Gas Upstream Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $240.27 Billion |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Exploration, Production, Drilling, Enhanced Recovery Technology: Hydraulic Fracturing, 3D Seismic, Horizontal Drilling, Gas Injection End User: Independent Operators, National Oil Companies, Service Providers, Joint Ventures Service Type: Geophysical, Well Engineering, Logging Services, Maintenance |
| Companies Covered | Rosneft Oil Company PJSC, PJSC Gazprom, PJSC Lukoil Oil Company, Novatek PAO, Surgutneftegas PJSC, PJSC TATNEFT, Gazprom Neft, CJSC Northgas, Bashneft, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russian Federation Oil and Gas Upstream Market Evolving Landscape
Upstream technology trajectories in Russia center on unlocking low-permeability formations, adapting to import substitution imperatives, and reconfiguring field development economics around domestic supply chains.
Multi-stage hydraulic fracturing in horizontal laterals is migrating from pilot testing to full-field development across the Bazhenov shale. Rosneft and independent operators deploy 30-stage completions in 1,500-meter laterals at Priobskoye and Samotlor. This technique is migrating from niche application to baseline development economics, compressing per-well breakeven thresholds against conventional vertical drilling.
Russia's subsoil use framework now mandates minimum exploration work programs with escalating financial guarantees for license retention. The Ministry of Energy ties block extensions to seismic acquisition and wildcat drilling commitments. Frontier operators in the Laptev Sea and East Siberian Sea face the steepest compliance ramps, accelerating farm-out negotiations with capital-rich partners.
Integrated service contracting is displacing discrete procurement of drilling, completion, and artificial lift services. Majors now bundle multi-well programs under single-source agreements with domestic contractors at Uvat and Yuzhno-Russkoye. This concentration is most visible in West Siberia, where operators consolidate vendor relationships to secure rig availability and standardize equipment specifications.
Russian Federation Oil and Gas Upstream Market Segmentation
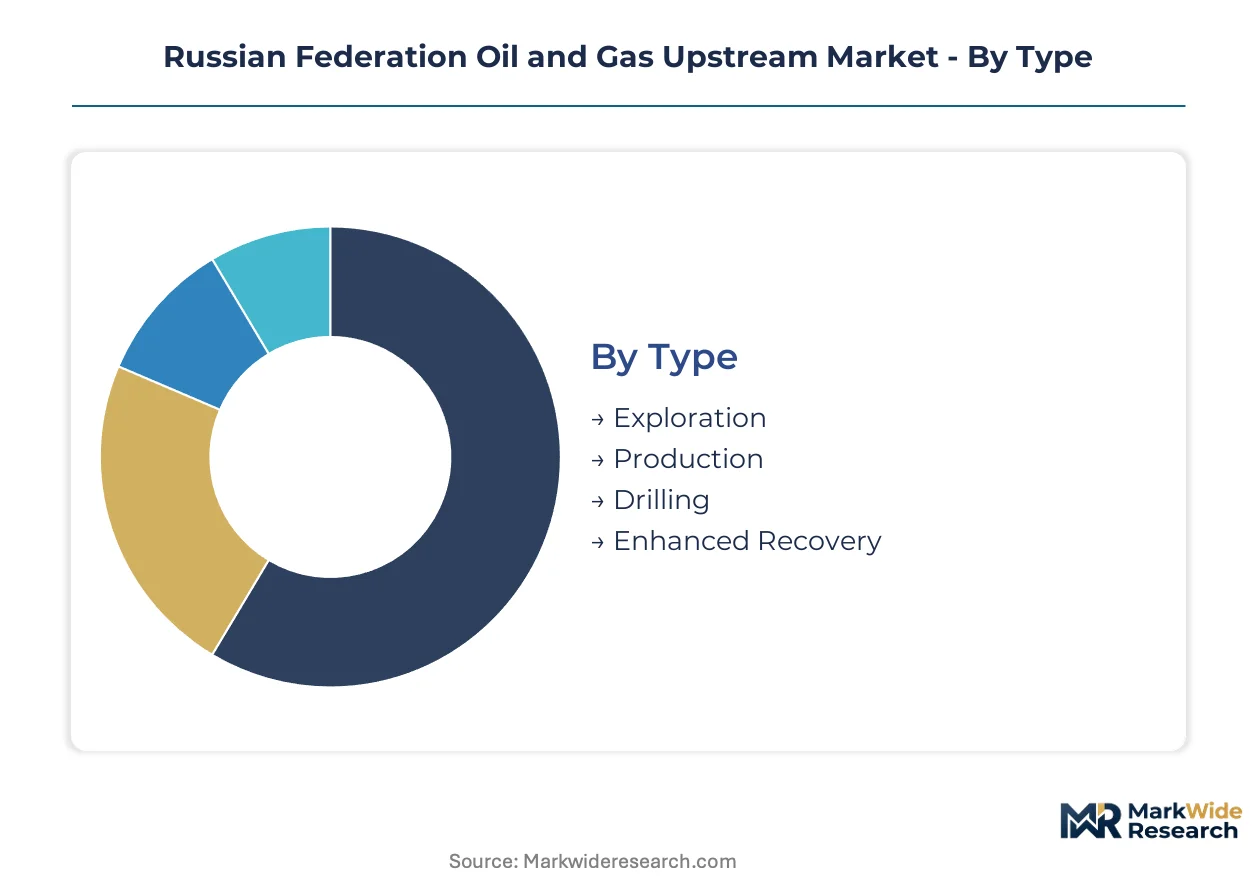
Upstream segmentation in Russia reveals how capital flows across distinct operational layers, from frontier exploration to mature field rehabilitation. Each dimension carries unique regulatory, technical, and competitive characteristics that shape operator strategy.
Type:
Activity type determines capital intensity, payback horizons, and exposure to mineral extraction tax regimes across Russian subsoil blocks.
- Production:Sustained extraction from West Siberian supergiants like Samotlor and Priobskoye underpins national output targets. Rosneft and Gazprom Neft concentrate brownfield optimization spending here, deploying artificial lift and well workovers to combat natural decline rates.
- Enhanced Recovery:Gas injection and thermal methods unlock stranded reserves in depleted reservoirs. The Ministry of Energy's production maintenance mandates accelerate deployment across the Bazhenov and Achimov formations, where recovery factors remain below international benchmarks.
- Exploration:Seismic acquisition and wildcat drilling target Arctic offshore and Eastern Siberian greenfields. Rosnedra licensing rounds in the Barents and Kara Seas require escalating work program guarantees.
- Drilling:Well construction spans vertical, directional, and horizontal trajectories across onshore and offshore complexes. Extended-reach laterals in the Bazhenov shale demand specialized geosteering capabilities.
Production commands the established base. The steepest expansion runs through Enhanced Recovery.
Technology:
Technical maturity and import substitution status differentiate service pricing and availability across Russian upstream operations.
- Horizontal Drilling:Extended-reach laterals up to 1,500 meters access low-permeability pay zones in the Bazhenov and Achimov formations. Domestic rig capacity constraints and sanctions on directional tools create supply bottlenecks for 30-stage completion programs.
- Hydraulic Fracturing:Multi-stage stimulation in tight reservoirs is migrating from pilot to full-field development. Rosneft deploys 30-stage fracs at Priobskoye, compressing per-well breakevens against conventional vertical completions.
- 3D Seismic:High-resolution subsurface imaging supports exploration targeting and reservoir characterization. Import restrictions on Western acquisition and processing software force certification of domestic alternatives under Rosnedra standards.
- Gas Injection:Pressure maintenance and miscible displacement sustain output from mature West Siberian fields. Gazprom's integrated infrastructure enables captive gas sourcing for injection programs at Yamburg and Urengoy.
Horizontal Drilling anchors current investment. Hydraulic Fracturing is gaining share fastest.
End User:
Ownership structure shapes access to capital, technology partnerships, and state-mandated production quotas across Russian acreage.
- National Oil Companies:Rosneft and Gazprom control supermajor-scale portfolios spanning West Siberia, East Siberia, and Arctic offshore. State-backed balance sheets absorb long-dated greenfield development cycles at Vankor and Yamal.
- Independent Operators:Smaller producers focus on marginal fields and service-intensive recovery projects. These entities face tighter credit conditions and limited technology access compared to state-backed rivals.
- Joint Ventures:Partnership structures with international partners historically transferred expertise for frontier developments. Current sanctions environment constrains foreign participation to non-aligned jurisdictions.
- Service Providers:Schlumberger, Halliburton, and domestic contractors deliver specialized drilling and completion services. Integrated contracting models now bundle multi-well programs under single-source agreements.
National Oil Companies dominate reserve holdings. Independent Operators are expanding most quickly in brownfield rehabilitation.
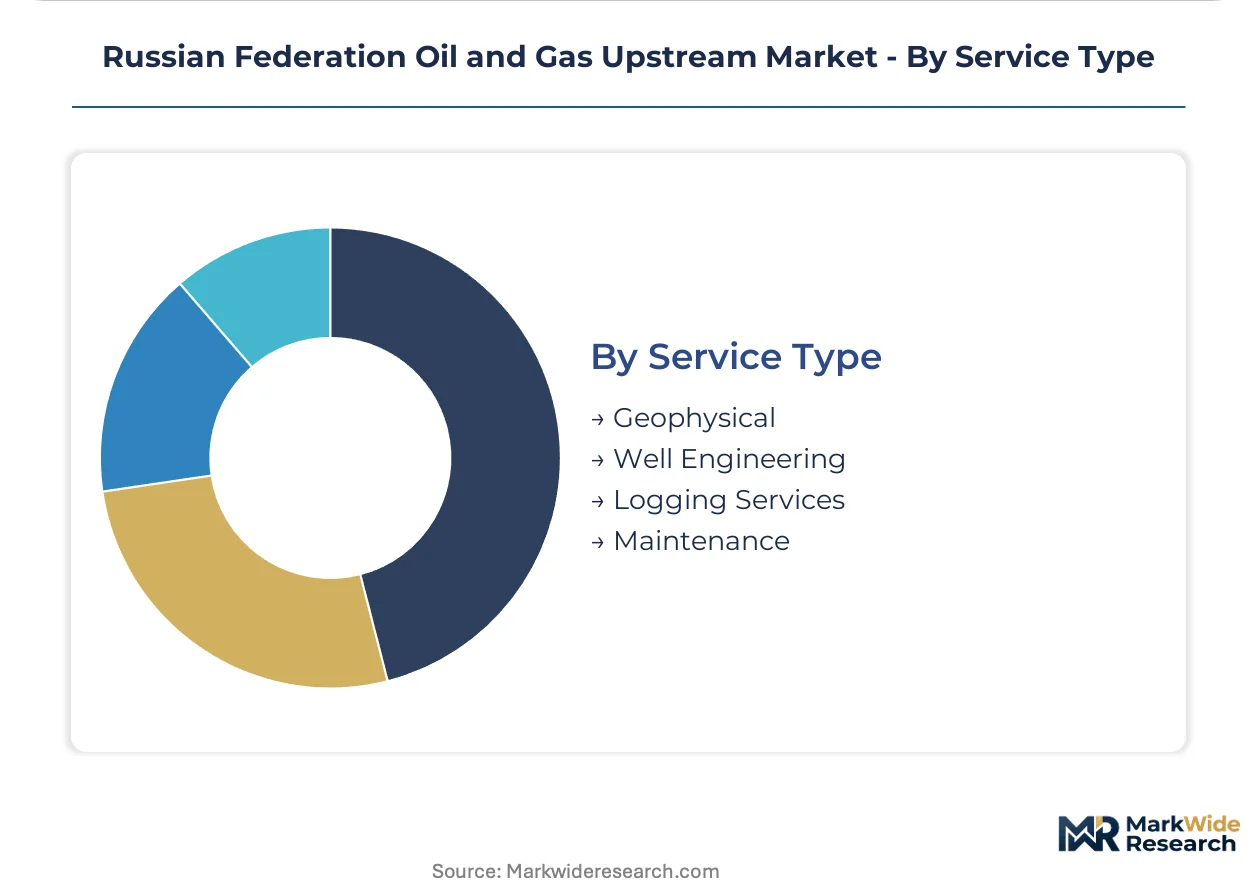
Service Type:
Service specialization determines pricing power and vulnerability to import substitution mandates across the Russian supplier base.
- Well Engineering:Drilling design, directional planning, and completion engineering command premium pricing due to technical complexity. Extended-reach horizontals in the Bazhenov require geosteering specialists with unconventional reservoir experience.
- Geophysical:Seismic acquisition, processing, and interpretation support exploration and reservoir monitoring. Domestic contractors are displacing Western providers for 2D and 3D surveys under localization requirements.
- Logging Services:Wireline and logging-while-drilling measurements evaluate formation properties and completion integrity. Tool availability faces constraints from sanctions on measurement electronics.
- Maintenance:Well intervention, artificial lift optimization, and facility upkeep sustain production from mature assets. Workover rig demand concentrates in West Siberia's supergiant fields.
Well Engineering captures the highest margins. Geophysical is climbing the fastest as exploration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Upstream investment concentrates around three distinct buyer archetypes: state-backed national oil companies funding multi-decade greenfield cycles, independent operators targeting marginal brownfield rehabilitation, and integrated service providers bundling multi-well programs under single-source contracts.
West Siberian Basin
Rosneft and Gazprom Neft anchor production maintenance spending across supergiant fields at Samotlor and Priobskoye. The Ministry of Energy's enhanced recovery mandates accelerate gas injection deployment under subsoil use framework obligations. Tobolsk petrochemical complexes expand offtake contracts for light crude and condensate, anchoring local demand against export corridor volatility.
East Siberia
Vankor and Verkhnechonsk cluster developments offer low-decline production profiles with pipeline connectivity to the Eastern Siberia-Pacific Ocean system. Rosnedra licensing rounds tie block extensions to escalating seismic acquisition and wildcat drilling commitments. Krasnoyarsk Krai infrastructure supports modular upstream configurations feeding Asian spot markets through the ESPO trunkline.
Arctic Offshore
Yamal and Gydan peninsula gas fields support LNG-optimized upstream configurations with direct access to Asian buyers. Rosnedra's expanded block allocation in the Barents and Kara Seas unlocks supergiant condensate prospects requiring ice-class vessel charters. Novatek anchors development timelines through the Obskaya Bay infrastructure corridor.
Volga-Ural Region
PJSC TATNEFT and Bashneft concentrate on mature reservoir rehabilitation across depleted carbonate formations. The mineral extraction tax framework shapes field economics toward tertiary recovery methods. Almetyevsk and Ufa industrial clusters host specialized drilling contractor bases serving extended-reach horizontal programs.
Timan-Pechora Basin
Surgutneftegas PJSC sustains output from offshore and coastal fields through integrated service contracting models. Arctic environmental compliance statutes mandate pre-positioned ice-capable spill response assets across remote installations. Naryan-Mar serves as the logistics hub for seasonal construction windows and personnel rotation.
Russian Federation Oil and Gas Upstream Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Russia's upstream service tiers. State-backed national oil companies dominate reserve holdings and capital deployment timelines, while independent operators fragment brownfield rehabilitation demand. Three archetypes define competitive positioning: integrated majors with full value chain control, specialists in unconventional reservoir development, and domestic service contractors capturing localization mandates. Capacity concentration and technology licensing arrangements constitute the dominant competitive moves, with operators consolidating vendor relationships to secure rig availability.
Among state-backed integrated majors, Rosneft Oil Company PJSC, PJSC Gazprom, and Novatek PAO exemplify distinct strategic orientations within the Russian upstream hierarchy. Rosneft anchors large-scale greenfield developments across East Siberia and the Arctic offshore through its dominance in frontier block allocation. Gazprom sustains integrated control across the full gas value chain from Yamal production bases through export corridor infrastructure. Novatek occupies a specialized position in LNG-optimized upstream configurations, competing for Arctic feedstock allocation against traditional pipeline-dependent monetization models.
| Leading Market Players |
|---|
| Rosneft Oil Company PJSC |
| PJSC Gazprom |
| PJSC Lukoil Oil Company |
| Novatek PAO |
| Surgutneftegas PJSC |
| PJSC TATNEFT |
| Gazprom Neft |
| CJSC Northgas |
| Bashneft |
| Others |
Value Network & Pricing Analysis
The Obskaya Bay infrastructure corridor anchors cost-plus contract negotiations for Arctic LNG feedstock, where ice-class vessel charter rates concentrate supply bargaining power among Yamal operators and force downstream price differentiation between Asian spot-indexed cargoes and European pipeline-linked deliveries.
Pricing Analysis
Cost-plus contracts with Brent crude indexation dominate long-term offtake agreements for West Siberian light crude and condensate. Price differentiation hinges on API gravity grades and Rosnedra-certified reserve classification tiers. Cost compression in standard-grade feedstocks is intensifying because domestic petrochemical complexes at Tobolsk and Ust-Luga consolidate procurement volumes. Independent operators exhibit the highest price sensitivity due to constrained credit access, while Rosneft and Gazprom absorb premium pricing for guaranteed reserve replacement.
Supply Chain Analysis
Supplier-financing facilities with 180-day payment terms have become standard for domestic drilling contractors serving extended-reach horizontal programs. Equipment sourcing draws from China, South Korea, and domestic Russian manufacturers for pressure pumping units and directional drilling tools. Single-source vulnerability concentrates around sanctioned seismic imaging software and measurement-while-drilling electronics. Distribution runs through integrated service contracting models at Uvat and Yuzhno-Russkoye, where majors bundle multi-well programs under single-source agreements with certified domestic providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
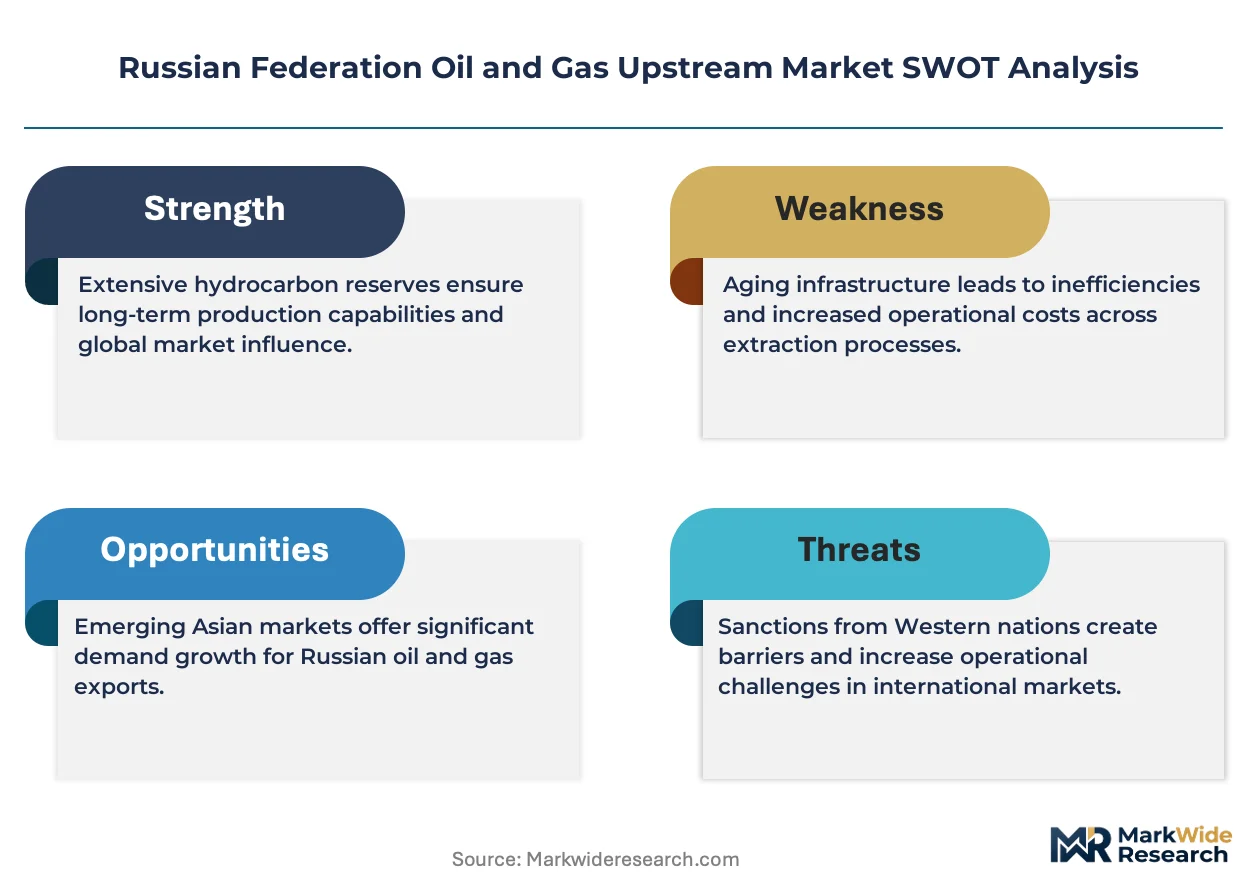
The Russian upstream sector operates as a regulatory-moat market, where Rosnedra licensing entrenchment and subsoil use framework obligations create prohibitive switching costs for reserve access.
For Market Incumbents: Pre-empt independent operator encroachment in brownfield rehabilitation by consolidating geosteering specialist contractors under exclusive multi-year service agreements. Anchor capacity addition in East Siberia's Vankor cluster to lock in Eastern Siberia-Pacific Ocean pipeline allocation before block extensions expire. Vertical integration into modular LNG liquefaction equipment manufacturing mitigates technology import friction from sanctions. For New Entrants and Emerging Players: Marginal field rehabilitation in the Volga-Ural region represents the most penetrable entry point, where depleted carbonate formations at Almetyevsk offer tertiary recovery contracts outside supergiant field hierarchies. Arctic logistics subcontracting for ice-class vessel chartering and seasonal construction windows opens service niches without reserve holding requirements. Partner with Krasnoyarsk Krai infrastructure operators for ESPO trunkline access rather than competing for greenfield block allocation. For Investors and Strategic Acquirers: Carve-out targets emerge from Western majors divesting non-core Russian joint venture stakes under sanctions compliance mandates. Five-to-ten-year viability hinges on operators securing Rosnedra license extensions with escalating work program guarantees. Watch Arctic environmental compliance statute enforcement as the inflection indicator for offshore development cost structures and ice-capable containment fleet pre-positioning requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Service Contracting Consolidation | Bundling multi-well programs at Uvat secures rig availability against contractor scarcity. |
| Domestic Seismic Technology Certification | Rosnedra-approved 3D imaging alternatives displace sanctioned Western processing software. |
| Arctic LNG Module Manufacturing Localization | In-house production of liquefaction trains reduces Yamal project import dependency. |
| Enhanced Recovery Mandate Compliance | Gas injection deployment at Samotlor satisfies Ministry of Energy production maintenance targets. |
| East Siberia-Pacific Ocean Pipeline Expansion | ESPO trunkline capacity addition locks in Asian spot market access for Vankor cluster output. |
Research Methodology
The analysis maps exploration licensing, production maintenance, enhanced recovery, and drilling service sub-sectors, each validated through upstream planning officers, subsoil use regulators, EPC contractors, and domestic equipment procurement leads. Primary interviews with Rosnedra technical standards officials and field development engineers at Priobskoye and Samotlor combined with secondary validation from customs/trade data, Ministry of Energy production statistics, and SEC filings from international oilfield service providers. Bottom-up project pipeline aggregation and top-down macroeconomic scenario triangulation anchored volume estimates.
Assumptions held fixed include current mineral extraction tax framework parameters and Arctic environmental compliance statute obligations, while Brent crude price trajectories and sanctions severity were varied across sensitivity scenarios. Segmentation dimensions modeled span activity type, technology tier, ownership structure, and service specialization, with regional licensing round timing and petrochemical complex offtake contract duration as industry-specific forecast inputs. CAGRs derived from production decline curve analysis and greenfield development timeline probability weighting.
Practitioners should monitor Rosnedra block allocation auction results and Ministry of Energy fiscal mechanism adjustment announcements for early signals of capital deployment redirection. Forecasts reflect documented assumptions regarding technology import substitution progress and contractor capacity expansion. Macroeconomic commodity price volatility, regulatory framework deviation, or accelerated sanctions escalation would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Algeria Oil and Gas Upstream Market
Oil & Gas
Zonal Isolation Market
Oil & Gas
United Kingdom LNG Market
Oil & Gas
Global Shale Gas Market
Oil & Gas
Leak Detection for Oil & Gas Market
Oil & Gas
Malaysia Oil and Gas Midstream Market
Oil & Gas
Small Scale LNG (SSLNG) Market
Oil & Gas
Canada LNG Bunkering Market
Oil & Gas
Well Abandonment Services Market
Oil & Gas
Asia Pacific Upstream Oil and Gas Services Market
Oil & Gas
Italy Oil and Gas Market
Oil & Gas
Oil and Gas Processing Seals Market
Oil & Gas
Mexico Oil and Gas Downstream Market
Oil & Gas
Enclosed Flares Market
Oil & Gas
Seismic Survey Equipment Market
Oil & Gas
Global LNG Regasification Terminals Market