
 MEMS Accelerometer and Gyroscope Market | 2026-2036
MEMS Accelerometer and Gyroscope Market Size, Share, and Industry Trends Forecast 2026-2036
MEMS Accelerometer and Gyroscope Market Foresight
Foundry leasing and asset-light wafer partnerships is reconfiguring capital barriers for fabless MEMS designers seeking 200mm silicon capacity. Bosch Sensortec leverages captive fabrication in Reutlingen to sustain margin control across consumer-grade accelerometer volumes. STMicroelectronics anchors European supply through its integrated MEMS foundry in Agrate Brianza. Murata Manufacturing competes via specialized ceramic packaging expertise that extends device reliability under harsh automotive thermal cycling.
MEMS accelerometers and gyroscopes are micro-machined electromechanical structures etched into silicon wafers, typically measuring displacement through capacitive sensing with resolutions reaching micro-g levels for navigation-grade performance. These devices enable precise motion detection, orientation tracking, and vibration monitoring across closed-loop control systems. Inertial measurement units now capture the fastest expansion within product type segments as robotics and autonomous platforms demand fused six-axis outputs. Silicon-based technology dominates fabrication economics, though optical MEMS gyroscopes occupy premium aerospace tiers where bias stability requirements exceed tactical-grade thresholds. Consumer electronics end users still generate the highest unit volumes, yet automotive qualification timelines are lengthening as OEMs enforce AEC-Q100 stress-test protocols.
FDA scrutiny of wearable health monitors with embedded accelerometers for fall detection is tightening electromagnetic compatibility and biocompatibility documentation requirements in the United States. EASA airworthiness directives for civil drones above certain mass thresholds are mandating redundant inertial reference units with traceable calibration chains in Europe. China's GB standards for vehicle stability control, enforced by MIIT homologation procedures, specify minimum gyroscope bias repeatability across temperature ranges. Stakeholders must monitor how automotive functional safety standards evolve from ISO 26262 ASIL ratings toward more stringent robotaxi certification benchmarks before committing next-generation design resources.
Market Dynamics
Automotive functional safety mandates are compressing MEMS qualification timelines as OEMs migrate from ISO 26262 ASIL-B toward ASIL-D ratings for robotaxi platforms, forcing foundries to reconfigure 200mm silicon processes for zero-defect traceability.
Growth Catalysts
- NHTSA rollover detection mandates:United States vehicle safety rules now require inertial measurement units in light trucks and SUVs, creating captive demand for six-axis MEMS clusters with temperature-compensated bias stability.
- EV battery thermal management:Chinese domestic brands specify accelerometer arrays for cell-level vibration monitoring during fast-charging cycles, extending sensor duty cycles beyond traditional chassis applications.
- Capacitive sensing resolution gains:Micro-g level displacement detection now enables navigation-grade performance in consumer-grade silicon, collapsing the cost barrier between tactical and industrial IMU tiers.
Market Restraints
- 200mm silicon capacity concentration:Foundry availability for MEMS-specific etching and wafer bonding remains concentrated in Taiwan and Germany, creating allocation risk during automotive demand spikes.
- AEC-Q100 protocol duration:Automotive qualification timelines now extend 18-24 months for new accelerometer designs, freezing R&D amortization across product generations.
- Optical gyroscope substitution:Fiber-optic and ring laser gyroscopes retain bias stability advantages above tactical-grade thresholds, limiting silicon MEMS penetration in commercial aviation attitude reference systems.
Strategic Opportunities
- Industrial robotics end-use expansion:Collaborative robot manufacturers in Germany and Japan are sourcing fused six-axis IMUs for force-limiting safety zones, opening volume contracts outside automotive procurement cycles.
- FDA wearable health monitor pathway:Fall detection algorithms in consumer wearables are migrating toward clinical-grade 510(k) submissions, creating premium pricing tiers for biocompatible MEMS packaging.
- EASA drone mass-threshold rules:European civil unmanned aircraft above 25kg now require redundant inertial reference units, generating dual-socket demand for calibrated gyroscope pairs with traceable temperature coefficients.
Industry Challenges
- MEMS-specific process engineering talent:Deep expertise in DRIE etching, wafer-level packaging, and resonant frequency trimming remains concentrated among aging specialists in Reutlingen and Agrate Brianza clusters.
- Legacy chassis controller integration:Tier-1 suppliers face software stack rewrites to fuse new IMU outputs with existing ESP and ABS modules without triggering vehicle-level recertification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MEMS Accelerometer and Gyroscope Market |
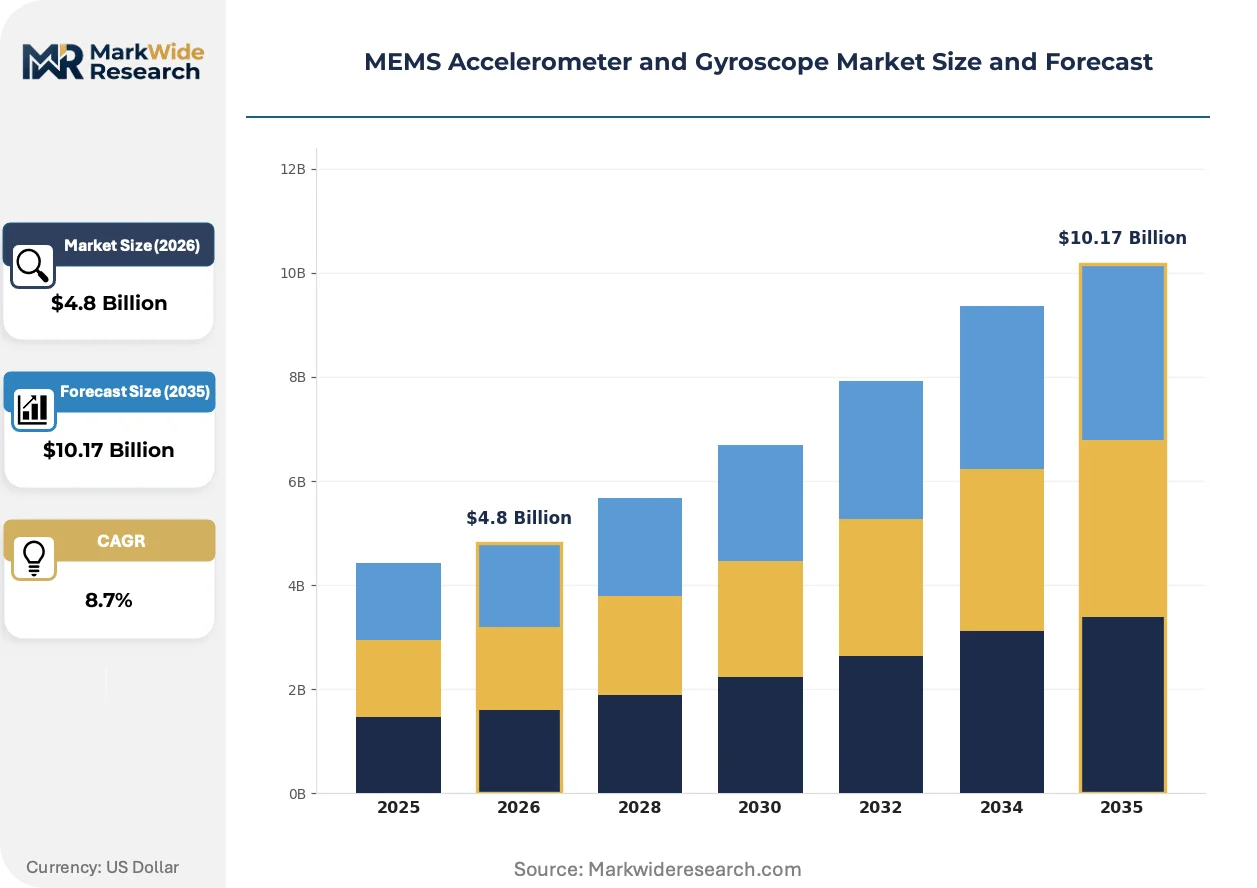
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Three-Axis Accelerometer, Two-Axis Gyroscope, Inertial Measurement Unit, Microelectromechanical Systems Technology: Silicon-Based, Analog, Digital, Optical End User: Consumer Electronics, Aerospace, Automotive, Industrial Automation Application: Motion Tracking, Navigation, Gaming, Robotics |
| Companies Covered | NXP Semiconductors, TDK Corporation, Analog Devices, Honeywell International, Microchip Technology, STMicroelectronics, Murata Manufacturing, ROHM, Bosch Sensortec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MEMS Accelerometer and Gyroscope Market Shifts & Advancements
Silicon photonics integration and AI-driven sensor fusion are collapsing the boundary between discrete MEMS components and system-level intelligence, redefining how motion data is processed at the edge versus centralized compute.
Capacitive MEMS accelerometers are hybridizing with piezoelectric thin-film layers to extend dynamic range without sacrificing micro-g resolution. Automotive ADAS module suppliers in Germany are piloting these stacked structures for simultaneous high-g crash detection and low-g lane-keeping feedback. The technology is hybridizing traditional single-physics designs into multi-modal sensors that reduce socket count and wiring harness complexity.
EU AI Act risk-classification rules are mandating explainability documentation for sensor fusion algorithms in autonomous systems. MEMS vendors must now provide deterministic bias drift models to satisfy conformity assessment procedures for high-risk AI applications. European robotaxi developers are responding by sourcing IMUs with embedded self-test diagnostics that generate auditable fault traces.
Buyer concentration among Chinese EV OEMs is forcing Western MEMS suppliers to localize calibration and final test operations within mainland China. Direct procurement relationships are replacing traditional distribution through Hong Kong-based component traders. This channel restructuring is most visible in Ningbo and Shenzhen, where domestic brands now specify GB-standard compliance certificates as mandatory bid qualifications.
MEMS Accelerometer and Gyroscope Market Segmentation
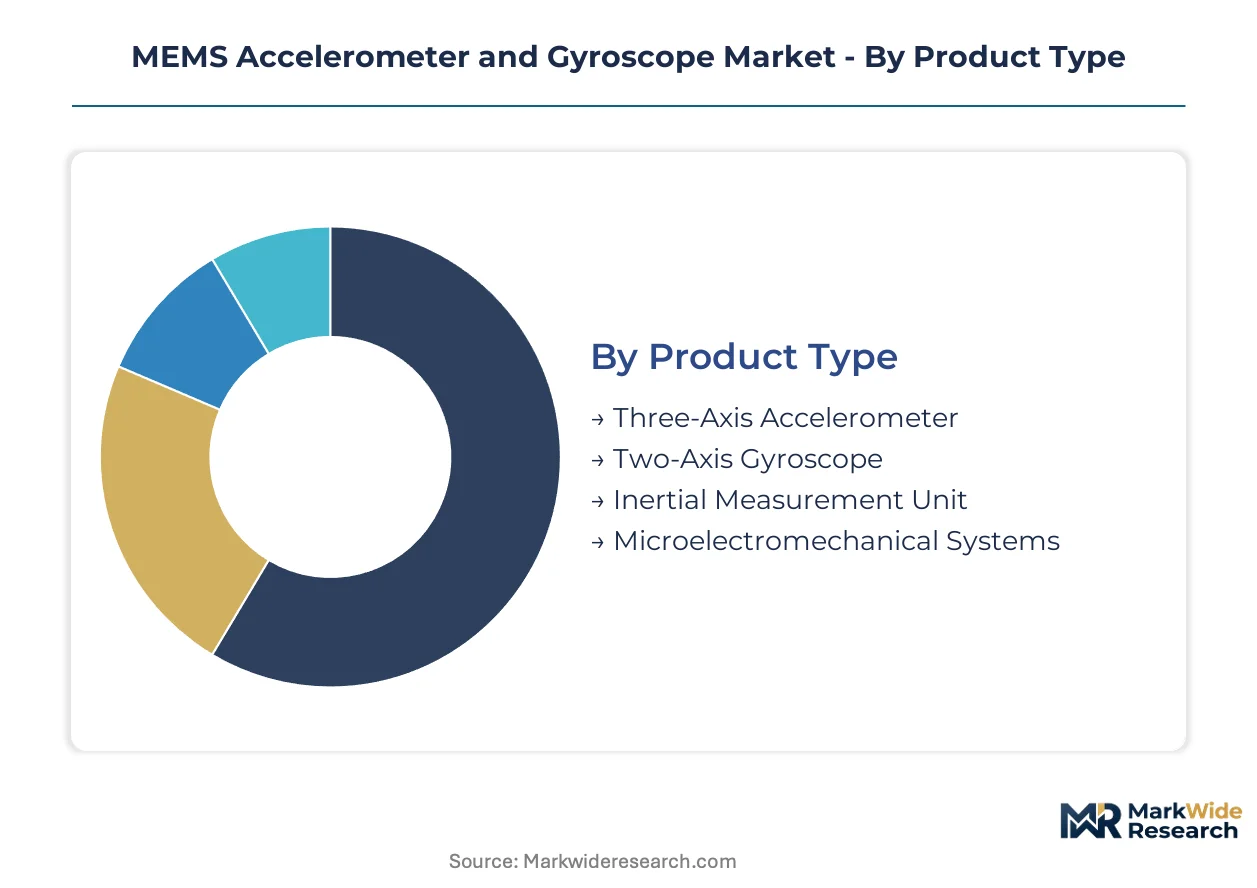
MEMS accelerometer and gyroscope procurement patterns diverge sharply across motion-sensing architectures, fabrication technologies, and end-use qualification thresholds. Understanding these dimensional splits reveals where silicon-based volumes concentrate versus where optical precision commands premium positioning.
Product Type:
Application complexity and axis integration density separate these motion-sensing form factors across cost-performance tiers.
- Inertial Measurement Unit:Fused six-axis packages combining accelerometer and gyroscope outputs in single surface-mount housings. Robotics developers in Germany and autonomous platform builders in the United States are standardizing on these for closed-loop attitude control, driving the steepest expansion trajectory among product categories.
- Three-Axis Accelerometer:Discrete capacitive sensors measuring linear acceleration across X-Y-Z planes with micro-g resolution capabilities. Chinese EV manufacturers specify these arrays for battery pack vibration monitoring during fast-charging cycles, extending duty cycles beyond traditional chassis stabilization roles.
- Two-Axis Gyroscope:Coriolis-effect resonators detecting rotational rate in pitch and yaw dimensions. Gaming peripheral manufacturers source these for motion-controlled input devices where cost sensitivity limits axis count.
- Microelectromechanical Systems:Foundational wafer-level fabrication category encompassing resonant structures etched through DRIE processes. Process engineers in Reutlingen and Agrate Brianza clusters concentrate expertise here.
Three-Axis Accelerometer holds installed capacity. Inertial Measurement Unit is rotating up the share rankings.
Technology:
Signal conditioning methodology and sensing physics determine which fabrication approaches capture volume versus precision-tier positioning.
- Silicon-Based:Bulk micromachined polysilicon structures with capacitive transduction dominating unit economics. STMicroelectronics anchors European supply through captive 200mm foundry capacity in Agrate Brianza, while Bosch Sensortec maintains Reutlingen fabrication for consumer-grade volumes.
- Digital:Embedded ASICs performing temperature compensation and self-test diagnostics at the sensor edge. EASA drone airworthiness directives above 25kg mass thresholds are mandating these traceable calibration chains for redundant inertial reference units.
- Analog:Raw voltage outputs requiring external ADC conversion and filtering. Legacy industrial controllers in Japanese automation installations still specify these for compatibility with existing signal conditioning architectures.
- Optical:Fiber-optic and ring laser interferometric gyroscopes achieving bias stability below tactical-grade thresholds. Commercial aviation attitude reference systems retain these where silicon MEMS cannot meet ARINC 704 specifications.
Silicon-Based commands wafer allocation priority. Digital is climbing the fastest among emerging qualification tiers.
End User:
Customer qualification protocols and volume procurement cycles segment demand across radically different certification timelines.
- Automotive:AEC-Q100 stress-test protocols extending 18-24 months for new accelerometer designs. NHTSA rollover detection mandates in the United States now require inertial measurement units in light trucks and SUVs, creating captive demand for temperature-compensated bias stability.
- Consumer Electronics:Highest unit volumes with shortest product lifecycles. FDA scrutiny of wearable health monitors with embedded accelerometers for fall detection is tightening electromagnetic compatibility documentation requirements in the United States.
- Industrial Automation:Collaborative robot manufacturers in Germany and Japan source fused six-axis IMUs for force-limiting safety zones, opening volume contracts outside automotive procurement cycles.
- Aerospace:Stringent bias repeatability requirements across temperature ranges. EASA airworthiness directives specify redundant architectures with traceable calibration chains.
Consumer Electronics maintains shipment scale leadership. Automotive is expanding most quickly as functional safety mandates tighten.
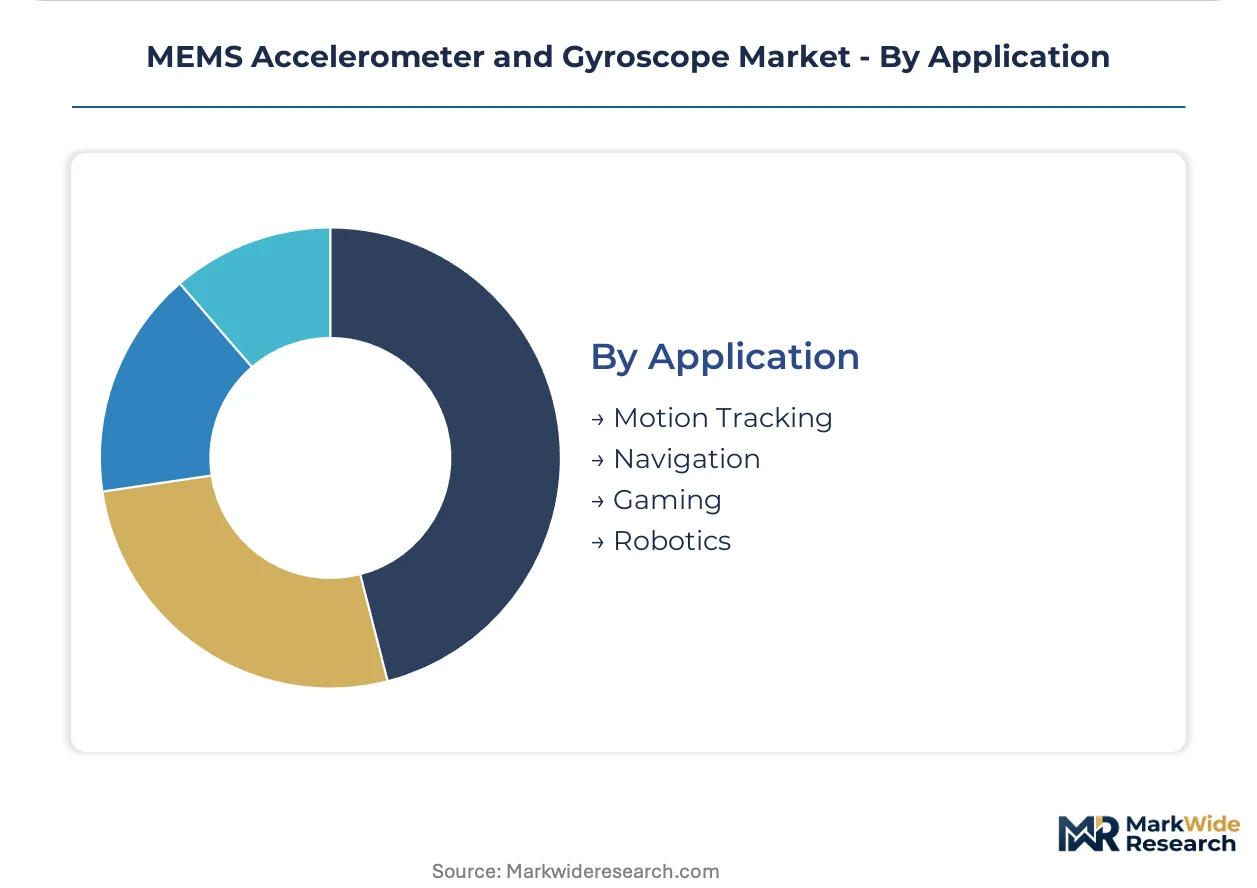
Application:
Use-case precision requirements and environmental exposure severity determine sensor specification differentiation.
- Navigation:Dead-reckoning position calculation requiring gyroscope bias stability below tactical-grade thresholds. Autonomous vehicle developers specify these for GPS-denied tunnel and urban canyon scenarios.
- Robotics:Six-axis fused outputs enabling closed-loop balance and manipulation control. German collaborative robot manufacturers are sourcing IMUs for force-limiting safety zones.
- Motion Tracking:Orientation and acceleration capture for human interface devices. Chinese domestic EV brands specify MEMS-based tracking for chassis stabilization feedback loops.
- Gaming:Low-cost gyroscopic input for controller and VR headset applications. Short qualification timelines align with annual hardware refresh cycles.
Motion Tracking holds cumulative deployment volume. Navigation is gaining share fastest as robotaxi platforms advance toward commercial service.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and consumer electronics manufacturers concentrate procurement authority across five national production clusters. Each geography imposes distinct qualification protocols that reshape local supply relationships.
United States
NHTSA rollover detection mandates drive six-axis IMU integration into light trucks and SUVs. FDA scrutiny tightens electromagnetic compatibility documentation for wearable health monitors with embedded accelerometers. Design engineering concentrates in California and Texas, where autonomous vehicle developers source navigation-grade sensors for GPS-denied scenarios.
Germany
Collaborative robot manufacturers source fused six-axis IMUs for force-limiting safety zones outside automotive procurement cycles. KBA type-approval rules enforce AEC-Q100 stress-test protocols for chassis stabilization systems. The Reutlingen cluster anchors captive fabrication expertise for consumer-grade accelerometer volumes.
China
Domestic EV brands specify MEMS-based motion tracking for battery thermal management and chassis stabilization feedback loops. MIIT homologation procedures enforce GB standards specifying minimum gyroscope bias repeatability across temperature ranges. Ningbo and Shenzhen host localized calibration and final test operations replacing Hong Kong-based distribution channels.
Japan
Industrial automation controllers in legacy installations specify analog-output accelerometers for existing signal conditioning architectures. METI industrial standards govern collaborative robot safety sensor specifications. Nagoya and Osaka manufacturing corridors concentrate ceramic packaging expertise for harsh automotive thermal cycling.
South Korea
Consumer electronics OEMs generate highest unit volumes for motion-controlled gaming peripherals and smartphone stabilization. MFDS medical device regulations influence biocompatibility documentation for wearable fall-detection monitors. Seoul Capital Area design houses specify digital-output sensors with embedded temperature compensation ASICs.
MEMS Accelerometer and Gyroscope Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Captive foundry operators leverage in-house 200mm silicon capacity to sustain margin control across high-volume consumer segments. Fabless designers rely on foundry leasing partnerships to access MEMS-specific etching and wafer bonding capacity. Asset-light specialists differentiate through ceramic packaging expertise and automotive qualification track records. Dominant competitive moves include strategic foundry partnerships for capacity allocation and backward integration into wafer-level packaging processes.
Among European-integrated fabricators, STMicroelectronics anchors supply through captive Agrate Brianza foundry capacity, while Bosch Sensortec exemplifies margin control through Reutlingen captive fabrication. Murata Manufacturing represents specialized ceramic packaging expertise extending device reliability under harsh thermal cycling. These three players occupy positions spanning the full spectrum from high-volume consumer supply to automotive-grade qualification tiers.
| Leading Market Players |
|---|
| NXP Semiconductors |
| TDK Corporation |
| Analog Devices |
| Honeywell International |
| Microchip Technology |
| STMicroelectronics |
| Murata Manufacturing |
| ROHM |
| Bosch Sensortec |
| Others |
Supply & Pricing Matrix
The Shanghai-Rotterdam maritime corridor's container rate volatility feeds directly into MEMS module landed costs, amplifying price spreads between captive-fabrication incumbents and fabless designers dependent on foundry leasing. This logistics-cost channel reinforces how 200mm silicon concentration in Taiwan and Germany translates into tiered pricing power across automotive qualification tiers.
Pricing Analysis
Cost-plus contracts with silicon wafer indexation dominate procurement between fabless MEMS designers and foundry partners. Price differentiation hinges on AEC-Q100 certification grade and volume scale, with automotive OEMs absorbing premiums for ASIL-D traceability while consumer electronics buyers squeeze standard-tier suppliers. Cost compression in consumer-grade accelerometers is intensifying because Chinese EV brands are consolidating direct procurement relationships. Tier-1 automotive suppliers exhibit lowest price sensitivity due to functional safety liability exposure, whereas gaming peripheral manufacturers drive hardest bargain hunting.
Supply Chain Analysis
TSMC's MEMS-specific foundry capacity, Bosch Sensortec's Reutlingen captive fabrication, and STMicroelectronics' Agrate Brianza integrated production anchor global 200mm silicon supply. Raw material dependencies include polysilicon feedstock, borosilicate glass wafers for anodic bonding, and ceramic substrates for harsh-environment packaging. Single-source vulnerability concentrates in DRIE etching equipment and resonant frequency trimming expertise held by aging specialists in Southern Germany and Northern Italy. Distribution runs through direct OEM procurement channels replacing Hong Kong-based component traders for Chinese EV accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market's defensive moat rests on regulatory entrenchment: AEC-Q100 and ISO 26262 certification timelines create 18-24 month barriers that freeze out unqualified competitors from automotive revenue pools.
For Market Incumbents: Pre-empt optical gyroscope substitution in commercial aviation by investing in bias stability R&D that narrows the performance gap with fiber-optic systems. Consolidate position through backward integration into wafer-level packaging processes, capturing margin currently leaked to ceramic substrate suppliers. Threat vector: Chinese domestic MEMS designers leveraging MIIT homologation proximity to undercut on GB-standard compliance timelines. For New Entrants and Emerging Players: Industrial robotics safety zones in Germany and Japan represent the most penetrable entry point, bypassing automotive qualification bottlenecks that favor established suppliers. FDA 510(k) wearable health monitor submissions offer a second white-space channel where biocompatibility packaging expertise differentiates against consumer-grade incumbents. Go-to-market angle: partner with collaborative robot OEMs on force-limiting IMU specifications outside traditional Tier-1 automotive procurement cycles. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized MEMS fabrication assets in European clusters. Long-term viability hinges on whether silicon MEMS can displace optical gyroscopes in navigation-grade tiers or remain locked in tactical-grade volume markets. Signal to watch: EASA airworthiness directive expansions beyond 25kg drone thresholds that would multiply redundant IMU socket demand.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Capacity Expansion | Bosch Sensortec's Reutlingen fabrication sustains margin control against fabless competitors dependent on Taiwan allocation. |
| Automotive Functional Safety Certification | ASIL-D qualification investments by STMicroelectronics lock in robotaxi platform supply relationships ahead of commercial service launches. |
| Biocompatible Packaging Development | Murata's ceramic expertise opens FDA 510(k) wearable pathways where electromagnetic compatibility documentation tightens. |
| China Localization Partnerships | Western suppliers establishing Ningbo calibration operations secure GB-standard compliance certificates mandatory for domestic EV procurement. |
| Silicon Photonics Integration | Hybrid capacitive-piezoelectric sensor stacks collapse socket count for German ADAS module suppliers piloting multi-modal architectures. |
Research Methodology
The analysis maps MEMS fabrication technology tiers, end-use qualification thresholds, and regional procurement patterns, each validated through primary interviews with MEMS process engineers, automotive Tier-1 supplier procurement leads, and industrial robotics safety system architects. Secondary validation draws from SEC 10-K filings of publicly traded sensor manufacturers, MIIT homologation procedure documentation, EASA airworthiness directives, and IHS Markit vehicle production databases. Bottom-up unit demand estimates triangulate against top-down wafer capacity allocation data from foundry operators.
Assumptions held fixed include NHTSA rollover detection mandate enforcement timelines and EASA drone mass-threshold rule stability, while variables tested include Chinese EV penetration rates and optical gyroscope cost-reduction curves. The projection framework segments by product type, technology architecture, end-user qualification tier, and application precision requirement, with CAGRs derived from installed base replacement cycles and content-per-vehicle expansion in autonomous platforms. Industry-specific inputs incorporate AEC-Q100 protocol duration estimates and GB-standard bias repeatability specifications.
Practitioners should monitor foundry allocation announcements, MIIT homologation procedure revisions, and EASA airworthiness directive expansions for early signals of forecast deviation. Quarterly review of wafer utilization rates at Agrate Brianza and Reutlingen clusters, alongside NHTSA rulemaking dockets, is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Smart Biosensors Market
Sensors and Controls
Bee Hive Monitoring Sensor Market
Sensors and Controls
Inline Quality Control Sensors Market
Sensors and Controls
Pressure Monitoring Market
Sensors and Controls
Solid Flow Rate Valve Control Market
Sensors and Controls
Hydrogen Pressure Sensor Market
Sensors and Controls
North America Sensor Market
Sensors and Controls
Thermography Condition Monitoring Equipment Market
Sensors and Controls
MEMS Energy Harvesting Devices Market
Sensors and Controls
Smart Pressure Gauge Market
Sensors and Controls
Wind Vane Sensor Market
Sensors and Controls
Latin America Proximity Sensors Market
Sensors and Controls
Europe Digital Thermometer Market
Sensors and Controls
Asia-Pacific Wireless Brain Sensors Market
Sensors and Controls
Automotive MEMS Sensor Market
Sensors and Controls
North America Bulk Acoustic Wave Sensors Market