
 APAC Pressure Sensors Market | 2026-2036
APAC Pressure Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Pressure Sensors Market Outlook
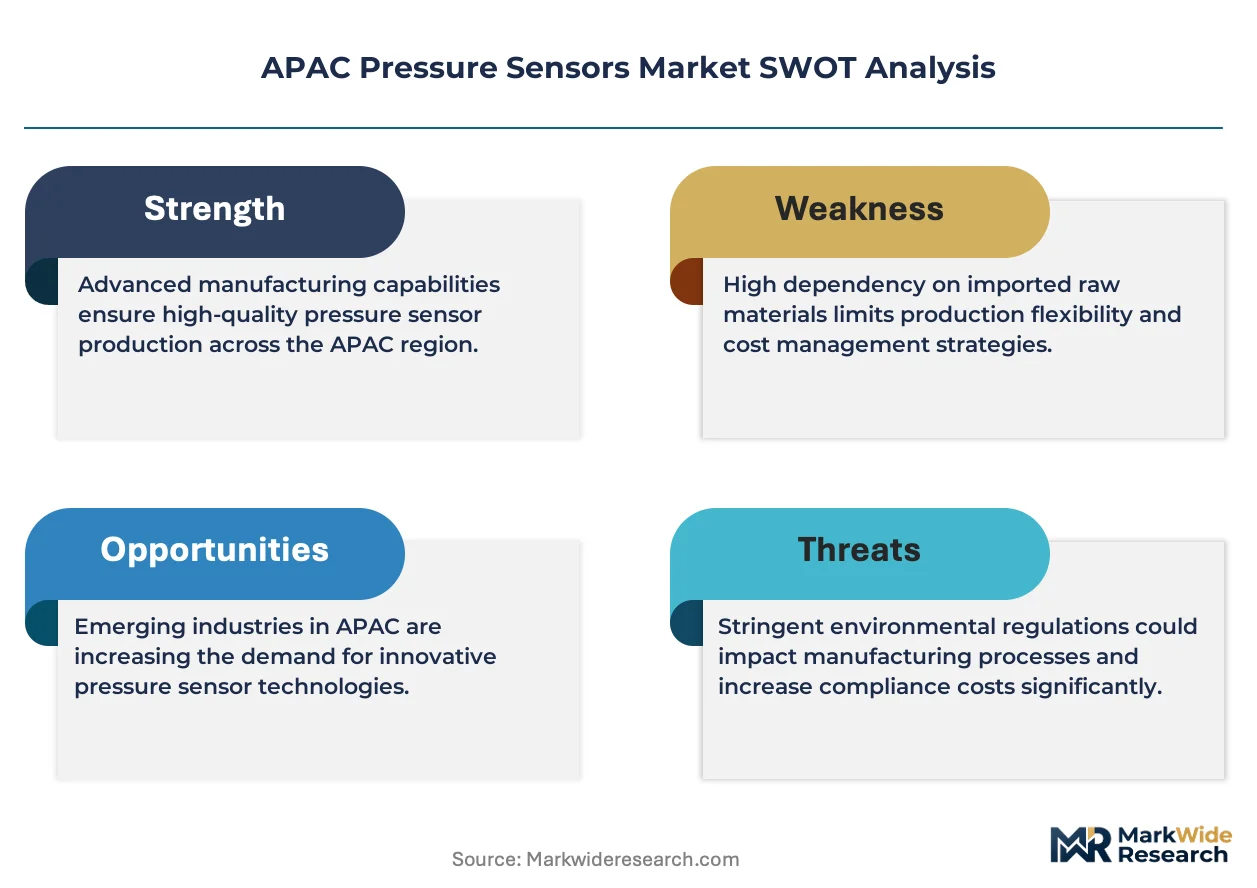
Asset-light leasing models for MEMS fabrication equipment is narrowing the capital barrier for mid-tier entrants in the APAC pressure sensor supply chain. Bosch Sensortec GmbH leverages captive wafer capacity to sustain margin control across automotive piezoelectric lines. TE Connectivity anchors its position through deep backward integration into ceramic substrate production. Honeywell International Inc. differentiates via aerospace-grade calibration protocols that command premium positioning in industrial safety applications.
Pressure sensors transduce fluid or gas pressure into electrical signals through piezoresistive, capacitive, or strain-sensitive elements, typically operating across ranges from millibars to thousands of bars with accuracy thresholds of ±0.1% full scale. These devices enable closed-loop process control, leak detection, and safety interlock functions in fluid-handling systems. Strain gauge variants dominate mature industrial installations where cost sensitivity outweighs miniaturization needs, while capacitive architectures capture expanding share in medical ventilators and wearable diagnostic equipment. Wireless technology segments are outpacing analog counterparts in oil and gas deployment, driven by reduced cabling costs in remote wellhead monitoring across Australian and Indonesian fields.
China's MIIT enforces GB standards for automotive pressure sensor reliability under new energy vehicle certification protocols, while Japan's METI administers JIS benchmarks that govern industrial sensor interoperability. India's BIS mandates pressure equipment certification for process industries under the Pressure Equipment Directive alignment, tightening market access for uncertified imports. Stakeholders must monitor evolving cross-border data localization rules affecting smart sensor cloud connectivity, as Australia's TGA and South Korea's MFDS advance separate cybersecurity frameworks for networked medical devices that incorporate pressure monitoring functions.
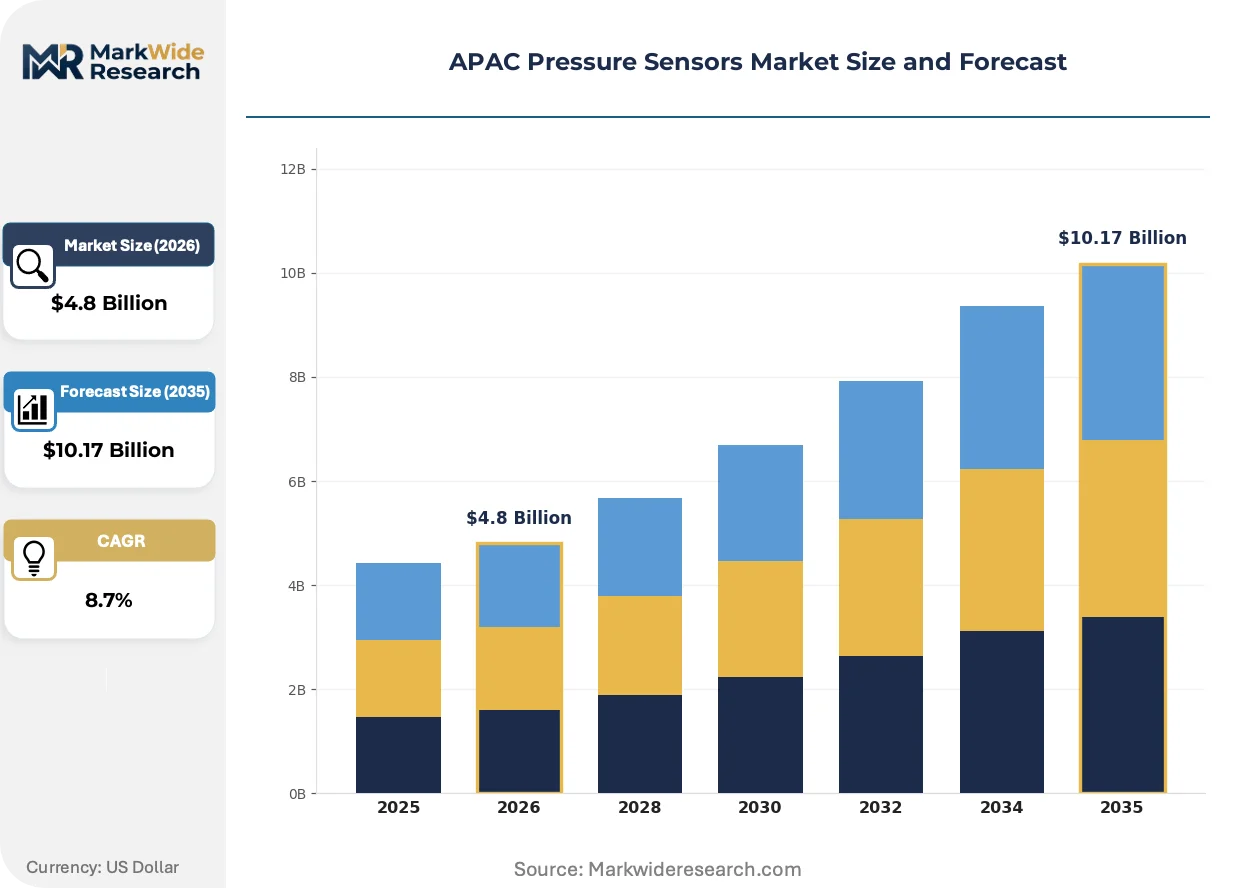
Market Dynamics
Automotive electrification programs across China, Japan, and South Korea are restructuring demand toward high-precision piezoelectric modules, while MIIT dual carbon mandates and BIS industrial safety certifications tighten performance thresholds for regional suppliers.
Growth Catalysts
- EV Powertrain Integration:China's new energy vehicle certification protocols under MIIT mandate pressure monitoring across battery thermal management systems, pulling silicon MEMS demand from tier-one suppliers.
- GB Standards Harmonization:Reliability benchmarks for automotive sensors are accelerating OEM localization in the Yangtze River Delta manufacturing cluster.
- Medical Device Expansion:Capacitive architectures are capturing share in ventilator and wearable diagnostic equipment as Australia's TGA advances networked device frameworks.
Market Restraints
- Wafer Supply Concentration:Captive fabrication capacity at dominant sensor manufacturers limits substrate access for mid-tier entrants across the region.
- Ceramic Substrate Volatility:Backward integration into alumina and zirconia production constrains margin flexibility for non-integrated assemblers.
- Calibration Protocol Fragmentation:Divergent aerospace-grade and industrial-grade certification requirements create SKU proliferation without volume leverage.
Strategic Opportunities
- Indonesian Oilfield Wireless Deployment:Reduced cabling costs in remote wellhead monitoring are outpacing analog counterpart adoption across Australian and Indonesian fields.
- India BIS Certification Gap:Pressure equipment mandates under industrial safety alignment create first-mover advantage for certified module suppliers.
- MEMS Fabrication Leasing:Asset-light equipment models are narrowing capital barriers for mid-tier supply chain entrants in secondary manufacturing hubs.
Industry Challenges
- Cross-Border Data Localization:Australia's TGA and South Korea's MFDS are advancing separate cybersecurity frameworks for cloud-connected smart sensors, complicating unified product architectures.
- Piezoresistive-Capacitive Process Integration:Hybrid manufacturing lines require dual cleanroom protocols that strain operational flexibility at multi-product facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Pressure Sensors Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Strain Gauge, Capacitive, Piezoelectric, Optical End User: Automotive, Oil & Gas, Healthcare, Industrial Technology: Analog, Digital, Wireless, Smart Application: Process Control, Level Measurement, Safety, Environmental Monitoring |
| Companies Covered | SensatA Technologies, Honeywell International Inc., Bosch Sensortec GmbH, ABB Ltd., Siemens AG, Robert Bosch GmbH, TDK Corporation, NXP Semiconductors, TE Connectivity, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Pressure Sensors Market Strategic Shifts
Digital twin architectures and wireless telemetry are compressing traditional sensor value chains, while regulatory fragmentation across MIIT, METI, and BIS jurisdictions is forcing modular certification strategies.
Silicon carbide MEMS pressure transducers are virtualizing thermal compensation circuits previously implemented through discrete analog components. Automotive OEMs in South Korea and China are adopting these devices for battery pack monitoring at accelerated qualification cycles. The technology is virtualizing signal conditioning hardware into firmware layers, reducing bill-of-materials complexity while shifting value toward embedded software calibration.
Japan's METI is administering revised JIS benchmarks governing industrial sensor interoperability across process automation networks. The standards mandate standardized digital output protocols that compress integration timelines for multi-vendor installations. Process industries in the Kansai and Chubu manufacturing belts are responding by consolidating procurement around certified platform suppliers.
Buyers are unbundling after-sales calibration services from initial hardware contracts, compressing supplier recurring revenue streams. Industrial safety distributors in India and Southeast Asia are replacing bundled service models with third-party metrology laboratory partnerships. This pattern is most visible in pharmaceutical and food processing verticals where BIS and CDSCO traceability requirements demand independent verification chains.
APAC Pressure Sensors Market Segmentation
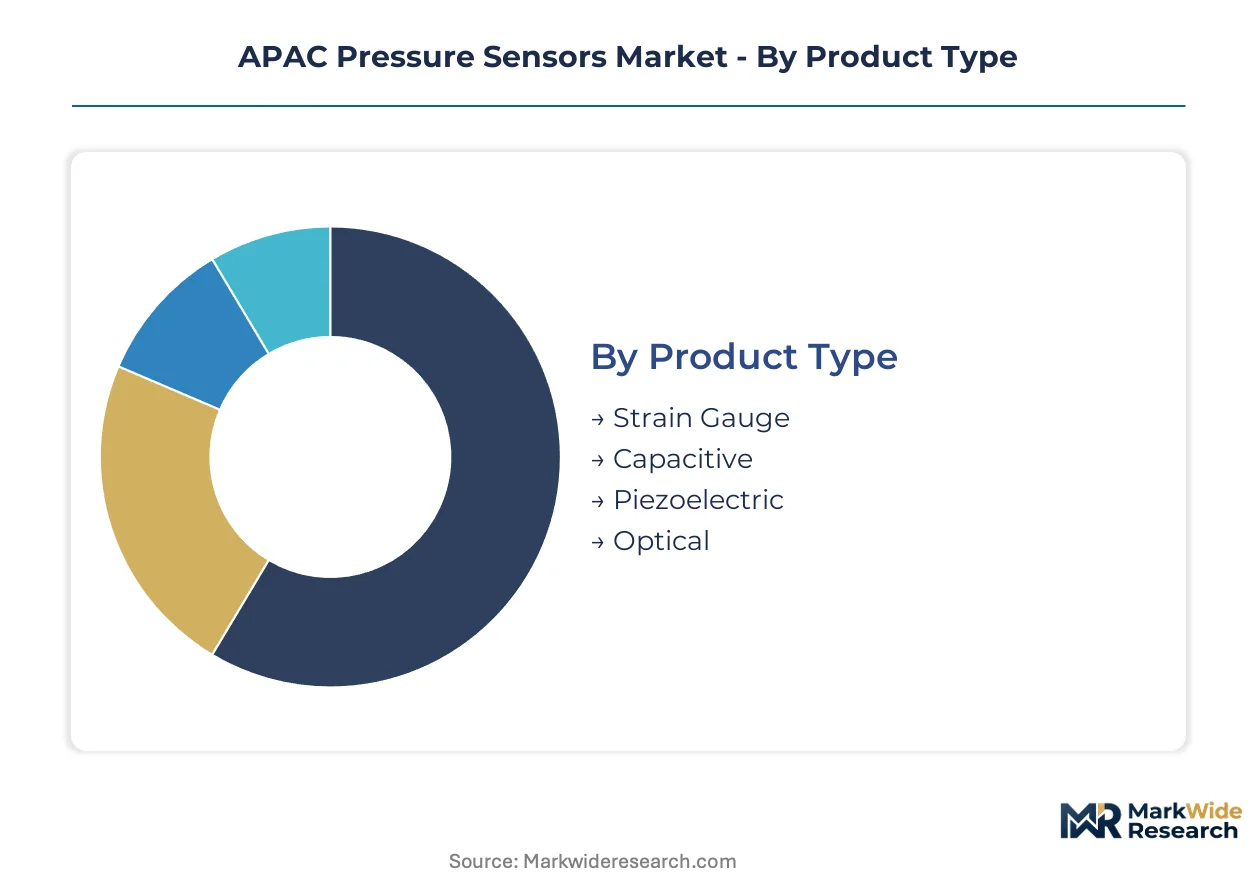
Pressure sensor segmentation in APAC reflects divergent service intensity across end-use verticals. Automotive and medical applications demand embedded calibration support, while industrial buyers unbundle after-sales contracts to third-party metrology labs.
Product Type:
After-sales calibration intensity varies sharply across sensing architectures, with piezoelectric modules requiring aerospace-grade recertification protocols that strain supplier service bandwidth.
- Strain Gauge:Mature metal-foil or semiconductor strain elements dominate legacy industrial installations across India's process plants and China's steel mills. Cost sensitivity in these mature sectors outweighs miniaturization needs, though BIS certification mandates are tightening traceability requirements for replacement cycles.
- Capacitive:MEMS-based capacitive cells achieve sub-millibar resolution through differential pressure measurement across micromachined diaphragms. Australia's TGA and South Korea's MFDS are advancing networked device frameworks that pull capacitive architectures into ventilator and wearable diagnostic equipment as cybersecurity compliance becomes mandatory.
- Piezoelectric:Ceramic crystal elements generate charge signals under mechanical stress, serving high-temperature automotive powertrain applications. MIIT dual carbon mandates are accelerating silicon carbide MEMS substitution.
- Optical:Fiber Bragg grating and interferometric designs isolate electronics from hazardous media in Indonesian and Australian oilfield deployments.
By volume, Strain Gauge leads. By growth pace, Capacitive is ahead.
End User:
Cost tier stratification separates premium-grade automotive modules from economy industrial sensors, with certification grade driving pricing spreads more than raw performance specifications.
- Automotive:Battery thermal management and fuel cell pressure monitoring are pulling silicon MEMS demand from Yangtze River Delta suppliers serving BYD and Tesla Shanghai. MIIT new energy vehicle certification protocols mandate redundant sensing architectures that double module counts per vehicle platform.
- Oil & Gas:Wireless telemetry is displacing analog cabling in remote Indonesian and Australian wellhead monitoring, with reduced installation costs justifying sensor hardware premiums. Asset operators are consolidating procurement around platform suppliers offering integrated cloud connectivity.
- Healthcare:Capacitive architectures are capturing ventilator and diagnostic equipment share as Australia's TGA advances separate cybersecurity frameworks from South Korea's MFDS, complicating unified product architectures.
- Industrial:Process control installations across Japan's Kansai and Chubu belts are consolidating around METI-certified platform suppliers as revised JIS benchmarks mandate standardized digital output protocols.
Automotive commands the highest unit values. Healthcare is climbing the fastest.
Technology:
Customer type bifurcation separates OEM-specified embedded modules from aftermarket replacement sensors, with procurement patterns diverging on calibration service bundling.
- Analog:Voltage or current-loop outputs dominate legacy process control infrastructure across mature industrial belts where digital retrofit economics remain unfavorable.
- Digital:I2C and SPI interfaces enable direct microcontroller integration, accelerating adoption in South Korean and Chinese automotive battery management systems.
- Wireless:LoRaWAN and proprietary radio protocols are eliminating cabling costs in Australian and Indonesian oilfield deployments, with battery life optimization becoming a competitive differentiator.
- Smart:Edge-computing sensors with embedded firmware calibration are virtualizing signal conditioning hardware, shifting value toward software layers in premium automotive and medical applications.
Analog retains installed base dominance. Smart sensors are expanding most quickly.
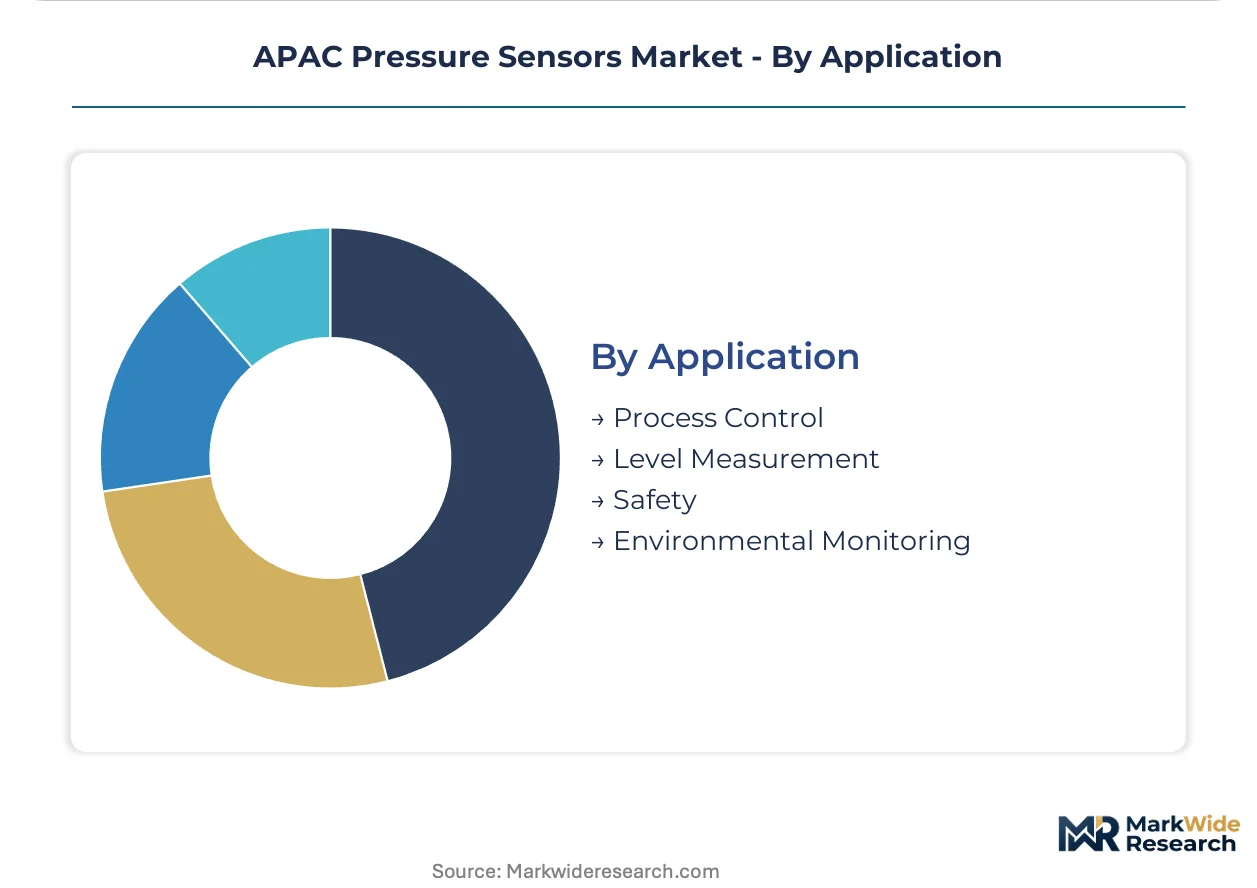
Application:
Supply concentration in the Yangtze River Delta and Japan's Chubu region shapes application-level availability, with certified suppliers prioritizing automotive safety and process control over environmental monitoring volume.
- Process Control:Closed-loop pressure regulation in fluid-handling systems requires ±0.1% full-scale accuracy thresholds that strain calibration infrastructure at Indian and Southeast Asian metrology labs.
- Level Measurement:Hydrostatic and differential pressure methods serve tank inventory management across China's petrochemical complexes and Australia's LNG facilities.
- Safety:Pressure interlock functions protect personnel and equipment in high-pressure processes governed by India's BIS pressure equipment mandates and Japan's METI industrial safety alignment.
- Environmental Monitoring:Atmospheric and water quality sensing applications face margin compression as procurement shifts toward low-cost uncertified imports for non-critical deployments.
Process Control leads by revenue contribution. Safety applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for high-precision MEMS substrates characterizes the regional trade balance, with fabrication equipment flows concentrating from Japan and South Korea toward Chinese packaging facilities. Export competitiveness hinges on MIIT certification alignment and BIS industrial safety mandates that filter supplier eligibility.
China
MIIT dual carbon mandates and new energy vehicle certification protocols are pulling silicon MEMS demand for battery thermal management systems. GB standards harmonization for automotive sensor reliability accelerates OEM localization requirements. The Yangtze River Delta manufacturing cluster hosts tier-one suppliers serving BYD, Tesla Shanghai, and domestic EV brands with aggressive localization targets.
Japan
METI-administered JIS benchmarks govern industrial sensor interoperability across process automation networks, compressing integration timelines for multi-vendor installations. Revised digital output protocol mandates are consolidating procurement around certified platform suppliers. The Kansai and Chubu manufacturing belts represent concentrated demand centers for standardized pressure instrumentation.
India
BIS certification mandates for industrial safety equipment under pressure equipment directive alignment are tightening market access for uncertified imports. Process industries face replacement cycle traceability requirements that strain domestic metrology infrastructure. Pharmaceutical and food processing verticals in Maharashtra and Gujarat are unbundling calibration services to third-party laboratory partnerships.
South Korea
MFDS cybersecurity frameworks for networked medical devices are complicating unified product architectures for capacitive pressure sensors in diagnostic equipment. Automotive battery management system demand is accelerating I2C and SPI interface adoption from domestic semiconductor suppliers. Seoul Capital Area fabricators maintain captive wafer capacity for automotive piezoelectric lines.
Australia
TGA-advanced cybersecurity requirements for cloud-connected smart sensors are fragmenting regulatory compliance across medical device categories. Wireless telemetry deployment in remote wellhead monitoring across Western Australian and Queensland LNG fields is outpacing analog counterpart adoption. Reduced cabling costs justify sensor hardware premiums in offshore and onshore asset operations.
APAC Pressure Sensors Market Competitive Environment
On the supply side, the industry is structured around three distinct capability tiers: integrated semiconductor conglomerates with captive fabrication, specialized sensor houses with deep backward integration into ceramic substrates, and modular assemblers dependent on leased MEMS equipment. Strategic archetypes include scale-driven volume players, premium-tier certification specialists, and asset-light regional entrants. Dominant competitive moves encompass backward integration into alumina and zirconia production to secure margin control, and geographic expansion through certified platform partnerships in secondary manufacturing hubs.
Among Germany-based fabricators, Bosch Sensortec GmbH exemplifies the captive-capability archetype, while TE Connectivity anchors the deep-integration tier through in-house ceramic substrate production. Honeywell International Inc. occupies a position representing premium-tier differentiation via aerospace-grade calibration protocols. These three entities collectively illustrate the competitive spectrum from volume-scale MEMS production to high-reliability industrial safety positioning.
| Leading Market Players |
|---|
| SensatA Technologies |
| Honeywell International Inc. |
| Bosch Sensortec GmbH |
| ABB Ltd. |
| Siemens AG |
| Robert Bosch GmbH |
| TDK Corporation |
| NXP Semiconductors |
| TE Connectivity |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta manufacturing cluster concentrates silicon MEMS fabrication capacity for battery thermal management systems, translating captive wafer supply into pricing leverage for tier-one suppliers serving BYD and Tesla Shanghai. This geographic concentration enables premium positioning for automotive-grade modules while compressing margins for non-integrated assemblers dependent on spot substrate markets.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the APAC pressure sensor market. Certification grade under MIIT new energy vehicle protocols and BIS industrial safety mandates drives sharper price spreads than raw performance specifications, with aerospace-grade calibration protocols commanding substantial premiums over uncertified alternatives. Pricing pressure stems from unbundling of after-sales calibration services to third-party metrology labs, eroding supplier recurring revenue. Pharmaceutical and food processing verticals exhibit highest price sensitivity due to traceability requirements, while automotive safety module procurement shows lowest elasticity given liability exposure.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Japanese and South Korean equipment vendors are easing capital constraints for Chinese packaging facilities expanding MEMS capacity. Raw material dependencies center on alumina and zirconia ceramic substrates, silicon wafers, and piezoelectric ceramics, with fabrication equipment flows concentrating from Japan and South Korea. Single-source vulnerability characterizes high-precision MEMS substrate supply, where captive capacity at Bosch Sensortec and TE Connectivity limits spot market access. Distribution runs through direct OEM contracts for automotive tier-one suppliers and industrial safety distributors for replacement cycles across Indian process plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The APAC pressure sensor market rewards service-attach strategies, with after-sales calibration and recertification protocols expanding faster than hardware unit growth as buyers unbundle bundled service models.
For Market Incumbents: Build certification moats through aggressive BIS and MIIT accreditation investment ahead of tightening industrial safety mandates. Deepen backward integration into ceramic substrate production to defend margin control against mid-tier entrants leveraging leased MEMS equipment. Threat substitution from silicon carbide MEMS virtualization of analog signal conditioning demands accelerated firmware calibration capability development. Priority lever rests on consolidating procurement relationships as Japan's METI JIS benchmarks mandate standardized digital output protocols. For New Entrants and Emerging Players: Indian pharmaceutical and food processing verticals present underpenetrated white-space as BIS pressure equipment certification mandates strain domestic metrology infrastructure. Indonesian oilfield wireless telemetry deployment offers second entry vector, with reduced cabling costs justifying sensor hardware premiums against established analog suppliers. Asset-light MEMS fabrication leasing models narrow capital barriers for secondary manufacturing hub establishment. Go-to-market angle should target third-party calibration laboratory partnerships replacing bundled supplier service models. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform suppliers with embedded firmware calibration capabilities capturing value migration from hardware to software layers. Long-term viability hinges on regulatory certification breadth across MIIT, METI, BIS, and MFDS jurisdictions as fragmentation intensifies. Acquisition target archetype combines captive wafer capacity with aerospace-grade calibration infrastructure. Watch silicon carbide MEMS adoption curves in South Korean and Chinese automotive battery management systems as inflection indicator for piezoelectric displacement timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrates | In-house alumina and zirconia production secures margin control against raw material volatility. |
| MIIT Certification Pre-Positioning | Early GB standards alignment captures OEM localization mandates in Yangtze River Delta cluster. |
| Wireless Telemetry Platform Development | LoRaWAN integration eliminates cabling costs in Australian and Indonesian oilfield deployments. |
| Calibration Service Unbundling Partnerships | Third-party metrology lab relationships replace eroding bundled supplier revenue streams. |
| Silicon Carbide MEMS Transition | Virtualized thermal compensation circuits reduce bill-of-materials complexity in automotive applications. |
Study Parameters
A spread of perspectives from MEMS fabrication engineers, automotive Tier 1 procurement managers, industrial safety distributors, and pharmaceutical plant maintenance directors converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through MIIT regulatory filings, METI JIS benchmark documentation, BIS certification registries, and customs trade data for pressure sensor component flows. Bottom-up unit economics from Yangtze River Delta suppliers triangulated against top-down demand modeling from EV powertrain integration requirements.
Demand-supply balance dynamics across the analysis window anchored the quantitative framework, with segmentation modeling spanning sensing architecture type, end-use vertical, technology interface, and application function. Automotive battery thermal management system content per vehicle, industrial process control replacement cycles, and medical device cybersecurity compliance thresholds served as industry-specific forecast inputs. CAGRs derived from installed base growth rates and technology substitution curves rather than extrapolated historical trends.
Practitioners should monitor regulatory divergence across Australia's TGA and South Korea's MFDS cybersecurity frameworks, ceramic substrate spot price volatility, and silicon carbide MEMS qualification timelines for early signals of forecast revision. Macroeconomic deviation in Chinese EV subsidy programs, regulatory acceleration in India's BIS enforcement, or breakthroughs in optical pressure sensing would prompt reassessment of projected market trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Fluid Management and Visualization Systems Market
Sensors and Controls
Force Sensor Market
Sensors and Controls
Middle East and Africa Touch Sensor Market
Sensors and Controls
Off-Highway Machine Position and Angle Sensor Components Market
Sensors and Controls
SQUID Sensor Market
Sensors and Controls
Steam Flow Meter Market
Sensors and Controls
North America Temperature Sensor Market
Sensors and Controls
Europe Machine Control System Market
Sensors and Controls
Control Knobs for Panel Potentiometer Market
Sensors and Controls
Artificial Intelligence (AI) Sensor Market
Sensors and Controls
Inline Quality Control Sensors Market
Sensors and Controls
Virtual Sensors Market
Sensors and Controls
Piezoelectric MEMS Resonators Market
Sensors and Controls
PID Controller Market
Sensors and Controls
Digital Array Microphone Market
Sensors and Controls
Europe Human Machine Interface Market