
 Europe Emission Monitoring System Market | 2026-2036
Europe Emission Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Emission Monitoring System Market Insights
The EU Green Deal is realigning capital allocation across European industrial compliance budgets. Siemens leverages its automation heritage to anchor turnkey CEMS installations across German power corridors. ABB competes through integrated digital twin architectures that extend hardware lifecycle value for utility clients. Emerson Electric specializes in predictive maintenance overlays that differentiate its analyzer portfolios from commodity sensor suppliers.
Emission monitoring systems comprise sensor arrays, gas analyzers, and data acquisition platforms engineered to quantify pollutant concentrations in industrial exhaust streams, typically measuring SO2, NOx, CO, and particulate matter at detection thresholds below one part per million for regulatory certification. Continuous Emission Monitoring Systems occupy the largest installed base due to mandated 24/7 reporting under EU Industrial Emissions Directive requirements, while Portable Analyzers represent the fastest-expanding category as environmental consultants deploy flexible audit tools across fragmented manufacturing sites. Infrared Sensors lead technology adoption for their non-dispersive absorption reliability in high-humidity stack environments, whereas Chemiluminescence dominates NOx-specific measurement where precision drives permit compliance.
EMA standards for analyzer certification and the EU Green Deal's carbon border adjustment mechanisms are tightening product qualification requirements, forcing vendors to redesign sensor platforms for traceability and interoperability. REACH compliance obligations on sensor materials and the F-Gas Regulation's phase-down of fluorinated calibration gases are reshaping supply chain specifications for component sourcing. Stakeholders must monitor how the EU AI Act's risk classification rules will apply to autonomous emission prediction algorithms embedded in next-generation monitoring platforms.
Market Dynamics
EU Industrial Emissions Directive enforcement is compressing compliance timelines for power utilities and cement manufacturers, forcing capital reallocation toward continuous monitoring infrastructure and away from periodic manual testing regimes.
Growth Catalysts
- EU Green Deal carbon border adjustments:German steel producers are accelerating stack monitoring deployments to document emissions intensity for CBAM declarations on exports to third countries.
- Power generation utilities:Dutch coal-to-biomass conversion projects require upgraded CEMS capable of measuring variable particulate loads from mixed fuel combustion.
- Infrared sensor platforms:Non-dispersive absorption technology is penetrating Polish heavy industry due to operational reliability in high-humidity flue gas conditions.
Market Restraints
- Fluorinated calibration gas phase-down:F-Gas Regulation restrictions are constraining supply chains for reference gases essential to analyzer certification.
- Sensor material compliance costs:REACH obligations on rare earth elements in electrochemical cells are elevating component qualification expenses.
- Technical limitation in mercury measurement:Cold vapor atomic absorption systems face detection threshold gaps for sub-ppb regulatory requirements in waste incineration.
Strategic Opportunities
- Romanian industrial zones:EU cohesion fund allocations are financing first-time CEMS installations at retrofitted manufacturing clusters.
- Digital twin convergence:ABB and Siemens are integrating physical analyzer hardware with predictive emissions modeling to extend service contract value.
- Environmental consultancy channel:Portable analyzer vendors are bypassing direct utility sales to reach fragmented food processing SMEs through certified audit firms.
Industry Challenges
- Analyzer technician scarcity:Specialized calibration expertise for chemiluminescence NOx systems is concentrating in German and Benelux service hubs.
- Legacy data integration:Pre-2015 SCADA architectures at Spanish power plants require expensive middleware to achieve EU AI Act traceability standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Emission Monitoring System Market |
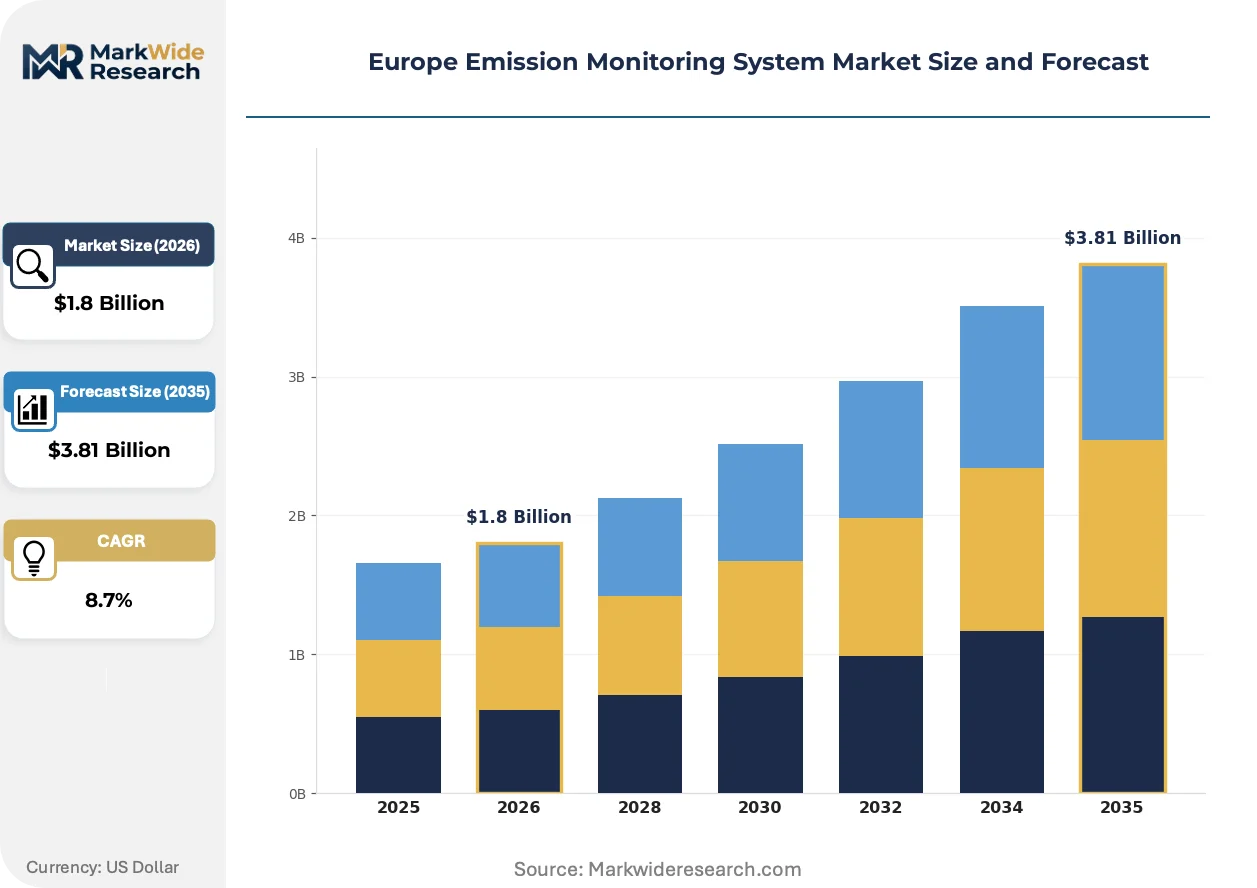
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Emission Monitoring Systems, Stack Test Equipment, Air Quality Monitors, Portable Analyzers Technology: Infrared Sensors, Gas Chromatography, Chemiluminescence, Optical Sensors Application: Power Generation, Oil & Gas, Waste Management, Manufacturing End User: Utilities, Industries, Regulatory Agencies, Environmental Consultants |
| Companies Covered | Siemens, ABB, Emerson Electric, AMETEK, Honeywell International, Thermo Fisher Scientific, SICK AG, Horiba, Teledyne Technologies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Emission Monitoring System Market Trends and Innovations
Edge computing architectures are redistributing data processing from central control rooms to stack-mounted sensor nodes, compressing latency for real-time emissions alerts while complicating cybersecurity protocols.
Wireless mesh networking is decentralizing CEMS data transmission across industrial sites. Cement manufacturers in France are deploying battery-powered sensor clusters to bypass cabling costs in remote kiln installations. This topology is enabling rapid reconfiguration of monitoring zones without infrastructure overhauls.
F-Gas Regulation phase-down mandates are forcing analyzer recalibration protocols toward synthetic reference blends. REACH compliance on sensor materials is simultaneously tightening supply qualification for electrochemical cell manufacturers. Combined, these frameworks are extending procurement cycles for German utility operators by six to nine months.
Environmental audit firms are unbundling after-sales service from hardware procurement. Dutch consulting groups now specify analyzer brands based on interoperability with their proprietary data platforms rather than manufacturer service contracts. This pattern concentrates in Benelux and Scandinavian markets where third-party verification carries regulatory weight.
Europe Emission Monitoring System Market Segmentation
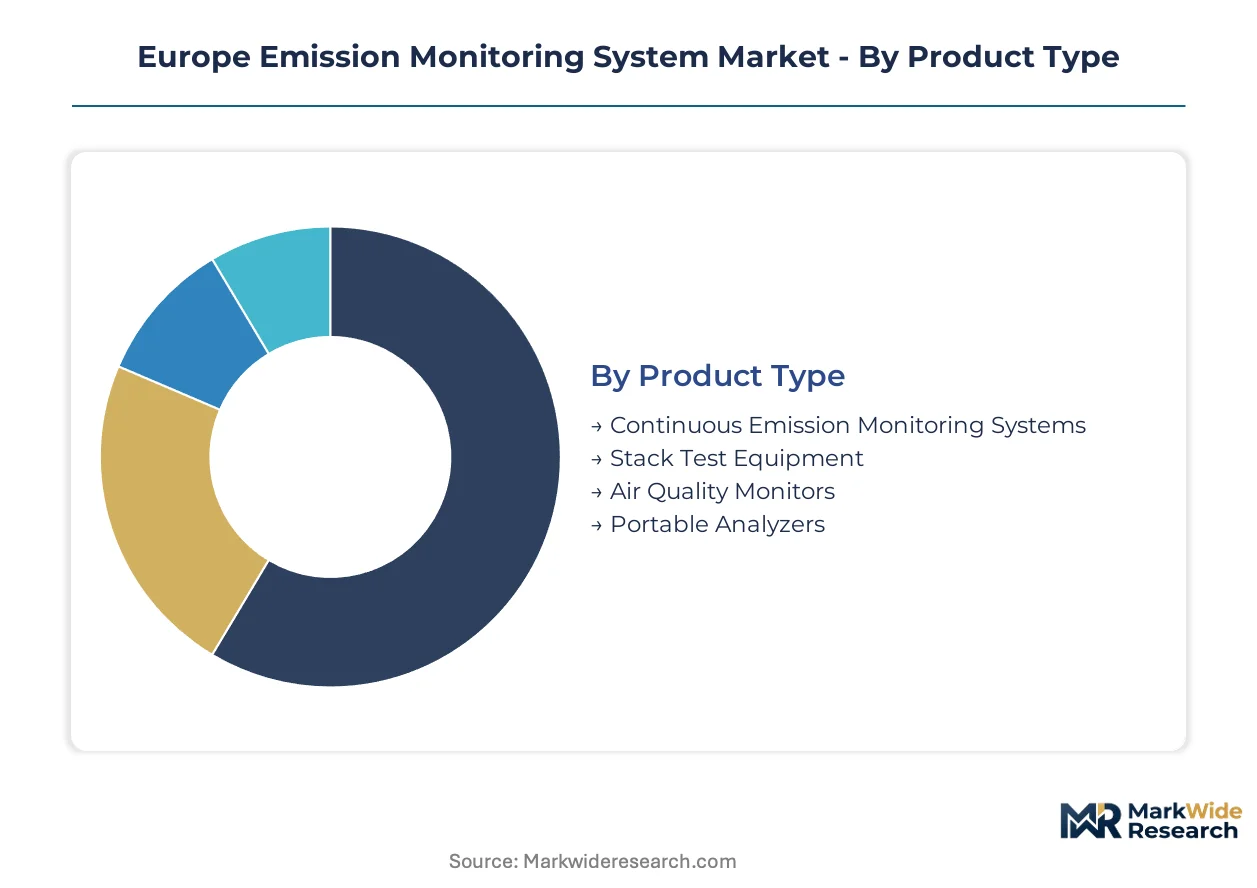
Segmentation in Europe's emission monitoring landscape reveals how regulatory pressure distributes across hardware architectures and operational contexts. Procurement patterns diverge sharply between continuous infrastructure investments and flexible audit tooling, with technology choices driven by specific pollutant targets and stack conditions.
Product Type:
Standalone rack-mounted systems dominate utility capital budgets, while embedded portable units serve fragmented compliance audits across industrial clusters.
- Continuous Emission Monitoring Systems:Permanent installations integrate sensor arrays, gas analyzers, and data acquisition platforms for 24/7 pollutant quantification at detection thresholds below one part per million. German power corridors under tightened EU Industrial Emissions Directive limits are compressing procurement timelines for these systems as operators phase out manual alternatives.
- Portable Analyzers:Battery-powered mobile units enable environmental consultants to conduct flexible stack testing across multiple sites without fixed infrastructure. Dutch consulting groups now specify analyzer brands based on interoperability with proprietary data platforms rather than manufacturer service contracts, accelerating category expansion.
- Stack Test Equipment:Periodic manual testing apparatus serves verification protocols and calibration cross-checks for continuous systems.
- Air Quality Monitors:Ambient perimeter sensors track fugitive emissions and community exposure at facility boundaries.
Continuous Emission Monitoring Systems lead volumes today; Portable Analyzers are gaining share fastest.
Technology:
Cost tiers separate proven absorption methods from precision spectroscopic techniques, with humidity tolerance and NOx specificity driving selection.
- Infrared Sensors:Non-dispersive absorption platforms deliver operational reliability in high-humidity flue gas conditions without consumable reagents. Polish heavy industry has penetrated this technology most aggressively due to stack moisture challenges in coal-dependent power generation.
- Chemiluminescence:NOx-specific measurement achieves sub-ppb precision through reaction-luminescence detection, commanding premium positioning where permit compliance margins are tight. German cement manufacturers deploying this technology face calibration gas supply constraints under F-Gas Regulation phase-down mandates.
- Gas Chromatography:Separates complex hydrocarbon mixtures for speciated organic pollutant identification in petrochemical applications.
- Optical Sensors:Laser-based particulate measurement addresses opacity and dust loading in biomass combustion stacks.
Infrared Sensors anchor the installed base across cost-sensitive deployments; Chemiluminescence commands the steepest expansion trajectory in precision-regulated segments.
Application:
Customer maturity varies by sector, with power utilities operating fully automated compliance architectures while manufacturing retains hybrid manual-periodic approaches.
- Power Generation:Coal-to-biomass conversion projects in the Netherlands require upgraded CEMS capable of measuring variable particulate loads from mixed fuel combustion, driving replacement cycles.
- Oil & Gas:Refinery flare monitoring and fugitive emission detection at storage terminals deploy integrated sensor networks.
- Waste Management:Incineration facilities face sub-ppb mercury detection gaps in cold vapor atomic absorption systems, constraining technology choices.
- Manufacturing:Fragmented food processing SMEs in Benelux rely on third-party environmental audit firms rather than captive monitoring infrastructure.
Power Generation concentrates the largest installed capacity; Waste Management faces the steepest technical upgrade requirements.
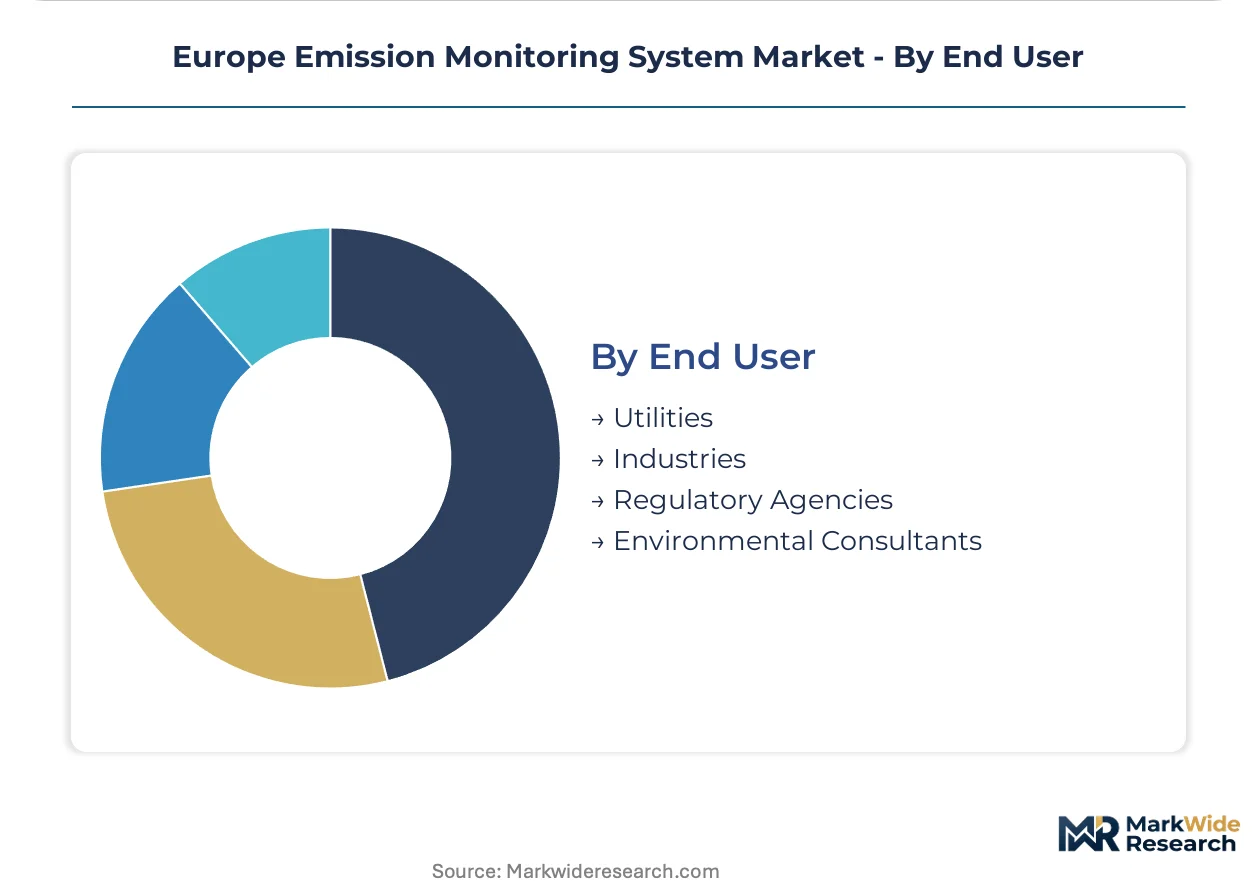
End User:
Procurement authority splits between captive operators with long-term service contracts and external auditors specifying hardware for intermittent deployment.
- Utilities:German and Dutch power operators maintain multi-year framework agreements with Siemens and ABB for turnkey CEMS installations and predictive maintenance overlays.
- Industries:Steel producers across the Ruhr region accelerate stack monitoring deployments to document emissions intensity for EU Green Deal carbon border adjustment declarations.
- Regulatory Agencies:National environmental authorities specify certification protocols under EMA analyzer standards and enforce EU Industrial Emissions Directive compliance timelines.
- Environmental Consultants:Certified audit firms in Scandinavian markets unbundle after-sales service from hardware procurement, selecting analyzers based on data platform interoperability.
Utilities dominate capital deployment; Environmental Consultants are expanding procurement influence fastest through audit-channel specification authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Calibration technicians for chemiluminescence NOx systems concentrate in German and Benelux service hubs, anchoring regional technical capacity for precision analyzer maintenance.
Germany
Power utilities along the Rhine corridor deploy turnkey CEMS installations under tightened EU Industrial Emissions Directive limits. Steel producers across the Ruhr region accelerate stack monitoring to document emissions intensity for EU Green Deal carbon border adjustment declarations. Siemens anchors automation heritage in German power corridors through continuous monitoring infrastructure.
Netherlands
Coal-to-biomass conversion projects require upgraded CEMS capable of measuring variable particulate loads from mixed fuel combustion. Dutch consulting groups specify analyzer brands based on interoperability with proprietary data platforms rather than manufacturer service contracts. Port of Rotterdam industrial clusters phase out manual stack testing in favor of continuous emission monitoring systems.
Poland
Heavy industry penetrates infrared sensor platforms aggressively due to stack moisture challenges in coal-dependent power generation. F-Gas Regulation restrictions constrain supply chains for reference gases essential to analyzer certification. Silesian industrial basins retrofit manufacturing clusters with first-time CEMS installations financed through EU cohesion fund allocations.
France
Cement manufacturers deploy battery-powered sensor clusters to bypass cabling costs in remote kiln installations through wireless mesh networking topologies. EMA standards for analyzer certification tighten product qualification requirements for traceability and interoperability. Lyon-Grenoble industrial corridors integrate edge computing architectures that redistribute data processing to stack-mounted sensor nodes.
Spain
Pre-2015 SCADA architectures at power plants require expensive middleware to achieve EU AI Act traceability standards for autonomous emission prediction algorithms. REACH compliance obligations on sensor materials elevate component qualification expenses for electrochemical cell manufacturers. Basque Country manufacturing sites confront legacy data integration challenges while upgrading monitoring infrastructure.
Europe Emission Monitoring System Market Competitive Landscape
The competitive structure tilts toward diversified industrial automation conglomerates with heritage in power sector instrumentation. Siemens and ABB anchor the premium tier through integrated digital architectures that extend hardware lifecycle value. Emerson Electric occupies a differentiated position through predictive maintenance overlays. Strategic moves concentrate on digital twin convergence and unbundling after-sales service from hardware procurement.
Among diversified automation specialists, Siemens, ABB, and Emerson Electric exemplify three competitive archetypes. Siemens represents turnkey installation heritage anchored in German industrial corridors. ABB exemplifies integrated digital twin architectures that merge physical analyzer hardware with predictive emissions modeling. Emerson Electric occupies the predictive maintenance overlay tier, differentiating analyzer portfolios from commodity sensor suppliers through service contract value extension.
| Leading Market Players |
|---|
| Siemens |
| ABB |
| Emerson Electric |
| AMETEK |
| Honeywell International |
| Thermo Fisher Scientific |
| SICK AG |
| Horiba |
| Teledyne Technologies |
| Others |
Pricing and Supply Chain Analysis
Analyzer certification tiers under EMA standards bifurcate hardware procurement into premium precision-grade systems and cost-optimized compliance units, with this divergence manifesting in both pricing premiums of 15-25% for certified platforms and supply chain configurations that concentrate high-specification component sourcing in German and Benelux manufacturing corridors while routing economy-tier assemblies through Eastern European contract manufacturers.
Pricing Analysis
Service bundling versus unbundling now defines pricing architecture across European emission monitoring procurement. Turnkey CEMS installations from Siemens and ABB command premium positioning through multi-year predictive maintenance overlays, while Dutch consulting groups drive price compression by specifying analyzers based on data platform interoperability rather than manufacturer service contracts. Price differentiation hinges on EMA certification grade and after-sales service integration, with margins tightening in the portable analyzer tier due to environmental audit firm purchasing consolidation. Utilities demonstrate lowest price sensitivity given regulatory non-compliance penalties, whereas fragmented food processing SMEs in Benelux prioritize capital expenditure minimization over performance headroom.
Supply Chain Analysis
Specialized calibration technician scarcity in German and Benelux service hubs constrains analyzer maintenance capacity and extends lead times for precision-grade system deployment. Component manufacturing concentrates in Germany, the Netherlands, and Switzerland for sensor arrays and gas analyzer subassemblies, while electrochemical cell production draws from Chinese and South Korean rare earth processing. Supply chain risk centers on F-Gas Regulation restrictions constraining fluorinated reference gas availability for analyzer certification. Distribution runs through direct utility framework agreements and environmental consultancy channel partnerships, with the latter gaining specification authority fastest in Scandinavian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in predictive maintenance overlays and digital twin service layers, as hardware commoditization pressures force vendors toward recurring revenue models anchored in emissions data analytics rather than capital equipment sales.
For Market Incumbents: Anchor defensive positioning through captive calibration gas supply arrangements that mitigate F-Gas Regulation phase-down exposure, while deepening predictive maintenance capabilities to extend service contract value beyond hardware replacement cycles. Siemens and ABB must consolidate technical talent in German and Benelux service hubs before competitor recruitment erodes maintenance response capabilities. Certification investment in EU AI Act traceability standards for autonomous emission algorithms represents a critical differentiation lever against emerging digital-native entrants. For New Entrants and Emerging Players: Launch via environmental consultancy channel partnerships in Romanian and Polish industrial zones where EU cohesion fund allocations finance first-time CEMS installations without incumbent service contract lock-in. Portable analyzer white space concentrates in food processing SME audits across fragmented Benelux manufacturing clusters, where third-party verification carries regulatory weight and direct utility sales penetration remains minimal. Target interoperability certification with Dutch consulting group proprietary data platforms as the primary go-to-market credential. For Investors and Strategic Acquirers: Consolidation pressure builds where environmental audit firms unbundle after-sales service from hardware procurement and concentrate specification authority in proprietary data platform ecosystems. Long-term viability favors vendors with integrated digital twin architectures that merge physical analyzer hardware with predictive emissions modeling, extending service contract value through the projection horizon. Acquisition target archetype: mid-tier portable analyzer specialists with established consultancy channel relationships and REACH-compliant sensor material sourcing. Signal to watch: EU AI Act enforcement timelines for autonomous emission prediction algorithm traceability requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | ABB and Siemens merge physical analyzers with predictive emissions modeling to extend service contract value. |
| Calibration Gas Backward Integration | Vendors secure captive fluorinated reference gas supply to mitigate F-Gas Regulation phase-down constraints. |
| Consultancy Channel Partnership | Portable analyzer vendors bypass direct utility sales to reach fragmented SMEs through certified audit firms. |
| EU AI Act Traceability Certification | Next-generation platforms embed autonomous emission prediction algorithms compliant with risk classification rules. |
| Wireless Mesh Networking Deployment | Cement manufacturers in France deploy battery-powered sensor clusters to bypass cabling costs in remote installations. |
Research Methodology
Coverage spans Western Europe, Central Europe, and Nordic markets, with primary inputs from each region combined with secondary validation. The research incorporates interviews with utility environmental compliance officers, plant engineers at cement and steel facilities, environmental consultancy technical directors, and CEMS maintenance technicians across German and Benelux service hubs. Secondary sources include EMA analyzer certification databases, EU Industrial Emissions Directive enforcement records, F-Gas Regulation implementation reports, and customs data on sensor component trade flows. Bottom-up installation counts by facility type triangulate against top-down capital expenditure estimates from utility and industrial operator disclosures.
Granularity-level modeling disaggregates volume and value outputs by product type, technology platform, application sector, and end-user category across the projection horizon. The analytical framework incorporates country-specific regulatory enforcement timelines, fuel conversion project pipelines, and EU cohesion fund allocation schedules as demand-side inputs. CAGRs derive from regression analysis of historical installation patterns against regulatory milestone acceleration. Industry-specific forecast inputs include coal-to-biomass conversion timelines in Dutch power generation and REACH compliance cost trajectories for electrochemical cell manufacturers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU AI Act enforcement acceleration or F-Gas Regulation phase-down timeline compression. Material deviation in carbon border adjustment mechanism implementation schedules or EMA certification protocol revisions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Refrigeration Leak Detector Market
Sensors and Controls
Machine Control System Market
Sensors and Controls
Photodiode Sensors Market
Sensors and Controls
Sensor Based Sorting System Market
Sensors and Controls
Actigraphy Sensors Market
Sensors and Controls
Digital Pool Thermometers Market
Sensors and Controls
Smart Visor Market
Sensors and Controls
Conveyor Belt Tracking Devices Market
Sensors and Controls
Air Particle Monitor System Market
Sensors and Controls
Global Mid-And-High-Level Precision GPS Receiver Market
Sensors and Controls
Russia Non-Contact Infrared Thermometer Market
Sensors and Controls
China Industrial Sensors Market
Sensors and Controls
APAC Proximity Sensors Market
Sensors and Controls
Automotive Steering Sensors Market
Sensors and Controls
Europe Human Machine Interface Market
Sensors and Controls
MEMS Gyroscope Market