
 Asia-Pacific Military 4D Printing Market | 2026-2036
Asia-Pacific Military 4D Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Military 4D Printing Market Analytics
The EU Green Deal's materials sustainability mandates are expanding into defense procurement frameworks across Asia-Pacific, reshaping supplier qualification criteria for programmable materials. Materialise anchors European-origin technology transfer into regional defense supply chains. Stratasys leverages its polymer expertise to compete in high-temperature military applications. General Electric sustains its position through jet engine heritage adapted to adaptive component architectures.
Asia-Pacific military 4D printing deploys programmable materials that respond to thermal, electrical, or mechanical stimuli after fabrication, typically using shape-memory polymers or hydrogels processed through directed energy deposition or vat photopolymerization to achieve post-manufacture reconfiguration for adaptive camouflage, self-healing structures, and deployable field equipment. Material Jetting commands premium positioning for micron-precision defense electronics housings where stimulus response tolerances are tightest. Fused Deposition Modeling occupies volume manufacturing for ground vehicle components where throughput outweighs resolution demands. On-Demand Manufacturing captures expanding margin pools as forward-deployed military units require distributed production capabilities reducing logistics tail vulnerability.
Japan's METI coordinates national additive manufacturing roadmaps that include defense-adjacent dual-use technologies, while Australia's Defence Science and Technology Group sets sovereign capability requirements affecting foreign vendor market access. China's MIIT and SAMR jointly govern materials standards and import certification for strategic manufacturing equipment, creating compliance complexity for non-domestic suppliers. Stakeholders must monitor evolving sovereign capability thresholds and cross-border technology transfer restrictions that will determine which fabrication platforms achieve theater-wide deployment authorization.
Market Dynamics
Programmable materials with stimulus-responsive architectures are compressing design-to-deployment cycles for adaptive military systems, forcing defense contractors to restructure supply chains around distributed manufacturing nodes rather than centralized fabrication.
Growth Catalysts
- Japan's METI innovation roadmaps:National additive manufacturing programs accelerate dual-use technology maturation by funding defense-adjacent research through civilian industrial channels.
- Self-healing armor systems:Shape-memory polymers processed via directed energy deposition enable battlefield components that autonomously repair microfractures under thermal stimulus.
- Australia's sovereign capability mandates:Defence Science and Technology Group requirements for domestic production capacity create guaranteed offtake for regional fabrication platform vendors.
Market Restraints
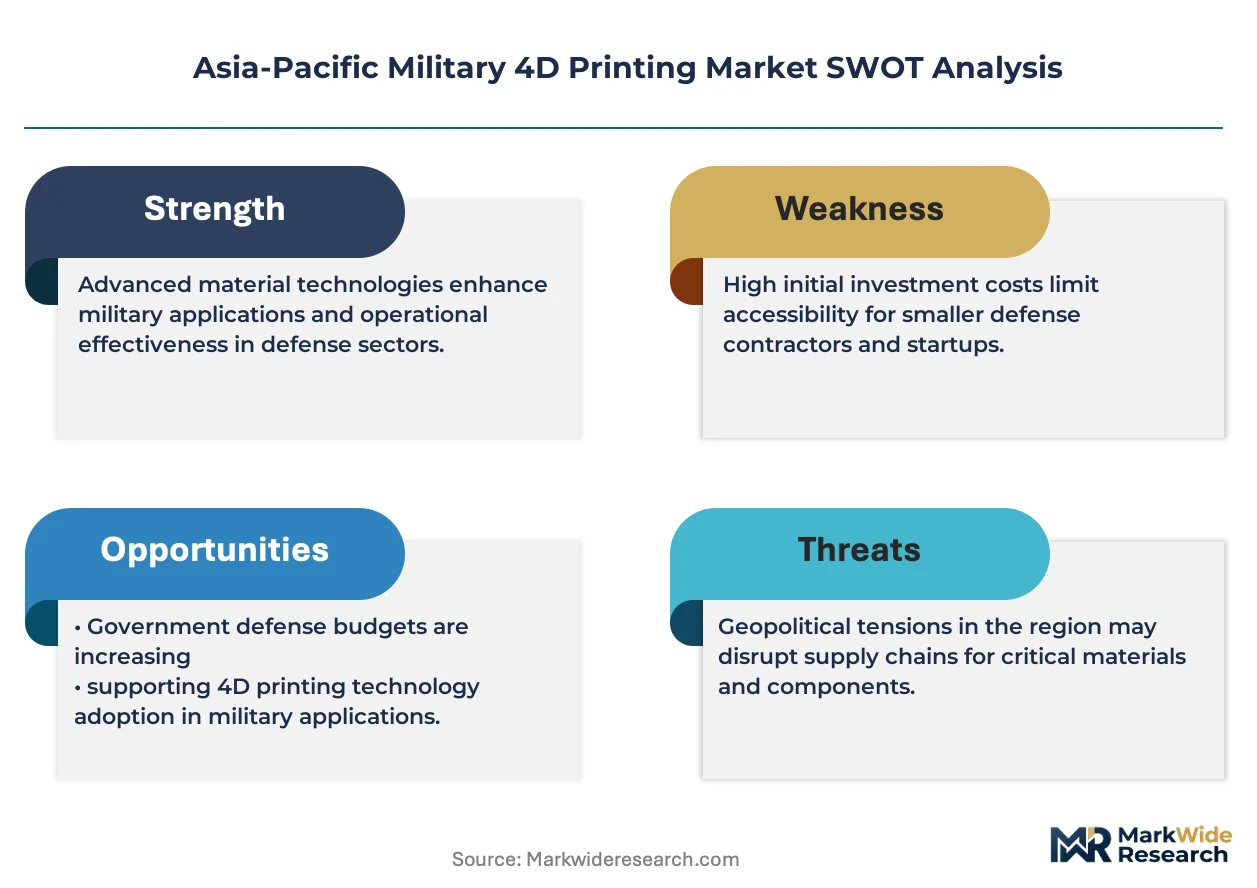
- High-purity precursor scarcity:Specialty photopolymer resins and metal powders for stimulus-responsive alloys concentrate among limited chemical suppliers, creating input cost volatility.
- China's MIIT-SAMR certification complexity:Joint materials standards and strategic manufacturing equipment import rules impose structural friction on non-domestic platform deployment.
- Technical tolerance limitations:Hydrogel-based actuators suffer moisture degradation in tropical operational environments, constraining reliability for forward-deployed applications.
Strategic Opportunities
- South Korea's indigenous R&D ecosystem:Defense Acquisition Program Administration funding for next-generation manufacturing creates white space for localized programmable material development.
- EU Green Deal procurement spillover:Sustainability mandates embedded in European defense export frameworks are reshaping Asia-Pacific supplier qualification criteria for biodegradable stimulus-responsive polymers.
- AI-driven generative design convergence:Machine learning algorithms optimizing lattice structures for 4D-printed components are compressing iteration cycles for adaptive camouflage systems.
Industry Challenges
- Multi-physics simulation expertise gaps:Defense contractors lack sufficient computational materials scientists capable of modeling coupled thermal-mechanical-electrical stimulus responses in programmable architectures.
- Cross-border technology transfer restrictions:Sovereign capability thresholds and export control classifications on directed energy deposition systems complicate theater-wide deployment authorization for multinational programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Military 4D Printing Market |
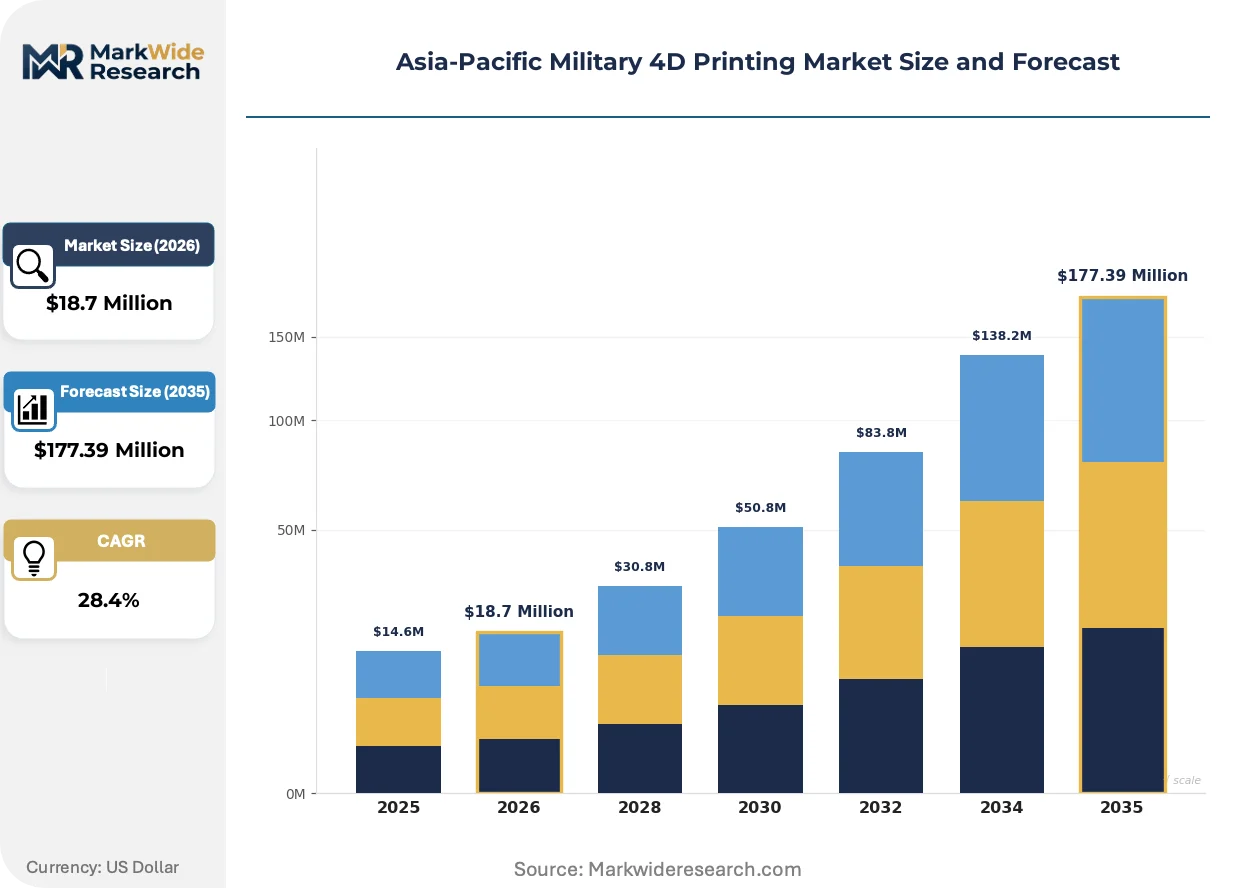
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $177.39 Million |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Armor, Weapons, Components, Accessories Technology: Material Jetting, Vat Photopolymerization, Fused Deposition Modeling, Continuous Liquid Interface Production Application: Supply Chain, On-Demand Manufacturing, Prototyping, Repair Services End User: Defense Contractors, Military Government, Research Institutions, Aerospace Firms |
| Companies Covered | Materialise, ExOne, Stratasys, General Electric, Markforged, Autodesk, Dassault Systems, Hewlett Packard Enterprise, 3D Systems, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Military 4D Printing Market Evolving Landscape
Material jetting systems with micron-precision capabilities are reconfiguring competitive boundaries between defense electronics specialists and traditional structural fabricators, compressing the resolution-throughput tradeoff that previously segmented the supplier base.
Vat photopolymerization using high-temperature-resistant shape-memory polymers is overtaking fused deposition modeling for adaptive camouflage applications. Australian and Japanese defense contractors are adopting these systems for field-deployable antenna arrays and conformal electronics housings. The technology is overtaking legacy subtractive methods by eliminating tooling lead times while enabling post-manufacture geometric reconfiguration under controlled thermal stimulus.
China's MIIT standards for advanced manufacturing equipment certification are tightening materials traceability requirements for imported programmable material platforms. Defense procurement officers must now document supply chain provenance for shape-memory alloy feedstocks through blockchain-enabled tracking systems. South Korean and Australian contractors are responding by qualifying domestic precursor suppliers to bypass cross-border certification bottlenecks.
Forward-deployed military units are unbundling centralized logistics contracts in favor of distributed on-demand manufacturing agreements with regional fabrication service providers. Australian Defence Force ground vehicle maintenance units are piloting containerized 4D printing cells for self-healing track pad replacement in remote operational theaters. This pattern is most visible in Australia's northern territory deployments and Japan's southwestern island chain garrisons where supply line vulnerability drives preference for stimulus-responsive component repair over spare parts inventory.
Asia-Pacific Military 4D Printing Market Segmentation
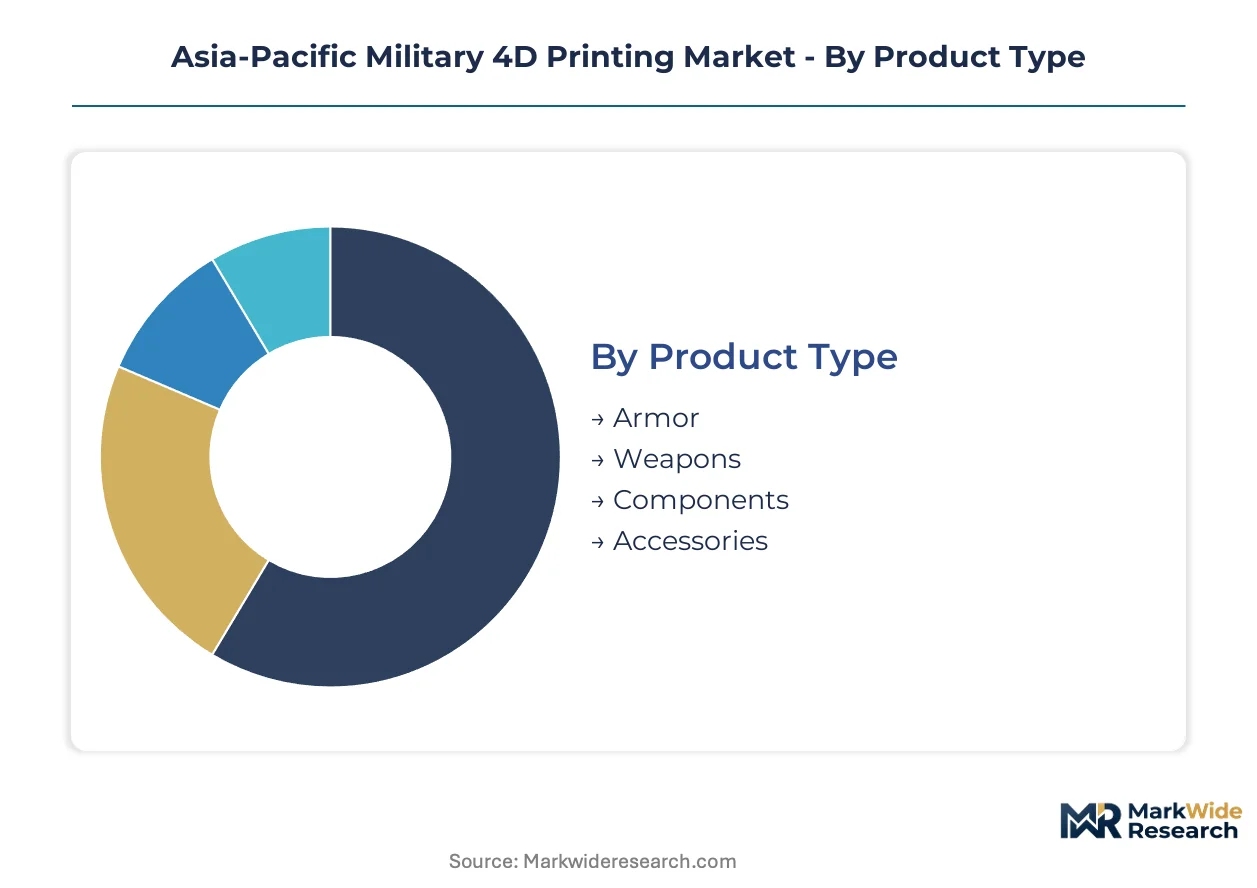
Programmable material architectures in defense applications require precise alignment between fabrication method and operational stimulus-response requirements. Segmentation reveals where capital deployment concentrates and which technology platforms capture sovereign capability investments across Australia's Defence Science and Technology Group programs, Japan's METI-funded dual-use initiatives, and South Korea's Defense Acquisition Program Administration roadmaps.
Product Type:
Capital intensity peaks in segments requiring certified stimulus-responsive material qualification and ballistic testing protocols.
- Armor:Shape-memory polymer composites processed via directed energy deposition enable self-healing plate systems that autonomously seal microfractures under thermal stimulus. Australia's sovereign capability mandates for domestic armor production guarantee offtake for regional programmable material vendors supplying the Australian Defence Force's next-generation soldier protection programs.
- Components:Adaptive structural elements—hinges, latches, deployable antenna arrays—utilize hydrogel actuators and shape-memory alloys for post-manufacture geometric reconfiguration. Japan's southwestern island chain garrisons drive demand for conformal electronics housings that reconfigure under controlled thermal stimulus.
- Weapons:Programmable material applications concentrate in adaptive grip systems and thermal-management heat sinks with stimulus-responsive geometries.
- Accessories:Field-deployable equipment including self-adjusting load-bearing straps and climate-responsive shelter materials.
Most installed capacity flows through Components. Expansion is steepest in Armor.
Technology:
Resolution-throughput tradeoffs determine platform selection across defense electronics precision requirements versus ground vehicle volume manufacturing.
- Material Jetting:Micron-precision deposition of photopolymer resins achieves tight stimulus-response tolerances for defense electronics housings and conformal antenna substrates. Australian contractors prioritize this platform for field-deployable communications equipment where geometric fidelity directly impacts signal performance.
- Vat Photopolymerization:High-temperature-resistant shape-memory polymers processed in vat systems enable adaptive camouflage applications with post-manufacture thermal reconfiguration. Japan's METI innovation programs fund civilian-industrial research that accelerates defense-adjacent dual-use maturation in this segment.
- Fused Deposition Modeling:Polymer filament extrusion dominates throughput-intensive ground vehicle component production where resolution demands are secondary to logistics tail reduction.
- Continuous Liquid Interface Production:Emerging platform for rapid-cure stimulus-responsive hydrogels with potential for deployable medical applications in forward theaters.
Platform deployment concentrates in Vat Photopolymerization for adaptive systems. Material Jetting captures premium positioning fastest.
Application:
Margin structure varies sharply between centralized prototyping services and distributed forward-deployment manufacturing.
- On-Demand Manufacturing:Containerized 4D printing cells deployed to remote operational theaters enable stimulus-responsive component repair without spare parts inventory. Australian Defence Force ground vehicle maintenance units pilot this model in northern territory deployments where supply line vulnerability drives operational preference.
- Repair Services:Self-healing track pads and armor plate regeneration using thermal-activated shape-memory polymers reduce logistics burden. South Korea's indigenous R&D ecosystem develops localized programmable material formulations for Defense Acquisition Program Administration-funded maintenance modernization.
- Supply Chain:Centralized precursor production and feedstock qualification for stimulus-responsive alloys and photopolymer resins.
- Prototyping:Rapid iteration for adaptive camouflage and conformal electronics design validation prior to theater qualification.
Revenue pools concentrate in Repair Services. On-Demand Manufacturing expands most quickly.
End User:
Procurement authority fragmentation shapes vendor access requirements across sovereign capability thresholds and dual-use technology classifications.
- Defense Contractors:Tier-1 systems integrators in Australia, Japan, and South Korea structure supply chains around distributed manufacturing nodes rather than centralized fabrication. These entities navigate China's MIIT-SAMR certification complexity for imported programmable material platforms while qualifying domestic precursor suppliers.
- Military Government:Australia's Defence Science and Technology Group and Japan's Acquisition, Technology and Logistics Agency set sovereign capability requirements that determine foreign vendor market access and theater-wide deployment authorization.
- Research Institutions:University and national laboratory programs advancing multi-physics simulation capabilities for coupled thermal-mechanical-electrical stimulus response modeling.
- Aerospace Firms:Adaptive component architectures for military aviation applications leveraging jet engine heritage adapted to programmable material systems.
Contracting volume concentrates with Defense Contractors. Aerospace Firms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
4D printing for military applications emerged from dual-use manufacturing research programs in Japan and the United States during the early 2010s, with Asia-Pacific defense establishments subsequently adapting programmable material architectures for field-deployable systems.
China
Domestic demand for adaptive armor and self-healing components concentrates among state-owned defense conglomerates modernizing ground vehicle fleets. MIIT and SAMR jointly administer materials standards and import certification rules that restrict non-domestic platform deployment. Beijing-Tianjin-Hebei corridor hosts concentrated research activity in stimulus-responsive alloy feedstock qualification.
Japan
Dual-use technology maturation accelerates through METI-funded civilian industrial channels that feed defense-adjacent additive manufacturing programs. Southwestern island chain garrisons generate operational demand for conformal electronics housings with thermal reconfiguration capabilities. Kanto region maintains leadership in precision deposition systems for micron-tolerance defense applications.
Australia
Sovereign capability mandates from the Defence Science and Technology Group guarantee offtake for domestic programmable material vendors supplying soldier protection programs. Northern territory deployments pilot containerized 4D printing cells for self-healing track pad replacement. Melbourne and Sydney anchor the national defense manufacturing cluster.
South Korea
Indigenous R&D ecosystem expansion receives Defense Acquisition Program Administration funding for next-generation manufacturing localization. Seoul Capital Area concentrates development activity for hydrogel actuator formulations adapted to peninsula operational environments. Busan-Ulsan corridor contributes maritime platform adaptive component expertise.
Singapore
Strategic positioning as regional technology transfer hub attracts European and North American defense contractors establishing Asia-Pacific additive manufacturing service centers. National additive manufacturing strategy aligns with defense procurement frameworks for distributed production capabilities. Advanced manufacturing clusters in Jurong and Tuas support precision component qualification.
Asia-Pacific Military 4D Printing Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification complexity and sovereign capability alignment. Market structure fragments across three tiers: established industrial conglomerates with jet engine heritage, specialized additive manufacturing platform vendors, and emerging regional fabrication service providers. Two strategic archetypes dominate: technology originators leveraging polymer expertise for high-temperature military applications, and systems integrators structuring distributed manufacturing nodes. Competitive moves concentrate on qualifying domestic precursor suppliers to bypass cross-border certification bottlenecks, and on securing theater-wide deployment authorization through sovereign capability partnerships.
Among European-origin technology providers, Materialise anchors technology transfer into regional defense supply chains through its position in programmable material software and services. Stratasys occupies a position within the polymer expertise tier, while General Electric sits within the industrial conglomerate archetype leveraging heritage in adaptive component architectures. These three exemplify how foreign vendors navigate Australia's Defence Science and Technology Group requirements and China's MIIT-SAMR certification complexity to maintain market access across divergent regulatory environments.
| Leading Market Players |
|---|
| Materialise |
| ExOne |
| Stratasys |
| General Electric |
| Markforged |
| Autodesk |
| Dassault Systems |
| Hewlett Packard Enterprise |
| 3D Systems |
| Others |
Value Network & Pricing Analysis
Computational materials scientists concentrated in Japan's Kanto region and Australia's Melbourne-Sydney corridor command premium compensation that compresses pricing-tier spreads between premium micron-precision systems and volume-oriented ground vehicle platforms.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates material jetting platforms with sub-100-micron tolerances from fused deposition modeling systems and emerging continuous liquid interface production units. Price differentiation centers on certification grade under China's MIIT-SAMR joint standards and Australia's Defence Science and Technology Group sovereign capability mandates. Cost compression in standard-tier vat photopolymerization systems is intensifying because South Korean domestic precursor qualification programs are bypassing import certification overhead. Defense contractors exhibit lowest price sensitivity for material jetting electronics housings, while forward-deployed maintenance units driving on-demand manufacturing contracts show highest sensitivity to total cost of ownership including logistics tail reduction.
Supply Chain Analysis
Certification and qualification gating through China's MIIT equipment standards and SAMR materials traceability requirements fragments supply chain authorization across theater-wide deployment scenarios. Feedstock concentration rests on Japan for high-purity shape-memory polymer precursors, South Korea for hydrogel actuator formulations, and Australia for sovereign-qualified armor plate composites. Specialty photopolymer resins, metal powders for stimulus-responsive alloys, and blockchain-enabled provenance tracking systems constitute critical input dependencies. Single-source vulnerability concentrates in China's domestic precursor production for non-domestic platform deployment. Distribution runs through defense contractor procurement networks with tier-1 systems integrators in Australia, Japan, and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Australia's sovereign capability premiums exceed China's MIIT-SAMR compliance costs, rewarding vendors with dual-qualification capacity across both regulatory environments.
For Market Incumbents: Cement theater-wide deployment authorization by qualifying domestic precursor suppliers in each of Australia's, Japan's, and South Korea's defense procurement jurisdictions. Deepen backward integration into shape-memory polymer resin production to offset specialty photopolymer feedstock volatility from limited chemical suppliers. Threat substitution from AI-driven generative design convergence compresses iteration cycle premiums for adaptive camouflage systems.
For New Entrants and Emerging Players: Begin with South Korea's Defense Acquisition Program Administration-funded indigenous R&D ecosystem where localized programmable material development white space exceeds Australia's sovereign capability saturation. Target hydrogel actuator formulations adapted to peninsula tropical operational environments as the most penetrable segment. Pursue joint development agreements with Melbourne and Sydney defense manufacturing clusters as the primary go-to-market angle.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabrication service providers with containerized 4D printing cell deployment capabilities and existing Australian Defence Force pilot program relationships. Long-term viability over the projection horizon hinges on sustained sovereign capability investment across Asia-Pacific defense modernization programs. Watch for MIIT-SAMR certification relaxation or tightening as the inflection signal for non-domestic platform market access expansion or contraction.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Precursor Qualification | Bypasses China's MIIT-SAMR cross-border certification bottlenecks for stimulus-responsive alloy feedstocks. |
| Containerized Deployment Cells | Enables Australian Defence Force self-healing track pad replacement in northern territory remote theaters. |
| Dual-Use Technology Maturation | Leverages Japan's METI civilian-industrial funding for defense-adjacent programmable material research acceleration. |
| AI-Driven Generative Design | Compresses lattice structure iteration cycles for adaptive camouflage systems using machine learning optimization. |
| Sovereign Capability Partnership | Secures guaranteed offtake through Australia's Defence Science and Technology Group domestic production mandates. |
Research Methodology
Coverage spans Australia, Japan, South Korea, China, and Singapore, with primary inputs from each national defense procurement jurisdiction combining structured interviews with additive manufacturing platform engineers, defense contractor procurement directors, regulatory affairs specialists managing MIIT-SAMR certification, and sovereign capability program officers at Australia's Defence Science and Technology Group. Secondary validation draws from METI innovation roadmap publications, Defense Acquisition Program Administration funding disclosures, MIIT advanced manufacturing equipment standards, and customs data on programmable material feedstock trade flows. Bottom-up capacity assessments and top-down defense budget allocation analysis triangulate market sizing.
Rate-of-change decomposition separates volume growth from value-per-unit evolution across the analysis window. Segmentation dimensions modeled include fabrication technology platform, programmable material architecture, application from on-demand manufacturing through repair services, and end-user procurement authority from defense contractors through military government research institutions. CAGRs derive from scenario-weighted projections of sovereign capability investment trajectories and dual-use technology maturation timelines. Industry-specific inputs incorporate stimulus-responsive material qualification protocol adoption rates and theater-wide deployment authorization timelines.
Caveats apply where MIIT-SAMR regulatory tightening or relaxation, sovereign capability threshold elevation, or breakthroughs in multi-physics simulation capabilities could materially shift the outlook. Forecasts reflect assumptions regarding sustained defense modernization funding across analyzed national programs and continued programmable material performance validation in tropical operational environments. A model refresh is warranted upon material change in China's import certification posture or Australia's Defence Science and Technology Group vendor qualification criteria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Nutricosmetics Market
Others
Software Synthesizers Market
Others
Asia-Pacific Intercom Devices Market
Others
Germany 3D Printing Construction Market
Others
Wearable AI Market
Others
Solid White Films Market
Others
Latin America Contract Packaging Market
Others
Europe Electric Forklift Market
Others
Global Platform Trolley Market
Others
Vacuum Evaporators Market
Others
Industrial Computers Market
Others
Balsa Wood Market
Others
Smart Card Market
Others
China Smart Home Market
Others
Remanufacturing-as-a-Service (RaaS) Market
Others
Fire Sprinkler Market