
 Latin America Contract Packaging Market | 2026-2036
Latin America Contract Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Contract Packaging Market Foresight
ISO 15378 certification for medicinal products is bifurcating the competitive landscape between qualified pharmaceutical packagers and generalist operators. Sonoco Products Company leverages its integrated fiber and plastic packaging network to sustain multi-country supply contracts across Brazil and Mexico. TricorBraun anchors its position through specialized rigid container design and sourcing capabilities that dominate premium cosmetic and personal care segments. Colep Consumer Products differentiates via automated aerosol and liquid filling lines that occupy a distinct tier in high-volume consumer goods packaging.
Contract packaging encompasses the outsourced execution of primary and secondary packaging operations performed by third-party providers on behalf of brand owners, encompassing processes such as automated liquid filling to within milliliter tolerances, induction heat sealing for hermetic closure integrity, and pressure-sensitive labeling with print verification. The primary commercial purpose centers on converting bulk-manufactured products into shelf-ready consumer units while relieving capital expenditure burdens from brand owners. Plastic material formats sustain the largest volume base due to cost efficiency and barrier adaptability across food and chemical end users, while pharmaceutical serialization and tamper-evident cartoning represent the fastest-expanding service category driven by regulatory compliance mandates. Food end users concentrate demand for pouch and box formats as retail-ready packaging requirements intensify across Latin American supermarket channels.
Brazil's ANVISA enforces serialization and traceability standards that shape pharmaceutical contract packaging qualification cycles and capital investment priorities. Mexico's COFEPRIS aligns with FDA-level good manufacturing practice expectations for cross-border pharmaceutical supply, filtering which providers can access North American-linked production networks. REACH-aligned chemical safety protocols in Mercosur trading relationships affect material selection and labeling specifications for chemical end users. Stakeholders must monitor evolving national pharmacopeia harmonization and sustainability disclosure requirements to determine qualification investments and geographic service expansion sequencing.
Market Dynamics
Pharmaceutical serialization mandates are restructuring capital allocation across Latin American contract packaging, forcing providers to choose between qualification-heavy compliance investments and exit from regulated segments. This regulatory pressure concentrates service capacity among certified operators while compressing margins for generalist competitors.
Growth Catalysts
- ANVISA Track-and-Trace Mandates:Brazil's pharmaceutical serialization requirements are pulling investment toward qualified contract packagers capable of integrating aggregation stations and verification systems into high-speed lines.
- Nearshoring to Mexico:North American supply chain repositioning is concentrating sterile filling demand in Mexican facilities with COFEPRIS-FDA dual qualification pathways.
- Sustainable Paperboard Substitution:Mercosur sustainability disclosure protocols are accelerating fiber-based format adoption across food and personal care contract packaging specifications.
Market Restraints
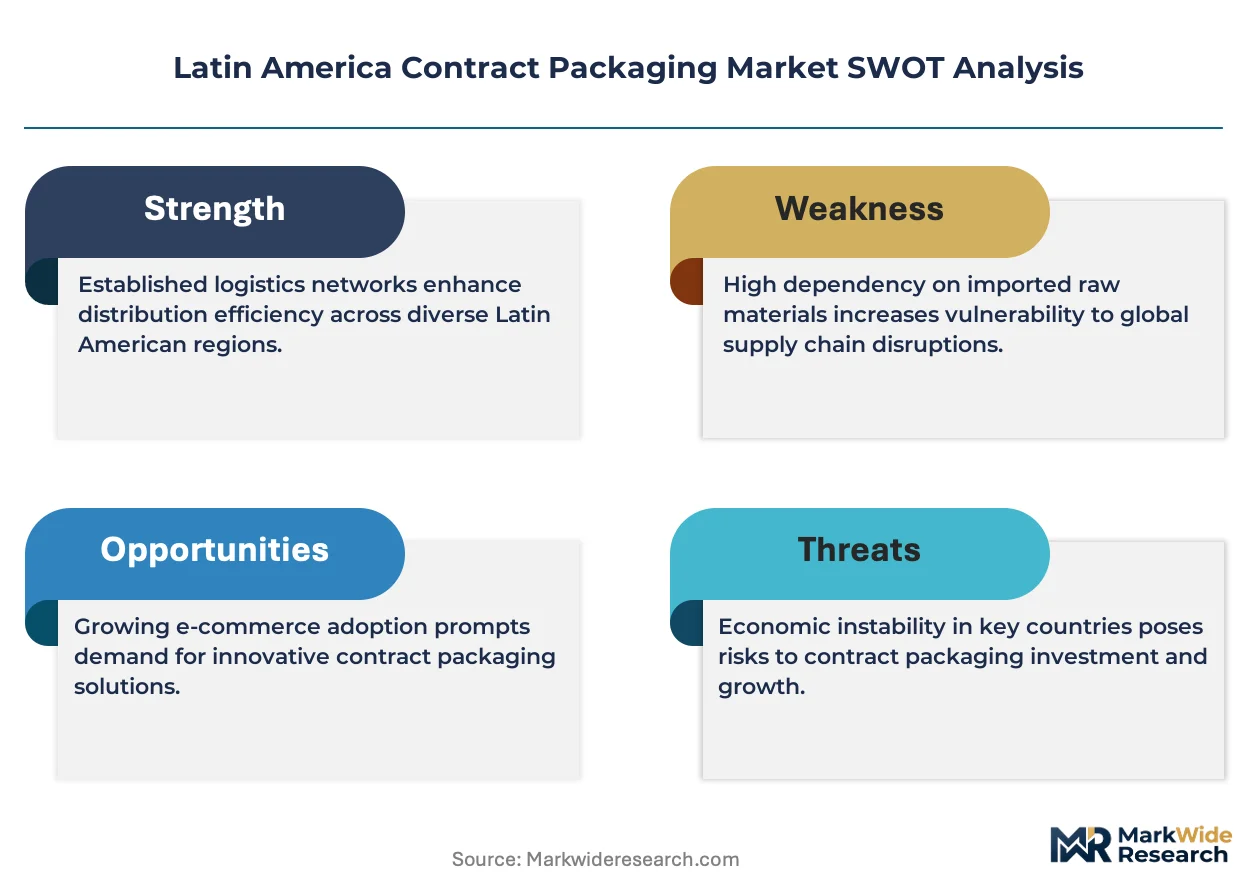
- Resin Price Volatility:Polypropylene and polyethylene input cost swings compress margin predictability for plastic-dominant contract packagers serving commodity food segments.
- Equipment Lead Times:European and Asian serialization line manufacturers face 12-18 month delivery backlogs, constraining Brazilian pharmaceutical packagers' compliance timelines.
- Qualified Labor Scarcity:ISO 15378-certified technicians and validation engineers remain concentrated in São Paulo and Mexico City metropolitan corridors.
Strategic Opportunities
- Andean Pharmaceutical Expansion:Colombia's INVIMA is harmonizing serialization rules with Brazil, creating first-mover advantage for packagers establishing Bogotá-Cali corridor capacity.
- Biologics Cold-Chain Packaging:Temperature-controlled secondary packaging for monoclonal antibodies represents an underpenetrated service tier with limited qualified regional competition.
- Digital Watermark Integration:Convergence of printed electronics with conventional folding cartons enables smart packaging authentication for premium cosmetic brands.
Industry Challenges
- Validation Timeline Compression:ANVISA's accelerated enforcement windows force simultaneous equipment qualification and process validation, straining quality assurance bandwidth.
- Legacy MES Integration:Pharmaceutical packagers face friction connecting new serialization equipment to existing manufacturing execution systems without production downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Contract Packaging Market |
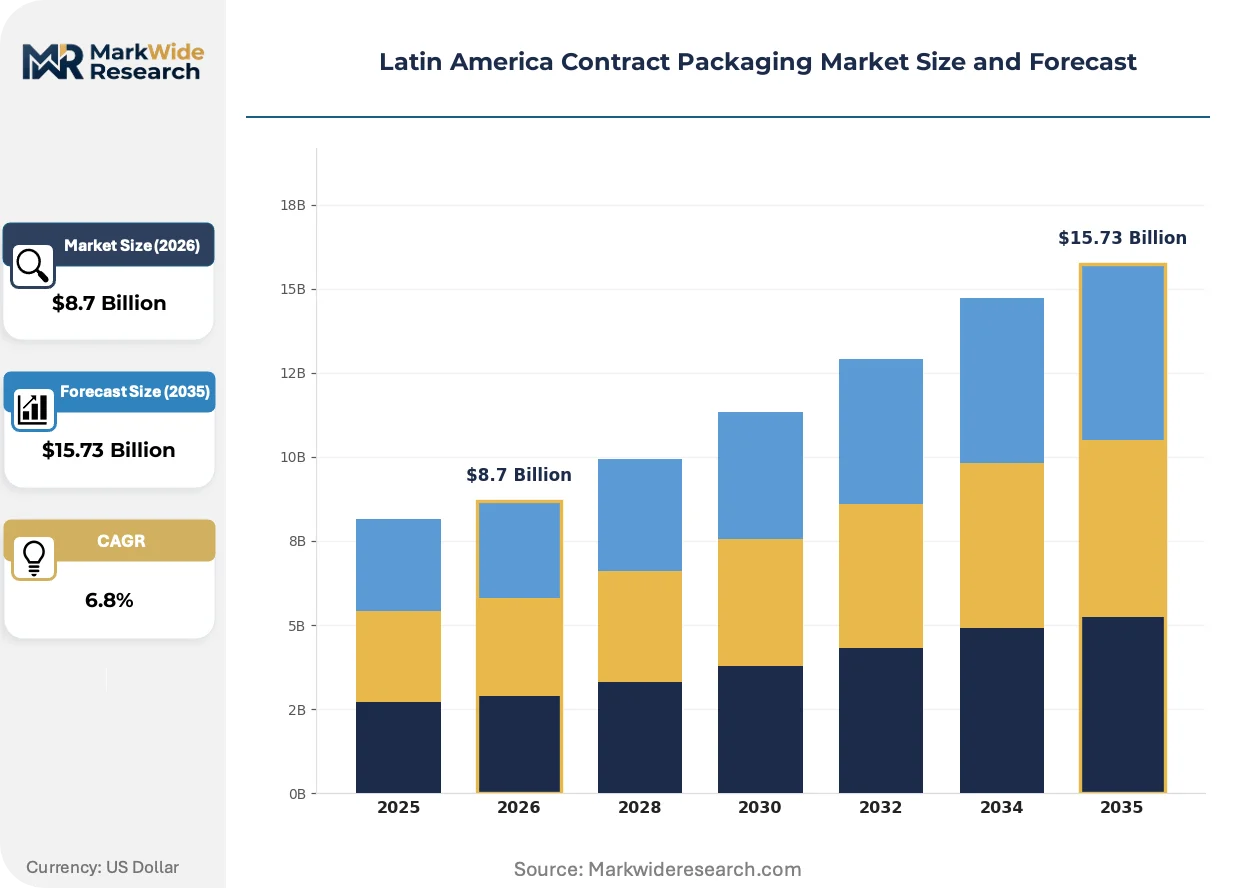
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Filling, Sealing, Labeling, Cartoning Material Type: Plastic, Glass, Metal, Paperboard End User: Food, Pharmaceuticals, Cosmetics, Chemicals Packaging Format: Bottles, Pouches, Tubs, Boxes |
| Companies Covered | U.S. Packaging & Wrapping, Rangel, TricorBraun, Sonoco Products Company, Colep Consumer Products, Assemblies Unlimited, PAC Worldwide, Tetra Pak International, VMA LOGDIST, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Contract Packaging Market Shifts & Advancements
Automation architectures are fragmenting as modular robotics and vision systems enable smaller-batch flexibility without sacrificing throughput. This technological shift favors mid-scale contract packagers previously locked out of pharmaceutical qualification tiers.
Modular robotic workcells with integrated machine vision are decomposing the traditional trade-off between line speed and changeover flexibility. Pharmaceutical packagers in Mexico's Querétaro corridor are deploying these systems for multi-SKU serialization runs. The technology is decomposing volume concentration among legacy high-speed dedicated lines, enabling qualified mid-capacity providers to capture niche biologics contracts.
ANVISA's RDC 430/2020 aggregation requirements are mandating parent-child serial number relationships across secondary and tertiary packaging levels. Brazilian contract packagers must deploy line-level software integration between cartoning and case-packing stations. The regulation most acutely affects generic drug manufacturers with limited in-house packaging engineering resources, driving outsourcing to specialized providers.
Brand owners are unbundling packaging specification development from manufacturing execution, retaining design control while outsourcing production. Cosmetic and personal care companies in Brazil's Southeast region are shifting from full-service contracts to toll-manufacturing arrangements with material-supply provisions. This pattern concentrates most visibly among multinational subsidiaries seeking to reduce working capital tied to packaging inventory.
Latin America Contract Packaging Market Segmentation
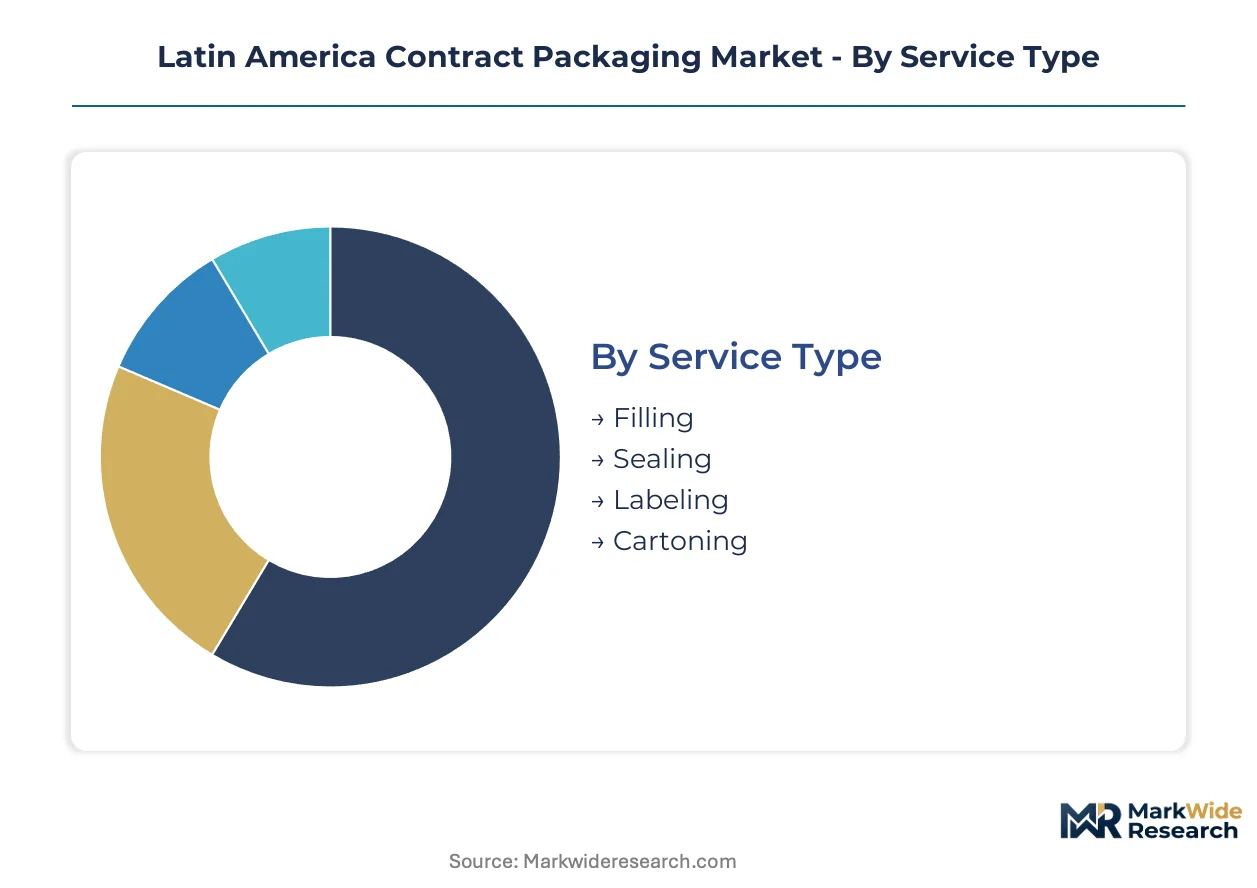
Segmentation in Latin American contract packaging reveals how regulatory fragmentation and material substitution trends concentrate margin pools across discrete service tiers. Packagers must align certification portfolios with specific segment qualification thresholds to capture sustainable revenue.
Service Type:
ANVISA and COFEPRIS enforcement windows differentiate which service lines require validated serialization infrastructure versus generalist equipment.
- Filling:Automated liquid and powder dispensing systems achieve milliliter-level tolerances for pharmaceutical and cosmetic applications. Brazilian generic drug manufacturers outsource sterile vial and syringe filling to ISO 15378-certified operators in São Paulo's pharmaceutical corridor, driven by ANVISA's accelerated compliance timelines.
- Sealing:Induction heat sealing and ultrasonic closure systems ensure hermetic integrity for moisture-sensitive pharmaceuticals and chemical formulations. Mexican facilities serving North American supply chains deploy COFEPRIS-validated sealing lines for cross-border pharmaceutical distribution, pressured by FDA-aligned audit protocols.
- Labeling:Pressure-sensitive and shrink-sleeve application with print verification supports regulatory serialization mandates.
- Cartoning:Automated carton erection and insertion systems handle secondary packaging for retail-ready unit formation.
Established volume favors Filling; emerging adoption favors Sealing as serialization aggregation requirements expand.
Material Type:
Cost tier stratification separates commodity resin formats from premium barrier materials with specialized qualification pathways.
- Plastic:Polypropylene and polyethylene formats dominate food and chemical contract packaging through cost efficiency and barrier adaptability. Resin price volatility compresses margins for Brazilian packagers serving commodity food segments, forcing volume concentration among operators with backward integration into resin sourcing.
- Paperboard:Fiber-based cartons and folding boxes gain specification share under Mercosur sustainability disclosure protocols. São Paulo-based cosmetic brands accelerate paperboard substitution for premium personal care lines, responding to retailer ESG scorecard requirements.
- Glass:Borosilicate and soda-lime containers serve pharmaceutical and high-end cosmetic segments requiring inert barrier properties.
- Metal:Aluminum and tinplate formats sustain aerosol and specialty chemical applications with pressure-resistant specifications.
Plastic retains volume leadership; paperboard climbs the fastest on sustainability-driven specification shifts.
End User:
Application-specific compliance burdens create divergent margin profiles across regulated and non-regulated segments.
- Pharmaceuticals:Serialization, tamper-evident cartoning, and cold-chain secondary packaging command premium pricing tied to ANVISA and COFEPRIS validation requirements. Mexican facilities with dual FDA qualification capture sterile filling contracts from North American biologics manufacturers repositioning supply chains.
- Food:Pouch and box formats concentrate demand from supermarket retail-ready packaging requirements across Latin American modern trade channels. Brazilian packagers automate high-speed pouch lines for processed food exporters facing Mercosur trading partner technical barriers.
- Cosmetics:Rigid container design and premium finishing support brand differentiation in personal care segments.
- Chemicals:REACH-aligned safety protocols in Mercosur relationships govern material selection and hazard labeling specifications.
Food commands absolute volume; pharmaceuticals generate steepest expansion trajectory on regulatory outsourcing.
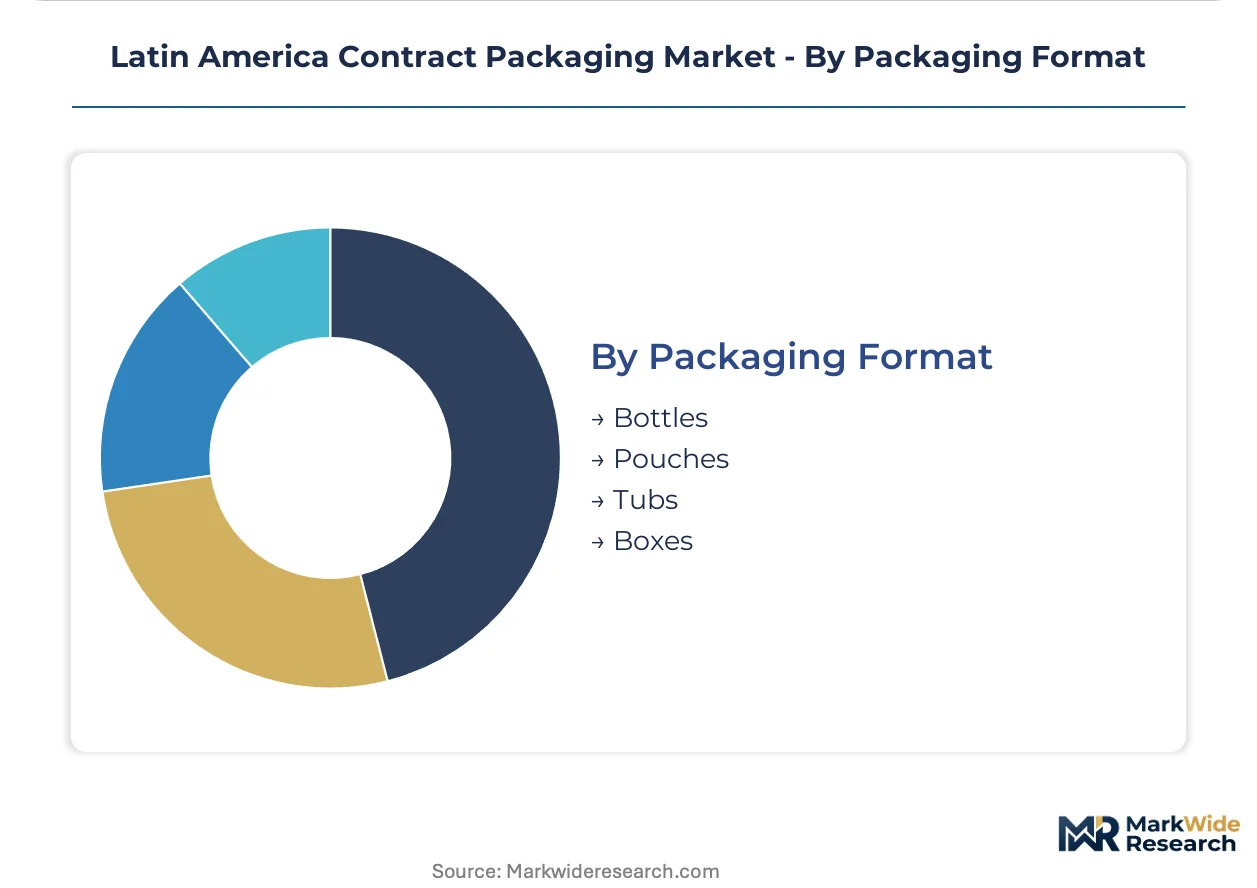
Packaging Format:
Customer type segmentation separates bulk industrial formats from unit-dose retail configurations with divergent automation requirements.
- Pouches:Flexible film structures with reseal features dominate food and personal care segments requiring shelf-life extension and convenience functionality. Colombian packagers in the Bogotá-Cali corridor invest in vertical form-fill-seal lines for Andean food exporters targeting modern retail channels.
- Bottles:Rigid plastic and glass containers serve liquid pharmaceutical, cosmetic, and chemical applications with precise dosing requirements. Mexican PET bottle blow-molding and filling integration supports nearshored personal care manufacturing from North American brand owners.
- Tubs:Wide-mouth rigid containers accommodate semi-solid food and cosmetic formulations with scoop-access convenience.
- Boxes:Corrugated and folding carton formats provide tertiary protection and retail presentation for multi-unit shipments.
Bottles sustain established volume; pouches gain share fastest on flexible packaging substitution in food segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical manufacturers and food processors concentrate demand across Latin America's contract packaging landscape, with regulatory compliance and supply chain proximity dictating provider selection. Brazil and Mexico absorb dominant capacity investments, while Andean markets emerge as secondary expansion corridors.
Brazil
ANVISA serialization mandates pull investment toward São Paulo's pharmaceutical corridor, where sterile filling and aggregation systems dominate capital allocation. RDC 430/2020 enforcement windows compress qualification timelines for generic drug packagers. Campinas and São Paulo metropolitan clusters host ISO 15378-certified operators serving multinational biologics manufacturers.
Mexico
COFEPRIS-FDA dual qualification pathways attract North American supply chain repositioning, concentrating sterile vial and syringe demand in Querétaro and Mexico City facilities. Nearshored personal care manufacturing from US brand owners drives PET bottle blow-molding integration. The Bajío Region automates high-speed pouch lines for processed food exporters facing USMCA technical barriers.
Colombia
INVIMA harmonizes serialization rules with Brazilian ANVISA standards, creating first-mover opportunities in the Bogotá-Cali corridor. Andean food exporters target modern retail channels with vertical form-fill-seal investments. The national pharmaceutical regulator accelerates track-and-trace compliance timelines for contract packagers serving regional generic drug distribution.
Argentina
Mercosur sustainability disclosure protocols reshape material specifications for Buenos Aires-based cosmetic and personal care packagers. REACH-aligned chemical safety protocols govern hazard labeling for industrial chemical contract packaging. The Greater Buenos Aires industrial belt concentrates pouch and box format automation for supermarket retail-ready requirements.
Chile
Pharmaceutical cold-chain secondary packaging demand concentrates in Santiago's biologics distribution hub, serving monoclonal antibody imports with temperature-controlled qualification. The national pharmaceutical regulator enforces serialization standards that filter provider access to regulated segments. Valparaíso corridor facilities integrate folding carton authentication for premium cosmetic exports.
Latin America Contract Packaging Market Competitive Landscape
Player mix skews toward diversified packaging conglomerates with multi-material capabilities and specialized pharmaceutical qualification operators. The competitive structure tiers between ISO 15378-certified providers capturing regulated pharmaceutical contracts and generalist operators serving commodity food segments. Strategic archetypes include integrated fiber-plastic networks, rigid container design specialists, and automated aerosol filling operators. Dominant competitive moves center on serialization equipment qualification investments and geographic expansion into Andean regulatory harmonization corridors.
Within the diversified packaging tier, Sonoco Products Company and Tetra Pak International exemplify multi-material network operators with sustained multi-country supply contracts. TricorBraun occupies a position among rigid container design specialists serving premium cosmetic segments. Colep Consumer Products represents the automated filling archetype with distinct positioning in high-volume consumer goods packaging. These anchors illustrate how certification portfolios and material specialization stratify competitive access across regulated and non-regulated demand pools.
| Leading Market Players |
|---|
| U.S. Packaging & Wrapping |
| Rangel |
| TricorBraun |
| Sonoco Products Company |
| Colep Consumer Products |
| Assemblies Unlimited |
| PAC Worldwide |
| Tetra Pak International |
| VMA LOGDIST |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts with resin indexation clauses lock in supply access for Brazilian food packagers while capping margin exposure to polypropylene price swings. These agreements tether pricing visibility to petrochemical benchmark movements, forcing buyers to absorb basis risk or pay premiums for fixed-price structures.
Pricing Analysis
Cost-plus contracts with ICIS polymer indexation dominate commodity plastic packaging tiers across Brazil and Mexico. Price differentiation separates ISO 15378-certified pharmaceutical operators from generalist food packagers, with certification premiums widening during ANVISA enforcement windows. Cost compression in commodity resin tiers is intensifying because Brazilian packagers lack backward integration into petrochemical feedstocks. Generic drug manufacturers exhibit highest price sensitivity, while biologics sponsors accept premium pricing for cold-chain validation.
Supply Chain Analysis
Strategic stockpiling of serialized cartons and aggregation hardware precedes ANVISA compliance deadlines, displacing just-in-time preferences in pharmaceutical tiers. Supply concentrates in Brazil, Mexico, and Colombia for qualified packaging services, with equipment sourcing drawn from European and Asian machinery builders. Single-source vulnerability runs through German and Italian serialization line manufacturers facing extended order backlogs. Distribution feeds from São Paulo and Querétaro production clusters into North American and Mercosur trading corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Serialization infrastructure interoperability is creating platform-economics dynamics where ANVISA-COFEPRIS-INVIMA regulatory convergence rewards packagers with multi-jurisdiction validation capabilities.
For Market Incumbents: Consolidate ISO 15378-certified capacity in the São Paulo-Campinas corridor to capture ANVISA-mandated generic drug outsourcing. Acquire Colombian packagers ahead of INVIMA harmonization completion to preempt new entrant positioning in the Andean corridor. For New Entrants and Emerging Players: INVIMA fast-track certification for existing Brazilian-qualified operators offers lowest-friction entry into Colombian pharmaceutical packaging. Target Bogotá-Cali corridor biologics cold-chain secondary packaging as the most penetrable white space, leveraging temperature-controlled qualification gaps among established competitors. For Investors and Strategic Acquirers: Mid-cap pharmaceutical packagers with dual FDA-COFEPRIS validation represent the highest-conviction acquisition archetype for North American supply chain repositioning exposure. Monitor INVIMA-ANVISA regulatory harmonization progress as the primary inflection signal for Andean corridor capacity valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Serialization Equipment Qualification | ANVISA RDC 430/2020 compliance locks in pharmaceutical contract access through 2035. |
| Dual FDA-COFEPRIS Certification Investment | North American nearshoring demand concentrates in Mexican facilities with cross-border validation. |
| Andean Corridor Capacity Expansion | INVIMA harmonization with Brazilian standards creates first-mover advantage in Colombia. |
| Biologics Cold-Chain Packaging Development | Temperature-controlled secondary packaging for monoclonal antibodies faces limited regional competition. |
| Sustainable Paperboard Format Substitution | Mercosur sustainability disclosure protocols accelerate fiber-based specification adoption. |
Research Methodology
Desk research of ANVISA regulatory filings, COFEPRIS validation registries, and pharmaceutical trade association capacity directories preceded structured interviews with contract packaging operations directors, regulatory affairs managers at multinational drug manufacturers, and serialization equipment vendor application engineers. Secondary triangulation drew from customs import records for packaging machinery, ISO certification databases, and Mercosur technical barrier notifications. Bottom-up facility capacity estimates were cross-checked against top-down pharmaceutical outsourcing spend allocations.
Variance decomposition across service type, material format, end-user industry, and national regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segmented volume-demand modeling with input from pharmaceutical serialization compliance timelines and food retail channel modernization rates. Forecast inputs incorporated ANVISA enforcement phase transitions and North American supply chain repositioning intensity.
The analysis sits within stated boundaries; outcomes outside sustained regulatory harmonization momentum or petrochemical price stability would require recalibration. Forecasts reflect assumptions regarding ANVISA compliance adherence and nearshoring continuation without major trade policy disruption. Revision becomes warranted when resin price volatility or equipment lead time extension crosses thresholds that compress packager margin sustainability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Retail Media Networks Market
Others
Smart Home As a Service Market
Others
Latin America 3D Printing Construction Market
Others
Coriolis Meters Market
Others
Global Phablets and Superphones Market
Others
Process Instrumentation Equipment Market
Others
Coloring Apps Market
Others
Sandbags Market
Others
Performance Testing Tools Market
Others
Europe Travel Retail Market
Others
North America Video Conferencing Hardware Market
Others
Global Mobile Gambling Market
Others
LAMEA Astrology Market
Others
Folding Screen Mobile Phone Market
Others
United States Indoor LBS Market
Others
Underwater Communication System Market