
 Germany 3D Printing Construction Market | 2026-2036
Germany 3D Printing Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Germany 3D Printing Construction Market Insights
Residential and municipal housing procurement is shifting toward printed structural elements as German cities face binding affordable housing quotas. PERI 3D Construction leverages its formwork heritage to dominate large-scale concrete printing for multi-unit projects. CyBe Construction anchors the mid-rise segment with mobile gantry systems designed for on-site deployment. Korte-Hoffmann Gebäudedruck specializes in custom architectural elements where traditional formwork costs prove prohibitive.
Germany 3D printing construction encompasses the robotic deposition of cementitious, polymeric, or metallic materials through layer-by-layer additive processes to create load-bearing walls, structural frames, or facade elements, typically achieving compressive strengths of 30-60 MPa for concrete mixes within 28 days. Binder jetting for concrete dominates current installed capacity due to its compatibility with conventional Portland cement blends and rapid build speeds. Concrete material formulations command the deepest margin pools because Heidelberg Materials and Züblin have secured captive supply chains for specialized admixtures and aggregate grading. Infrastructure applications represent the fastest-growing demand channel as Deutsche Bahn and federal transport agencies pilot printed bridge abutments and noise barriers.
The Federal Institute for Research on Building, Urban Affairs and Spatial Development (BBSR) establishes performance benchmarks for printed structural elements, while the German Institute for Standardization (DIN) develops material testing protocols that determine market access for new cementitious formulations. KfW promotional bank subsidies and the federal Building Energy Act (GEG) jointly steer developer capital toward processes that reduce embodied carbon and construction waste. Stakeholders must monitor whether DIN grants full structural approval for multi-story printed buildings or maintains provisional certification limits that constrain addressable project scale.
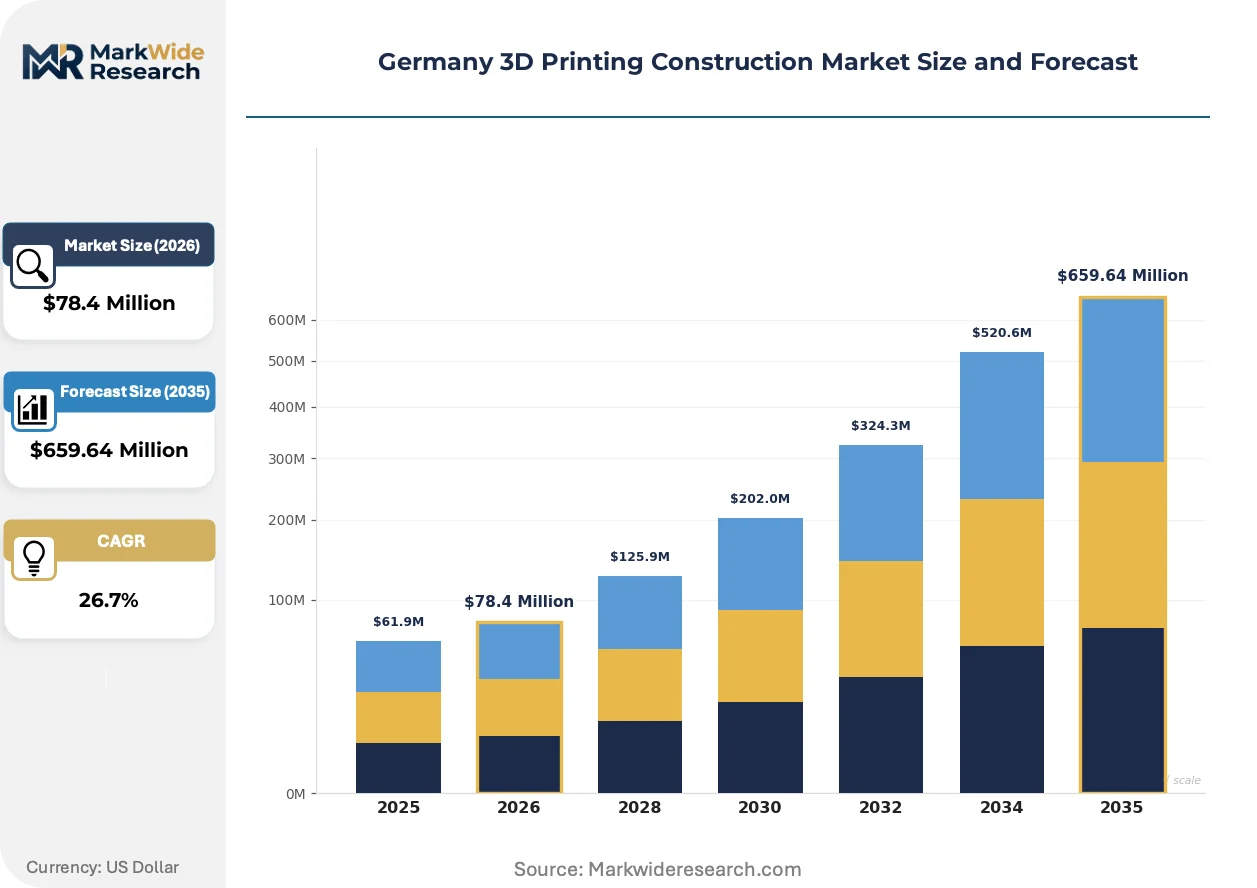
Market Dynamics
The KfW climate construction subsidy is redirecting developer capital toward low-carbon building methods, compressing approval timelines for printed structural components and accelerating municipal procurement across North Rhine-Westphalia and Bavaria.
Growth Catalysts
- Building Energy Act (GEG):The federal mandate for embodied carbon reduction is compelling housing associations to evaluate printed wall systems that cut material waste by eliminating traditional formwork.
- Binder jetting:This deposition technology achieves build speeds compatible with conventional construction schedules, attracting infrastructure agencies piloting printed bridge abutments for Deutsche Bahn corridors.
- Bavaria's experimental zones:State-sanctioned regulatory sandboxes allow multi-story printed buildings to proceed under provisional DIN certification, creating reference projects for national code adoption.
Market Restraints
- Specialized admixture supply:Heidelberg Materials and Züblin control captive supply chains for high-performance concrete formulations, creating input cost volatility for independent contractors.
- DIN provisional certification limits:The German Institute for Standardization maintains height and occupancy restrictions on printed structures, constraining addressable project scale for residential towers.
- Conventional precast concrete:Established off-site manufacturing retains cost advantages at volume, threatening substitution for mid-rise housing where printed elements seek entry.
Strategic Opportunities
- Berlin affordable housing districts:Binding municipal quotas for social housing units create dedicated procurement channels for rapid-build printed components in designated pilot zones.
- Federal transport infrastructure:Noise barrier and retaining wall applications along Autobahn corridors offer standardized geometries that match current printer gantry dimensions.
- BBSR performance benchmarking:The Federal Institute for Research on Building is establishing comparative data protocols that will enable printed elements to compete for public contracts on lifecycle cost grounds.
Industry Challenges
- Structural engineer certification:The limited pool of professionals qualified to sign off on printed load-bearing elements creates bottlenecks during project permitting phases.
- On-site integration complexity:Coordinating robotic deposition schedules with conventional trades for MEP rough-in and facade sealing requires rework of standard construction sequencing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany 3D Printing Construction Market |
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $659.64 Million |
| CAGR (2026 – 2036) | 26.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: FDM, SLS, DLP, Binder Jetting Material Type: Concrete, Plastics, Metal Alloys, Composites Application: Residential, Commercial, Infrastructure, Artistic Constructs End User: Construction Companies, Architects, Engineers, Developers |
| Companies Covered | CyBe Construction, Korte-Hoffmann Gebäudedruck, PERI 3D Construction, Voxeljet, BigRep, Heidelberg Materials, Züblin, CONCR3DE, Instatiq, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany 3D Printing Construction Market Trends and Innovations
Mobile gantry systems are compressing the boundary between factory prefabrication and on-site construction, enabling mid-rise projects to deploy printing equipment directly at building locations rather than transporting precast elements.
Robotic concrete deposition is modularizing project delivery by allowing developers to sequence structural printing in discrete vertical segments. Municipal housing authorities in North Rhine-Westphalia are adopting this approach for phased occupancy of multi-unit buildings. The technique compresses financing exposure by enabling revenue generation from completed floors while upper levels remain under construction.
The KfW climate construction subsidy is tightening eligibility criteria to exclude high-carbon building methods from promotional loan programs. Developers accessing subsidized capital must now document embodied carbon reductions through material selection and waste minimization. Affordable housing projects in Berlin's pilot districts are restructuring procurement specifications to prioritize printed structural elements that satisfy these threshold requirements.
Architectural practices are bundling design services with material sourcing guarantees to secure municipal contracts. This model displaces traditional bid-then-design sequences by locking in printed component suppliers during schematic phases. Bavaria's experimental construction zones exhibit the strongest uptake, where state permitting offices coordinate directly with integrated design-build entities to accelerate project approvals.
Germany 3D Printing Construction Market Segmentation
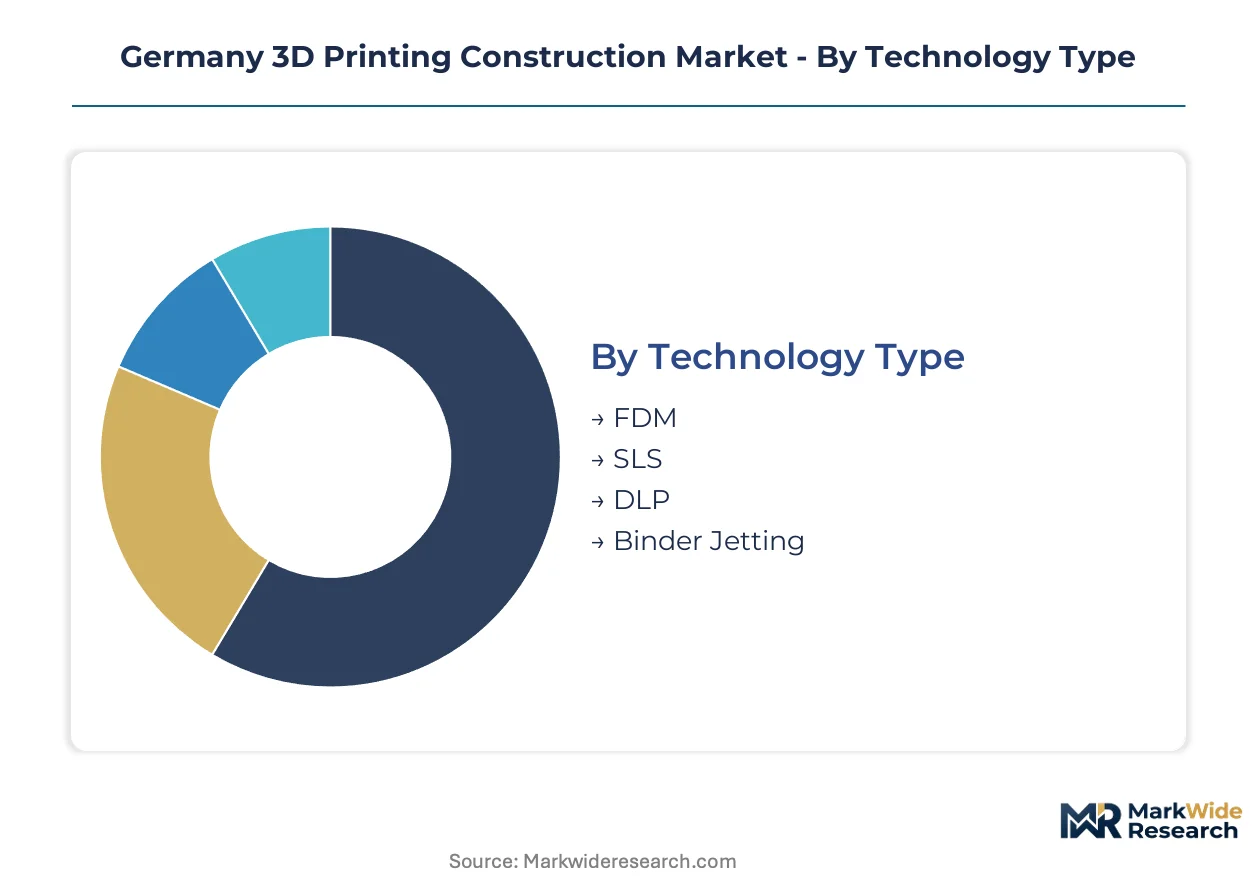
Segmentation reveals how German 3D printing construction splits between proven deposition methods and emerging material categories. Understanding these divides exposes where capital concentrates and where regulatory approval creates first-mover advantages.
Technology Type:
Binder jetting commands volume leadership while DLP occupies premium niche positioning for architectural precision.
- Binder Jetting:Layer-wise deposition of cementitious powders with liquid binding agents achieves build speeds matching conventional construction schedules. Deutsche Bahn corridors and Autobahn noise barrier projects concentrate demand here due to compatibility with standard Portland cement blends.
- DLP:Photopolymerization of resin-based materials delivers micron-scale precision for facade elements and ornamental components. Bavaria's experimental zones and Berlin's affordable housing pilot districts drive procurement where surface finish quality outweighs raw material cost premiums.
- FDM:Thermoplastic extrusion dominates small-scale architectural modeling and temporary formwork applications.
- SLS:Selective laser sintering of polymer powders serves specialized tooling and custom connection hardware production.
Mature deployment sits with Binder Jetting. Newer deployment is concentrated in DLP.
Material Type:
Concrete formulations anchor commercial viability while metal alloys capture infrastructure durability requirements.
- Concrete:Cementitious mixes with specialized admixtures achieve 30-60 MPa compressive strength within standard curing windows. Heidelberg Materials and Züblin have locked captive supply chains, making this the margin pool for multi-unit residential projects across North Rhine-Westphalia.
- Metal Alloys:Steel and aluminum deposition produces structural connectors and reinforcement elements where cyclic loading resistance matters. Federal transport infrastructure applications—bridge abutments, retaining walls—concentrate demand as DIN develops fatigue testing protocols.
- Plastics:ABS and PETG formulations serve non-load-bearing interior partitions and temporary protective structures.
- Composites:Fiber-reinforced polymers enable lightweight facade panels with thermal performance advantages.
Concrete dominates project economics. Composites are climbing the fastest as Building Energy Act thermal requirements tighten.
Application:
Infrastructure applications expand most quickly while residential anchors near-term revenue.
- Infrastructure:Standardized geometries for noise barriers, retaining walls, and bridge components match current gantry dimensions. BBSR performance benchmarking enables lifecycle cost competition against precast concrete for Autobahn corridor contracts.
- Residential:Multi-unit housing in Berlin's affordable housing pilot districts and Bavaria's experimental zones absorbs printed wall systems that eliminate traditional formwork waste. KfW climate construction subsidy eligibility hinges on embodied carbon documentation.
- Commercial:Office and retail facades utilize printed elements for complex curvature unachievable with conventional methods.
- Artistic Constructs:Custom architectural installations leverage design freedom where budget constraints permit experimental procurement.
Residential commands current deployment scale. Infrastructure shows the steepest expansion trajectory as federal transport agencies accelerate pilot programs.
End User:
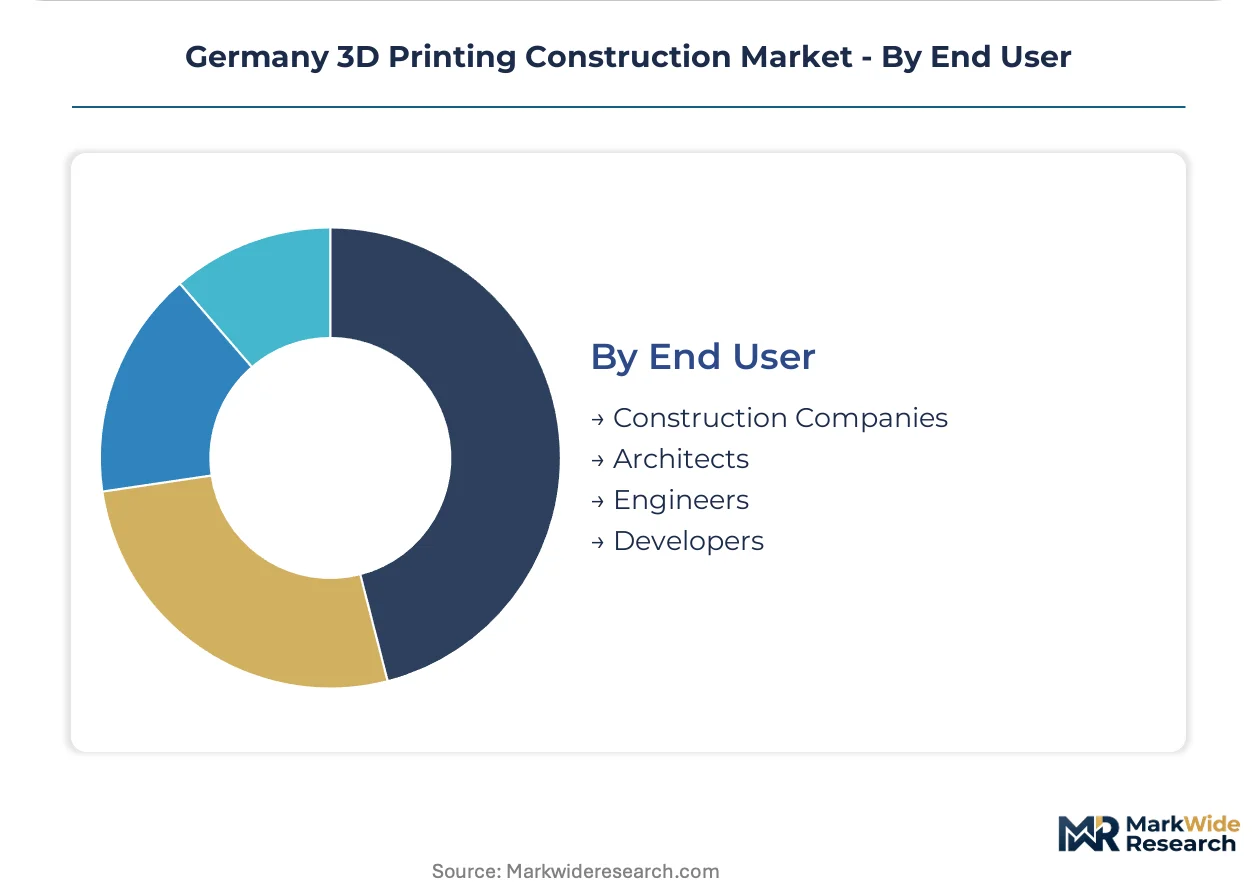
Construction companies drive equipment procurement while architects control specification gatekeeping.
- Construction Companies:PERI 3D Construction and CyBe Construction deploy mobile gantry systems directly to job sites, compressing delivery schedules for municipal housing authorities. Equipment ownership creates differentiation against conventional precast competitors.
- Architects:Design practices bundle material sourcing guarantees during schematic phases, locking in printed component suppliers before competitive bidding. Bavaria's state permitting offices coordinate with these integrated design-build entities.
- Engineers:Structural certification bottlenecks concentrate with this group—limited qualified professionals constrain project permitting velocity.
- Developers:Capital access through KfW promotional bank programs steers procurement toward low-carbon printed methods.
Construction companies own installed capacity. Architects are gaining share fastest as bundled design-build contracts displace traditional sequencing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's experimental construction zones concentrate state-sanctioned regulatory sandboxes where multi-story printed buildings proceed under provisional DIN certification. North Rhine-Westphalia anchors municipal housing procurement through climate-focused development banks. Berlin-Brandenburg pilot districts channel federal affordable housing subsidies toward rapid-build printed components.
North Rhine-Westphalia
Municipal housing authorities in Cologne and Dortmund expand procurement of printed structural components for social housing quotas. The KfW climate construction subsidy redirects developer capital toward low-carbon building methods through promotional bank programs. The Ruhr industrial corridor hosts equipment deployment for multi-unit residential projects.
Bavaria
State-sanctioned regulatory sandboxes enable multi-story printed buildings under provisional DIN certification limits. The Building Energy Act compels housing associations to evaluate printed wall systems that eliminate traditional formwork waste. Munich and Nuremberg experimental zones generate reference projects for national code adoption.
Berlin-Brandenburg
Binding municipal quotas for social housing units create dedicated procurement channels for rapid-build printed components. Federal transport infrastructure pilots along Autobahn corridors test noise barrier applications with standardized geometries. The capital region integrates robotic deposition schedules with conventional trades for phased occupancy.
Baden-Württemberg
Automotive supplier networks transition precision manufacturing capabilities toward construction robotics and gantry system components. The state's dual vocational training system supplies technicians for equipment maintenance and on-site operation. Stuttgart industrial clusters support mid-rise printing equipment fabrication.
Lower Saxony
Federal transport agencies pilot printed bridge abutments and retaining walls along Deutsche Bahn corridors and highway networks. The BBSR establishes performance benchmarks that enable printed elements to compete for public contracts on lifecycle cost grounds. Hanover engineering consultancies develop structural certification protocols for load-bearing printed elements.
Germany 3D Printing Construction Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with equipment owners creating differentiation against conventional precast competitors through mobile gantry deployment. The vendor base organizes around three strategic archetypes: formwork heritage players leveraging construction equipment distribution, materials conglomerates securing captive supply chains for specialized admixtures, and robotics specialists anchoring mid-rise on-site deployment. Consolidation pressures concentrate among concrete formulation suppliers while printing equipment remains fragmented across technology approaches. Competitive moves center on strategic partnerships between materials suppliers and equipment fabricators, plus capacity expansion into state-sanctioned experimental zones.
Within the equipment-owning tier, PERI 3D Construction and CyBe Construction exemplify divergent scale strategies. PERI leverages formwork heritage to anchor large-scale concrete printing for multi-unit projects. CyBe occupies a position in the mid-rise segment with mobile systems designed for on-site deployment. Heidelberg Materials represents the materials conglomerate archetype through captive supply chain control over specialized admixtures and aggregate grading.
| Leading Market Players |
|---|
| CyBe Construction |
| Korte-Hoffmann Gebäudedruck |
| PERI 3D Construction |
| Voxeljet |
| BigRep |
| Heidelberg Materials |
| Züblin |
| CONCR3DE |
| Instatiq |
| Others |
Pricing and Supply Chain Analysis
Portland cement price volatility cascades through specialized admixture tiers into project-based pricing bands, with Heidelberg Materials and Züblin extracting margin premiums from captive supply chains while independent contractors absorb input cost shocks.
Pricing Analysis
Short lead-time premiums for mobile gantry deployment compress project timelines for municipal housing authorities, while spot inventory discounts apply to standardized concrete formulations. Project-based pricing dominates, with differentiation driven by DIN certification grade and volume scale. Cost compression in mid-rise residential tiers intensifies because conventional precast concrete retains volume advantages. Municipal procurement offices exhibit highest price sensitivity; federal transport agencies demonstrate lowest sensitivity due to lifecycle cost framing.
Supply Chain Analysis
The Building Energy Act's domestic-content thresholds reshape sourcing toward German-sourced cementitious powders and locally fabricated gantry components. Supply concentrates in Germany, Netherlands, and Belgium for specialized admixtures and robotic deposition hardware. Raw material dependencies center on Portland cement clinker, high-purity silica sands, and steel reinforcement feedstock. Single-source vulnerability concentrates with Heidelberg Materials' captive admixture chains. Distribution runs through equipment-owning construction firms deploying directly to Bavaria's experimental zones and North Rhine-Westphalia municipal sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Germany 3D printing construction market reads as a cost-of-compliance story where DIN provisional certification creates a barrier-to-entry moat for players with established BBSR performance benchmarks.
For Market Incumbents: Extend certification investment into multi-story structural approval pathways before DIN relaxes height restrictions, locking in addressable project scale advantages against emerging robotics specialists. Deepen captive supply relationships with Züblin for specialized aggregate grading to defend margin position against materials conglomerates. Prioritize Bavaria's experimental zones for capacity expansion to anchor reference projects before national code adoption accelerates. For New Entrants and Emerging Players: Enter via Berlin's affordable housing pilot districts where KfW climate construction subsidy eligibility creates dedicated procurement channels with compressed competitive bidding. Target noise barrier applications along Autobahn corridors where standardized geometries match current gantry dimensions and BBSR lifecycle cost benchmarking enables contract capture. Pursue design-build bundling with architectural practices to displace traditional bid-then-design sequences. For Investors and Strategic Acquirers: Distressed-cycle entries favor mobile gantry system fabricators in Baden-Württemberg where automotive supplier networks transition precision manufacturing capabilities toward construction robotics. Long-term viability hinges on DIN granting full structural approval for multi-story printed buildings. Watch for inflection when BBSR publishes comparative lifecycle cost data enabling printed elements to compete for federal transport infrastructure contracts on equal footing with precast concrete.| Strategic Initiative | Industry Significance |
|---|---|
| DIN Certification Investment | Multi-story structural approval unlocks addressable project scale for residential towers in Bavaria. |
| Mobile Gantry Capacity Expansion | On-site deployment compresses delivery schedules for North Rhine-Westphalia municipal housing authorities. |
| Captive Admixture Supply Agreement | Heidelberg Materials' specialized formulations anchor margin pools in high-performance concrete tiers. |
| Design-Build Integration | Bavaria's state permitting offices coordinate directly with bundled entities to accelerate project approvals. |
| BBSR Performance Benchmarking | Lifecycle cost protocols enable printed elements to compete for Autobahn corridor public contracts. |
Research Methodology
Independent corroboration across equipment fabricators, municipal procurement officers, and structural engineering consultancies underwrites the qualitative findings in this study. Primary interviews with construction company project directors, DIN certification specialists, KfW promotional bank program managers, and BBSR research staff combined with secondary validation from federal transport agency pilot documentation, BBSR technical reports, and DIN material testing protocol drafts. Bottom-up project pipeline analysis and top-down construction output triangulation anchored volume estimates.
Comparable-period anchoring to historical KfW subsidy disbursement patterns and municipal housing procurement cycles established the forecast window baseline. The analytical framework models technology type, material formulation, application segment, and end-user archetype across the projection horizon. CAGRs derive from segment-level build-out assumptions and regulatory approval velocity. Forecast inputs incorporate DIN certification timeline scenarios and KfW climate construction subsidy uptake curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under delayed multi-story structural approval or accelerated conventional precast cost reduction. Projections reflect documented assumptions regarding regulatory adoption velocity and materials cost trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Printed Leather Market
Others
Global Mica Market
Others
France Smart Home Market
Others
Pickup Truck Market
Others
Dried Egg Market
Others
Global Application Testing Services Market
Others
Computer on Module Market
Others
Printing Machines Market
Others
Ceramic Machinery Market
Others
Smart Home As a Service Market
Others
India 3D Printing Construction Market
Others
Middle East Paper Making Machine Market
Others
North America Orange Market
Others
Thermoformed Plastics Market
Others
Saudi Arabia Laser Hair Removal Market
Others
Hybrid Switchgear Market