
 Wearable AI Market | 2026-2036
Wearable AI Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable AI Market Analysis
The capital-intensity divergence between in-house semiconductor design and outsourced chip procurement is reorganizing competitive hierarchies in wearable AI. Apple leverages its custom silicon pipeline to sustain margin structures that commodity assemblers cannot match. Samsung Electronics anchors display and memory verticals to control component costs across smartwatch and earwear lines. Xiaomi competes on manufacturing scale, extending hardware access into price-sensitive segments across South Asia and Africa.
Wearable AI denotes edge-computing devices worn on the body that process biometric, environmental, or spatial data through embedded neural networks without persistent cloud tethering. These systems integrate accelerometers, photoplethysmography sensors, and sub-10nm application processors to deliver real-time health monitoring, contextual assistance, or industrial safety alerts. Smartwatches and earwear dominate current shipment volumes, yet smart glasses represent the fastest-expanding margin pool as optical waveguide costs decline. Machine learning deployment in on-device inference is maturing fastest among technology layers, while natural language processing lags due to power-constrained acoustic front-end limitations.
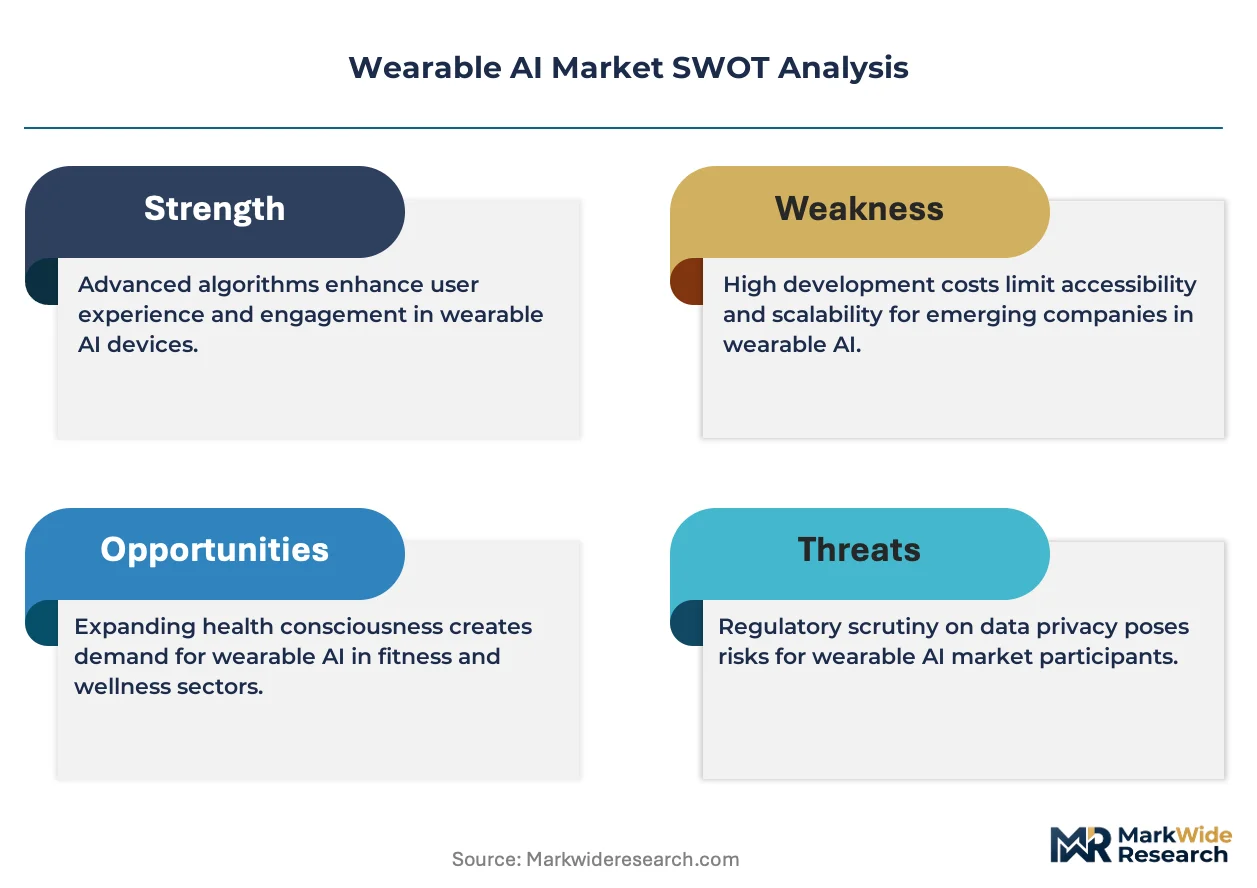
FDA regulates AI-enabled diagnostic wearables as Software as a Medical Device in the United States, requiring clinical validation that shapes product development timelines and reimbursement eligibility. The EU AI Act classifies health-monitoring wearables as high-risk systems, mandating conformity assessments that filter market access for non-compliant vendors. Enterprise buyers must monitor evolving liability frameworks for algorithmic health alerts as deployment shifts from personal wellness to clinical decision support.
Market Dynamics
On-device neural inference is compressing cloud dependency in wearable AI, forcing semiconductor architectures toward sub-5nm efficiency targets and rewiring power management hierarchies across the supply base.
Growth Catalysts
- FDA Software as a Medical Device pathway:Accelerated clearance timelines for algorithm-enabled diagnostic wearables are unlocking reimbursement eligibility and clinical procurement channels in the United States.
- Photoplethysmography sensor miniaturization:Continuous blood oxygen and cardiac rhythm monitoring at wrist-worn scale is expanding addressable use cases from fitness tracking into chronic disease management.
- China's dual carbon goals:Domestic manufacturing incentives for energy-efficient edge compute are concentrating battery and display supply around Huawei Technologies and Xiaomi Corporation production ecosystems.
Market Restraints
- Optical waveguide input cost volatility:Smart glasses margin expansion remains tethered to limited suppliers of precision etched substrates, creating margin compression risk for non-vertically integrated assemblers.
- EU AI Act high-risk system classification:Conformity assessment mandates for health-monitoring wearables are filtering market access and extending compliance timelines for non-EU vendors.
- Acoustic front-end power constraints:Natural language processing on-device remains technically bounded by microphone array energy budgets, limiting voice assistant responsiveness in earwear form factors.
Strategic Opportunities
- Industrial safety alert systems:Construction and logistics verticals in Germany are piloting AI-enabled hard hats and exoskeletons for predictive fatigue monitoring and collision avoidance.
- India PLI scheme for electronics manufacturing:Production-linked incentives for wearable component assembly are attracting contract manufacturers to establish domestic capacity outside China concentration.
- Optical waveguide plus micro-LED convergence:Display technology fusion is enabling all-day smart glasses battery life, opening enterprise augmented reality workflows previously blocked by thermal and power limitations.
Industry Challenges
- ISO 13485 medical device quality management certification:Wearable vendors pivoting from wellness to clinical decision support face 12-18 month quality system implementation timelines that compress product launch windows.
- Edge AI compiler toolchain fragmentation:Proprietary neural network optimization software from Qualcomm, MediaTek, and Apple silicon is forcing developers to maintain parallel codebases, inflating firmware engineering headcount.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable AI Market |
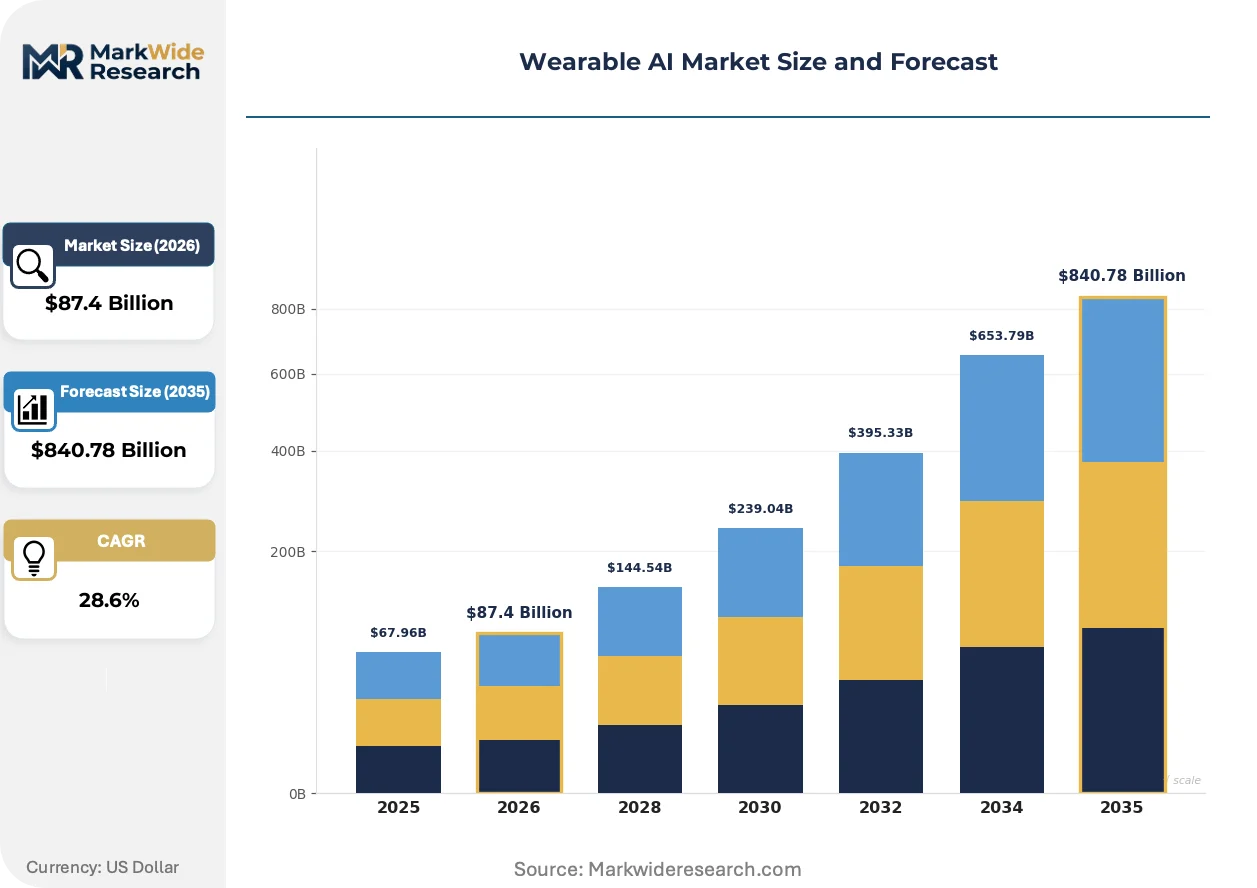
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $840.78 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, Earwear, Smart Glasses Technology: Machine Learning, Computer Vision, Natural Language Processing, Augmented Reality End User: Healthcare Professionals, Fitness Enthusiasts, Corporate Users, Elderly Care Deployment: Personal Use, Enterprise Solutions, Healthcare Integration, Industrial Applications |
| Companies Covered | Apple Inc., Samsung Electronics Co. Ltd., Garmin Ltd., Fitbit, Inc., Google Inc., Huawei Technologies Co. Ltd., Xiaomi Corporation, Sony Corporation, Meta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable AI Market Emerging Trajectories
Silicon architecture specialization is bifurcating the wearable AI competitive map between custom chip designers and fabless assemblers, with power efficiency emerging as the decisive performance vector.
Sub-10nm application processors with dedicated neural engine cores are fragmenting the smartwatch semiconductor landscape. Fitness-oriented brands without captive silicon design are outsourcing to MediaTek and Qualcomm platforms, ceding margin to chip vendors while Apple and Samsung retain in-house power-performance optimization. This technology stratification is compressing pricing power at the mid-tier and concentrating premium margins around vertically integrated ecosystems.
The EU AI Act high-risk system classification is mandating conformity assessments for health-monitoring wearables sold in European markets. Vendors must document algorithm training data provenance and clinical validation protocols before CE marking, extending product development timelines by six to nine months. Germany and France are enforcing these requirements most stringently, pushing non-compliant Asian manufacturers toward wellness-only positioning in those markets.
Enterprise procurement of wearable AI for industrial safety is rotating from device purchase toward outcome-based fleet management contracts. Mining and logistics operators in Australia and Canada are unbundling hardware acquisition from predictive analytics subscriptions, shifting vendor relationships from equipment suppliers to occupational risk partners. This model compresses upfront capital commitment while locking in multi-year data service revenue for platform providers.
Wearable AI Market Segmentation
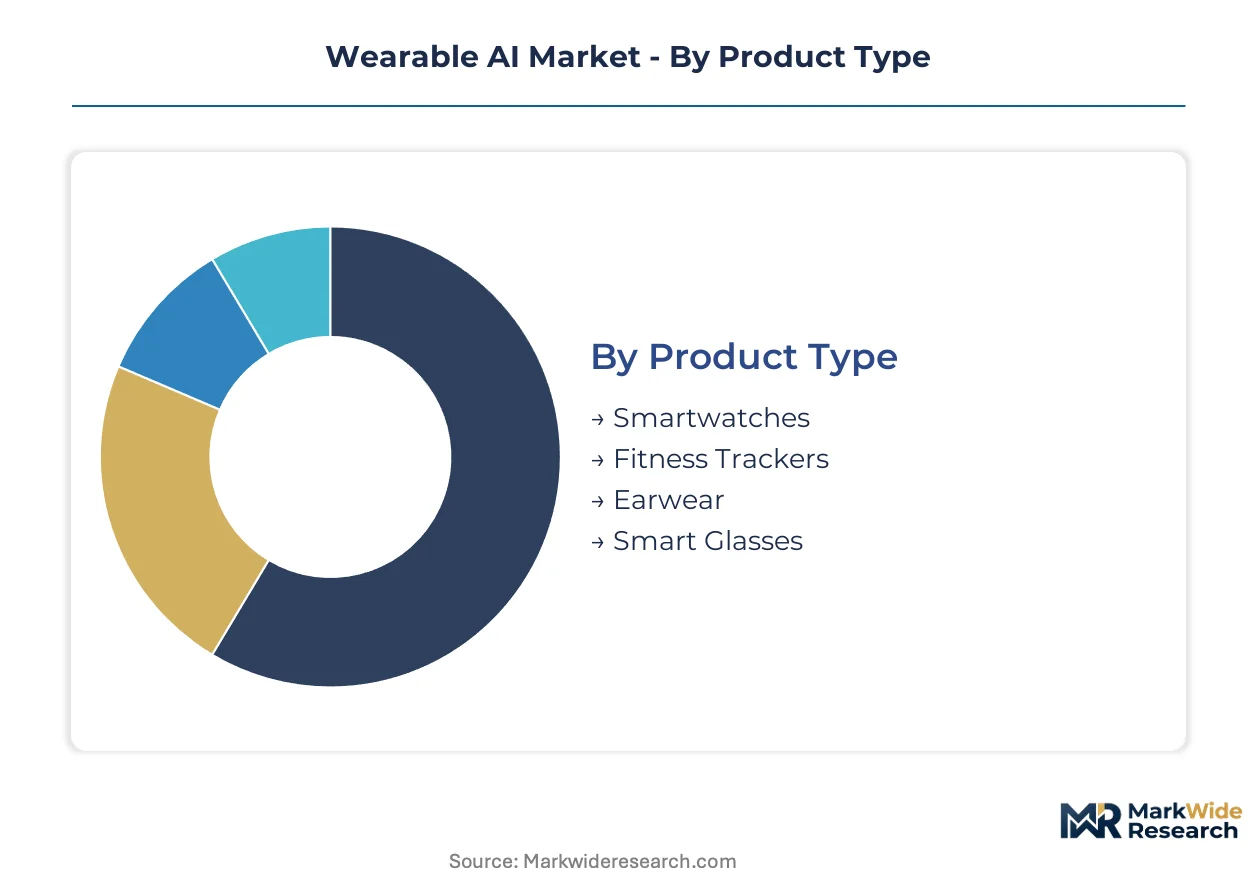
Wearable AI segmentation reveals how regulatory pathways, power constraints, and use-case maturity split the market into divergent commercial trajectories. Product form factors and deployment modes carry distinct compliance burdens that reshape vendor economics.
Product Type:
FDA Software as a Medical Device clearance applies differentially across form factors, with diagnostic claims triggering clinical validation requirements that wellness-only devices bypass.
- Smartwatches:Photoplethysmography-enabled cardiac monitoring at wrist-worn scale dominates FDA 510(k) submissions for algorithmic arrhythmia detection. Healthcare procurement in the United States concentrates here due to reimbursement eligibility under remote patient monitoring codes.
- Fitness Trackers:Accelerometer-based activity quantification without diagnostic claims avoids SaMD pathways, preserving faster launch timelines. Demand clusters in price-sensitive segments across India and Southeast Asia where Xiaomi and local brands compete on manufacturing scale.
- Earwear:Acoustic front-end power budgets constrain on-device natural language processing, limiting clinical voice assistant deployment to premium tiers with larger battery cells.
- Smart Glasses:Optical waveguide input costs and EU AI Act high-risk classification for AR-overlay health data compress margins for non-vertically integrated assemblers.
Smartwatches handle the majority of throughput; smart glasses are expanding most quickly on share as waveguide costs decline.
Technology:
Edge inference efficiency divides the competitive map between mature on-device deployment and cloud-dependent architectures still resolving power-thermal constraints.
- Machine Learning:Sub-10nm neural engine cores enable real-time biometric inference without persistent connectivity. Apple and Samsung deploy proprietary architectures; fabless vendors rely on Qualcomm and MediaTek platforms.
- Computer Vision:Gesture recognition and fall detection run on low-resolution image sensors with sub-watt power envelopes. Industrial safety pilots in Germany integrate this into hard-hat systems for predictive fatigue monitoring.
- Natural Language Processing:Acoustic front-end energy budgets limit responsive on-device assistants in earwear form factors.
- Augmented Reality:Micro-LED plus optical waveguide convergence is unlocking all-day battery life for enterprise AR workflows previously blocked by thermal limits.
Machine Learning captures the dominant deployment volume; Augmented Reality shows the steepest expansion trajectory as display-battery integration matures.
End User:
Customer type determines pricing architecture, with clinical procurement commanding premium tiers and wellness segments competing on hardware accessibility.
- Healthcare Professionals:FDA-cleared diagnostic algorithms and ISO 13485 quality systems define vendor eligibility. Reimbursement codes in the United States lock in multi-year fleet contracts for remote patient monitoring.
- Fitness Enthusiasts:Subscription monetization for training analytics drives recurring revenue models. Strava and Apple Fitness+ integrations concentrate demand in North American and Western European urban markets.
- Corporate Users:Enterprise wellness programs and productivity monitoring deploy standardized device fleets with centralized data governance.
- Elderly Care:Fall detection and medication adherence alerts serve institutional buyers in Japan and aging European demographics with specific regulatory quality requirements.
Healthcare Professionals generate the highest revenue per unit; Elderly Care is gaining share fastest as aging demographics expand addressable populations.
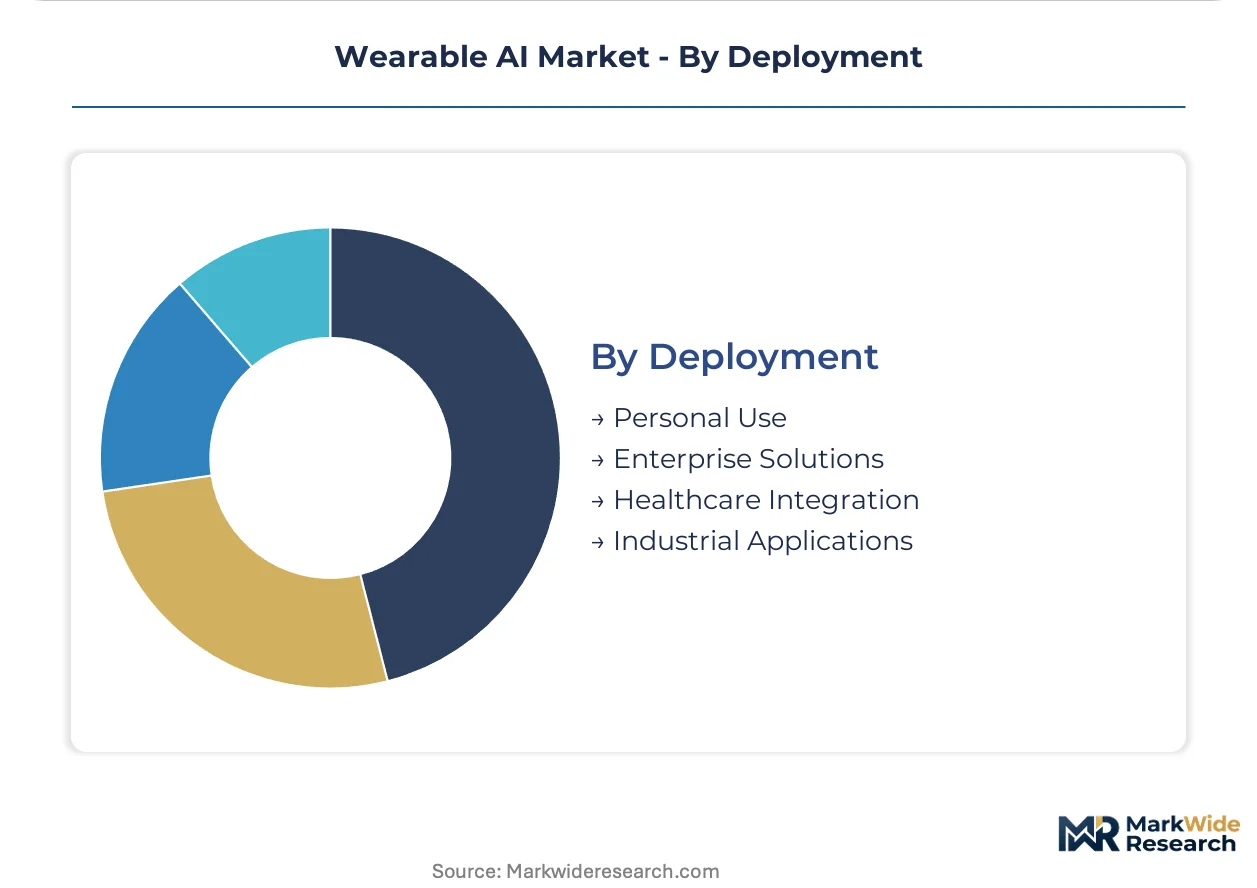
Deployment:
Deployment mode shapes vendor business models, separating upfront hardware margins from recurring platform revenue and outcome-based risk partnerships.
- Personal Use:Direct-to-consumer retail channels with 18-24 month replacement cycles dominate shipment volumes. Brand loyalty programs and ecosystem lock-in sustain pricing power for vertically integrated vendors.
- Enterprise Solutions:Outcome-based fleet management contracts unbundle hardware from analytics subscriptions. Mining operators in Australia and Canada procure predictive fatigue monitoring as occupational risk services rather than equipment.
- Healthcare Integration:FDA-cleared devices integrate with Epic and Cerner EHR systems, requiring interoperability certification that extends sales cycles.
- Industrial Applications:Exoskeletons and AI-enabled hard hats for collision avoidance pilot in German construction and logistics verticals with strict TÜV safety certification.
Personal Use accounts for the largest installed base; Industrial Applications are climbing the fastest as safety regulation tightens across European worksites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in the United States and Germany where FDA and EU AI Act compliance create certification moats, while manufacturing scale advantages cluster in China's coastal provinces where component ecosystems compress production costs.
United States
Healthcare procurement drives demand through FDA-cleared remote patient monitoring devices eligible for reimbursement codes. The FDA Software as a Medical Device pathway accelerates clearance timelines for algorithm-enabled diagnostic wearables. Silicon Valley and Greater Boston anchor development clusters where Apple and Google maintain AI research operations.
Germany
Industrial safety applications in construction and logistics verticals pilot AI-enabled hard hats and exoskeletons for predictive fatigue monitoring. The EU AI Act high-risk system classification mandates conformity assessments that extend compliance timelines for health-monitoring wearables. Bavaria and North Rhine-Westphalia concentrate manufacturing automation expertise where TÜV safety certification shapes product specifications.
China
Domestic production ecosystems around Huawei Technologies and Xiaomi Corporation concentrate battery and display supply chains serving price-sensitive segments. Dual carbon goals incentivize energy-efficient edge compute manufacturing. The Yangtze River Delta and Pearl River Delta anchor assembly operations where MIIT standards govern wireless transmission protocols.
India
Fitness tracker demand clusters in urban centers where Xiaomi and local brands compete on manufacturing scale accessibility. The PLI scheme for electronics manufacturing attracts contract manufacturers to establish domestic assembly capacity outside China concentration. Karnataka and Tamil Nadu host emerging production clusters where BIS certification requirements filter import competition.
Japan
Elderly care applications for fall detection and medication adherence alerts serve institutional buyers in aging demographics with specific quality requirements. METI standards govern data privacy frameworks for biometric wearables. The Kanto region around Tokyo anchors precision sensor manufacturing where PMDA consultation shapes clinical validation protocols.
Wearable AI Market Vendor Landscape
Concentration sits with vertically integrated technology conglomerates that control custom silicon design and component supply chains. The vendor base stratifies across three tiers: captive chip designers commanding premium margins, fabless assemblers outsourcing to MediaTek and Qualcomm platforms, and manufacturing-scale specialists competing on hardware accessibility. Dominant competitive moves include backward integration into semiconductor architectures and geographic expansion through production-linked incentive schemes in India and Vietnam.
Among North American technology conglomerates, Apple Inc. and Google Inc. exemplify the captive silicon archetype through in-house neural engine development. Samsung Electronics Co. Ltd. anchors the Korean vertically integrated position spanning display, memory, and application processor verticals. Xiaomi Corporation represents the manufacturing-scale archetype competing on hardware accessibility across South Asian and African price-sensitive segments.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics Co. Ltd. |
| Garmin Ltd. |
| Fitbit, Inc. |
| Google Inc. |
| Huawei Technologies Co. Ltd. |
| Xiaomi Corporation |
| Sony Corporation |
| Meta |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation agreements with optical waveguide suppliers lock in margin visibility for smart glasses assemblers while insulating them from substrate price volatility that compresses non-vertically integrated vendors. These contracts tether pricing power to supply security, creating divergent cost structures between captive component producers and fabless competitors.
Pricing Analysis
The customization-premium spread separates FDA-cleared diagnostic wearables from wellness-only devices, with clinical validation tiers commanding three-to-five-fold hardware premiums. Subscription-SaaS tiered models dominate enterprise procurement, where outcome-based fleet management contracts unbundle hardware from analytics services. Price differentiation rests on ISO 13485 certification grade and geographic delivery cost, with EU AI Act compliance adding six-to-nine month timeline premiums. Cost compression in mid-tier smartwatches is intensifying because MediaTek and Qualcomm platform commoditization erodes pricing power for fabless assemblers. Price-sensitive fitness tracker buyers in India and Southeast Asia drive volume, while healthcare procurement in the United States shows least sensitivity due to reimbursement eligibility.
Supply Chain Analysis
Taiwan and South Korea anchor sub-5nm wafer fabrication for neural engine cores, while China concentrates battery cell and display module assembly. The supply chain draws from photoplethysmography sensors in Japan, precision etched optical substrates in Germany, and rare earth magnet components in China. Single-source vulnerability sits with limited suppliers of optical waveguide inputs, creating margin compression risk for smart glasses vendors lacking backward integration into display verticals. Distribution runs through direct-to-consumer retail channels for personal use segments and GPO-contracted procurement for healthcare system integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent wearable AI vendors face substitution pressure from smartphone-native health monitoring pipelines that compress the addressable market for dedicated wrist-worn devices. Defense requires structural repositioning around irreplaceable form factors and clinical certification moats.
For Market Incumbents: Fortify captive silicon design pipelines to sustain power-performance optimization that commodity assemblers cannot replicate. Deepen FDA 510(k) submission portfolios for algorithmic diagnostic claims, locking in reimbursement eligibility that smartphone competitors cannot easily access. Channel control through Epic and Cerner EHR interoperability certification extends sales cycles but creates switching costs for healthcare system buyers.
For New Entrants and Emerging Players: Differentiate on industrial safety applications where TÜV certification requirements filter incumbent competition and outcome-based contracts reward specialized analytics capabilities. Target German construction and logistics verticals piloting predictive fatigue monitoring, where regulatory complexity deters consumer-focused competitors. A go-to-market angle through occupational risk partnerships rather than equipment supply compresses upfront capital barriers while securing multi-year data service revenue.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among enterprise fleet management platforms unbundling hardware from predictive analytics subscriptions. Long-term viability over the next decade hinges on regulatory compliance infrastructure that extends product development timelines into defensible moats. Acquisition target archetypes include vertically integrated optical component specialists with waveguide etching capabilities. The signal to watch is FDA SaMD clearance velocity for algorithm-enabled diagnostic wearables as an inflection indicator for reimbursement-accessible market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Custom Silicon Development | Apple and Samsung deploy proprietary neural engines that commodity assemblers cannot match on power efficiency. |
| FDA SaMD Clearance Pathway | Algorithm-enabled diagnostic wearables unlock reimbursement eligibility under remote patient monitoring codes. |
| Optical Waveguide Integration | Micro-LED convergence enables all-day battery life for enterprise AR workflows previously blocked by thermal limits. |
| Outcome-Based Fleet Contracts | Australian mining operators procure predictive fatigue monitoring as occupational risk services rather than equipment. |
| India PLI Manufacturing Expansion | Production-linked incentives attract contract manufacturers to establish assembly capacity outside China concentration. |
Methodological Framework
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads at wearable device vendors, then refined through secondary validation. Sources included FDA 510(k) filings, EU AI Act conformity assessment documentation, CMS Medicare reimbursement code databases, and hospital procurement contract records. Bottom-up shipment estimates by form factor and top-down market sizing by end-use segment were triangulated to resolve variance.
Variance decomposition across product type, technology layer, end-user archetype, and deployment mode shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth trajectory modeling incorporating semiconductor node transition timelines, regulatory clearance velocity by geography, and optical waveguide cost decline curves. Industry-specific forecast inputs included photoplethysmography sensor miniaturization rates and EU AI Act implementation stringency by member state.
Material uncertainties — FDA guidance shifts on AI diagnostic validation, optical substrate supply disruptions, and smartphone health feature convergence — sit outside the modeled envelope. Forecasts reflect assumptions about reimbursement code stability and CE marking timeline consistency. Recalibration cycles align with material shifts in regulatory clearance frameworks and display-battery integration breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Turkey Health and Medical Insurance Market
Others
AC Switchgear Market
Others
Pickup Truck Market
Others
Fibert Market
Others
Japan Coal Market
Others
Hybrid Switchgear Market
Others
Receiving Scales Market
Others
8K Technology Market
Others
Security Envelopes Market
Others
Security Bottles Market
Others
Europe Polycarbonate Sheets Market
Others
Saudi Arabia Laser Hair Removal Market
Others
Language Translation Device Market
Others
AI In Government And Public Services Market
Others
Remanufacturing-as-a-Service (RaaS) Market
Others
Digital Bass Processor Market