
 Smart Card Market | 2026-2036
Smart Card Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Card Market Analysis
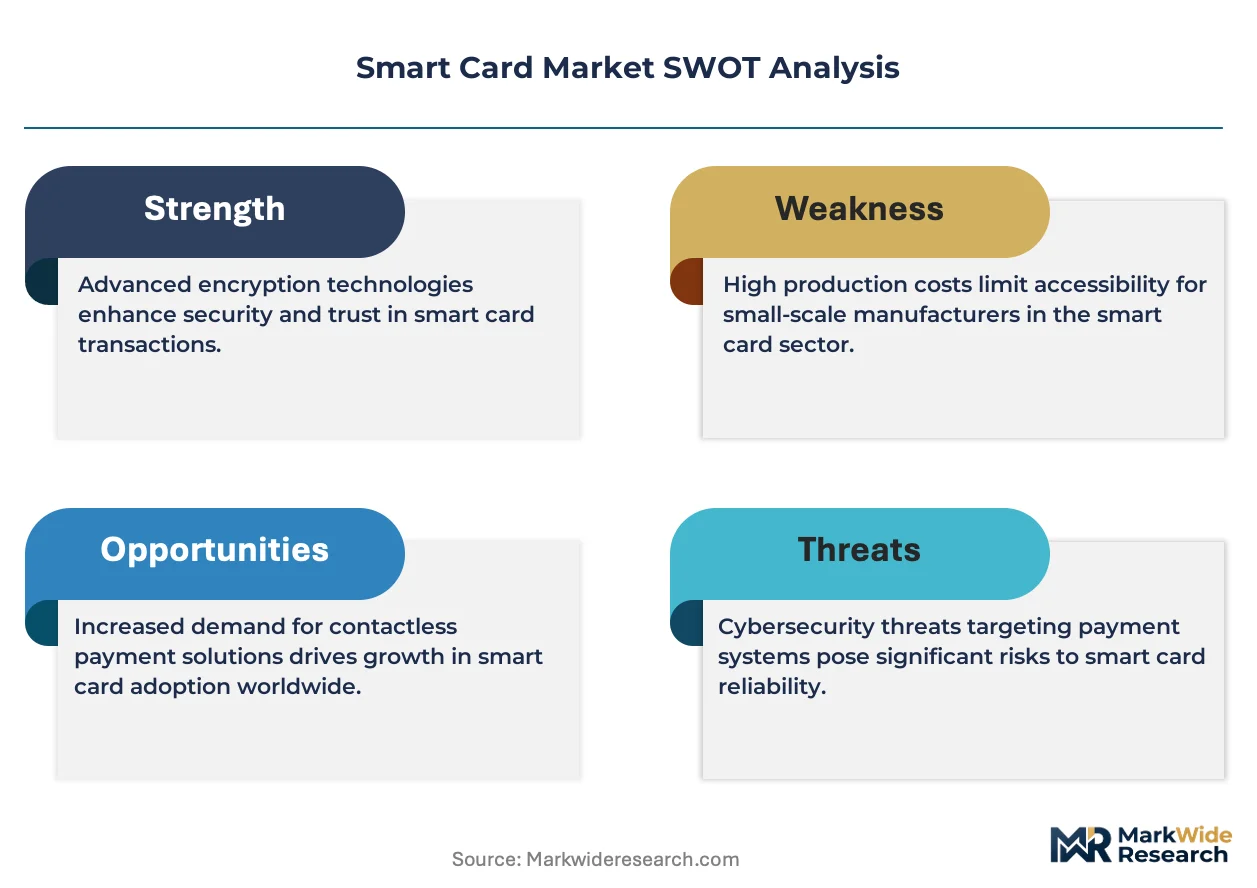
Common Criteria EAL5+ certification is bifurcating the competitive landscape into qualified and non-qualified suppliers. NXP Semiconductors leverages its secure element portfolio to anchor government ID contracts across multiple continents. Infineon Technologies sustains manufacturing scale through captive semiconductor fabrication. Giesecke+Devrient differentiates via embedded software integration and personalization services.
A smart card is a pocket-sized plastic card with an embedded integrated circuit chip that stores, processes, and transmits data through physical contact or radio frequency interfaces, typically operating at 13.56 MHz for contactless variants and requiring ISO 7816 compliance for contact-based communication. Its primary commercial purpose is to enable authenticated transactions, secure identity verification, and controlled access to physical or digital resources. Contactless cards lead volume shipments in payment solutions as tap-to-pay behavior displaces magnetic stripe usage. EMV technology commands the highest security premium among chip standards, while hybrid cards occupy a transitional niche for markets with mixed terminal infrastructure.
FCC regulations in the United States govern RF emission profiles for contactless cards, while the EU AI Act and GDPR shape how biometric-enabled smart IDs process personal data across European member states. India's BIS certification mandates local testing for imported secure components, creating market access friction for foreign suppliers. Stakeholders must monitor how central bank digital currency pilots reshape card-based payment architectures and whether semiconductor supply constraints alter chip sourcing strategies.
Market Dynamics
EMV chip mandates from payment networks are compelling terminal and card upgrades across banking infrastructure, while India's national identity program concentrates demand volume in government ID issuance.
Growth Catalysts
- EMV Migration Mandates:Payment network deadlines in the United States and European Union are forcing magnetic stripe replacement. Terminal infrastructure upgrades cascade into card reissuance cycles.
- Financial Inclusion Policy:India's Jan Dhan Yojana and comparable programs in Brazil and Nigeria are expanding banked populations. Unbanked consumer segments require payment credential issuance at scale.
- Contactless Interface Standardization:ISO 14443 protocol maturation enables tap-to-pay deployment. Retail banking channels prioritize dual-interface card procurement to capture transaction speed advantages.
Market Restraints
- Semiconductor Supply Concentration:Secure element fabrication concentrates among three foundry groups. Geopolitical friction in Taiwan Strait regions threatens wafer supply continuity for card-embedded chips.
- BIS Certification Friction:India's Bureau of Indian Standards mandates local testing for imported secure components. Foreign suppliers face six-to-nine month approval timelines before market entry.
- Mobile Wallet Substitution:Smartphone-based payment applications bypass physical card requirements. Younger demographics in developed markets show reduced card-carrying behavior.
Strategic Opportunities
- Central Bank Digital Currency Integration:Pilot programs in China, India, and the European Union are testing hardware-secured CBDC wallets. Dual-currency cards could bridge fiat and digital settlement.
- Biometric-Enabled Government IDs:Fingerprint and iris matching on national identity cards addresses fraud in benefit distribution. African and South Asian markets represent underpenetrated deployment zones.
- Healthcare Credential Convergence:Insurance cards with embedded clinical data storage streamline provider verification. Germany's electronic health card infrastructure offers a template for regional expansion.
Industry Challenges
- EAL5+ Certification Timeline:Common Criteria security evaluations require eighteen-to-twenty-four months. Product development cycles must anticipate certification bottlenecks.
- Legacy System Integration:Government ID programs must interface with decades-old civil registry databases. Middleware development consumes project budgets and extends deployment schedules.
- Secure Element Talent Scarcity:Cryptographic engineering and side-channel attack mitigation skills concentrate among limited specialist pools. Recruitment competition intensifies with automotive and aerospace sectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Card Market |
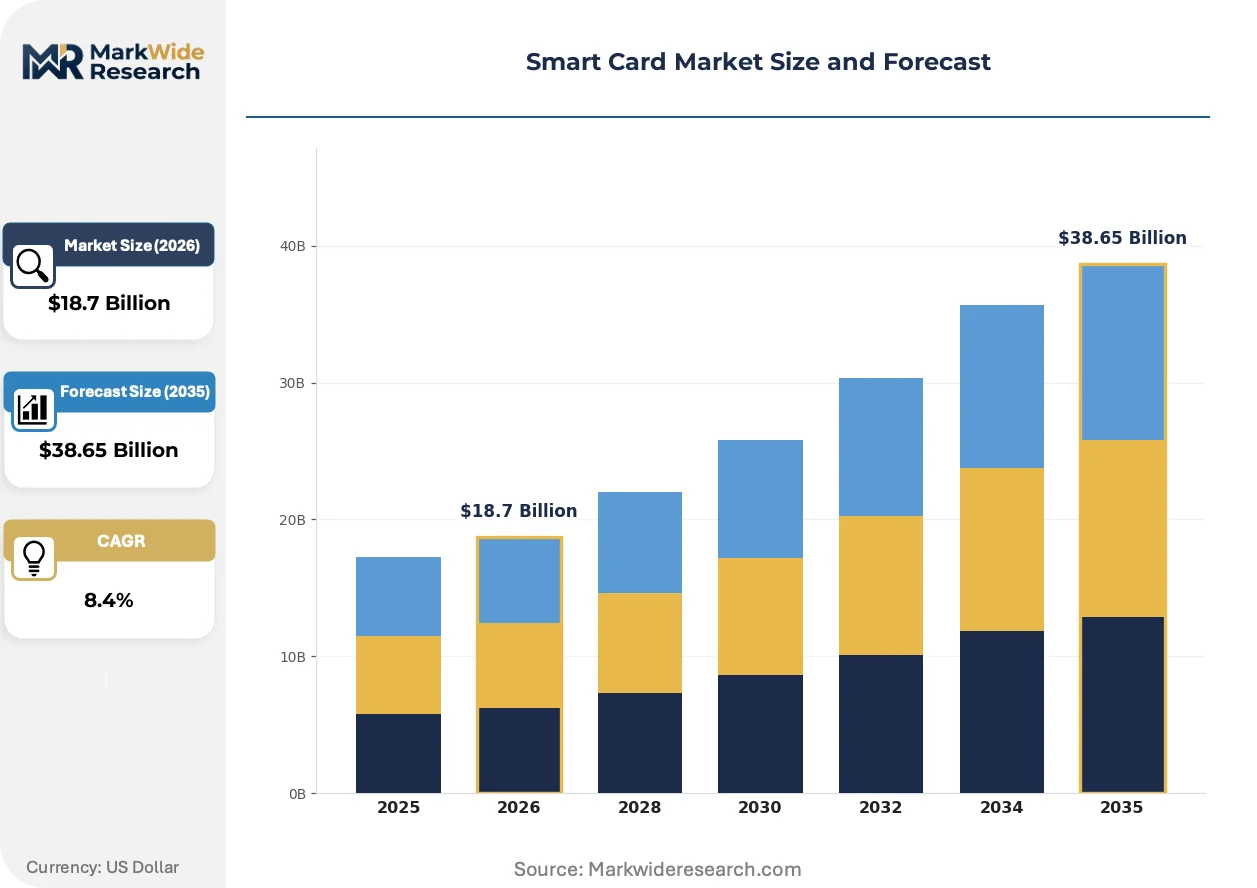
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contactless Cards, Contact Cards, Hybrid Cards, Smart ID Cards End User: Banking, Transportation, Government, Healthcare Technology: RFID, NFC, EMV, Magnetic Stripe Application: Payment Solutions, Access Control, Identification, Loyalty Programs |
| Companies Covered | NXP Semiconductors, HID Global, IDEMIA, STMicroelectronics, CPI Card Group, Thales, Infineon Technologies, Gemalto, Giesecke+Devrient, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Card Market Emerging Trajectories
Dual-interface card architectures are mainstreaming across payment portfolios as tap-to-pay behavior displaces contact-only transaction patterns. Regulatory pressure on biometric data handling and semiconductor supply security are reshaping product roadmaps.
Biometric payment cards embedding fingerprint sensors are displacing PIN-entry protocols in European and Asian pilot deployments. Issuers in France and South Korea are testing battery-less capacitive sensors for offline authentication. The structural consequence is compressing fraud liability exposure while raising unit costs thirty to fifty percent above standard EMV cards.
GDPR and the EU AI Act are imposing algorithmic transparency requirements on biometric-enabled smart IDs. Personal data processing must demonstrate explicit consent chains and purpose limitation. European government ID contractors are re-engineering enrollment workflows to embed privacy-by-design architectures before 2025 compliance deadlines.
Consolidated procurement by national payment switch operators is displacing fragmented bank-by-bank tendering in emerging markets. India's NPCI and Brazil's Elo are negotiating volume commitments directly with semiconductor vendors. This concentration is visible across South Asia and Latin America where state-linked payment infrastructure dominates retail transaction routing.
Smart Card Market Segmentation
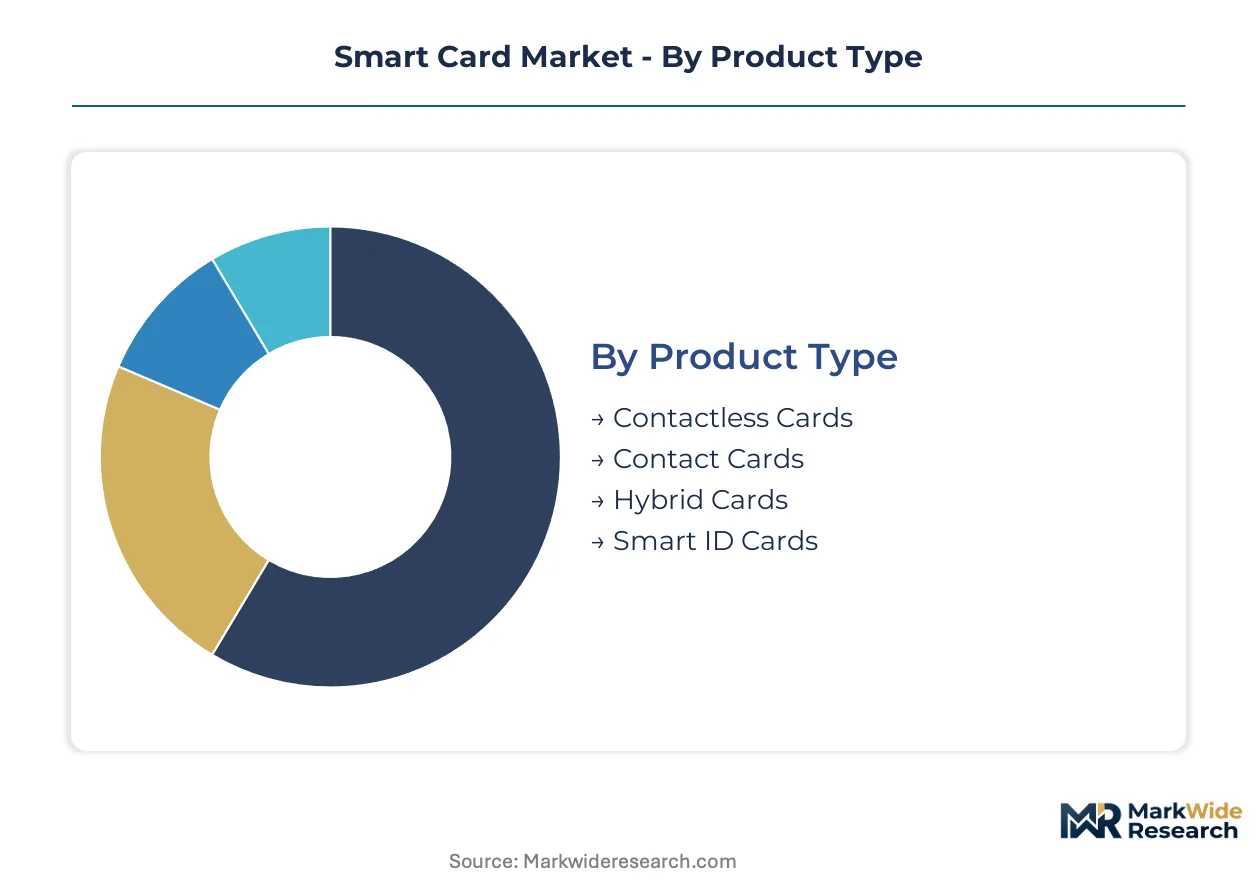
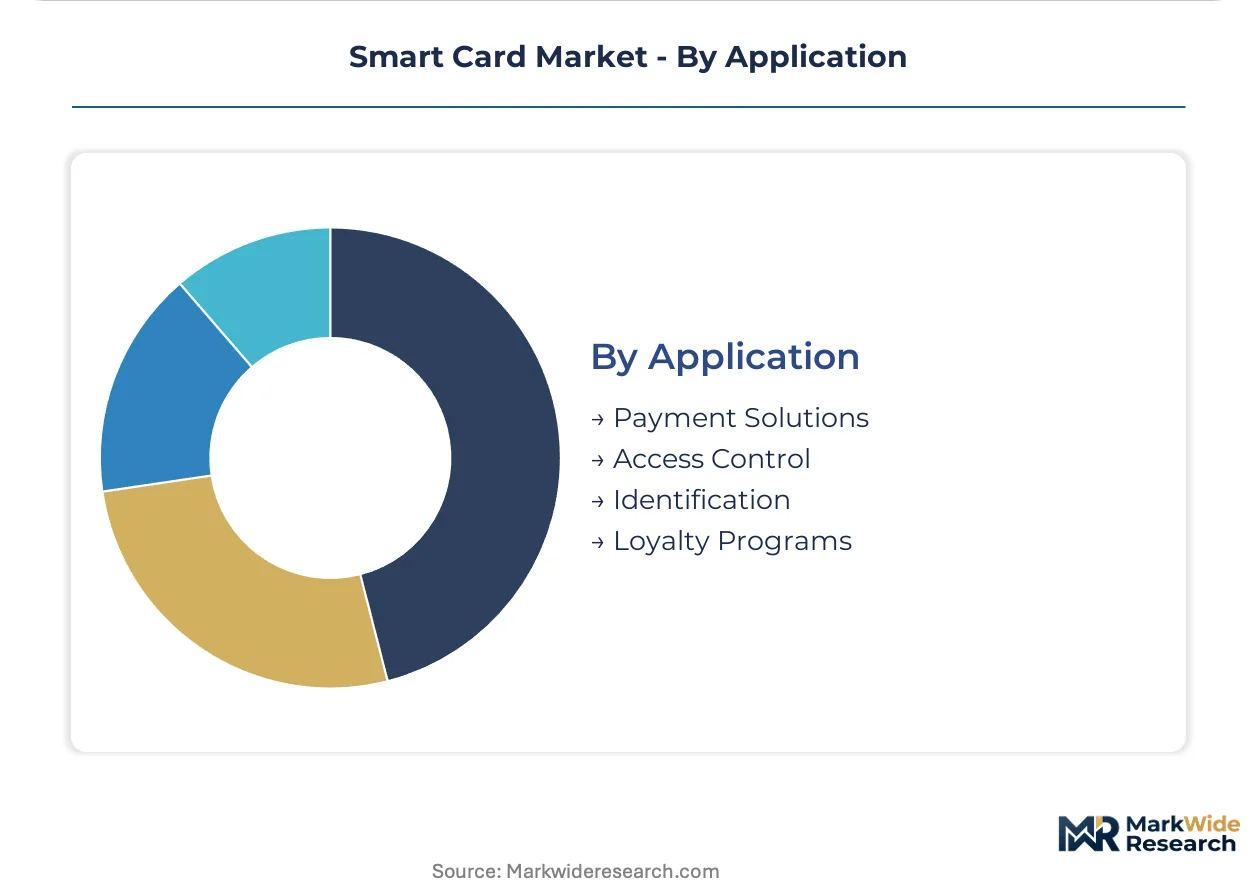
Smart card procurement channels bifurcate between government tender processes and commercial bank RFP cycles. Understanding segment-channel alignment reveals where pricing power concentrates and which specifications dominate volume contracts.
Product Type:
Channel mix varies sharply by interface technology: contactless cards flow predominantly through retail banking procurement, while smart ID cards route through national government tenders with extended certification timelines.
- Contactless Cards:ISO 14443-compliant devices operating at 13.56 MHz enable tap-to-pay transactions without physical terminal insertion. Demand concentrates in France and South Korea where biometric pilots are displacing PIN-entry protocols, though unit costs run thirty to fifty percent above standard EMV cards.
- Smart ID Cards:Multi-application credentials embedding secure microcontrollers for national identity programs. India's national identity program concentrates volume here, with BIS certification mandates creating six-to-nine month approval friction for foreign component suppliers.
- Contact Cards:ISO 7816-compliant devices requiring physical chip-to-terminal electrical contact. Legacy infrastructure in North American banking sustains residual demand.
- Hybrid Cards:Dual-interface architectures supporting both contact and contactless protocols. Transitional markets with mixed terminal infrastructure drive procurement.
Contact cards dominate installed base. Contactless cards are where expansion concentrates.
End User:
Cost tier stratification separates government ID contracts with extended payment terms from commercial banking procurement with faster settlement cycles.
- Government:National identity and benefit distribution programs requiring Common Criteria EAL5+ certification. India's Jan Dhan Yojana and comparable financial inclusion initiatives in Brazil and Nigeria are expanding banked populations and credential issuance at scale.
- Banking:Payment card issuance for credit, debit, and prepaid products. EMV migration mandates in the United States and European Union are forcing magnetic stripe replacement and terminal infrastructure upgrades.
- Transportation:Transit fare collection and mobility-as-a-service credentials. Urban transit authorities in East Asian cities are deploying closed-loop contactless systems.
- Healthcare:Insurance cards with embedded clinical data storage for provider verification. Germany's electronic health card infrastructure offers a template for regional expansion.
Government contracts anchor volume commitments. Banking is expanding most quickly through EMV replacement cycles.
Technology:
Application specificity determines technology selection: EMV commands the highest security premium in payment solutions, while RFID dominates access control with lower authentication overhead.
- EMV:Europay-Mastercard-Visa chip standard with dynamic data authentication for payment security. Payment network deadlines are compelling terminal and card upgrades across banking infrastructure.
- NFC:Near Field Communication enabling peer-to-peer data exchange and mobile wallet integration. Smartphone-based payment applications are creating substitution pressure on physical card requirements.
- RFID:Radio frequency identification for asset tracking and physical access control. ISO 15693 and ISO 18000-3 protocols serve non-payment authentication use cases.
- Magnetic Stripe:Legacy data storage on iron oxide tape. EMV mandates are accelerating displacement except in residual transit and hospitality applications.
Magnetic stripe retains residual installed base. EMV is where specification upgrades concentrate.
Application:
Customer type segmentation separates enterprise security buyers from consumer-facing issuers, with loyalty programs bridging both through co-brand arrangements.
- Payment Solutions:Credit, debit, and prepaid transaction authorization. Contactless tap-to-pay behavior is displacing magnetic stripe usage in retail banking channels.
- Identification:Government and corporate identity verification with biometric matching. Fingerprint and iris matching on national identity cards addresses fraud in benefit distribution across African and South Asian markets.
- Access Control:Physical facility and digital resource entry management. Corporate campus security departments prioritize dual-interface credentials for multi-factor authentication.
- Loyalty Programs:Co-branded retail and airline reward credentials with stored value functionality. Retailers in developed markets are consolidating program management onto payment-card substrates.
Payment solutions dominate transaction volume. Identification is where government procurement concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Jan Dhan Yojana and national identity program concentrate government procurement volume, while EMV mandates in the United States and European Union drive banking infrastructure replacement cycles. Regulatory fragmentation across BIS certification requirements and GDPR biometric data rules shapes supplier market access strategies.
United States
EMV migration deadlines from Visa and Mastercard force magnetic stripe replacement across retail banking channels. FCC regulations govern RF emission profiles for contactless card deployment. Terminal infrastructure upgrades in Chicago and New York financial districts cascade into dual-interface card reissuance programs.
India
The national identity program and Jan Dhan Yojana financial inclusion initiative drive credential issuance at unprecedented scale. BIS certification mandates six-to-nine month approval timelines for imported secure components. Manufacturing clusters in Bengaluru and Hyderabad assemble domestic card personalization capacity to bypass import friction.
Germany
Electronic health card infrastructure templates regional healthcare credential convergence across European insurance networks. GDPR and the EU AI Act impose algorithmic transparency requirements on biometric-enabled smart IDs. Frankfurt and Munich host secure element engineering talent pools for government ID contract development.
France
Biometric payment card pilots embedding fingerprint sensors displace PIN-entry protocols in retail banking channels. ANSM and CNIL oversight shapes personal data processing consent chains for national ID programs. Paris-based personalization bureaus serve African government ID export markets.
South Korea
Battery-less capacitive fingerprint sensors enable offline authentication in contactless payment pilots. MFDS-equivalent standards govern healthcare credential data security for regional insurance integration. Seoul semiconductor design houses specialize in low-power secure element architectures for transit and payment convergence.
Smart Card Market Vendor Landscape
Player mix skews toward semiconductor-integrated specialists with captive fabrication capacity and certification-qualified personalization bureaus. Common Criteria EAL5+ bifurcation separates qualified from non-qualified supplier tiers. Strategic archetypes include secure element foundries with government ID anchoring, embedded software integrators with personalization service bundling, and fabless chip designers licensing IP to card manufacturers. Competitive moves concentrate on foundry capacity reservation agreements and biometric sensor module partnerships.
Within the semiconductor-anchored tier, NXP Semiconductors and Infineon Technologies occupy positions defined by secure element portfolio breadth and captive wafer fabrication scale. Giesecke+Devrient exemplifies the software-integration archetype through embedded operating system and personalization service bundling. These three anchors represent how EAL5+ certification concentration and government contract anchoring stratify competitive positioning across banking and identity verticals.
| Leading Market Players |
|---|
| NXP Semiconductors |
| HID Global |
| IDEMIA |
| STMicroelectronics |
| CPI Card Group |
| Thales |
| Infineon Technologies |
| Gemalto |
| Giesecke+Devrient |
| Others |
Supply Flow & Price Mechanics
Capacity reservation agreements with tier-one semiconductor foundries lock in both secure element supply and eighteen-month price visibility for smart card manufacturers bidding government ID tenders. These contractual structures concentrate procurement leverage among EAL5+ certified suppliers while exposing non-qualified vendors to spot-market silicon volatility.
Pricing Analysis
Cost-plus contracts indexed to wafer fabrication pricing dominate government ID procurement, with BIS certification tiers creating three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on Common Criteria evaluation grade and volume commitment scale, with Indian national identity program issuers commanding lowest unit costs through consolidated tendering. Pricing pressure stems from biometric sensor module integration raising bill-of-materials thirty to fifty percent above standard EMV configurations. Banking segments exhibit highest price sensitivity due to mobile wallet substitution eroding transaction fee economics, while government buyers prioritize certification compliance over unit cost.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for secure element production, with Germany and France hosting personalization bureau capacity for European and African government ID contracts. Raw material dependencies center on silicon wafers, copper-clad laminates for antenna inlays, and cobalt-tantalum alloys for tamper-resistant packaging. Single-source vulnerability concentrates in advanced node secure element lithography, where geopolitical friction in Taiwan Strait regions threatens supply continuity. Distribution runs through national payment switch operators in emerging markets and direct bank procurement channels in developed economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized cryptographic engineering talent pools are contracting as automotive and aerospace sectors compete for identical secure microcontroller design capabilities, compressing product development timelines for certification-intensive contracts.
For Market Incumbents: Consolidate foundry capacity reservation agreements to defend against semiconductor supply concentration risks, particularly for 40nm and below secure element nodes. Deepen backward integration into antenna inlay manufacturing to capture margin from hybrid card architectures. Prioritize biometric sensor module partnerships before European GDPR compliance deadlines reshape enrollment workflow specifications.
For New Entrants and Emerging Players: Lead with healthcare credential convergence applications in German-speaking European markets, where electronic health card infrastructure templates create replicable deployment models. Target African national identity programs with fingerprint-matching credentials as underpenetrated zones with less entrenched incumbent relationships. Pursue co-development partnerships with regional personalization bureaus to bypass eighteen-to-twenty-four month EAL5+ certification bottlenecks.
For Investors and Strategic Acquirers: Embedded software integrators with captive personalization services represent the most defensible acquisition profile for exposure to government ID contract anchoring. Long-term viability hinges on dual-interface card architecture dominance persisting through central bank digital currency pilot phases. Monitor CBDC hardware wallet procurement announcements from China's e-CNY and India's digital rupee programs as inflection signals for secure element demand trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Sensor Module Partnership | Enables offline fingerprint authentication for European payment card pilots displacing PIN-entry protocols. |
| EAL5+ Certification Fast-Track Investment | Compresses eighteen-month evaluation timelines to capture Indian government ID tender windows. |
| Foundry Capacity Reservation Agreement | Locks wafer supply through Taiwan Strait geopolitical volatility for dual-interface card production. |
| Healthcare Credential Platform Expansion | Leverages Germany's electronic health card infrastructure template for regional insurance network integration. |
| Privacy-by-Design Enrollment Workflow | Embeds GDPR and EU AI Act compliance before 2025 biometric data processing deadlines. |
Methodological Framework
A standing panel of secure element engineering directors, government ID procurement officers, payment network compliance leads, and biometric sensor module specialists provided ongoing calibration across the analysis window. Primary fieldwork combined structured interviews with semiconductor foundry account managers and personalization bureau operations heads, validated against secondary sources including BIS certification registries, EMVCo specification releases, and NPCI tender documentation. Bottom-up volume modeling from national identity program issuance targets triangulated against top-down payment card reissuance cycle projections.
Consistency checks validated volume and value outputs against external benchmarks from customs trade data, secure element import filings, and central bank payment system reports. The analytical framework modeled segmentation across interface technology, end-user vertical, certification tier, and regional regulatory cluster throughout the forecast period. CAGRs were derived from weighted average of historical issuance trajectories and policy-mandated replacement schedules, with specific inputs from Jan Dhan Yojana enrollment targets and EMV terminal penetration curves.
Forecasts assume regulatory continuity in India's BIS certification regime and European GDPR enforcement; material policy shifts would require re-modeling of supplier market access timelines and biometric data processing architectures. Supply constraint scenarios and central bank digital currency pilot accelerations represent specific risk factors that could revise projection trajectories. Recalibration cycles align with material shifts in semiconductor foundry capacity allocation and government ID tender award announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Medium-Voltage Switchgear Market
Others
Global Radar Systems Market
Others
Cloud Broadcasting Solutions Market
Others
Process Instrumentation Equipment Market
Others
Sports Events Market
Others
Channel-In-A-Box (Ciab) Market
Others
Evidence Management Market
Others
Stichtite Market
Others
Global Thermally Conductive Grease Market
Others
5G Enabled Healthcare Services Market
Others
Billet Market
Others
Global Webinar and Webcast Market
Others
IT Device Market
Others
Viral Vector Contract Development and Manufacturing Organization (CDMO) Market
Others
Lychee Market
Others
Nanomedicine for Drug Delivery Market