
 Solid White Films Market | 2026-2036
Solid White Films Market Size, Share, and Industry Trends Forecast 2026-2036
Solid White Films Market Analytics
A capital-intensity divergence between integrated resin producers and downstream converters is reorganizing competitive tiers in solid white films. Amcor plc leverages captive polymer sourcing and blown film extrusion assets across multiple continents to sustain margin stability. Toray Industries anchors its position through biaxially oriented polyethylene terephthalate leadership and optical-grade coating capabilities that differentiate performance tiers.
Solid white films are opaque polymer substrates engineered with titanium dioxide or calcium carbonate loadings typically between 8% and 15% by weight, manufactured through cast or blown extrusion processes to achieve uniform light-blocking properties for shelf-life extension and UV protection. Polyethylene grades dominate volume in food-contact pouch and lidding applications where cost efficiency and heat-sealability matter most, while PET variants command premium positioning in pharmaceutical blister packs demanding dimensional stability and barrier precision. Polypropylene occupies a middle ground in retort and microwaveable packaging where thermal resistance intersects with moderate opacity requirements.
The EU's Packaging and Packaging Waste Regulation alongside FDA food-contact substance notifications and REACH chemical compliance frameworks collectively elevate testing burdens and reformulation costs for cross-border suppliers. ISO 9001 and BRC packaging certifications have become baseline qualifiers for entry into European and North American food and pharmaceutical supply chains rather than differentiators. Stakeholders must monitor evolving extended producer responsibility schemes and substrate-specific recycling quotas that will determine which resin platforms retain access to premium application segments.
Market Dynamics
Recyclability mandates under the EU's Packaging and Packaging Waste Regulation are forcing substrate reformulation across the solid white films value chain, compressing margins for non-compliant suppliers while rewarding early adopters of mono-material designs.
Growth Catalysts
- Extended Producer Responsibility schemes:Germany's VerpackG and France's Citeo eco-modulation are accelerating demand for detectable white films in sorting streams. Food brands in the Rhine-Ruhr cluster are specifying these grades for private-label launches.
- Blown film extrusion advances:New die designs enabling 15% TiO2 loading without melt fracture are expanding addressable applications into high-opacity lidding for ready-meal trays. Equipment suppliers in Italy and Austria are retrofitting lines for this capability.
- India:FSSAI's tightening food-contact notification requirements are displacing unorganized film suppliers in Mumbai and Ahmedabad. Organized converters with BIS certification are capturing volume in snack and dairy packaging.
Market Restraints
- Titanium dioxide feedstock concentration:Over 60% of chloride-route TiO2 capacity sits with Chinese producers subject to export license variability. European compounders face working capital pressure from six-month procurement cycles.
- Multi-layer incompatibility:EVOH and PA barrier layers in legacy white films block mechanical recycling under APR design guidelines. Brand owners face write-downs on existing film inventories.
- Paperboard substitution in frozen food:Fiber-based trays with bio-barrier coatings are capturing share in Scandinavian retail chains where plastic taxes exceed €200 per tonne.
Strategic Opportunities
- Chemical recycling integration:Pyrolysis partnerships with petrochemical majors in Rotterdam and Antwerp are creating outlets for mixed-polymer white film waste. This unlocks circularity claims for premium food brands.
- Digital watermarking convergence:Digimarc and AIM standards integration with white film substrates enables AI-powered sorting. Early deployments in French supermarkets are demonstrating 95% detection rates.
- Pharmaceutical serialization:EU MDR's unique device identification requirements for blister packs favor white PET films with laser-markable top layers. Contract manufacturers in Ireland and Switzerland are qualifying these grades.
Industry Challenges
- Migration testing capacity:ISO 17025-accredited laboratories for overall migration and specific migration limits face six-month backlogs in Southern Europe. Film suppliers miss launch windows awaiting compliance documentation.
- Extrusion line reconfiguration:Transitioning from multi-layer to mono-material white films requires screw and die replacement costing €800,000-1.2 million per line. Mid-size converters in Spain and Poland defer capex decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid White Films Market |
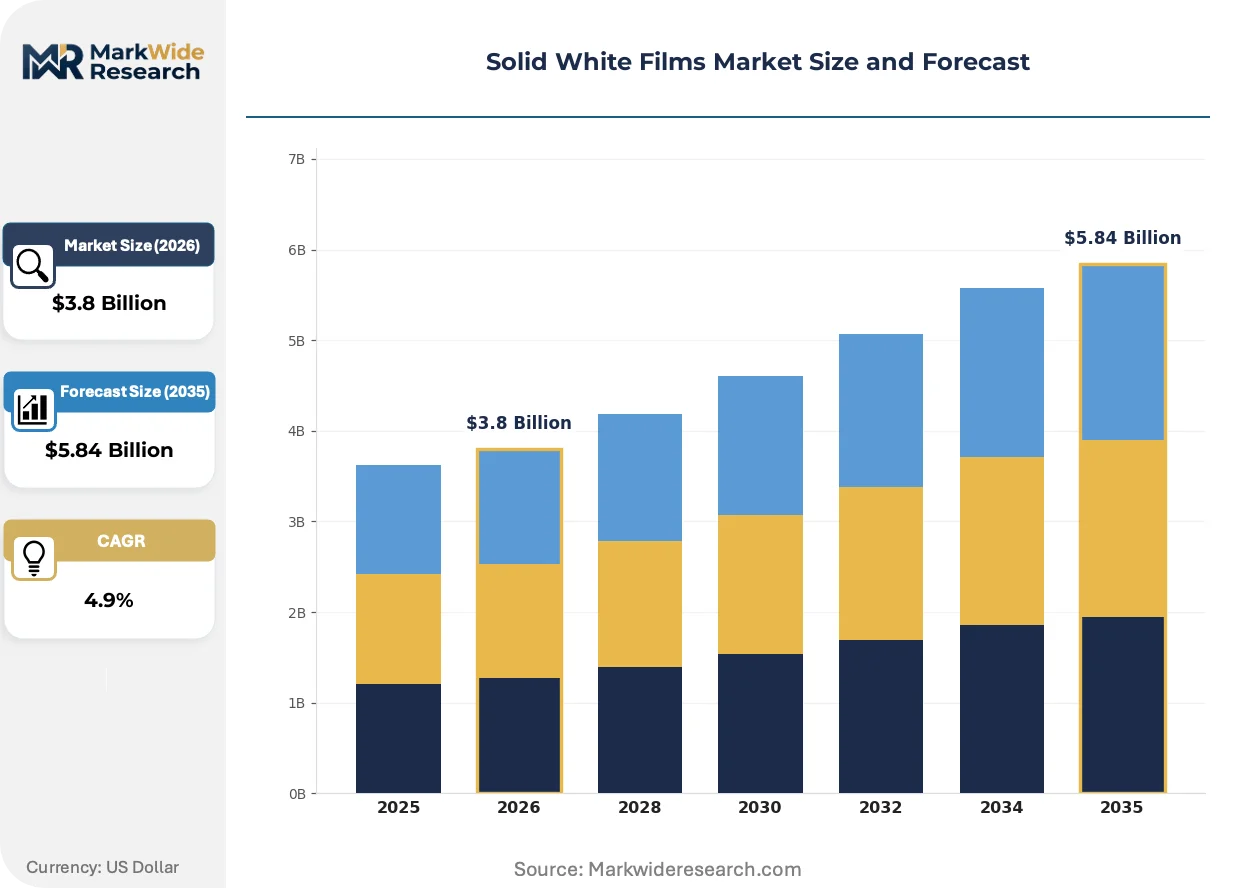
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.84 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, PVC, PET Application: Packaging, Agriculture, Construction, Medical End User: Food Industry, Pharmaceutical, Retail, Automotive Thickness: Micron, Millimeter, Custom, Standard |
| Companies Covered | Berry Global Inc., Amcor plc, Berry Global Group, Inc., Cosmo Films, Toray Industries, Polyplex Corporation, Jindal Poly Films Ltd, Taghleef Industries, Flex Films, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid White Films Market Evolving Landscape
Material science advances and detection technologies are reshaping how solid white films achieve opacity, recyclability, and supply chain traceability simultaneously.
Calcium carbonate masterbatch formulations with surface-treated nano-particles are decomposing the traditional TiO2 monopoly in cost-sensitive applications. Turkish and Egyptian converters serving Middle Eastern dairy markets are adopting these grades for 20-30% raw material savings. The technology is compressing margin pools for legacy pigment suppliers while enabling price-competitive entry into private-label supply chains.
REACH's restriction roadmap for microplastics is compelling film producers to validate biodegradation pathways for oxo-degradable additives previously used in agricultural mulch films. The European Chemicals Agency's 2026 sunset clause for non-compliant additives is accelerating reformulation programs. Italian compounders are pivoting toward bio-based fillers certified under OK Compost INDUSTRIAL standards.
Consolidated buying desks at pan-European retail alliances are unbundling technical specification from logistics procurement. Carrefour and Ahold Delhaize's centralized packaging teams now issue film tenders separating performance requirements from delivery terms. This bifurcation is visible most acutely in Germany and the Netherlands, where regional converters compete solely on conversion economics while resin sourcing decisions migrate to headquarters-level category managers.
Solid White Films Market Segmentation
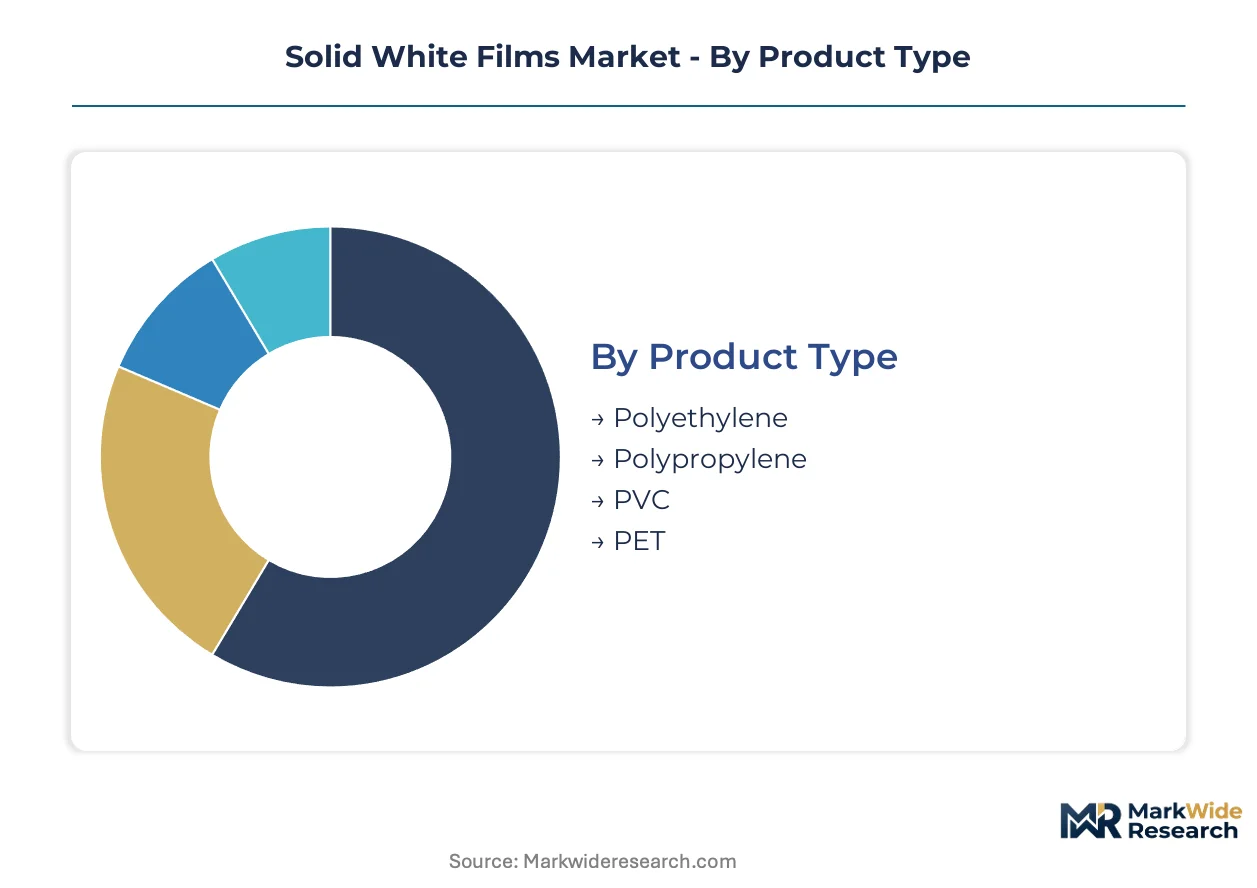
Segmentation in solid white films reveals how resin chemistry, end-use performance requirements, and regulatory compliance intersect to determine channel access and margin capture. Distinct procurement patterns separate commodity converters serving food packaging from specialized suppliers qualified for pharmaceutical and medical applications.
Product Type:
Polyethylene grades flow predominantly through high-volume food packaging channels, while PET and specialty resins route through certified pharmaceutical supply chains with intensive documentation requirements.
- Polyethylene:Low-density and linear low-density formulations carry 8-15% titanium dioxide loading for uniform opacity in pouch and lidding applications. German food brands in the Rhine-Ruhr cluster specify these grades for private-label dairy and ready-meal packaging under VerpackG detectability mandates.
- PET:Biaxially oriented polyethylene terephthalate delivers dimensional stability and barrier precision for pharmaceutical blister packs. Swiss and Irish contract manufacturers prioritize laser-markable white PET variants to satisfy EU MDR serialization requirements for unique device identification.
- Polypropylene:Retort and microwaveable packaging applications exploit thermal resistance alongside moderate opacity.
- PVC:Medical device packaging and specialized construction membranes where chemical resistance outweighs recyclability concerns.
By volume, Polyethylene leads. By growth pace, PET is ahead.
Application:
Cost tiers separate high-compliance medical and pharmaceutical segments from price-sensitive agricultural and construction end-uses with minimal regulatory burden.
- Packaging:Food-contact pouch, lidding, and tray applications dominate procurement volumes. French supermarket chains are deploying Digimarc-enabled white films for AI-powered sorting, with early installations achieving 95% detection accuracy in waste streams.
- Medical:Sterile barrier systems and device packaging demand ISO 13485-certified manufacturing with validated sterilization compatibility. Migration testing backlogs at Southern European laboratories create six-month qualification delays for new film grades.
- Agriculture:Mulch films and greenhouse coverings face REACH sunset pressure on oxo-degradable additives, compelling Italian compounders toward OK Compost INDUSTRIAL-certified bio-based alternatives.
- Construction:Vapor barriers and protective membranes prioritize cost efficiency over optical properties.
Packaging commands the largest revenue pool. Medical applications are expanding most quickly.
End User:
Customer type determines specification intensity, with pharmaceutical and food industry buyers imposing divergent compliance frameworks on their film suppliers.
- Food Industry:Extended producer responsibility schemes in Germany and France are reshaping procurement criteria toward detectable mono-material designs. Carrefour and Ahold Delhaize's centralized buying desks now unbundle technical specifications from logistics terms, concentrating resin decisions at headquarters level.
- Pharmaceutical:Blister pack and cold-form foil applications require FDA food-contact substance notifications and REACH compliance documentation. EU MDR's unique device identification mandates are accelerating adoption of laser-markable white PET films.
- Retail:Private-label packaging teams specify opacity and seal-strength thresholds without direct resin selection authority.
- Automotive:Interior trim protection and component packaging with moderate performance requirements.
Food Industry generates the highest absolute demand. Pharmaceutical end-use is climbing the fastest.
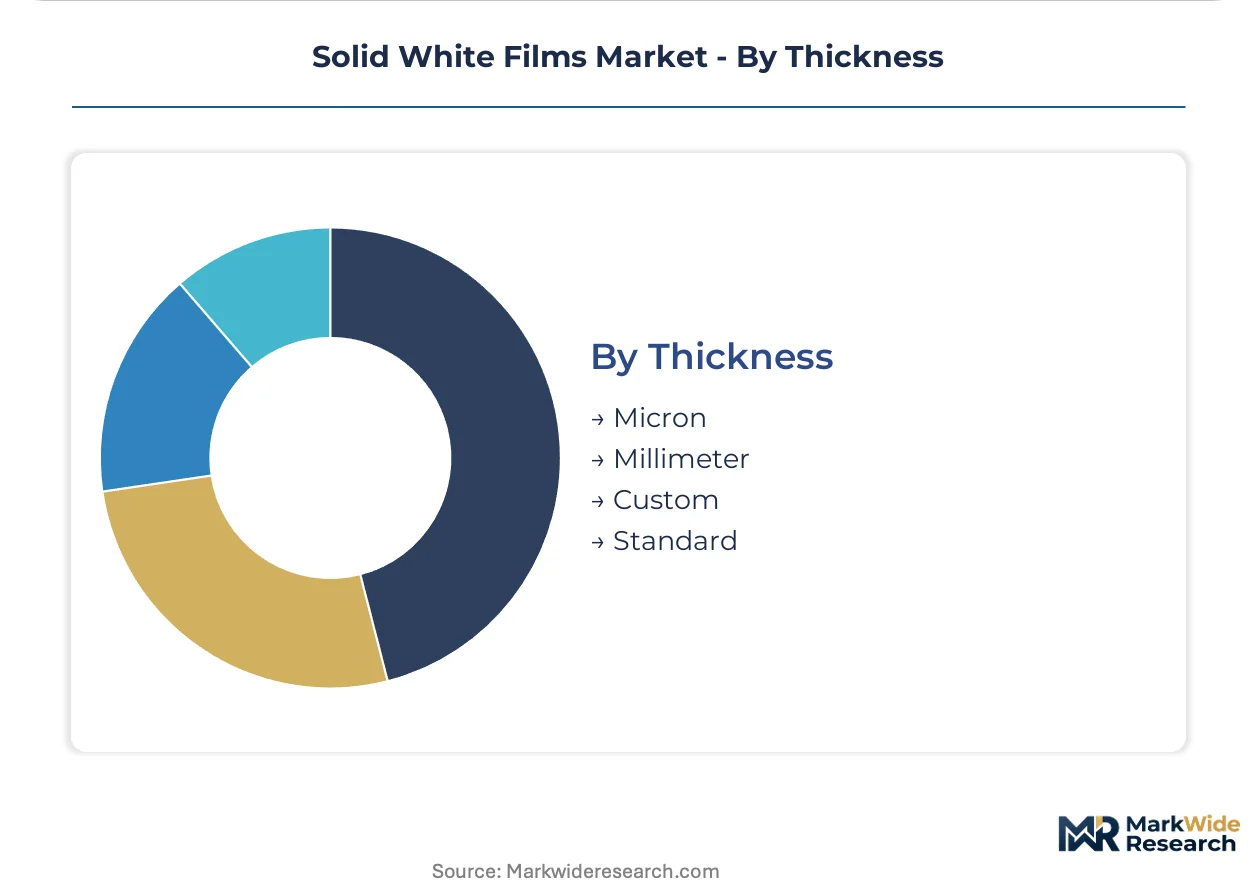
Thickness:
Volume concentration sits with standard gauges serving commodity food packaging, while custom thicknesses capture premium positioning in specialized medical and industrial applications.
- Standard:Established gauge tolerances for high-volume pouch and lidding production. Blown film extrusion advances enabling 15% TiO2 loading without melt fracture are expanding opacity performance in these specifications.
- Custom:Tailored caliper for pharmaceutical serialization layers and multi-ply barrier constructions. Extrusion line reconfiguration costs of €800,000-1.2 million per line restrict mid-size Spanish and Polish converters from entering this tier.
- Micron:Precision thin-gauge films for weight-reduction initiatives in flexible packaging.
- Millimeter:Heavy-duty construction and agricultural membranes requiring mechanical durability.
Standard thickness dominates shipment volumes. Custom specifications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany's Rhine-Ruhr corridor exceeds that of India's Mumbai-Ahmedabad belt by 40-60 basis points on equivalent specifications, reflecting divergent regulatory compliance burdens and feedstock access.
United States
Food packaging manufacturers are expanding orders for high-opacity barrier films to serve private-label dairy and ready-meal segments. FDA food-contact substance notification requirements elevate testing burdens for cross-border suppliers. The Midwest industrial corridor around Chicago concentrates blown film extrusion capacity serving national distribution networks.
Germany
VerpackG extended producer responsibility schemes accelerate demand for detectable white films in sorting streams. The EU's Packaging and Packaging Waste Regulation tightens recyclability mandates for plastic substrates. The flexible packaging hub around Düsseldorf and the surrounding Rhine-Ruhr industrial cluster concentrates specification authority for pan-European retail alliances.
India
FSSAI's tightening food-contact notification requirements displace unorganized film suppliers in Mumbai and Ahmedabad. Organized converters with BIS certification capture volume in snack and dairy packaging. The western Gujarat corridor anchors domestic compounder activity serving regional brand owners.
France
Citeo eco-modulation penalizes non-recyclable packaging formats, redirecting procurement toward mono-material designs. Digimarc and AIM standards integration with white film substrates enables AI-powered sorting in supermarket waste streams. The northern Hauts-de-France region hosts early deployment sites achieving detection rate benchmarks.
China
Over 60% of chloride-route TiO2 capacity sits with domestic producers subject to export license variability. European compounders face working capital pressure from six-month procurement cycles tied to Chinese feedstock. The Yangtze River Delta concentrates downstream film conversion for regional food and pharmaceutical packaging.
Solid White Films Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics. Integrated resin producers with captive polymer sourcing sustain margin stability against feedstock volatility, while downstream converters compete on extrusion efficiency and specification compliance. Three archetypes dominate: multinational packaging conglomerates with continental-scale assets, regional specialists with certified pharmaceutical qualifications, and commodity converters serving price-sensitive agricultural and construction segments. Capacity expansion and strategic partnerships represent the dominant competitive moves, with pyrolysis alliances emerging as a circularity differentiator.
Among Asia-Pacific-based specialists, Cosmo Films and Polyplex Corporation exemplify the certified-converter archetype, while Jindal Poly Films Ltd anchors the scale-driven commodity tier. Toray Industries occupies a position within the technology-differentiated segment through biaxially oriented film leadership. These three names illustrate how geographic origin and corporate structure correlate with strategic positioning across the value chain.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Amcor plc |
| Berry Global Group, Inc. |
| Cosmo Films |
| Toray Industries |
| Polyplex Corporation |
| Jindal Poly Films Ltd |
| Taghleef Industries |
| Flex Films |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between German food brands and Rhine-Ruhr compounders lock in TiO2 supply visibility while insulating converters from chloride-route pigment volatility. These arrangements bind pricing to resin indices with quarterly adjustments, embedding working capital efficiency into procurement structures.
Pricing Analysis
The customization-premium spread separates laser-markable white PET for pharmaceutical serialization from commodity polyethylene grades for dairy lidding. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity, with ISO 13485-qualified medical films commanding substantial uplifts over BRC-baseline food-contact grades. Cost compression in standard polyethylene tiers is intensifying because calcium carbonate masterbatch substitution erodes legacy TiO2 pigment premiums. Food brands and private-label retailers exhibit highest price sensitivity, while pharmaceutical contract manufacturers prioritize specification compliance over unit economics.
Supply Chain Analysis
Container availability on Asia-Europe trade lanes directly constrains TiO2 feedstock delivery schedules for European compounders, amplifying inventory carrying costs. Supply concentrates in China for chloride-route pigment, Germany for biaxially oriented film extrusion, and India for emerging flexible packaging conversion. Raw material dependencies span titanium dioxide from Chinese producers, polyethylene resin from Middle Eastern crackers, and calcium carbonate from Turkish quarries. Single-source vulnerability around Chinese TiO2 export licensing creates procurement risk. Distribution runs through pan-European retail alliance buying desks that unbundle technical specifications from logistics terms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. Certification backlogs and reformulation costs create switching barriers that protect qualified incumbents from price-only competition.
For Market Incumbents: Consolidate pyrolysis partnerships with Rotterdam and Antwerp petrochemical majors to secure circularity claims for premium food brands. Deepen backward integration into captive polymer sourcing to defend margin stability against resin volatility. Paperboard substitution in Scandinavian frozen food segments and calcium carbonate masterbatch displacement of TiO2 represent dual margin pressure points requiring proactive formulation investment. For New Entrants and Emerging Players: Anchor in India's western Gujarat corridor where FSSAI notification requirements displace unorganized Mumbai and Ahmedabad suppliers. Target BIS-certified organized converter status to capture snack and dairy packaging volume from displaced informal competitors. Lead with digital watermarking integration as a go-to-market differentiator for AI-powered sorting compliance in French and German retail chains. For Investors and Strategic Acquirers: Certified pharmaceutical converters with EU MDR-qualified laser-markable PET capabilities present the most defensible acquisition profile. Long-term viability hinges on extended producer responsibility scheme maturation across European markets. Watch for REACH microplastic restriction enforcement timelines as an inflection indicator for bio-based filler adoption rates and oxo-degradable additive obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-material Design Transition | VerpackG and Citeo eco-modulation compliance unlocks access to German and French retail procurement. |
| Pyrolysis Partnership Formation | Rotterdam and Antwerp chemical recycling integration enables circularity claims for premium food brand customers. |
| Digital Watermarking Deployment | Digimarc and AIM standards integration achieves 95% detection rates in French supermarket waste streams. |
| Calcium Carbonate Masterbatch Adoption | Surface-treated nano-particle formulations deliver 20-30% raw material savings in Middle Eastern dairy markets. |
| Laser-Markable PET Qualification | EU MDR serialization requirements for blister packs create premium positioning in Irish and Swiss contract manufacturing. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the solid white films value chain. Primary interviews captured perspectives from blown film extrusion plant managers, procurement leads at pan-European retail alliances, technical R&D directors at masterbatch compounders, and quality assurance heads at pharmaceutical contract manufacturers. Secondary validation drew from EU Packaging and Packaging Waste Regulation filings, ECHA REACH restriction roadmaps, FSSAI food-contact notifications, and customs trade data for TiO2 and polyethylene resin flows. Bottom-up volume estimates triangulated against top-down market sizing from resin consumption patterns.
Across the analysis window, the forecasting framework modeled demand trajectories by resin chemistry, end-use application, regulatory compliance tier, and regional production cluster. CAGRs were derived from segment-level volume elasticities tied to packaging output growth and substitution dynamics. Industry-specific inputs included VerpackG detectability mandate implementation schedules, FSSAI certification displacement rates in Indian organized conversion, and EU MDR serialization rollout pacing for pharmaceutical films.
Material uncertainties — TiO2 export license variability from Chinese producers, REACH microplastic restriction enforcement timing, and paperboard substitution acceleration in Nordic retail — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory compliance cost trajectories and resin price correlation stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Africa 3D Printing Construction Market
Others
Smart-Connected Power Plug Socket Market
Others
Europe Postal Services Market
Others
Football Sportswear Market
Others
North America Machine Vision Systems Market
Others
Underwater Light Market
Others
Dried Egg Market
Others
Gym Wipes Market
Others
Pollen Allergy Market
Others
Japan Smart Home Market
Others
Workstation Desktops Market
Others
Augmented Reality (AR) in Warehousing and Logistics Market
Others
Allogeneic T Cell Therapies Market
Others
Hypermarket Market
Others
UK Cat Food Market
Others
Germany Smart Home Market