
 China Smart Home Market | 2026-2036
China Smart Home Market Size, Share, and Industry Trends Forecast 2026-2036
China Smart Home Market Insights
Premium whole-home integration is rotating toward AI-powered predictive automation as the baseline expectation for new construction. Xiaomi Inc leverages its IoT ecosystem density to dominate mass-market connectivity. Huawei anchors high-end deployments through its proprietary HarmonyOS distributed architecture. Haier sustains appliance-centric smart home positioning with integrated kitchen and climate systems.
Smart home technology encompasses residential automation systems that interconnect lighting, climate, security, and appliances through centralized control platforms, typically operating via Wi-Fi, Zigbee, or Bluetooth protocols with voice and mobile app interfaces. Smart Security Systems leads product type revenue due to government-backed safe-city initiatives spilling into residential monitoring demand. Zigbee connectivity segments capture margin pools through mesh-network reliability in multi-device installations. DIY installation types expand fastest among urban renters seeking non-permanent automation solutions.
MIIT enforces IoT device cybersecurity review requirements under GB standards, while SAMR administers product quality certification that shapes market access timelines. NMPA oversight extends to health-monitoring smart home devices, creating additional compliance layers for biometric-integrated products. Stakeholders must monitor regulatory convergence between data privacy mandates and interoperability standards as the decisive factor for ecosystem viability.
Market Dynamics
Pre-installed smart home packages in tier-one residential developments are forcing suppliers to pivot from retrofit hardware sales to B2B system integration contracts with property developers.
Growth Catalysts
- MIIT Cybersecurity Certification:Mandatory GB standards compliance for IoT devices creates a quality filter that rewards certified vendors with preferential developer partnerships.
- Safe-City Spillover:Government surveillance infrastructure investments normalize residential monitoring expectations, expanding smart security system penetration in high-end housing.
- Zigbee Mesh Reliability:Multi-device installations in luxury developments favor Zigbee connectivity protocols over Wi-Fi for whole-home stability.
Market Restraints
- Silicon Supply Concentration:Semiconductor fabrication bottlenecks in Taiwan and South Korea constrain chipset availability for domestic gateway manufacturers.
- GB Standards Friction:SAMR certification timelines extend product launch cycles by six to twelve months for biometric-integrated health devices.
- Installation Cost Structure:Specialized low-voltage wiring requirements for predictive automation systems inflate upfront deployment costs beyond mass-market tolerance.
Strategic Opportunities
- NMPA Health Device Pathway:Regulatory clarity for biometric-integrated products opens reimbursement-linked revenue streams for chronic disease monitoring applications.
- DIY Channel Expansion:Urban renters in Shenzhen and Hangzhou drive plug-and-play automation kit demand through e-commerce direct-to-consumer platforms.
- HarmonyOS Distributed Architecture:Proprietary ecosystem integration enables premium positioning through seamless cross-device orchestration in high-end developments.
Industry Challenges
- Interoperability Fragmentation:Competing proprietary protocols between ecosystem providers force developers to maintain multiple certification tracks.
- Legacy Property Retrofit Complexity:Post-2010 residential stock lacks conduit infrastructure for centralized automation, limiting addressable market expansion.
- Data Privacy Compliance Layering:Converging MIIT cybersecurity mandates and local data residency requirements multiply legal review burdens for cloud-connected services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Smart Home Market |
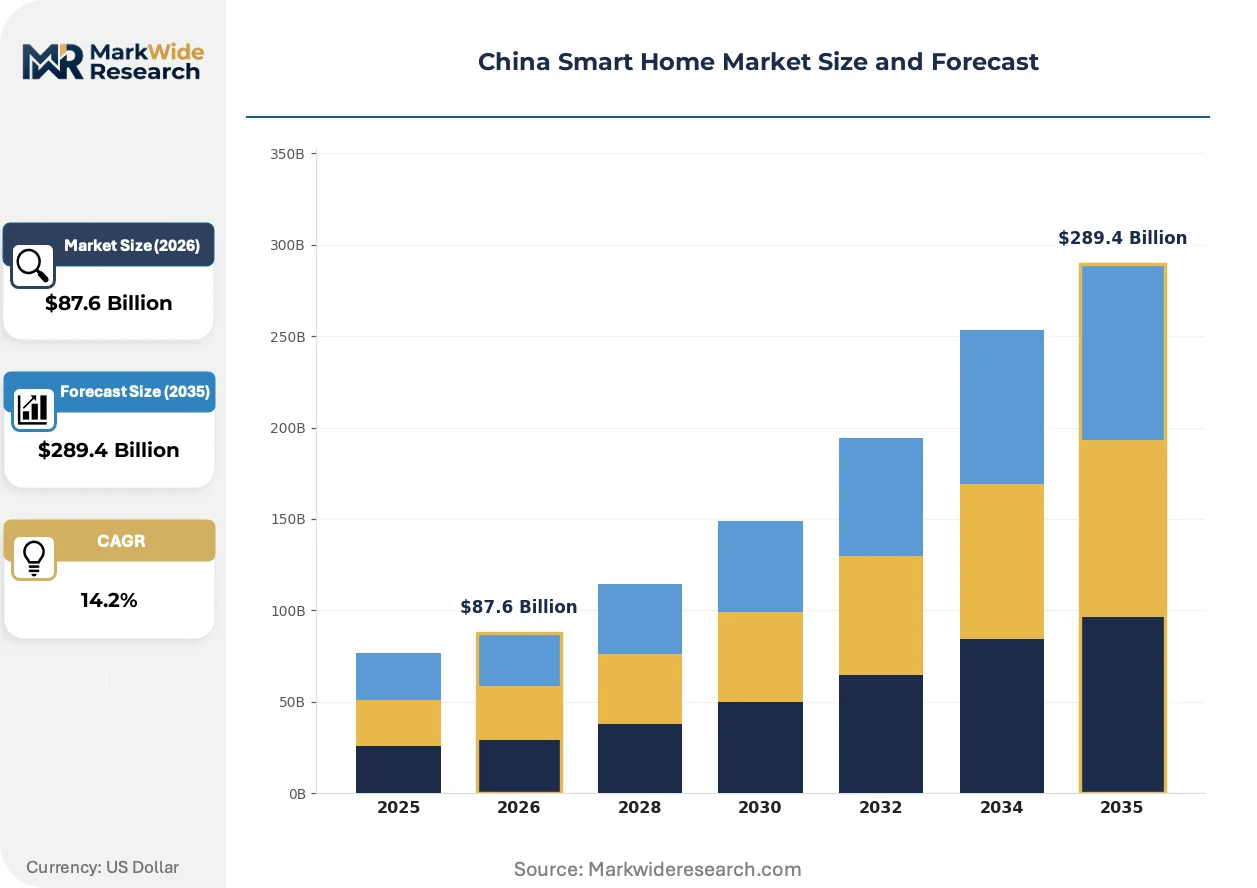
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $289.4 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lighting, Smart Security Systems, Smart Thermostats, Smart Appliances Connectivity: Wi-Fi, Zigbee, Z-Wave, Bluetooth End User: Homeowners, Renters, Property Managers, Developers Installation Type: DIY, Professional, Hybrid, Integrated |
| Companies Covered | Xiaomi Inc, Huawei, Haier, Alibaba Group, Midea, Hisense Co. Ltd, Tuya Smart, AQARA, JD.com, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Smart Home Market Trends and Innovations
Edge AI inference engines are displacing cloud-dependent processing for latency-sensitive automation, while regulatory pressure on data localization accelerates on-device architecture investments.
Millimeter-wave radar sensors for non-contact vital sign monitoring are miniaturizing from medical-grade equipment to consumer appliance integration. Residential developers in Beijing and Shanghai specify these for elderly care units in premium projects. Component cost curves are compressing deployment thresholds, enabling predictive health alerts without wearable device dependencies.
MIIT's mandatory IoT device cybersecurity review under GB standards is tightening firmware update obligations and vulnerability disclosure timelines. Manufacturers must maintain domestic security audit capabilities or forfeit certification eligibility. Smart security camera segments face the steepest compliance ramp, with Shenzhen-based vendors restructuring quality assurance teams to meet accelerated review cycles.
Property developer procurement is consolidating around turnkey system integrators capable of delivering certified pre-installed packages. Fragmented hardware vendors without B2B contracting expertise are losing direct access to new construction pipelines. Tier-one city developers in Guangzhou and Chengdu now specify single-point accountability clauses that exclude multi-vendor patchwork solutions.
China Smart Home Market Segmentation
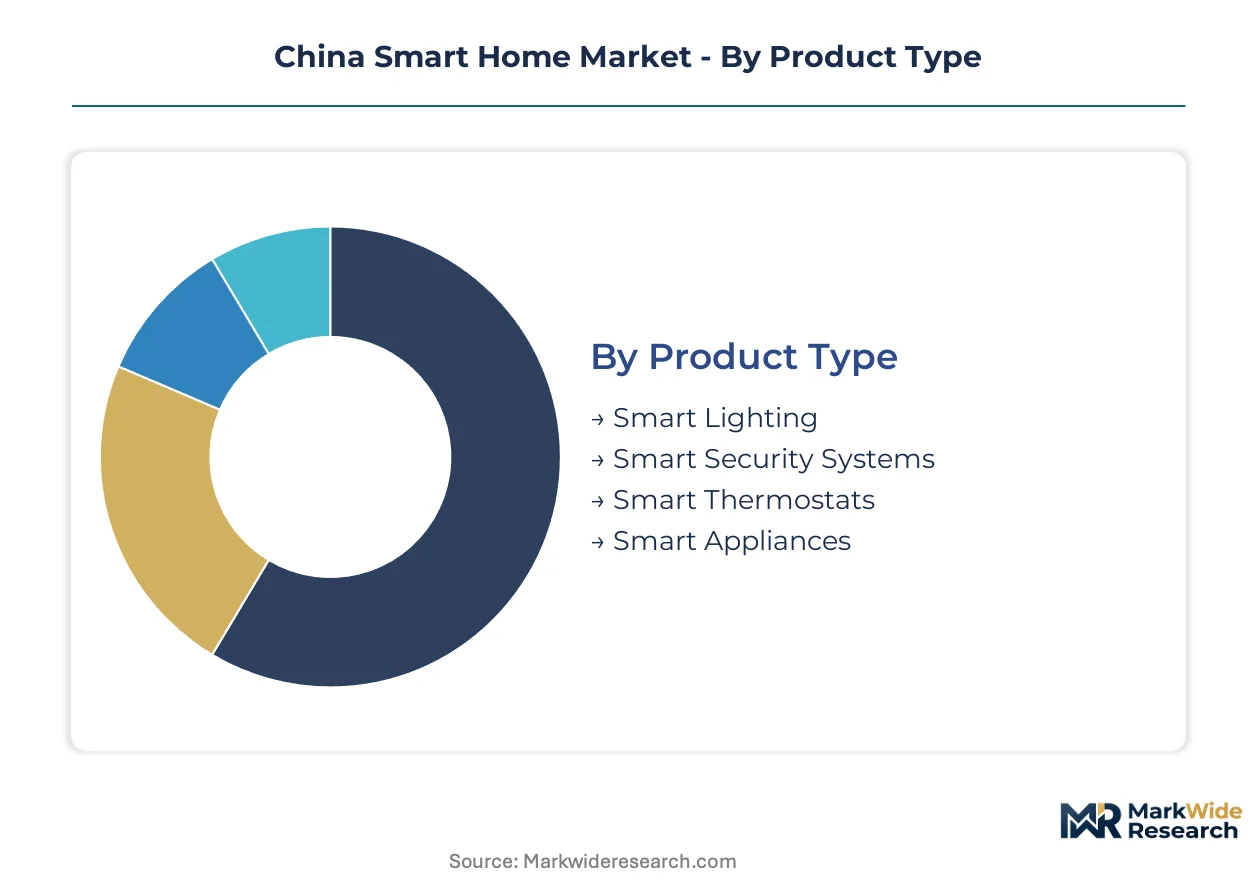
Smart home suppliers in China must navigate four distinct segmentation axes simultaneously. Property developer procurement consolidation and MIIT certification requirements reshape which segments capture margin pools.
Product Type:
Margin concentration follows government surveillance infrastructure spillover and pre-installation mandates in tier-one residential developments.
- Smart Security Systems:Video surveillance, access control, and intrusion detection systems with facial recognition integration. Demand concentrates in Beijing and Shanghai high-end residential towers driven by safe-city initiative normalization into private housing expectations.
- Smart Appliances:Connected refrigerators, washing machines, and climate systems with predictive maintenance algorithms. Haier and Midea anchor procurement in integrated kitchen specifications for Guangzhou and Shenzhen luxury developments.
- Smart Lighting:Tunable white and RGB systems with circadian rhythm programming. Xiaomi ecosystem density drives mass-market penetration through cost-optimized LED driver integration.
- Smart Thermostats:Multi-zone climate controllers with occupancy sensing and energy optimization. Northern China heating retrofit programs expand addressable base beyond new construction.
Smart Security Systems holds installed capacity. Smart Appliances is rotating up the share rankings.
Connectivity:
Protocol selection determines certification complexity and developer partnership eligibility under MIIT cybersecurity review.
- Zigbee:Mesh network protocol operating at 2.4 GHz with self-healing topology for 50+ device installations. Shenzhen and Chengdu luxury developments specify Zigbee for whole-home reliability where Wi-Fi congestion degrades performance.
- Wi-Fi:IP-based connectivity leveraging existing residential broadband infrastructure. Renters in Hangzhou and Nanjing favor Wi-Fi for plug-and-play deployment without gateway hardware investment.
- Bluetooth:Low-energy protocol for battery-powered sensors and localized control. Smart locks and proximity-based lighting triggers dominate this segment's application profile.
- Z-Wave:Sub-GHz mesh protocol with regional frequency variants. Limited China adoption due to spectrum allocation conflicts with domestic IoT standards.
Zigbee captures developer specification share. Wi-Fi is climbing the fastest in rental channel penetration.
End User:
Procurement authority shifts from individual consumers to institutional buyers as pre-installed packages displace retrofit sales.
- Developers:Tier-one city property firms specifying turnkey smart home systems with single-point accountability clauses. Vanke and Country Garden consolidate vendor lists to three certified system integrators per region.
- Property Managers:Commercial and residential building operators deploying centralized monitoring for multi-unit portfolios. Energy optimization and predictive maintenance drive operational cost reduction mandates.
- Homeowners:Individual purchasers of retrofit systems for existing residential stock. Post-2010 property infrastructure limitations constrain addressable base to lighting and plug-in appliance categories.
- Renters:Urban mobile professionals seeking non-permanent automation through portable devices. Shenzhen and Hangzhou e-commerce platforms direct-to-consumer sales expand this segment fastest.
Developers command specification authority. Renters are gaining share fastest through DIY channel expansion.
Installation Type:
Cost structure and certification liability separate professional integration from consumer self-deployment.
- Integrated:Hardwired systems installed during construction with centralized control panels and dedicated low-voltage infrastructure. Beijing and Shanghai premium projects specify integrated packages as standard amenity.
- Professional:Post-construction installation by certified technicians with SAMR compliance documentation. Biometric-integrated health devices require this pathway for NMPA regulatory clearance.
- DIY:Consumer-installed plug-and-play devices with minimal configuration. Urban renters in tier-one cities drive fastest expansion through Tmall and JD.com direct sales.
- Hybrid:Professional gateway installation with consumer-managed device addition. Balances reliability requirements with flexibility preferences in mid-market housing.
Integrated holds new construction pipeline access. DIY is rotating up the share rankings through rental market expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gateway and chipset supply concentrates in Taiwan and South Korea fabrication clusters, constraining tier-one city deployment timelines. Developer procurement consolidation across Beijing, Shanghai, and Shenzhen is reshaping vendor access patterns.
Yangtze River Delta
Shanghai and Hangzhou luxury residential towers specify pre-installed Zigbee mesh systems with MIIT cybersecurity certification. SAMR compliance documentation requirements extend vendor qualification cycles. Suzhou industrial parks host gateway manufacturers scaling domestic chipset substitution programs.
Pearl River Delta
Shenzhen property developers mandate single-point accountability clauses for turnkey smart home packages. GB standards firmware update obligations tighten vulnerability disclosure timelines for security camera vendors. Dongguan electronics clusters supply Zigbee module components to certified system integrators.
Beijing-Tianjin-Hebei
Safe-city infrastructure spillover normalizes facial recognition integration in high-end residential access control. MIIT IoT device cybersecurity review shapes developer procurement specifications. Tianjin port logistics handle semiconductor imports for domestic gateway assembly.
Sichuan-Chongqing
Chengdu developer specifications favor Wi-Fi-based plug-and-play systems for mid-market housing. Local data residency requirements multiply legal review burdens for cloud-connected services. Chongqing manufacturing bases produce cost-optimized LED drivers for Xiaomi ecosystem integration.
Shandong Peninsula
Qingdao appliance manufacturers anchor integrated kitchen specifications for northern China heating retrofit programs. NMPA regulatory clarity for biometric-integrated health devices opens reimbursement-linked revenue streams. Jinan industrial zones supply climate control components for multi-zone thermostat installations.
China Smart Home Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated market structure. Ecosystem providers with proprietary operating systems anchor high-end developer specifications, while mass-market connectivity vendors leverage hardware volume density. Three archetypes dominate: ecosystem orchestrators with distributed architecture, appliance-centric integrators with climate and kitchen systems, and platform-agnostic device aggregators. Competitive moves concentrate on B2B system integration contracts with tier-one property developers and MIIT certification pre-qualification programs.
Within the ecosystem orchestrator tier, Huawei occupies a position exemplifying proprietary distributed architecture deployment, while Xiaomi Inc represents mass-market IoT density through cost-optimized hardware integration. Among appliance-centric integrators, Haier anchors integrated kitchen and climate system specifications for premium developer procurement.
| Leading Market Players |
|---|
| Xiaomi Inc |
| Huawei |
| Haier |
| Alibaba Group |
| Midea |
| Hisense Co. Ltd |
| Tuya Smart |
| AQARA |
| JD.com |
| Others |
Pricing and Supply Chain Analysis
Forty-five to sixty-day chipset lead times from Taiwan and South Korea fabrication clusters compress margin buffers for domestic gateway manufacturers while amplifying pricing power among certified system integrators with secured allocation agreements. MIIT cybersecurity certification requirements add six-to-twelve-month qualification overhead that stratifies vendor tiers by compliance velocity.
Pricing Analysis
GB standards compliance dictates the pricing tier structure across the China smart home landscape. Three-tier pricing structure across premium HarmonyOS-integrated, standard Zigbee-certified, and economy Wi-Fi-only levels separates developer-specified packages from retail retrofit kits. Price differentiation hinges on MIIT certification grade and after-sales firmware update bundling. Cost compression in mass-market connectivity hardware intensifies because Xiaomi ecosystem density forces component cost transparency. Urban renters in Shenzhen exhibit highest price sensitivity, while Beijing luxury developers demonstrate lowest sensitivity due to amenity premium recovery through property valuations.
Supply Chain Analysis
Strategic stockpile preferences dominate among tier-one property developers facing semiconductor allocation constraints, contrasting with just-in-time inventory practices among mass-market device aggregators. Gateway manufacturing draws from Taiwan and South Korea for advanced node chipsets, Dongguan electronics clusters for Zigbee modules, and Suzhou industrial parks for domestic substitution programs. Raw material dependencies span silicon wafers, rare-earth magnets for sensor motors, and lithium-ion cells for battery-powered devices. Single-source vulnerability concentrates in Taiwan semiconductor fabrication. Distribution runs through certified system integrators with direct developer procurement contracts, supplemented by Tmall and JD.com direct-to-consumer channels for DIY segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has concentrated around tier-one property developers consolidating vendor lists to three certified system integrators per region, fragmenting hardware-only suppliers from new construction pipelines.
For Market Incumbents: Secure MIIT cybersecurity certification pre-qualification status before developer procurement cycles commence. Anchor B2B system integration capabilities through turnkey package delivery with single-point accountability clauses. Vertical integration into domestic chipset substitution programs mitigates Taiwan fabrication bottleneck exposure. Certification investment in NMPA health device pathways opens reimbursement-linked revenue streams against emerging biometric-integrated entrants. For New Entrants and Emerging Players: Differentiate on DIY channel specialization targeting urban renters in Hangzhou and Shenzhen with plug-and-play automation kits. The rental segment represents the most penetrable white-space as permanent installation barriers exclude incumbent integrated-system providers. E-commerce direct-to-consumer platforms offer the lowest friction go-to-market angle against developer-centric incumbents. Zigbee mesh compatibility without gateway hardware investment addresses renter portability requirements. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because MIIT certification requirements and GB standards compliance create durable barriers against unqualified hardware vendors. Acquisition targets should demonstrate certified system integrator status with active tier-one developer contracts. The signal to watch as inflection indicator is NMPA regulatory clarity expansion for biometric-integrated health devices enabling reimbursement-linked revenue models.| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Cybersecurity Certification Investment | GB standards compliance unlocks preferential developer partnership access in tier-one cities. |
| B2B System Integration Capability Buildout | Turnkey package delivery meets single-point accountability clauses specified by Vanke and Country Garden. |
| Domestic Chipset Substitution Program | Suzhou industrial park partnerships reduce Taiwan fabrication dependency for gateway manufacturers. |
| NMPA Health Device Pathway Development | Regulatory clarity enables reimbursement-linked revenue for chronic disease monitoring applications. |
| DIY Channel E-commerce Expansion | Tmall and JD.com direct sales capture urban renter demand in Shenzhen and Hangzhou. |
Research Methodology
Desk research of MIIT regulatory filings, SAMR certification databases, and property developer procurement specifications preceded structured interviews with smart home system integrators, tier-one developer procurement directors, and Zigbee module manufacturers. Secondary validation incorporated GB standards documentation, NMPA device registration records, and semiconductor trade flow data. Bottom-up demand modeling across connectivity protocols and installation types triangulated against top-down market sizing from construction pipeline data.
Variance decomposition across product type, connectivity protocol, end-user category, and installation method shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include smart security systems versus appliance-centric packages, Zigbee mesh versus Wi-Fi infrastructure, developer-led versus homeowner procurement, and integrated hardwired versus DIY plug-and-play deployment. CAGRs derived from installed base growth rates and replacement cycle assumptions, with edge AI inference engine adoption curves and millimeter-wave radar sensor cost compression curves as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained tier-one residential construction velocity or MIIT certification timeline stability would require recalibration. Forecasts reflect documented assumptions regarding safe-city infrastructure spillover persistence and semiconductor supply normalization. Revision becomes warranted when Taiwan fabrication capacity utilization crosses thresholds that trigger allocation rationing beyond current strategic stockpile mitigation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Military Apparel Market
Others
Stichtite Market
Others
Cloud Advertising Market
Others
North America Micro Market
Others
Hot Air System Market
Others
Channel-In-A-Box (Ciab) Market
Others
Space Power Supply Market
Others
Digital Mortgage Software Market
Others
Smart Home Market
Others
Mexico Retail Market
Others
Global B2B Enterprise and Industrial Wearables Market
Others
Belt Loader Market
Others
China 3D Printing Construction Market
Others
Insoluble Sulfur Market
Others
Vegan Confectionery Market
Others
Global OTA Testing Market