
 Remanufacturing-as-a-Service (RaaS) Market | 2026-2036
Remanufacturing-as-a-Service (RaaS) Market Size, Share, and Industry Trends Forecast 2026-2036
Remanufacturing-as-a-Service (RaaS) Market Insights
The shift from captive in-house remanufacturing to outsourced multi-vendor programs is decoupling asset ownership from lifecycle responsibility across industrial sectors. Robert Bosch leverages its global service network to anchor component refurbishment contracts with automotive and industrial clients. ABB competes through technology leadership in predictive diagnostics that extend equipment operating life. Caterpillar dominates heavy machinery overhaul through captive dealer networks that control aftermarket access.
Remanufacturing-as-a-Service delivers industrial asset restoration through disassembly, inspection, replacement of worn elements, and performance verification to original or upgraded specifications. Cloud-based platform deployments enable real-time condition monitoring and automated scheduling of reconditioning cycles, reducing unplanned downtime for capital-intensive equipment. Component refurbishment leads service type revenue due to recurring demand from rotating machinery and electronic control systems. Module reconditioning represents the fastest-growing segment as aerospace suppliers adopt serialized tracking for flight-critical assemblies.
The EPA governs hazardous waste handling in US remanufacturing facilities, while the EU Green Deal mandates recycled content thresholds for newly placed industrial equipment. REACH compliance in Europe restricts certain substances in refurbished electronics, shaping material selection and supplier qualification processes. Stakeholders must monitor how emerging extended producer responsibility frameworks alter cost allocation between OEMs and third-party service providers.
Market Dynamics
The EU Green Deal is forcing heavy machinery OEMs to decouple asset ownership from lifecycle responsibility, accelerating outsourced module reconditioning programs across industrial clusters in Germany, France, and Italy.
Growth Catalysts
- Circular Economy Mandates:The EU Green Deal mandates recycled content thresholds for newly placed industrial equipment, compelling manufacturers to source refurbished components rather than virgin materials.
- Automotive Cluster Concentration:Germany's dense automotive and machinery ecosystems generate high-volume refurbishment demand for rotating equipment and electronic control systems.
- Cloud-Based Condition Monitoring:Real-time asset tracking platforms enable predictive scheduling of reconditioning cycles, reducing unplanned downtime for capital-intensive production lines.
Market Restraints
- REACH Compliance Burden:ECHA restrictions on substances in refurbished electronics force costly material requalification and supplier audits across European remanufacturing networks.
- Core Supply Volatility:Availability of used equipment cores fluctuates with original sales cycles, creating input uncertainty for reconditioning service providers.
- Technical Limitation in Aerospace:Flight-critical assemblies require serialized traceability that exceeds current refurbishment tracking capabilities for non-OEM service providers.
Strategic Opportunities
- Extended Producer Responsibility Expansion:Emerging EPR frameworks in France and Italy will reallocate end-of-life costs toward OEMs, creating third-party service entry points.
- Aerospace Module Tracking:Serialized lifecycle documentation for flight-critical components opens high-margin reconditioning contracts with tier-one suppliers.
- Dealer Network Disintermediation:Independent platforms are aggregating multi-vendor refurbishment demand outside captive Caterpillar and Bosch service networks.
Industry Challenges
- Metrology and Diagnostics Talent Gap:Precision inspection of worn rotating machinery requires scarce technicians trained in non-destructive testing protocols.
- Performance Verification Certification:Demonstrating restored equipment meets original specifications demands lengthy validation cycles with notified bodies under EU machinery directives.
- Legacy System Integration:Cloud-based scheduling platforms must interface with decades-old SCADA infrastructure prevalent in German and Italian manufacturing plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remanufacturing-as-a-Service (RaaS) Market |
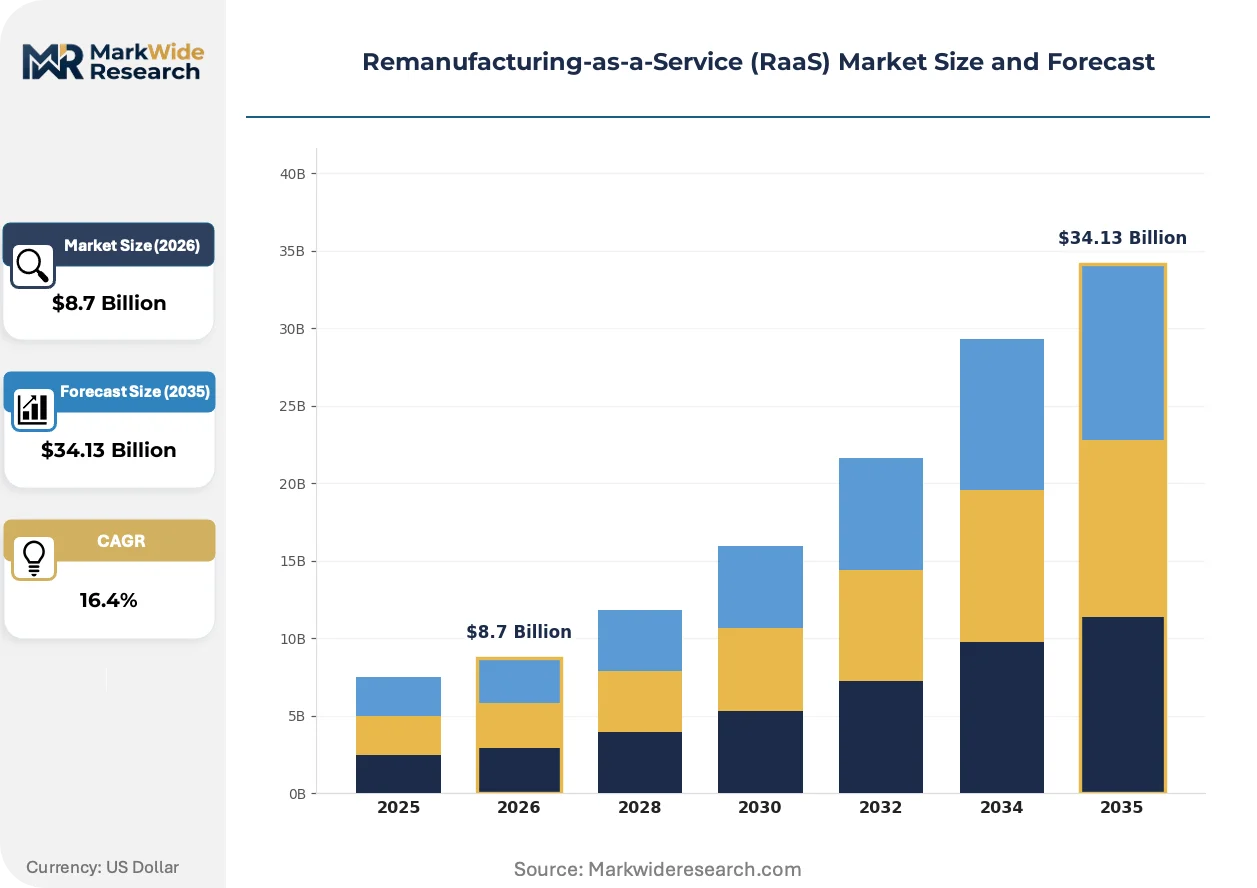
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Component Refurbishment, Engine Overhaul, Module Reconditioning, Equipment Upgrading Deployment Model: Cloud-Based Platform, On-Premises Solution, Hybrid Deployment, Edge Computing End User Industry: Heavy Machinery OEMs, Aerospace Suppliers, Consumer Electronics Manufacturers, Medical Device Providers Pricing Model: Subscription-Based, Pay-Per-Use, Outcome-Based, Tiered Pricing |
| Companies Covered | Robert Bosch, ABB, FANUC, KUKA, Yaskawa Electric, Caterpillar, Siemens, Ricoh, Renault Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remanufacturing-as-a-Service (RaaS) Market Trends and Innovations
Digital thread technologies are compressing refurbishment cycle times while regulatory pressure on embodied carbon intensifies material provenance requirements across European industrial supply chains.
Industrial internet-of-things sensor networks is consolidating equipment health data into unified platforms that predict component degradation before functional failure. Automotive suppliers in Stuttgart and Munich are deploying these systems at scale. The technology is consolidating previously fragmented maintenance decisions into centralized procurement of reconditioning services.
REACH substance restrictions are tightening material selection for refurbished electronics, forcing remanufacturers to maintain dual supply chains for compliant and non-compliant components. Industrial control system refurbishers face particular exposure. German electronics remanufacturers are responding by pre-qualifying alternative substrate materials and coatings.
Buyers are unbundling after-sales service contracts from original equipment purchases, negotiating standalone reconditioning agreements with third-party specialists. This pattern disrupts captive dealer networks that historically controlled aftermarket access. The shift is most pronounced among mid-sized machinery operators in northern Italy seeking cost transparency.
Remanufacturing-as-a-Service (RaaS) Market Segmentation
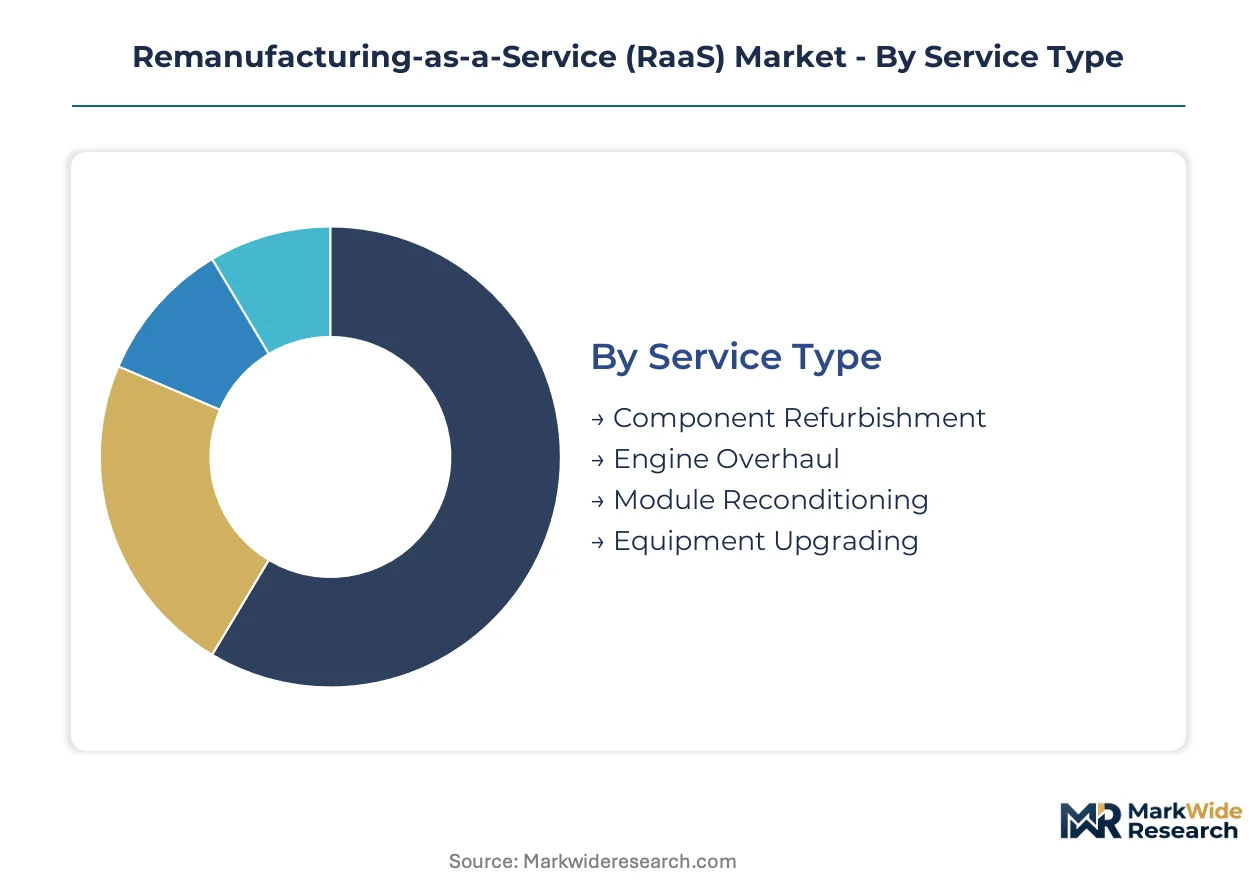
Segmentation in RaaS reveals how service delivery, technology infrastructure, and commercial terms intersect with asset lifecycle economics. Each dimension shapes procurement patterns and margin structures differently across industrial verticals.
Service Type:
Upgrade and replacement cycles vary dramatically by service depth, with deeper interventions commanding longer sales cycles but higher contract values.
- Component Refurbishment:Disassembly, inspection, and restoration of individual parts like bearings, gears, and circuit boards to original specifications. Demand concentrates in German automotive clusters where rotating machinery from Stuttgart and Munich plants requires recurring refurbishment of high-wear elements.
- Module Reconditioning:System-level restoration of integrated assemblies such as hydraulic power units or avionics modules with serialized traceability. Aerospace suppliers in Toulouse and Hamburg are adopting this for flight-critical systems where documentation requirements exceed component-level service capabilities.
- Engine Overhaul:Complete teardown and rebuild of prime movers to factory performance standards. Industrial operators in northern Italy favor this for captive power generation assets.
- Equipment Upgrading:Restoration combined with specification enhancement through embedded sensor integration or control system modernization. French machinery OEMs bundle this with EU Green Deal compliance retrofits.
Component refurbishment sits at the top of the volume ranking, with module reconditioning climbing the fastest.
Deployment Model:
Technology architecture selection tracks directly to facility age and IT maturity, with older plants requiring bridge solutions.
- Cloud-Based Platform:Centralized data aggregation with remote analytics and automated reconditioning scheduling. Heavy machinery OEMs in Germany deploy these at scale across distributed dealer networks.
- Hybrid Deployment:Split processing between local edge analytics and cloud-based long-term trend analysis. Italian mid-sized manufacturers prefer this for SCADA integration without full infrastructure replacement.
- On-Premises Solution:Fully localized data storage and processing for facilities with restricted external connectivity. Defense contractors and certain medical device providers mandate this architecture.
- Edge Computing:Real-time condition monitoring with millisecond-latency response for safety-critical applications. Aerospace final assembly lines in Toulouse deploy these for predictive intervention on automated drilling systems.
Hybrid deployment captures the broadest addressable base, while edge computing gains share fastest in safety-regulated environments.
End User Industry:
Industry selection determines regulatory exposure, with medical and aerospace verticals imposing documentation burdens that reshape service provider economics.
- Heavy Machinery OEMs:Captive dealer networks and high-volume refurbishment of construction and mining equipment. Caterpillar's controlled aftermarket access in Germany and France limits third-party penetration.
- Aerospace Suppliers:Tier-one and tier-two manufacturers requiring serialized lifecycle documentation for flight-critical assemblies. Airbus supplier clusters in Hamburg and Toulouse drive demand for module-level traceability.
- Consumer Electronics Manufacturers:High-volume, low-margin refurbishment of smartphones and computing devices. ECHA REACH compliance restricts material selection for European operations.
- Medical Device Providers:FDA and EMA-regulated restoration of diagnostic and surgical equipment with validation requirements. German and Swiss clusters concentrate demand for imaging system refurbishment.
Heavy machinery OEMs anchor current revenue, though aerospace suppliers are expanding most quickly as tier-one contracts open to qualified service providers.
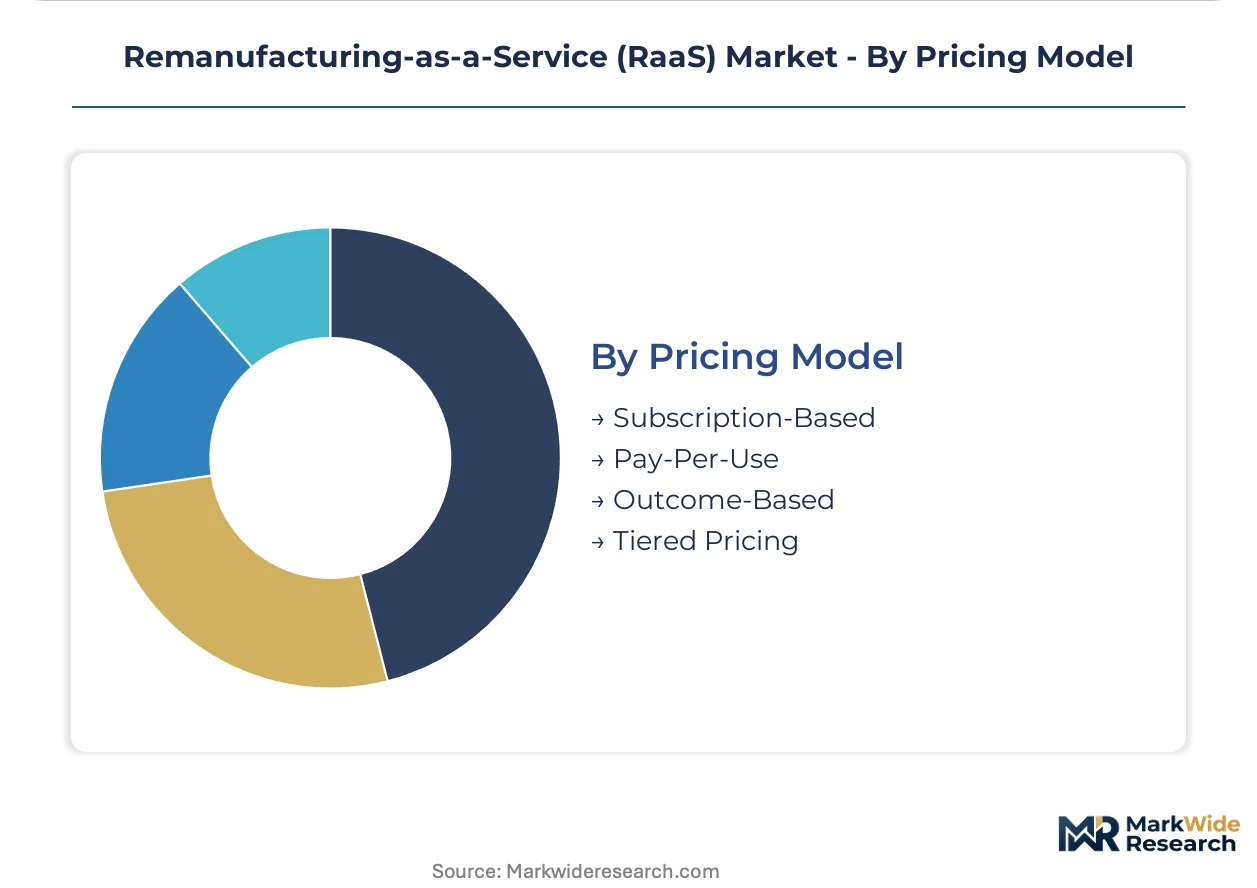
Pricing Model:
Commercial structure selection reflects asset criticality and customer sophistication, with outcome-based terms requiring deeper operational integration.
- Subscription-Based:Fixed periodic fees covering preventive maintenance and scheduled reconditioning. German automotive plants favor this for production line equipment with predictable wear patterns.
- Outcome-Based:Payment tied to uptime guarantees or performance metrics rather than service delivery. Italian machinery operators are piloting these for critical bottleneck equipment.
- Pay-Per-Use:Variable pricing scaled to equipment utilization hours or output volume. Construction equipment fleets in France adopt this for seasonal demand patterns.
- Tiered Pricing:Three-level structure separating premium certified refurbishment from standard and economy grades. Medical device providers in Switzerland use this to match pricing to clinical risk classification.
Subscription-based contracts dominate installed base penetration, while outcome-based structures are gaining traction fastest among risk-averse operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive and machinery clusters generate the highest refurbishment volumes, with Stuttgart and Munich plants driving recurring demand for rotating equipment restoration.
Germany
Automotive production lines in Stuttgart and Munich require continuous refurbishment of bearings, gears, and electronic control systems. The EU Green Deal mandates recycled content thresholds for newly placed industrial equipment, compelling manufacturers to source refurbished components. Baden-Württemberg's dense supplier ecosystem concentrates module reconditioning contracts with tier-one aerospace and machinery clients.
France
Aerospace suppliers in Toulouse and Hamburg drive demand for serialized lifecycle documentation of flight-critical assemblies. ANSM and EASA regulations impose strict traceability requirements on refurbished avionics modules. Île-de-France machinery OEMs bundle equipment upgrading services with EU Green Deal compliance retrofits for aging production assets.
United States
Heavy machinery operators across the Midwest and Southeast favor engine overhaul services for captive power generation and construction fleets. EPA hazardous waste handling rules govern facility operations, while state-level extended producer responsibility pilots emerge in California and New York. Caterpillar's dealer networks in Illinois and Texas control substantial aftermarket refurbishment volume.
Italy
Mid-sized machinery operators in northern Italy unbundle after-sales contracts to negotiate standalone reconditioning agreements with third-party specialists. ECHA REACH compliance restricts substance selection in refurbished electronics, forcing material requalification across Emilia-Romagna and Lombardy remanufacturing facilities. Piedmont's industrial automation cluster pilots outcome-based pricing for critical bottleneck equipment.
Japan
Precision electronics and robotics manufacturers in Kanto and Kansai regions demand high-grade component refurbishment for semiconductor production equipment. METI circular economy guidelines encourage resource efficiency in industrial supply chains. Nagoya's automotive supplier density creates concentrated demand for predictive maintenance platforms that schedule reconditioning cycles.
Remanufacturing-as-a-Service (RaaS) Market Competitive Landscape
Global majors compete with regional champions across technology integration and service network reach. The market structures around three tiers: diversified industrial conglomerates with captive service arms, specialized remanufacturing pure-plays, and emerging platform aggregators. Strategic archetypes include predictive diagnostics leaders, dealer network controllers, and cloud-based condition monitoring specialists. Dominant competitive moves center on M&A to acquire serialized tracking capabilities and strategic partnerships to bypass entrenched aftermarket access points.
Within the diversified industrial tier, Robert Bosch and ABB exemplify contrasting approaches to service delivery. Bosch leverages its global service network to anchor component refurbishment contracts across automotive and industrial verticals. ABB occupies a position emphasizing technology leadership in predictive diagnostics that extend equipment operating life. Caterpillar sits within the captive network archetype, controlling heavy machinery overhaul through dealer networks that limit third-party aftermarket penetration.
| Leading Market Players |
|---|
| Robert Bosch |
| ABB |
| FANUC |
| KUKA |
| Yaskawa Electric |
| Caterpillar |
| Siemens |
| Ricoh |
| Renault Group |
| Others |
Pricing and Supply Chain Analysis
Precision metrology technicians concentrated in Baden-Württemberg and Stuttgart command wage premiums that widen spreads between premium-certified and economy-grade refurbishment tiers, compressing margins for mid-tier service providers competing on price.
Pricing Analysis
Input-cost pass-through from REACH-compliant material requalification and scarce non-destructive testing labor compresses margins at the economy tier while reinforcing premium-tier pricing power. Pricing stratifies across premium, standard, and economy tiers, with differentiation driven by EASA/FAA certification level and serialized traceability depth. Cost compression in standard-grade electronics refurbishment is intensifying because dual supply chain maintenance for REACH-compliant substrates erodes unit economics. Mid-sized Italian machinery operators exhibit highest price sensitivity, while aerospace tier-one suppliers accept premium pricing for flight-critical module documentation.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from German automotive clusters, while independent platforms aggregate fragmented Italian and French mid-market buyers. Core supply concentrates in Germany, Italy, and France, with used equipment availability tethered to original machinery sales cycles in Stuttgart, Munich, and Turin. Critical inputs include aerospace-grade alloys, REACH-compliant electronic substrates, and precision bearings. Single-source vulnerability from serialized tracking system suppliers exposes non-OEM service providers to capacity constraints. Distribution runs through captive dealer networks for heavy machinery and direct platform integrations for automotive and aerospace verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Remanufacturing-as-a-Service constitutes a late-cycle quality story as EU Green Deal mandates shift procurement specifications toward certified circular content and documented carbon reduction.
For Market Incumbents: Cement aftermarket control by acquiring serialized lifecycle documentation capabilities for aerospace module tracking, countering independent platform disintermediation. Extend predictive diagnostics R&D investment to differentiate from commodity refurbishment competitors. Vertical integration into REACH-compliant material qualification reduces supplier audit burden and protects margin structure. For New Entrants and Emerging Players: Begin with outcome-based pricing pilots for critical bottleneck equipment in northern Italian machinery clusters, where incumbent dealer networks show coverage gaps. Target tier-two aerospace suppliers in Toulouse seeking module reconditioning alternatives to OEM-captive services. Deploy cloud-based condition monitoring platforms with SCADA bridge architecture to capture hybrid-deployment demand from legacy plant infrastructure. For Investors and Strategic Acquirers: Heavy machinery OEMs are the most active acquirer in this space, seeking predictive diagnostics capabilities to extend equipment operating life and defend aftermarket revenue streams. Five-to-ten-year viability rests on circular economy mandate durability and EPR framework expansion. Watch for ECHA substance restriction updates as inflection indicators for material requalification cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Serialized Tracking Capability Acquisition | Enables tier-one aerospace contracts requiring EASA-traceable flight-critical assembly documentation. |
| REACH-Compliant Material Pre-Qualification | Reduces supplier audit cycles and accelerates electronics refurbishment throughput for German automotive clients. |
| Cloud-Based Platform Integration | Consolidates fragmented maintenance decisions into centralized procurement for Stuttgart and Munich production lines. |
| Outcome-Based Pricing Pilot Programs | Aligns service provider incentives with uptime guarantees for critical bottleneck equipment in Italian machinery plants. |
| Predictive Diagnostics R&D Expansion | Extends equipment operating life and differentiates from commodity component refurbishment competitors. |
Research Methodology
Coverage spans Germany, France, Italy, the United States, and Japan, with primary inputs from each combining structured interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads alongside secondary validation. Secondary sources include EU Green Deal implementation documents, ECHA REACH substance restriction databases, SEC filings from listed industrial conglomerates, and customs trade data for refurbished equipment flows. Bottom-up service provider revenue aggregation triangulates against top-down end-user industry spend estimates.
Rate-of-change decomposition separates volume expansion from pricing mix shifts across the projection horizon. Segmentation dimensions modeled include service type depth, deployment architecture, end-user industry vertical, and regional regulatory cluster. CAGRs derive from historical trajectory analysis adjusted for policy mandate implementation schedules and technology adoption S-curves. Industry-specific forecast inputs incorporate EU Green Deal recycled content threshold phase-ins and EPR framework expansion timelines.
Several conditions sit outside the modeled scope, including geopolitical disruptions to aerospace supply chains and unilateral tariff impositions on refurbished equipment trade. Forecasts reflect assumptions regarding REACH substance restriction stability and circular economy mandate enforcement continuity. Periodic stress-testing of base assumptions is recommended against ECHA regulatory update calendars and extended producer responsibility legislative progress in France and Italy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Biopharma Plastics Market
Others
Medical Simulation Market
Others
Mobile Computer Cart Market
Others
Aerospace Tester Market
Others
Spend Analytics Market
Others
United States Air Furnaces Market
Others
Grna Market
Others
Pin Mills Market
Others
North America Machine Vision Systems Market
Others
Bimodal Identity Management Solutions Market
Others
Bulgur Market
Others
North America Luxury Car Market
Others
Pediatric Measuring Devices Market
Others
Asia Pacific Foodservice Paper Packaging Market
Others
Next Gen Video Codecs Market
Others
Animal Feed Alternative Protein Market