
 Software Synthesizers Market | 2026-2036
Software Synthesizers Market Size, Share, and Industry Trends Forecast 2026-2036
Software Synthesizers Market Insights
Film scoring and game audio production is expanding as a revenue vertical for software synthesizer vendors. Native Instruments leverages its Komplete ecosystem to anchor studio workflows across professional composer suites. Arturia specializes in analog modeling architectures that dominate retro-synth segments. Spectrasonics sustains premium positioning through proprietary sample-streaming engines that occupy the high-end scoring market.
Software synthesizers are digital audio applications that generate or manipulate sound through algorithmic oscillators, filter networks, and modulation matrices, typically operating at sample rates of 44.1 kHz or higher with latency below 10 milliseconds for real-time performance. Virtual instruments command the largest revenue pool among product types, though granular synthesis technology is accelerating fastest in experimental electronic and ambient production circles. Cloud-based deployment is displacing standalone installations in educational and collaborative settings where subscription economics reduce upfront barriers.
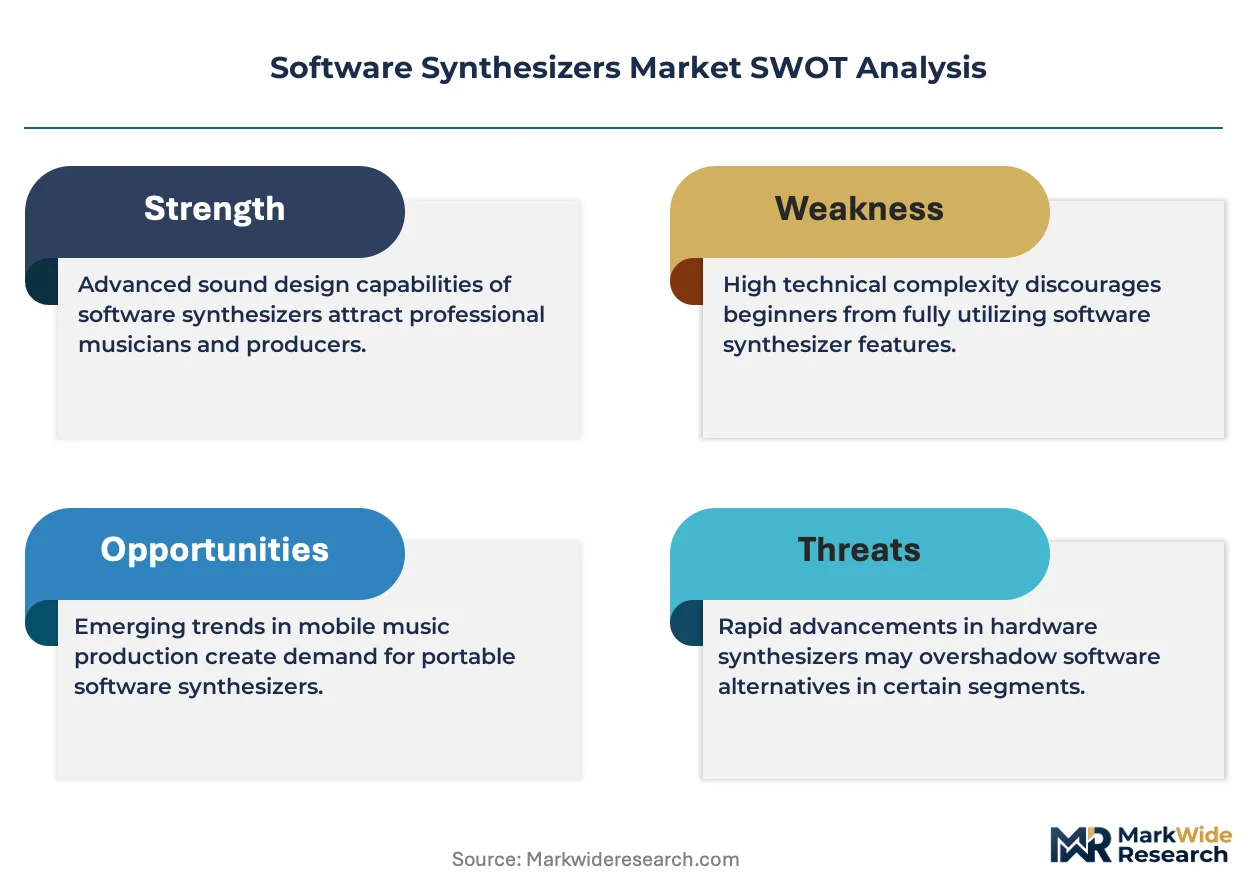
FCC guidelines on digital transmission integrity and EU copyright directives administered by EFSA-aligned bodies shape cross-border licensing of sample libraries and plugin distribution. GDPR compliance costs filter into pricing for European customers while FDA-registered medical audio applications create adjacent demand for precision synthesis tools. Stakeholders must monitor how generative AI training datasets intersect with existing intellectual property frameworks before committing to long-term platform strategies.
Market Dynamics
Generative AI training on copyrighted audio corpora is forcing software synthesizer vendors to renegotiate licensing frameworks and rebuild sample provenance systems from the oscillator level upward.
Growth Catalysts
- EU Digital Services Act compliance mandates:Platform transparency requirements are accelerating enterprise adoption of auditable virtual instrument libraries in German and French production studios.
- Granular synthesis engines:Experimental electronic producers in Berlin and London are pushing algorithmic sound design into mainstream film scoring workflows.
- Cloud-native deployment architectures:Educational institutions across North America and Europe are abandoning perpetual licenses for subscription models that reduce IT overhead.
Market Restraints
- Proprietary DSP core concentration:Three semiconductor foundries in Taiwan and South Korea control fabrication of low-latency audio processing chips, creating single-source vulnerability.
- GDPR compliance cost pass-through:European customers bear elevated pricing for sample library hosting services due to data localization and consent management infrastructure.
- Analog hardware substitution:Boutique modular synthesizer manufacturers in Portland and Tokyo are capturing premium segments resistant to software emulation.
Strategic Opportunities
- Medical audio applications:FDA-registered precision synthesis tools for auditory research and therapeutic soundscapes remain underdeveloped relative to entertainment verticals.
- Spatial audio format convergence:Dolby Atmos and MPEG-H 3D adoption in streaming platforms is creating demand for binaural-capable virtual instruments.
- India's PLI scheme for electronics manufacturing:Domestic assembly incentives could localize plugin distribution infrastructure for South Asian composer markets.
Industry Challenges
- Generative AI training dataset provenance:Vendors face escalating legal exposure as copyright holders challenge unlicensed use of recorded instrument samples in machine learning corpora.
- Legacy DAW integration debt:Maintaining backward compatibility with decade-old sequencer architectures consumes engineering resources that could advance real-time synthesis performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Software Synthesizers Market |
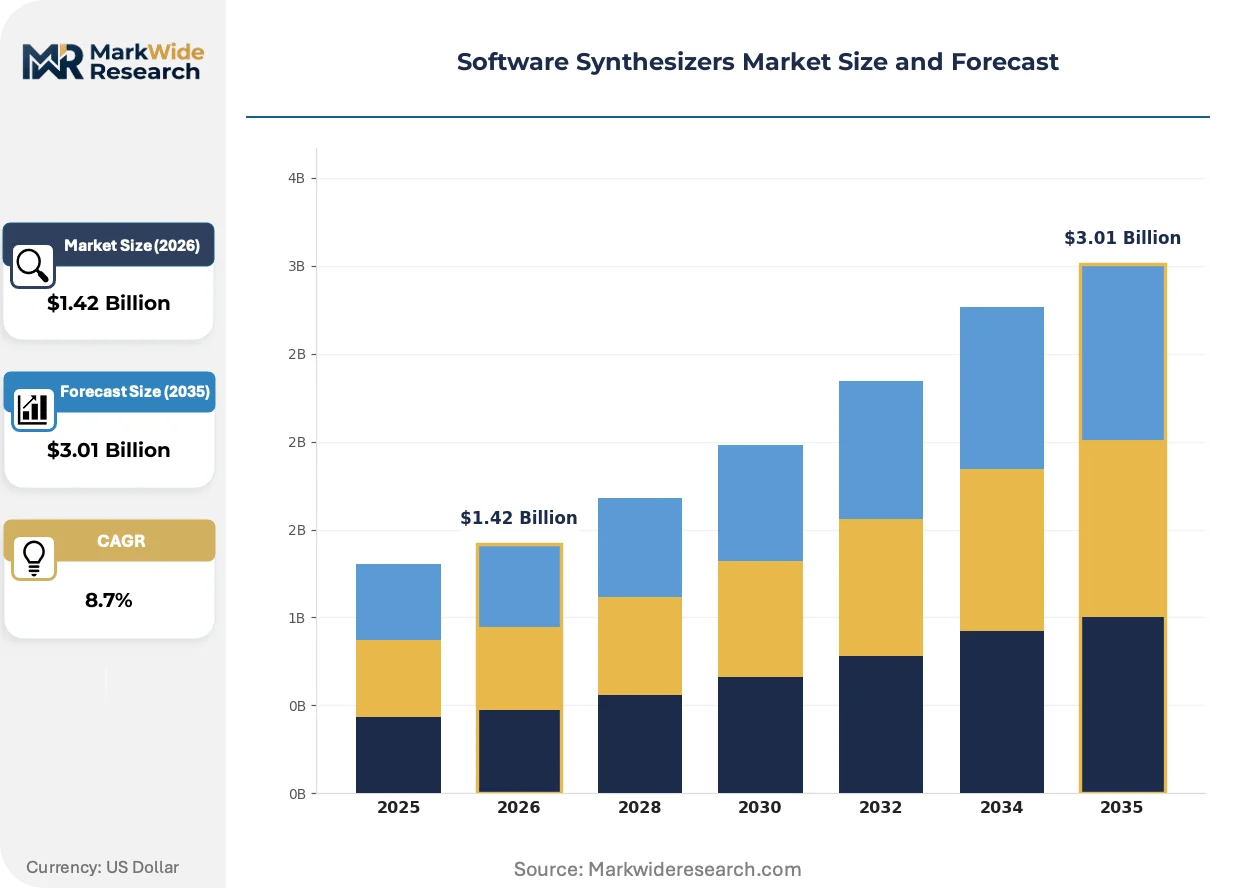
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virtual Instruments, MIDI Controllers, Effect Processors, Sampling Software Deployment Model: Cloud-Based, On-Premise, Hybrid, Standalone End User: Professional Musicians, Audio Engineers, Music Producers, Hobbyists Technology: Analog Modeling, Granular Synthesis, FM Synthesis, Additive Synthesis |
| Companies Covered | Native Instruments, Arturia, u-he, Xfer Records, Spectrasonics, Reason Studios, Ableton AG, Steinberg, Cherry Audio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Software Synthesizers Market Trends and Innovations
Neural network-based timbre transfer and real-time style interpolation are compressing traditional sound design timelines from hours to minutes in professional workflows.
Physical modeling synthesis is overtaking subtractive architectures in orchestral and acoustic instrument emulation. Composers in Los Angeles and London are abandoning sample libraries for algorithmic instruments that respond dynamically to performance gesture. This shift is overtaking the premium scoring market segment that Spectrasonics and East West have dominated through disk-streaming sample engines.
The EU AI Act's transparency requirements for generative systems are mandating disclosure of training data composition in AI-assisted composition tools. Plugin manufacturers must now document sample provenance or risk market exclusion from European distribution channels. German regulators are enforcing these provisions most aggressively, creating compliance templates that other member states are adopting.
Perpetual license abandonment is accelerating among independent producers who prioritize cash flow flexibility over asset ownership. Subscription bundles from Native Instruments and Ableton are displacing à la carte plugin purchases in the bedroom producer demographic. This pattern is most visible in the United Kingdom, where freelance composer density and gig-economy income volatility favor operational expenditure models.
Software Synthesizers Market Segmentation
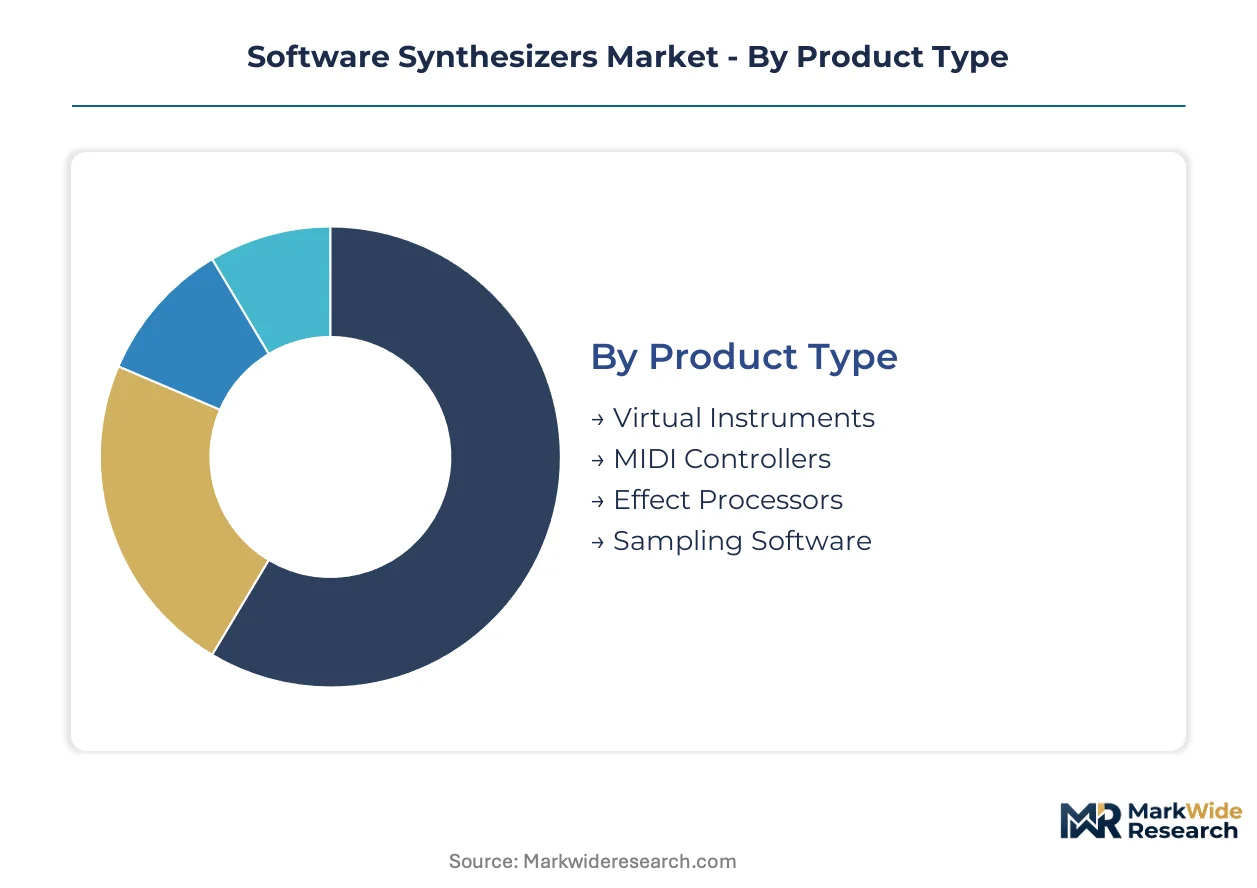
Software synthesizer vendors structure product portfolios around distinct technical architectures and user workflows. Segmentation reveals where engineering resources concentrate and which customer cohorts drive recurring revenue.
Product Type:
Capital intensity peaks with sampling software requiring extensive disk-streaming infrastructure and licensed content libraries, while virtual instruments demand sustained DSP optimization investment.
- Virtual Instruments:Algorithmic sound engines generate timbre through oscillators, filters, and modulation matrices without external audio files. German electronic producers in Berlin and Hamburg favor these for real-time performance flexibility. Cloud-native licensing is displacing perpetual purchases in educational markets.
- Sampling Software:Disk-streaming architectures deliver multi-gigabyte orchestral and acoustic instrument libraries with velocity-layered articulations. Film composers in Los Angeles and London dominate demand for premium-tier offerings. Storage and memory requirements create higher hardware barriers than pure synthesis alternatives.
- MIDI Controllers:Hardware interfaces translating physical gesture into digital control data, often bundled with software instruments.
- Effect Processors:Signal processing plugins shaping timbre through distortion, modulation, spatialization, and dynamics.
Most installed capacity flows through Virtual Instruments. Expansion is steepest in Sampling Software.
Deployment Model:
Customer IT maturity determines adoption patterns, with subscription economics favoring institutions over individual asset owners.
- Cloud-Based:Browser-accessible synthesis engines with centralized patch libraries and collaborative project hosting. North American universities are abandoning campus license servers for SaaS delivery. GDPR compliance costs elevate European pricing relative to other markets.
- On-Premise:Locally installed executables with perpetual or term-limited activation. Professional studios in Germany and France retain preference for offline-capable workflows. Network dependency risks in cloud architectures reinforce this segment's resilience.
- Hybrid:Split architectures processing audio locally while synchronizing presets and projects through cloud services.
- Standalone:Self-contained applications operating without host DAW software, favored by live performers.
Cloud-Based deployments are climbing the fastest among institutional buyers. On-Premise retains dominance in commercial scoring facilities.
End User:
Revenue concentration skews toward professionals with established studio infrastructure, though hobbyist volume creates platform ecosystem effects.
- Professional Musicians:Touring and session performers requiring low-latency, road-stable configurations. Electronic artists in London and Berlin drive demand for compact, CPU-efficient instruments. Hardware controller integration is non-negotiable for this cohort.
- Music Producers:Recording and mixing specialists shaping final commercial releases across genre categories. Freelance producers in the United Kingdom favor subscription bundles preserving cash flow flexibility. Project-based income volatility reinforces operational expenditure preference.
- Audio Engineers:Technical specialists optimizing signal chains for broadcast, live sound, and post-production.
- Hobbyists:Non-commercial creators prioritizing accessibility and learning resources over professional feature depth.
Music Producers represent the largest revenue pool. Hobbyists are expanding most quickly as entry-price barriers fall through subscription models.
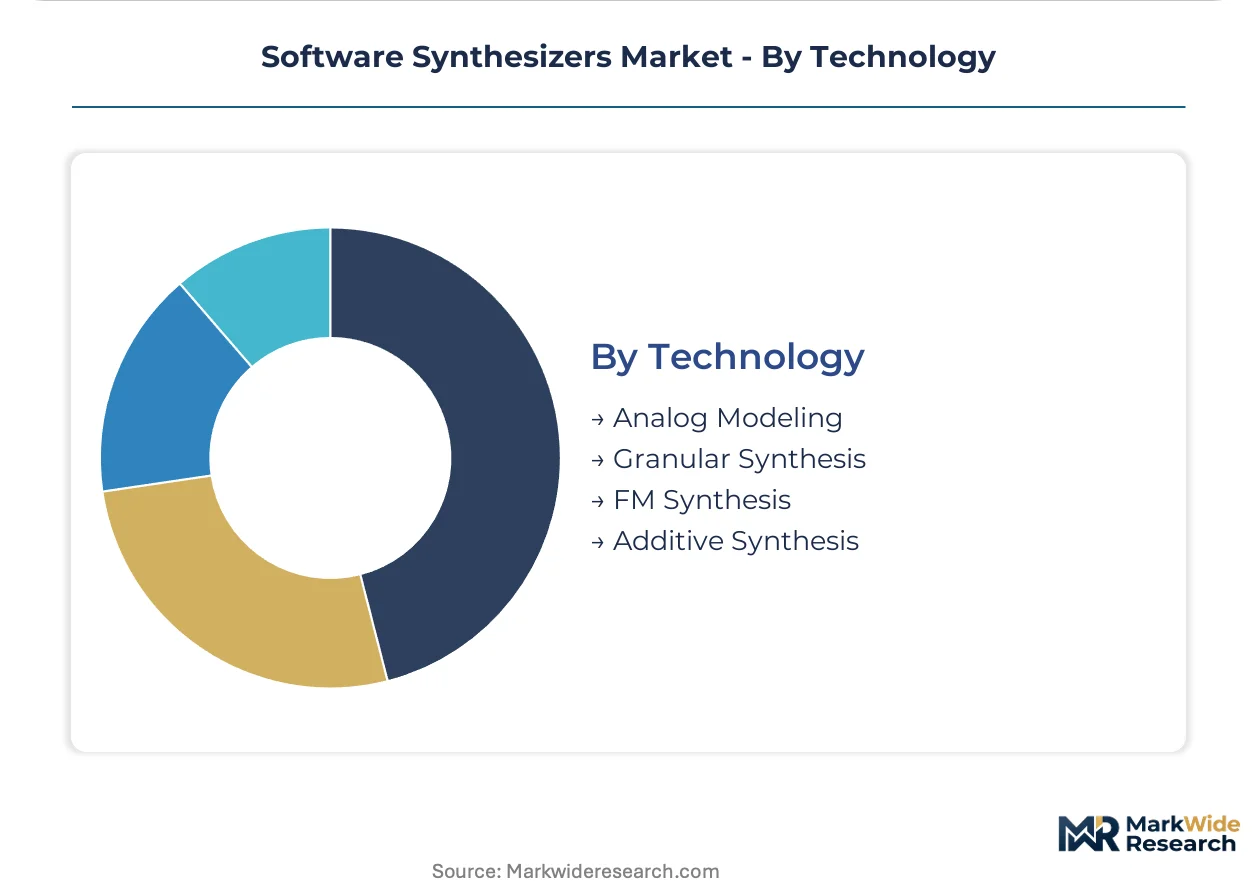
Technology:
R&D allocation reflects shifting composer preferences away from sample libraries toward algorithmic instruments responding dynamically to performance gesture.
- Physical Modeling:Mathematical simulation of acoustic instrument behavior including string vibration, air column resonance, and mechanical noise. Orchestral composers in Los Angeles are abandoning disk-streaming libraries for these responsive alternatives. CPU requirements remain higher than sample playback.
- Granular Synthesis:Microsound architectures decomposing audio into grain clouds manipulated through density, pitch, and position parameters. Experimental producers in Berlin and London push these techniques into mainstream film scoring. The EU AI Act's training data transparency mandates complicate sample-source documentation.
- FM Synthesis:Frequency modulation architectures generating complex spectra through operator chains.
- Additive Synthesis:Fourier-based timbre construction through harmonic partial summation.
Physical Modeling captures the steepest expansion trajectory in premium scoring segments. Granular Synthesis leads experimental and ambient production adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where software synthesizer vendors concentrate compliance infrastructure, with GDPR cost differentials pushing cloud-hosting decisions toward jurisdictions with lighter data-localization burdens.
United States
Film scoring studios in Los Angeles and game audio developers in Austin drive premium-tier demand for disk-streaming orchestral libraries. FCC guidelines on digital transmission integrity shape cross-border sample distribution compliance. Seattle hosts dense clusters of cloud-native audio platform engineers building SaaS delivery architectures for educational markets.
Germany
Berlin's electronic music producers and Hamburg's audio technology developers anchor European demand for real-time virtual instruments. The EU AI Act's transparency mandates enforce sample-provenance documentation requirements most aggressively here. Munich-based engineering teams specialize in low-latency DSP optimization for professional touring configurations.
United Kingdom
Freelance music producers in London favor subscription bundles preserving cash flow flexibility amid gig-economy income volatility. GDPR compliance costs elevate pricing for sample library hosting services relative to North American markets. Bristol's experimental electronic scene pushes granular synthesis techniques toward mainstream film scoring adoption.
Japan
Professional musicians in Tokyo and Osaka demand compact, CPU-efficient instruments with hardware controller integration for road-stable performance rigs. METI standards influence domestic certification requirements for medical audio applications using precision synthesis tools. Kyoto hosts specialized physical modeling research clusters advancing algorithmic orchestral emulation.
India
Educational institutions in Bangalore and Mumbai are abandoning perpetual licenses for subscription models reducing IT overhead in campus deployments. The PLI scheme for electronics manufacturing could localize plugin distribution infrastructure for South Asian composer markets. Chennai's emerging audio technology workforce supports regional customer success operations.
Software Synthesizers Market Competitive Landscape
Portfolio diversification dominates the current landscape as vendors extend from standalone instruments into integrated production ecosystems. The market structures around three tiers: full-suite platform providers, specialized modeling architects, and boutique experimental developers. Two strategic archetypes predominate: ecosystem builders anchoring studio workflows through bundled subscriptions, and precision specialists commanding premium pricing through proprietary technical differentiation. M&A activity concentrates on acquiring granular synthesis and physical modeling engineering teams, while technology licensing partnerships proliferate for spatial audio format compliance.
Within the ecosystem-builder tier, Native Instruments and Ableton AG exemplify platform strategies that integrate hardware controllers, software instruments, and cloud collaboration tools into unified subscription offerings. Spectrasonics occupies a position representing the premium-specialist archetype, sustaining market presence through proprietary sample-streaming architectures that serve high-end film scoring verticals. These three companies collectively illustrate how competitive positioning bifurcates between breadth-driven recurring revenue models and depth-driven technical differentiation in professional composer markets.
| Leading Market Players |
|---|
| Native Instruments |
| Arturia |
| u-he |
| Xfer Records |
| Spectrasonics |
| Reason Studios |
| Ableton AG |
| Steinberg |
| Cherry Audio |
| Others |
Pricing and Supply Chain Analysis
DSP engineering talent concentration in Berlin and Hamburg drives labor-cost differentials that widen pricing-tier spreads between boutique physical modeling specialists and mass-market virtual instrument vendors. GDPR compliance infrastructure in Germany and France elevates European cloud-hosting costs relative to North American SaaS delivery, compressing margins for subscription-tier offerings while premium perpetual licenses absorb these overheads through higher upfront pricing.
Pricing Analysis
Distributor margins in sample library distribution absorb 25-35 points before reaching end composers, while direct-to-studio sales from Native Instruments and Spectrasonics bypass this layer entirely. Three-tier pricing structure across premium orchestral suites, mid-tier producer bundles, and entry-level subscription tiers dominates the market, with quality grade and certification level (CE marking for EU distribution) as primary differentiation drivers. Cost compression in the mid-tier is intensifying because cloud-native competitors are undercutting perpetual-license incumbents on total cost of ownership. Hobbyist segments exhibit highest price sensitivity, while film scoring studios in Los Angeles and London demonstrate lowest elasticity due to project-budget insulation.
Supply Chain Analysis
Low-latency audio processing chip fabrication rests on Taiwanese and South Korean foundry capacity, with analog-to-digital converter components drawing from Japanese precision electronics manufacturers. Proprietary DSP core architectures, licensed sample content libraries, and cloud-hosting infrastructure constitute the three critical input dependencies. Single-source vulnerability in semiconductor fabrication creates supply chain risk, particularly for vendors dependent on custom ASIC designs for real-time synthesis performance. Distribution runs through direct digital storefronts, authorized plugin resellers, and bundled hardware-software channel partnerships with MIDI controller manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software synthesizers function as a stable compounder anchored by recurring subscription revenue from producer ecosystems and steady replacement demand from studio infrastructure upgrades. The market's defensibility stems from high switching costs embedded in DAW workflow integration and preset library accumulation.
For Market Incumbents: Anticipate generative AI training dataset litigation by rebuilding sample provenance systems from oscillator architectures upward and securing indemnification clauses in content licensing agreements. Vertical integration into hardware controller manufacturing in Germany and Japan locks in road-stable performance configurations that touring electronic artists demand, while certification investment in FDA-registered medical audio applications opens adjacent revenue pools with higher margin profiles than entertainment verticals. For New Entrants and Emerging Players: EU AI Act transparency mandates in Germany open a window for compliance-native entrants to capture European distribution channels from incumbents burdened by legacy sample library documentation debt. India's educational subscription market represents the most penetrable geography, with campus IT departments abandoning perpetual license servers for SaaS delivery models. A go-to-market angle anchored in granular synthesis engines for experimental film scoring in Bristol and Berlin bypasses saturated orchestral library competition. For Investors and Strategic Acquirers: Full-suite platform providers are the most active acquirer in this space, consolidating physical modeling engineering teams to fill capability gaps in responsive algorithmic instruments. The five-to-ten-year viability window favors vendors with cloud-native architectures and subscription revenue concentration above fifty percent of total sales. Acquisition target archetype: boutique granular synthesis developers with proprietary DSP cores and established composer relationships in London and Los Angeles. The signal to watch is Dolby Atmos spatial audio format adoption velocity in streaming platform mandates, which will determine binaural-capable instrument demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native Instruments' Komplete ecosystem anchors studio workflows through unified subscription bundles reducing customer churn. |
| Acquisition of Specialist Firm | Physical modeling engineering teams in Kyoto and Los Angeles command premium valuations as orchestral composers abandon sample libraries. |
| Product Launch | Cloud-native synthesis engines with GDPR-compliant European hosting infrastructure capture institutional buyers abandoning campus license servers. |
| Strategic Partnership | MIDI controller hardware bundling with software instruments locks in touring electronic artist configurations in Berlin and Tokyo. |
| Geographic Expansion | India's PLI scheme for electronics manufacturing enables localized plugin distribution infrastructure for South Asian composer markets. |
Research Methodology
Coverage spans Germany, the United States, the United Kingdom, Japan, and India, with primary inputs from each market informing demand-side validation. The analysis combines structured interviews with CTOs at software synthesizer vendors, IT procurement officers at educational institutions, platform engineers building cloud-native audio infrastructure, and integration specialists at DAW manufacturers. Secondary validation draws from SEC filings, EU regulatory transparency databases, hyperscaler capex disclosures for cloud-hosting capacity, and customs records for semiconductor component trade flows. Bottom-up demand modeling triangulates against top-down market sizing across deployment models and end-user segments.
Granularity extends to deployment model, organization size, vertical application, integration complexity, and regional adoption pattern. Value projections across the analysis window derive from segment-specific CAGRs applied to installed base evolution and replacement cycle timing. Physical modeling R&D investment trajectories and granular synthesis patent filing velocity serve as industry-specific forecast inputs, alongside cloud-hosting infrastructure expansion rates in North American and European data center markets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under generative AI copyright litigation scenarios and Taiwan semiconductor supply disruption conditions. Projections reflect documented assumptions regarding subscription conversion rates, DAW platform consolidation patterns, and spatial audio format adoption curves. A small set of named triggers—EU AI Act enforcement intensity, Dolby Atmos mandate expansion, and India's PLI scheme implementation pace—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Electroshock Weapons Market
Others
Industrial Gauges Market
Others
Next Gen Video Codecs Market
Others
Toy Packaging Market
Others
Smart Home Technologies Market
Others
South Korea Smart Home Market
Others
Smart Badge Market
Others
Thailand Commercial Vehicles Lubricants Market
Others
Rotary Union Market
Others
Hybrid System Market
Others
United States Smart Homes Market
Others
Safety Critical Software Testing Market
Others
ISO Cylinder Market
Others
Asia-Pacific B2B Legal Services Market
Others
Mobile Computing Devices Market
Others
Global Bio-Based Chemicals Market