
 Canada LNG Bunkering Market | 2026-2036
Canada LNG Bunkering Market Size, Share, and Industry Trends Forecast 2026-2036
Canada LNG Bunkering Market Outlook
Conventional marine diesel is shifting toward LNG as the dominant bunker fuel for vessels calling Canadian Pacific ports, driven by IMO sulfur caps and domestic carbon intensity targets. Shell PLC leverages its integrated gas supply chain to secure feedstock advantages across British Columbia terminal networks. FortisBC anchors downstream distribution through its Tilbury LNG facility and marine loading infrastructure. Seaspan Energy specializes in coastal barge-based delivery systems that serve Vancouver Island and mainland port clusters.
Canada LNG bunkering denotes the commercial supply of liquefied natural gas as marine fuel to vessels operating in Canadian waters, with product stored at minus 162 degrees Celsius in cryogenic tanks and vaporized through regasification skids prior to engine injection. The primary purpose is enabling compliance with sulfur oxide emission limits while reducing particulate matter and carbon dioxide output versus residual fuel oils. Ship-to-Ship delivery dominates transaction volumes for large cargo vessels and container ships requiring minimal port downtime, while Truck-to-Ship operations serve smaller ferry fleets and fishing trawlers at secondary harbors lacking fixed bunkering infrastructure. Port-Based facilities capture the highest margin pools through long-term storage and throughput contracts with major shipping lines.
Transport Canada administers Vessel Pollution and Dangerous Chemicals Regulations that mandate sulfur content limits and record-keeping for fuel switching, while the International Maritime Organization's MARPOL Annex VI provides the overarching framework for emission control areas covering Canadian Pacific and Atlantic coastlines. British Columbia's provincial clean fuel regulations and the federal Clean Fuel Standard create overlapping compliance obligations that accelerate LNG infrastructure investment at marine terminals. Stakeholders must monitor regulatory alignment between federal carbon pricing mechanisms and port authority green tariff structures to anticipate bunkering cost differentials across Canadian trade corridors.
Market Dynamics
Transport Canada's Vessel Pollution and Dangerous Chemicals Regulations are compressing the conversion timeline for coastal fleets, forcing terminal operators to accelerate cryogenic infrastructure deployment along British Columbia's trade corridors before sulfur enforcement deadlines.
Growth Catalysts
- IMO MARPOL Annex VI:International sulfur caps in emission control areas are compelling transpacific container lines to switch from residual fuel oils to LNG at Vancouver and Prince Rupert.
- British Columbia provincial mandates:Port authority green tariff structures reward early LNG adopters with berthing priority and reduced harbor fees.
- Dual-fuel engine technology:Marine engine manufacturers have commercialized retrofittable LNG-diesel systems that preserve vessel resale value during fuel transition periods.
Market Restraints
- Cryogenic storage capex:Minus 162 degree Celsius tankage and regasification skids require capital intensity that excludes smaller fishing cooperatives from direct LNG access.
- Feedstock supply concentration:Tilbury facility and limited western Canadian liquefaction capacity create geographic chokepoints for marine fuel distribution.
- Methane slip regulation uncertainty:Unburned methane venting standards under federal Clean Fuel Standard remain unresolved, chilling long-term vessel conversion commitments.
Strategic Opportunities
- Arctic shipping corridors:Northwest Passage route development positions Canadian LNG bunkering as a strategic refueling node between Atlantic and Pacific transshipment lanes.
- Truck-to-ship channel expansion:Mobile cryogenic delivery systems can capture ferry fleets and coastal tugs at secondary harbors lacking fixed loading arms.
- Federal carbon pricing alignment:Clean Fuel Standard credit generation for LNG versus marine diesel creates margin pools for early infrastructure investors.
Industry Challenges
- Cryogenic technician scarcity:Specialized training for minus 162 degree Celsius handling and boil-off gas management exceeds current marine workforce certification capacity.
- Interoperability standards:ISO 20519 bunkering connection protocols lack uniform adoption across vessel classes, forcing redundant equipment configurations at multi-user terminals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada LNG Bunkering Market |
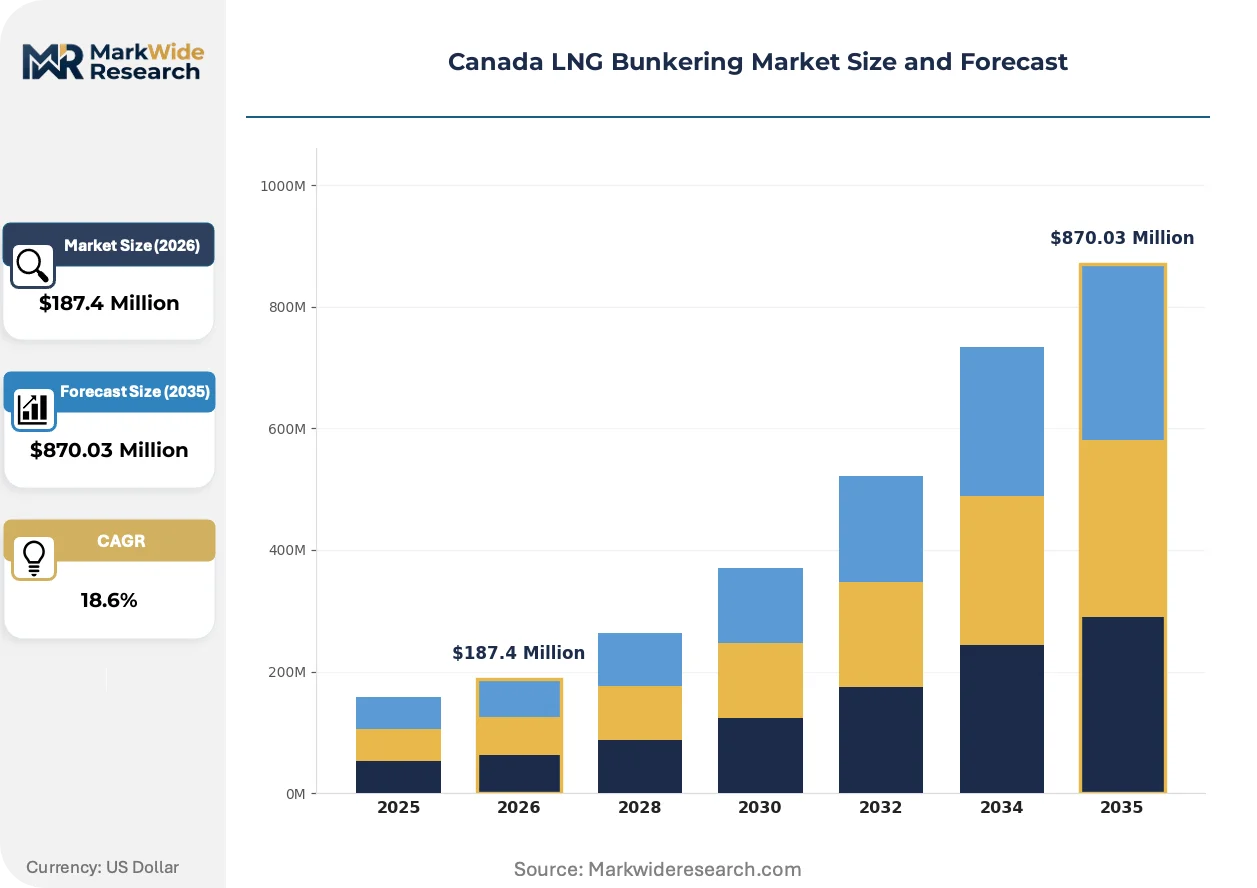
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Port-Based, Ship-to-Ship, Truck-to-Ship, Bunkering Facility Delivery Method: Direct Supply, On-Demand, Scheduled Delivery, Mobile Bunkering Vessel Type: Cargo Ships, Ferry Boats, Container Vessels, Fishing Trawlers Client Type: Commercial Enterprises, Government Vessels, Offshore Operators, Others |
| Companies Covered | Shell PLC, TotalEnergies SE, Harvey Gulf International Marine LLC, Nauticor GmbH & Co. KG, Gasum AS, FortisBC, Seaspan Energy, ENGIE, Gazprom Neft, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada LNG Bunkering Market Strategic Shifts
Digitalization of fuel custody transfer and cryogenic monitoring systems is compressing transaction friction at marine terminals, while regulatory alignment between federal and provincial frameworks accelerates infrastructure standardization across British Columbia port networks.
Integrated vapor recovery systems are unifying boil-off gas management with vessel fueling operations, eliminating venting losses during bunkering. Container lines operating Vancouver-Asia routes are retrofitting these systems at pace to preserve cargo refrigeration energy balance. The technology is unifying environmental compliance with operational cost control in a market where methane accountability is tightening.
Canada's Clean Fuel Standard credit trading mechanism is reshaping LNG marine fuel economics by assigning carbon intensity scores to bunker deliveries. British Columbia port authorities are embedding these scores into green tariff calculations, forcing terminal operators to document supply chain emissions. Transpacific shipping lines with Science Based Targets initiative commitments are prioritizing Canadian Pacific ports for this regulatory transparency.
Ship-to-ship bunkering contracts are displacing traditional port-based fueling for large cargo vessels seeking minimal downtime. Container operators are negotiating throughput guarantees directly with LNG suppliers, bypassing terminal storage intermediaries. This pattern concentrates most visibly among Asia-North America trade lanes where schedule reliability commands premium pricing.
Canada LNG Bunkering Market Segmentation
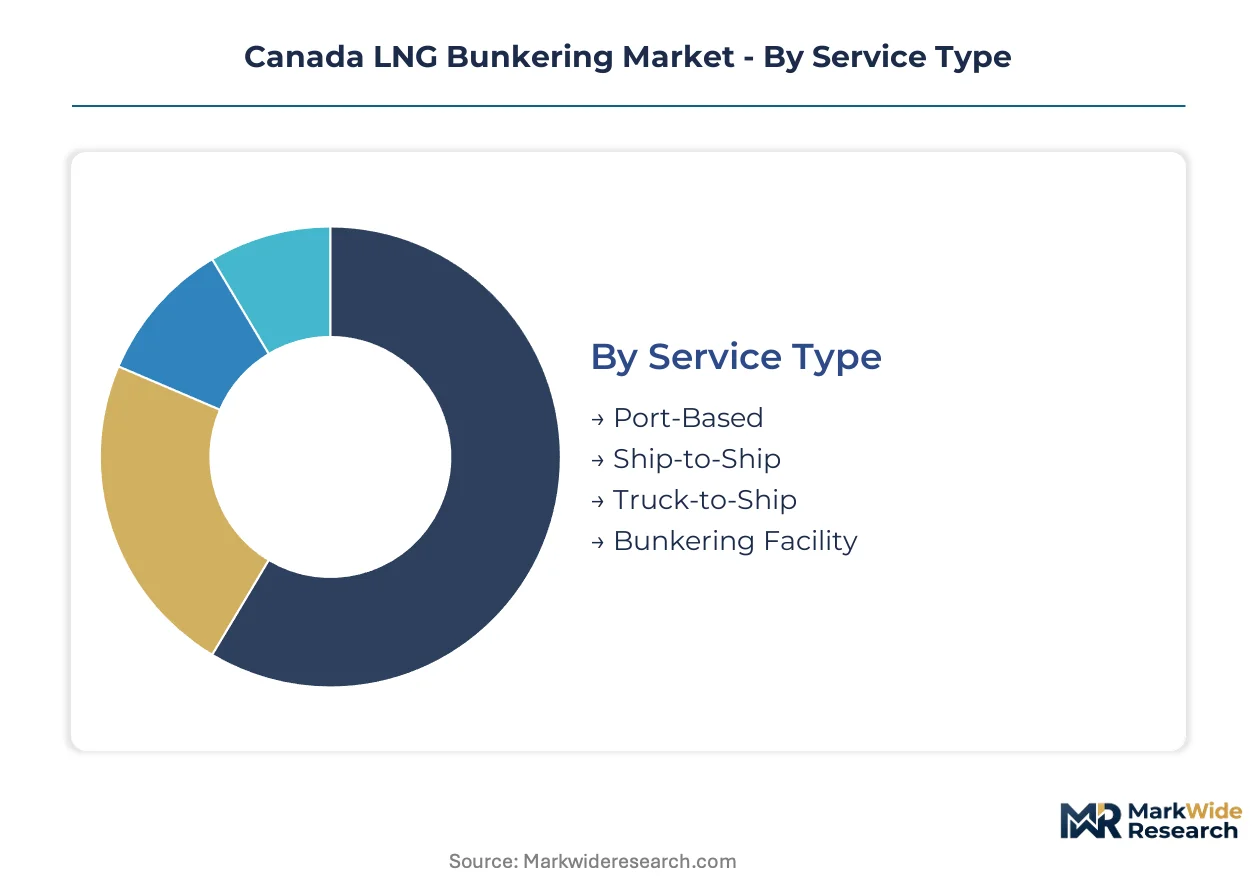
LNG bunkering service configurations in Canada reflect the geographic dispersion of vessel traffic along British Columbia's coastline and the cryogenic infrastructure constraints at Pacific terminals. Segmentation choices determine capital deployment intensity, regulatory compliance pathways, and margin capture potential for marine fuel suppliers.
Service Type:
Supply concentration at Tilbury LNG and limited western Canadian liquefaction capacity shapes how service tiers compete for vessel traffic.
- Ship-to-Ship:Cryogenic transfer operations between dedicated LNG bunkering vessels and receiving ships eliminate port downtime for transpacific container lines. Demand concentrates at Vancouver and Prince Rupert where Asia-North America trade lanes require rapid turnaround.
- Port-Based:Fixed terminal infrastructure with long-term storage contracts captures premium margins through throughput guarantees with major shipping lines. British Columbia port authorities embed green tariff structures that reward dedicated facility investment.
- Truck-to-Ship:Mobile cryogenic delivery systems serve secondary harbors lacking fixed loading arms, targeting ferry fleets and coastal tugs at Vancouver Island terminals.
- Bunkering Facility:Dedicated marine fueling terminals with ISO 20519 connection protocols serve multi-user vessel classes through standardized equipment configurations.
Today's leader: Port-Based. Tomorrow's challenger: Ship-to-Ship.
Delivery Method:
Cost tier differentiation separates capital-intensive scheduled operations from premium-priced responsive delivery models.
- Scheduled Delivery:Pre-arranged bunkering windows align with vessel port calls, enabling inventory optimization at storage terminals. Container lines with fixed Asia-North America rotations favor this predictability for fuel cost budgeting.
- On-Demand:Reactive provisioning for unscheduled vessel movements commands price premiums, serving fishing trawlers and coastal cargo operators with irregular routing patterns.
- Direct Supply:Producer-to-vessel contracts bypass terminal intermediaries, concentrating among integrated gas suppliers with captive liquefaction capacity.
- Mobile Bunkering:Barge-based and truck-mounted systems extend LNG access to harbors without fixed cryogenic infrastructure, expanding the addressable market beyond primary port clusters.
Scheduled Delivery dominates volume. On-Demand climbs the fastest as fleet flexibility requirements intensify.
Vessel Type:
Application-specific fuel consumption patterns and emission compliance timelines drive segment prioritization for infrastructure investors.
- Container Vessels:Transpacific operators face the tightest IMO MARPOL Annex VI enforcement timelines, converting dual-fuel engine fleets at pace to secure berthing priority under British Columbia port authority green tariffs.
- Ferry Boats:Coastal passenger services with predictable daily routes enable dedicated bunkering infrastructure amortization, particularly at Vancouver Island terminals serving mainland connections.
- Cargo Ships:General freight operators exhibit slower conversion timelines due to asset replacement cycles and fragmented ownership structures across smaller Pacific fleet operators.
- Fishing Trawlers:Cooperative ownership models and seasonal operating patterns limit direct LNG access, relegating this segment to truck-to-ship delivery channels at secondary harbors.
Container Vessels anchor current investment. Ferry Boats represent the steadiest expansion trajectory.
Client Type:
Customer procurement sophistication and regulatory compliance mandates create distinct service requirement profiles across buyer categories.
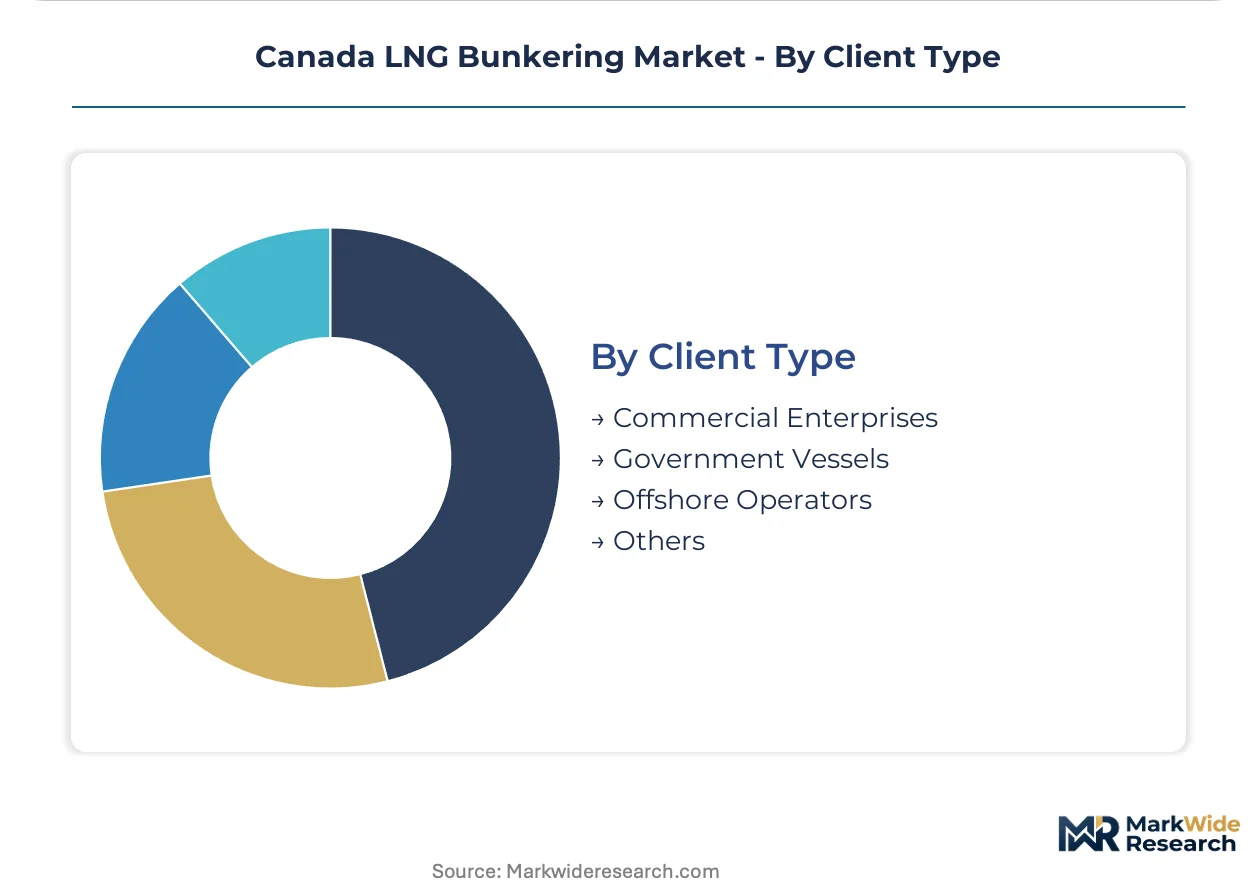
- Commercial Enterprises:Container lines and bulk operators with Science Based Targets initiative commitments prioritize Canadian Pacific ports for Clean Fuel Standard credit transparency, driving demand for documented carbon intensity scoring.
- Government Vessels:Canadian Coast Guard and federal fleet operators follow procurement mandates aligned with federal carbon pricing mechanisms, creating stable demand for compliant marine fuel.
- Offshore Operators:Oil and gas platform supply vessels and exploration support craft require specialized cryogenic handling protocols for remote operating environments.
- Others:Research vessels, cruise operators, and specialty craft with intermittent fueling needs complete the client portfolio through flexible contracting arrangements.
Commercial Enterprises command infrastructure design. Government Vessels provide demand floor stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
British Columbia anchors Canadian LNG bunkering demand through Vancouver and Prince Rupert terminals serving transpacific container traffic. Provincial mandates and federal emission regulations compress infrastructure deployment timelines across Pacific coastal corridors.
British Columbia
Container vessels at Vancouver and Prince Rupert drive cryogenic fuel demand under Transport Canada's sulfur enforcement deadlines. The province's clean fuel regulations overlap with federal Clean Fuel Standard to accelerate terminal investment. Tilbury LNG facility and coastal barge networks concentrate supply capacity in the Lower Mainland and Vancouver Island corridors.
Ontario
Great Lakes shipping operators evaluate LNG conversion for St. Lawrence Seaway transit routes facing emission control area expansion. Environment and Climate Change Canada coordinates with Transport Canada on vessel pollution regulations affecting provincial waterways. Hamilton and Thunder Bay marine terminals explore truck-to-ship delivery systems for regional ferry and cargo fleets.
Quebec
Montreal and Quebec City port authorities assess LNG infrastructure for Atlantic container services connecting to European emission control areas. The province's carbon pricing mechanism intersects with federal marine fuel standards to create compliance cost differentials. Saguenay liquefaction projects position the region for potential bunkering supply expansion.
Alberta
Natural gas producers evaluate marine fuel pathways for captive liquefaction output beyond traditional pipeline markets. The Alberta Energy Regulator oversees upstream feedstock certification relevant to downstream carbon intensity scoring. Calgary-based energy traders develop supply contracts linking provincial gas fields to Pacific coast bunkering terminals.
Atlantic Canada
Halifax and Saint John ports serve as potential LNG bunkering nodes for Atlantic transshipment routes and Arctic shipping preparation. The Canadian Coast Guard fleet conversion creates stable demand for compliant marine fuel in regional waters. Newfoundland offshore supply vessels represent a specialized customer segment requiring cryogenic handling protocols.
Canada LNG Bunkering Market Competitive Environment
Global majors compete with regional champions across feedstock access and coastal infrastructure positioning. The market structures around integrated gas suppliers with captive liquefaction capacity, utility-backed terminal operators, and specialized marine fuel logistics providers. Strategic archetypes include upstream-integrated players leveraging supply chain control, downstream infrastructure specialists monetizing port access, and mobile delivery operators capturing dispersed vessel traffic. Competitive moves concentrate on terminal capacity expansion and ship-to-ship bunkering vessel deployment.
Among upstream-integrated suppliers, Shell PLC and TotalEnergies SE occupy positions exemplifying global feedstock-to-bunker supply chain control. FortisBC anchors the regional infrastructure tier through its Tilbury facility and marine loading systems. Seaspan Energy represents the specialized coastal logistics archetype with barge-based delivery networks serving Vancouver Island and mainland port clusters.
| Leading Market Players |
|---|
| Shell PLC |
| TotalEnergies SE |
| Harvey Gulf International Marine LLC |
| Nauticor GmbH & Co. KG |
| Gasum AS |
| FortisBC |
| Seaspan Energy |
| ENGIE |
| Gazprom Neft |
| Others |
Value Chain & Pricing Dynamics
Cryogenic storage capex for minus 162 degree Celsius tankage and regasification skids flows downstream through three-tier pricing structure across premium, standard, and economy levels, with British Columbia port authority green tariffs compressing margin capture for terminal operators serving transpacific container lines.
Pricing Analysis
Input-cost pass-through from Tilbury LNG feedstock pricing and ISO 20519 certification tiers shapes contract-based long-term offtake structures for major shipping lines. Price differentiation separates Science Based Targets initiative-compliant deliveries from standard bunker fuel transactions, with volume scale driving negotiation leverage for container operators. Cost compression in the truck-to-ship channel is intensifying because mobile cryogenic systems compete for ferry fleet contracts at secondary harbors. Fishing cooperatives exhibit highest price sensitivity due to seasonal operating patterns, while dual-fuel container vessels demonstrate lowest sensitivity given berthing priority rewards.
Supply Chain Analysis
Specialized cryogenic technician certification programs in Canada, South Korea, and Germany constrain workforce availability for minus 162 degree Celsius handling and boil-off gas management. The supply chain draws from western Canadian natural gas fields, Korean-built LNG bunkering vessels, and German-manufactured regasification skids. Single-source vulnerability concentrates at Tilbury facility for Pacific coast distribution, with limited backup liquefaction capacity. Distribution runs through integrated terminal networks for port-based delivery, barge-based coastal logistics for Vancouver Island clusters, and mobile truck-mounted systems for secondary harbors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada LNG bunkering market compounds steadily as Transport Canada's sulfur enforcement deadlines force fleet conversion timelines regardless of fuel price volatility.
For Market Incumbents: Acquire cryogenic bunkering vessel capacity to preempt ship-to-ship contract concentration by transpacific container lines. Fortify position against methane slip regulation uncertainty by investing in integrated vapor recovery systems at Tilbury and Prince Rupert terminals. Secure long-term throughput guarantees with Asia-North America trade lane operators before federal Clean Fuel Standard credit trading mechanisms mature. For New Entrants and Emerging Players: The premium-to-economy price gap in mobile bunkering services opens white-space at Vancouver Island secondary harbors lacking fixed loading arms. Target fishing cooperative clusters through seasonal contract structures that align with harvest cycles. Pursue truck-to-ship certification partnerships with FortisBC to leverage existing Tilbury feedstock access without terminal infrastructure investment. For Investors and Strategic Acquirers: Consolidation pressure builds where cryogenic technician scarcity and ISO 20519 interoperability gaps fragment service quality across Pacific terminals. The five-to-ten year viability window favors acquisition of coastal barge operators with established marine loading protocols and regulatory compliance track records. Watch federal methane venting standard resolution as the inflection signal triggering accelerated vessel conversion commitments.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Bunkering Vessel Deployment | Ship-to-ship capability at Vancouver and Prince Rupert captures Asia-North America container traffic seeking minimal port downtime. |
| Integrated Vapor Recovery Installation | Boil-off gas management unifies environmental compliance with cargo refrigeration energy balance for refrigerated container lines. |
| Mobile Truck-to-Ship Network Expansion | Cryogenic delivery systems extend LNG access to ferry fleets at Vancouver Island terminals lacking fixed infrastructure. |
| Clean Fuel Standard Credit Documentation | Carbon intensity scoring transparency attracts Science Based Targets initiative-committed shipping lines to Canadian Pacific ports. |
| Cryogenic Technician Training Program | Specialized certification capacity alleviates workforce constraints for minus 162 degree Celsius handling and regasification operations. |
Study Parameters
Multiple input streams — structured interviews with marine terminal operators, LNG supplier procurement leads, and Transport Canada regulatory affairs officers; secondary validation through Environment and Climate Change Canada filings, British Columbia port authority infrastructure disclosures, and IMO MARPOL Annex VI enforcement schedules; plus customs data on cryogenic equipment imports — were reconciled through bottom-up vessel fleet conversion modeling and top-down bunkering demand projection across the analysis window.
Data-stream reconciliation anchored volume and value outputs to segmented modeling across service type, delivery method, vessel class, and provincial regulatory framework throughout the forecast period. CAGRs were derived from infrastructure deployment timelines, sulfur enforcement deadline impacts, and dual-fuel engine commercialization curves. Forecast inputs incorporated Clean Fuel Standard credit trading mechanics and green tariff structure evolution at Vancouver and Prince Rupert.
Caveats apply where federal methane slip standards, Arctic shipping corridor development pace, or feedstock supply concentration at Tilbury could materially shift the outlook. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Digital Oilfield Solutions Market
Oil & Gas
Latin America Artificial Lift System Market
Oil & Gas
Iron Ore Mining Market
Oil & Gas
Oil and Gas Logistics Market
Oil & Gas
Microbial Enhanced Oil Recovery Market
Oil & Gas
Intelligent Well Completion Market
Oil & Gas
Open Hole Logging Services Market
Oil & Gas
Oil and Gas Fittings Market
Oil & Gas
HPHT Cubic Press Market
Oil & Gas
Blockchain in Oil and Gas Market
Oil & Gas
North America Hydraulic Fracturing Fluids Market
Oil & Gas
Colombia Oil and Gas Downstream Market
Oil & Gas
Oil and Gas Fabrication Market
Oil & Gas
Oil and Gas Swell Packers Market
Oil & Gas
Frac Tree Market
Oil & Gas
Desalter Market