
 Blowout Preventers (BOP) Market | 2026-2036
Blowout Preventers (BOP) Market Size, Share, and Industry Trends Forecast 2026-2036
Blowout Preventers (BOP) Market Outlook
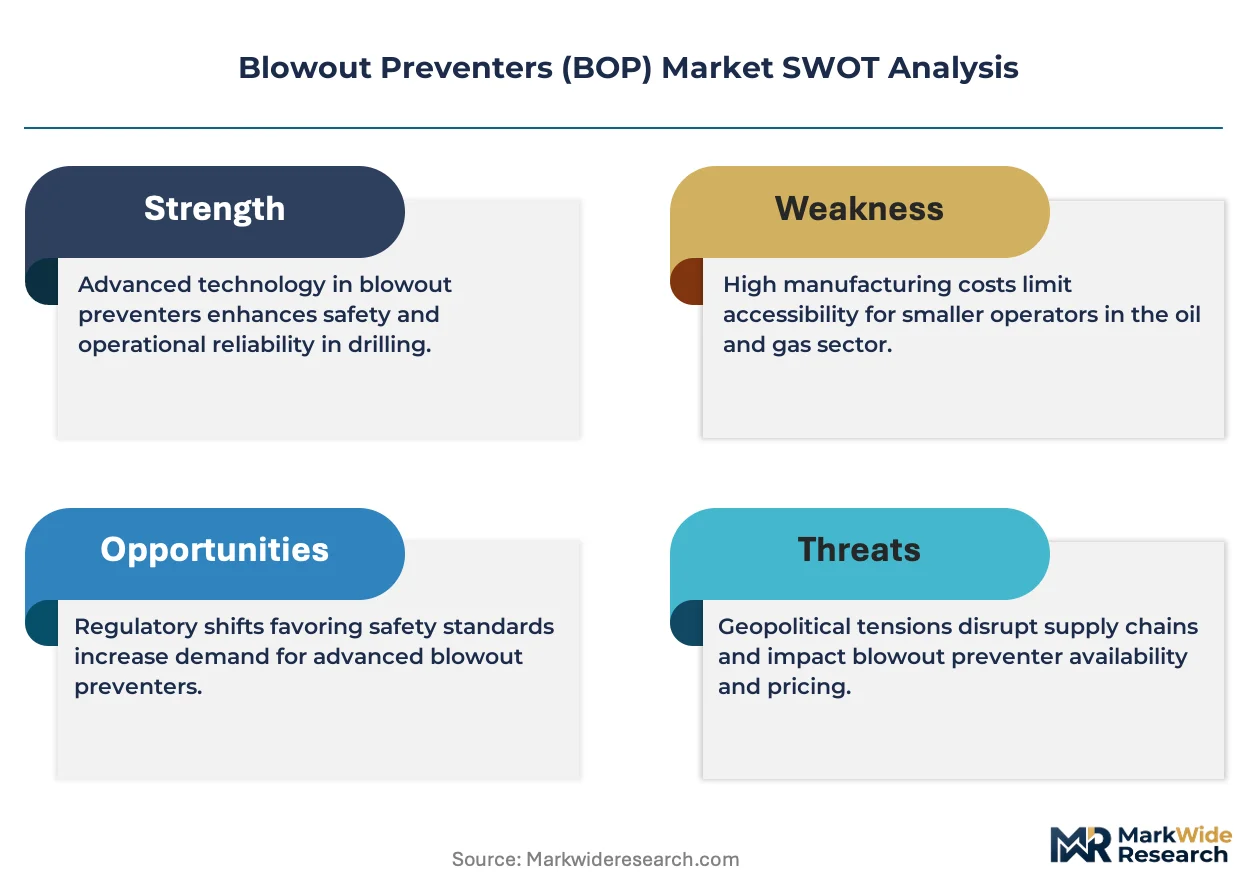
API 16A is decoupling legacy manufacturing from next-generation stack certification, forcing capital retooling across the supplier base. Baker Hughes Company leverages integrated pressure-control portfolios to sustain offshore contract flow. NOV Inc. anchors its position through vertical forging capabilities in ram BOP housings. Shandong Kerui Holding Group competes on cost-engineered annular units for onshore Chinese deployment.
Blowout preventers are high-pressure wellhead sealing devices rated typically to 15,000 psi, employing elastomer packers and forged steel rams to seal annular or pipe-to-bore interfaces during drilling or workover. Ram BOP and annular BOP configurations dominate capital allocation, with ram types commanding premium pricing for deepwater stacks while annular units penetrate shallow offshore and land markets. Hydraulic actuation systems represent the fastest-growing installation subset as drillers automate emergency disconnect sequences.
BSEE in the United States, NORSOK in Norway, and API standards collectively dictate pressure-testing frequencies, material traceability, and subsea stack redundancy requirements that inflate OEM compliance spending. China's SAMR enforces GB standard convergence with API for import substitution programs. Stakeholders must monitor regulatory divergence between North Sea well-control directives and Gulf of Mexico BOP recertification cycles as procurement specifications fragment across basins.
Market Dynamics
Deepwater exploration economics are forcing rig operators to consolidate BOP stack specifications around fewer certified configurations, compressing supplier engineering bandwidth and amplifying procurement leverage for supermajors.
Growth Catalysts
- API 16A recertification waves:BSEE mandates in the US Gulf of Mexico are accelerating replacement cycles for legacy ram BOP stacks, creating sustained demand for forged-housing fabricators with pressure-testing capabilities.
- Subsea automation protocols:Hydraulic actuation systems with integrated emergency disconnect sequences are displacing manual intervention models in Norwegian North Sea drilling contracts.
- Chinese import substitution:SAMR enforcement of GB standard convergence with API specifications is redirecting procurement toward domestic annular BOP producers for onshore shale development.
Market Restraints
- Alloy steel input volatility:Forged ram housing production depends on specialized high-chromium steel grades subject to mining supply concentration in South Africa and Kazakhstan.
- Fabrication cluster lock-in:US Gulf Coast and Stavanger-region suppliers control 80% of deepwater stack assembly capacity, creating geographic concentration risk for non-integrated operators.
- Elastomer packer degradation limits:Current nitrile and hydrogenated nitrile compounds face temperature-pressure envelopes that restrict ultra-deepwater deployment beyond 15,000 psi rated systems.
Strategic Opportunities
- Pre-salt Brazil expansion:Petrobras drilling programs in the Santos Basin are specifying dual-ram BOP configurations that exceed current South American supplier certification levels.
- Digital twin integration:Real-time pressure monitoring and predictive maintenance algorithms are converging with subsea BOP control systems to reduce unplanned stack pulls.
- Modular stack architecture:Standardized annular-ram interface specifications are enabling faster field reconfiguration for jack-up rigs migrating between North Sea and West African contracts.
Industry Challenges
- Weld inspector certification bottlenecks:API and ASME-qualified ultrasonic testing technicians are concentrated among a handful of third-party verification firms, extending delivery timelines for forged housing orders.
- Legacy control system integration:Newer hydraulic multiplex units must interface with 1990s-era surface control pods on retrofitted semisubmersibles, complicating automation rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blowout Preventers (BOP) Market |
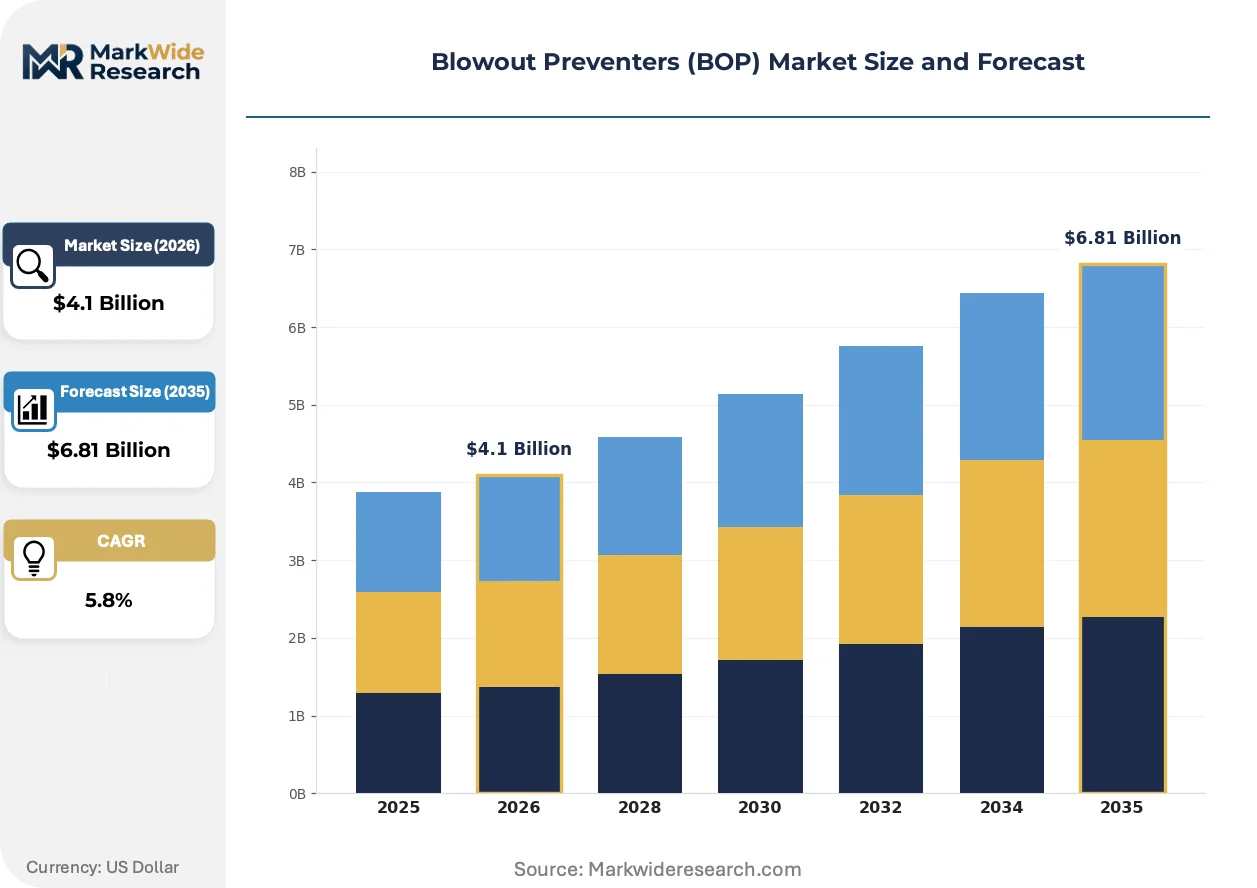
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
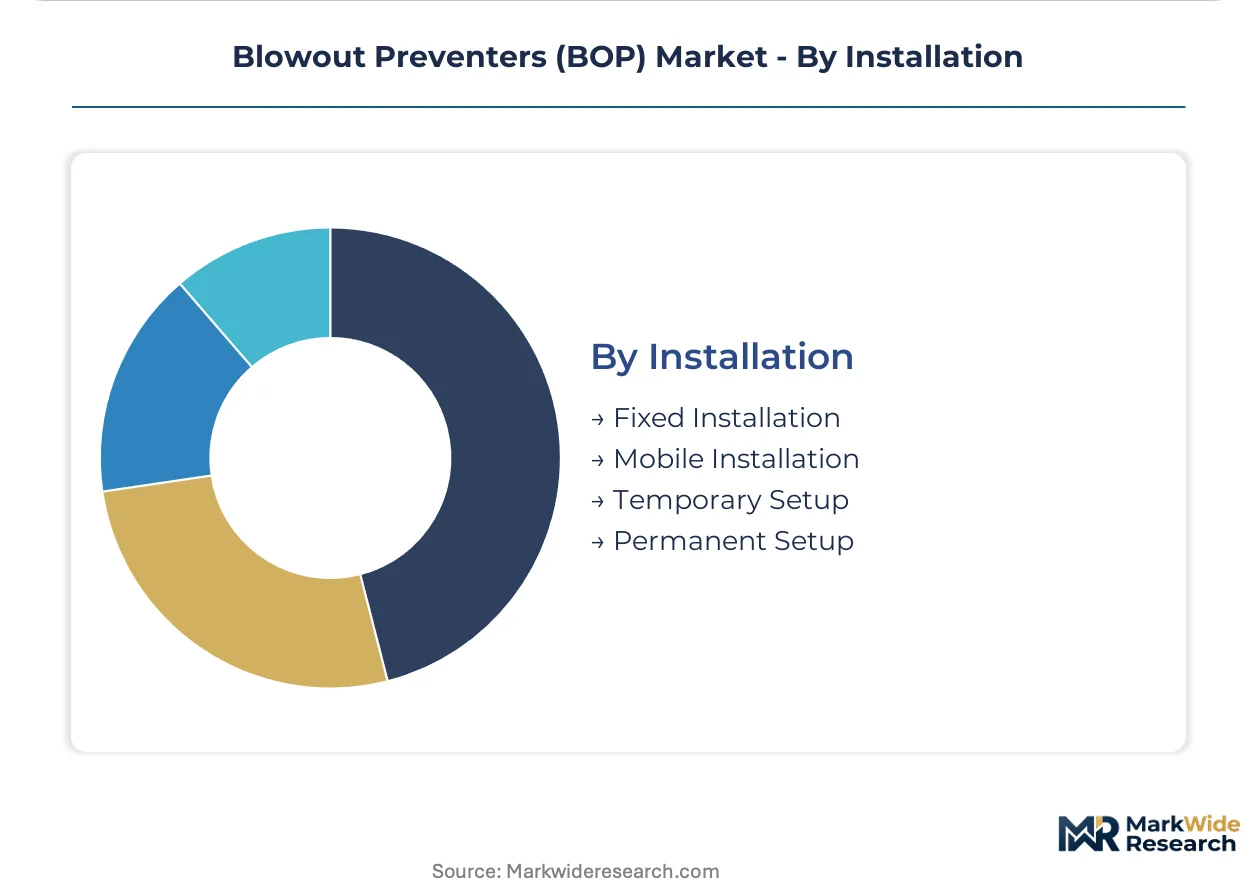
| Segmentation | Type: Ram BOP, Annular BOP, Hydraulic BOP, Stack BOP Application: Offshore Drilling, Onshore Drilling, Workover Operations, Exploration Activities End User: Oil & Gas Companies, Drilling Contractors, Service Providers, Engineering Firms Installation: Fixed Installation, Mobile Installation, Temporary Setup, Permanent Setup |
| Companies Covered | Baker Hughes Company, SLB, NOV Inc., Halliburton Company, Weatherford International, TechnipFMC plc, Aker Solutions, Shandong Kerui Holding Group, Cameron International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blowout Preventers (BOP) Market Strategic Shifts
Subsea pressure control is undergoing a transition from mechanical redundancy to sensor-integrated predictive systems, compressing the traditional divide between BOP hardware and drilling automation software layers.
Shear-seal ram technology is unifying pipe-cutting and annular-sealing functions into single-actuator configurations. Deepwater drillers in the US Gulf of Mexico are specifying these units for high-pressure high-temperature wells where conventional sequential ram closure risks wellbore communication. This unification is compressing stack height requirements and enabling slimmer subsea BOP profiles that reduce riser tensioner loads.
REACH substance restrictions in Europe are phasing out legacy elastomer formulations containing short-chain chlorinated paraffins. BOP packer manufacturers serving North Sea contracts are reformulating hydrogenated nitrile compounds to maintain pressure ratings under revised ECHA authorization timelines. Annular BOP units with compliant seal materials are commanding procurement preference in Norwegian drilling tenders.
Integrated service contracting is displacing component-level BOP procurement for floating rig fleets. Supermajors are bundling stack maintenance, recertification, and emergency response into multi-year agreements with pressure-control specialists. This consolidation is most visible in UK and Netherlands offshore sectors where drilling contractors face BSEE-equivalent NORSOK well-control audit frequencies.
Blowout Preventers (BOP) Market Segmentation
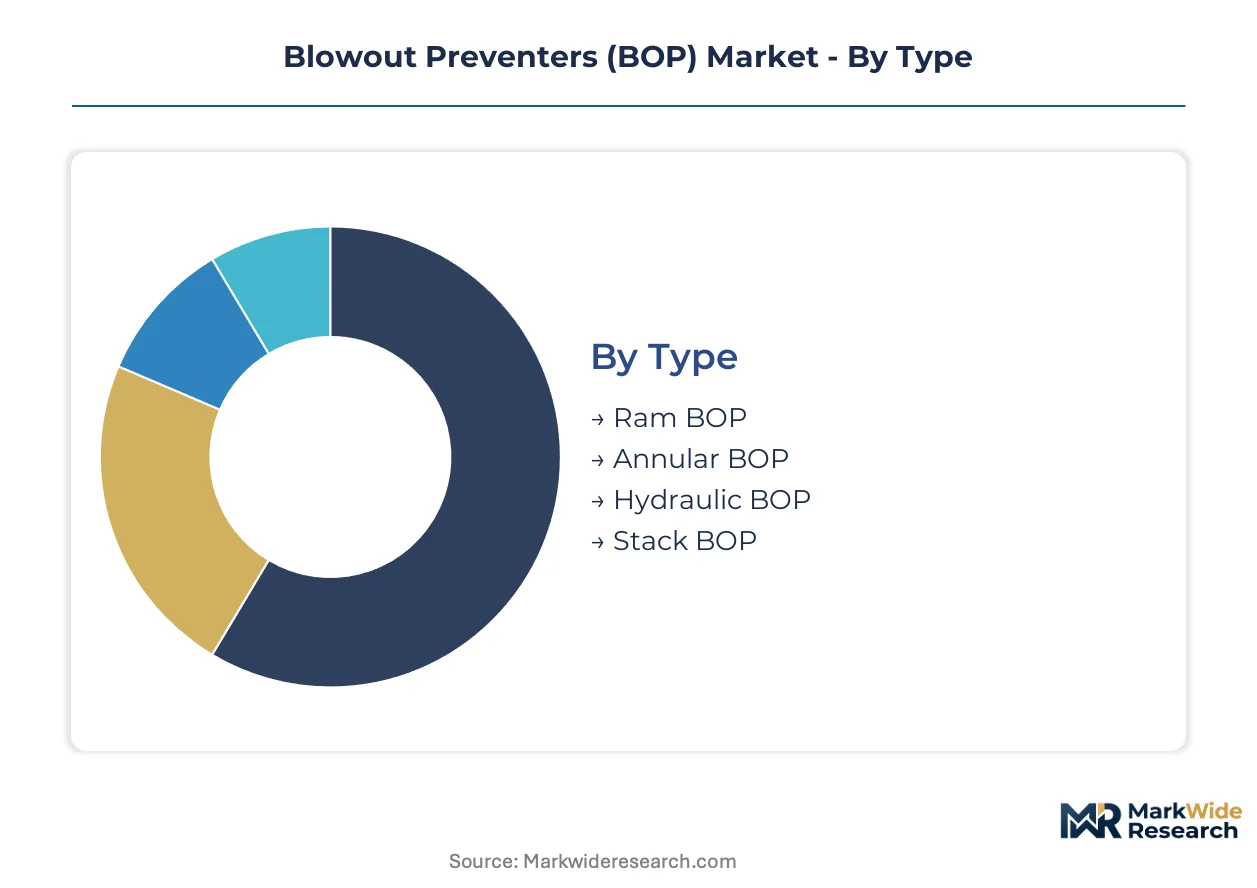
BOP procurement specifications fragment across pressure ratings, deployment environments, and regulatory jurisdictions. Certification requirements from BSEE, NORSOK, and API 16A create tiered compliance burdens that reshape supplier eligibility and end-user sourcing patterns.
Type:
API 16A certification tiers separate legacy-qualified fabricators from next-generation stack providers, with pressure-testing protocols varying significantly by BOP configuration.
- Ram BOP:Forged steel housings with dual-ram configurations seal pipe-to-bore interfaces through vertical rams. Deepwater stacks in the US Gulf of Mexico specify these units for 15,000 psi HPHT wells, with BSEE mandating shear-seal capabilities for new procurements.
- Annular BOP:Elastomer packer elements seal around irregular pipe geometries and open-hole conditions. Onshore Chinese shale development favors these units for cost-engineered deployment, with SAMR GB standard convergence redirecting procurement toward domestic producers.
- Hydraulic BOP:Automated actuation systems enable emergency disconnect sequences without manual intervention. Norwegian North Sea contracts specify these for floating rig integration.
- Stack BOP:Integrated multi-component assemblies combine ram and annular functions in subsea configurations. Pre-salt Brazil drilling programs demand dual-ram stack specifications exceeding regional supplier certification levels.
Ram BOP sits at the top of the volume ranking, with hydraulic BOP climbing the fastest.
Application:
Cost tiers stratify sharply between deepwater offshore requiring redundant subsea stacks and onshore land rigs specifying single annular units.
- Offshore Drilling:Subsea BOP stacks with integrated hydraulic multiplex controls serve floating rig fleets. US Gulf Coast fabrication clusters dominate deepwater assembly capacity, with supermajors consolidating procurement around fewer certified configurations.
- Onshore Drilling:Land-based jack-up and pad drilling operations specify lighter annular BOP units. Chinese shale basins drive volume through import substitution programs aligned with GB-API convergence.
- Workover Operations:Well intervention and recompletion activities require portable BOP stacks with rapid rig-up capabilities. Modular architectures enable faster field reconfiguration for rigs migrating between contracts.
- Exploration Activities:Wildcat drilling in frontier basins demands high-specification stacks with predictive maintenance integration. Digital twin convergence reduces unplanned stack pulls in remote deployments.
Offshore drilling commands the premium pricing tier, while onshore drilling delivers the steepest expansion trajectory.
End User:
Customer type determines contract structure, with integrated service agreements displacing component-level procurement for fleet operators.
- Oil & Gas Companies:Supermajors bundle stack maintenance, recertification, and emergency response into multi-year pressure-control agreements. UK and Netherlands offshore sectors show this consolidation most visibly.
- Drilling Contractors:Fleet operators face BSEE-equivalent NORSOK audit frequencies that inflate compliance spending. Third-party verification bottlenecks extend delivery timelines for forged housing orders.
- Service Providers:Specialist pressure-control firms capture aftermarket recertification waves. API 16A recertification mandates accelerate replacement cycles for legacy ram stacks.
- Engineering Firms:Design contractors specify stack configurations for newbuild rigs and retrofit projects. Legacy control system integration complicates automation rollouts on 1990s-era semisubmersibles.
Oil & gas companies anchor procurement volume, with service providers gaining share fastest through aftermarket specialization.
Installation:
Supply concentration in US Gulf Coast and Stavanger-region clusters creates geographic lock-in for permanent subsea installations.
- Fixed Installation:Permanent subsea stacks on production platforms require 20-year design life with predictive maintenance protocols. REACH substance restrictions phase out legacy elastomer formulations in North Sea contracts.
- Mobile Installation:Drillship and semisubmersible fleets specify rapidly deployable stacks with standardized interfaces. Modular annular-ram specifications enable faster reconfiguration for rigs migrating between West African and North Sea contracts.
- Temporary Setup:Exploration drilling and workover campaigns use rental BOP stacks with short-term certification cycles. Alloy steel input volatility from South African and Kazakh mining concentration affects rental fleet availability.
- Permanent Setup:Production platform BOPs integrate with subsea production control systems. Shear-seal ram technology compresses stack height requirements and reduces riser tensioner loads.
Fixed installation dominates capital allocation, with mobile installation expanding most quickly through floating rig fleet renewal.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized welding inspectors and forged-housing engineers concentrate in Houston, Stavanger, and Singapore, anchoring the three dominant fabrication clusters for subsea pressure-control equipment.
United States
Deepwater drilling in the Gulf of Mexico drives demand for 15,000 psi ram BOP stacks with shear-seal capabilities. BSEE mandates API 16A recertification cycles that accelerate replacement procurement from legacy fabricators. Houston-Galveston fabrication yards control the majority of domestic deepwater stack assembly capacity.
Norway
North Sea floating rig fleets specify hydraulic multiplex BOP controls with automated emergency disconnect sequences. NORSOK well-control directives enforce pressure-testing frequencies that exceed Gulf of Mexico baselines. Stavanger-region suppliers dominate subsea stack integration for Norwegian drilling contractors.
Brazil
Pre-salt Santos Basin exploration programs demand dual-ram BOP configurations exceeding regional certification thresholds. ANP regulatory frameworks align with API standards while requiring localized content commitments. Rio de Janeiro fabrication clusters struggle to meet Petrobras specifications for ultra-deepwater stacks.
China
Onshore shale development in Sichuan and Xinjiang basins favors cost-engineered annular BOP units for pad drilling operations. SAMR enforces GB standard convergence with API specifications to redirect procurement toward domestic producers. Shandong Province forging facilities supply ram housings for both domestic deployment and export markets.
United Arab Emirates
Offshore expansion in the Zakum and Umm Shaif fields creates demand for high-specification subsea stacks with predictive maintenance integration. ADNOC technical standards incorporate API 16A with supplementary regional requirements for H2S service environments. Dubai-Jebel Ali fabrication zones serve as logistics hubs for Middle East and East African drilling contracts.
Blowout Preventers (BOP) Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered certification levels. The supplier base concentrates around three structural layers: integrated oilfield service majors with full pressure-control portfolios, forging-centric equipment fabricators with captive metallurgy capabilities, and regional cost-engineered producers serving onshore markets. Strategic moves center on API 16A certification acquisition and emergency-response service bundling.
Within the integrated-service tier, Baker Hughes Company and SLB exemplify full-stack pressure-control positioning through combined hardware and aftermarket service offerings. NOV Inc. anchors the forging-specialist archetype with vertical capabilities in ram BOP housing production. Shandong Kerui Holding Group occupies the cost-engineered domestic producer position for Chinese onshore deployment.
| Leading Market Players |
|---|
| Baker Hughes Company |
| SLB |
| NOV Inc. |
| Halliburton Company |
| Weatherford International |
| TechnipFMC plc |
| Aker Solutions |
| Shandong Kerui Holding Group |
| Cameron International |
| Others |
Value Chain & Pricing Dynamics
REACH substance restrictions on legacy elastomer formulations gate qualified supply for North Sea contracts while compressing margins for non-compliant fabricators seeking premium-tier pricing access. Buyers face bifurcated procurement landscapes where certified hydrogenated nitrile packer producers command service premiums against cost-engineered annular units serving Chinese shale basins.
Pricing Analysis
Bundled service contracts versus unbundled component procurement split pricing models across integrated pressure-control agreements and standalone stack sales. Three-tier pricing structure across API 16A-certified premium stacks, legacy-recertified standard units, and GB-converged economy annular BOPs differentiates offerings by certification grade and after-sales service depth. Cost compression in economy tiers intensifies because SAMR-directed import substitution floods Chinese onshore markets with domestic annular production. Drilling contractors show highest price sensitivity for land-based jack-up fleets, while supermajors absorb premiums for deepwater shear-seal configurations.
Supply Chain Analysis
Single-source vulnerability sits with South African and Kazakh mining concentration for high-chromium alloy steel grades essential to forged ram housing production. Forged-housing fabrication draws from Houston-Galveston, Stavanger-region, and Singapore clusters, with specialized welding inspectors concentrated among third-party verification firms in these geographies. Regulatory restriction risk manifests through API and ASME-qualified ultrasonic technician bottlenecks extending forged housing delivery timelines. Distribution runs through OEM-direct channels for deepwater stacks and rental-service intermediaries for temporary exploration deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion potential through predictive maintenance software integration that shifts revenue from transactional hardware sales toward recurring service streams.
For Market Incumbents: Extend API 16A certification coverage into shear-seal ram configurations before BSEE mandates harden competitive barriers. Deepen backward integration into captive forging capacity to defend against alloy steel input volatility from South African supply concentration. Acquire specialized third-party verification firms to eliminate weld inspector certification bottlenecks threatening delivery timelines. For New Entrants and Emerging Players: Digital-channel routes through drilling automation software partnerships offer lower-friction entry than hardware fabrication. Target temporary rental stack segments in West African exploration markets where modular architecture specifications reduce certification burden. Pursue white-label annular BOP supply agreements with Chinese domestic producers seeking GB-API convergence compliance. For Investors and Strategic Acquirers: Roll-up economics work for aftermarket service specialists because API 16A recertification waves create predictable revenue visibility across fragmented regional maintenance providers. Focus acquisition screening on firms with emergency-response service bundling capabilities and NORSOK audit compliance infrastructure. Watch BSEE enforcement intensity as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Shear-Seal Ram Certification Investment | BSEE mandates for Gulf of Mexico HPHT wells lock in premium-tier positioning. |
| Predictive Maintenance Platform Development | Digital twin integration with subsea control systems reduces unplanned stack pulls. |
| Backward Integration into Forging Capacity | Captive ram housing production insulates against high-chromium steel price volatility. |
| Emergency Response Service Bundling | Multi-year pressure-control agreements displace component-level procurement in UK-Netherlands sectors. |
| GB-API Convergence Compliance Program | SAMR-aligned annular BOP specifications unlock Chinese onshore shale procurement flows. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions with drilling contractors, pressure-control procurement leads at supermajors, API certification auditors, and subsea stack maintenance directors informed demand-side dynamics. Secondary validation drew from BSEE incident databases, NORSOK standard revisions, ANP regulatory filings, and SAMR GB standard convergence documentation. Bottom-up segment sizing and top-down macro triangulation anchored volume estimates.
Segment-weighting approaches modeled BOP configurations, pressure rating tiers, installation types, and regional regulatory clusters across the projection horizon. CAGRs derived from fitted growth curves against disclosed supermajor capital expenditure patterns and rig fleet renewal schedules. Forecast inputs incorporated deepwater exploration economics, elastomer packer degradation limits, and hydraulic actuation adoption curves.
The model assumes a particular technology adoption path; alternative pathways for all-electric BOP actuation would alter the outlook. Forecasts reflect assumptions about BSEE enforcement continuity, NORSOK audit frequency stability, and Petrobras pre-salt drilling commitment levels. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Refinery Maintenance Services Market
Oil & Gas
Asia-Pacific Natural Gas Market
Oil & Gas
Underwater Monitoring System for Oil and Gas Market
Oil & Gas
Sensors in Oil and Gas Market
Oil & Gas
United States Oil and Gas Upstream Market
Oil & Gas
Asia-Pacific Intelligent Pigging Market
Oil & Gas
Sudan Oil and Gas Market
Oil & Gas
Whipstocks Market
Oil & Gas
LNG Storage Tank Market
Oil & Gas
Middle East and Africa Coiled Tubing Market
Oil & Gas
Kuwait Oil and Gas Market
Oil & Gas
Global Seismic Survey Market
Oil & Gas
Turkmenistan Oil and Gas Market
Oil & Gas
GCC and North Africa Coiled Tubing Market
Oil & Gas
Digital Drilling Rigs Market
Oil & Gas
Land Drilling Rig Market