
 Downhole Tractor Market | 2026-2036
Downhole Tractor Market Size, Share, and Industry Trends Forecast 2026-2036
Downhole Tractor Market Analysis
The Middle East is rewriting competitive dynamics for downhole tractor deployment as Saudi Arabia and the UAE expand unconventional well intervention capacity. Weatherford leverages integrated drilling and evaluation portfolios to sustain service density across Gulf state markets. NOV anchors regional supply chains through localized manufacturing and aftermarket support infrastructure. Baker Hughes competes on high-temperature electric tractor architectures designed for extended-reach laterals.
A downhole tractor is a motorized conveyance system that traverses deviated or horizontal wellbores using wheeled or tracked drive mechanisms, typically rated for temperatures exceeding 150°C and pressures above 15,000 psi, to deploy logging, perforating, or intervention tools to target depth. Electric tractors lead product type demand due to precise speed control and reduced fluid contamination risk in sensitive formations. Coiled tubing integration represents the fastest-expanding technology segment as operators seek to eliminate wireline depth limitations in extended-reach wells. Service providers dominate end user procurement, though independent operators are gaining purchasing influence through rental and performance-based contracting models.
API Q2 and ISO 13628-7 standards govern mechanical design verification and pressure containment testing for downhole tractors sold into US and international markets. Saudi Arabia's national oil company mandates Saudi Aramco Engineering Standards compliance for all intervention tools deployed in its fields, creating a parallel certification pathway. Stakeholders must monitor regulatory divergence between American Petroleum Institute frameworks and emerging national standards in Middle Eastern producing regions to avoid market access friction.
Market Dynamics
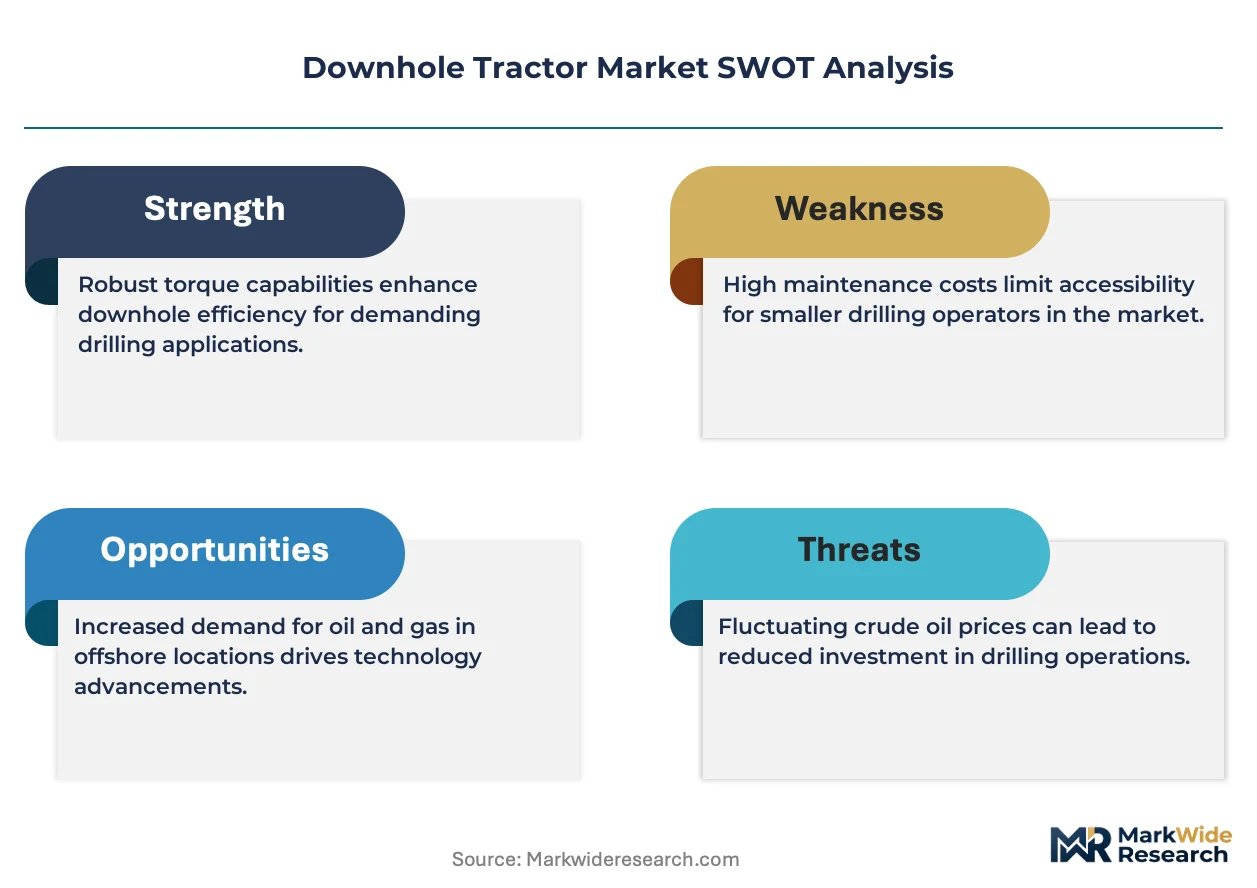
The downhole tractor market is being fundamentally restructured by the migration from wireline conveyance to coiled tubing-integrated systems in extended-reach laterals, compressing deployment timelines and expanding addressable well geometries beyond historical mechanical limits.
Growth Catalysts
- Permian Basin lateral extension:West Texas and southeastern New Mexico operators are pushing laterals past 15,000 feet, creating mechanical conveyance gaps that tractors fill.
- API Q2 certification tightening:Enhanced mechanical design verification requirements are filtering out marginal equipment suppliers and consolidating procurement toward certified vendors.
- Electric tractor precision control:Formation-sensitive zones in unconventional reservoirs demand speed-modulated deployment that hydraulic systems cannot deliver.
Market Restraints
- High-temperature electronics sourcing:Components rated above 175°C face concentrated supply from Japanese and German specialty semiconductor foundries.
- Saudi Aramco parallel standards:Engineering Standards compliance creates dual certification burdens for manufacturers serving both US and Saudi markets.
- Coiled tubing unit availability:Tractor deployment depends on scarce mobile coiled tubing spreads, creating bottlenecked activation capacity.
Strategic Opportunities
- UAE unconventional pilot programs:Adnoc's tight gas and shale appraisal campaigns are opening first-mover positioning for intervention technology specialists.
- Performance-based rental contracting:Independent operators in the Delaware sub-basin are adopting meterage-fee structures that shift capital burden to service providers.
- ISO 13628-7 and API Q2 convergence:Emerging alignment between American and international standards is reducing duplicate testing costs for multi-territory vendors.
Industry Challenges
- Mechatronics technician scarcity:Cross-functional expertise combining downhole mechanics, electronics, and software diagnostics remains concentrated among legacy wireline service engineers.
- Extended certification timelines:Saudi Aramco field validation protocols add 8-14 months to product qualification for Middle East deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Downhole Tractor Market |
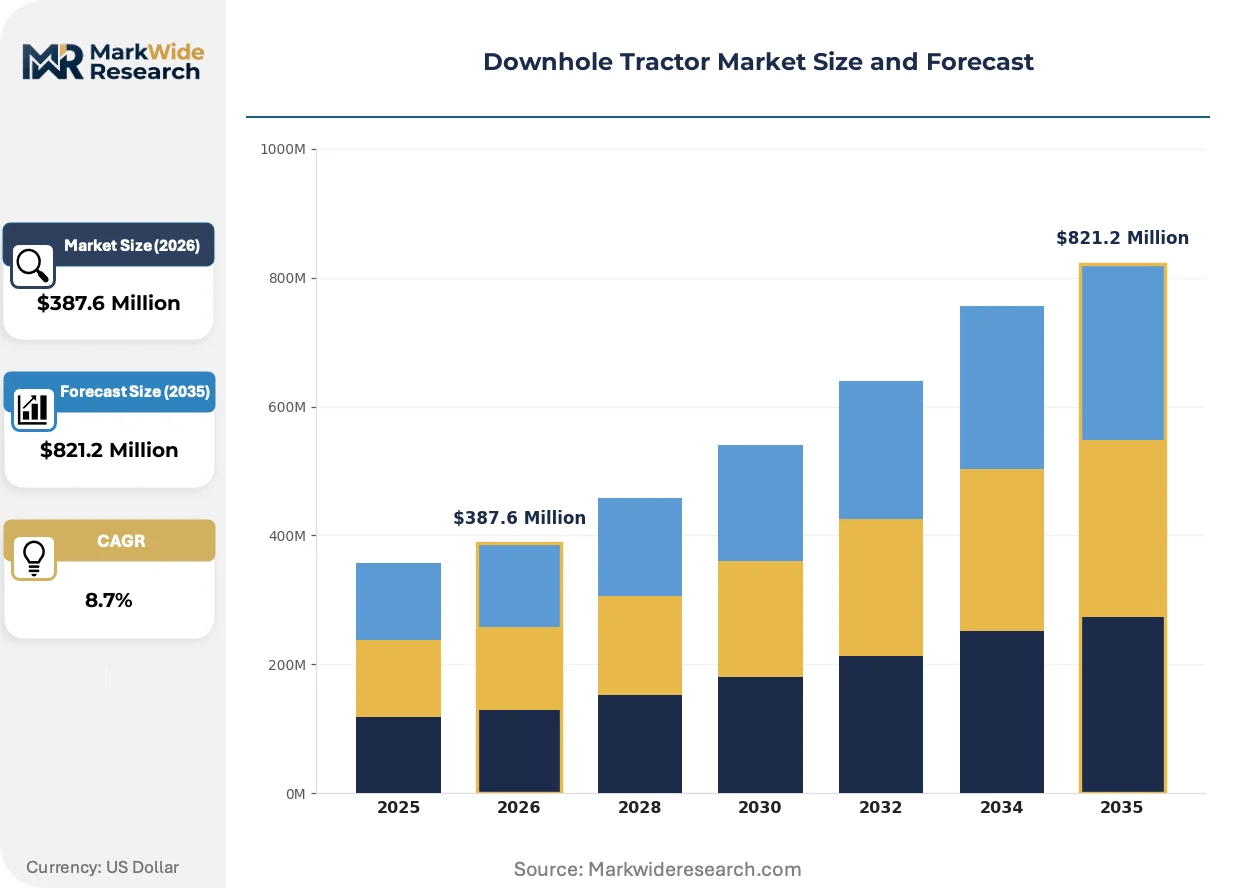
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Tractors, Hydraulic Tractors, Mechanical Tractors, Hybrid Tractors Technology: Coiled Tubing, Direct Drive, Push-Pull, Torque Control End User: Oil & Gas Companies, Service Providers, Independent Operators, Exploration Firms Application: Well Intervention, Drilling, Production Enhancement, Maintenance |
| Companies Covered | Weatherford, NOV, Schlumberger, Hunting Energy Services, Global Technology and Innovation, Halliburton, Welltec, Neo Oiltools, Baker Hughes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Downhole Tractor Market Emerging Trajectories
Downhole tractor technology is undergoing platform-level transformation as operators demand conveyance systems that bridge the gap between wireline economics and drilling-grade reliability in tortuous wellbores.
Electric tractor architectures are migrating from niche high-temperature applications to standard deployment across Permian and Eagle Ford laterals. Operators running multistage perforating strings in 12,000-foot laterals have adopted battery-powered tractors as default conveyance. This shift is compressing market space for hydraulic tractor variants that cannot deliver precise speed modulation through variable-dogleg sections.
ISO 13628-7 pressure containment testing protocols are tightening verification requirements for subsea-rated tractor systems. Manufacturers must now document fatigue life across 500+ pressure cycles rather than single-event qualification. Gulf of Mexico deepwater projects and North Sea high-pressure high-temperature wells are driving compliance investment, with vendors restructuring quality assurance departments to capture third-party witnessed testing documentation.
Rental fleet utilization models are displacing direct equipment purchases among independent Permian operators. Capital-constrained producers in the Midland and Delaware sub-basins are contracting tractor services on day-rate or meterage-fee structures rather than owning conveyance assets. This behavioral shift concentrates fleet ownership among service companies with balance sheet capacity for 50+ unit inventories and regional maintenance infrastructure.
Downhole Tractor Market Segmentation
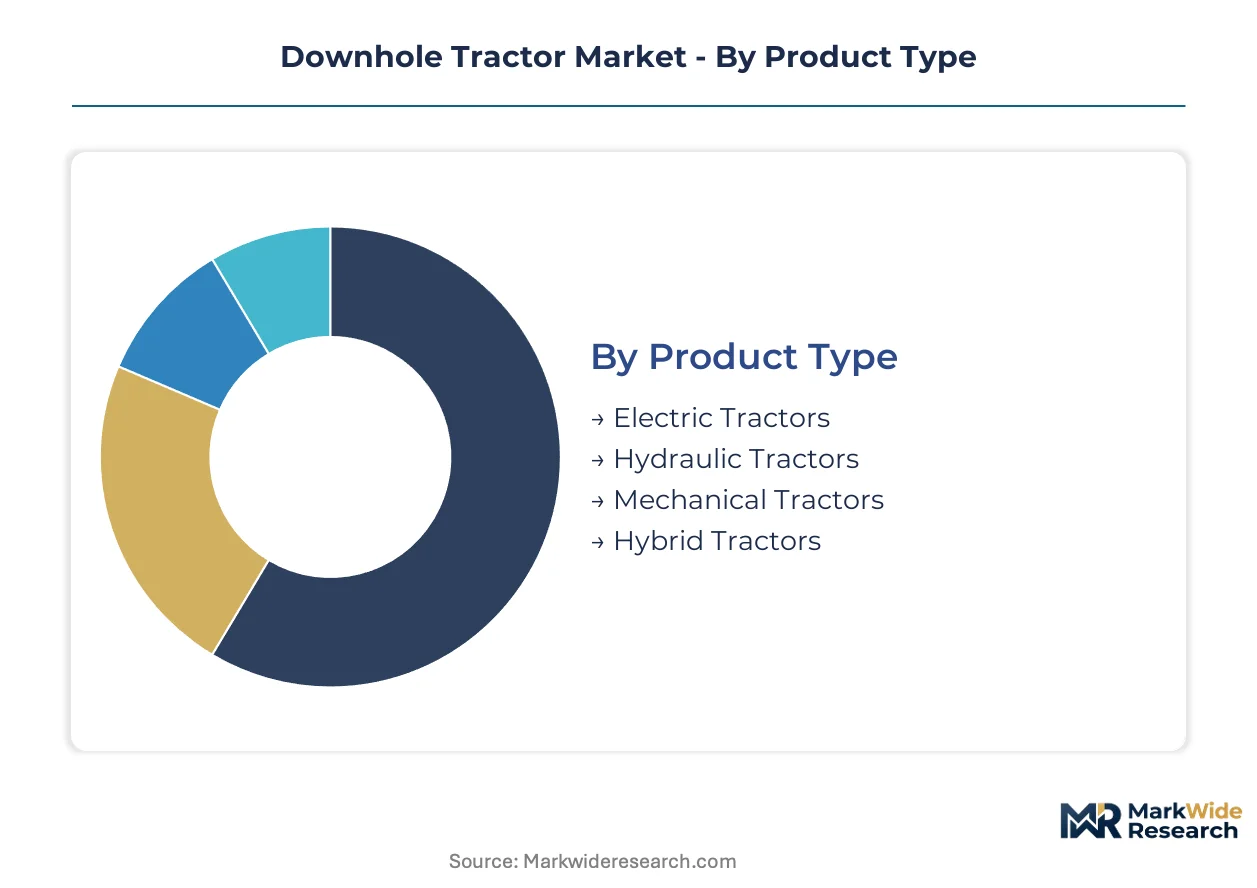
Segmentation in the downhole tractor market reveals distinct procurement patterns across powertrain architectures and deployment technologies. Equipment replacement cycles vary dramatically between electric and mechanical systems, directly influencing fleet planning decisions for service providers and operators.
Product Type:
Electric tractors command the shortest replacement cycles due to electronics degradation in high-temperature wellbores, while mechanical tractors persist longest in low-complexity vertical applications.
- Electric Tractors:Battery-powered drive systems with precise speed modulation rated above 150°C operating temperatures. Demand concentrates in Permian Basin extended-reach laterals where formation-sensitive zones require controlled deployment speeds that hydraulic architectures cannot achieve. API Q2 certification requirements filter marginal suppliers and consolidate procurement toward vendors with witnessed testing documentation.
- Hydraulic Tractors:Fluid-pressure drive mechanisms utilizing wellbore hydrostatic pressure for propulsion in deviated sections. Operators in mature Gulf of Mexico fields specify these systems for high-pull force applications where electric motor torque limits create mechanical constraints.
- Mechanical Tractors:Spring or weight-actuated drive systems for shallow vertical wellbores with minimal dogleg severity.
- Hybrid Tractors:Dual-mode architectures combining electric precision with hydraulic power density for high-temperature extended-reach applications.
Electric tractors anchor the volume base while hybrid tractors gain share at the steepest rate as operators seek to bridge precision control with power density requirements.
Technology:
Technology selection tracks directly to wellbore geometry complexity, with coiled tubing integration commanding premium positioning in tortuous lateral sections where wireline conveyance fails.
- Coiled Tubing:Continuous conduit deployment eliminating wireline depth limitations through surface-fed tubing integration. Saudi Aramco unconventional pilot programs specify coiled tubing-tractor combinations for tight gas appraisal campaigns in the Jafurah Basin, creating first-mover positioning for integrated system specialists.
- Direct Drive:Motor-to-wheel power transmission without intermediate gearing for simplified maintenance profiles. North Sea operators favor direct drive architectures in subsea intervention contexts where ISO 13628-7 pressure cycling requirements demand reduced component count to minimize fatigue failure modes.
- Push-Pull:Reciprocating motion systems for highly deviated wellbores with excessive friction coefficients.
- Torque Control:Real-time downhole torque monitoring with automated speed adjustment to prevent stuck-pipe incidents.
Coiled tubing integration captures the highest value per deployment while torque control systems expand most quickly as real-time monitoring becomes standard in unconventional basins.
End User:
Procurement authority concentrates among service providers with balance sheet capacity for fleet ownership, though contracting structures are shifting capital burden through performance-based rental models.
- Oil & Gas Companies:Integrated operators with captive intervention divisions specifying equipment for proprietary well portfolios. National oil companies in the UAE and Saudi Arabia maintain direct procurement relationships for high-volume unconventional development programs, bypassing third-party service layers for critical path operations.
- Service Providers:Specialist intervention companies with regional fleet infrastructure and maintenance capabilities. Weatherford and NOV dominate service provider procurement through integrated drilling-evaluation portfolios and localized manufacturing support.
- Independent Operators:Capital-constrained producers in the Delaware sub-basin adopting meterage-fee contracting rather than asset ownership.
- Exploration Firms:Appraisal-phase operators with intermittent intervention requirements driving spot-market rental demand.
Service providers anchor the volume base while independent operators gain purchasing influence fastest through rental and performance-based contracting adoption.
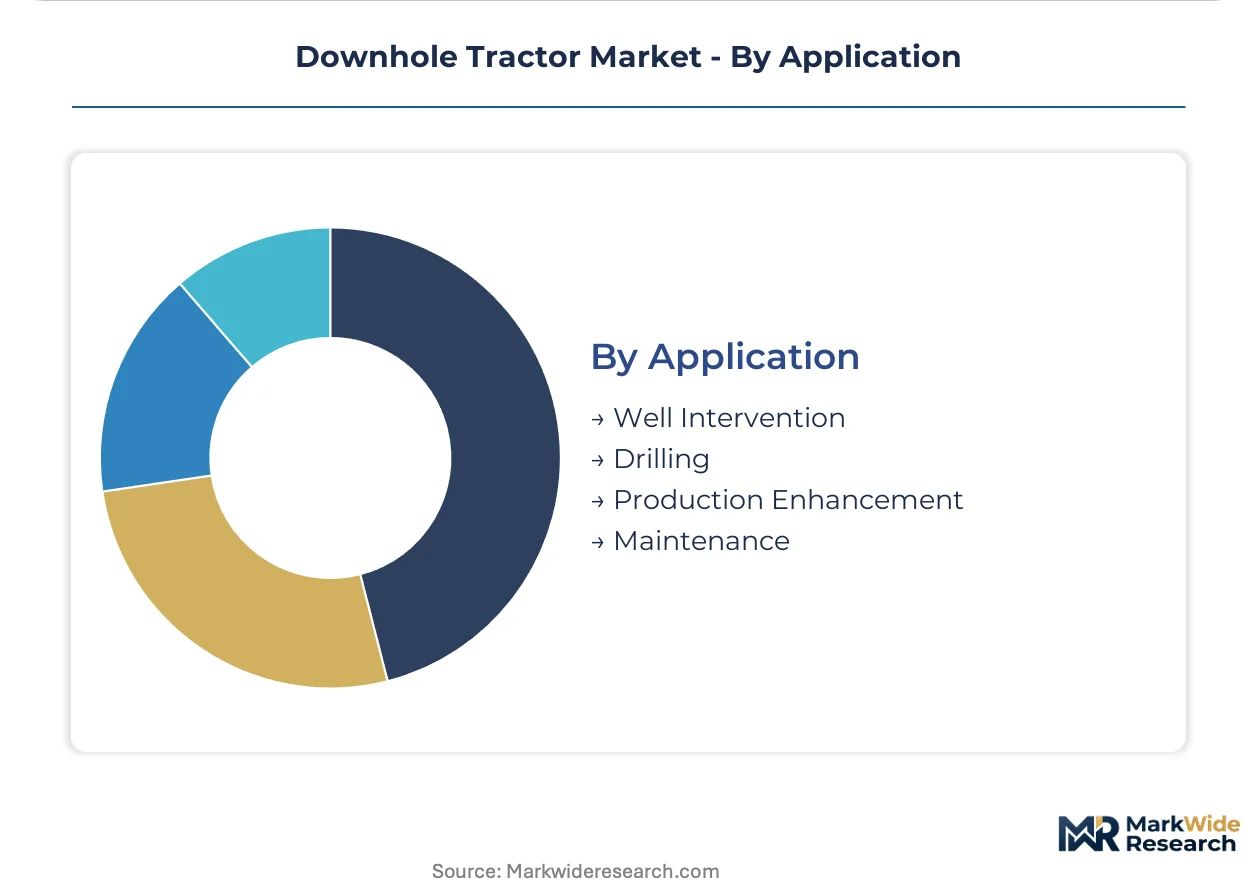
Application:
Application mix reflects basin maturity profiles, with well intervention dominating deployment hours in established producing regions while drilling support expands in frontier unconventional plays.
- Well Intervention:Logging, perforating, and remedial operations in existing wellbores. West Texas and southeastern New Mexico operators push laterals past 15,000 feet, creating mechanical conveyance gaps that tractors fill for multistage perforating string deployment.
- Drilling:Conveyance of measurement-while-drilling and logging-while-drilling tools in extended-reach sections. Adnoc tight gas appraisal campaigns in the UAE specify tractor-assisted drilling for pilot hole sections where conventional drill pipe limitations constrain reach.
- Production Enhancement:Stimulation tool deployment and artificial lift optimization in mature fields.
- Maintenance:Routine inspection and integrity verification in aging well stock.
Well intervention anchors the volume base while drilling applications expand most quickly as extended-reach laterals exceed mechanical limits of conventional conveyance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin pipeline network and Midland-anchored logistics corridors sustain North American dominance in downhole tractor deployment density. West Texas and southeastern New Mexico field operations generate concentrated demand for extended-reach conveyance systems.
United States
Permian Basin operators push laterals past 15,000 feet, creating mechanical conveyance gaps that electric tractors fill for multistage perforating deployment. API Q2 certification requirements filter marginal suppliers and consolidate procurement toward witnessed-testing vendors. Midland-Odessa service company clusters maintain the densest regional fleet infrastructure for intervention tool deployment.
Saudi Arabia
Jafurah Basin tight gas appraisal campaigns specify coiled tubing-tractor combinations for unconventional well intervention. Saudi Aramco Engineering Standards mandate parallel certification pathways that add 8-14 months to product qualification timelines. Dhahran-based intervention technology specialists anchor regional supply relationships for national oil company procurement.
United Arab Emirates
Adnoc tight gas and shale pilot programs in Abu Dhabi emirate open first-mover positioning for integrated system providers. MOHAP equipment import regulations govern downhole tool registration for onshore and offshore deployment. Ruwais industrial zone fabrication capabilities support localized aftermarket service infrastructure development.
Norway
North Sea high-pressure high-temperature subsea wells drive ISO 13628-7 pressure cycling compliance investment for tractor system vendors. Norwegian Petroleum Directorate well integrity regulations mandate documented fatigue life verification across 500+ pressure cycles. Stavanger subsea technology clusters concentrate system integration expertise for deepwater intervention applications.
China
Sichuan-Chongqing shale gas development programs in the Fuling and Weirong fields expand demand for extended-reach conveyance systems. GB standards and NMPA equipment registration requirements govern downhole tool import and domestic manufacturing certification. Chengdu-based oilfield service companies build regional fleet capacity for unconventional reservoir intervention.
Downhole Tractor Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply architecture. The vendor base organizes around three structural tiers: diversified energy service conglomerates with captive tractor divisions, independent intervention specialists with regional fleet density, and emerging technology licensors with modular drive system IP. Consolidation pressure concentrates procurement authority among service providers with 50+ unit balance sheet capacity. Competitive moves center on coiled tubing spread integration partnerships and Saudi Aramco field validation queue positioning.
Among diversified service conglomerates, Weatherford, NOV, and Baker Hughes occupy positions that exemplify integrated drilling-evaluation-intervention portfolio strategies. Weatherford leverages density across Gulf state markets; NOV anchors regional supply chains through localized manufacturing infrastructure; Baker Hughes competes on high-temperature electric architectures. These three represent the tier where system-level contracting authority concentrates.
| Leading Market Players |
|---|
| Weatherford |
| NOV |
| Schlumberger |
| Hunting Energy Services |
| Global Technology and Innovation |
| Halliburton |
| Welltec |
| Neo Oiltools |
| Baker Hughes |
| Others |
Supply Flow & Price Mechanics
Coiled tubing spread undercapacity in West Texas and southeastern New Mexico compresses tractor deployment availability and elevates day-rate pricing for qualified service providers. API Q2 certification bottlenecks simultaneously restrict vendor participation, amplifying pricing power for witnessed-testing-compliant manufacturers.
Pricing Analysis
API Q2 dictates the pricing tier structure across the downhole tractor market, separating premium-certified vendors from uncertified economy suppliers. Three-tier pricing stratifies across API-witnessed premium, self-certified standard, and non-compliant economy levels, with certification grade and volume scale as primary differentiation drivers. Pricing pressure stems from capital-constrained independent operators in the Delaware sub-basin demanding meterage-fee structures that shift capital burden upstream. Service providers exhibit least price sensitivity due to fleet ownership economics, while exploration firms drive spot-market volatility.
Supply Chain Analysis
Japanese and German specialty semiconductor foundries hold concentrated capacity for high-temperature electronics rated above 175°C, anchoring upstream component supply. Manufacturing concentrates in the United States, Norway, and China, with raw material dependencies spanning rare-earth magnets, high-grade steel alloys, and ceramic pressure housings. Single-source vulnerability in Japanese foundry supply creates exposure for electric tractor architectures. Distribution runs through regional service company clusters in Midland-Odessa, Dhahran, and Stavanger.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The downhole tractor market represents a high-growth disruption as extended-reach lateral technology exceeds wireline mechanical limits and coiled tubing integration becomes mandatory for unconventional well intervention.
For Market Incumbents: Entrench certification moats by accelerating Saudi Aramco Engineering Standards queue positioning before field validation timelines extend further. Deepen backward integration into high-temperature electronics sourcing to neutralize Japanese and German foundry bottlenecks. Weatherford and NOV should leverage existing Gulf state density to capture Adnoc pilot program procurement. For New Entrants and Emerging Players: Establish a beachhead in UAE unconventional tight gas appraisal where first-mover positioning remains open and MOHAP registration requirements create manageable barriers. Target torque control system modules as the fastest-expanding technology segment with lower capital requirements than full tractor platforms. Pursue licensing partnerships with established coiled tubing spread operators to bypass fleet ownership economics. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because service provider procurement authority concentrates among 50+ unit fleet owners and rental model adoption accelerates capital barrier formation. Acquisition target archetype: regional intervention specialists with Saudi Aramco field validation completion and coiled tubing integration partnerships. Monitor coiled tubing spread utilization rates in the Permian as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| API Q2 Certification Investment | Witnessed testing documentation filters marginal suppliers and consolidates procurement authority. |
| Coiled Tubing Spread Partnership | Integration with mobile deployment units eliminates wireline depth limitations in extended-reach laterals. |
| Saudi Aramco Field Validation | Engineering Standards compliance opens national oil company procurement for Jafurah Basin campaigns. |
| High-Temperature Electronics Sourcing | Direct relationships with Japanese and German foundries secure component supply for electric architectures. |
| Performance-Based Rental Contracting | Meterage-fee structures align service provider incentives with operator capital constraints in the Permian. |
Methodological Framework
Cross-validation between primary interviews with oilfield service executives and secondary regulatory filings anchors the qualitative findings in this study. Interviews with intervention technology directors, coiled tubing operations managers, national oil company procurement leads, and aftermarket service heads combined with API specification documents, ISO 13628-7 testing protocols, Saudi Aramco Engineering Standards, and SEC 10-K equipment disclosures. Bottom-up unit deployment estimates and top-down market sizing triangulate volume figures.
Calibration against historical deployment data across product type, technology, and application segments shapes the analytical framework over the projection horizon. Modeled dimensions include powertrain architecture, deployment technology, end user procurement authority, and regional regulatory cluster. CAGRs derive from segment-level growth rate reconciliation with basin-specific lateral extension trajectories and coiled tubing spread capacity expansion plans.
Sensitivities concentrate around coiled tubing unit availability constraints, Saudi Aramco validation timeline extensions, and high-temperature electronics supply disruptions. Forecasts reflect assumptions about Permian lateral length progression and unconventional pilot program scaling in the UAE and Saudi Arabia. Quarterly review of regional coiled tubing spread utilization and API Q2 certification backlog is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Downhole Motor Market
Oil & Gas
Well Testing Services Market
Oil & Gas
Thailand Oil and Gas Market
Oil & Gas
Wellhead System Market
Oil & Gas
Downhole Equipment Market
Oil & Gas
Europe Natural Gas Market
Oil & Gas
Coal Seam Gas Market
Oil & Gas
LNG Bunkering Market
Oil & Gas
Oil and Gas Asset Integrity Management Services Market
Oil & Gas
Mud Balance Market
Oil & Gas
Oil and Gas Field Services Market
Oil & Gas
Oil and Gas Pipeline and Transportation Automation Market
Oil & Gas
Mobile Servicing Rig Market
Oil & Gas
Qatar Oilfield Service Market
Oil & Gas
Frac Services Market
Oil & Gas
Microbial Enhanced Oil Recovery Market