
 Kazakhstan Oil and Gas Downstream Market | 2026-2036
Kazakhstan Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
Kazakhstan Oil and Gas Downstream Market Foresight
REACH-equivalent fuel quality benchmarks is hardening the cost-of-entry calculus for new downstream participants in Kazakhstan. KazMunayGas sustains integrated control across extraction, transit, and refining assets along the Caspian corridor. Atyrau Oil Refinery LLP leverages its coastal location to process heavier crude grades with specialized hydrocracking configurations. Sinopec competes through technology transfer partnerships that upgrade residual oil conversion yields at Kazakh facilities.
Kazakhstan oil and gas downstream encompasses refining, petrochemical processing, and finished product distribution of crude oil into transportation fuels and chemical feedstocks, with modern refineries operating fluid catalytic cracking units achieving conversion rates above 80 percent on medium-sour domestic crudes. The sector supplies gasoline, diesel, and jet fuel to domestic and export markets while generating naphtha and propylene precursors for polymer production. Product type segmentation shows diesel commanding the largest volume share due to freight and mining equipment consumption, while jet fuel represents the fastest-expanding category as Aktau and Astana airports expand international route networks. End user segmentation reveals commercial vehicles as the dominant diesel offtake segment, with aviation demand growing fastest as Air Astana and low-cost carriers expand fleet sizes.
Kazakhstan's Committee for Technical Regulation and Metrology enforces fuel standards aligned with Eurasian Economic Union technical regulations, while the Ministry of Energy governs refinery utilization mandates and strategic reserve obligations. These frameworks shape capital allocation toward desulfurization units and reformer investments required for specification compliance. Stakeholders must monitor pipeline tariff negotiations and the progress of the Kazakhstan-China crude diversification routes that could redirect feedstock flows away from traditional Caspian refining centers.
Market Dynamics
Kazakhstan's downstream sector faces structural pressure from the Committee for Technical Regulation and Metrology's Euro-5 equivalence mandate, which forces refineries to deploy hydrocracking and catalytic reforming investments or surrender market access.
Growth Catalysts
- Atyrau-Aktobe corridor clustering:Petrochemical feedstock projects concentrate near Caspian pipeline infrastructure, creating integrated demand basins for refined products and chemical precursors.
- REACH-equivalent fuel standards:Eurasian Economic Union technical regulations harden quality benchmarks, filtering out marginal participants and protecting compliant asset returns.
- Aviation route expansion:Aktau and Astana airports add international destinations, pulling jet fuel offtake volumes upward as Air Astana and low-cost carriers enlarge fleets.
Market Restraints
- Crude slate heaviness:Domestic medium-sour crudes require specialized hydrocracking configurations that elevate capital intensity per barrel of refined output.
- Pipeline tariff uncertainty:Negotiations over Kazakhstan-China crude diversification routes threaten to redirect feedstock flows away from traditional Caspian refining centers.
- Residual oil conversion limits:Existing fluid catalytic cracking units face yield ceilings on heavier feedstocks, constraining light product recovery rates.
Strategic Opportunities
- Polymer precursor verticalization:Naphtha and propylene output can feed domestic polyethylene and polypropylene plants, capturing margin that currently leaks to imported feedstocks.
- Strategic reserve infrastructure:Ministry of Energy mandates for stockholding obligations create contracted storage demand with predictable revenue streams.
- Diesel quality arbitrage:Commercial trucking fleet expansion in the mining and freight sectors rewards ultralow-sulfur diesel production with premium offtake terms.
Industry Challenges
- Hydrocracker engineering scarcity:Specialized process design talent for heavy crude upgrading commands premium compensation and extends project timelines.
- Desulfurization unit synchronization:Coordinating catalyst replacement cycles across reformer and hydrotreater trains without disrupting Euro-5 compliance requires precise logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kazakhstan Oil and Gas Downstream Market |
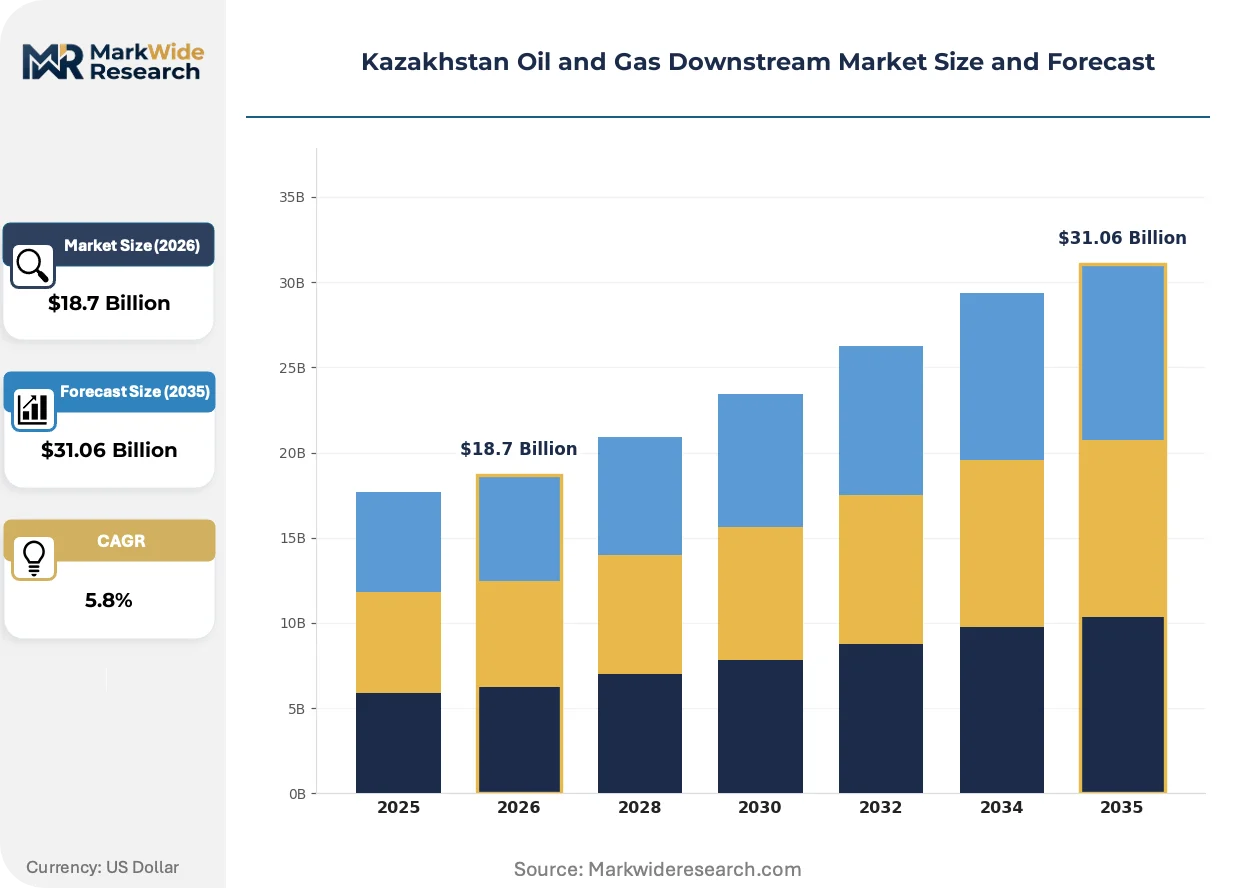
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline, Diesel, Kerosene, Jet Fuel End User: Commercial Vehicles, Passenger Cars, Aviation, Industrial Distribution Channel: Retail Outlets, Direct Sales, Online Platforms, Bulk Suppliers Application: Transportation, Energy Generation, Petrochemical Production, Heating |
| Companies Covered | KazTransOil JSC, Atyrau Oil Refinery LLP, National Company KazMunayGas, SIBUR, Sinopec, PJSC Lukoil Oil Company, Kazakhstan Petrochemical Industries LLP, MOL Group, PetroKazakhstan Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kazakhstan Oil and Gas Downstream Market Shifts & Advancements
Digital process control systems and advanced analytics are penetrating Kazakh refining operations, compressing yield variance and enabling real-time quality adjustment to specification thresholds.
Artificial intelligence-driven predictive maintenance is automating catalyst performance monitoring across fluid catalytic cracking units. Atyrau Oil Refinery and comparable facilities deploy machine learning models to forecast coking rates and optimize regeneration cycles. This capability is automating the scheduling of turnaround intervals, extending run lengths between maintenance events.
Eurasian Economic Union technical regulations on fuel quality are tightening sulfur and aromatic limits in stages. Refineries must sequence investments in hydrotreaters and reformers to maintain compliance without stranding intermediate assets. Diesel and gasoline blending operations face the steepest adaptation costs as specifications converge toward Euro-5 equivalence.
Long-term supply contracts are displacing spot market purchases among commercial trucking fleets and mining operators. Large offtakers negotiate fixed-volume, price-adjusted agreements directly with KazMunayGas refining subsidiaries, bypassing wholesale distributors. This pattern concentrates procurement leverage with fleet operators in the Karaganda and East Kazakhstan mining belts.
Kazakhstan Oil and Gas Downstream Market Segmentation
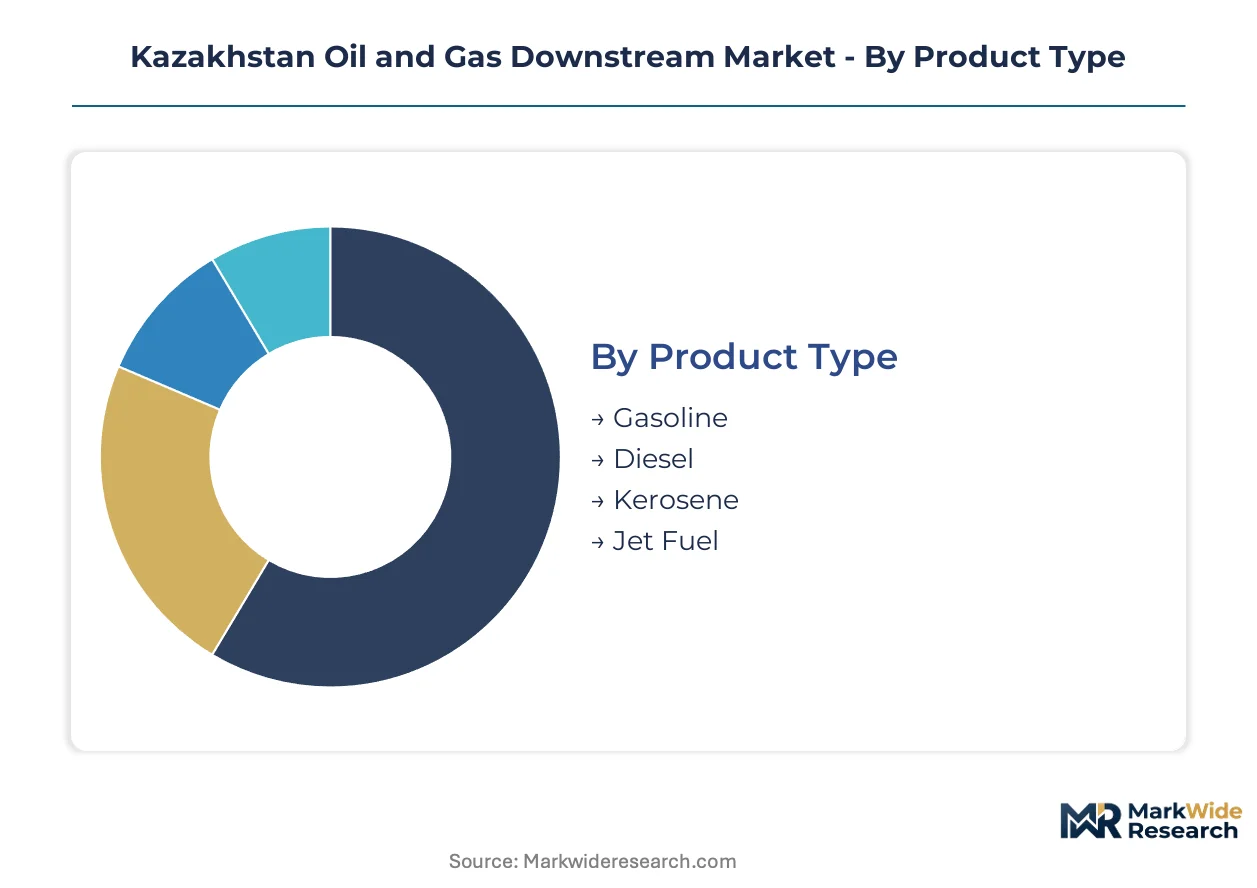
Kazakhstan's downstream segmentation reflects divergent margin profiles across fuel grades and the concentration of diesel demand in mining freight corridors. Understanding these splits enables precise capacity allocation between Euro-5 compliance investments and petrochemical feedstock expansion.
Product Type:
Buyers select fuel grades based on engine compatibility, sulfur tolerance, and bulk procurement economics tied to fleet specifications.
- Diesel:Ultralow-sulfur formulations dominate commercial offtake from Karaganda mining belts and cross-border trucking routes. The Atyrau-Aktobe corridor absorbs the largest volumes as heavy equipment operators lock in long-term supply contracts.
- Jet Fuel:Aviation turbine kerosene with stringent freeze-point specifications serves expanding international routes from Aktau and Astana airports. Air Astana's fleet enlargement pulls volumes upward faster than ground transportation fuels.
- Gasoline:Reformate-blended motor fuels with octane ratings meeting Eurasian Economic Union standards supply passenger vehicle fleets in Almaty and Nur-Sultan urban zones.
- Kerosene:Illuminating-grade and heating kerosene serves remote industrial settlements lacking pipeline natural gas connectivity.
Diesel leads on scale; jet fuel leads on momentum.
End User:
Customer procurement power varies sharply between fragmented retail motorists and concentrated mining fleet operators negotiating direct refinery terms.
- Commercial Vehicles:Heavy-duty trucking and mining equipment fleets in East Kazakhstan consume the largest diesel volumes. Operators leverage scale to bypass wholesale distributors and secure price-adjusted contracts from KazMunayGas refining subsidiaries.
- Aviation:International carriers and low-cost operators expanding from Aktau International Airport drive jet fuel offtake. Route network growth outpaces domestic ground transportation demand expansion.
- Industrial:Petrochemical plants and remote power generation facilities purchase residual fuel oils and naphtha feedstocks through bulk tender processes.
- Passenger Cars:Fragmented retail demand across Almaty, Shymkent, and Nur-Sultan concentrates at branded retail outlets with Euro-5 certified gasoline grades.
Commercial vehicles dominate procurement volume; aviation posts the steepest expansion trajectory.
Distribution Channel:
Channel selection tracks customer scale, with large offtakers disintermediating traditional wholesale layers.
- Direct Sales:Mining conglomerates and airline fuel suppliers negotiate fixed-volume agreements directly with Atyrau and Pavlodar refineries. This channel captures the highest-margin ultralow-sulfur diesel and aviation turbine fuel volumes.
- Bulk Suppliers:Intermediate distributors serve industrial heating and remote power generation customers lacking pipeline access. Tariff negotiations with KazTransOil shape delivered cost competitiveness.
- Retail Outlets:Branded station networks in urban corridors handle fragmented passenger car gasoline demand. Euro-5 specification compliance elevates working capital requirements for inventory management.
- Online Platforms:Digital procurement portals emerging for lubricants and specialty chemicals remain marginal for bulk hydrocarbon offtake.
Direct sales commands margin concentration; bulk suppliers anchor geographic reach.
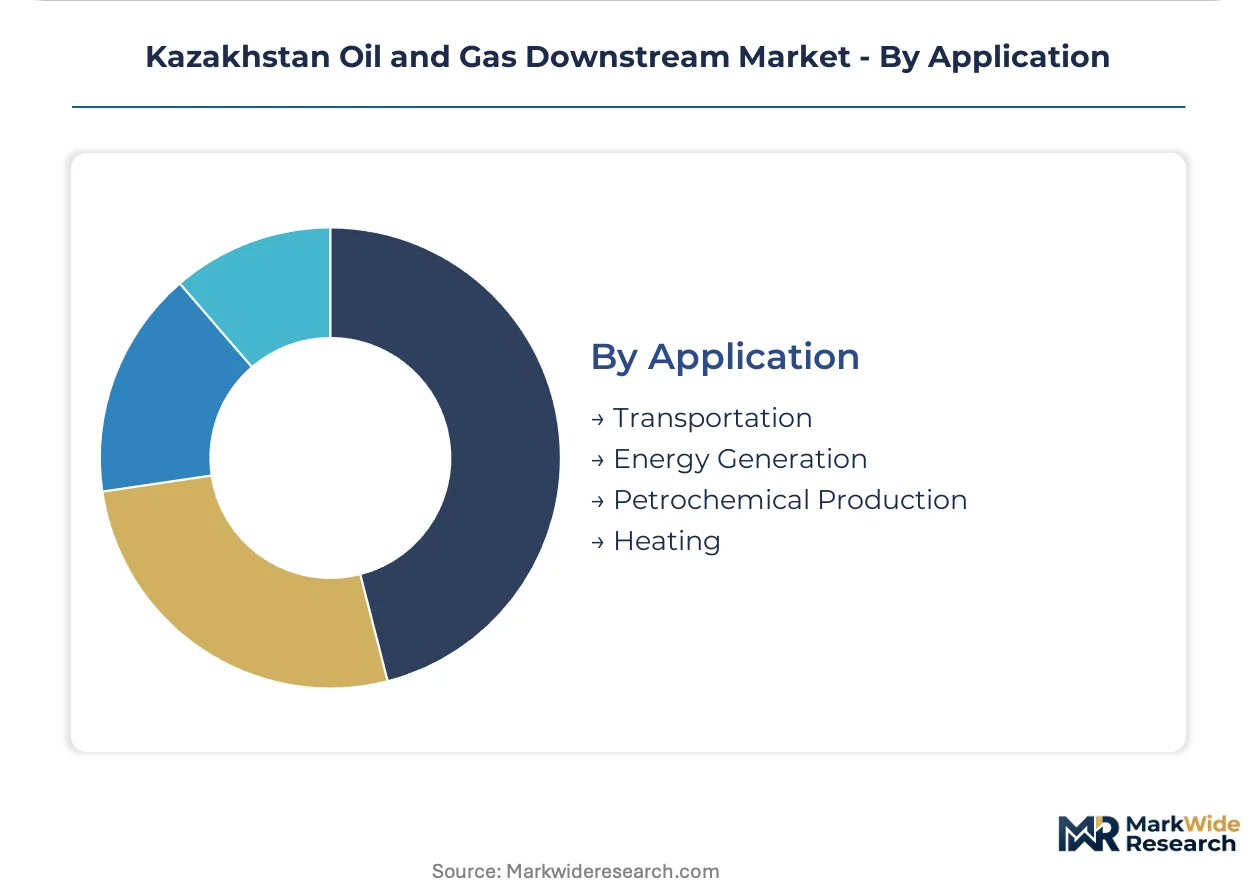
Application:
End-use prioritization shapes refinery configuration investments between transportation fuels and chemical precursors.
- Transportation:Road, rail, and aviation fuel specifications drive the largest refinery output share. Committee for Technical Regulation and Metrology Euro-5 mandates force continuous hydrotreater and reformer upgrades.
- Petrochemical Production:Naphtha and propylene precursors feed domestic polyethylene and polypropylene plants clustered near Atyrau. Captive feedstock supply reduces import dependency for polymer manufacturing.
- Energy Generation:Residual fuel oils and diesel power remote industrial settlements and grid backup facilities in western regions lacking gas pipeline infrastructure.
- Heating:Kerosene and diesel heating fuels serve seasonal demand in northern oblasts with severe winter temperature profiles.
Transportation absorbs capacity scale; petrochemical production offers the highest value-add conversion path.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kazakhstan's downstream sector traces its modern lineage to Soviet-era refinery construction at Atyrau and Pavlodar, facilities later retrofitted for Euro-5 equivalence under post-independence modernization programs. These installations anchor processing capacity along the Caspian corridor.
Atyrau Region
Heavy crude upgrading complexes and petrochemical feedstock projects concentrate along the Caspian coastline. The Committee for Technical Regulation and Metrology enforces Eurasian Economic Union fuel quality standards, mandating continuous hydrotreater investments. Atyrau Oil Refinery processes medium-sour domestic crudes through specialized hydrocracking configurations.
Aktobe Region
Mining equipment fleets and cross-border trucking corridors generate concentrated diesel demand from Karaganda through eastern oblasts. Ministry of Energy utilization mandates shape refinery offtake obligations. The Atyrau-Aktobe pipeline corridor feeds integrated demand basins for refined products and chemical precursors.
Pavlodar Region
Northern refining capacity serves heating fuel demand across severe winter temperature profiles. The national technical regulator's sulfur limits force synchronized catalyst replacement cycles across reformer trains. Pavlodar refinery operations supply residual fuel oils to remote industrial settlements lacking pipeline natural gas connectivity.
Almaty Urban Agglomeration
Passenger vehicle fleets and retail gasoline demand concentrate in Kazakhstan's largest metropolitan zone. Euro-5 specification compliance elevates working capital requirements for branded station networks. Almaty distribution terminals handle fragmented motor fuel demand across southern population centers.
Astana Metropolitan Area
International aviation route expansion from Nursultan Nazarbayev International Airport pulls jet fuel offtake volumes upward. Air Astana fleet enlargement and low-cost carrier entry drive aviation turbine kerosene specifications. Astana logistics hubs coordinate refined product flows to northern and central regions.
Kazakhstan Oil and Gas Downstream Market Competitive Landscape
The competitive structure tilts toward state-integrated incumbents with pipeline and refining asset control. KazMunayGas sustains integrated positions across extraction, transit, and downstream processing along the Caspian corridor. Two strategic archetypes dominate: national oil companies with vertical infrastructure control, and technology-transfer partners supplying process licensing. Capacity expansion and strategic partnerships constitute the primary competitive vectors as Euro-5 compliance investments strain balance sheets.
Within the state-integrated tier, National Company KazMunayGas and KazTransOil JSC exemplify domestic infrastructure control, while Atyrau Oil Refinery LLP occupies a coastal processing position. Among international technology partners, Sinopec represents Chinese process licensing engagement, and SIBUR anchors Russian petrochemical feedstock integration. These entities collectively illustrate the sector's bifurcation between captive domestic supply chains and foreign technology-dependent upgrading investments.
| Leading Market Players |
|---|
| KazTransOil JSC |
| Atyrau Oil Refinery LLP |
| National Company KazMunayGas |
| SIBUR |
| Sinopec |
| PJSC Lukoil Oil Company |
| Kazakhstan Petrochemical Industries LLP |
| MOL Group |
| PetroKazakhstan Inc. |
| Others |
Supply & Pricing Matrix
Captive integration across KazMunayGas-controlled extraction, pipeline transit, and refining assets anchors supply positioning and pricing power in Kazakhstan's downstream sector. This vertical control enables differential pricing between direct sales to mining conglomerates and wholesale distribution layers, with Euro-5 compliance costs passed through to fragmented retail channels.
Pricing Analysis
Contract-based long-term offtake agreements dominate the bundled service layer, while spot market purchases persist for unbundled wholesale transactions. Price differentiation separates ultralow-sulfur diesel volumes sold direct to Karaganda mining fleets from reformate-blended gasoline distributed through branded retail networks. Pricing pressure stems from hydrocracker engineering scarcity and catalyst replacement cycle costs. Mining fleet operators exhibit lowest price sensitivity due to volume scale and captive supply arrangements, while passenger car motorists face highest sensitivity at urban retail outlets.
Supply Chain Analysis
Regional distribution centers at Atyrau and Pavlodar refineries anchor hub-and-spoke patterns feeding bulk suppliers and retail networks across Kazakhstan. Geographic supply concentration centers on domestic Caspian crude extraction with supplemental feedstock draws from Russian pipeline connections. Raw material dependencies include medium-sour crude grades, specialized hydrocracking catalysts, and hydrogen supply for desulfurization units. Single-source vulnerability runs through KazTransOil pipeline infrastructure controlling feedstock flows to refining centers. Distribution runs through direct sales channels for large offtakers and intermediate bulk suppliers for remote industrial settlements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kazakhstan's downstream sector functions as a geographic-arbitrage play between Euro-5-equivalent fuel premiums in domestic markets and lower-specification export opportunities to neighboring Eurasian Economic Union members with phased compliance timelines.
For Market Incumbents: To counter pipeline tariff uncertainty from Kazakhstan-China crude diversification routes, KazMunayGas should deepen backward integration into strategic reserve infrastructure to lock in contracted storage revenues. Incumbents must accelerate desulfurization unit synchronization capabilities to maintain Euro-5 compliance without yield disruption during catalyst replacement cycles. For New Entrants and Emerging Players: Launch via technology transfer partnerships targeting residual oil conversion yield improvements at existing Kazakh facilities. White-space targets include polymer precursor verticalization feeding domestic polyethylene plants and digital process control system deployment for predictive maintenance services. The most penetrable segment is specialty chemical procurement portals for lubricants and catalyst supply. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale hydrocracker engineering specialists because project timeline extensions and premium compensation for process design talent create scarcity value. Long-term viability hinges on Euro-5 enforcement consistency across Eurasian Economic Union jurisdictions. Watch for Ministry of Energy refinery utilization mandate adjustments as inflection indicators for capacity investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strategic Reserve Infrastructure | Ministry of Energy stockholding obligations create contracted demand with predictable revenue streams. |
| Hydrocracking Technology Licensing Partnership | Sinopec-style process transfer agreements upgrade residual conversion yields at Caspian corridor facilities. |
| Polymer Precursor Verticalization | Naphtha and propylene captive supply reduces import dependency for Atyrau petrochemical plants. |
| Digital Predictive Maintenance Platform Deployment | Machine learning coking rate forecasts extend fluid catalytic cracking unit run lengths between turnarounds. |
| Direct Sales Channel Expansion to Mining Belts | Long-term fixed-volume agreements with East Kazakhstan fleet operators bypass wholesale margin leakage. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with refinery operations managers, KazTransOil logistics planners, mining fleet procurement directors, and Committee for Technical Regulation and Metrology officials with secondary validation. Secondary sources included Eurasian Economic Union technical regulation filings, Ministry of Energy utilization mandate disclosures, customs trade data for refined product flows, and KazMunayGas integrated reporting. Bottom-up capacity modeling and top-down demand projection triangulation anchored volume estimates.
Comparable historical periods across the analysis window established baseline utilization rates and yield progression patterns for forward projection. Segmentation dimensions modeled include fuel grade tier, end-use application, distribution channel structure, and regional demand basin concentration. CAGRs were derived from capacity expansion schedules, regulatory compliance investment timelines, and aviation route network growth trajectories. Industry-specific inputs incorporated hydrocracker engineering project backlogs and catalyst replacement cycle frequencies.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Committee for Technical Regulation and Metrology enforcement intensity shifts or Kazakhstan-China pipeline tariff renegotiations. Forecasts reflect documented assumptions regarding Euro-5 phase-in consistency and mining sector equipment fleet expansion rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Downhole Tools Market
Oil & Gas
Malaysia Oil and Gas Midstream Market
Oil & Gas
Coal Mining Market
Oil & Gas
Middle-East Oil and Gas Line Pipe Market
Oil & Gas
Romania Oil and Gas Upstream Market
Oil & Gas
Oil and Gas Swell Packers Market
Oil & Gas
Africa Oil Refining Market
Oil & Gas
Oriented Perforating System Market
Oil & Gas
North Sea Oilfield Equipment Market
Oil & Gas
LNG Bunkering Market
Oil & Gas
Russia Oil and Gas EPC Market
Oil & Gas
Oil and Gas Downhole Cables Market
Oil & Gas
HPHT Cubic Press Market
Oil & Gas
Asia-Pacific Small-Scale LNG Market
Oil & Gas
Oil Well Cement Market
Oil & Gas
Open Hole Logging Services Market