
 Leukemia Inhibitory Factor (LIF) Market | 2026-2036
Leukemia Inhibitory Factor (LIF) Market Size, Share, and Industry Trends Forecast 2026-2036
Leukemia Inhibitory Factor (LIF) Market Insights
Academic institutions are unwinding from pharmaceutical companies as the dominant buyer archetype for research-grade LIF. STEMCELL Technologies leverages its specialized cell culture media portfolio to anchor North American supply chains for stem cell applications. Merck KGaA sustains broad geographic coverage through its life science distribution network. Bio Techne differentiates via recombinant protein quality grades that serve both research and preclinical therapeutic workflows.
Leukemia Inhibitory Factor is a pleiotropic cytokine belonging to the interleukin-6 family, typically manufactured as a recombinant protein expressed in E. coli or mammalian systems with purity thresholds exceeding 95% by SDS-PAGE, and it maintains embryonic stem cell pluripotency and supports hematopoietic cell survival in industrial and academic research settings. Recombinant proteins command the largest revenue share among product types due to their direct use in cell culture protocols, while ELISA kits represent the fastest-expanding category as laboratories scale up cytokine quantification for quality control. Therapeutics applications remain nascent but attract the highest per-unit margins as drug developers explore LIF-mediated pathways for neuroprotection and tissue repair.
FDA oversight of ancillary materials in cell therapy production elevates documentation burdens for GMP-grade LIF suppliers, while ISO 13485 certification increasingly gates access to diagnostic assay partnerships in Europe. The EU MDR framework reclassifies certain LIF-containing diagnostic products, compelling manufacturers to rebuild technical files for continued CE marking. Stakeholders must weigh the capital requirements of GMP facility upgrades against the margin premiums available in therapeutic-grade supply chains as regulatory thresholds diverge between research and clinical applications.
Market Dynamics
Academic procurement of recombinant LIF proteins is decoupling from pharmaceutical sourcing patterns as stem cell research programs scale pluripotency maintenance protocols independently of therapeutic development pipelines. This bifurcation is compressing supplier margins in research-grade segments while amplifying documentation burdens for clinical-grade certification.
Growth Catalysts
- NIH Regenerative Medicine Funding:United States federal grants flow into academic consortia maintaining embryonic stem cell lines, generating sustained demand for high-purity cytokine inputs. Research institutions in California, Massachusetts, and Maryland anchor procurement volume.
- ISO 13485 Certification Expansion:European diagnostic manufacturers are rebuilding technical files under EU MDR reclassification rules, creating compliant supplier slots for LIF-containing assay components. CE marking renewal cycles accelerate vendor qualification timelines.
- E. coli Expression System Maturation:Bacterial production platforms achieve 95%+ purity thresholds at research-grade scale, lowering unit costs for high-throughput screening applications. Mammalian systems retain dominance for therapeutic-grade output.
Market Restraints
- GMP Facility Capital Intensity:Upgrading E. coli or CHO production lines to FDA-validated standards requires eight-figure facility investments. Smaller suppliers face exclusion from therapeutic-grade supply chains.
- Serum-Free Media Substitution:Chemically defined formulations reduce batch-to-batch cytokine variability, compressing demand for research-grade LIF in downstream applications. STEMCELL Technologies and competitors integrate LIF directly into proprietary media cocktails.
- Single-Source CHO Cell Line Dependencies:Therapeutic-grade production concentrates among contract manufacturers holding specific master cell bank licenses. Supply interruption risks elevate procurement contingency costs.
Strategic Opportunities
- India CDMO Expansion:Indian contract development organizations are investing in biosimilar-grade cytokine production capacity. BIS quality standards and CDSCO alignment create pathways for export-oriented GMP certification.
- Organoid Culture Integration:Three-dimensional stem cell models for disease modeling and drug screening consume LIF at 10-20x monolayer volumes. Academic core facilities and biotech startups drive adoption curves.
- Japan PMDA Regenerative Medicine Pathway:Conditional approval frameworks for cell therapies accelerate timeline-to-market for LIF-mediated neuroprotection candidates. METI funding supports domestic supply chain localization.
Industry Challenges
- GMP Documentation Specialist Scarcity:Cell therapy manufacturers face 12-18 month hiring cycles for quality assurance personnel capable of FDA master file preparation. Training pipelines at U.S. universities lag industry demand.
- Legacy ELISA Validation Backlogs:Laboratories migrating from research-grade to GMP-grade LIF must revalidate quantification assays. Lot release testing protocols require six-month stability studies that delay protocol transfers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leukemia Inhibitory Factor (LIF) Market |
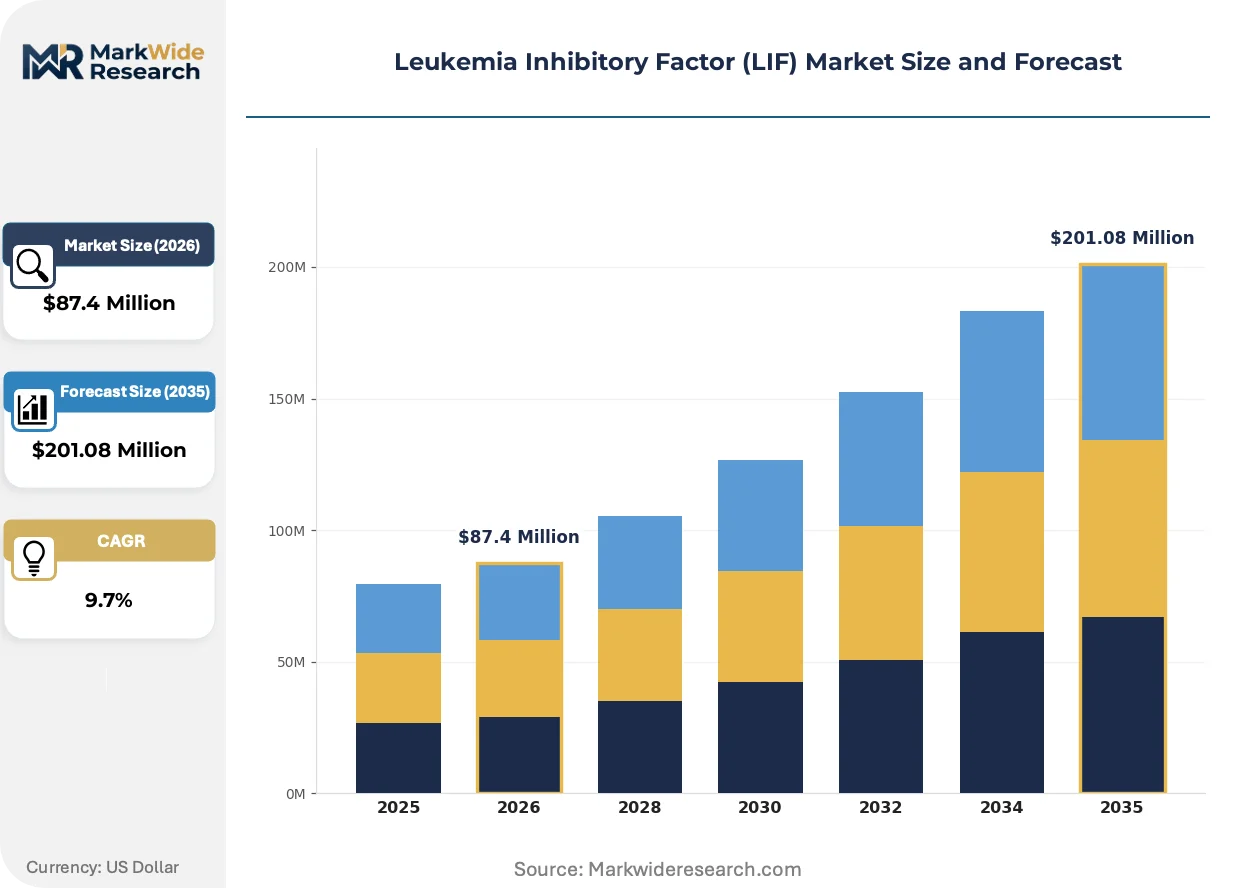
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $201.08 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Research, Diagnosis, Therapeutics, Drug Discovery Product Type: Recombinant Proteins, Antibodies, ELISA Kits, Assay Products End User: Pharmaceutical Companies, Biotech Firms, Academic Institutions, Research Labs Delivery Mode: Injection, Inhalation, Oral, Infusion |
| Companies Covered | Bristol Myers Squibb, Merck KGaA, Thermo Fisher Scientific, Bio Techne, InVitria, STEMCELL Technologies, Sino Biological, ACROBiosystems, ProSpec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leukemia Inhibitory Factor (LIF) Market Trends and Innovations
Microfluidic integration and automated cell culture platforms are compressing manual handling steps in stem cell maintenance workflows. Suppliers must adapt packaging formats and concentration specifications to match closed-system bioreactor architectures.
Microcarrier-based expansion systems for pluripotent stem cells are miniaturizing traditional flask-based LIF supplementation protocols. Contract manufacturers in Singapore and South Korea are adopting these platforms for clinical-scale lot production. The shift is reducing per-dose cytokine consumption while demanding higher-concentration, low-volume aliquot formats from suppliers.
EU MDR reclassification of certain LIF-containing in vitro diagnostic devices is forcing manufacturers to resubmit technical files for CE marking renewal. German and French notified bodies are extending review timelines by 8-12 months for cytokine-based fertility and stem cell quality assays. Diagnostic partnerships now require ISO 13485 certification as a gating criterion, elevating compliance investments for protein suppliers.
Academic core facilities are consolidating cytokine procurement through group purchasing organizations rather than individual PI-driven ordering. University of California and MIT systems have centralized LIF sourcing through preferred vendor agreements with annual volume commitments. This concentration is squeezing smaller distributors while rewarding suppliers with integrated media-cytokine portfolios.
Leukemia Inhibitory Factor (LIF) Market Segmentation
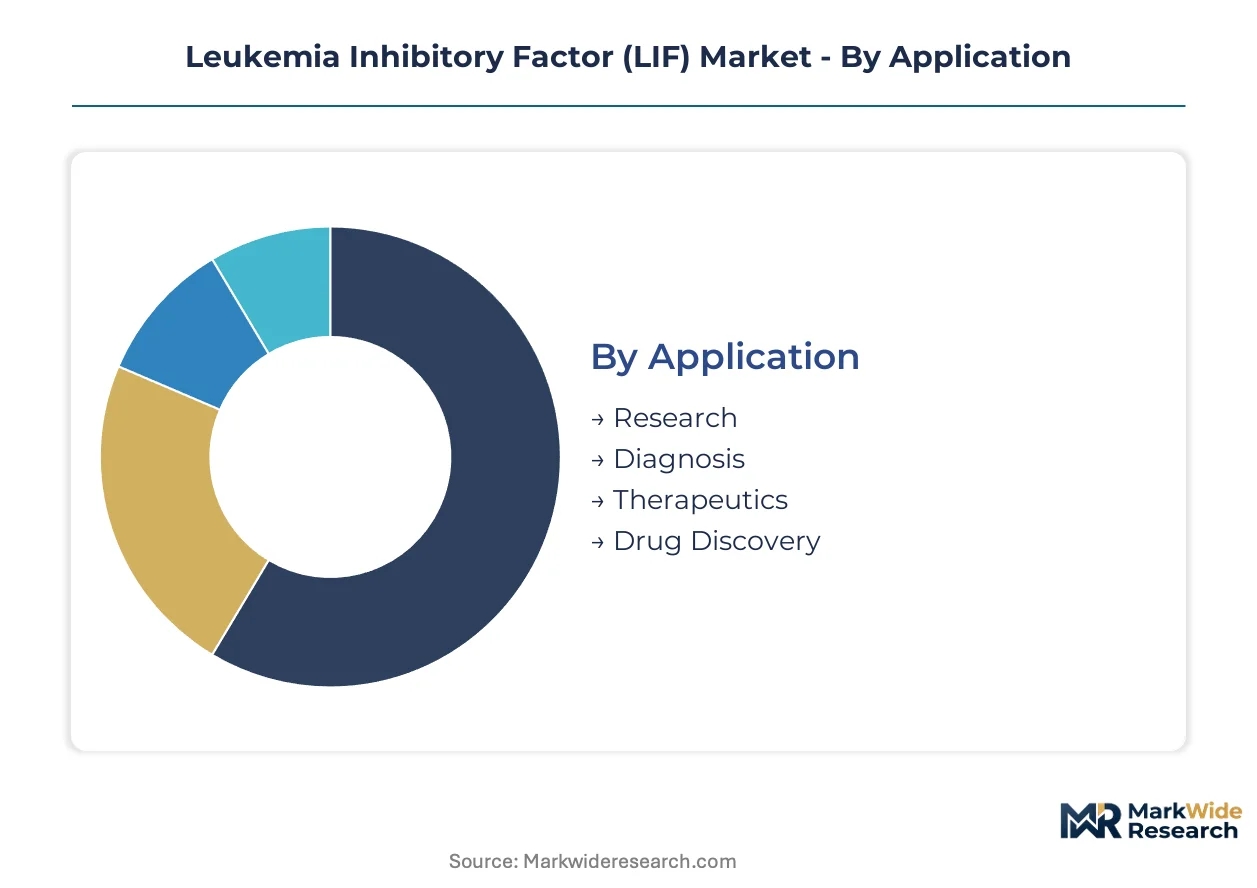
LIF market segmentation reflects divergent purity standards between research-grade and therapeutic-grade supply chains. FDA and EMA documentation requirements create tiered pricing and procurement patterns that suppliers must navigate across customer archetypes.
Application:
FDA oversight of ancillary materials in cell therapy manufacturing elevates compliance burdens differentially across use cases.
- Research:Academic stem cell programs at institutions like MIT and University of California systems drive volume through pluripotency maintenance protocols. NIH regenerative medicine funding concentrates procurement in Massachusetts, California, and Maryland research clusters.
- Therapeutics:Drug developers exploring LIF-mediated neuroprotection pathways command premium per-unit margins. PMDA conditional approval frameworks in Japan accelerate timeline-to-market for cell therapy candidates utilizing cytokine inputs.
- Diagnosis:EU MDR reclassification compels manufacturers to rebuild technical files for CE marking renewal.
- Drug Discovery:High-throughput screening applications consume research-grade recombinant proteins at scale.
Established volume favors Research; emerging adoption favors Therapeutics.
Product Type:
Production platform selection—E. coli versus mammalian expression systems—determines cost structures and addressable market tiers.
- Recombinant Proteins:Bacterial expression achieves 95%+ purity thresholds for research applications while mammalian CHO lines retain dominance for therapeutic-grade output. STEMCELL Technologies and competitors integrate these proteins directly into proprietary serum-free media cocktails.
- ELISA Kits:Laboratories scaling cytokine quantification for quality control drive category expansion. Lot release testing protocols require six-month stability studies that delay protocol transfers from research-grade to GMP-grade workflows.
- Antibodies:Diagnostic assay partnerships demand ISO 13485 certification as a gating criterion.
- Assay Products:Fertility and stem cell quality assays face extended review timelines from German and French notified bodies.
Recombinant Proteins anchor current revenue; ELISA Kits are climbing the fastest.
End User:
Procurement centralization through group purchasing organizations is reshaping vendor access patterns.
- Academic Institutions:Core facilities consolidate cytokine sourcing through preferred vendor agreements with annual volume commitments. Individual PI-driven ordering is unwinding at major university systems.
- Pharmaceutical Companies:GMP facility capital intensity—eight-figure investments for FDA-validated production lines—excludes smaller suppliers from therapeutic-grade supply chains.
- Biotech Firms:Organoid culture adoption consumes LIF at 10-20x monolayer volumes for three-dimensional disease modeling.
- Research Labs:Microfluidic integration and automated platforms demand adapted packaging formats and concentration specifications.
Academic Institutions dominate procurement volume; Biotech Firms show steepest expansion trajectory.
Delivery Mode:
Route of administration correlates with development stage and regulatory pathway complexity.
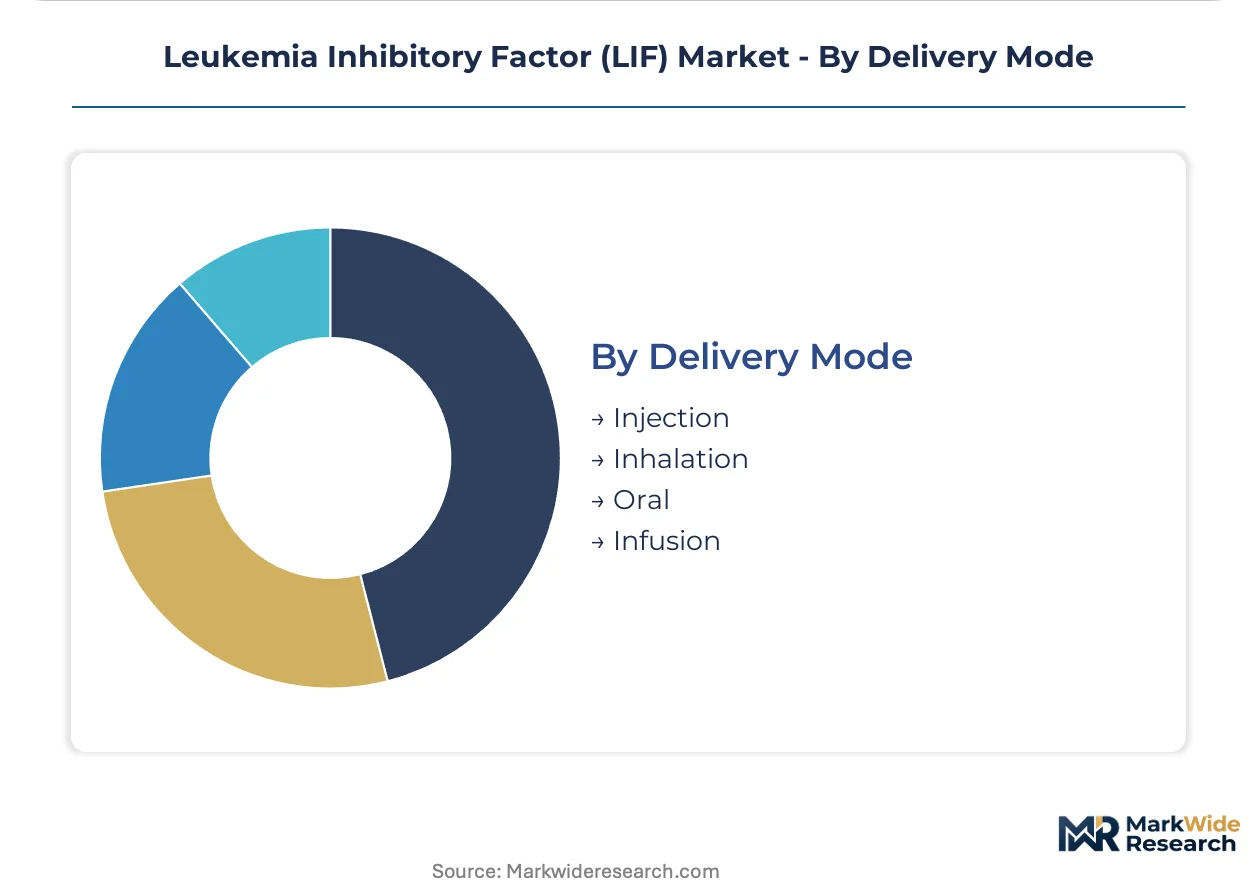
- Injection:Subcutaneous and intravenous formulations dominate preclinical therapeutic workflows. Parenteral delivery requires stringent endotoxin controls that elevate manufacturing costs.
- Infusion:Clinical-scale cell therapy production utilizes continuous delivery systems for bioreactor supplementation.
- Inhalation:Pulmonary delivery routes remain exploratory for neuroprotection indications.
- Oral:Gastrointestinal administration faces bioavailability challenges given LIF's protein structure.
Injection commands development investment; Infusion scales with clinical manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CHO cell line licenses and GMP facility investments cluster among contract manufacturers in the United States, Germany, Japan, India, and Singapore. NIH funding flows, EMA documentation requirements, and PMDA conditional approval frameworks shape procurement patterns across these jurisdictions.
United States
NIH regenerative medicine consortia in Massachusetts, California, and Maryland drive sustained demand for high-purity cytokine inputs. FDA guidelines on ancillary materials in cell therapy manufacturing tighten purity documentation burdens for GMP-grade suppliers. Boston and San Francisco Bay Area research clusters anchor procurement volume through academic core facility consolidation.
Germany
German notified bodies extend EU MDR review timelines by 8-12 months for LIF-containing diagnostic devices, compelling manufacturers to rebuild technical files. EMA oversight of therapeutic-grade cytokine inputs elevates ISO 13485 certification requirements. Heidelberg and Munich biotech corridors concentrate diagnostic assay development partnerships.
Japan
METI funding supports domestic supply chain localization for regenerative medicine inputs. PMDA conditional approval frameworks accelerate timeline-to-market for cell therapy candidates utilizing LIF-mediated neuroprotection pathways. Tokyo and Osaka metropolitan areas host the majority of stem cell research programs driving cytokine procurement.
India
Indian contract development organizations invest in biosimilar-grade cytokine production capacity for export markets. CDSCO alignment and BIS quality standards create pathways for GMP certification. Hyderabad and Bengaluru biotech parks emerge as production hubs for research-grade recombinant proteins.
Singapore
Microcarrier-based expansion systems for pluripotent stem cells miniaturize traditional LIF supplementation protocols at clinical scale. The national biomedical sciences initiative supports contract manufacturing infrastructure for regional cell therapy supply chains. Biopolis research cluster integrates automated cell culture platforms demanding adapted cytokine packaging formats.
Leukemia Inhibitory Factor (LIF) Market Competitive Landscape
Concentration sits with diversified life science conglomerates and specialized cell culture media suppliers. The vendor base spans three tiers: multinational distributors with broad geographic coverage, integrated media-cytokine portfolio specialists, and regional recombinant protein manufacturers. Strategic moves center on GMP facility certification upgrades and preferred vendor agreements with academic purchasing consortia.
Among North American suppliers, STEMCELL Technologies exemplifies the integrated media-cytokine archetype through its specialized cell culture portfolio. Merck KGaA anchors the diversified distribution tier with broad life science supply chain coverage. Bio Techne occupies a position bridging research-grade and preclinical therapeutic workflows through recombinant protein quality differentiation. These three represent distinct competitive vectors in a market where documentation capabilities increasingly gate access to higher-margin segments.
| Leading Market Players |
|---|
| Bristol Myers Squibb |
| Merck KGaA |
| Thermo Fisher Scientific |
| Bio Techne |
| InVitria |
| STEMCELL Technologies |
| Sino Biological |
| ACROBiosystems |
| ProSpec |
| Others |
Pricing and Supply Chain Analysis
Six-month lot release testing cycles for GMP-grade LIF validate supply chain bottlenecks while amplifying pricing power for certified manufacturers serving cell therapy developers. FDA master file preparation timelines concentrate procurement leverage among incumbent suppliers with pre-validated documentation.
Pricing Analysis
FDA guidelines on ancillary materials in cell therapy manufacturing dictate the pricing tier structure across research, preclinical, and therapeutic-grade segments. Three-tier pricing separates GMP-certified premium grades from ISO 13485-compliant diagnostic tiers and research-grade economy batches. Price differentiation rests on documentation depth and endotoxin certification thresholds. Cost compression in research-grade segments is intensifying because academic core facilities consolidate procurement through group purchasing organizations. Academic buyers exhibit highest price sensitivity; therapeutic developers prioritize supply security over unit cost.
Supply Chain Analysis
Single-source CHO cell line licenses held by contract manufacturers in the United States, Germany, and Japan constitute a chokepoint that constrains therapeutic-grade output expansion. Production draws from E. coli bacterial platforms for research applications and mammalian expression systems for clinical batches. Raw material dependencies include defined media formulations, endotoxin-free water systems, and qualified packaging components. Supply interruption risks elevate procurement contingency costs for master cell bank dependencies. Distribution runs through life science distributors and direct academic contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect as automated cell culture systems demand standardized cytokine aliquot formats, creating interoperability premiums for suppliers with integrated media portfolios.
For Market Incumbents: Shield market position by deepening GMP facility certifications ahead of FDA guideline tightening on ancillary materials documentation. Anchor preferred vendor status with University of California and MIT procurement consortia through annual volume commitments. Counter serum-free media substitution threats by embedding LIF directly into proprietary chemically defined formulations. For New Entrants and Emerging Players: Lead with organoid culture applications as the most penetrable white-space target, where three-dimensional stem cell models consume cytokine at 10-20x monolayer volumes. Target Indian CDMO partnerships for biosimilar-grade production capacity under BIS quality standards. Pursue diagnostic assay partnerships requiring ISO 13485 certification as the fastest qualification pathway. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates seeking to monetize non-core cytokine production assets. Five-to-ten-year viability hinges on therapeutic-grade margin expansion as cell therapy pipelines mature. Monitor PMDA conditional approval timelines for LIF-mediated neuroprotection candidates as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Facility Certification Upgrade | FDA master file preparation capabilities gate access to therapeutic-grade supply chains. |
| Preferred Vendor Agreement with Academic Consortia | University of California and MIT systems consolidate procurement through annual volume commitments. |
| ISO 13485 Certification Investment | EU MDR reclassification elevates compliance requirements for diagnostic assay partnerships. |
| Organoid Culture Format Development | Three-dimensional stem cell models demand higher-concentration, low-volume aliquot specifications. |
| India CDMO Partnership Formation | Hyderabad and Bengaluru biotech parks offer export-oriented GMP certification pathways. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA guidance documents, EMA regulatory filings, NIH funding disclosures, and ISO certification databases. Interviews with cell therapy manufacturing executives, academic core facility directors, GMP quality assurance leads, and diagnostic assay developers inform demand-side validation. Secondary sources include ClinicalTrials.gov entries, CDSCO registration data, and PMDA conditional approval records. Bottom-up segment sizing triangulates against top-down market aggregation.
Segmentation dimensions modeled include application tier, product type, end-user archetype, and delivery mode across the analysis window. CAGRs derive from volume trajectory analysis by segment and pricing tier evolution. Forecast inputs incorporate NIH regenerative medicine funding allocations, EU MDR implementation timelines, and PMDA pathway acceleration metrics.
The analysis sits within stated boundaries; outcomes outside FDA guideline stability, master cell bank license continuity, or academic funding levels would require recalibration. Practitioners should keep alternative scenarios live as regulatory divergence between research and therapeutic-grade standards evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Cholangitis Market
Specialty Medicine
Myelofibrosis Market
Specialty Medicine
Global Cryptococcosis Treatment Market
Specialty Medicine
Advanced Basal Cell Carcinoma Market
Specialty Medicine
Tinnitus Management Market
Specialty Medicine
Global Postmenopausal Osteoporosis Market
Specialty Medicine
Progressive Supranuclear Palsy (PSP) Market
Specialty Medicine
Achondroplasia Treatment Market
Specialty Medicine
Tinea Corporis Market
Specialty Medicine
Personalized Medicine Market
Specialty Medicine
Synovial Sarcoma Market
Specialty Medicine
Combined Immune Deficiency (CID) Market
Specialty Medicine
Hemophilia Market
Specialty Medicine
Cystic Fibrosis Market
Specialty Medicine
Cubital Tunnel Syndrome Market
Specialty Medicine
Sporothrix Schenckii Infection Treatment Market