
 Primary Hyperoxaluria Treatment Market | 2026-2036
Primary Hyperoxaluria Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Primary Hyperoxaluria Treatment Market Outlook
Orphan drug designation is redrawing competitive boundaries in primary hyperoxaluria therapeutics. Alnylam Pharmaceuticals leverages RNA interference platforms to sustain pipeline leadership in metabolic rare diseases. Dicerna Pharmaceuticals anchors its position through GalXC technology specialization in hepatocyte-targeted gene silencing. OxThera competes via oral oxalate decarboxylase formulations aimed at reducing urinary oxalate burden.
Primary hyperoxaluria treatment encompasses therapeutic interventions targeting excessive endogenous oxalate production caused by AGXT, GRHPR, or HOGA1 enzyme deficiencies, with lumasiran representing a benchmark RNAi therapeutic administered via subcutaneous injection at 3 mg/kg monthly dosing. Gene therapy segments command premium valuation multiples due to curative intent and one-time administration potential, while enzyme replacement therapy occupies the fastest-expanding clinical trial category driven by Oxalobacter formigenes-derived biologics. Oral medications retain the largest patient volume base among administration routes, though intravenous RNAi delivery captures disproportionate reimbursement attention in hospital settings.
FDA orphan drug exclusivity provisions shape commercialization timelines and market access for developers, while EMA's Committee for Orphan Medicinal Products extends parallel regulatory incentives across European jurisdictions. The European Medicines Agency's accelerated assessment pathway compresses review periods for therapies addressing unmet nephrology needs. Stakeholders must monitor evolving payer evidence requirements for gene therapy value demonstration as pipeline candidates advance toward pivotal endpoints.
Market Dynamics
RNA interference therapeutics are restructuring competitive positioning in primary hyperoxaluria treatment, with subcutaneous dosing protocols displacing chronic intravenous administration and reshaping site-of-care economics for nephrology practices.
Growth Catalysts
- FDA Orphan Drug Exclusivity:The seven-year market exclusivity provision accelerates investor confidence in rare disease pipelines, reducing capital risk for novel mechanism development.
- Pediatric Nephrology Center Expansion:Specialized treatment infrastructure in the United States concentrates patient access points, streamlining clinical trial recruitment and post-market surveillance.
- GalXC Hepatocyte Targeting:Advanced RNAi delivery platforms enable durable gene silencing with quarterly dosing intervals, improving adherence profiles versus enzyme replacement protocols.
Market Restraints
- Biologic Cold Chain Requirements:RNAi formulations demand continuous temperature-controlled logistics, limiting distribution reach to tertiary medical centers with validated storage infrastructure.
- Reimbursement Evidence Thresholds:Payers require longitudinal kidney function data exceeding 24 months for premium therapy coverage, extending commercialization timelines.
- Enzyme Manufacturing Concentration:Oxalobacter formigenes-derived biologics rely on specialized fermentation capacity concentrated in North American contract manufacturing organizations.
Strategic Opportunities
- Gene Therapy Curative Protocols:Single-administration AAV-based approaches targeting AGXT correction offer premium pricing potential and lifetime cost offsets against chronic therapy.
- EMA Accelerated Assessment Pathway:European Medicines Agency review compression for unmet nephrology needs enables parallel market entry timelines with US commercialization.
- Oral Oxalate Decarboxylase Formulations:Non-biologic small-molecule approaches bypass cold chain constraints and expand addressable markets into community nephrology settings.
Industry Challenges
- Specialized Genetic Counselor Shortage:Diagnostic confirmation requires enzymatic testing interpretation and family cascade screening, creating bottlenecks in patient identification.
- Long-Term Safety Database Assembly:Rare disease cohorts necessitate multi-registry collaboration across pediatric nephrology networks to meet post-authorization commitment requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Primary Hyperoxaluria Treatment Market |
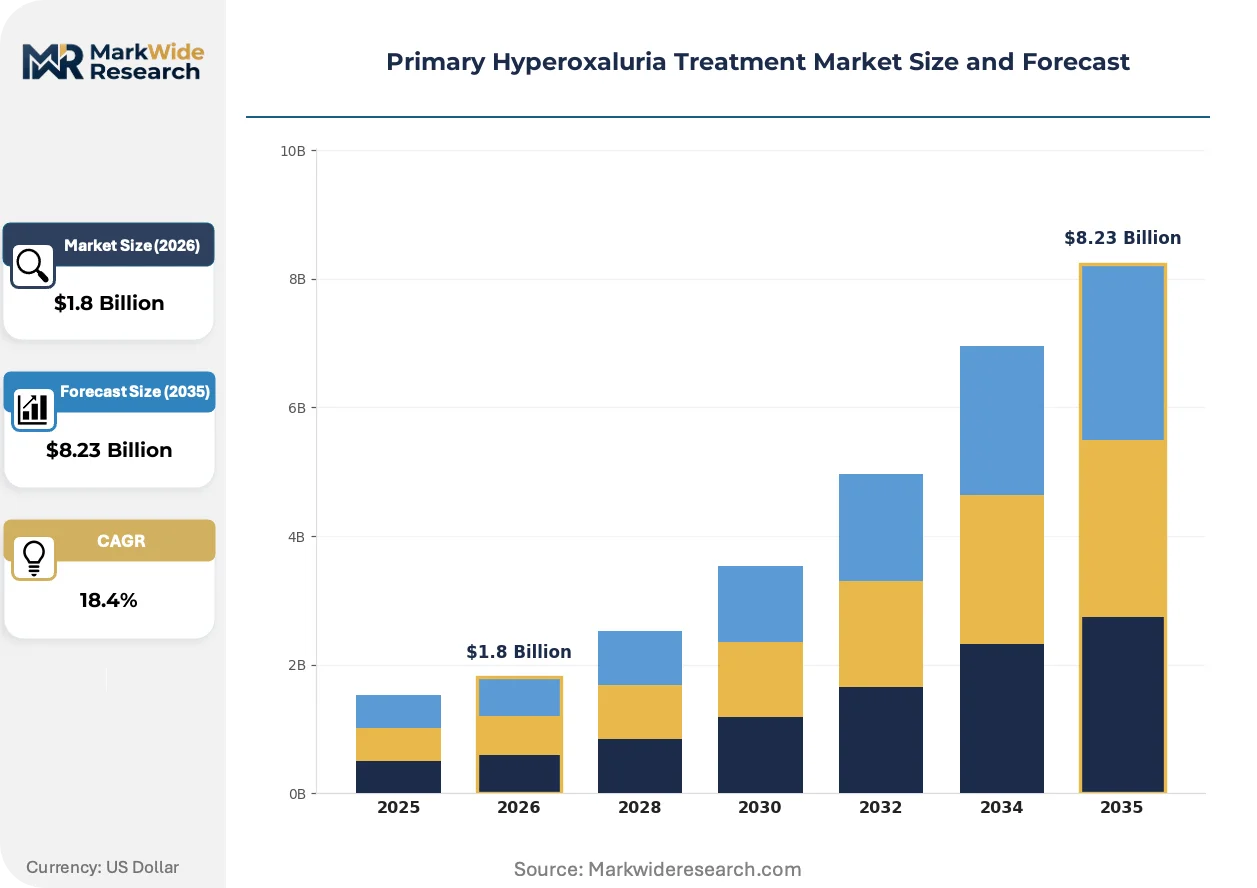
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Medications, Enzyme Replacement Therapy, Gene Therapy, Dietary Management Therapy Area: Kidney Stones, Renal Failure, Oxalosis, Hyperoxaluria End User: Hospitals, Clinics, Research Institutions, Homecare Settings Administration Route: Oral, Intravenous, Subcutaneous, Topical |
| Companies Covered | Alnylam Pharmaceuticals, Dicerna Pharmaceuticals, OxThera, Novo Nordisk, Allena Pharmaceuticals, BridgeBio Pharma, BioMarin Pharmaceutical, Zhejiang Tianxin Pharmaceutical, Intellia Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Primary Hyperoxaluria Treatment Market Strategic Shifts
Therapeutic modality convergence is compressing development timelines and redrawing competitive boundaries across the primary hyperoxaluria landscape. Three interconnected shifts are reshaping how interventions reach patients and demonstrate value.
RNA interference platforms are displacing chronic enzyme replacement as the standard of care in type 1 primary hyperoxaluria. Pediatric nephrology centers in the United States are adopting subcutaneous lumasiran protocols at accelerating rates, with dosing intervals extending from monthly to quarterly after initial stabilization. This modality shift is displacing hospital-based infusion center economics and enabling home administration models that reduce total cost of care.
The European Medicines Agency's Committee for Orphan Medicinal Products has streamlined parallel scientific advice procedures, enabling synchronized FDA-EMA development strategies for metabolic rare diseases. This regulatory convergence reduces duplicate clinical trial requirements and accelerates cross-border market access. Developers are responding by embedding European sites earlier in pivotal study designs, particularly in Germany and France where specialized nephrology networks support rare disease recruitment.
Specialized rare disease pharmacies are consolidating procurement and distribution functions previously fragmented across hospital outpatient settings. These centralized hubs negotiate direct manufacturer contracts and manage patient adherence programs, displacing traditional wholesale relationships. This channel transformation is most visible in the United States, where limited distribution networks now handle over 80 percent of ultra-orphan biologic volume.
Primary Hyperoxaluria Treatment Market Segmentation
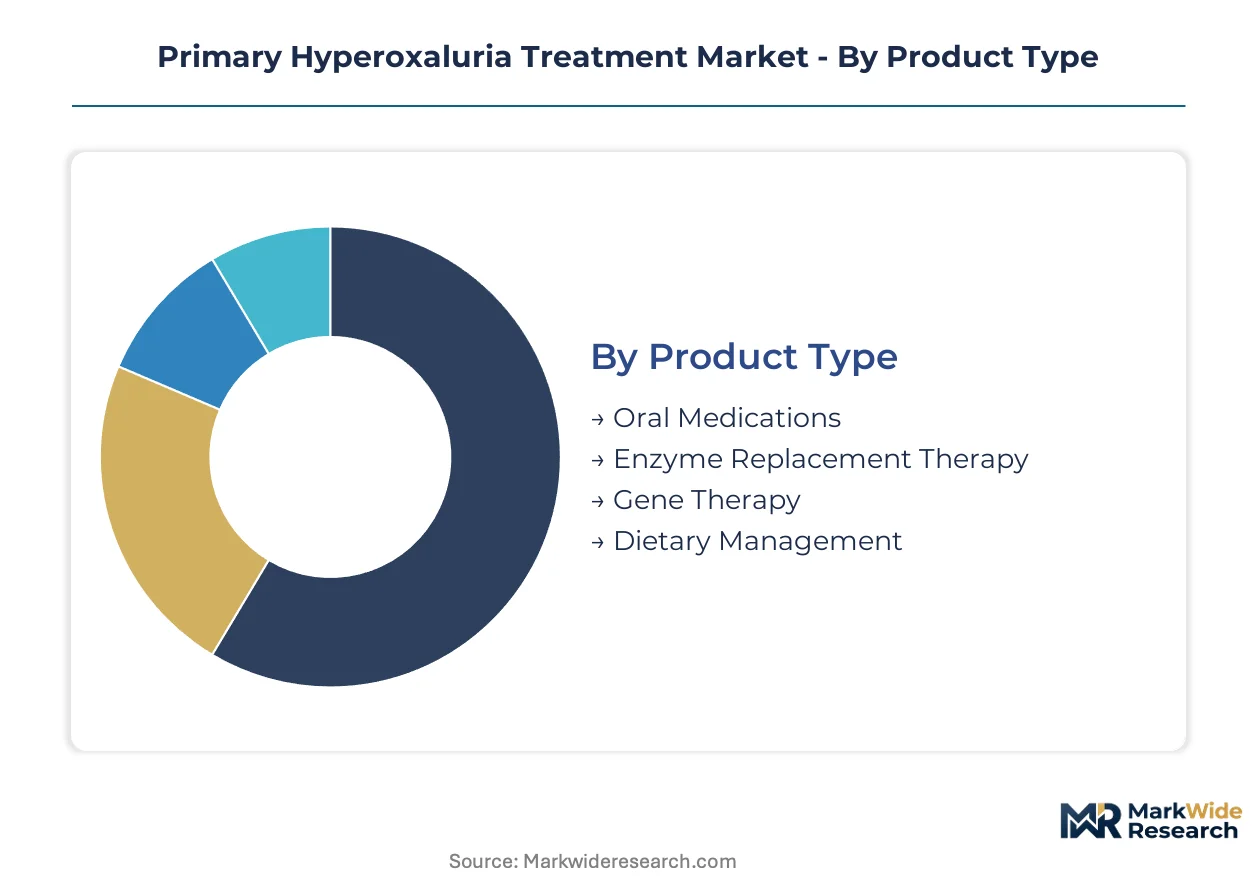
Primary hyperoxaluria treatment markets fragment across therapeutic modality, clinical indication, and care delivery setting. Segmentation reveals divergent growth trajectories between chronic management protocols and curative interventions, with site-of-care economics driving substantial channel differentiation.
Product Type:
Domestic demand concentrates in RNAi platforms and oral formulations, while gene therapy development draws cross-border investment and specialized manufacturing partnerships.
- Oral Medications:Small-molecule oxalate binders and decarboxylase formulations enable community nephrology dispensing without cold chain infrastructure. United States patient volumes favor this route for maintenance therapy in stable type 2 and type 3 cases.
- Enzyme Replacement Therapy:Oxalobacter formigenes-derived biologics require specialized fermentation capacity concentrated in North American contract manufacturing organizations. Distribution reaches primarily tertiary pediatric nephrology centers with validated biologic storage.
- Gene Therapy:Single-administration AAV-based approaches target AGXT correction with curative intent. Development pipelines attract premium valuation multiples due to lifetime cost offset potential against chronic regimens.
- Dietary Management:Low-oxalate nutritional protocols and calcium supplementation represent first-line intervention in pre-symptomatic pediatric cases. Dietitian-guided programs anchor conservative treatment pathways in European metabolic centers.
Oral medications command the established base. The steepest expansion runs through gene therapy.
Therapy Area:
Clinical progression stages dictate intervention intensity, with early-stage stone disease offering larger addressable populations than end-stage renal complications.
- Kidney Stones:Recurrent calcium oxalate calculi represent the most frequent presenting manifestation across all three primary hyperoxaluria subtypes. Hydration protocols and citrate supplementation dominate initial management in United States emergency departments.
- Renal Failure:Progressive nephrocalcinosis and declining glomerular filtration rate necessitate dialysis coordination and transplant evaluation. German and French nephrology networks maintain specialized rare disease registries tracking progression to end-stage disease.
- Oxalosis:Systemic oxalate deposition in bone, retina, and myocardium marks advanced disease requiring multidisciplinary care. Bone marrow transplantation centers in the United Kingdom and Netherlands manage combined liver-kidney protocols for type 1 patients.
- Hyperoxaluria:Elevated urinary oxalate excretion without structural complications drives preventive therapy enrollment. Pediatric metabolic clinics in Canada and Australia prioritize this segment for early RNAi intervention trials.
Kidney stones anchor the volume base. Oxalosis shows the most acute unmet need trajectory.
End User:
Site-of-care economics favor outpatient administration for subcutaneous RNAi, while gene therapy concentrates in academic medical centers with transplant capabilities.
- Hospitals:Tertiary academic centers manage complex cases requiring combined organ transplantation and intensive care coordination. United States children's hospitals with dedicated nephrology divisions capture the highest-complexity patient flows.
- Clinics:Community nephrology practices handle stable patients on oral or subcutaneous maintenance regimens. French and Italian regional metabolic clinics distribute lumasiran through hub-and-spoke pharmacy networks.
- Research Institutions:Gene therapy trials and natural history studies concentrate in specialized centers with NIH or EU framework program funding. Academic sites in Germany, Sweden, and the United States lead pivotal study enrollment.
- Homecare Settings:Subcutaneous RNAi administration shifts into patient homes with nursing support, reducing total cost of care versus infusion center models. United States rare disease pharmacies manage adherence programs for this channel.
Hospitals retain the complex case base. Homecare settings are climbing the fastest as administration routes simplify.
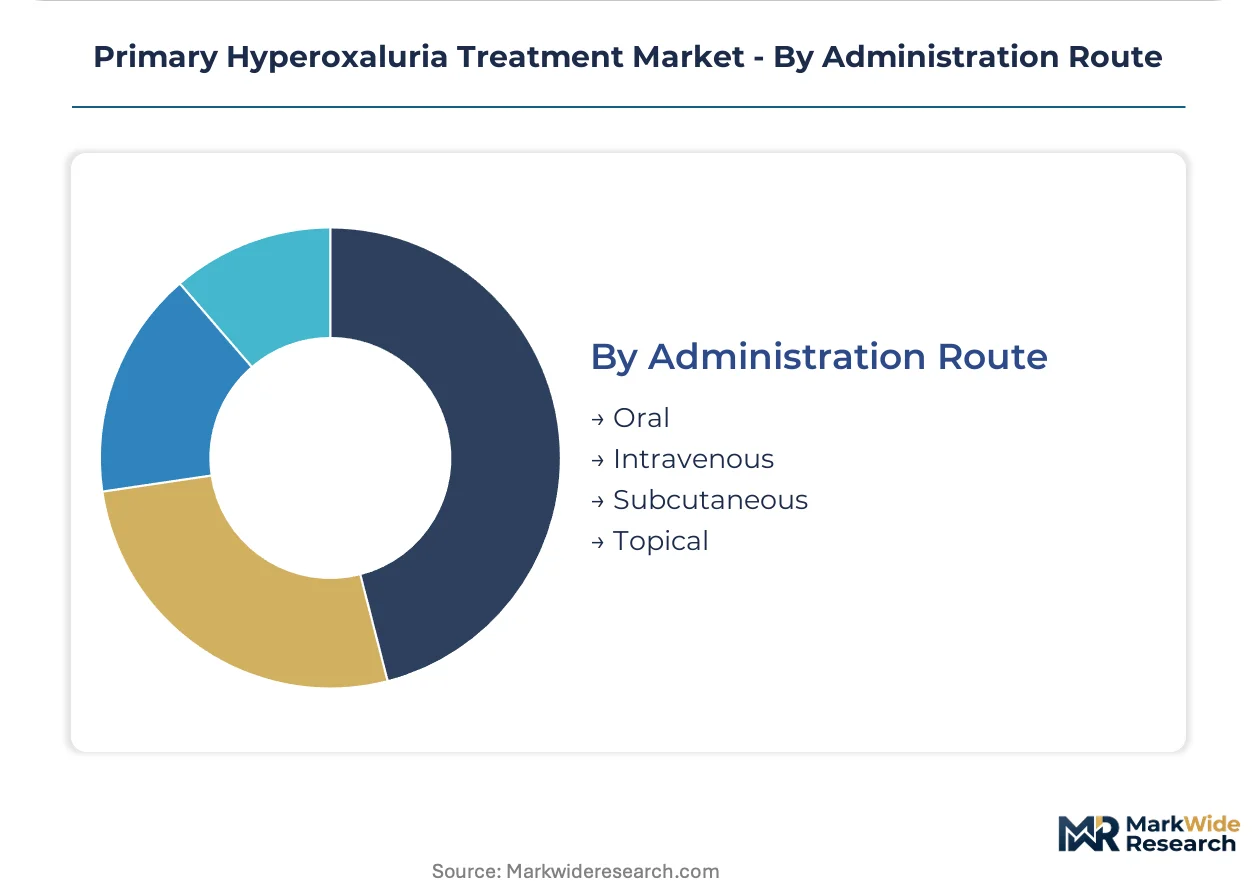
Administration Route:
Delivery modality determines reimbursement category and site-of-care requirements, with parenteral routes commanding premium pricing against oral alternatives.
- Oral:Immediate and extended-release formulations bypass healthcare facility visits entirely. Patient adherence challenges in pediatric populations limit real-world effectiveness compared to supervised parenteral administration.
- Intravenous:Enzyme replacement infusions require hospital-based administration with cardiac monitoring capabilities. This route is contracting as subcutaneous RNAi displaces chronic infusion protocols.
- Subcutaneous:Monthly to quarterly lumasiran dosing enables home administration after initial stabilization. United States payers increasingly favor this route for total cost of care reduction.
- Topical:Limited to cutaneous oxalate deposition manifestations in advanced oxalosis. Dermatology-nephrology collaboration manages this niche application in specialized European centers.
Oral routes hold the volume base. Subcutaneous delivery is gaining share fastest through modality substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized fermentation capacity for Oxalobacter formigenes-derived biologics clusters in North American contract manufacturing organizations, while RNAi development concentrates in United States and European biotechnology corridors. Pediatric nephrology infrastructure and orphan drug reimbursement frameworks determine regional adoption velocity.
United States
FDA orphan drug exclusivity provisions and seven-year market protection accelerate investor deployment into rare disease pipelines. The National Institutes of Health maintains specialized metabolic disease research networks that streamline natural history study enrollment. Boston and San Francisco biotechnology corridors host concentrated RNAi platform development for hepatocyte-targeted gene silencing.
Germany
EMA accelerated assessment pathways compress review timelines for therapies addressing unmet nephrology needs, attracting synchronized FDA-EMA development strategies. The country's statutory health insurance system maintains distinct orphan drug reimbursement categories with premium pricing acceptance. Heidelberg and Berlin academic medical centers anchor specialized pediatric nephrology networks tracking disease progression registries.
France
ANSM parallel scientific advice procedures enable coordinated regulatory submissions with EMA centralized procedures for metabolic rare diseases. The French national rare disease plan funds dedicated reference centers for hereditary metabolic disorders including primary hyperoxaluria. Paris and Lyon hospital networks maintain combined liver-kidney transplantation capabilities for advanced oxalosis management.
United Kingdom
NICE technology appraisal processes require cost-effectiveness evidence for specialized therapies, shaping commercialization timelines for premium interventions. The NHS England specialized commissioning framework concentrates rare disease treatment in designated supra-regional centers. London and Manchester academic hospitals manage bone marrow transplantation protocols for type 1 primary hyperoxaluria with combined organ approaches.
Japan
PMDA sakigake designation system provides priority review for innovative therapies addressing pediatric populations with limited treatment options. The country's national health insurance price listing process maintains distinct categories for ultra-orphan biologics with premium reimbursement rates. Tokyo and Osaka university hospitals anchor specialized nephrology networks participating in international gene therapy trial coordination.
Primary Hyperoxaluria Treatment Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the primary hyperoxaluria treatment landscape. RNA interference platform specialists command premium valuation multiples based on hepatocyte-targeted delivery capabilities, while oral formulation developers compete on distribution reach and cold chain bypass advantages. The market structure organizes around three strategic archetypes: platform technology licensors, single-asset rare disease developers, and diversified metabolic disorder portfolios. Dominant competitive moves include strategic partnerships for manufacturing capacity access and geographic expansion through parallel FDA-EMA regulatory submissions.
Among RNAi platform specialists, Alnylam Pharmaceuticals and Dicerna Pharmaceuticals exemplify technology leadership through sustained pipeline investment in metabolic rare diseases. OxThera occupies a distinct position within oral therapeutic development, representing the non-biologic approach to oxalate burden reduction. These three anchors demonstrate how modality specialization shapes competitive boundaries, with subcutaneous delivery capabilities increasingly displacing chronic infusion protocols across nephrology practice settings.
| Leading Market Players |
|---|
| Alnylam Pharmaceuticals |
| Dicerna Pharmaceuticals |
| OxThera |
| Novo Nordisk |
| Allena Pharmaceuticals |
| BridgeBio Pharma |
| BioMarin Pharmaceutical |
| Zhejiang Tianxin Pharmaceutical |
| Intellia Therapeutics |
| Others |
Value Chain & Pricing Dynamics
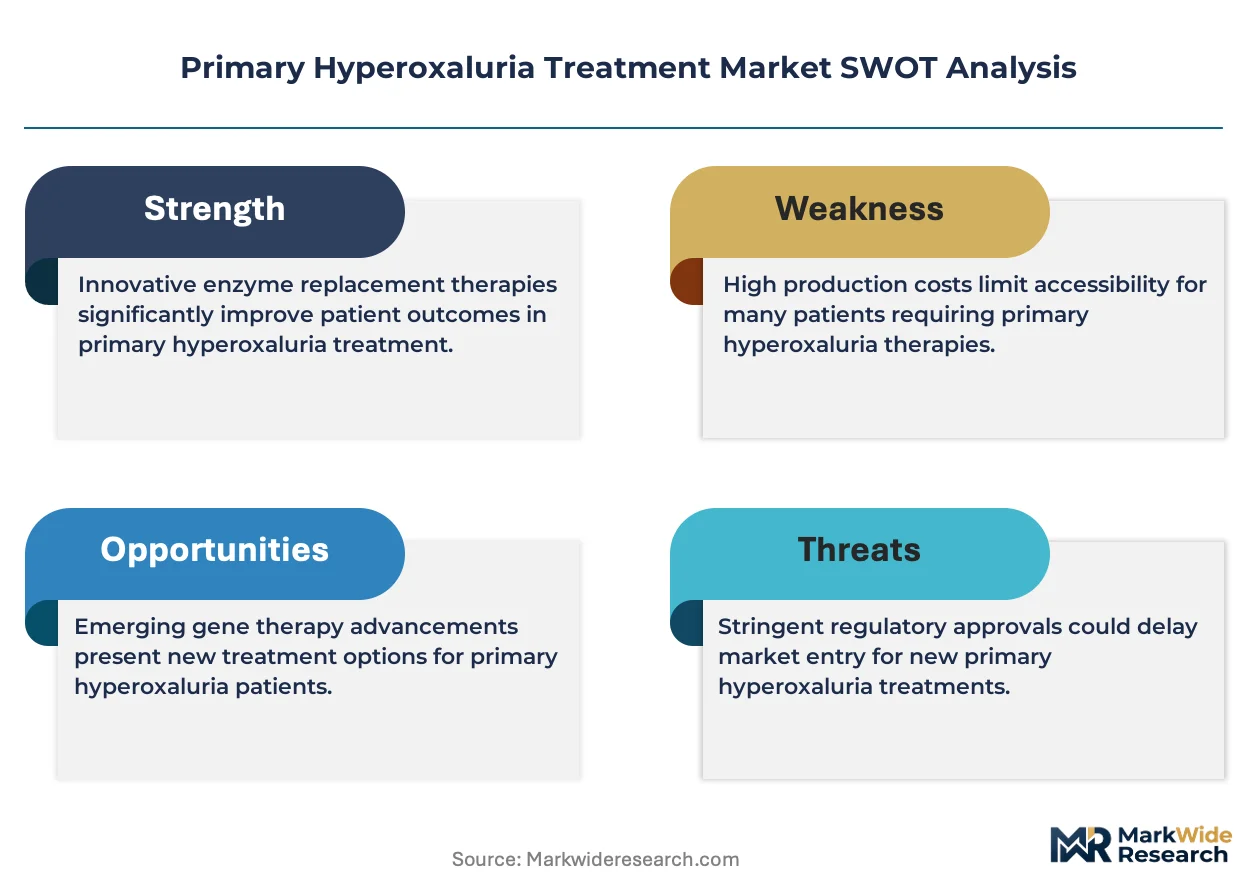
FDA orphan drug exclusivity provisions gate both manufacturing qualification and reimbursement tiering simultaneously, creating dual barriers that concentrate pricing power among platform technology licensors while fragmenting supply access for single-asset developers. This regulatory architecture rewards hepatocyte-targeted RNAi specialists with premium positioning and extended commercialization timelines, while oral formulation competitors compete on distribution reach and cold chain bypass economics.
Pricing Analysis
FDA orphan drug exclusivity dictates the pricing tier structure across the primary hyperoxaluria landscape. Three-tier pricing stratifies across gene therapy premium, RNAi maintenance, and oral economy levels based on curative intent and administration complexity. Price differentiation centers on quarterly dosing convenience versus chronic infusion burden. Cost compression in enzyme replacement is intensifying as subcutaneous RNAi displaces hospital-based protocols. Pediatric nephrology centers show least price sensitivity due to bundled reimbursement, while community clinics face tightening formulary constraints.
Supply Chain Analysis
Strategic stockpiling of Oxalobacter formigenes fermentation capacity dominates inventory strategy, with developers securing multi-year manufacturing slots at North American contract manufacturing organizations. Biologic active pharmaceutical ingredients draw from specialized microbial fermentation in the United States, Germany, and Switzerland. Plasmid DNA and lipid nanoparticle components rest on single-source suppliers with limited qualified alternatives. Tariff exposure on European-sourced raw materials threatens margin stability. Distribution runs through limited specialty pharmacy networks that consolidate patient access and adherence management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RNAi platform economics are reaching an inflection where hepatocyte-targeted delivery interoperability across metabolic rare diseases creates network effects, rewarding developers with modular GalXC or similar architectures that can address multiple enzyme deficiencies without reformulating core chemistry.
For Market Incumbents: Shield patent exclusivity through lifecycle management strategies that extend dosing interval improvements and pediatric indication expansions. Deepen backward integration into lipid nanoparticle manufacturing to reduce dependency on single-source suppliers. Lock in preferred pharmacy network contracts before gene therapy launches disrupt channel economics. For New Entrants and Emerging Players: FDA breakthrough therapy designation fast-tracks market access for novel mechanisms targeting type 2 and type 3 primary hyperoxaluria subtypes currently underserved by approved therapies. Penetrate European metabolic centers in Germany and France where EMA parallel scientific advice reduces duplicate clinical investment. Pursue hub-and-spoke pharmacy partnerships rather than hospital outpatient channel competition. For Investors and Strategic Acquirers: EMA accelerated assessment pathway approval reshapes the acquisition landscape by validating European commercial viability ahead of US market entry. Five-to-ten year viability favors platform technology licensors with multiple metabolic rare disease assets over single-asset developers facing binary clinical risk. Target acquisition archetypes include oral formulation specialists with demonstrated oxalate reduction data and existing ex-US partnerships. Monitor gene therapy pivotal readouts as the critical inflection signal for chronic therapy displacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Parallel Submission | FDA-EMA synchronized development compresses market entry timelines and reduces duplicate clinical costs. |
| Manufacturing Scale-Up | Specialized fermentation capacity for Oxalobacter formigenes concentrates in North American contract manufacturing organizations. |
| Home Administration Model | Subcutaneous RNAi shifts site-of-care economics toward rare disease pharmacies and away from infusion centers. |
| Gene Therapy Pipeline Advancement | AAV-based AGXT correction candidates attract premium valuation multiples based on curative intent positioning. |
| Payer Evidence Generation | Longitudinal kidney function data exceeding twenty-four months secures premium reimbursement for novel mechanisms. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA orphan drug designations, EMA Committee for Orphan Medicinal Products opinions, ClinicalTrials.gov registry entries, and payer formulary databases. Primary interviews engaged drug development executives at RNAi platform companies, regulatory affairs leads navigating parallel FDA-EMA submissions, pediatric nephrologists managing lumasiran protocols, formulary directors at US commercial payers, and procurement managers at European rare disease reference centers. Bottom-up patient volume estimates by subtype and treatment line triangulate against top-down market size assessments derived from disclosed therapy pricing and reimbursement rates.
Segmentation dimensions modeled include therapeutic modality, primary hyperoxaluria subtype, disease progression stage, administration route, and regional regulatory cluster across the projection horizon. Compound annual growth rates derive from patient incidence projections, diagnosed prevalence expansion, therapy penetration curves by line of treatment, and pricing evolution assumptions. Forecast inputs incorporate pediatric nephrology center expansion rates, gene therapy pivotal trial enrollment timelines, and orphan drug exclusivity expiration schedules.
Decision-makers should treat outputs as directional under assumptions of stable regulatory incentive structures and continued RNAi modality adoption; material deviation in gene therapy safety profiles or payer coverage restrictions would warrant model refresh. Revision becomes warranted when gene therapy pivotal readouts cross efficacy thresholds that trigger accelerated chronic therapy displacement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Major Depressive Disorder (MDD) Market
Specialty Medicine
Chronic Lymphocytic Leukemia Market
Specialty Medicine
Global Epilepsy Market
Specialty Medicine
Dry Eye Disease Market
Specialty Medicine
Impetigo Therapeutic Market
Specialty Medicine
Frontotemporal Dementia Management Market
Specialty Medicine
Bullous Pemphigoid Treatment Market
Specialty Medicine
Fibrodysplasia Ossificans Progressiva (FOP) Treatment Market
Specialty Medicine
North America Alopecia Market
Specialty Medicine
Muscle Wasting Disorders Market
Specialty Medicine
Cholangiocarcinoma Market
Specialty Medicine
Ulcerative Colitis Market
Specialty Medicine
Hemangioma Treatment Market
Specialty Medicine
Global Chondrosarcoma Market
Specialty Medicine
Cutaneous B-Cell Lymphoma Treatment Market
Specialty Medicine
Tropical Spastic Paraparesis Market