
 Dupuytrens Disease Market | 2026-2036
Dupuytrens Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Dupuytrens Disease Market Analytics
Collagenase enzyme production is fragmenting across contract manufacturers and in-house biologics facilities. Bayer AG leverages its pharmaceutical manufacturing scale to sustain bulk enzyme supply chains. Endo International plc anchors North American distribution networks for injectable formulations. Novartis AG competes through specialized R&D programs targeting fibroblast biology.
Dupuytrens disease is a progressive fibroproliferative disorder characterized by abnormal collagen deposition in the palmar fascia, forming palpable cords and fixed flexion contractures of the fingers. Collagenase Clostridium Histolyticum enzymatically disrupts collagen types I and III at specific cleavage sites, enabling percutaneous cord dissolution without open surgery. The treatment approach dimension shows minimally invasive procedures capturing expanded reimbursement codes while surgical intervention retains dominance for severe recurrent contractures. End user dynamics reveal hospitals consolidating complex case volumes as clinics absorb routine enzymatic injections.
The FDA regulates collagenase biologics under BLA pathways with REMS requirements for safe administration. EMA's MDR framework governs CE-marked surgical instruments and needle aponeurotomy devices across European markets. Stakeholders must monitor evolving HTA assessments for collagenase versus surgical comparators as payers recalibrate value-based contracting structures.
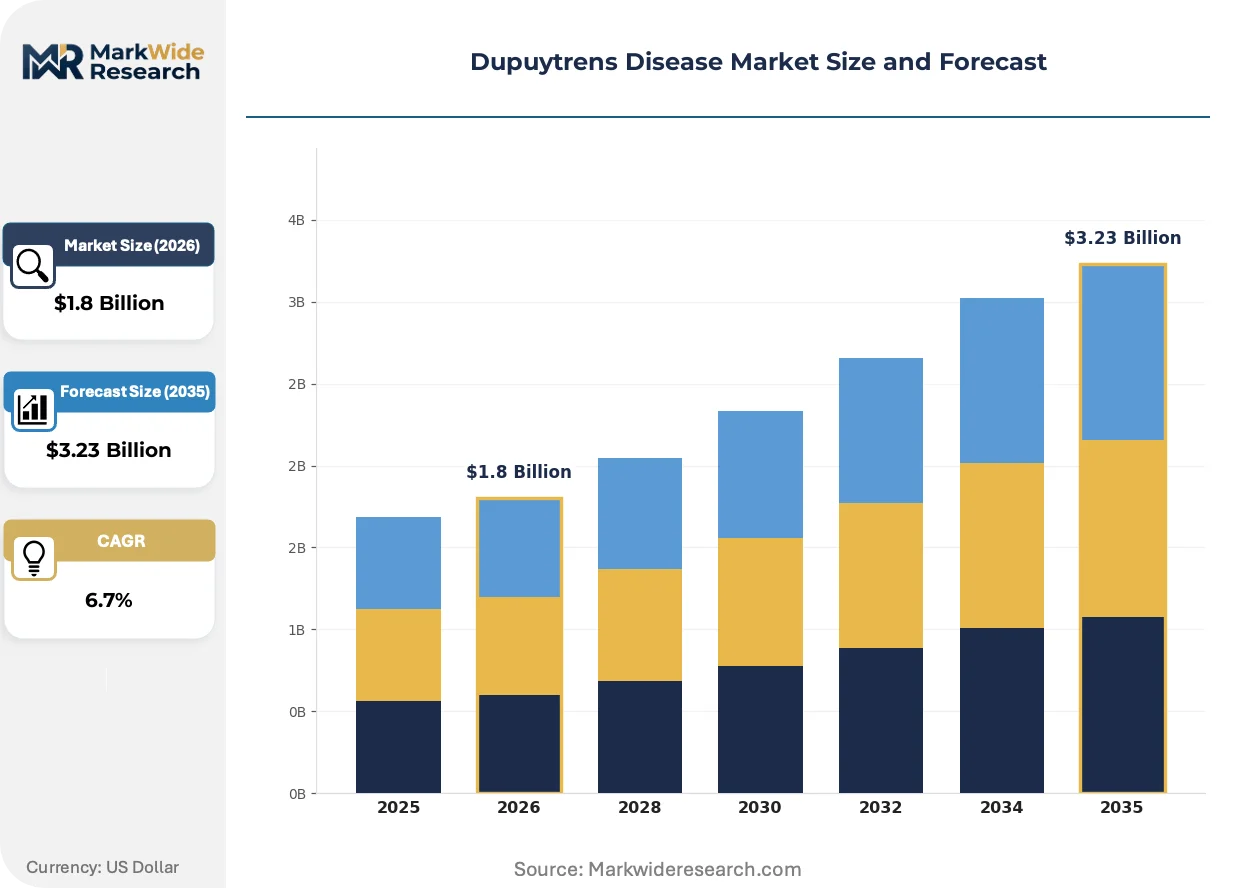
Market Dynamics
Hospital outpatient departments are consolidating complex enzymatic procedures while specialized hand surgery centers absorb routine collagenase injections, reshaping referral patterns and capital allocation across treatment settings.
Growth Catalysts
- Orphan drug designation pathway:The FDA's accelerated approval mechanism shortens development timelines for novel enzymatic treatments targeting fibroblast biology.
- Minimally invasive reimbursement expansion:Germany's statutory health insurance funds have broadened procedure codes for percutaneous cord dissolution in specialized hand surgery centers.
- Collagenase manufacturing scale-up:Contract biologics facilities in Switzerland and Ireland are expanding GMP-compliant enzyme production capacity to meet hospital procurement volumes.
Market Restraints
- Clostridial enzyme supply concentration:Bulk collagenase production remains captive to three specialized fermentation facilities in Western Europe, creating single-source vulnerability.
- EMA MDR compliance burden:The Medical Device Regulation framework imposes extended clinical evaluation timelines for needle aponeurotomy instruments, delaying CE-marked product launches.
- Surgical recurrence substitution:Open fasciectomy retains dominance for severe recurrent contractures with palmar involvement exceeding 40 degrees, limiting enzymatic addressable cases.
Strategic Opportunities
- Early-stage disease interception:Diagnostic ultrasound protocols enable detection of pre-cord palmar thickening in Dutch occupational health screening programs.
- Combination therapy protocols:Simultaneous enzymatic injection with low-dose radiation therapy is being evaluated in French university hospital consortiums for aggressive diathesis patients.
- Specialized clinic channel development:Standalone hand surgery clinics in Australia are securing direct-to-payer contracts for same-day enzymatic procedures, bypassing hospital facility fees.
Industry Challenges
- REMS administration training:The FDA-mandated Risk Evaluation and Mitigation Strategy requires certified healthcare providers for collagenase injection, creating enrollment bottlenecks.
- Cold-chain distribution integrity:Temperature excursions during last-mile delivery to ambulatory surgery centers compromise enzyme potency and trigger batch recalls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dupuytrens Disease Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Needle Aponeurotomy, Collagenase Clostridium Histolyticum, Surgery, Radiation Therapy End User: Clinics, Hospitals, Surgical Centers, Rehabilitation Facilities Treatment Approach: Minimally Invasive, Surgical, Conservative, Physiotherapy Age Group: Adults, Seniors, Teenagers, Geriatric |
| Companies Covered | Endo International plc, Bayer AG, Novartis AG, Pfizer Inc., AstraZeneca PLC, Bristol-Myers Squibb Company, GSK plc, Hikma Pharmaceuticals PLC, LEO Pharma A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dupuytrens Disease Market Evolving Landscape
Enzymatic therapy protocols are compressing treatment timelines from multi-visit surgical pathways to single-visit interventions, forcing equipment manufacturers and facility operators to reconfigure procedural workflows and revenue recognition models.
Next-generation collagenase formulations are collapsing the distinction between cord dissolution and functional rehabilitation. Bioengineered enzyme variants with extended half-lives enable complete cord rupture within 24 hours, allowing hand therapists to initiate same-day range-of-motion protocols. German rehabilitation clinics are adopting these accelerated pathways to reduce total episode costs.
EMA's Medical Device Regulation is tightening clinical evidence requirements for percutaneous needle aponeurotomy devices. Manufacturers must now submit prospective registry data demonstrating non-inferiority to surgical comparators for severe contractures. Irish and Dutch notified bodies are prioritizing review queues for devices with integrated ultrasound guidance capabilities.
Patient-directed care models are fragmenting traditional referral networks. Self-referring patients in the United Kingdom are accessing private enzymatic injection clinics through direct online booking platforms, bypassing general practitioner gatekeeping. This channel shift is concentrating volume in high-throughput metropolitan clinics while depleting rural hospital outpatient departments of routine cases.
Dupuytrens Disease Market Segmentation
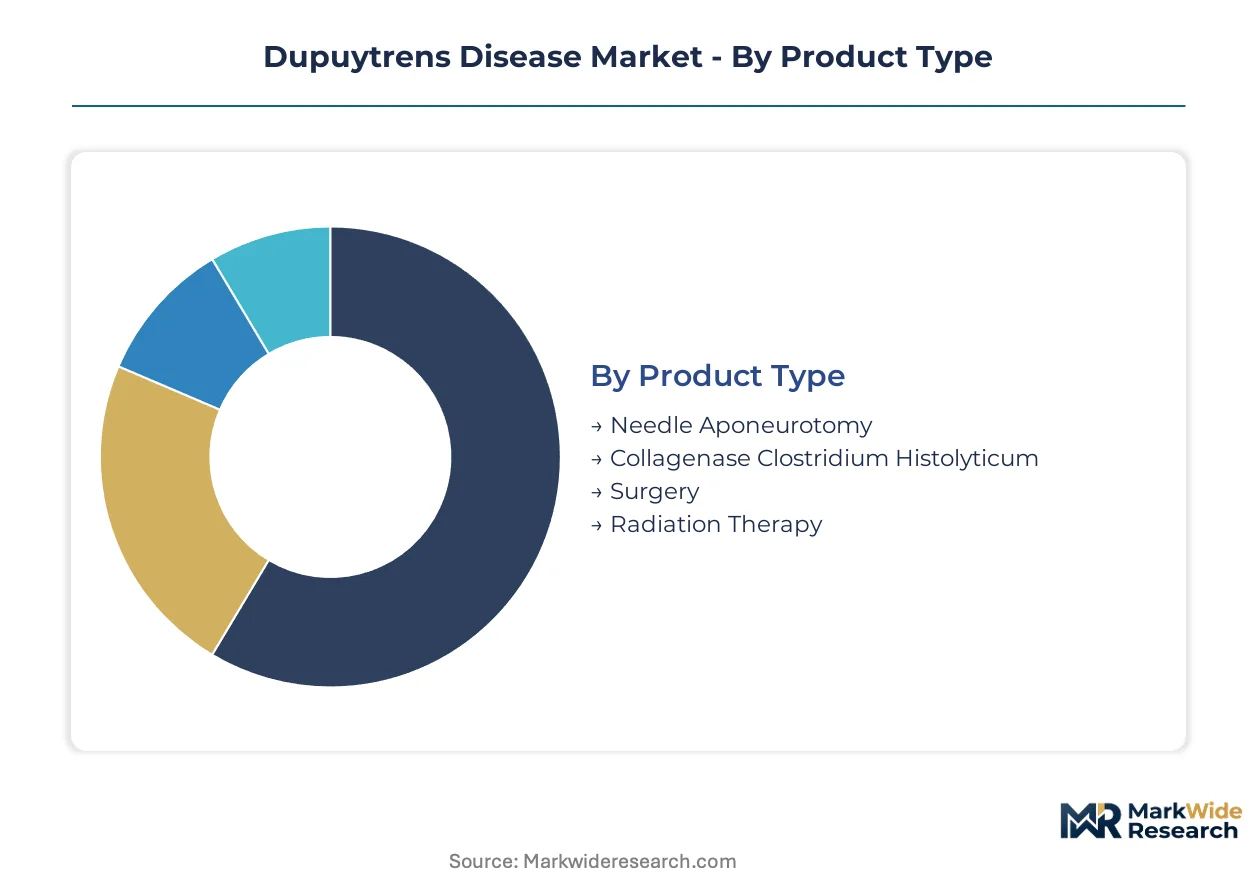
Dupuytrens disease treatment pathways fragment across intervention intensity, care setting, and patient demographics. Each dimension carries distinct reimbursement logic, regulatory requirements, and capital deployment patterns that reshape competitive positioning.
Product Type:
Cost tier differentiation separates enzymatic biologics from capital-intensive surgical infrastructure and single-use percutaneous instruments.
- Collagenase Clostridium Histolyticum:Purified bacterial enzyme formulation cleaves collagen types I and III at specific Gly-Ile/Leu bonds. Hospital outpatient departments in Germany and the United States are consolidating procurement volumes under centralized pharmacy contracts, though cold-chain logistics constraints limit ambulatory expansion.
- Surgery:Open fasciectomy and dermofasciectomy procedures require operating room infrastructure and specialized hand surgery fellowship training. Severe recurrent contractures with palmar involvement exceeding 40 degrees retain surgical dominance due to durability advantages over enzymatic alternatives.
- Needle Aponeurotomy:Percutaneous cord transection using beveled hypodermic needles performed under local anesthesia in office settings.
- Radiation Therapy:Low-dose orthovoltage or electron beam protocols targeting proliferative disease stages in European university hospital consortiums.
Collagenase commands the established base. The steepest expansion runs through needle aponeurotomy.
End User:
Customer type stratification reflects diverging risk tolerance for complex cases versus routine procedure throughput.
- Hospitals:Academic medical centers and community hospitals capture severe bilateral cases, recurrent contractures, and complications requiring microvascular reconstruction. EMA MDR compliance burdens for surgical instruments concentrate purchasing decisions within centralized supply chain committees.
- Surgical Centers:Ambulatory surgery facilities optimize same-day fasciectomy workflows with dedicated hand therapy co-location. Standalone clinics in Australia are securing direct-to-payer contracts that bypass hospital facility fees.
- Clinics:Office-based settings deliver collagenase injections and needle aponeurotomy with lower overhead structures.
- Rehabilitation Facilities:Post-intervention hand therapy centers manage splinting protocols and range-of-motion restoration.
Hospitals anchor complex case revenue. Surgical centers are climbing the fastest as same-day procedure volumes migrate from inpatient settings.
Treatment Approach:
Application intensity spans from watchful waiting to tissue-disrupting interventions with irreversible structural consequences.
- Minimally Invasive:Enzymatic injection and percutaneous techniques preserve palmar skin integrity while achieving functional correction. Germany's statutory health insurance funds have broadened procedure codes for these approaches in specialized hand surgery centers.
- Surgical:Excisional techniques remain definitive for aggressive diathesis patterns and digital neurovascular involvement.
- Conservative:Splinting and observation protocols manage early-stage disease without tissue disruption.
- Physiotherapy:Post-intervention rehabilitation and maintenance programs prevent recurrence.
Surgical approaches retain the revenue base. Minimally invasive methods show the steepest expansion trajectory as reimbursement codes broaden.
Age Group:
Volume concentration aligns with disease prevalence curves and surgical risk stratification.
- Seniors:Patients aged 65-75 present highest procedure volumes with established contractures requiring intervention. Dutch occupational health screening programs are detecting pre-cord thickening in this demographic earlier through diagnostic ultrasound protocols.
- Geriatric:Patients over 80 face anesthesia risk constraints that favor office-based enzymatic injection over operative management.
- Adults:Working-age patients between 50-64 drive early intervention demand to preserve manual occupational function.
- Teenagers:Rare juvenile onset cases require specialized pediatric hand surgery referral pathways.
Seniors represent the procedural volume base. Geriatric patients are expanding most quickly as enzymatic alternatives reduce anesthesia exposure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys collagenase interventions as first-line therapy through specialized hand surgery centers, while the United States maintains surgical dominance for severe recurrent contractures. This consumption-mix differential shapes procurement patterns and reimbursement negotiations across markets.
United States
Hospital outpatient departments in the United States are consolidating enzymatic procedure volumes under centralized pharmacy contracts. The FDA regulates collagenase biologics under BLA pathways with REMS requirements for certified healthcare providers. Major metropolitan clusters in the Northeast and Midwest are absorbing routine injections while academic medical centers retain complex revision cases.
Germany
Statutory health insurance funds in Germany have broadened procedure codes for percutaneous cord dissolution in specialized hand surgery centers. The country's national pharmaceutical regulator, the Federal Institute for Drugs and Medical Devices (BfArM), aligns with EMA MDR frameworks for CE-marked surgical instruments. The Rhineland and Bavaria regions host high-throughput metropolitan clinics that bypass traditional hospital referral networks through direct patient access.
United Kingdom
Self-referring patients in the United Kingdom are accessing private enzymatic injection clinics through direct online booking platforms. The Medicines and Healthcare products Regulatory Agency (MHRA) oversees post-Brexit biologics licensing with retained EU MDR alignment for medical devices. London and the Southeast are concentrating volume in high-throughput metropolitan clinics while depleting rural hospital outpatient departments of routine cases.
France
French university hospital consortiums are evaluating combination therapy protocols involving simultaneous enzymatic injection with low-dose radiation therapy for aggressive diathesis patients. The National Agency for Food, Environmental and Occupational Health Safety (ANSM) governs clinical trial authorizations for novel enzymatic formulations. The Paris metropolitan region anchors multicenter research coordination while Lyon and Marseille clusters specialize in post-intervention rehabilitation protocols.
Australia
Standalone hand surgery clinics in Australia are securing direct-to-payer contracts for same-day enzymatic procedures, bypassing hospital facility fees. The Therapeutic Goods Administration (TGA) maintains parallel registration pathways for biologics and medical devices with priority review queues for ultrasound-integrated delivery systems. Sydney and Melbourne metropolitan areas are pioneering patient-directed care models that fragment traditional referral networks.
Dupuytrens Disease Market Competitive Landscape
Capability concentration sits with specialized biologics manufacturers; scale advantage sits with diversified pharmaceutical conglomerates. The market structure organizes around three strategic archetypes: integrated pharmaceutical conglomerates with captive enzyme supply chains, contract biologics manufacturers with GMP-compliant fermentation capacity, and specialized hand surgery device developers with percutaneous delivery platforms. Dominant competitive moves include backward integration into bulk collagenase production and strategic partnerships with rehabilitation clinic networks for post-intervention protocol standardization.
Within the integrated pharmaceutical tier, Bayer AG and Endo International plc occupy positions that exemplify divergent geographic anchoring. The German conglomerate leverages pharmaceutical manufacturing scale to sustain bulk enzyme supply chains, while the Irish-domiciled specialty pharmaceutical company anchors North American distribution networks for injectable formulations. Novartis AG sits within the R&D-intensive archetype, competing through specialized programs targeting fibroblast biology rather than manufacturing scale.
| Leading Market Players |
|---|
| Endo International plc |
| Bayer AG |
| Novartis AG |
| Pfizer Inc. |
| AstraZeneca PLC |
| Bristol-Myers Squibb Company |
| GSK plc |
| Hikma Pharmaceuticals PLC |
| LEO Pharma A/S |
| Others |
Value Network & Pricing Analysis
Frankfurt-Rotterdam pharmaceutical freight corridors carry cold-chain collagenase shipments where temperature-controlled logistics costs compound the pricing power of Western European fermentation facilities. Hospital procurement committees in Germany and the United States negotiate centralized pharmacy contracts that compress margins for distributors while enzymatic manufacturers retain premium tiers through REMS-certified provider networks.
Pricing Analysis
Long-term offtake agreements dominate hospital system procurement, with spot purchasing limited to emergency stockouts and clinical trial supply. Pricing stratifies across premium certified-provider tiers, standard hospital outpatient bundles, and economy clinic-direct channels, with REMS certification and cold-chain reliability as primary differentiation drivers. Cost compression in the economy tier is intensifying as Australian standalone clinics bypass hospital facility fees through direct-to-payer contracting. Academic medical centers show lowest price sensitivity due to bundled episode reimbursement, while rural ambulatory surgery centers face acute margin pressure from logistics overhead.
Supply Chain Analysis
Fermentation feedstock for Clostridium histolyticum enzyme production draws from specialized biologics facilities in Switzerland, Ireland, and Germany, with GMP-compliant capacity expansion concentrated in Basel and Dublin industrial clusters. Raw material dependencies include bacterial culture media, chromatography resins, and pharmaceutical-grade stabilizers for lyophilized formulations. Single-source vulnerability runs through the three Western European bulk enzyme producers, where any regulatory inspection shutdown disrupts global hospital pharmacy inventories. Distribution runs through temperature-controlled third-party logistics networks with validated cold-chain monitoring to hospital outpatient departments and ambulatory surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patient-directed care models fragment traditional referral networks into metropolitan clinic clusters and rural hospital outposts, creating niche entry points for specialized service providers and regional distributors.
For Market Incumbents: Harden REMS-certified provider networks against encroachment from direct-to-consumer booking platforms that bypass hospital gatekeeping. Secure backward integration into bulk collagenase fermentation capacity in Switzerland or Ireland to eliminate single-source supply risk. Anchor procurement relationships with German statutory health insurance funds through outcomes-based contracting for percutaneous cord dissolution protocols. For New Entrants and Emerging Players: Rural hospital outpatient departments in the United Kingdom present the most penetrable white space, depleted of routine cases by metropolitan clinic concentration. Target radiation therapy combination protocols in French university hospital consortiums as a differentiated service layer. Pursue ultrasound-integrated delivery system partnerships with Australian standalone clinics to establish channel presence without hospital infrastructure investment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors contract biologics manufacturers with GMP-compliant fermentation assets and established hospital pharmacy relationships over pure-play device developers. Long-term viability hinges on enzymatic formulation durability versus surgical recurrence rates in severe contracture populations. Monitor EMA MDR approval timelines for needle aponeurotomy devices with integrated imaging guidance as an inflection signal for percutaneous technique adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Provider Network Expansion | Certified injection training programs lock in hospital outpatient volume against clinic competitors. |
| Cold-Chain Logistics Partnership | Temperature-validated distribution agreements with Swiss and Irish carriers reduce batch recall risk. |
| Ultrasound-Guided Device Development | CE-marked instruments with integrated imaging satisfy EMA MDR clinical evidence requirements. |
| Combination Therapy Clinical Trial | French radiation-enzyme protocols create differentiation in aggressive diathesis patient segments. |
| Direct-to-Payer Contracting | Australian clinic models bypass hospital facility fees and compress total episode costs. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA BLA submissions, EMA MDR technical documentation, German BfArM procedure code registers, and Australian TGA priority review queues. Hand surgeons, hospital pharmacy directors, collagenase manufacturing quality leads, and statutory health insurance fund formulary managers provided structured input. Bottom-up procedure volume estimates from hospital procurement databases triangulate against top-down pharmaceutical sales audits.
Forecast inputs span treatment approach intensity, care setting migration patterns, patient age demographic shifts, and regional regulatory cluster adoption curves across the projection horizon. Segmentation dimensions model product type tiering, end-user facility category, intervention invasiveness level, and age-stratified procedure eligibility. CAGRs derive from logarithmic trend fitting to historical procedure volume trajectories adjusted for reimbursement code expansion and enzymatic manufacturing capacity constraints.
Practitioners should monitor EMA MDR inspection schedules for notified body backlogs, FDA REMS provider enrollment bottlenecks, and cold-chain logistics disruption events for early signals of forecast revision. Cross-checking against German statutory health insurance quarterly procedure reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
ACTH Deficiency Treatment Market
Specialty Medicine
Global Lung Transplant Therapeutics Market
Specialty Medicine
Polymyalgia Rheumatica Treatment Market
Specialty Medicine
Global Gastroparesis Treatment Market
Specialty Medicine
Severe Combined Immunodeficiency Market
Specialty Medicine
Hypertrophic Cardiomyopathy (HCM) Therapeutics Market
Specialty Medicine
Central Nervous System (CNS) Biomarkers Market
Specialty Medicine
Global Photodynamic Therapy Market
Specialty Medicine
United States Specialty Generics Market
Specialty Medicine
Triple X Syndrome Management Market
Specialty Medicine
Ankylosing Spondylitis Treatment Market
Specialty Medicine
Animal Hormone Therapy Market
Specialty Medicine
Barotrauma Market
Specialty Medicine
Major Depressive Disorder (MDD) Treatment Market
Specialty Medicine
Acute Hepatic Porphyria (APH) Market
Specialty Medicine
Piriformis Syndrome Market