
 Rotogravure Printing Inks Market | 2026-2036
Rotogravure Printing Inks Market Size, Share, and Industry Trends Forecast 2026-2036
Rotogravure Printing Inks Market Outlook
EU REACH chemical authorization thresholds is repositioning the cost-of-entry calculus for solvent-based gravure ink suppliers serving European flexible packaging converters. DIC Corporation leverages integrated pigment manufacturing to sustain margin control across Asia-Pacific supply chains. Flint Group anchors its competitive stance through specialized cylinder engraving partnerships that reduce job-change downtime for high-volume publication gravure runs. Siegwerk Druckfarben AG & Co. KGaA differentiates via bio-based binder development programs targeting food-contact compliance without toluene-based carrier systems.
Rotogravure printing inks comprise fluid formulations engineered for transfer from engraved copper cylinders to substrates at speeds exceeding 300 meters per minute, with solvent-based variants historically dominating due to superior drying latitude on non-absorbent films. These inks serve primarily high-volume, long-run applications demanding precise color consistency across millions of impressions. Solvent-based formulations retain structural dominance in flexible packaging for retort pouches and metallized films where water-based systems still face adhesion limits on polyolefin surfaces. Water-based gravure inks represent the fastest-expanding category as brand owners mandate elimination of volatile organic compound emissions in consumer-facing wrap applications. UV-curable segments concentrate margin pools in narrow-web decorative and security printing where instant polymerization enables substrate versatility unavailable to thermal drying architectures.
EPA National Emission Standards for Hazardous Air Pollutants governs gravure press solvent capture requirements in US flexible packaging operations, while China's MEE enforces progressively stricter VOC discharge limits that compel domestic converters toward water-based or recovered-solvent systems. Japan's METI chemical substance reporting frameworks add compliance layering for imported ink formulations containing designated priority assessment chemicals. Stakeholders must monitor regulatory divergence between Asian production hubs and European import standards to avoid stranded inventory in cross-border packaging supply chains.
Market Dynamics
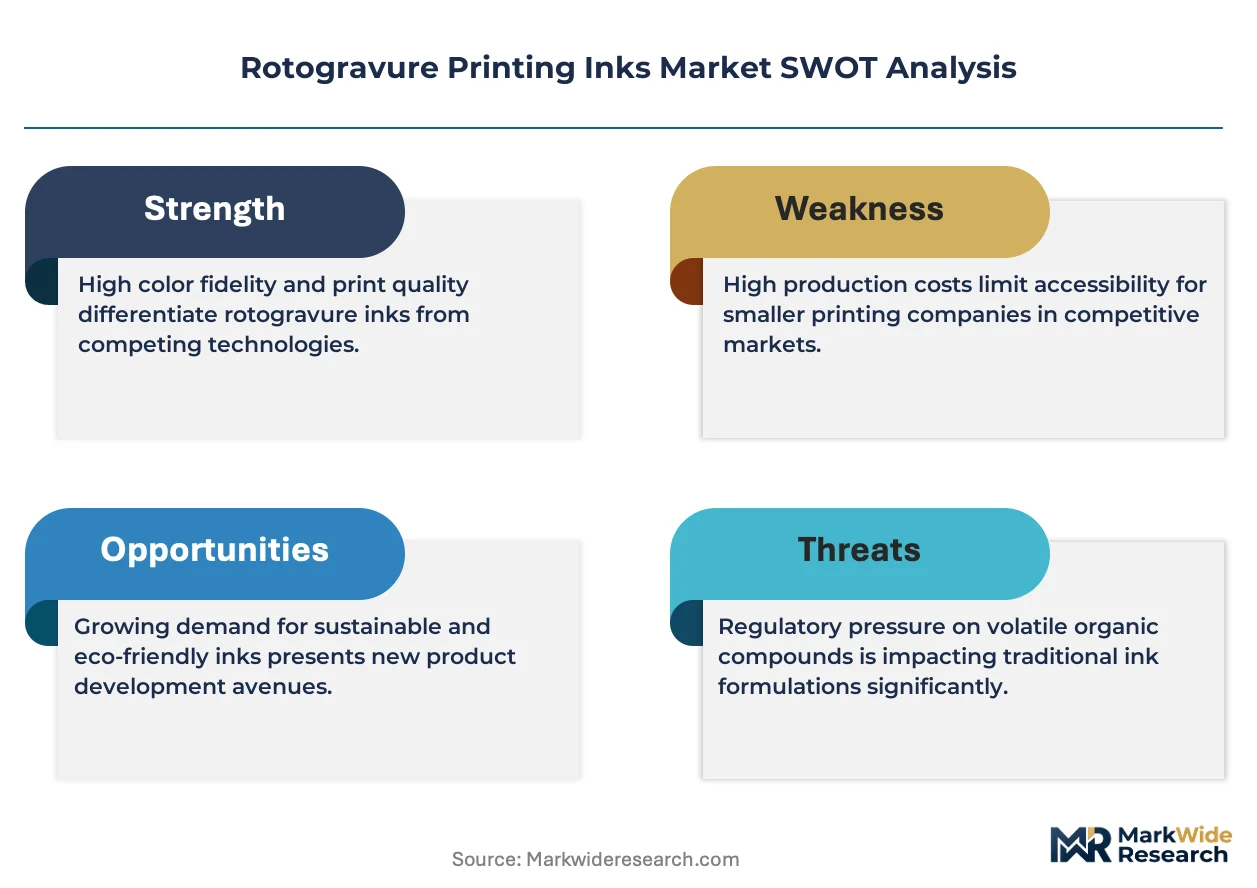
Water-based gravure ink adoption is compressing solvent-based margins as converters absorb compliance costs from tightening VOC discharge limits across major manufacturing hubs.
Growth Catalysts
- Flexible packaging demand:Food and beverage wrap production in China, India, and Indonesia is outpacing domestic ink supply maturity, pulling in capacity expansion from regional converters.
- REACH chemical authorization:European compliance thresholds are repositioning entry economics for solvent-based suppliers, accelerating investment in recovery systems and alternative formulations.
- High-speed press architecture:Engraved copper cylinder technology sustaining run lengths exceeding millions of impressions preserves gravure's cost position against digital alternatives in long-run publishing.
Market Restraints
- Pigment cost volatility:Titanium dioxide and organic pigment feedstock fluctuations compress formulation margins for mid-tier ink suppliers without captive mineral processing.
- Water-based adhesion limits:Polyolefin film surfaces resist aqueous binder systems, trapping retort pouch and metallized film applications in solvent-based architectures despite regulatory pressure.
- MEE enforcement layering:China's progressively stricter VOC discharge limits strand converters with legacy solvent recovery infrastructure insufficient for new thresholds.
Strategic Opportunities
- Bio-based binder development:Food-contact compliant toluene-free carrier systems open premium positioning for suppliers targeting EU Packaging and Packaging Waste Regulation alignment.
- Indonesia domestic consumption:Underdeveloped local ink supply relative to packaging demand growth creates white space for regional production facilities.
- UV-curable narrow-web expansion:Instant polymerization technology enables substrate versatility in decorative and security printing applications where thermal drying architectures face constraints.
Industry Challenges
- Cylinder engraving skill scarcity:Specialized engraving partnerships require multi-year apprenticeship pipelines that lag press capacity expansion timelines.
- Cross-border inventory stranding:Regulatory divergence between Asian production hubs and European import standards creates compliance layering complexity for multinational converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotogravure Printing Inks Market |
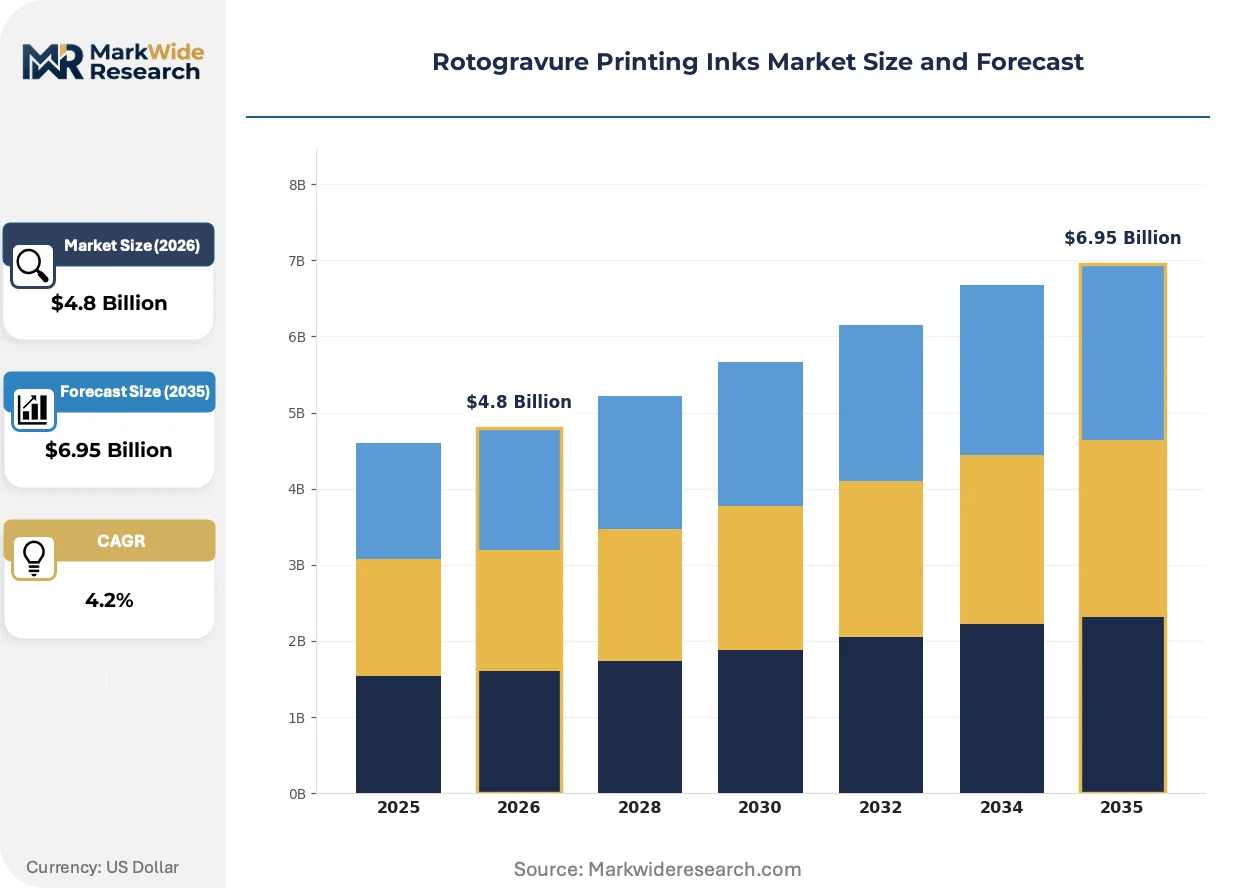
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ink Type: Solvent-based, Water-based, UV-curable, Eco-solvent Substrate Type: Paper, Plastic, Metal, Film End User: Packaging, Publishing, Labels, Decorative Application: Flexible Packaging, Cartons, Wraps, Tags |
| Companies Covered | Toyo Ink SC Holdings Co., Ltd., INX International Ink Co., DIC Corporation, Dainichiseika Color & Chemicals Mfg. Co., Ltd., T&K Toka Co., Ltd., Flint Group, Sakata INX Corporation, Hubergroup Deutschland GmbH, Siegwerk Druckfarben AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotogravure Printing Inks Market Strategic Shifts
Formulation chemistry and drying architecture are diverging along regulatory fault lines, with compliance-driven R&D investment reshaping competitive differentiation.
Water-based gravure ink technology is absorbing the bulk of converter capex in food-contact flexible packaging as brand owners mandate VOC elimination in consumer-facing applications. Major flexible packaging converters across Asia-Pacific are retrofitting drying systems to accommodate aqueous formulations at speeds approaching solvent-based benchmarks. The technology is absorbing margin pressure from extended drying tunnels and energy consumption while capturing share in snack and confectionery wrap segments previously dominated by toluene-based systems.
EPA National Emission Standards for Hazardous Air Pollutants is mandating solvent capture infrastructure in US flexible packaging operations, pressuring smaller converters toward consolidated press operations or third-party tolling arrangements. The regulation compresses operational flexibility for multi-substrate job shops while favoring dedicated high-volume facilities with integrated recovery systems. California and Northeast corridor states are layering additional air district rules that exceed federal minima, accelerating regional consolidation among gravure service providers.
Brand-led sustainability specifications are compressing procurement cycles as converters pre-qualify ink suppliers against evolving restricted substance lists prior to contract renewal. Tier-one food manufacturers are unbundling ink supply from legacy cylinder house arrangements, creating direct supplier relationships that bypass traditional converter intermediation. This pattern concentrates most visibly in European retail private label supply chains where ESG disclosure requirements cascade through packaging specifications.
Rotogravure Printing Inks Market Segmentation
Gravure ink procurement decisions hinge on regulatory compliance tiers and drying infrastructure compatibility. Converters segment supply by formulation chemistry, substrate adhesion requirements, and end-use certification burdens.
Ink Type:
REACH authorization thresholds and FDA food-contact notifications determine which formulations access premium flexible packaging contracts versus commodity publication runs.
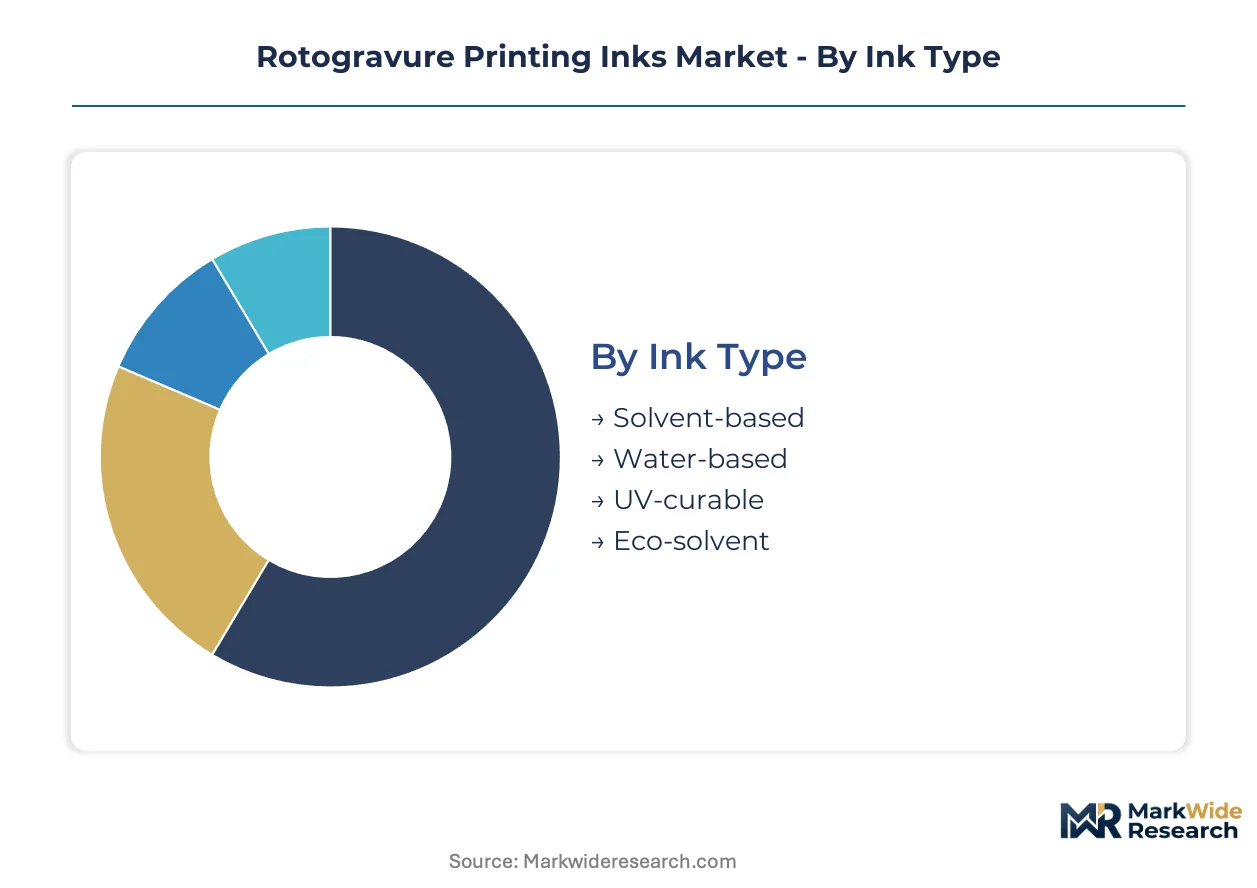
- Solvent-based:Toluene and ester carrier systems deliver sub-second drying on non-absorbent films at press speeds exceeding 300 meters per minute. Demand concentrates in retort pouch and metallized film applications across China and India where polyolefin adhesion requirements trap converters in legacy architectures despite MEE enforcement layering.
- Water-based:Acrylic and polyurethane dispersions eliminate VOC emissions but require extended drying tunnels and infrared-assisted ovens. Snack and confectionery wrap converters in Indonesia and European private label supply chains are retrofitting press lines to capture brand-owner sustainability mandates.
- UV-curable:Photoinitiator-acrylate systems enable instant polymerization for narrow-web decorative and security printing.
- Eco-solvent:Reduced-VOC glycol ether formulations serve signage and display graphics with lower regulatory burden than conventional solvent systems.
Solvent-based formulations sit at the top of the volume ranking, with water-based systems climbing the fastest.
Substrate Type:
Surface energy differentials and barrier layer requirements dictate binder chemistry selection and cylinder engraving depth specifications.
- Plastic:Polyethylene and polypropylene films dominate flexible food wrap with corona-treated surfaces enabling aqueous ink wetting.
- Film:Biaxially oriented polypropylene and polyester structures require solvent-based or energy-cured systems for metallized layer protection in high-barrier applications.
- Paper:Absorbent cellulosic substrates accommodate water-based gravure with minimal drying infrastructure.
- Metal:Aluminum coil and tinplate applications demand specialized adhesion promoters for decorative and protective coatings.
Plastic substrates command the largest formulation volume, with film applications gaining share fastest in barrier packaging.
End User:
Food-contact compliance layering and impression volume economics separate packaging procurement from publication supply chains.
- Packaging:Flexible food and beverage wrap requires EU Packaging and Packaging Waste Regulation alignment and toluene-free carrier systems for direct food contact.
- Publishing:Long-run magazine and catalog production sustains gravure cost advantages against digital alternatives in million-impression campaigns.
- Labels:Pressure-sensitive and shrink-sleeve applications favor UV-curable systems for substrate versatility.
- Decorative:Wallpaper and flooring patterns utilize eco-solvent formulations for color gamut requirements.
Packaging end users generate the dominant formulation demand, with labels expanding most quickly in narrow-web conversion.
Application:
Run length thresholds and color consistency requirements determine whether gravure retains cost position against flexographic and digital alternatives.
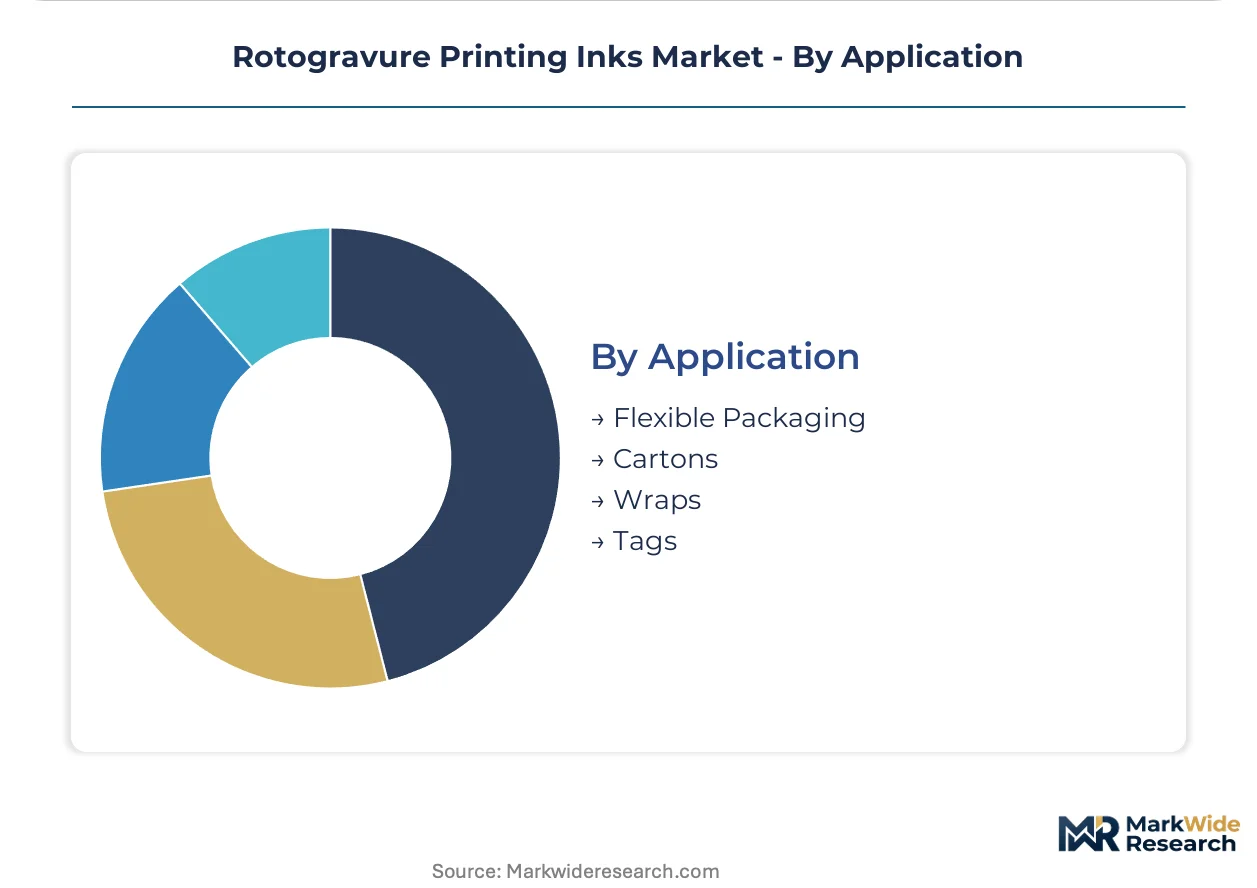
- Flexible Packaging:Stand-up pouches and flow wraps for snacks, confectionery, and pet food drive water-based ink retrofit investments.
- Wraps:Gift and floral wrap applications utilize solvent-based systems for metallic effects and high-gloss finishes.
- Cartons:Folding carton gravure serves premium cosmetics and spirits with embossed cylinder engraving for tactile effects.
- Tags:Apparel and luggage tag applications favor UV-curable inks for durability and instant finishing.
Flexible packaging applications anchor the volume base, with tags showing the steepest expansion trajectory in security and authentication segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gravure cylinder engraving specialists cluster in industrial corridors across Germany, Japan, and China, anchoring regional production networks for high-volume flexible packaging converters. Their apprenticeship pipelines lag press capacity expansion timelines by three to five years.
China
Flexible packaging demand in Yangtze River Delta cities outpaces domestic ink formulation maturity, pulling imports from Japanese and European suppliers. MEE enforcement layering compels Zhejiang and Jiangsu converters toward water-based retrofits or recovered-solvent systems. Shanghai and Suzhou industrial zones host the densest concentrations of gravure press installations serving snack food and beverage wrap exports.
Germany
REACH chemical authorization thresholds reposition cost structures for solvent-based suppliers serving European flexible packaging converters. ECHA substance of very high concern listings accelerate investment in recovery infrastructure across North Rhine-Westphalia. The Düsseldorf-Cologne corridor maintains specialized cylinder engraving partnerships that reduce job-change downtime for publication gravure runs.
India
Domestic packaging consumption in Maharashtra and Gujarat outpaces local ink supply maturity, creating procurement reliance on regional Asian imports. BIS certification requirements for food-contact formulations add compliance layering for converters supplying multinational brand owners. The Mumbai-Pune industrial belt concentrates flexible packaging gravure capacity for confectionery and spice exports.
Indonesia
Underdeveloped local ink supply relative to packaging demand growth creates white space for regional production facility investments. FSSAI-aligned import standards for food-contact materials shape procurement pre-qualification cycles among Jakarta and Surabaya converters. Java-based flexible packaging clusters are expanding gravure capacity for palm oil and instant noodle wrap production.
United States
EPA National Emission Standards for Hazardous Air Pollutants mandates solvent capture infrastructure in flexible packaging operations across Wisconsin and Illinois. California air district rules exceed federal minima, accelerating regional consolidation among gravure service providers. The Chicago-Milwaukee corridor hosts dedicated high-volume facilities with integrated recovery systems serving snack food brand owners.
Rotogravure Printing Inks Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and cylinder service integration tiers. The vendor base stratifies into pigment-integrated manufacturers, independent ink blenders, and regional distributors with technical service capabilities. Three archetypes dominate: integrated chemical conglomerates with captive mineral processing, specialized ink houses with engraving partnerships, and regional converters with backward formulation capabilities. Competitive moves concentrate on solvent recovery infrastructure partnerships and bio-based binder development licensing.
Within the integrated chemical tier, DIC Corporation and Toyo Ink SC Holdings Co., Ltd. exemplify pigment-integrated manufacturers sustaining margin control across Asia-Pacific supply chains. Among European specialists, Siegwerk Druckfarben AG & Co. KGaA and Hubergroup Deutschland GmbH occupy positions emphasizing food-contact compliance and regional technical service density. Flint Group represents the engraving-integrated archetype through specialized cylinder partnerships that reduce operational downtime.
| Leading Market Players |
|---|
| Toyo Ink SC Holdings Co., Ltd. |
| INX International Ink Co. |
| DIC Corporation |
| Dainichiseika Color & Chemicals Mfg. Co., Ltd. |
| T&K Toka Co., Ltd. |
| Flint Group |
| Sakata INX Corporation |
| Hubergroup Deutschland GmbH |
| Siegwerk Druckfarben AG & Co. KGaA |
| Others |
Value Chain & Pricing Dynamics
Water-based formulation retrofits across Asia-Pacific converter operations simultaneously elevate capital expenditure burdens and concentrate procurement leverage among pigment-integrated manufacturers with captive mineral processing. This technology transition reshapes cost economics by extending drying tunnel requirements while thinning margins for independent ink blenders lacking backward integration into titanium dioxide supply.
Pricing Analysis
Bundled cylinder engraving and ink supply arrangements are unbundling as tier-one food manufacturers establish direct supplier relationships, fragmenting legacy pricing architectures. Three-tier pricing structure across premium, standard, and economy levels stratifies by food-contact certification grade and volume scale, with EU Packaging and Packaging Waste Regulation alignment commanding premium positioning. Cost compression in mid-tier solvent-based formulations is intensifying because MEE enforcement layering in China strands converters with insufficient recovery infrastructure. Small-scale flexible packaging converters in Indonesia exhibit highest price sensitivity, while multinational brand owners with ESG disclosure mandates show least sensitivity for certified toluene-free systems.
Supply Chain Analysis
Direct-to-converter channels handle high-volume flexible packaging demand from Yangtze River Delta and Mumbai-Pune industrial belts, bypassing traditional distributor intermediation. Geographic supply concentration centers on China, Japan, and Germany for specialized cylinder engraving and pigment manufacturing. Raw material dependencies draw from titanium dioxide feedstocks, organic pigment intermediates, and acrylic resin dispersions. Single-source vulnerability in copper cylinder engraving apprenticeship pipelines lags press capacity expansion by three to five years, creating bottleneck risk for high-volume publication runs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by irreversible flexible packaging demand growth in Asia-Pacific food and beverage wrap production. Long-run gravure cost advantages against digital alternatives in million-impression campaigns sustain predictable margin pools.
For Market Incumbents: Cement pigment-integrated supply positions through captive mineral processing investments in China and India, insulating against titanium dioxide feedstock volatility that compresses independent blender margins. Prioritize bio-based binder R&D licensing to capture EU Packaging and Packaging Waste Regulation alignment premiums before REACH chemical authorization thresholds harden. Defensive capacity must target water-based formulation technical service density, as brand-led sustainability specifications compress procurement cycles and reward suppliers with direct converter relationships. For New Entrants and Emerging Players: Regional distributors with cylinder technical service capabilities represent the most accessible channel partner type for penetrating Indonesia's underdeveloped ink supply landscape relative to palm oil and instant noodle wrap demand growth. Target white-space in Surabaya and Jakarta converter clusters lacking local formulation maturity. Pursue toll manufacturing arrangements with established pigment houses to circumvent capital intensity of integrated production, leveraging FSSAI-aligned import standards as procurement pre-qualification leverage. For Investors and Strategic Acquirers: Valuations sit cheapest among independent ink blenders without captive mineral processing or engraving partnerships, as margin compression from water-based transition and pigment cost volatility erodes standalone viability. Long-term viability framing favors pigment-integrated specialists with Asia-Pacific supply chain control and bio-based formulation patent positions. Watch MEE enforcement layering intensity in Zhejiang and Jiangsu provinces as inflection indicator for accelerated water-based retrofit capex cycles and stranded solvent-recovery asset risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pigment Manufacturing | DIC Corporation and Toyo Ink sustain margin control across Asia-Pacific supply chains through captive titanium dioxide processing. |
| Water-Based Formulation Technical Service Expansion | Siegwerk and Hubergroup capture EU Packaging and Packaging Waste Regulation alignment premiums via bio-based binder development. |
| Specialized Cylinder Engraving Partnerships | Flint Group reduces job-change downtime for high-volume publication gravure runs through apprenticeship pipeline investments. |
| Solvent Recovery Infrastructure Licensing | Converters in China's Yangtze River Delta license recovery systems to comply with MEE VOC discharge limits without full retrofit. |
| Regional Production Facility Establishment | Indonesia's Java-based flexible packaging clusters attract greenfield ink capacity to serve palm oil and instant noodle wrap demand. |
Study Parameters
Direct dialogue with gravure press operators, flexible packaging procurement leads, cylinder engraving specialists, and ink formulation R&D directors anchored qualitative findings, cross-referenced with customs trade data, SEC filings from diversified chemical conglomerates, MEE enforcement bulletins, and ECHA substance of very high concern listings. Bottom-up and top-down triangulation validated volume estimates across formulation chemistry tiers.
Bottom-up modeling aggregated press capacity installations by industrial zone, while top-down analysis traced flexible packaging demand through food and beverage export flows. Segmentation dimensions included ink type, substrate compatibility, end-use certification burden, and regional regulatory cluster. CAGRs were derived from converter capex cycle analysis and brand-owner sustainability specification adoption curves, incorporating cylinder engraving apprenticeship pipeline lag effects and solvent recovery infrastructure deployment timelines.
Revisions become necessary when MEE enforcement layering accelerates beyond modeled thresholds, REACH authorization timelines shift, or polyolefin surface treatment breakthroughs eliminate water-based adhesion limits. Forecasts reflect assumptions about sustained long-run gravure cost advantages in million-impression publication campaigns and continued Asia-Pacific flexible packaging demand growth. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Solder Resist for Inkjet Printer Market
Printing Inks
Global Flexographic Inks Market
Printing Inks
Global Decorative Print Market
Printing Inks
Global Printing Blanket Market
Printing Inks
Inkjet Colorants Market
Printing Inks
Global Printing Toners Market
Printing Inks
Global Chemical Indicator Inks Market
Printing Inks
Global Water-Based Inks Market
Printing Inks
Commercial Printing Market
Printing Inks
Global Low Migration Inks Market
Printing Inks
Lithographic Printing Chemicals Market
Printing Inks
North America Ink Market
Printing Inks
Screen Printing Mesh Market
Printing Inks
Flexible Letterpress Printing Ink Market
Printing Inks
Flexographic Printing Inks Market
Printing Inks
Eco-Friendly Inks Market