
 Calcium Silicate Market | 2026-2036
Calcium Silicate Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Silicate Market Intelligence
The substitution of asbestos in high-temperature insulation applications is realigning the product economics for calcium silicate. This shift creates opportunities for specialized material suppliers. Saint-Gobain SA leverages its extensive global distribution network to supply the construction sector. In contrast, Johns Manville specializes in high-performance insulation products tailored for demanding industrial environments in the oil and gas and power generation sectors.
Calcium silicate is an inorganic compound, typically produced by reacting calcium oxide and silica, resulting in a material with low thermal conductivity and high compressive strength. It serves as a high-performance insulation and building material due to its fire resistance and structural integrity. Industrial insulation applications represent a mature, high-volume segment for calcium silicate. However, the use of calcium silicate boards for passive fireproofing in commercial and residential buildings constitutes a faster-growing application area.
Regulatory frameworks dictate market access and product specifications. Europe's REACH regulation and the US EPA's rules on asbestos substitutes directly influence material composition and safety standards. Concurrently, China's GB standards for building material fire safety set stringent performance benchmarks. These regulations collectively drive demand for certified, high-performance calcium silicate products. Success hinges on a manufacturer's ability to innovate formulations that meet evolving energy efficiency and fire safety codes.
Market Dynamics
The market is defined by a structural pivot towards high-performance materials, driven by global fire safety mandates and energy efficiency targets. Regulations like the EU Green Deal are compelling the construction industry to adopt certified, non-combustible materials like calcium silicate, particularly for passive fireproofing.
Growth Catalysts
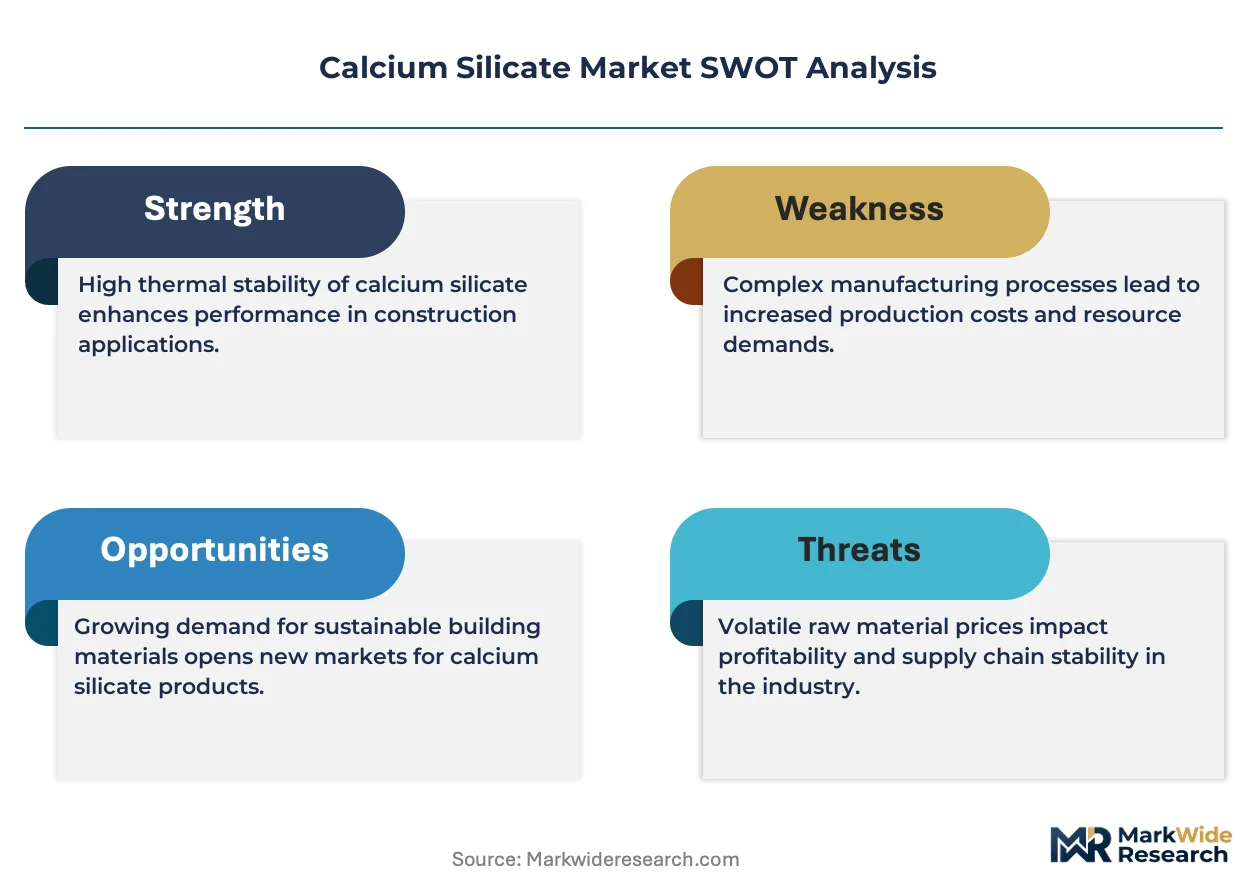
- Stringent Building Codes:The enforcement of stricter fire safety and energy efficiency regulations, such as Europe's Construction Products Regulation (CPR), is mandating the use of certified non-combustible insulation materials in commercial and residential buildings.
- Infrastructure Expansion in Asia:Massive infrastructure and industrial projects, especially in China, create sustained, high-volume demand for calcium silicate in applications ranging from industrial pipe insulation to fire-rated partitions in new buildings.
- Asbestos Replacement:The continued global phase-out of asbestos creates a direct substitution opportunity for calcium silicate, which offers comparable high-temperature performance without the associated health risks, particularly in industrial insulation.
Market Restraints
- Energy-Intensive Production:The manufacturing process, particularly the autoclaving step, consumes significant amounts of energy, making production costs highly sensitive to fluctuations in electricity and natural gas prices.
- Competition from Substitutes:In certain thermal insulation applications, calcium silicate faces performance and cost competition from alternative materials like mineral wool, perlite, and advanced aerogel blankets.
- Material Brittleness:The inherent rigidity and brittleness of calcium silicate boards can lead to handling and installation challenges, requiring specialized cutting tools and techniques to prevent breakage on job sites.
Strategic Opportunities
- Electric Vehicle Battery Protection:The use of calcium silicate as a thermal runaway barrier in electric vehicle battery packs represents a high-value, emerging application driven by automotive safety standards.
- Southeast Asian Construction Boom:Rapid urbanization and industrialization in countries like Vietnam and Indonesia present underpenetrated markets for advanced fireproofing materials, offering growth avenues beyond mature regions.
- Bio-Based Binders:Developing formulations that replace traditional binders with bio-based or recycled alternatives can create products with a lower carbon footprint, appealing to projects targeting green building certifications like LEED or BREEAM.
Industry Challenges
- Complex Certification Pathways:Navigating the disparate and time-consuming certification requirements for fire safety across key markets, such as CE marking in Europe and UL certification in the US, creates significant barriers to entry and expansion.
- Skilled Labor Scarcity:A shortage of installers trained in the proper handling and application of passive fire protection systems can lead to incorrect installations, compromising fire safety performance and creating liability risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Silicate Market |
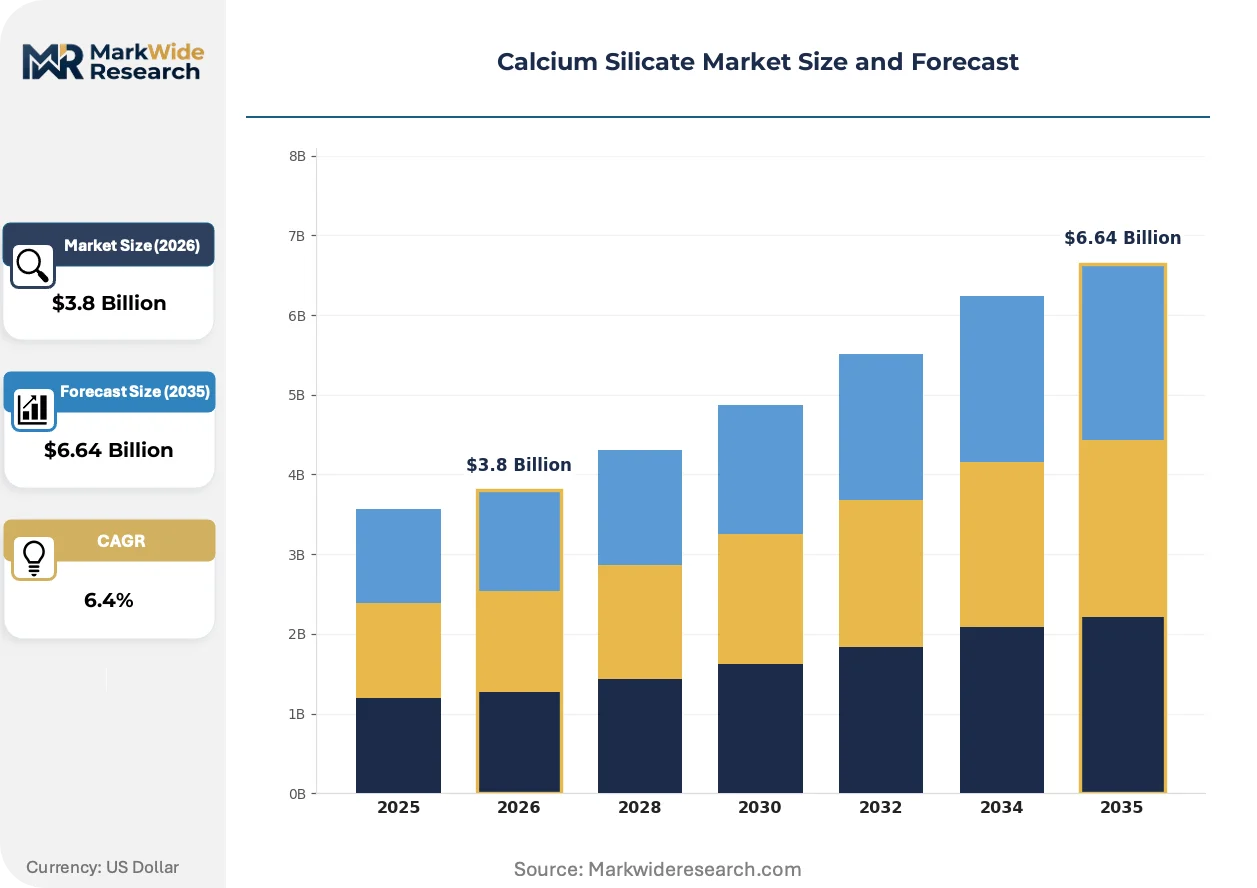
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulation, Mortars, Flooring, Boards Application: Building Materials, Fireproofing, Industrial Insulation, Soundproofing End Use Industry: Construction, Oil & Gas, Aerospace, Automotive Packaging Type: Bags, Drums, Bulk, Pallets |
| Companies Covered | Promat International (Etex), Morgan Advanced Materials plc, Johns Manville, Unifrax I LLC, Saint-Gobain SA, American Elements, Skamol Group, HIL Limited, BNZ Materials, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Silicate Market Strategic Shifts & Innovations
The market's trajectory is being redefined by a push for material specialization and system-level performance. Innovations are focused on enhancing fire resistance, thermal efficiency, and manufacturing consistency to meet the demands of advanced industrial processes and next-generation building designs.
Advanced process control is transforming manufacturing. Digital monitoring and automation of the autoclaving and curing stages ensure precise control over material density and crystal structure. Industrial insulation manufacturers are the primary adopters, seeking to achieve uniform product quality for demanding high-temperature applications. This level of control is automating quality assurance, reducing material variance and ensuring compliance with strict performance specifications like ASTM standards.
Regulatory scrutiny of material safety is intensifying globally. The US EPA's ongoing risk evaluation of asbestos and its substitutes under the Toxic Substances Control Act (TSCA) is formalizing the safety requirements for alternative materials. This action solidifies the market position for calcium silicate but simultaneously imposes stringent data reporting on chemical composition and potential health impacts. Manufacturers supplying the North American industrial and marine sectors are most affected, facing increased compliance costs.
A significant behavioral change is the shift toward procuring complete, certified systems over individual components. Architects and contractors now specify integrated passive fire protection solutions that include calcium silicate boards, compatible sealants, and tested installation frameworks. This trend disrupts traditional distributors who focus on component sales, favoring suppliers that provide comprehensive technical support and system-wide fire-test certifications. The shift is most visible in large-scale commercial and infrastructure projects in Europe and the Middle East.
Calcium Silicate Market Segmentation
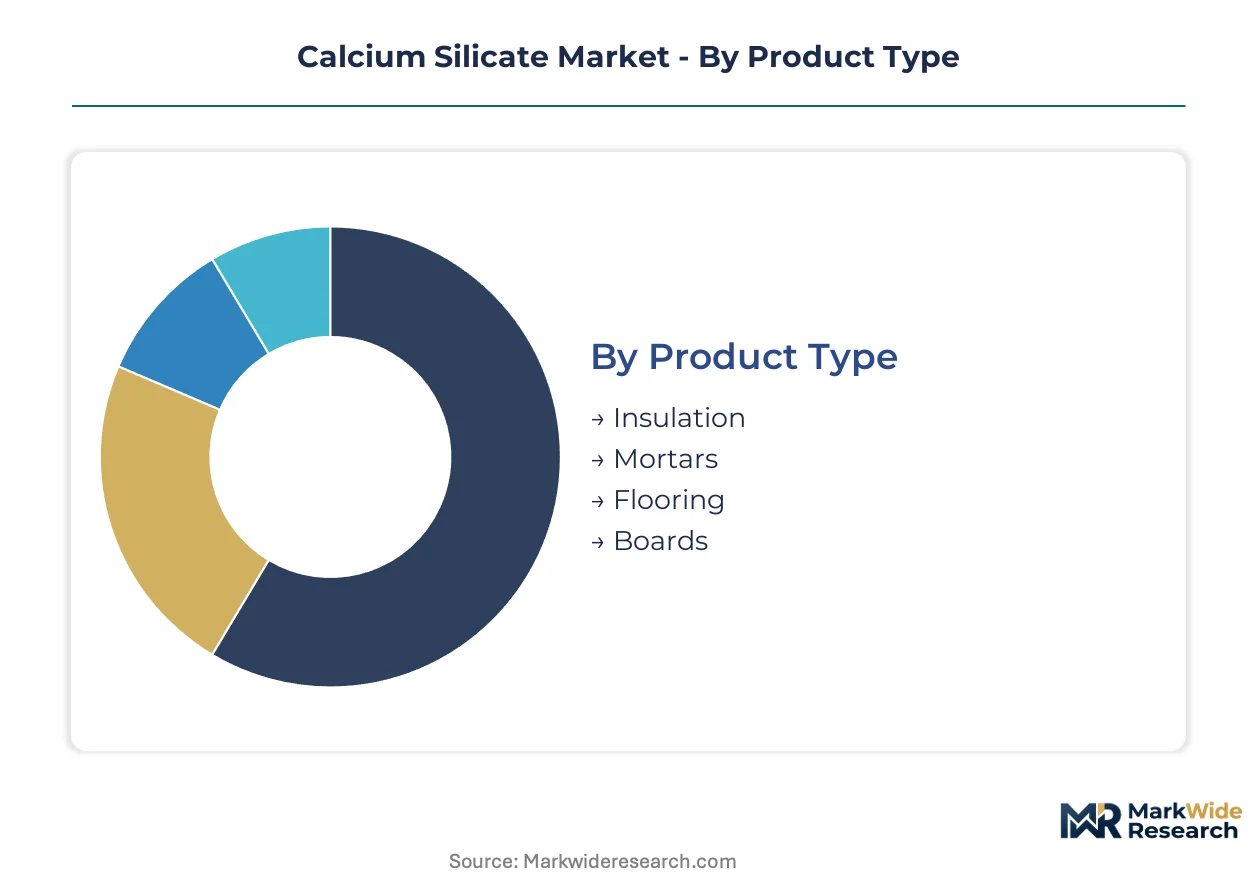
The Calcium Silicate market's segmentation reflects the material's adaptability across diverse industrial and construction requirements. Understanding these segments is crucial for manufacturers to align product development with specific market demands and regulatory landscapes. Each category delineates distinct value propositions and user needs within the broader calcium silicate ecosystem.
Product Type:
The product type segmentation highlights the spectrum from highly customized formulations to standardized, mass-produced materials.
- Insulation:This product form typically consists of pre-formed blocks, pipe sections, or blankets designed for thermal management in high-temperature industrial settings. Demand concentrates in the industrial sector for process efficiency and energy conservation, especially in regions with high energy costs like Europe.
- Boards:Calcium silicate boards are rigid panels used extensively in passive fire protection and general construction for their structural integrity and fire resistance. Demand for these boards is rapidly expanding in commercial and residential building construction, driven by stricter fire safety codes in China and Europe.
- Mortars:These specialized formulations leverage calcium silicate's properties for fire-resistant coatings and high-temperature bonding applications, particularly in furnace and refractory linings.
- Flooring:Calcium silicate can be incorporated into flooring systems, primarily for its fire-resistant and sound-dampening qualities in commercial and public buildings.
Leading the category by volume: Insulation. Growing fastest: Boards.
Application:
Application areas for calcium silicate reflect its diverse functional properties across various environments.
- Fireproofing:This application involves using calcium silicate products to protect structural elements and critical infrastructure from fire, enhancing building safety and occupant evacuation time. Stringent building codes in Europe and North America drive significant demand in this segment.
- Industrial Insulation:Calcium silicate provides high-performance thermal insulation for pipes, vessels, and equipment in energy-intensive industries, reducing heat loss and improving operational efficiency. The Oil & Gas sector and power generation facilities globally represent major consumers.
- Building Materials:This broad application encompasses the use of calcium silicate in wall panels, ceilings, and other architectural components for its non-combustibility and moisture resistance.
- Soundproofing:Calcium silicate's porous structure contributes to acoustic dampening in commercial and residential buildings, reducing noise transmission between spaces.
Fireproofing applications significantly contribute to market value due to stringent regulatory mandates.
End Use Industry:
The end-use industry classification delineates the primary customer bases driving demand for calcium silicate products.
- Construction:This industry utilizes calcium silicate extensively for passive fire protection, thermal insulation, and general building components in residential, commercial, and infrastructure projects. Massive infrastructure expansion in China and rapid urbanization in Southeast Asia generate substantial demand.
- Oil & Gas:Calcium silicate serves as critical high-temperature insulation for pipelines, refineries, and petrochemical plants, ensuring operational safety and energy efficiency. The demand from this sector is consistent due to ongoing maintenance and new project development in the Middle East and North America.
- Aerospace:Specialized calcium silicate composites find use in aircraft components requiring lightweight, fire-resistant, and high-temperature tolerant materials.
- Automotive:Calcium silicate is an emerging material for thermal management and fire protection in electric vehicle battery packs, addressing critical safety concerns.
Construction and Oil & Gas remain foundational end-use industries, while Automotive presents an emerging prospect.
Packaging Type:
Packaging type segmentation underscores the logistical considerations and typical volumes associated with calcium silicate distribution.
- Bulk:This packaging method involves shipping large quantities of powdered or granular calcium silicate directly in industrial containers or specialized vehicles, suitable for high-volume industrial consumers. This method optimizes transport costs for large-scale manufacturing and processing plants.
- Bags:Calcium silicate powders and granular products are commonly packaged in bags of various sizes for easier handling and distribution to smaller construction sites and retail channels. This format supports a wide range of applications in the building materials sector.
- Drums:Drums are typically used for specialty calcium silicate products or smaller, more controlled batches, often for specific industrial applications requiring precise material handling.
- Pallets:Boards and pre-formed insulation shapes are commonly stacked and wrapped on pallets for efficient transport and storage, preventing damage during transit.
Efficient supply chains prioritize Bulk and Bags for cost-effective material handling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Special Economic Zones, particularly those focused on advanced manufacturing and infrastructure, drive significant concentration for calcium silicate demand. This material is crucial for large-scale construction projects and industrial facilities across key growth regions. Regulatory shifts and construction booms in other major economies also shape regional demand patterns.
China
Massive infrastructure and industrial projects create sustained demand for calcium silicate, particularly in fire-rated partitions and pipe insulation. China's GB standards for building material fire safety set stringent performance benchmarks for these products. The Yangtze River Delta, a major industrial and economic hub, sees extensive use of calcium silicate in new commercial and residential developments.
Germany
Demand stems from the country's focus on energy-efficient building materials and high-performance industrial insulation. The EU Green Deal compels the construction industry to adopt certified non-combustible materials, benefiting calcium silicate. The Ruhr region, with its heavy industrial base, utilizes calcium silicate extensively for process efficiency and thermal management.
United States
The continued global phase-out of asbestos creates a direct substitution opportunity for calcium silicate in high-temperature applications. US EPA's rules on asbestos substitutes directly influence material composition and safety standards. The Gulf Coast region, a center for oil & gas and petrochemicals, relies on calcium silicate for critical industrial insulation projects.
India
Rapid urbanization and substantial infrastructure development projects generate high-volume demand for calcium silicate in construction. The Bureau of Indian Standards (BIS) mandates specific fire resistance and insulation properties for building materials. The Delhi-NCR region experiences significant demand for calcium silicate boards in new commercial and residential construction.
Vietnam
Rapid industrialization and urbanization present underpenetrated markets for advanced fireproofing materials. National building codes increasingly emphasize fire safety and energy efficiency in new developments. Ho Chi Minh City, a rapidly growing urban center, is a focal point for new commercial and high-rise residential construction demanding such materials.
Calcium Silicate Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the calcium silicate market. The industry structure is moderately consolidated at the global level, with a few large players holding significant market presence. Archetypes include diversified global material suppliers, specialized high-performance insulation providers, and regional construction material manufacturers. Companies engage in strategic partnerships to expand geographic reach and invest in capacity expansion to meet rising demand.
Global material supplier Saint-Gobain SA, a French multinational corporation, exemplifies a diversified approach, leveraging its extensive distribution network for construction applications. Johns Manville, an American company, represents specialized high-performance insulation providers, focusing on demanding industrial environments like oil and gas. Morgan Advanced Materials plc, a UK-based engineering company, also occupies a position within the specialized materials segment, catering to industrial and high-temperature insulation needs.
| Leading Market Players |
|---|
| Promat International (Etex) |
| Morgan Advanced Materials plc |
| Johns Manville |
| Unifrax I LLC |
| Saint-Gobain SA |
| American Elements |
| Skamol Group |
| HIL Limited |
| BNZ Materials, Inc. |
| Others |
Cost & Logistics Intelligence
EU Green Deal mandates for energy-efficient building materials gate qualified calcium silicate supply and premium-tier pricing access. These regulations compel manufacturers to invest in certified, high-performance formulations.
Pricing Analysis
Immediate delivery for specialized calcium silicate products commands a premium, while standard boards in high volume often see spot market discounts. The dominant pricing structure is contract-based long-term offtake for industrial applications, supplemented by per-unit transactional sales in construction. Certification level, such as UL or CE marking, and volume scale are key price differentiation drivers. Pricing softness reflects intense competition from substitute materials like mineral wool. Construction contractors, especially for large-scale projects, exhibit the highest price sensitivity.
Supply Chain Analysis
Returns and waste material flows from construction sites present reverse-logistics challenges for calcium silicate board manufacturers. Geographic supply concentration centers in China for basic materials and manufacturing, with specialized product facilities in Europe and North America. Key raw material dependencies include high-purity calcium oxide and silica. Energy price volatility, particularly for natural gas, poses a significant structural risk due to the energy-intensive autoclaving process. Distribution runs through a hybrid model combining direct sales to large industrial projects and extensive networks of building material distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The calcium silicate market presents a consolidation play, as the increasing complexity of certification pathways forces out smaller, less capitalized manufacturers. This pressure drives market rationalization.
For Market Incumbents: Cement market leadership through strategic capacity expansion in regions like Southeast Asia, targeting underpenetrated construction markets. Invest in R&D to innovate bio-based binders, reducing environmental footprint and appealing to green building certifications. Acquire smaller, specialized firms with unique formulation expertise or strong regional distribution networks to mitigate competitive threats from alternative insulation materials.
For New Entrants and Emerging Players: A pricing gap exists between highly specialized, certified industrial insulation and commodity construction boards, offering a clear market entry point. Target the automotive sector's demand for thermal runaway barriers in electric vehicle battery packs, leveraging specialized thermal management expertise. Focus on niche applications requiring advanced fire resistance and partner with automotive Tier 1 suppliers for market penetration.
For Investors and Strategic Acquirers: Regulatory convergence on global fire safety standards is the leading indicator that long-term market stability favors integrated producers. Target acquisition archetypes include mid-sized manufacturers with strong regional brand recognition and established certification portfolios. Watch for shifts in national infrastructure spending patterns in emerging economies, as this signals sustained demand for fireproofing materials over the next decade.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | Addresses rising demand from rapid urbanization and industrialization in countries like Vietnam. |
| Bio-Based Binder R&D | Enhances product sustainability, aligning with global green building certifications and regulations. |
| Acquisition of Niche Manufacturers | Consolidates market share and gains specialized product lines or regional distribution channels. |
| Automotive Sector Penetration | Captures high-value demand for thermal runaway barriers in electric vehicle battery packs. |
| Investment in Digital Process Control | Ensures uniform product quality and compliance with stringent performance specifications like ASTM standards. |
Research Approach
Independent corroboration across regulatory filings, industry association reports, and patent databases underwrites the qualitative findings. This study combined extensive primary interviews with secondary validation. Key stakeholders interviewed included construction project managers, industrial insulation engineers, R&D chemists, and regulatory compliance officers. Bottom-up and top-down triangulation ensured data consistency and accuracy across all segments.
The forecast window was anchored to historical reference periods, establishing a baseline for future projections across the analysis window. The analytical framework modeled key segmentation dimensions, including product type, application, end-use industry, and material density. Compound annual growth rates were derived from a multi-factor regression analysis. Infrastructure spending forecasts and energy efficiency regulation updates served as critical industry-specific forecast inputs.
Inputs from national building codes and major industrial project databases were available through the study window; gaps in emerging market regulatory data introduce uncertainty bands. Forecasts reflect assumptions regarding global economic stability and continued regulatory enforcement of fire safety standards. Material deviation in raw material pricing or significant shifts in substitute material performance warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Europe Ceramic Coatings Market
Ceramics
Global Thermal Ceramics Market
Ceramics
Global Ceramic Tube Market
Ceramics
Carbon-Ceramic Discs Market
Ceramics
East Africa Ceramic Tiles Market
Ceramics
Global Ceramic and Porcelain Tiles Market
Ceramics
Dielectric Ceramics Market
Ceramics
China Clay Market
Ceramics
Ceramic Setter Plate Market
Ceramics
Nano Ceramic Coatings Market
Ceramics
Cerium Carbonate Market
Ceramics
Methyl Silicate Market
Ceramics
Global Ceramic Balls Market
Ceramics
Malaysia Ceramic Tiles Market
Ceramics
Traditional Ceramic Market
Ceramics
Ceramic Frit Market