
 IP Camera Market | 2026-2036
IP Camera Market Size, Share, and Industry Trends Forecast 2026-2036
IP Camera Market Intelligence
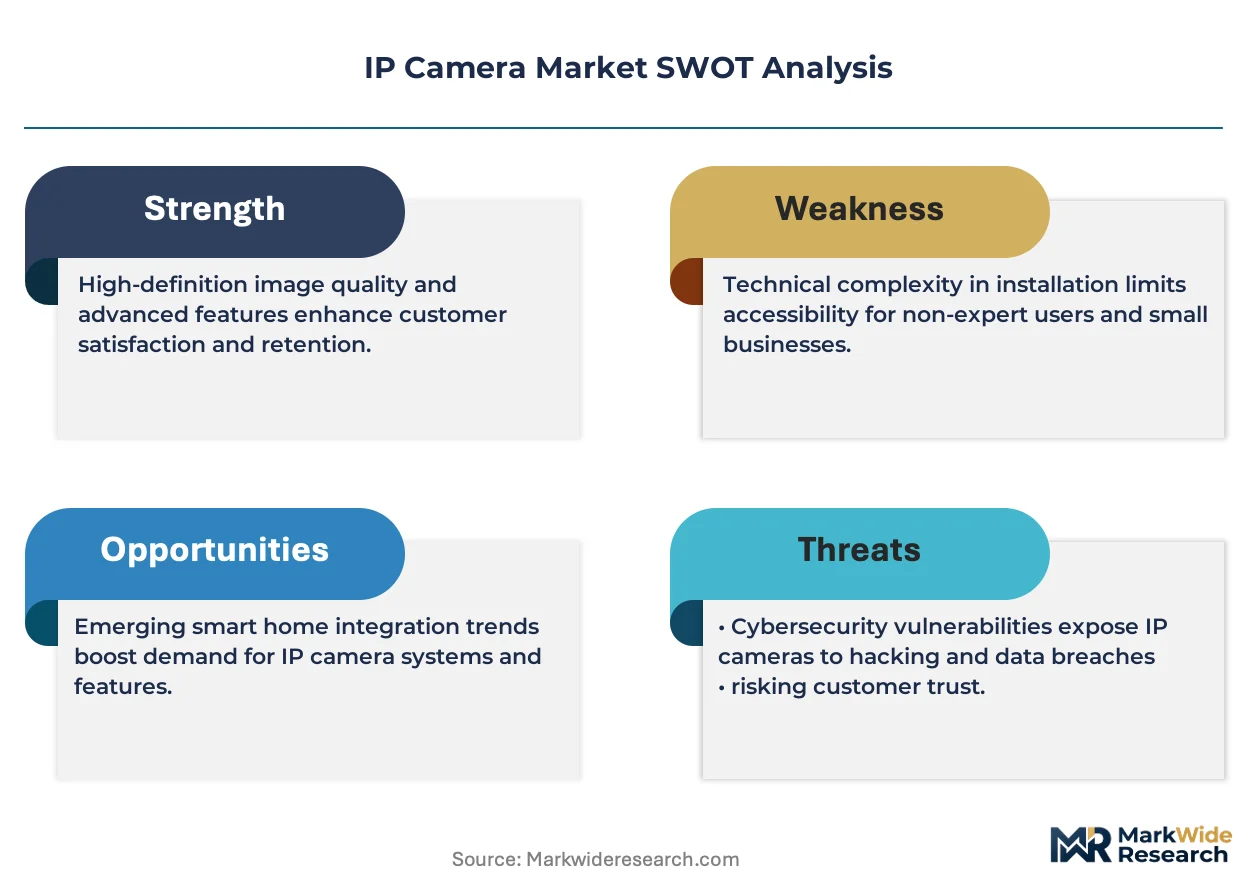
The gap between premium AI-enabled units and commodity fixed-lens hardware is expanding as enterprise buyers demand real-time analytics at the edge while budget segments compete on unit cost alone. Hikvision leverages its captive sensor supply chain to dominate mid-market volume. Axis Communications differentiates through open-platform software architecture that sustains partner ecosystem loyalty. Bosch Security Systems anchors European premium installations with cybersecurity-hardened firmware.
An IP camera is a networked digital video device that captures, compresses, and transmits visual data over internet protocol infrastructure, typically employing H.265 or H.266 codecs with resolutions from two to eight megapixels for real-time surveillance and forensic review. Dome cameras retain the largest installed base in retail and commercial corridors where vandal resistance and discreet positioning matter. PTZ cameras capture the fastest growth in traffic monitoring and large-campus applications where operators require remote directional control over wide perimeters. Wireless network technology, including Wi-Fi six and mesh backhaul variants, is displacing legacy coaxial runs in retrofit installations where trenching costs would erode project returns.
FCC certification governs radio-frequency emissions for wireless models sold in the United States, while the EU AI Act imposes risk-classification obligations on cameras deploying biometric identification in public spaces. China's GB standards and MIIT network-access permits create a dual-compliance burden for manufacturers serving both domestic and export channels. Buyers must weigh sovereign data-localization mandates against the interoperability benefits of ONVIF Profile T and Profile M conformance when architecting multi-site deployments.
Market Dynamics
Edge-AI silicon migration is compressing analytics latency requirements from cloud-dependent architectures to on-device inference, forcing procurement criteria to prioritize TOPS-per-watt metrics over raw sensor resolution in enterprise RFPs.
Growth Catalysts
- Smart city infrastructure mandates:Government facilities across Vietnam, South Korea, and China are deploying city-scale video networks for traffic flow optimization and public safety monitoring, creating sustained volume demand for outdoor-rated dome and bullet form factors.
- ONVIF Profile M conformance:Standardized metadata exchange between cameras and video management systems is reducing integration friction for multi-vendor deployments, accelerating replacement cycles in commercial real estate and logistics campuses.
- Wi-Fi six mesh backhaul:Wireless retrofit projects in aging urban cores are eliminating trenching costs that previously made IP camera upgrades economically unviable, unlocking demand in European and North American heritage building stock.
Market Restraints
- CMOS sensor supply concentration:Captive production at vertically integrated Chinese manufacturers limits second-source availability for mid-tier vendors, exposing procurement timelines to single-geography disruption risk.
- EU AI Act biometric restrictions:Risk-classification obligations for facial recognition deployments in public spaces are forcing architecture redesigns and compliance documentation burdens that extend sales cycles by six to twelve months.
- Legacy coaxial infrastructure:Entrenched analog installations in budget-constrained verticals such as small-format retail and municipal buildings create substitution economics that favor encoder-based hybrid upgrades over full IP replacement.
Strategic Opportunities
- India smart city mission:Underpenetrated urban surveillance deployments across tier-two and tier-three municipalities present volume expansion potential for vendors establishing local manufacturing under PLI scheme incentives.
- Edge-to-cloud orchestration platforms:Convergence of containerized video analytics with Kubernetes-based fleet management is enabling recurring software revenue streams that decouple vendor economics from hardware shipment cycles.
- Healthcare patient monitoring:Fall detection and mobility analytics applications in acute care facilities are creating new demand for privacy-preserving edge processing that keeps video streams within facility network perimeters.
Industry Challenges
- Firmware security certification:Cybersecurity-hardened development lifecycles required by European critical infrastructure operators are extending engineering validation timelines and compressing margin structures for non-specialized vendors.
- Legacy VMS integration:Proprietary SDK dependencies in installed-base video management systems are forcing custom middleware development that erodes project profitability and complicates multi-site standardization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IP Camera Market |
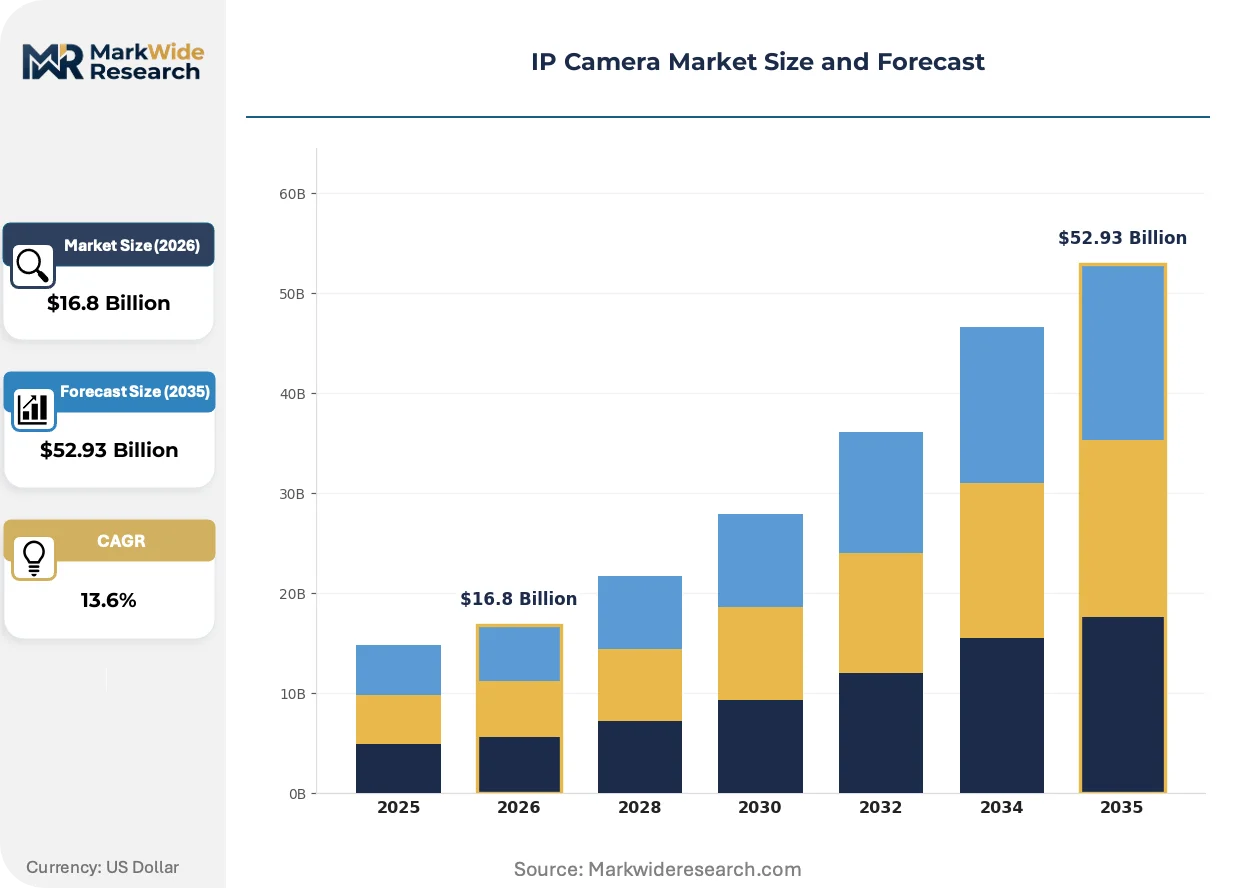
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $52.93 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Camera, PTZ Camera, Dome Camera, Bullet Camera, Panoramic Camera Technology: Wired Network, Wireless Network, PoE, Fiber Optic Application: Home Security, Traffic Monitoring, Industrial Surveillance, Campus Safety, Retail Monitoring End User: Commercial Establishments, Educational Institutions, Government Facilities, Warehousing, Transportation Facilities |
| Companies Covered | Bosch Security Systems, Panasonic, Hikvision, Uniview, Honeywell Security, Dahua Technology, Hanwha Vision, Pelco, Axis Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IP Camera Market Strategic Shifts & Innovations
Computational imaging pipelines are displacing optical complexity with software-defined enhancement, collapsing the traditional trade-off between low-light performance and form factor constraints that governed dome camera industrial design for two decades.
Neural network accelerators embedded at the sensor edge are automating real-time object classification and behavioral anomaly flagging without upstream bandwidth consumption. Logistics fulfillment centers and critical infrastructure perimeters are deploying these units at scale, compressing response times from minutes to seconds while reducing cloud compute subscription dependencies. The architectural shift is automating tiered service models where premium pricing attaches to inference capability rather than image quality alone.
China's MIIT network-access permits and GB standards compliance requirements are fragmenting product roadmaps for vendors serving both domestic and export channels. Manufacturers must maintain dual firmware branches and certification documentation sets, increasing SKU complexity and inventory carrying costs. European buyers are responding by tightening supplier qualification criteria to exclude devices that cannot demonstrate simultaneous CE marking and MIIT registration traceability.
Specification authority is migrating from security integrators to IT infrastructure teams as camera deployments converge with corporate zero-trust network architectures. Chief information officers are mandating certificate-based authentication and automated patch management that legacy analog-transitioned procurement channels cannot deliver. This pattern is most pronounced in North American financial services and technology campus deployments where network security audit requirements override traditional video surveillance vendor relationships.
IP Camera Market Segmentation
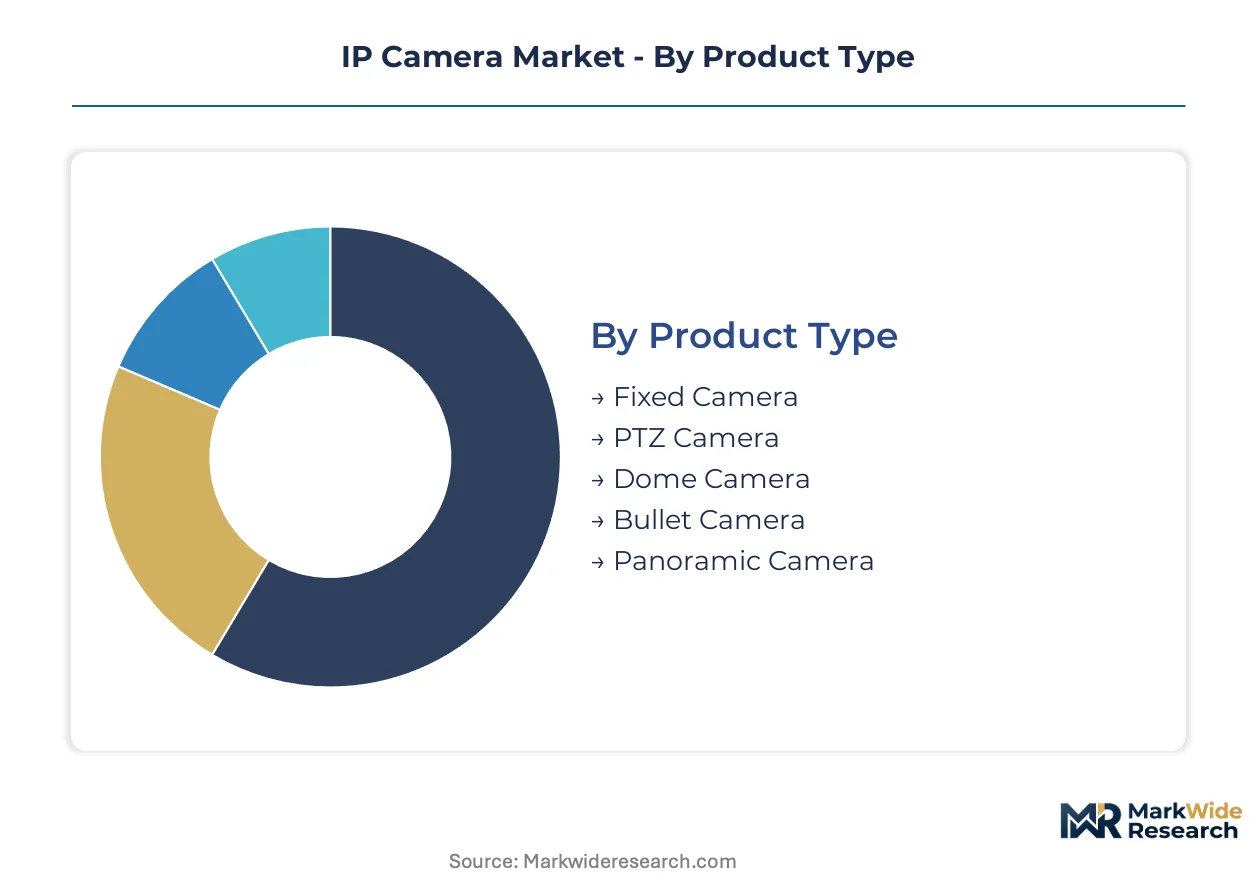
IP camera procurement criteria diverge sharply between volume-driven municipal deployments and premium enterprise installations where edge-AI inference capabilities command pricing power. Understanding these segment boundaries enables vendors to align R&D roadmaps with buyer willingness-to-pay rather than competing on specification tables alone.
Product Type:
Dome and bullet units split the volume base, while PTZ and panoramic variants capture premium budgets in perimeter defense and situational awareness applications.
- Dome Camera:Vandal-resistant housings with discreet positioning dominate retail corridors and commercial lobbies where aesthetic integration matters. Demand concentrates in South Korean and Vietnamese smart city corridors where government facilities specify IK10 impact ratings for public space durability.
- PTZ Camera:Motorized pan-tilt-zoom mechanisms enable remote directional control over wide perimeters with optical zoom ranges exceeding thirty-to-one. Traffic monitoring installations across Chinese provincial highways and large-campus security in Singapore drive replacement cycles as operators demand smoother preset positioning and lower-latency joystick response.
- Fixed Camera:Stationary lens assemblies with fixed focal lengths serve cost-sensitive indoor corridors and back-office monitoring where scene geometry is predictable.
- Bullet Camera:Weather-sealed cylindrical housings with integrated IR illumination anchor outdoor perimeter deployments in warehousing and industrial zones.
- Panoramic Camera:Multi-sensor or fisheye lens configurations deliver 180-to-360-degree coverage without mechanical movement, gaining traction in casino gaming floors and logistics fulfillment centers where single-point coverage reduces camera count.
Mature deployment sits with dome cameras in established retail and commercial real estate. Newer deployment is concentrated in panoramic and PTZ variants as edge-AI analytics justify unit cost premiums through reduced camera density requirements.
Technology:
Power-over-Ethernet dominates new construction while wireless retrofit projects unlock demand in heritage building stock where trenching costs would erode project returns.
- PoE:IEEE 802.3bt standard delivers up to 90 watts over single Ethernet runs, powering heaters, wipers, and edge-AI accelerators without separate electrical contractor engagement. Campus safety deployments across German educational institutions and Dutch commercial real estate standardize on PoE++ infrastructure to simplify cable plant management.
- Wireless Network:Wi-Fi six and mesh backhaul variants eliminate coaxial infrastructure in aging urban cores. Municipal retrofit projects in Boston and Philadelphia heritage districts adopt wireless IP cameras where landmark preservation restrictions prohibit facade penetration for cable runs.
- Wired Network:Dedicated Ethernet switching remains preferred in greenfield data centers and critical infrastructure where deterministic latency and cybersecurity segmentation override installation labor savings.
- Fiber Optic:Single-mode fiber backhaul extends deployment range beyond copper distance limitations in airport perimeters, seaport container terminals, and sprawling industrial complexes where camera locations exceed 100 meters from aggregation switches.
Greenfield construction favors PoE for integrated power-data simplicity. Fiber optic deployment is climbing the fastest in transportation facilities and critical infrastructure where electromagnetic interference and ground potential differences threaten copper-based signaling integrity.
Application:
Traffic monitoring and campus safety command premium analytics budgets while home security competes on subscription bundling and installation simplicity.
- Traffic Monitoring:License plate recognition and vehicle classification algorithms require high frame rates and WDR performance against headlight glare. Chinese provincial transport authorities and South Korean metropolitan governments deploy these at scale for congestion pricing and incident detection.
- Campus Safety:Multi-building educational and corporate environments integrate video with access control and mass notification systems. Vietnamese university expansions and Indian IT park developments specify ONVIF Profile M conformance to reduce vendor lock-in across phased construction timelines.
- Home Security:Consumer-grade devices emphasize mobile app integration and cloud storage subscriptions over local analytics, with FCC certification governing wireless models sold in the United States.
- Industrial Surveillance:Explosion-proof housings and thermal imaging extensions monitor process safety in petrochemical, mining, and energy facilities where conventional visible-spectrum cameras fail.
- Retail Monitoring:Shrinkage reduction and queue management analytics drive deployment in grocery and big-box formats, though budget constraints favor encoder-based hybrid upgrades over full IP replacement in smaller formats.
Established penetration sits with retail monitoring where analog-to-IP transition cycles began earliest. Steepest expansion trajectory belongs to campus safety as zero-trust network architectures elevate video surveillance to IT infrastructure priority status.
End User:
Government facilities anchor volume demand through smart city mandates while warehousing and transportation facilities drive edge-AI premium adoption.
- Government Facilities:City-scale video networks for public safety and traffic optimization create sustained procurement pipelines. Vietnam's urban surveillance expansions and China's safe-city initiatives specify outdoor-rated dome and bullet form factors with GB standards compliance and MIIT network-access permits.
- Warehousing:Logistics fulfillment centers deploy neural network accelerators for real-time object classification and behavioral anomaly flagging without upstream bandwidth consumption. Amazon, DHL, and regional 3PL operators in Germany and the Netherlands compress response times from minutes to seconds while reducing cloud compute subscription dependencies.
- Commercial Establishments:Office complexes and hospitality properties balance aesthetic constraints with cybersecurity-hardened firmware requirements, particularly in European installations where Bosch Security Systems anchors premium positioning.
- Educational Institutions:K-12 and university environments prioritize vandal resistance and privacy-preserving edge processing that keeps video streams within facility network perimeters.
- Transportation Facilities:Airports, seaports, and rail terminals demand redundant power, environmental sealing, and integration with passenger information systems, with EU AI Act biometric restrictions forcing architecture redesigns for facial recognition deployments in Schengen Area hubs.
Volume concentration rests with government facilities under smart city infrastructure mandates. Emerging demand is migrating toward warehousing as containerized video analytics with Kubernetes-based fleet management enables recurring software revenue streams that decouple vendor economics from hardware shipment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's electronics manufacturing corridor anchors global IP camera production, with component suppliers clustering within 50 kilometers of final assembly facilities. Smart city infrastructure spending across Asia-Pacific, European retrofit mandates, and North American cybersecurity compliance requirements create divergent demand patterns.
China
Provincial safe-city initiatives in Guangdong and Jiangsu drive bulk procurement of outdoor-rated dome and bullet cameras. MIIT network-access permits and GB standards compliance create dual-certification requirements for domestic and export channels. Hikvision and Dahua Technology anchor manufacturing clusters in Hangzhou and Shenzhen, supplying both government facilities and international distributors.
South Korea
Metropolitan governments in Seoul and Busan deploy city-scale video networks for traffic flow optimization and congestion pricing. KISA cybersecurity certification requirements harden procurement specifications for public sector deployments. Hanwha Vision's domestic manufacturing base in Seongnam supplies regional smart city projects across Vietnam and Indonesia.
Germany
Industrial surveillance deployments in North Rhine-Westphalia's chemical corridor demand explosion-proof housings and thermal imaging extensions. CE marking and EU AI Act biometric restrictions extend sales cycles for facial recognition architectures. Bosch Security Systems anchors European premium positioning through cybersecurity-hardened firmware developed in Stuttgart.
United States
Campus safety deployments across Texas and California educational institutions prioritize zero-trust network integration and certificate-based authentication. FCC certification governs radio-frequency emissions for wireless models in municipal retrofit projects. Boston and Philadelphia heritage districts adopt Wi-Fi six mesh backhaul where landmark preservation restricts facade penetration.
Vietnam
Tier-two and tier-three municipalities expand urban surveillance under national smart city directives. Government facilities specify IK10 impact ratings for public space durability in Ho Chi Minh City and Hanoi corridors. Local system integrators partner with Chinese and South Korean manufacturers for volume supply under preferential procurement frameworks.
IP Camera Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the IP camera value chain. The market structure consolidates around vertically integrated sensor manufacturers and open-platform software specialists. Three archetypes dominate: captive supply chain operators controlling CMOS production, cybersecurity-focused premium vendors, and volume-oriented original design manufacturers. Competitive moves center on edge-AI silicon integration and strategic partnerships with video management system providers.
Within the captive supply chain tier, Hikvision exemplifies backward integration into sensor manufacturing that compresses unit costs for mid-market volume. Axis Communications occupies a position among open-platform architects sustaining partner ecosystem loyalty through software conformance. Bosch Security Systems anchors European premium installations with hardened firmware development. Among South Korean fabricators, Hanwha Vision represents the regional specialist archetype serving Asia-Pacific smart city mandates.
| Leading Market Players |
|---|
| Bosch Security Systems |
| Panasonic |
| Hikvision |
| Uniview |
| Honeywell Security |
| Dahua Technology |
| Hanwha Vision |
| Pelco |
| Axis Communications |
| Others |
Cost & Logistics Intelligence
CMOS sensor wafer pricing indices from Taiwan and South Korea cascade through three distinct procurement tiers, compressing margins for non-integrated vendors while amplifying cost advantages for manufacturers with captive foundry relationships. Chinese GB standards compliance and MIIT network-access permits add certification-driven cost layering that European buyers increasingly filter through dual-traceability requirements.
Pricing Analysis
Inference-throughput guarantees anchor value-based pricing for edge-AI enabled units, with TOPS-per-watt metrics commanding premium positioning over raw sensor resolution. Three-tier pricing structure across premium, standard, and economy levels stratifies around cybersecurity certification grade and ONVIF Profile M conformance. Price erosion runs through commodity fixed-lens segments as Hikvision's captive sensor supply chain compresses unit economics for mid-tier competitors. Government facilities under smart city mandates exhibit lowest price sensitivity, while small-format retail buyers prioritize encoder-based hybrid economics over full IP replacement.
Supply Chain Analysis
CE marking and MIIT registration traceability requirements gate supplier qualification, fragmenting product roadmaps for vendors serving domestic Chinese and export channels simultaneously. Manufacturing concentrates in China, South Korea, and Vietnam, with Shenzhen's electronics corridor anchoring final assembly within 50 kilometers of component suppliers. Production draws from Sony and Omnivision CMOS sensors, Ambarella and HiSilicon edge-AI silicon, and precision motor assemblies for PTZ mechanisms. Single-source vulnerability in vertically integrated Chinese sensor manufacturers exposes procurement timelines to geographic concentration risk. Distribution runs through security integrators and IT infrastructure channels, with specification authority migrating toward corporate technology procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over edge-AI silicon supply and cybersecurity-hardened firmware development determines sustainable margin capture across enterprise and government segments.
For Market Incumbents: Deepen backward integration into neural network accelerator supply through strategic foundry partnerships or in-house ASIC development, defending against margin compression from commodity sensor vendors. Fortify open-platform software architectures to sustain video management system ecosystem loyalty as IT infrastructure teams displace traditional security integrators in specification authority. Prioritize EU AI Act compliance documentation investments to compress six-to-twelve month sales cycle extensions for biometric recognition deployments.
For New Entrants and Emerging Players: India's PLI scheme incentives for local manufacturing open a window for cost-competitive entry into tier-two and tier-three municipal smart city deployments. Target healthcare patient monitoring applications where privacy-preserving edge processing requirements favor new architectural approaches over incumbent retrofit constraints. Pursue Kubernetes-based fleet management partnerships to attach recurring software revenue streams that decouple economics from hardware shipment cycles.
For Investors and Strategic Acquirers: Distressed-cycle entries favor cybersecurity-focused firmware specialists in Germany and open-platform software architects with established ONVIF conformance track records. Long-term viability hinges on containerized video analytics capabilities converging with zero-trust network architectures across financial services and technology campus deployments. Watch for inflection signals in FCC certification backlogs for Wi-Fi six mesh backhaul models, indicating wireless retrofit demand acceleration in North American heritage building stock.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Silicon Integration | TOPS-per-watt performance separates premium pricing from commodity hardware in enterprise RFPs. |
| ONVIF Profile M Certification | Standardized metadata exchange reduces integration friction for multi-vendor campus deployments. |
| Cybersecurity-Hardened Firmware | CE marking and EU AI Act compliance extend sales cycles but anchor European premium positioning. |
| Wireless Mesh Backhaul Deployment | Wi-Fi six eliminates trenching costs in Boston and Philadelphia heritage retrofit projects. |
| Containerized Analytics Platform | Kubernetes-based fleet management enables recurring software revenue decoupled from hardware cycles. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across security integrators, IT infrastructure procurement officers, video management system developers, and smart city program directors. ONVIF conformance databases, MIIT network-access permit registries, FCC equipment authorization records, and EU AI Act implementation guidance provided segmentation boundaries. Bottom-up unit shipment analysis triangulated against top-down infrastructure spending forecasts from government procurement disclosures.
Shipment volume and value outputs reconciled across product type, technology architecture, application vertical, and end-user segment dimensions throughout the forecast period. CAGRs derived from regression analysis against smart city infrastructure budget trajectories, edge-AI silicon cost curves, and wireless retrofit project pipelines. Modeling incorporated PoE++ infrastructure deployment rates, GB standards compliance adoption timelines, and zero-trust network architecture migration patterns in North American financial services.
The model assumes a particular technology adoption path; alternative pathways for edge-to-cloud orchestration would alter the outlook if hyperscaler video analytics subscriptions displace on-device inference faster than projected. Forecasts reflect assumptions about MIIT permit processing timelines, EU AI Act enforcement consistency, and CMOS sensor supply concentration stability. A model refresh is warranted upon material change in edge-AI silicon foundry capacity allocation or smart city infrastructure budget reprioritization across Asia-Pacific municipalities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Whole Slide Imaging Systems Market
Imaging
CMOS Smartphone Camera Lens Market
Imaging
Infrared Imaging Software Market
Imaging
Gel Imaging Documentation Market
Imaging
Camera Lens Market
Imaging
Handheld Imaging Devices Market
Imaging
US Near Infrared Imaging Market
Imaging
PET Imaging Systems Market
Imaging
Global Ingaas Camera Market
Imaging
Pan-Tilt-Zoom (PTZ) Camera Market
Imaging
Light Field Market
Imaging
Contact Image Sensor Market
Imaging
Mobile Camera Module Market
Imaging
Visualiser Market
Imaging
Global Digital Photography Market
Imaging
X-Ray Systems Market