
 Insurance Aggregators Market | 2026-2036
Insurance Aggregators Market Size, Share, and Industry Trends Forecast 2026-2036
Insurance Aggregators Market Analysis
Subscription-based policy management services is consolidating around bundled renewal reminders, claims advocacy, and cross-sell engines that transform one-time quote comparisons into recurring revenue streams. CHECK24 Vergleichsportal GmbH leverages its German market footprint to sustain dominance in auto and home insurance verticals. Policybazaar Insurance Web Aggregator Private Limited anchors the Indian market through extensive agent networks and direct digital reach. Insurify Insurance Services Inc. differentiates via AI-driven quote personalization that reduces user friction across multiple carrier APIs.
An insurance aggregator operates as a digital intermediary platform that aggregates policy quotations from multiple underwriters through standardized data APIs and algorithmic matching engines, enabling consumers to compare premiums, coverage terms, and exclusions within unified interfaces. Auto insurance commands the largest transaction volume on aggregator platforms due to regulatory mandates and high policy turnover rates. Health insurance segments generate premium commission pools as aging populations and rising medical costs drive consumers toward comparative shopping tools. Brokerages represent a growing end-user category as independent agents adopt white-label aggregator infrastructure to expand their carrier panels without direct appointments.
The US market navigates state-level insurance commissioner oversight alongside FTC consumer protection standards that govern quote accuracy and data privacy disclosures. India's IRDAI web aggregator regulations mandate capital requirements, lead disclosure protocols, and exclusive online licensing frameworks that shape platform economics. GDPR and emerging EU AI Act provisions constrain European aggregator data processing and algorithmic recommendation transparency. Stakeholders must monitor evolving open insurance mandates and embedded distribution rules that will determine whether aggregators evolve into full policy administration platforms or remain comparison-only intermediaries.

Market Dynamics
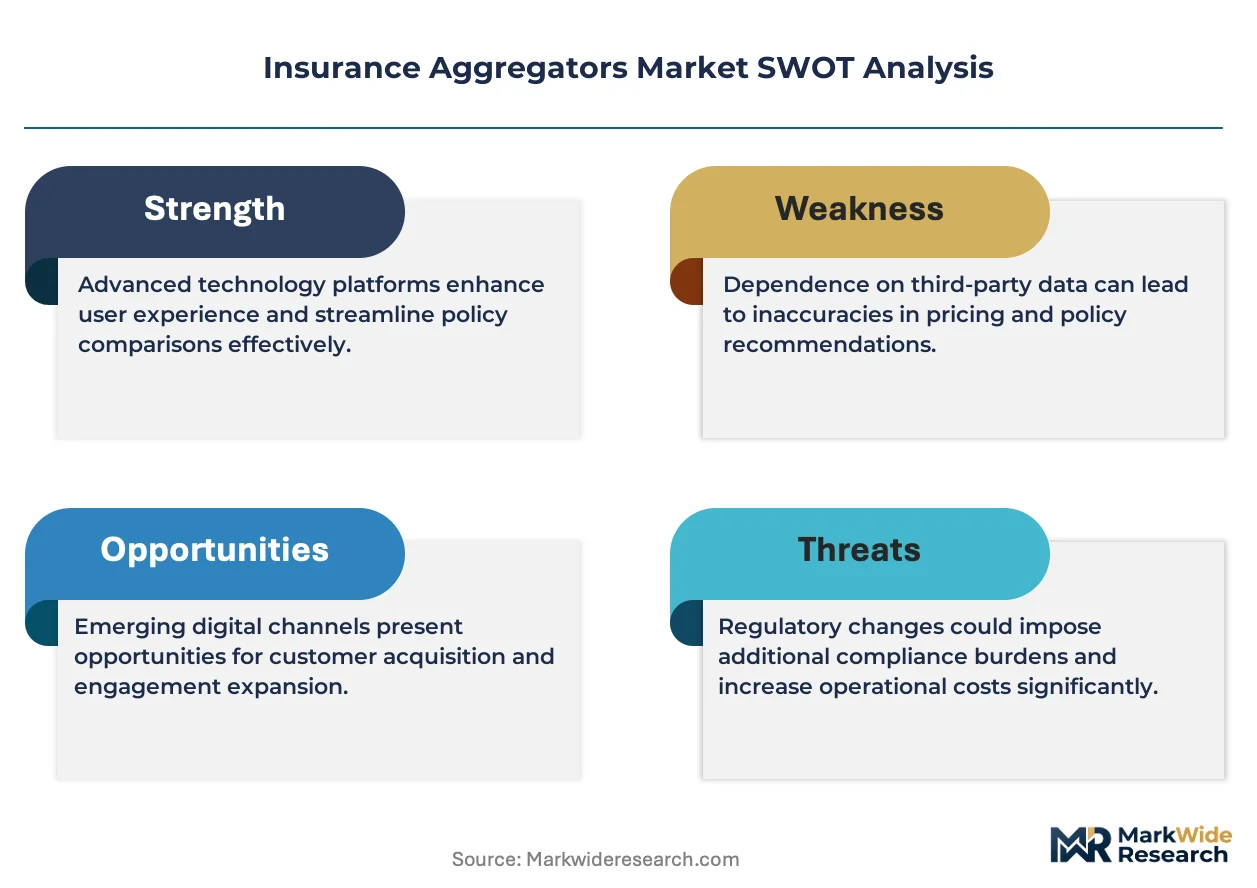
Open insurance API mandates and embedded distribution frameworks are compressing the traditional aggregator value proposition from pure comparison toward policy lifecycle administration.
Growth Catalysts
- IRDAI web aggregator licensing:India's capital requirements and exclusive online frameworks legitimize digital intermediaries, accelerating first-time insurance purchaser adoption through regulated trust signals.
- Small business coverage gaps:Underpenetrated commercial lines create demand for streamlined multi-carrier comparisons as micro-enterprises formalize operations and seek mandatory liability protection.
- Digital identity verification:Biometric KYC protocols reduce onboarding friction, enabling real-time quote binding that converts comparison shoppers into bound policyholders.
Market Restraints
- Carrier commission compression:Direct-to-consumer digital channels from incumbent insurers erode aggregator referral fees, squeezing unit economics in mature auto and home verticals.
- Data localization mandates:GDPR and emerging national privacy frameworks fragment cloud infrastructure requirements, raising compliance costs for cross-border platform operators.
- Algorithmic transparency rules:EU AI Act provisions constrain recommendation engine opacity, limiting personalization depth that drives conversion optimization.
Strategic Opportunities
- Claims advocacy services:Post-bind policy management creates recurring revenue streams through dispute resolution and renewal automation, transforming one-time commissions into subscription relationships.
- White-label broker infrastructure:Independent agents seek carrier panel expansion without direct appointments, creating B2B demand for private-branded comparison engines.
- Embedded insurance partnerships:E-commerce checkout integrations and IoT device bundling open distribution channels beyond traditional search-driven discovery.
Industry Challenges
- Legacy system integration:Carrier back-end modernization lags behind aggregator front-end capabilities, creating API connectivity gaps that fragment quote accuracy.
- Actuarial talent scarcity:Pricing model transparency requirements demand specialized compliance personnel that platform economics struggle to retain against carrier employers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insurance Aggregators Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Auto Insurance, Health Insurance, Life Insurance, Home Insurance End User: Individuals, Small Businesses, Corporates, Brokerages Distribution Channel: Online Platforms, Mobile Apps, Call Centers, Third-Party Agents Pricing Model: Commission-Based, Subscription, Pay-Per-Lead, Flat Fee |
| Companies Covered | CHECK24 Vergleichsportal GmbH, Gocompare.com Limited, InsuranceDekho Services Private Limited, Policybazaar Insurance Web Aggregator Private Limited, Huize Holding Limited, One97 Communications Limited, The Zebra Insurance Services LLC, Insurify Insurance Services Inc., TurtleMint Technologies Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insurance Aggregators Market Emerging Trajectories
Aggregator platforms are pivoting from transaction facilitation toward policy administration, embedding renewal management and claims support into core offerings. This shift redefines competitive differentiation beyond price comparison depth.
Blockchain-based smart contracts are decentralizing policy issuance and premium settlement by enabling programmable coverage terms that auto-execute upon verified events. Parametric insurers and insurtech startups adopt these protocols to bypass traditional claims adjustment delays. The structural consequence is compressing administrative overhead that previously justified aggregator intermediary fees.
GDPR and the EU AI Act are constraining algorithmic recommendation transparency across European aggregator operations. Industrial consequence includes mandatory explainability for premium ranking logic and explicit consent frameworks for predictive cross-selling. Health and life insurance verticals face the steepest compliance burden, with platforms restructuring data architecture to isolate training sets from inference engines.
Buyer behavior is fragmenting across generational lines as younger purchasers prioritize mobile-native experiences and instant binding over exhaustive comparison depth. Agent-assisted digital channels are displacing pure self-service models in complex commercial lines. India exhibits the sharpest behavioral divergence, with first-time buyers favoring voice-enabled local language interfaces over traditional web forms.
Insurance Aggregators Market Segmentation

Insurance aggregators segment across service verticals, buyer categories, and revenue mechanisms that determine platform architecture and carrier partnership strategies. Each dimension shapes technology investment priorities and regulatory compliance burdens differently.
Service Type:
Technical sophistication varies by policy complexity and data standardization maturity across insurance lines.
- Auto Insurance:Standardized vehicle data APIs and DMV integration enable real-time quote generation with minimal user input. Regulatory mandates in Germany through KBA and US state-level compulsory coverage laws sustain high transaction velocity on aggregator platforms.
- Health Insurance:Medical underwriting complexity and HIPAA privacy constraints in the US create friction in quote comparison workflows. India's IRDAI standardized product definitions reduce comparison complexity for first-time purchasers in metropolitan clusters.
- Life Insurance:Long-duration contracts with parametric mortality tables require simplified issue products for aggregator compatibility. Term life segments concentrate demand through direct-to-consumer digital channels.
- Home Insurance:Property valuation APIs and catastrophe risk scoring tools determine quote accuracy. Reinsurance treaty terms constrain carrier appetite displayed on comparison interfaces.
Auto Insurance leads on scale; Health Insurance leads on momentum.
End User:
Buyer sophistication and procurement authority reshape platform interface design and sales cycle length.
- Individuals:Personal line purchasers prioritize mobile-native interfaces and instant binding capabilities. GDPR consent frameworks in Europe and biometric KYC protocols in India segment onboarding workflows by jurisdiction.
- Small Businesses:Micro-enterprise liability coverage gaps drive demand for streamlined multi-carrier commercial package comparisons. Policybazaar and InsuranceDekho target this segment through agent-assisted digital channels in Indian tier-2 cities.
- Corporates:Risk manager procurement processes require customized RFP tools and loss history analytics that exceed standard aggregator capabilities. Direct broker relationships dominate this tier.
- Brokerages:Independent agents adopt white-label comparison engines to expand carrier panels without direct appointments. CHECK24 supplies private-branded infrastructure to German broker networks.
Individuals dominate transaction volume; Small Businesses expand most quickly.
Distribution Channel:
Channel economics determine customer acquisition cost structures and lifetime value optimization strategies.
- Online Platforms:Web-based quote engines capture search-driven demand through SEO-optimized landing pages. EU AI Act transparency requirements constrain recommendation algorithm opacity.
- Mobile Apps:Native application experiences prioritize push notification renewal reminders and claims status tracking. Younger demographics in India favor voice-enabled local language interfaces over traditional web forms.
- Call Centers:Agent-assisted channels persist in complex commercial lines and senior demographics. Labor cost arbitrage centers operations in Philippine and Indian BPO clusters.
- Third-Party Agents:Exclusive agent networks in India drive offline-to-online conversion for first-time insurance purchasers. Commission disclosure mandates under IRDAI regulations shape lead handoff protocols.
Online Platforms anchor revenue; Mobile Apps gain share fastest.
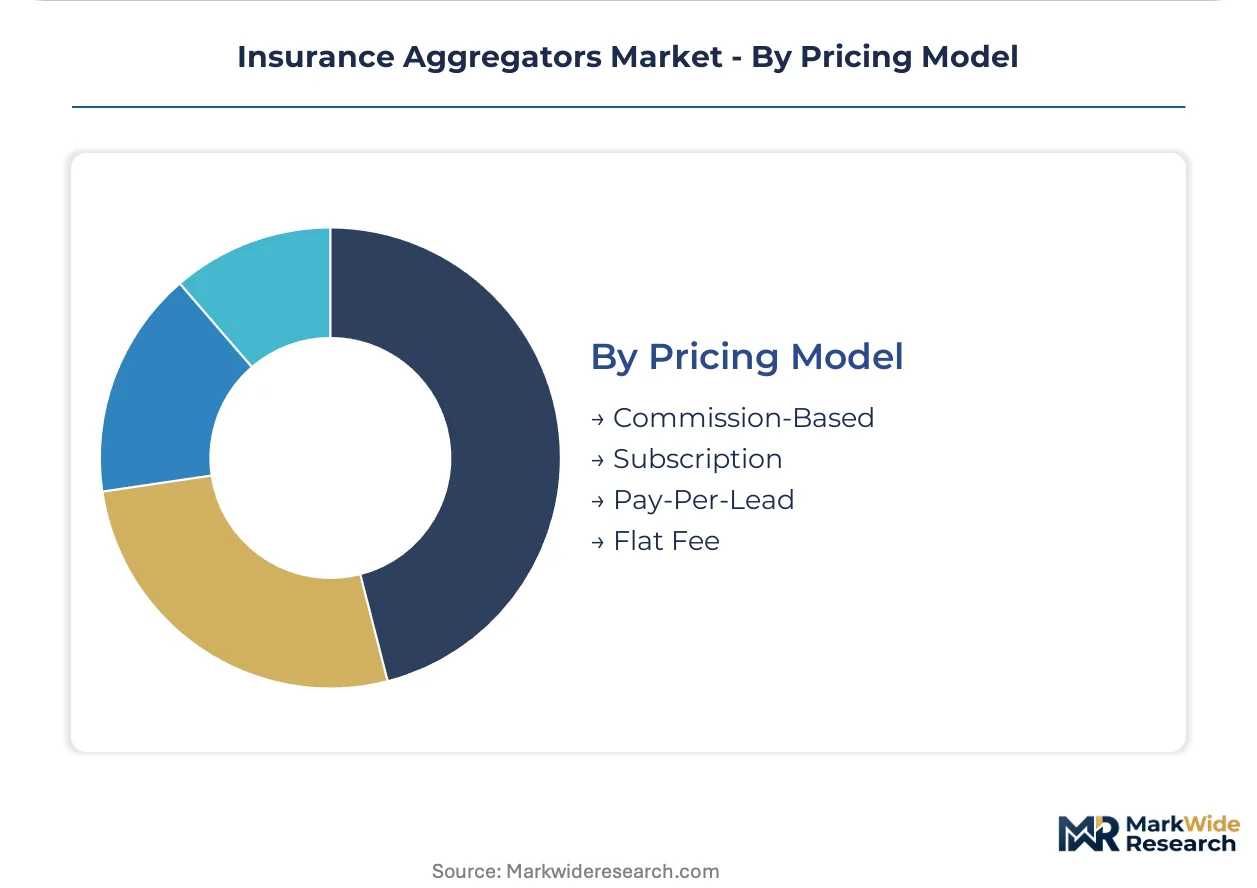
Pricing Model:
Revenue mechanism selection reflects platform maturity and carrier relationship power dynamics.
- Commission-Based:Percentage-of-premium fees align aggregator incentives with policy binding success. Carrier direct digital channels compress these rates in mature auto and home verticals.
- Subscription:Recurring fees for policy management and claims advocacy services transform one-time commissions into predictable revenue streams. Renewal automation tools justify ongoing customer payments.
- Pay-Per-Lead:Flat fees per qualified prospect shift risk to carriers but require robust lead scoring to prevent arbitrage. Data quality guarantees differentiate premium lead suppliers.
- Flat Fee:Fixed annual licensing for white-label broker infrastructure enables B2B revenue without transaction dependency. Implementation and training services supplement base platform fees.
Commission-Based retains scale dominance; Subscription demonstrates steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's auto insurance aggregator penetration exceeds India's by a wide margin, yet India's first-time purchaser growth rate outpaces all mature markets. Regulatory frameworks in each geography determine platform economics and carrier partnership viability.
United States
State-level compulsory auto coverage mandates sustain high transaction velocity across digital comparison platforms. The FTC enforces quote accuracy standards alongside HIPAA privacy constraints in health verticals. Silicon Valley insurtech clusters and Chicago-based BPO operations anchor customer acquisition infrastructure.
Germany
KBA vehicle registration integration enables real-time premium calculations with minimal user friction. GDPR and the EU AI Act constrain algorithmic recommendation opacity, mandating explainability for ranking logic. Munich and Berlin host the densest concentration of aggregator-carrier API development teams.
India
IRDAI web aggregator licensing legitimates digital intermediaries among first-time insurance purchasers in tier-2 cities. Capital requirements and exclusive online frameworks accelerate trust-based adoption. Mumbai and Bangalore anchor Policybazaar and InsuranceDekho's agent-assisted digital networks.
United Kingdom
FCA conduct rules govern price walking prohibitions and renewal transparency mandates across personal lines. GDPR data processing constraints reshape cross-selling consent frameworks. London's Lloyd's proximity sustains specialty commercial line aggregator development.
China
SAMR platform governance and MIIT data localization requirements fragment cloud infrastructure for cross-border operators. WeChat-embedded distribution channels displace traditional search-driven discovery. Shanghai and Shenzhen concentrate insurtech-aggregator partnership negotiations with state-owned carriers.
Insurance Aggregators Market Vendor Landscape
Top-tier vendors anchor multi-vertical platform scale, while regional specialists defend niche carrier relationships and local regulatory expertise. The vendor base stratifies across three tiers: pan-national comparison engines, vertical-specific aggregators, and white-label infrastructure providers. Strategic archetypes include AI-driven personalization specialists, agent-network hybrids, and embedded distribution enablers. Consolidation pressure manifests through carrier direct-channel expansion and API standardization mandates that raise fixed-cost barriers.
Within the agent-network hybrid archetype, Policybazaar Insurance Web Aggregator Private Limited and InsuranceDekho Services Private Limited exemplify India's dominant model combining extensive offline agent presence with direct digital reach. CHECK24 Vergleichsportal GmbH anchors the German market's auto and home verticals through sustained carrier panel breadth. Insurify Insurance Services Inc. occupies a position exemplifying AI-driven quote personalization that reduces user friction across multiple carrier APIs.
| Leading Market Players |
|---|
| CHECK24 Vergleichsportal GmbH |
| Gocompare.com Limited |
| InsuranceDekho Services Private Limited |
| Policybazaar Insurance Web Aggregator Private Limited |
| Huize Holding Limited |
| One97 Communications Limited |
| The Zebra Insurance Services LLC |
| Insurify Insurance Services Inc. |
| TurtleMint Technologies Private Limited |
| Others |
Supply Flow & Price Mechanics
EU AI Act algorithmic transparency mandates gate qualified supply for premium-tier aggregator platforms, restricting API access to carriers with compliant recommendation engines while compressing margins for non-compliant intermediaries. This regulatory filter concentrates pricing power among platforms that invested early in explainable AI infrastructure.
Pricing Analysis
Capacity additions in India's tier-2 cities are reshaping price floors for agent-assisted digital channels as Policybazaar and InsuranceDekho expand exclusive networks. Commission-based revenue dominates auto and home verticals, though carrier direct channels compress these rates. Price differentiation hinges on AI personalization depth and biometric KYC integration speed. Pricing pressure stems from embedded insurance partnerships that bypass traditional discovery fees. Small businesses show highest price sensitivity; corporates least.
Supply Chain Analysis
API infrastructure supply rests on cloud providers in the United States, Germany, and India, with carrier back-end systems in legacy mainframe architectures creating integration bottlenecks. Critical inputs include standardized vehicle data feeds, medical underwriting algorithms, and biometric identity verification protocols. Single-source vulnerability concentrates in DMV and KBA registration databases that enable real-time auto quoting. Distribution runs through white-label broker platforms, direct mobile apps, and exclusive agent networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Insurance aggregators function as a geographic-arbitrage play between India's IRDAI-regulated trust frameworks and Europe's GDPR compliance costs, with capital requirements in Mumbai and Bangalore running substantially below Munich and Berlin infrastructure investments.
For Market Incumbents: Deploy claims advocacy subscription services to counter carrier commission compression. CHECK24 and Policybazaar should deepen renewal automation tools that transform one-time commissions into recurring revenue. Direct-to-consumer digital channels from incumbent insurers threaten unit economics in mature auto verticals. Backward integration into policy administration software captures margin from lifecycle services.
For New Entrants and Emerging Players: Enter via small business commercial lines in Indian tier-2 cities where agent-assisted digital channels remain underpenetrated. White-label broker infrastructure offers the most penetrable B2B segment as independent agents seek carrier panel expansion without direct appointments. Voice-enabled local language interfaces provide a differentiated go-to-market angle for first-time insurance purchasers.
For Investors and Strategic Acquirers: Roll-up economics work for AI-driven personalization specialists because carrier API standardization raises fixed-cost barriers that favor scaled platforms. Five-to-ten year viability hinges on evolution from comparison-only intermediaries toward full policy administration platforms. Target acquisition archetype: vertical-specific aggregators with proprietary loss-history analytics. Watch open insurance mandate implementation pace as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Claims Advocacy Service Launch | Transforms one-time commissions into subscription revenue through dispute resolution automation. |
| Biometric KYC Integration | Reduces onboarding friction for Policybazaar and InsuranceDekho in Indian tier-2 expansion. |
| White-Label Broker Platform | CHECK24 supplies private-branded infrastructure to German independent agent networks. |
| Embedded Insurance Partnership | WeChat-integrated distribution in China bypasses traditional search-driven discovery channels. |
| EU AI Act Compliance Investment | Mandatory explainability for ranking logic constrains algorithmic opacity across European operations. |
Methodological Framework
Direct dialogue with aggregator platform executives, carrier digital distribution heads, IRDAI regulatory affairs specialists, and independent insurance brokers grounded the qualitative foundation. Secondary validation drew from IRDAI web aggregator licensing records, GDPR enforcement decisions, EU AI Act draft provisions, and carrier API documentation. SEC filings from listed insurtech platforms supplemented trade data on commission rate trends. Bottom-up segmentation modeling triangulated against top-down market sizing across service verticals.
Market value and volume trajectories emerged from algorithmic matching engine deployment rates, carrier API connectivity expansion, and small business formalization patterns across the projection horizon. Segmentation dimensions included service type, end-user category, distribution channel, and pricing model. CAGRs derived from regression analysis of historical transaction velocity and regulatory adoption curves. Forecast inputs incorporated biometric KYC penetration rates and open insurance mandate implementation schedules.
Inputs from carrier partnership disclosure filings and IRDAI licensing databases were available through the study window; gaps in private commission rate structures introduce uncertainty bands around revenue projections. Forecasts reflect documented assumptions on regulatory timeline adherence and API standardization velocity. Carrier direct-channel expansion, data localization mandate proliferation, and algorithmic transparency rule enforcement warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Indonesia Private Health Insurance Market
Insurance
United Kingdom Health and Medical Insurance Market
Insurance
Liability Insurance Market
Insurance
Consumer Electronics Extended Warranty Market
Insurance
Denmark Property and Casualty Insurance Market
Insurance
Asia-Pacific Electronic Gadgets Insurance Market
Insurance
Fire Insurance Market
Insurance
Intellectual Property Insurance Market
Insurance
Canada Parametric Insurance Market
Insurance
Dental Insurance Market
Insurance
Global Fine Art Insurance Market
Insurance
Logistics Insurance Market
Insurance
Cancer Insurance Market
Insurance
Germany Health and Medical Insurance Market
Insurance
India Liability Insurance Market
Insurance
India Health and Medical Insurance Market