
 Indonesia Private Health Insurance Market | 2026-2036
Indonesia Private Health Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Private Health Insurance Market Foresight
The capital-intensity divergence between established insurers and digital-first entrants is redrawing competitive boundaries in Indonesia's private health insurance sector. Allianz Indonesia leverages its bancassurance network through Mandiri Bank channels to sustain premium volume leadership. Prudential Indonesia anchors its position through agency-force density in secondary cities. AXA Mandiri competes by integrating corporate wellness programs with group policy structures.
Indonesia private health insurance constitutes risk-pooling financial instruments underwritten by commercial entities to cover medical treatment costs outside the national BPJS Kesehatan scheme, with policies typically specifying room-class limits, surgical procedure ceilings, and annual benefit caps. Individual Plans command premium pricing flexibility but Group Plans generate the largest premium pools through employer-sponsored enrollment at Indonesian manufacturing and services firms. Family Plans represent the fastest-growing product type as middle-income households seek coordinated outpatient and inpatient coverage across dependents.
BPJS Kesehatan coordination rules issued by the Ministry of Health and Otoritas Jasa Keuangan (OJK) capital adequacy requirements shape product design and distributor licensing. OJK's microinsurance regulations and sharia compliance standards under the National Sharia Council influence market access for domestic and foreign-owned underwriters. Stakeholders must monitor regulatory shifts around BPJS-private integration mandates and digital distribution licensing to align product portfolios with evolving compliance thresholds.
Market Dynamics
BPJS Kesehatan integration mandates from Indonesia's Ministry of Health are forcing private insurers to redesign products around gap-filling coverage rather than standalone comprehensive policies, compressing premium structures while expanding addressable enrollment pools.
Growth Catalysts
- Corporate Wellness Mandates:Indonesian manufacturing and services firms are expanding employer-sponsored group enrollment as employee retention instruments, channeling premium volume through payroll deduction systems.
- OJK Microinsurance Framework:Indonesia's financial services authority has streamlined capital requirements for low-premium products, enabling domestic underwriters to penetrate informal sector households previously excluded from commercial coverage.
- Jakarta-Surabaya Employer Density:Metropolitan concentration of multinational and large domestic enterprises sustains group policy origination through captive broker networks and direct corporate relationships.
Market Restraints
- Medical Cost Inflation:Private hospital tariff escalation in tier-one Indonesian cities outpaces premium adjustment cycles, eroding loss ratios and compressing underwriting margins.
- BPJS-Private Coordination Friction:Ministry of Health reimbursement rules create claims adjudication complexity, delaying settlement timelines and elevating administrative cost burdens for supplementary coverage providers.
- Agency Distribution Concentration:Reliance on individual agent networks in secondary cities limits digital penetration and inflates acquisition costs relative to bancassurance channels.
Strategic Opportunities
- Sharia-Compliant Product Lines:National Sharia Council certification requirements under OJK guidelines create differentiated positioning for takaful operators targeting Muslim-majority household segments.
- Telemedicine Integration:Convergence of remote consultation platforms with outpatient reimbursement riders is opening policy design space beyond traditional inpatient-centric coverage.
- Eastern Indonesia Geographic Expansion:Underpenetrated provinces outside Java present first-mover potential for digital-native distributors with lower fixed-cost infrastructure.
Industry Challenges
- Actuarial Talent Scarcity:Shortage of qualified underwriters familiar with BPJS coordination mechanics complicates product development and pricing accuracy.
- Legacy Core System Modernization:Incumbent insurers face integration friction between established policy administration platforms and API-driven distribution partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Private Health Insurance Market |
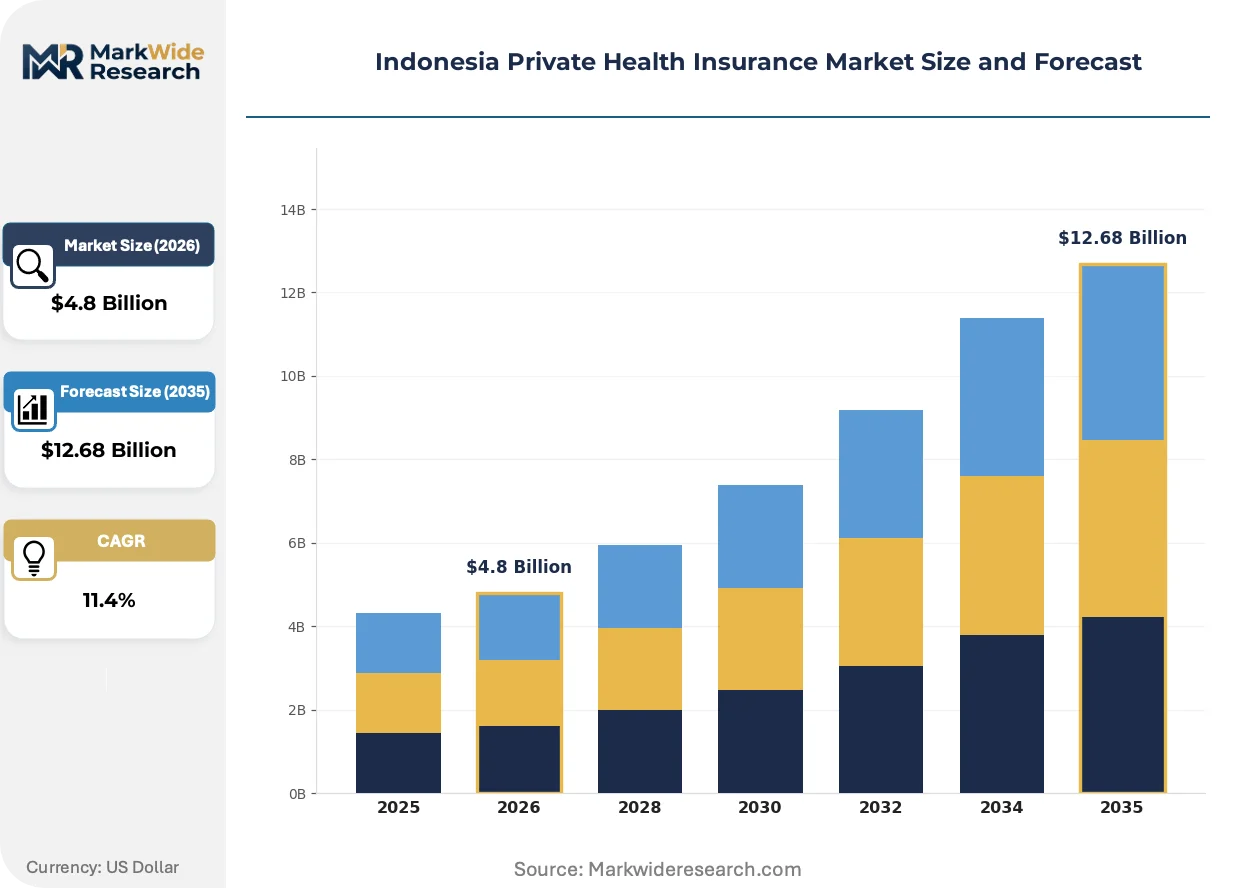
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Individual Plans, Family Plans, Group Plans, Critical Illness Plans Coverage Type: Inpatient Coverage, Outpatient Coverage, Dental Coverage, Vision Coverage Payment Model: Lifetime Coverage, Annual Limit, Pay-per-Visit, Fixed Benefit Customer Type: Employees, Self-Employed Individuals, Families, Seniors |
| Companies Covered | Allianz Indonesia, PT FWD Insurance Indonesia, Prudential Indonesia, AIA Financial Indonesia, Manulife Indonesia, AXA Mandiri, Pacific Cross Indonesia, Etiqa Indonesia, BNI Life, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Private Health Insurance Market Shifts & Advancements
Digital distribution architectures and regulatory coordination requirements are converging to reshape product design, channel economics, and customer acquisition strategies across Indonesian private health insurance.
Embedded insurance APIs are displacing traditional agent-led enrollment for individual and family plans. Fintech platforms and e-commerce marketplaces in Jakarta and Bandung are integrating health riders at point-of-transaction, compressing customer acquisition costs while reducing policy issuance friction. This channel shift is forcing established insurers to restructure commission frameworks and retrain field forces toward complex corporate cases.
OJK's digital distribution licensing framework is tightening capital and operational requirements for insurtech partnerships. The regulation mandates segregation of customer data custody and underwriting risk retention, elevating compliance costs for platform-dependent entrants. Domestic insurers with existing bancassurance infrastructure are adapting fastest by retrofitting API gateways onto legacy core systems.
Subscription-based outpatient riders are gaining traction among middle-income Jakarta households seeking predictable cash-flow management. Annual unlimited consultation packages are replacing per-visit reimbursement models, transferring utilization risk to underwriters while simplifying claims processing. This preference shift is most visible in employer-sponsored family plans at technology and professional services firms.
Indonesia Private Health Insurance Market Segmentation
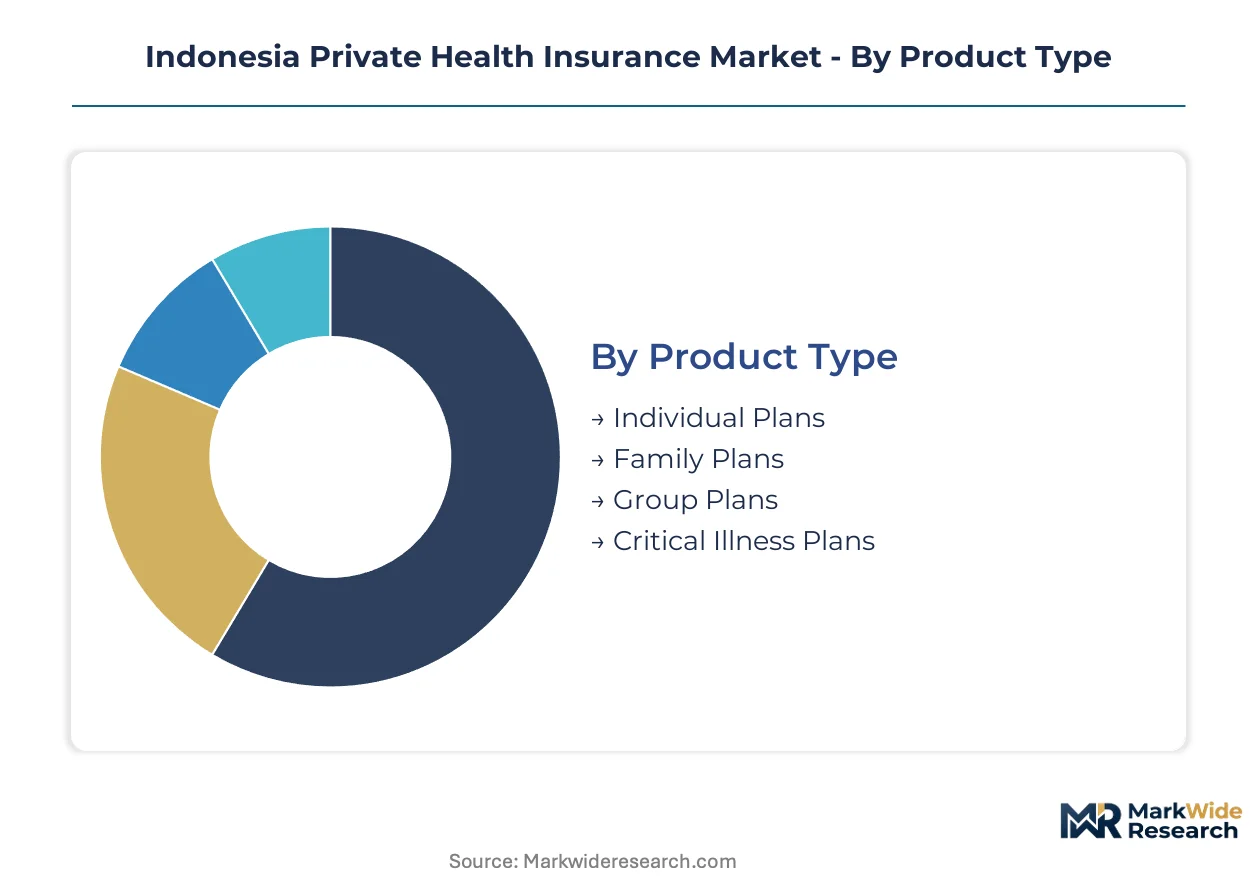
Product architecture in Indonesia's private health insurance sector reflects the tension between BPJS Kesehatan coordination mandates and employer-sponsored coverage expansion. Segment boundaries are blurring as underwriters redesign offerings around gap-filling rather than comprehensive standalone protection.
Product Type:
Geographic concentration varies sharply across product categories, with metropolitan employer pools driving group plan origination while family plans penetrate suburban Jakarta and Surabaya households.
- Individual Plans:Single-policyholder contracts specifying room-class limits and surgical ceilings. Demand concentrates among self-employed professionals in Jakarta's central business district, where brokers target lawyers, consultants, and medical practitioners seeking coverage above BPJS tier thresholds.
- Family Plans:Multi-dependent policies coordinating outpatient and inpatient benefits across household members. Middle-income households in Surabaya and Bandung are driving uptake as employers expand dependent eligibility in retention-focused benefit redesigns.
- Group Plans:Employer-sponsored enrollment through payroll deduction at manufacturing and services firms. Premium volume leadership rests with multinational captive programs in Jakarta's industrial corridors.
- Critical Illness Plans:Lump-sum diagnosis-triggered benefits for specified conditions. Penetration remains shallow outside executive tiers at large domestic enterprises.
Group Plans hold the largest share; momentum sits with Family Plans.
Coverage Type:
Cost tier differentiation separates premium inpatient riders from basic outpatient add-ons, with dental and vision occupying peripheral benefit positions.
- Inpatient Coverage:Hospitalization benefits specifying room class, surgical procedure ceilings, and annual maximums. Corporate wellness mandates at Indonesian manufacturing firms are expanding enrollment in mid-tier room-class configurations.
- Outpatient Coverage:Consultation, diagnostic, and pharmacy reimbursement structures. Subscription-based unlimited consultation packages are displacing per-visit models among technology sector employers in Jakarta.
- Dental Coverage:Preventive and restorative procedure benefits typically capped at low annual limits. Bundling rates remain minimal outside executive policy tiers.
- Vision Coverage:Examination and corrective lens allowances. Penetration tracks employer size, with negligible uptake in SME-sponsored programs.
Inpatient Coverage dominates premium contribution; Outpatient Coverage is climbing the fastest as telemedicine integration reshapes policy design.
Payment Model:
Application context determines model selection, with lifetime products anchoring high-net-worth retention strategies and annual limits serving cost-conscious employer segments.
- Lifetime Coverage:Guaranteed renewable contracts without age-based termination. Wealth preservation objectives among Jakarta's affluent professional class sustain demand despite elevated premium structures.
- Annual Limit:Calendar-year benefit maximums with renewal reunderwriting. Employer-sponsored programs at Indonesian services firms favor this structure for predictable budget forecasting.
- Pay-per-Visit:Direct reimbursement or cashless settlement per treatment episode. Administrative complexity limits scalability beyond niche broker arrangements.
- Fixed Benefit:Predetermined lump-sum payments regardless of actual treatment cost. Critical illness and hospital cash products utilize this mechanism for simplified claims adjudication.
Annual Limit configurations command the largest enrollment base; Fixed Benefit structures are gaining share fastest through insurtech platform distribution.
Customer Type:
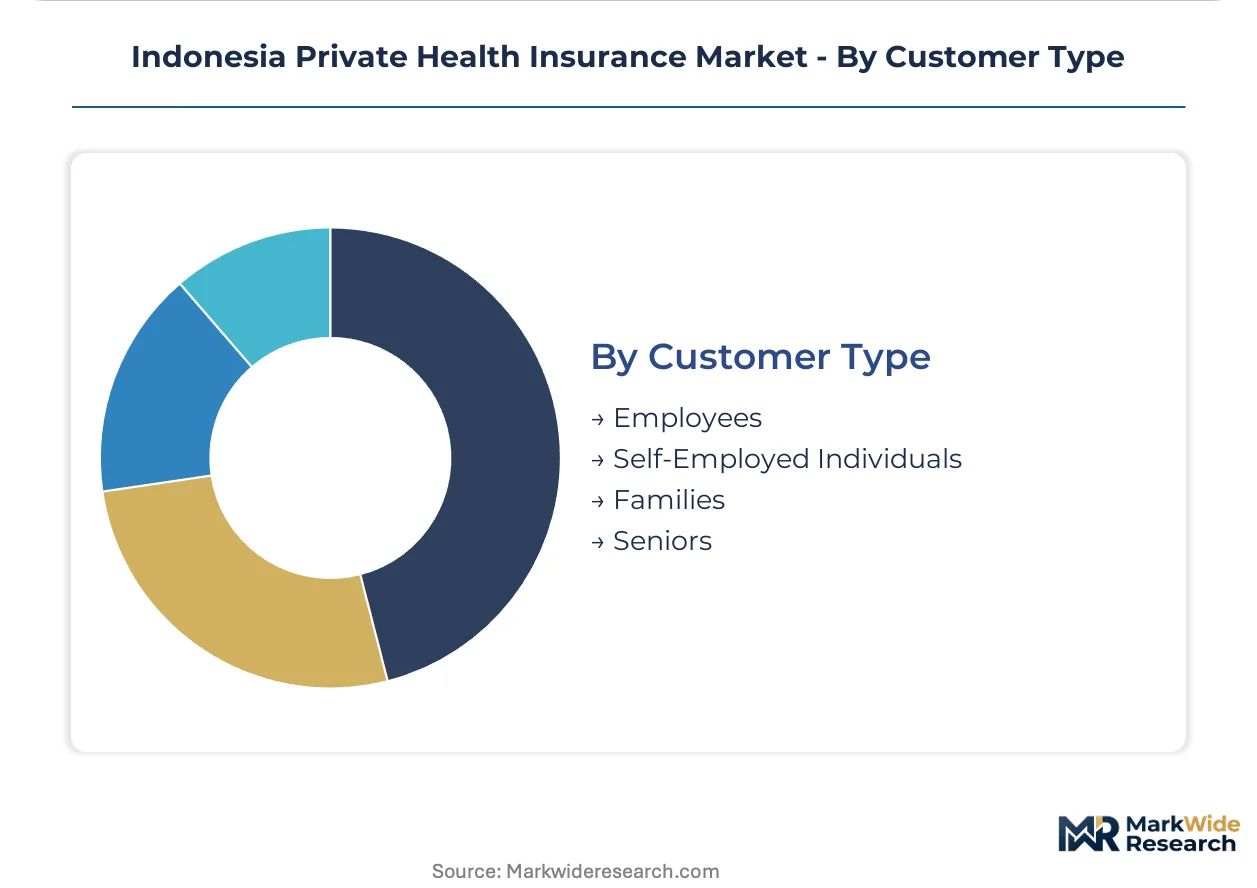
Volume concentration sits with payroll-deducted employee pools, while margin profiles favor senior segments requiring age-adjusted premium loading.
- Employees:Employer-sponsored enrollment through group master contracts. Manufacturing and services firms in Jakarta-Surabaya corridors generate the largest premium pools via captive broker relationships.
- Self-Employed Individuals:Direct-purchase policies without employer contribution. OJK microinsurance frameworks are expanding access for informal sector participants in Bandung and Medan.
- Families:Multi-generational household coverage spanning working adults and dependents. Middle-class expansion in secondary Javanese cities is driving coordinated benefit demand.
- Seniors:Age-65-plus policies with elevated premium tiers and restricted benefit periods. Product availability remains constrained by actuarial risk assessment limitations.
Employees constitute the largest addressable segment; Families are expanding most quickly as dependent coverage becomes standard in metropolitan employer benefit redesigns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Jakarta and Surabaya metropolitan corridors, while Eastern Indonesia provinces operate at compressed rate structures due to sparse hospital network density and lower employer concentration.
Java
Corporate wellness mandates at manufacturing and services firms drive group plan origination through payroll deduction systems. OJK capital adequacy requirements and BPJS Kesehatan integration rules issued by the Ministry of Health shape product design for supplementary coverage. Jakarta's central business district and Surabaya's industrial corridors generate the largest premium pools via captive broker relationships with multinational enterprises.
Sumatra
Medan and Palembang employer clusters sustain mid-tier group enrollment despite thinner hospital infrastructure compared to Java. OJK microinsurance frameworks expand access for informal sector participants in plantation and logistics-dependent economies. Distribution runs through agency networks with higher acquisition costs relative to bancassurance channels dominant in Java.
Sulawesi
Makassar anchors private health insurance penetration in Eastern Indonesia with emerging employer-sponsored programs at mining and fisheries processing operations. National Sharia Council certification requirements under OJK guidelines create positioning opportunities for takaful operators targeting Muslim-majority household segments. Hospital network gaps limit inpatient coverage depth outside the provincial capital.
Kalimantan
Balikpapan and Samarinda energy sector employers sustain executive-tier critical illness and international evacuation coverage demand. BPJS-private coordination friction creates claims adjudication complexity for supplementary providers operating in remote site locations. Telemedicine integration is opening policy design space for outpatient riders beyond traditional inpatient-centric structures.
Bali and Nusa Tenggara
Tourism sector employment pools in Denpasar generate seasonal group enrollment patterns distinct from manufacturing-based Java models. OJK digital distribution licensing mandates elevate compliance costs for platform-dependent entrants targeting hospitality industry microbusinesses. Underpenetration outside the southern tourist corridor presents first-mover potential for digital-native distributors with lower fixed-cost infrastructure.
Indonesia Private Health Insurance Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with established insurers leveraging bancassurance infrastructure against insurtech entrants compressing acquisition costs through embedded distribution APIs. The market structure tiers between capital-heavy incumbents with agency-force density and digital-first challengers reliant on platform partnerships. Three archetypes dominate: integrated financial conglomerates with captive bank channels, specialist health underwriters with corporate wellness program expertise, and technology-enabled distributors with API-driven enrollment. Competitive moves center on M&A to secure distribution access and strategic partnerships with fintech platforms for customer acquisition.
Within the integrated conglomerate tier, Allianz Indonesia and AXA Mandiri exemplify archetypes leveraging bancassurance networks to sustain premium volume leadership through established bank channel relationships. Prudential Indonesia occupies a position emphasizing agency-force density in secondary cities outside metropolitan Java corridors. Among specialist underwriters, AIA Financial Indonesia and Manulife Indonesia represent positioning anchored in corporate wellness program integration with employer-sponsored group structures.
| Leading Market Players |
|---|
| Allianz Indonesia |
| PT FWD Insurance Indonesia |
| Prudential Indonesia |
| AIA Financial Indonesia |
| Manulife Indonesia |
| AXA Mandiri |
| Pacific Cross Indonesia |
| Etiqa Indonesia |
| BNI Life |
| Others |
Supply & Pricing Matrix
Forty-five-day policy issuance cycles from quote to coverage activation compress pricing power for underwriters competing on speed, while extended claims adjudication timelines—stretching sixty to ninety days for BPJS-coordinated cases—elevate working capital requirements and force premium loading adjustments that vary by distributor channel efficiency.
Pricing Analysis
The customization-premium spread between individually negotiated corporate master contracts and standard off-the-shelf family plans runs wide, with group policies commanding fifteen to thirty percent rate advantages through volume pooling and streamlined underwriting. Price differentiation hinges on room-class tier selection and annual benefit ceiling configuration, with Jakarta-based multinationals least sensitive to premium escalation and self-employed professionals in secondary cities most responsive to rate competition. Pricing pressure stems from medical cost inflation at tier-one private hospitals outpacing annual adjustment cycles, compressing margins on legacy inpatient-centric products. Cost-conscious SME employers exhibit highest price sensitivity, driving demand for stripped-down gap-filling riders over comprehensive coverage.
Supply Chain Analysis
Inventory of licensed underwriter capacity concentrates in Jakarta and Surabaya, where established insurers maintain captive bancassurance infrastructure and agency-force density. Policy administration systems draw from legacy core platforms, cloud-hosted API gateways, and third-party claims management software. Supply chain risk centers on single-source vulnerability for BPJS claims coordination data feeds, which bottleneck settlement timelines when Ministry of Health systems experience downtime. Distribution runs through payroll deduction systems at employer sponsors, individual agent networks in secondary cities, and embedded APIs at fintech platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's private health insurance sector operates as a defensive-moat market where regulatory entrenchment—through OJK licensing requirements and BPJS integration mandates—erects substantial barriers against unlicensed entrants and protects incumbent premium pools.
For Market Incumbents: Shield core group policy portfolios against digital-native disintermediation by retrofitting API gateways onto legacy policy administration systems, preserving bancassurance channel control while compressing issuance friction. Deepen vertical integration into telemedicine platform partnerships to capture outpatient rider growth and defend margin position against insurtech challengers. For New Entrants and Emerging Players: Differentiate on sharia-compliant takaful architecture to access Muslim-majority household segments underserved by conventional underwriters, leveraging National Sharia Council certification as a positioning wedge. Target Eastern Indonesia provinces outside Java—Makassar, Denpasar, Manado—where hospital network gaps and thin incumbent presence create first-mover terrain for digital-native distributors with lower fixed-cost infrastructure. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified financial conglomerates seeking to divest non-core insurance subsidiaries amid OJK capital adequacy pressure; specialist health underwriters with corporate wellness program expertise command strategic premium. Long-term viability frames around integration density with BPJS Kesehatan systems and employer sponsor retention rates. The signal to watch is Ministry of Health reimbursement rule modifications that would accelerate or delay claims settlement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| API Gateway Integration | Retrofitting legacy core systems enables embedded distribution partnerships with fintech platforms in Jakarta. |
| Sharia Certification Investment | National Sharia Council approval opens differentiated positioning for takaful operators targeting Muslim households. |
| Telemedicine Platform Partnership | Remote consultation integration expands outpatient rider design space beyond inpatient-centric coverage structures. |
| Eastern Indonesia Geographic Expansion | Underpenetrated provinces outside Java present first-mover potential for digital-native distributors with lean infrastructure. |
| Corporate Wellness Program Development | Employer-sponsored enrollment through payroll deduction sustains premium volume leadership in manufacturing corridors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of OJK regulatory filings, Ministry of Health BPJS coordination circulars, and hospital tariff databases. Interviews with product development executives at established insurers, corporate benefits managers at Jakarta-Surabaya manufacturing firms, and digital distribution heads at insurtech platforms ground qualitative assessments. Secondary validation draws from OJK capital adequacy disclosures, National Sharia Council certification registries, and private hospital network expansion announcements. Bottom-up enrollment data by product type and province triangulates against top-down premium volume estimates across the analysis window.
Segmentation dimensions modeled encompass product architecture, coverage type, payment model, and customer category, with geographic concentration and distributor channel as cross-cutting variables. CAGRs derive from regression analysis of historical premium growth against employer density, hospital network expansion, and regulatory coordination intensity. Forecast inputs incorporate BPJS Kesehatan integration mandate implementation pace and OJK digital distribution licensing enforcement thresholds.
The analysis sits within stated boundaries; outcomes outside sustained employer-sponsored enrollment growth or accelerated BPJS-private coordination friction would require recalibration. Forecasts reflect documented assumptions around regulatory stability and medical cost inflation trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
China Group Health Insurance Market
Insurance
Slovenia Property and Casualty Insurance Market
Insurance
Asia-Pacific Family Floater Health Insurance Market
Insurance
Road Assistance Insurance Market
Insurance
US Electronic Gadgets Insurance Market
Insurance
Digital Innovation in Insurance Market
Insurance
Singapore Property and Casualty Insurance Market
Insurance
Insurance Protection Products Market
Insurance
Directors and Officers (Dando) Insurance Market
Insurance
General Insurance Market
Insurance
Cyber Liability Insurance Market
Insurance
Europe Liability Insurance Market
Insurance
Cybersecurity Insurance Market
Insurance
China Liability Insurance Market
Insurance
UK Commercial Insurance Market
Insurance
Peru Insurance Market