
 Saudi Arabia Property and Casualty Insurance Market | 2026-2036
Saudi Arabia Property and Casualty Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Property and Casualty Insurance Market Insights
Embedded maintenance and renewal subscription models within commercial policies is recalibrating how insurers capture lifetime value from corporate clients. Tawuniya leverages its government-linked heritage to anchor large infrastructure risk pools. Bupa Arabia for Cooperative Insurance differentiates through health-coverage cross-selling into corporate P&C portfolios. MEDGULF competes on reinsurance-backed capacity for complex energy and construction risks.
Property and casualty insurance in Saudi Arabia constitutes risk-transfer contracts covering asset damage, legal liability, and business interruption, with policy terms typically spanning twelve months and premiums calculated through actuarial loss-ratio modeling against regional catastrophe exposure. Its primary purpose is to absorb financial shocks from fire, natural disaster, theft, and third-party claims across commercial and personal balance sheets. Auto Insurance leads product-type premium generation due to mandatory motor coverage requirements, while Commercial Insurance captures the fastest expansion as megaproject construction accelerates capital-risk underwriting. Brokerage dominates distribution channel flows for complex corporate placements, though Online Platforms are gaining transaction share among individual policyholders seeking rate transparency.
SAMA, the country's national insurance regulator, enforces cooperative structure requirements and capital adequacy ratios that shape carrier formation and foreign participation limits. SAMR's mandatory motor insurance rules and building-code-linked property coverage obligations directly expand addressable demand pools. Stakeholders must monitor how regulatory liberalization of foreign ownership caps and digital distribution licensing reshape competitive dynamics and capital deployment priorities.
Market Dynamics
Vision 2030 megaprojects are compressing risk-transfer timelines as contractors demand faster policy issuance and bundled coverage for construction-phase liabilities.
Growth Catalysts
- Cooperative insurance regulations:SAMR's enforcement of mutualized capital structures expands carrier formation and deepens market participation.
- NEOM and Red Sea Project construction:These giga-developments generate concentrated demand for contractor all-risk and delayed start-up coverage.
- Telematics-enabled motor underwriting:Usage-based pricing models are penetrating the mandatory auto segment through smartphone-linked risk scoring.
Market Restraints
- Reinsurance capacity concentration:Lloyd's and regional retrocession markets control pricing for catastrophe-exposed property layers, creating volatility.
- Actuarial data scarcity:Limited historical loss experience for Saudi-specific perils distorts pricing models and inflates risk margins.
- Sharia compliance overhead:Takaful operational structures impose duplicate governance costs that compress expense ratios versus conventional peers.
Strategic Opportunities
- Eastern Province industrial clusters:Jubail and Ras Al-Khair petrochemical zones remain underpenetrated for specialty environmental liability coverage.
- Embedded insurance APIs:Real estate platforms and auto dealerships are integrating point-of-sale policy issuance into purchase journeys.
- SAMA sandbox licensing:Digital distribution waivers enable insurtechs to bypass traditional broker networks for direct consumer acquisition.
Industry Challenges
- Actuarial talent scarcity:The shortage of Arabic-speaking catastrophe modelers constrains product development cycles.
- Legacy core system integration:Mainframe-dependent carriers face friction connecting policy administration to cloud-based distribution channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Property and Casualty Insurance Market |
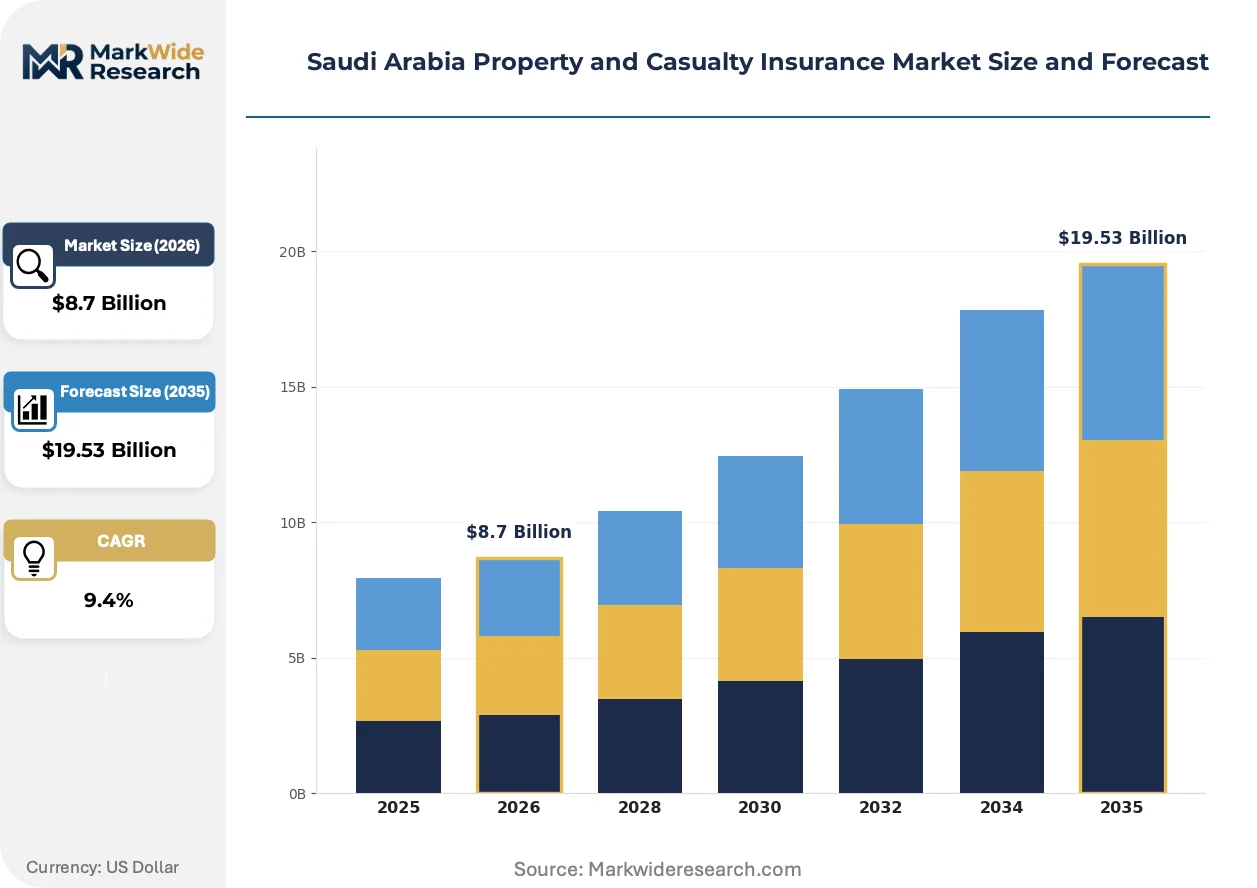
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Home Insurance, Auto Insurance, Liability Insurance, Commercial Insurance Distribution Channel: Brokerage, Direct Sales, Online Platforms, Agents Customer Type: Individuals, SMEs, Large Enterprises, Corporates Coverage Type: Fire, Theft, Natural Disaster, General Liability |
| Companies Covered | The Company for Cooperative Insurance (Tawuniya), Bupa Arabia for Cooperative Insurance, Mediterranean & Gulf Cooperative Insurance & Reinsurance (MEDGULF), Malath Cooperative Insurance Co., Arabian Shield Cooperative Insurance Co., Saudi Arabian Cooperative Insurance Co., Gulf Union Cooperative Insurance Company, Al-Ittihad Cooperative Insurance Company, Allianz SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Property and Casualty Insurance Market Trends and Innovations
Digital risk assessment tools are compressing underwriting cycles while regulatory pressure on cooperative structures forces operational redesign across carrier balance sheets.
Artificial intelligence is integrating into claims triage workflows across Saudi carriers. Tawuniya and MEDGULF have deployed computer-vision damage assessment for auto and property losses. The technology is integrating fraud detection with automated reserve setting, collapsing settlement timelines from weeks to hours.
SAMR's mandatory motor third-party liability enforcement has eliminated uninsured driving in the Kingdom. The regulation compels real-time policy verification through traffic authority integration. Fleet operators now face automated compliance checks at registration renewal, shifting broker priorities toward commercial motor portfolios.
Corporate risk managers are consolidating coverage procurement through captive insurance arrangements. Large construction firms and petrochemical operators are establishing licensed captives in Riyadh to retain predictable loss layers. This concentration is visible among Vision 2030 prime contractors seeking balance-sheet efficiency on multi-billion riyal project schedules.
Saudi Arabia Property and Casualty Insurance Market Segmentation
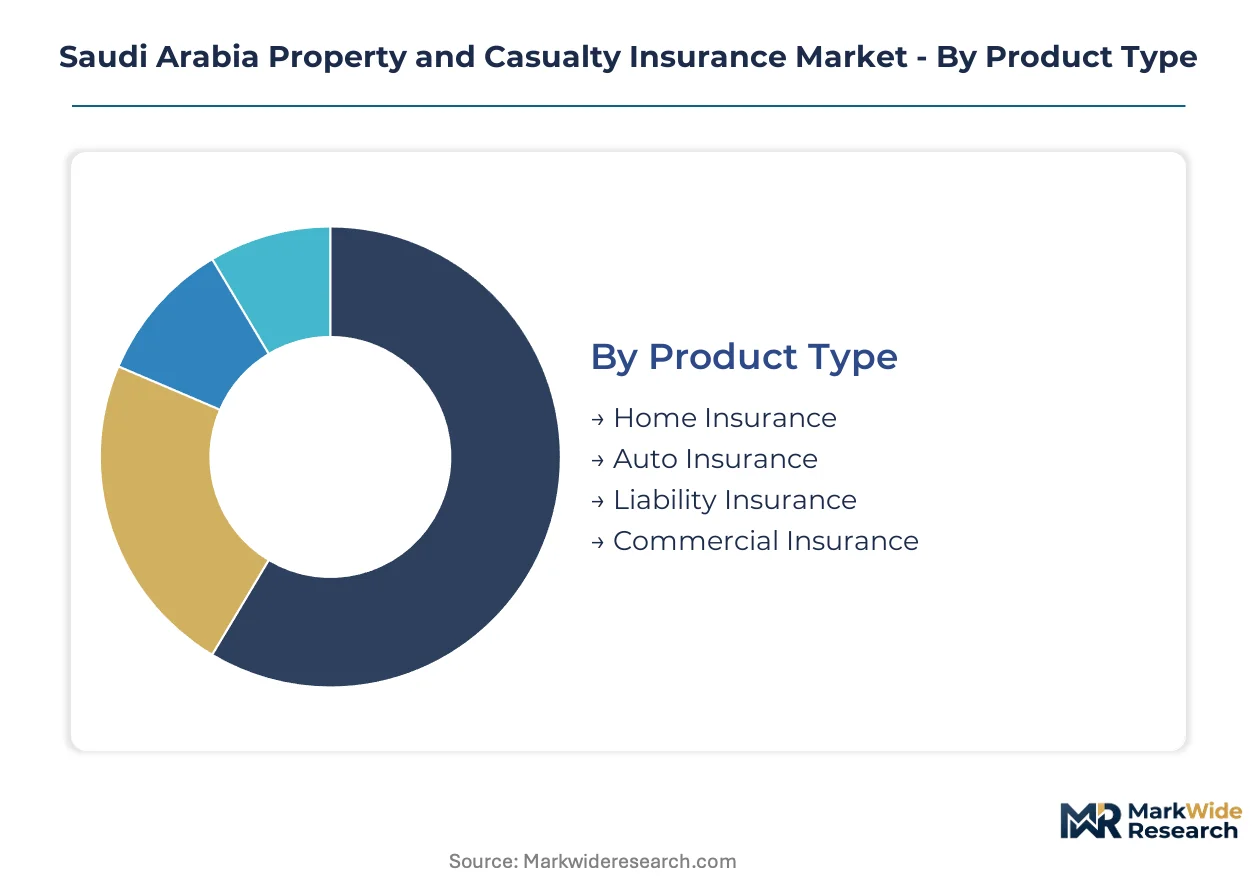
Segmentation in the Saudi Arabia Property and Casualty Insurance Market reveals how risk appetite, procurement complexity, and regulatory exposure fragment demand across policy structures and buyer profiles. Carrier product development and distribution investment priorities depend on which segments concentrate premium volume versus which segments expand addressable coverage pools.
Product Type:
Premium allocation across product lines reflects mandatory coverage obligations versus voluntary capital protection decisions by corporate risk managers.
- Auto Insurance:Mandatory motor third-party liability dominates transaction volumes through SAMR enforcement and real-time traffic authority integration. Fleet operators in Riyadh and Jeddah drive commercial motor expansion as Vision 2030 logistics networks scale.
- Commercial Insurance:Contractor all-risk and delayed start-up policies capture the steepest expansion trajectory as NEOM and Red Sea Project construction compress issuance timelines and demand bundled liability structures.
- Home Insurance:Building-code-linked property coverage obligations in urban centers generate baseline demand, though penetration lags commercial lines due to price-sensitive retail buyers.
- Liability Insurance:Professional indemnity and directors-and-officers coverage concentrate among listed entities and government contractors facing procurement compliance requirements.
Auto Insurance leads on scale; Commercial Insurance leads on momentum.
Distribution Channel:
Channel selection tracks policy complexity and buyer sophistication, with corporate placements demanding advisory depth while personal lines shift toward digital convenience.
- Brokerage:Complex corporate placements and construction-phase liability bundling require specialized intermediaries with reinsurance market access and actuarial support capabilities. Broker networks concentrate premium flows from large enterprises and petrochemical operators in the Eastern Province.
- Online Platforms:Direct-to-consumer digital distribution gains transaction share among individual policyholders seeking rate transparency and instant policy issuance. SAMA sandbox licensing enables insurtechs to bypass traditional networks for personal auto and home coverage acquisition.
- Direct Sales:Carrier captive channels serve multinational corporate accounts with centralized risk management functions and captive insurance arrangements.
- Agents:Tied-agent networks retain relevance in SME commercial motor placement and regulatory compliance verification services.
Brokerage dominates premium value; Online Platforms dominate volume expansion.
Customer Type:
Buyer scale determines policy structure complexity, from standardized individual products to customized corporate risk-transfer programs with captive retention layers.
- Large Enterprises:Vision 2030 prime contractors and petrochemical operators consolidate coverage through captive insurance arrangements in Riyadh, retaining predictable loss layers on multi-billion riyal project schedules while ceding catastrophe exposure to reinsurance markets.
- SMEs:Small and medium enterprises concentrate demand in packaged commercial motor and property coverage, with brokers prioritizing this segment as compliance automation reduces individual policy servicing margins.
- Corporates:Listed entities and government-linked companies drive demand for directors-and-officers liability and professional indemnity coverage tied to procurement qualification requirements.
- Individuals:Mandatory auto coverage and building-code-linked home insurance generate baseline retail demand, with telematics-enabled usage-based pricing penetrating the smartphone-linked risk scoring segment.
Large Enterprises lead on premium concentration; SMEs lead on addressable pool expansion.
Coverage Type:
Peril-specific coverage demand tracks regional catastrophe exposure, regulatory mandates, and sectoral liability concentrations across the Kingdom.
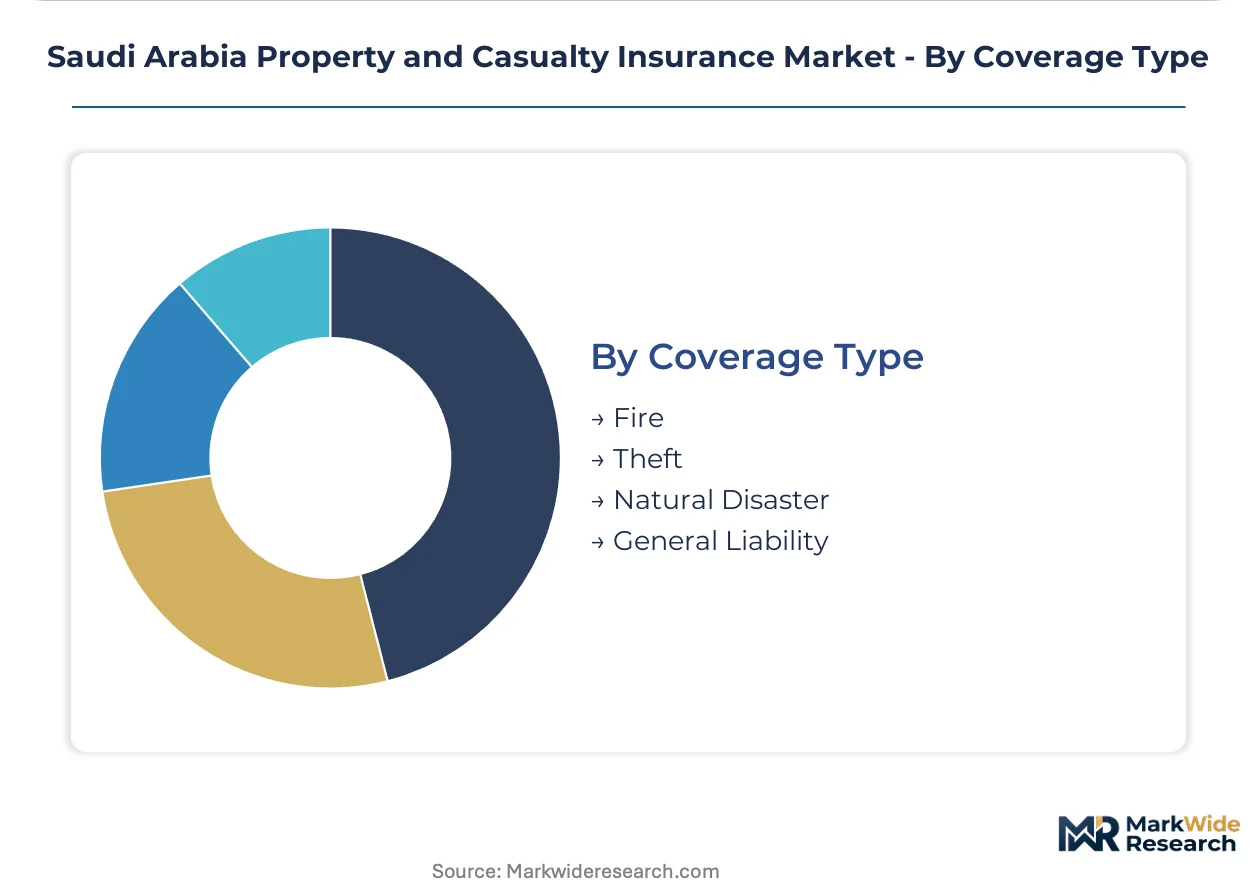
- Fire:Property damage coverage dominates commercial and residential policy structures, with pricing calibrated to Saudi-specific construction materials and suppression system standards. Industrial clusters in Jubail and Ras Al-Khair drive specialty fire engineering requirements for petrochemical facilities.
- General Liability:Third-party bodily injury and property damage coverage expands through contractor all-risk policies tied to megaproject construction timelines, with delayed start-up endorsements addressing business interruption from supply chain disruption.
- Natural Disaster:Flood and earthquake coverage remains limited by actuarial data scarcity and reinsurance capacity concentration, creating pricing volatility for catastrophe-exposed property layers.
- Theft:Crime coverage concentrates in commercial inventory and construction equipment policies, with demand clustering in high-value logistics corridors between Riyadh and Dammam.
Fire leads on policy penetration; General Liability leads on growth acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UAE carriers command premium pricing in Gulf-wide specialty lines, while Saudi operators leverage Vision 2030 construction volumes to outpace regional growth trajectories. This divergence shapes competitive positioning across the Arabian Peninsula insurance corridor.
United Arab Emirates
DIFC-based reinsurance hubs and Dubai's maritime trade flows sustain demand for marine cargo and political risk coverage. The UAE Insurance Authority mandates solvency margin requirements that filter carrier formation. Abu Dhabi National Oil Company supply chain contractors cluster in Khalifa Industrial Zone, driving contractor all-risk placement volumes.
Qatar
Liquefied natural gas expansion projects and FIFA World Cup legacy infrastructure sustain commercial property underwriting. The Qatar Financial Centre Regulatory Authority governs captive insurance licensing for energy majors. Ras Laffan Industrial City petrochemical operators retain predictable loss layers through licensed captives, ceding catastrophe exposure to London markets.
Kuwait
Oil field renewal contracts and port modernization generate delayed start-up coverage demand. The Kuwait Insurance Regulatory Unit enforces cooperative structure requirements mirroring Saudi SAMA frameworks. Mina Al-Ahmadi refinery complex contractors bundle construction-phase liability with business interruption endorsements.
Bahrain
Regional banking headquarters and aluminum smelting operations concentrate professional indemnity and environmental liability demand. The Central Bank of Bahrain licenses captive arrangements for Gulf corporate treasury functions. Alba Line 6 expansion contractors in Askar procure specialty pollution coverage through Manama-based intermediaries.
Oman
Duqm Special Economic Zone port and logistics investments accelerate contractor all-risk issuance timelines. The Capital Market Authority mandates motor third-party liability coverage through traffic authority integration. Salalah Free Zone manufacturing tenants procure packaged commercial property and general liability through broker networks.
Saudi Arabia Property and Casualty Insurance Market Competitive Landscape
Top-tier vendors anchor government-linked heritage positions, while mid-tier cooperative insurers compete on reinsurance-backed capacity and cross-selling integration. The Saudi P&C market exhibits tiered consolidation around Vision 2030 prime contractor relationships and SAMA cooperative capital requirements. Three archetypes dominate: heritage carriers with state-linked origination, health-P&C cross-sellers leveraging employer-sponsored portfolios, and reinsurance-dependent specialists in energy and construction layers. Competitive moves concentrate on captive insurance structuring for large enterprises and telematics-enabled motor pricing to capture individual policyholder data flows.
Within the heritage carrier tier, The Company for Cooperative Insurance (Tawuniya) occupies a position exemplifying government-linked origination advantages, while Bupa Arabia for Cooperative Insurance represents the health-P&C cross-selling archetype through employer portfolio integration. Mediterranean & Gulf Cooperative Insurance & Reinsurance (MEDGULF) anchors the reinsurance-backed specialist segment for complex energy and construction risks. These three carriers collectively illustrate the strategic segmentation governing competitive dynamics in the Kingdom's cooperative insurance framework.
| Leading Market Players |
|---|
| The Company for Cooperative Insurance (Tawuniya) |
| Bupa Arabia for Cooperative Insurance |
| Mediterranean & Gulf Cooperative Insurance & Reinsurance (MEDGULF) |
| Malath Cooperative Insurance Co. |
| Arabian Shield Cooperative Insurance Co. |
| Saudi Arabian Cooperative Insurance Co. |
| Gulf Union Cooperative Insurance Company |
| Al-Ittihad Cooperative Insurance Company |
| Allianz SE |
| Others |
Pricing and Supply Chain Analysis
Heritage carrier dominance versus insurtech challenger pricing creates a bifurcated market where government-linked origination commands premium placement fees while digital-native distributors compress margins through automated underwriting. This divergence manifests in SAMA-regulated cooperative structures absorbing higher compliance costs that flow into policy pricing, whereas sandbox-licensed entrants strip out intermediary layers to capture price-sensitive individual segments.
Pricing Analysis
Capacity additions in Riyadh-based cooperative formations are reshaping price floors for commercial property coverage as new entrants compete for Vision 2030 contractor portfolios. Three-tier pricing structure across premium, standard, and economy levels reflects reinsurance backing depth and actuarial sophistication, with Lloyd's-linked carriers capturing catastrophe-exposed layers at premium multiples. Pricing pressure stems from telematics-enabled motor commoditization eroding traditional broker commissions. SMEs exhibit highest price sensitivity, while large enterprises prioritize captive structuring over rate competition.
Supply Chain Analysis
Freight costs for London and Bermuda reinsurance capacity constitute a material pricing component for Saudi catastrophe layers, with retrocession markets controlling property pricing volatility. Supply concentrates in Lloyd's syndicates, Munich Re, and regional Gulf retrocession pools for complex energy and construction risks. Raw material dependencies include actuarial modeling software from US and UK vendors, Arabic-language claims adjusters, and Sharia compliance audit services. Single-source vulnerability sits with concentrated reinsurance capacity for flood and earthquake exposure. Distribution runs through brokerage networks for corporate placements and direct digital channels for individual policyholders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where corporate risk managers are consolidating procurement through captive arrangements, signaling sustained demand for premium advisory services over transactional placement.
For Market Incumbents: Hedge reinsurance capacity concentration by diversifying retrocession relationships across Lloyd's, Bermuda, and emerging Asian markets. Lock in multi-year contractor relationships with Vision 2030 prime developers before SAMA liberalizes foreign ownership caps that could admit global carriers with deeper balance sheets. For New Entrants and Emerging Players: The mid-market SME gap between Tawuniya's government-linked premium positioning and basic digital auto coverage offers white-space opportunity. Target Eastern Province industrial clusters for environmental liability specialization where incumbent actuarial talent scarcity constrains product development. Deploy embedded insurance APIs through real estate platforms as the primary go-to-market vector. For Investors and Strategic Acquirers: Consolidation pressure builds where cooperative capital requirements and SAMA solvency ratios strain sub-scale carriers. Long-term viability favors reinsurance-backed specialists with demonstrated megaproject placement capabilities. Monitor SAMA foreign ownership liberalization announcements as the inflection signal for global carrier entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Insurance Licensing | Enables large enterprises to retain predictable loss layers while ceding catastrophe exposure to reinsurance markets. |
| Telematics Platform Integration | Compresses motor underwriting cycles through smartphone-linked risk scoring that displaces traditional broker verification. |
| Reinsurance Relationship Diversification | Reduces pricing volatility from Lloyd's capacity concentration for flood and earthquake-exposed property layers. |
| Embedded Insurance API Development | Integrates point-of-sale policy issuance into real estate and auto dealership purchase journeys. |
| Actuarial Talent Localization | Addresses Arabic-speaking catastrophe modeler scarcity that constrains product development cycles. |
Research Methodology
Bottom-up corporate risk manager modeling reconciled against top-down SAMA regulatory filing tracking forms the analytical core of this study. Primary interviews with chief risk officers at Vision 2030 contractors, cooperative insurance actuaries, brokerage placement specialists, and SAMA regulatory affairs directors combined with secondary validation from SAMA annual reports, cooperative insurer financial disclosures, and Lloyd's market intelligence filings. Triangulation across these sources calibrated premium volume estimates and growth trajectory assumptions.
Input-output matrices mapped policy issuance volumes by product type against distribution channel capacity and customer segment procurement patterns throughout the forecast period. Segmentation dimensions modeled include product line complexity, buyer scale archetype, coverage peril type, and regional regulatory cluster. CAGRs derived from actuarial loss-ratio projections against construction-phase liability expansion timelines and mandatory motor enforcement saturation curves. Forecast inputs incorporated NEOM and Red Sea Project construction schedules alongside SAMA sandbox licensing penetration rates.
Caveats apply where reinsurance market capacity contraction or SAMA foreign ownership liberalization timing could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Europe Entertainment Insurance Market
Insurance
Asia-Pacific EV Insurance Market
Insurance
Asia-Pacific Family Floater Health Insurance Market
Insurance
Saudi Arabia Travel Insurance Market
Insurance
Asia-Pacific Extended Warranty Market
Insurance
Global Long Term Care Insurance Market
Insurance
United Kingdom Parametric Insurance Market
Insurance
Group Health Insurance Market
Insurance
Spain Parametric Insurance Market
Insurance
Vietnam Private Health Insurance Market
Insurance
Russia Property and Casualty Insurance Market
Insurance
Self Funded Insurance Market
Insurance
Asia-Pacific Electronic Gadgets Insurance Market
Insurance
Saudi Arabia Health & Medical Insurance Market
Insurance
Usage-Based Insurance (UBI) Market
Insurance
Marine Cargo Insurance Market