
 Identity Theft Insurance Market | 2026-2036
Identity Theft Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Identity Theft Insurance Market Analysis
Market Context
Certified cybersecurity actuarial talent is collapsing across the insurance sector, tightening product development cycles and delaying regional rollout timelines. Gen Digital leverages its consumer security software heritage to anchor subscription bundling models that embed identity coverage at low marginal cost. Allstate competes through agency channel control, sustaining agent-driven policy attachment rates that outperform direct-to-consumer benchmarks.
Technical Definition and Segment Structure
Identity theft insurance is a specialized risk-transfer instrument that reimburses policyholders for direct financial losses, legal fees, and remediation costs arising from stolen personal identifiers, typically covering credit monitoring, fraud affidavit filing, and identity restoration services with benefit limits ranging from ten thousand to one million dollars. The product serves commercial and individual buyers seeking financial protection against synthetic identity fraud, account takeover, and tax refund theft. Insurance Coverage dominates premium volume among product types due to its explicit loss reimbursement structure, while Monitoring Services leads service-type growth as real-time dark-web surveillance becomes standard in employer benefit packages. Enterprise customer segments concentrate margin pools through multi-year master policies, though Individuals still anchor absolute policy count across distribution channels.
Regulatory Frame and Outlook
FCC rules on data breach notifications for telecommunications carriers, state-level insurance commissioner rate filings, and GDPR cross-border data handling standards collectively shape product design, pricing freedom, and cross-border policy portability. HIPAA obligations for healthcare sector breach response create adjacent demand for identity restoration riders among medical practice group policies. Stakeholders must monitor how fragmented US state legislation and EU Digital Operational Resilience Act implementation timelines reshape coverage definitions and trigger new exclusion language.
Market Dynamics
Cyberattack frequency is compressing enterprise procurement cycles for identity protection coverage, with breach notification mandates across fragmented US state laws and EU GDPR compliance obligations forcing faster policy adoption decisions than traditional insurance purchasing patterns allow.
Growth Catalysts
- EU AI Act compliance burdens:European corporations face expanded liability frameworks for automated decision-making systems processing personal identifiers, driving bundled identity protection procurement alongside cyber policies.
- Healthcare sector HIPAA breach response:Medical practice groups confront mandatory patient notification timelines after data incidents, creating adjacent demand for identity restoration riders on professional liability coverage.
- Telecommunications carrier exposure:FCC data breach notification rules for telecom providers expand the insured population base as employers in this sector sponsor workforce enrollment.
Market Restraints
- Certified cybersecurity actuarial scarcity:Collapsing talent pools across the insurance sector tighten product development cycles and delay regional rollout timelines for specialized coverage forms.
- Synthetic identity fraud detection limitations:Current monitoring technologies struggle to distinguish fabricated identities from legitimate consumers, inflating loss ratios and constraining benefit limit expansion.
- State-level rate filing friction:US insurance commissioners impose varying approval timelines and capital requirements, fragmenting product standardization and raising compliance overhead.
Strategic Opportunities
- Dark-web surveillance integration:Real-time credential monitoring technology convergence with employer benefit platforms enables low-marginal-cost subscription bundling at scale.
- Tax refund theft coverage gaps:Seasonal filing vulnerabilities create underpenetrated application white space for specialized indemnity riders targeting individual policyholders.
- EU Digital Operational Resilience Act implementation:Financial entity operational continuity mandates will trigger new exclusion language and coverage definition expansions across member states.
Industry Challenges
- Identity restoration service capacity constraints:Fraud affidavit filing and case management workflows require specialized operational infrastructure that scales unevenly with policy volume growth.
- Legacy policy administration system integration:Carrier core platforms built for traditional property-casualty lines resist modification for real-time monitoring service delivery and claims automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Identity Theft Insurance Market |
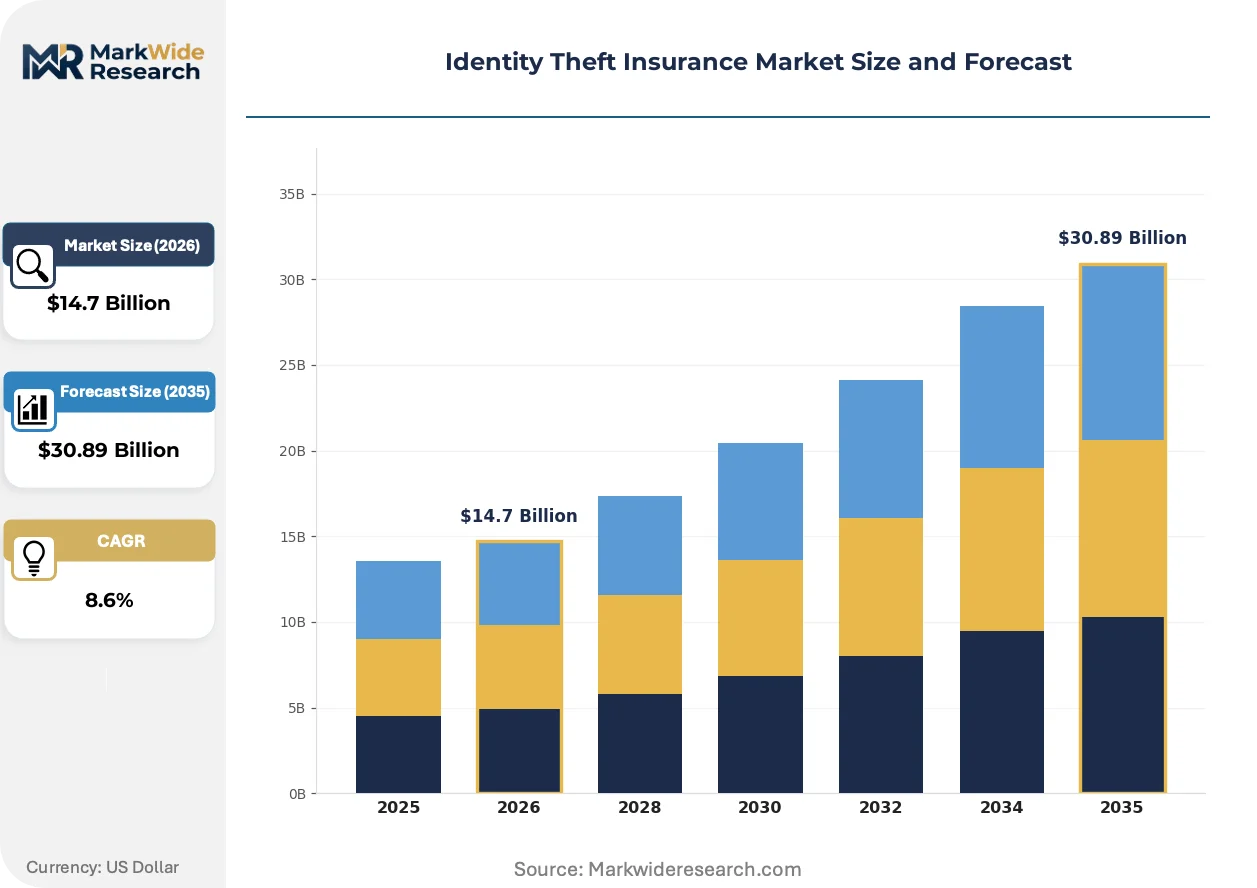
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Credit Monitoring, Fraud Alerts, Identity Restoration, Insurance Coverage Customer Type: Individuals, Families, Businesses, Enterprises Service Type: Consulting, Prevention Services, Recovery Services, Monitoring Services Distribution Channel: Online Platforms, Insurance Brokers, Financial Institutions, Direct Sales |
| Companies Covered | Gen Digital, Aura, Allstate, Experian, Equifax, Nationwide Mutual Insurance Company, IdentityForce, Zander Insurance, Chubb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Identity Theft Insurance Market Emerging Trajectories
Automated dark-web credential scanning is embedding into standard employer benefit packages, compressing the distinction between insurance and technology service delivery while reshaping how carriers structure subscriber relationships and recurring revenue models.
Machine-learning-driven fraud pattern recognition is displacing rule-based transaction monitoring in identity protection platforms. Large employers with self-insured health arrangements are adopting these tools at twelve-to-eighteen-month refresh cycles. The technology is displacing manual case review workflows and collapsing per-incident restoration costs below traditional service delivery benchmarks.
GDPR cross-border data handling standards are forcing carriers to redesign policy portability clauses for multinational workforces. The regulation mandates explicit consent mechanisms for personal data transfers between EU and non-EU jurisdictions. Enterprise master policies covering US-Germany-UK employee populations face the most complex restructuring, with underwriters introducing territory-specific sub-limits and local claims handling mandates.
Employer-sponsored enrollment is crowding out individual direct purchase as the dominant distribution channel. Benefits administrators are unbundling identity protection from packaged voluntary offerings and attaching it to core medical plans. This pattern is most visible in US states with the most stringent breach notification statutes, where HR departments treat coverage as compliance infrastructure rather than discretionary perk.
Identity Theft Insurance Market Segmentation
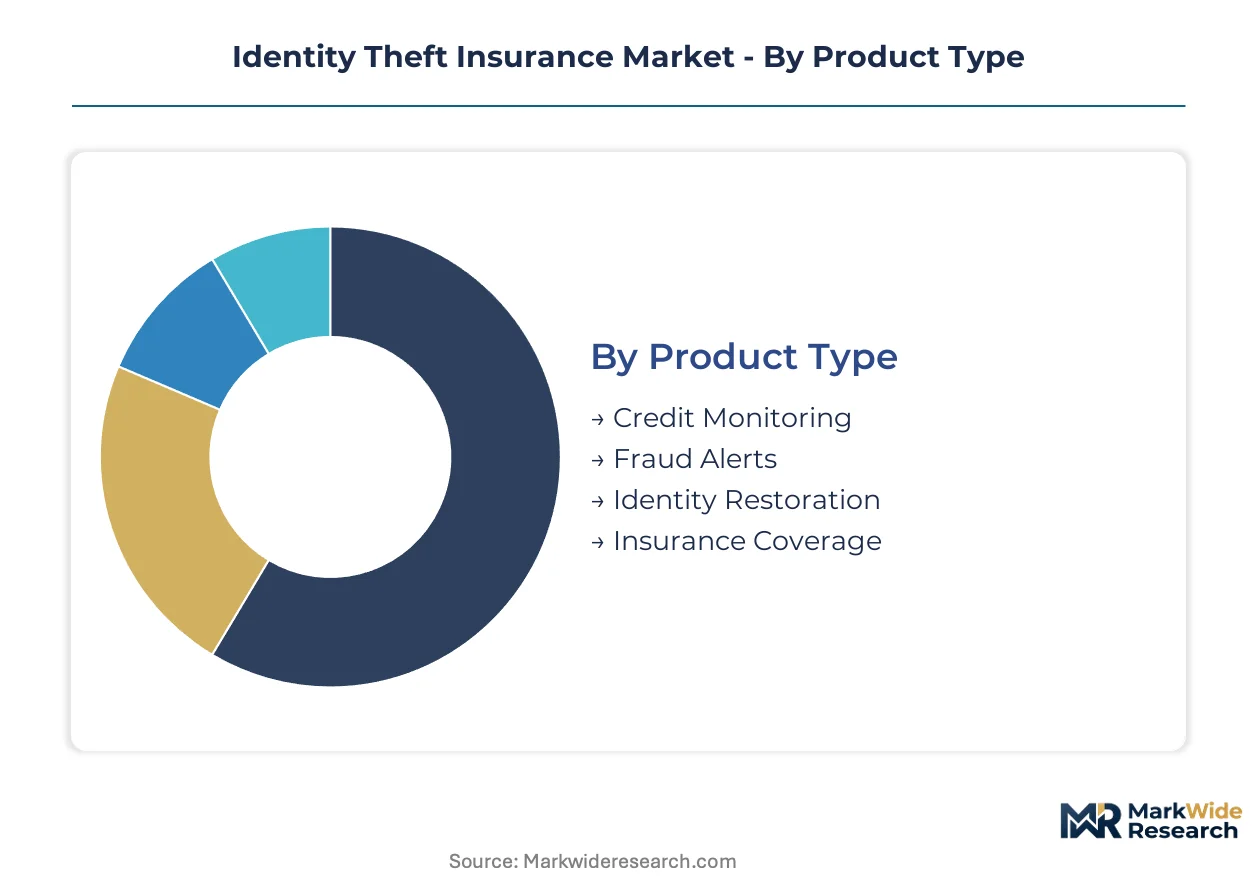
Identity theft insurance segments fragment across product architecture, buyer sophistication, and service delivery models. Channel economics and regulatory exposure determine which segments concentrate margin versus volume.
Product Type:
Credit Monitoring and Fraud Alerts flow predominantly through financial institution partnerships, while Insurance Coverage and Identity Restoration attach more heavily to broker-sold commercial policies.
- Credit Monitoring:Continuous surveillance of credit bureau files detects unauthorized account openings and inquiry spikes. Demand clusters among US consumers in states with stringent breach notification statutes where employers sponsor enrollment as compliance infrastructure.
- Insurance Coverage:Explicit loss reimbursement for direct financial damages, legal fees, and remediation costs with benefit limits spanning ten thousand to one million dollars. Enterprise procurement concentrates margin pools through multi-year master policies driven by GDPR and EU AI Act compliance burdens.
- Fraud Alerts:Automated notification systems flag suspicious transactions across financial accounts. Banks embed these as free retail banking features.
- Identity Restoration:Case-managed recovery services handle fraud affidavit filing and creditor negotiations. HIPAA breach response mandates in the healthcare sector create adjacent demand for these riders on professional liability coverage.
By volume, Credit Monitoring leads. By growth pace, Insurance Coverage is climbing the fastest.
Customer Type:
Cost tiers separate this category: Individuals and Families purchase through low-touch digital channels, while Businesses and Enterprises negotiate bespoke terms through broker relationships.
- Individuals:Single-policyholders seeking personal financial protection against synthetic identity fraud and account takeover. US state-level variation in breach notification laws drives employer-sponsored enrollment as the dominant acquisition path.
- Enterprises:Large organizations procuring workforce-wide master policies with integrated dark-web monitoring. EU Digital Operational Resilience Act implementation timelines reshape coverage definitions and trigger new exclusion language for financial entities.
- Families:Multi-member household coverage extending protection to dependents. Benefits administrators increasingly attach these plans to core medical offerings.
- Businesses:Small and mid-sized entities purchasing standalone policies or endorsements to commercial packages. FCC data breach notification rules for telecommunications carriers expand the insured population base in that sector.
By absolute policy count, Individuals dominate. By premium per contract, Enterprises command the steepest expansion trajectory.
Service Type:
Application maturity divides this category: Prevention and Monitoring Services represent standardized technology platforms, while Consulting and Recovery Services require specialized operational infrastructure.
- Monitoring Services:Real-time dark-web surveillance for credential exposure and identity theft precursors. Machine-learning-driven fraud pattern recognition displaces rule-based transaction monitoring at twelve-to-eighteen-month refresh cycles among large self-insured employers.
- Recovery Services:Post-incident case management including identity restoration and legal support. Capacity constraints in fraud affidavit filing workflows scale unevenly with policy volume growth.
- Prevention Services:Proactive tools including credit freezes and security freezes. These embed at low marginal cost into consumer security software subscription bundling.
- Consulting:Advisory engagements for breach response planning and regulatory compliance. HIPAA obligations for healthcare sector breach response create specialized demand among medical practice groups.
By deployment scale, Monitoring Services leads. By margin structure, Recovery Services gains share fastest.
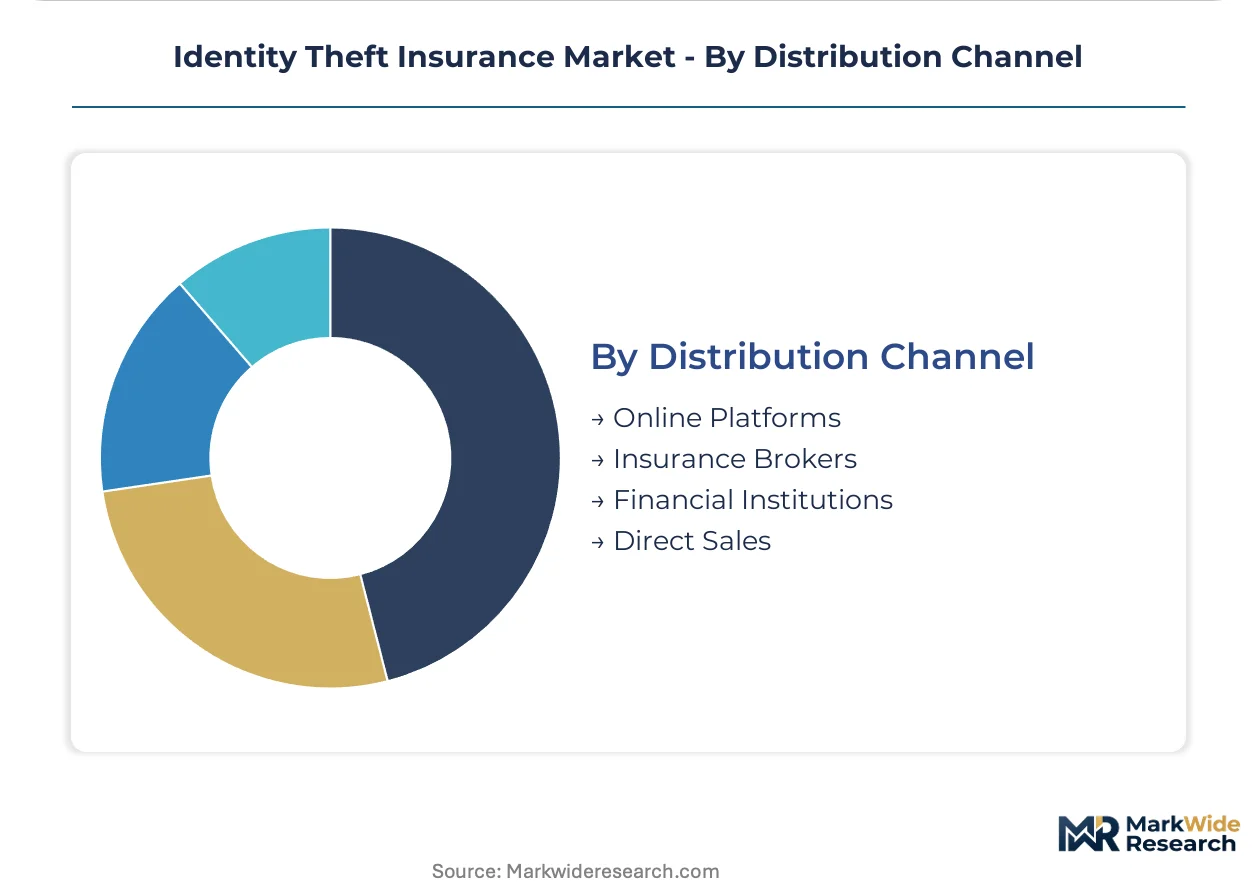
Distribution Channel:
Supply concentration shapes this category: Financial Institutions and Insurance Brokers control commercial placement, while Online Platforms and Direct Sales serve retail velocity.
- Financial Institutions:Banks and credit unions embedding identity protection into retail banking relationships and credit card offerings. Gen Digital leverages consumer security software heritage to anchor subscription bundling models here.
- Insurance Brokers:Independent agents and wholesale brokers placing commercial coverage with policy attachment rates that outperform direct-to-consumer benchmarks. Allstate competes through agency channel control in this segment.
- Online Platforms:Digital-native enrollment through employer benefits portals and direct-to-consumer websites. Benefits administrators unbundle identity protection from packaged voluntary offerings here.
- Direct Sales:Carrier-controlled acquisition without intermediary involvement. State-level rate filing friction fragments product standardization and raises compliance overhead in this channel.
By policy volume, Financial Institutions lead. By growth pace, Online Platforms is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Employer-sponsored enrollment dominates in the United States where breach notification statutes vary by state, while European corporations procure bundled identity protection under GDPR and EU AI Act mandates. This consumption-mix differential reflects regulatory fragmentation versus harmonized compliance frameworks.
United States
State-level variation in breach notification laws drives employer-sponsored enrollment as the dominant acquisition path. HIPAA obligations for healthcare sector breach response create adjacent demand for identity restoration riders among medical practice groups. The Greater Boston cluster concentrates insurtech innovation for real-time credential monitoring platforms.
Germany
EU AI Act compliance burdens for automated decision-making systems processing personal identifiers accelerate bundled policy procurement. The country's national data protection regulator enforces GDPR cross-border data handling standards that reshape policy portability clauses. The Frankfurt-Rhine-Main financial cluster anchors enterprise master policy negotiations for multinational workforces.
United Kingdom
Post-Brexit regulatory divergence creates complexity for carriers designing coverage for US-UK-Germany employee populations. The Information Commissioner's Office mandates explicit consent mechanisms for personal data transfers. London's insurance broker ecosystem concentrates placement activity for commercial identity protection coverage.
Canada
Financial institution partnerships dominate distribution as banks embed identity protection into retail banking relationships. Health Canada breach response guidelines for healthcare sector data incidents parallel HIPAA-driven demand patterns. The Toronto-Waterloo corridor hosts dark-web surveillance technology development for employer benefit platforms.
France
CNIL enforcement of GDPR standards shapes product design for multinational corporate clients with French operations. The EU Digital Operational Resilience Act implementation timeline triggers new exclusion language for financial entities. The Paris-La Défense business district concentrates enterprise procurement decision-making for workforce-wide master policies.
Identity Theft Insurance Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the market structure consolidating around cybersecurity heritage players and traditional carriers with agency channel control. Strategic archetypes include consumer security software bundlers, agency-driven personal lines insurers, and credit bureau data monetizers. Competitive moves center on subscription bundling at low marginal cost and dark-web surveillance technology integration into employer benefit platforms.
Among cybersecurity-heritage bundlers, Gen Digital leverages its consumer security software background to anchor subscription models that embed identity coverage at low marginal cost. Aura occupies a comparable position within the digital-native protection tier. Allstate represents the agency-channel control archetype, sustaining agent-driven policy attachment rates through traditional insurance distribution infrastructure.
| Leading Market Players |
|---|
| Gen Digital |
| Aura |
| Allstate |
| Experian |
| Equifax |
| Nationwide Mutual Insurance Company |
| IdentityForce |
| Zander Insurance |
| Chubb |
| Others |
Supply Flow & Price Mechanics
Platform scale economies in dark-web surveillance technology compress marginal delivery costs for identity monitoring services, concentrating supply power among cybersecurity-heritage bundlers while establishing price floors that legacy carriers struggle to match without operational restructuring.
Pricing Analysis
Long-term master policy contracts dominate enterprise procurement, with multi-year offtake structures anchoring premium stability for carriers serving large employers under GDPR and EU AI Act mandates. Price differentiation rests on restoration service depth and real-time monitoring integration, with self-insured employers showing least sensitivity due to compliance infrastructure framing, while small businesses face acute pressure from state-level rate filing friction and capital requirements.
Supply Chain Analysis
Just-in-time credential scanning infrastructure dominates technology delivery, with strategic stockpiling limited to specialized identity restoration case management capacity. Supply concentrates in the United States, Ireland, and India—drawing from cybersecurity engineering talent pools, cloud compute infrastructure, and back-office fraud affidavit processing operations. Single-source vulnerability in certified cybersecurity actuarial talent constrains product development velocity. Distribution runs through financial institution partnerships and employer benefits platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from consumer security software bundlers embedding identity coverage at near-zero marginal cost, eroding traditional policy attachment economics.
For Market Incumbents: Secure exclusive agency channel control to sustain policy attachment rates that outperform direct-to-consumer benchmarks. Invest in machine-learning fraud pattern recognition to collapse per-incident restoration costs below service delivery benchmarks, defending margin position against Gen Digital and Aura subscription models.
For New Entrants and Emerging Players: EU Digital Operational Resilience Act certification fast-tracks open white-space for financial entity coverage with territory-specific sub-limits. Target tax refund theft indemnity riders for individual policyholders in US states with stringent breach notification statutes, leveraging seasonal filing vulnerabilities through digital-native enrollment platforms.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among employer-sponsored enrollment platforms with integrated dark-web monitoring. Long-term viability favors carriers with cybersecurity heritage and cloud-native infrastructure. Watch synthetic identity fraud detection accuracy as the inflection indicator—material improvement would unlock benefit limit expansion and margin recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Dark-Web Surveillance Integration | Real-time credential monitoring embedded into employer benefit platforms compresses service delivery costs. |
| Agency Channel Expansion | Independent agent networks sustain policy attachment rates above direct-to-consumer benchmarks for personal lines carriers. |
| Machine-Learning Fraud Recognition | Automated pattern detection displaces manual case review and collapses per-incident restoration expenses. |
| EU Compliance Certification | GDPR and EU AI Act alignment unlocks bundled procurement from multinational enterprise workforces. |
| Identity Restoration Capacity Buildout | Specialized case management infrastructure scales unevenly with policy volume, creating bottleneck risk. |
Methodological Framework
Desk research of regulatory filings, insurance commissioner rate databases, and cybersecurity incident reports preceded structured interviews with chief underwriting officers, benefits administrators, identity restoration service operators, and dark-web surveillance technology vendors. Primary fieldwork with enterprise risk managers and HR benefits directors combined with secondary validation against FCC rulemakings, GDPR implementation guidance, and NAIC market conduct examinations. Bottom-up policy count estimates triangulated against top-down premium volume assessments.
Variance decomposition across product type, customer sophistication tier, service delivery model, and distribution channel shaped the analytical framework over the projection horizon. CAGRs derived from fitted growth curves applied to baseline premium volumes, with explicit modeling of EU AI Act implementation timelines and US state legislative fragmentation as demand accelerants. Synthetic identity fraud loss ratios and certified actuarial talent availability served as industry-specific forecast sensitivity inputs.
Decision-makers should treat outputs as directional under stable regulatory enforcement and breach notification statute proliferation; material deviation would warrant model refresh. Revision becomes warranted when synthetic identity fraud detection accuracy crosses thresholds enabling benefit limit expansion, or when EU Digital Operational Resilience Act implementation timelines accelerate coverage definition changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Europe Travel Insurance Market
Insurance
South Africa Property and Casualty Insurance Market
Insurance
Europe Extended Warranty Market
Insurance
United States Insurance Brokerage Market
Insurance
Saudi Arabia Health & Medical Insurance Market
Insurance
Insurance Protection Products Market
Insurance
France Property and Casualty Insurance Market
Insurance
Medical Claims Processing Services Market
Insurance
Event Insurance Market
Insurance
Slovenia Property and Casualty Insurance Market
Insurance
Internet of Things Insurance Market
Insurance
Europe Health Insurance Market
Insurance
Vietnam Private Health Insurance Market
Insurance
New Zealand Property and Casualty Insurance Market
Insurance
India Travel Insurance Market
Insurance
Europe Online Insurance Market