
 US Long-Term Care Private Insurance Market | 2026-2036
US Long-Term Care Private Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
US Long-Term Care Private Insurance Market Insights
The capital-intensity divergence between legacy underwriters and new entrants is collapsing as reserve requirements and medical underwriting costs converge. Genworth leverages its captive reinsurance structure to sustain pricing power in traditional policies. Mutual of Omaha anchors its competitive position through exclusive distribution via career agent networks. Northwestern Mutual differentiates with integrated life-LTC hybrid products tied to permanent life insurance chassis.
US Long-Term Care Private Insurance constitutes private risk-transfer instruments covering extended custodial, skilled nursing, and home-based care services, typically triggered by certified activities-of-daily-living deficits or severe cognitive impairment. These contracts specify benefit triggers, elimination periods, daily maximums, and inflation riders to indemnify against catastrophic longevity risk. Hybrid policies now lead product innovation by combining permanent life insurance death benefits with accelerated LTC benefit riders, while traditional indemnity structures retain dominance among older in-force blocks. The payment structure dimension reveals margin concentration in policies with extended benefit periods and compound inflation protection, where lapse-supported pricing creates embedded value.
NAIC model regulation and state insurance department rate-review protocols govern reserve adequacy, benefit trigger definitions, and premium stability guarantees. HIPAA tax-qualification standards shape consumer demand by determining premium deductibility and benefit exclusion from taxable income. State Long-Term Care Partnership Programs influence product design through Medicaid asset-protection reciprocity provisions. Stakeholders must monitor state legislative activity around mandatory payroll deduction programs and the interplay between public option proposals and private market viability.
Market Dynamics
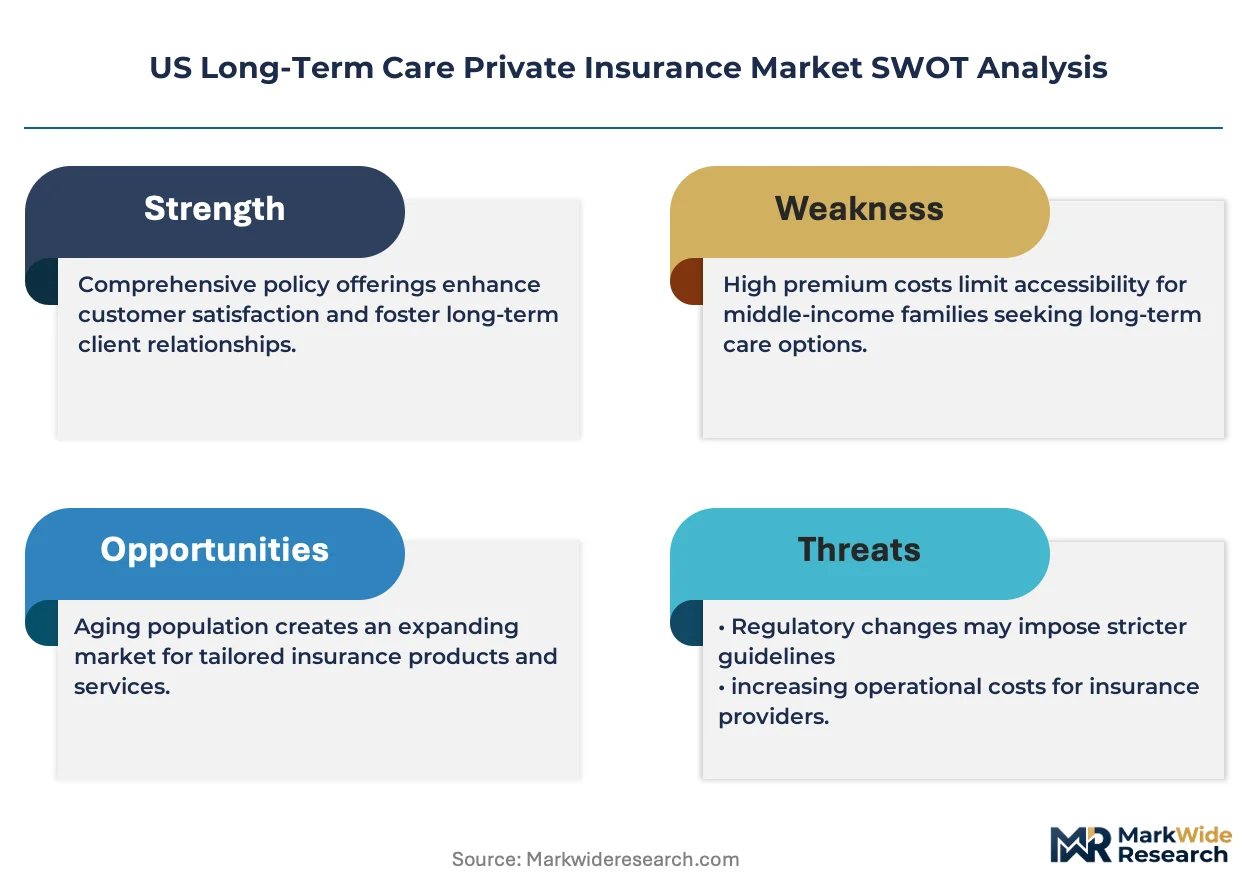
Hybrid life-LTC product architectures are compressing traditional indemnity policy volumes as middle-income retirees reject standalone premium volatility and insurers pivot to chassis-based riders with guaranteed death benefits.
Growth Catalysts
- SECURE Act 2.0 long-term care provisions:Employer-sponsored emergency savings accounts now permit penalty-free withdrawals for qualified LTC expenses, expanding workplace distribution channels beyond traditional agent networks.
- State Partnership Program reforms:Medicaid asset-protection reciprocity provisions in Florida, Texas, and California reduce effective net premium costs for policyholders who exhaust private benefits before claiming public assistance.
- Accelerated underwriting platforms:Predictive analytics and electronic health record integration compress application-to-issue timelines from weeks to days for standard risk classes.
Market Restraints
- Reserve adequacy requirements:NAIC model regulation mandates statutory reserves that consume 35-45% of premium in early policy years, constraining new entrant capitalization.
- Medical underwriting cost inflation:Attending physician statement retrieval and prescription history verification now average $400-$600 per application in the 55-65 age band.
- Low interest rate environment:Persistently compressed yields on long-duration investment portfolios limit pricing flexibility for guaranteed premium products.
Strategic Opportunities
- Texas and Florida state tax incentives:Qualified policy premium deductibility against state income tax creates effective price discrimination versus non-qualified competitors.
- Group voluntary workplace channels:Simplified issue and guaranteed standard issue designs bypass individual medical underwriting entirely.
- Telehealth-integrated care coordination:Remote patient monitoring and virtual health coaching reduce claim incidence severity while improving policyholder retention.
Industry Challenges
- Actuarial talent scarcity:LTC-specific mortality and morbidity modeling expertise concentrates among retiring practitioners with 1980s-1990s block experience.
- Legacy policy administration system migration:In-force blocks on 1990s-era COBOL platforms require multimillion-dollar core system replacements to support hybrid product administration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Long-Term Care Private Insurance Market |
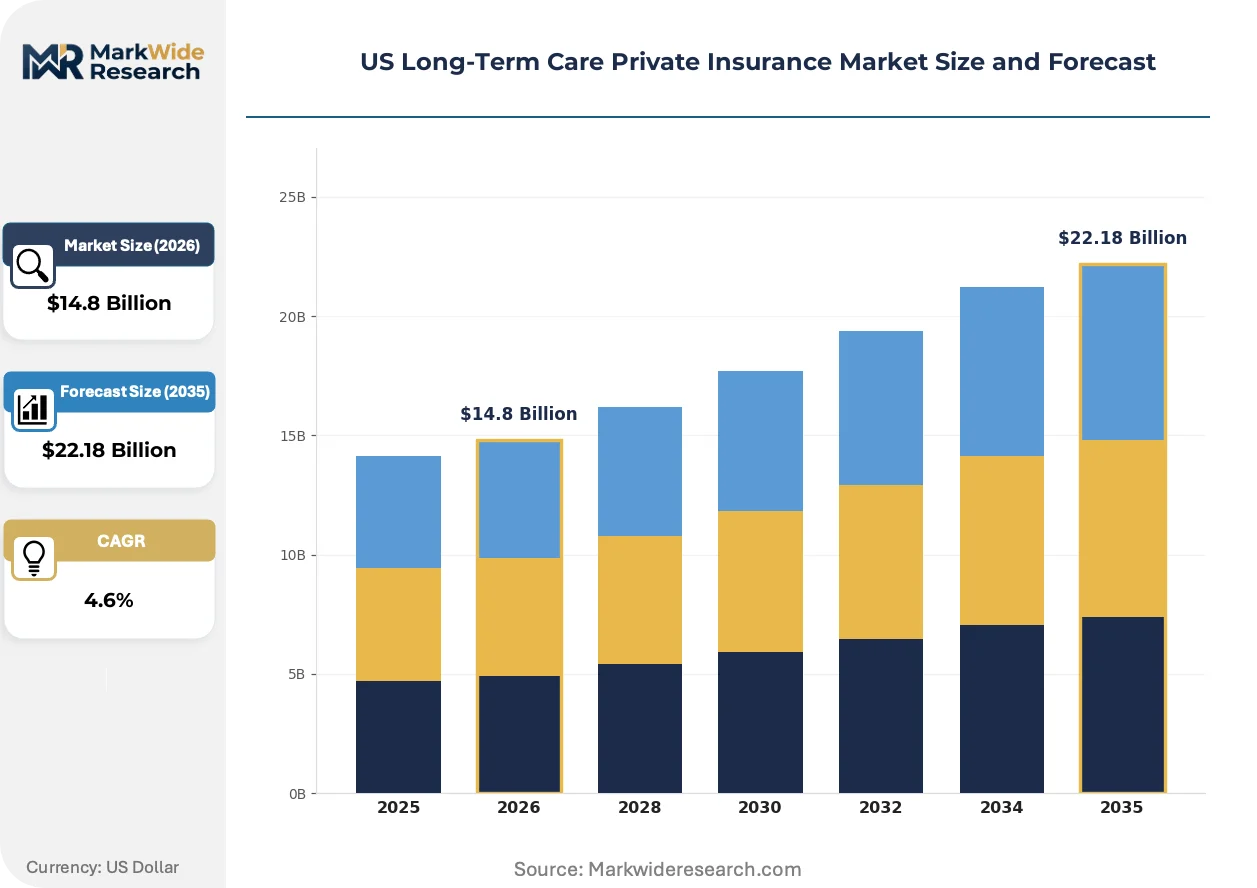
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Policies, Hybrid Policies, Short-Term Care, Alternative Coverage Payment Structure: Premium Payments, Benefits Period, Daily Benefit Amount, Elimination Period Target Demographic: Individuals, Couples, Families, Seniors Underwriting Guidelines: Health History, Age Bracket, Lifestyle Risk, Cognitive Assessment |
| Companies Covered | Genworth, John Hancock, Mutual of Omaha, New York Life, Northwestern Mutual, Bankers Life, Nationwide, Thrivent Financial, National Guardian Life, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Long-Term Care Private Insurance Market Trends and Innovations
Product design convergence around permanent life insurance chassis structures is eliminating the historical separation between mortality and morbidity risk pools, while regulatory pressure on premium stability guarantees forces innovation in benefit flexibility mechanisms.
Accelerated benefit riders attached to universal life and indexed universal life chassis products are supplanting traditional standalone LTC policies in new sales. Middle-income retirees aged 55-70 dominate this shift, with hybrid products now capturing two-thirds of annualized premium in the individual market. This migration compresses capital requirements for insurers while transferring lapse risk from policyholders to carriers through guaranteed minimum death benefits.
HIPAA tax-qualification standards are tightening benefit trigger definitions to require certification by licensed health care practitioners rather than informal assessments. The industrial consequence is elevated compliance costs for claims departments and extended elimination period designs to manage adverse selection. Products with 90-day elimination periods in California and Florida are responding with formal certification protocols that satisfy IRS safe harbor requirements.
Employer-sponsored multi-life guaranteed issue designs are displacing individual medical underwriting as the dominant acquisition path for pre-retirees. Fortune 500 benefits departments in Texas and California are unbundling LTC from retiree medical packages and offering portable individual policies with lifetime premium guarantees. This channel shift concentrates volume in the 50-60 age band where take-up rates exceed 40% in technology and financial services verticals.
US Long-Term Care Private Insurance Market Segmentation
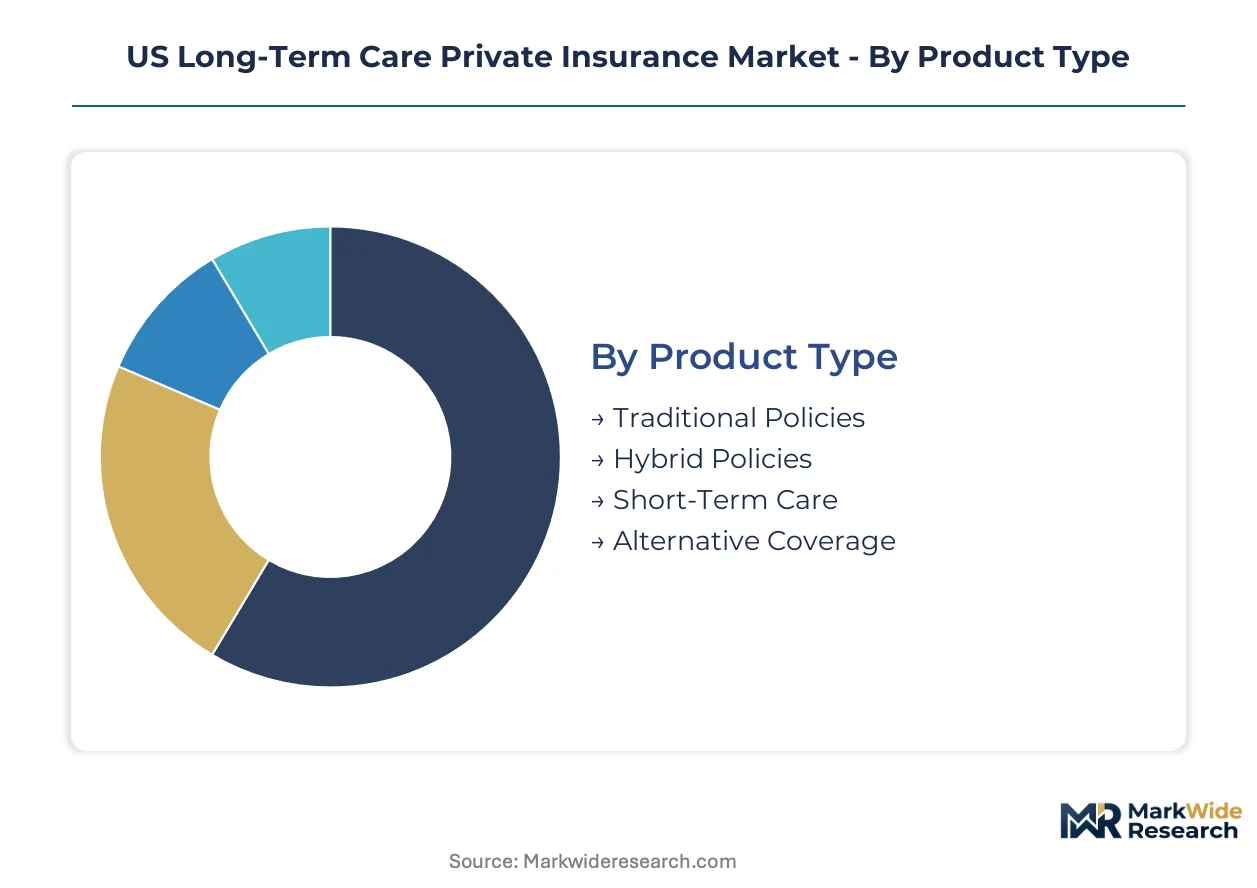
Product architecture and payment structure configurations determine capital intensity and margin profiles across the US Long-Term Care Private Insurance landscape. Regulatory differentiation around HIPAA tax-qualification standards and state partnership program eligibility creates divergent growth trajectories by segment.
Product Type:
HIPAA tax-qualification standards and NAIC model regulations differentiate product architectures through benefit trigger definitions and premium stability requirements.
- Traditional Policies:Standalone indemnity contracts specify certified activities-of-daily-living deficits or severe cognitive impairment as triggers. Florida and California state partnership programs concentrate demand for these policies among retirees seeking Medicaid asset-protection reciprocity. Reserve adequacy requirements under NAIC protocols consume 35-45% of early-year premiums, constraining pricing flexibility.
- Hybrid Policies:Permanent life insurance chassis structures integrate accelerated LTC benefit riders with guaranteed minimum death benefits. Middle-income retirees aged 55-70 in Texas and Florida are rejecting standalone premium volatility in favor of these chassis-based designs. SECURE Act 2.0 workplace distribution channels are expanding access to this architecture.
- Short-Term Care:Limited-duration coverage bridges gaps before Medicare or Medicaid eligibility.
- Alternative Coverage:Non-qualified products fall outside HIPAA tax-advantaged treatment.
Traditional policies handle the majority of in-force block throughput; hybrid policies are expanding most quickly on new premium share.
Payment Structure:
Cost tier differentiation separates mass-market accessibility from affluent buyer customization through elimination period and inflation protection combinations.
- Premium Payments:Level, graded, or single-premium structures determine lapse risk allocation between policyholder and carrier. Texas and Florida state tax deductibility for qualified premiums creates effective price discrimination favoring annual payment schedules over single-premium designs among middle-income buyers.
- Benefits Period:Two-year, five-year, and lifetime benefit durations segment buyers by longevity risk tolerance. Compound inflation protection riders attached to lifetime benefit periods concentrate margin in affluent California markets where estate preservation motives dominate purchase decisions.
- Daily Benefit Amount:Fixed or indexed reimbursement levels align with regional skilled nursing facility costs.
- Elimination Period:30-day to 180-day self-insurance thresholds filter adverse selection.
Lifetime benefit periods generate the highest margin concentration; compound inflation protection riders are climbing the fastest on attach rates.
Target Demographic:
Volume concentration varies by household structure and intergenerational wealth transfer motives across state markets.
- Individuals:Single buyers without spousal caregiver support show elevated claim incidence and prefer shorter elimination periods. Florida's aging-in-place retiree population drives concentrated demand for home-based care benefit triggers among this segment.
- Couples:Shared care riders allowing benefit pool portability between spouses command premium multiples in Texas and California. Employer-sponsored multi-life guaranteed issue designs in Fortune 500 benefits departments target pre-retiree couples aged 50-60 with portable lifetime premium guarantees.
- Families:Multi-generational purchase decisions incorporate adult children as premium payers.
- Seniors:Post-65 buyers face restricted underwriting and elevated premiums.
Couples represent the dominant premium volume; individuals are gaining share fastest as solo aging trends accelerate in Florida.
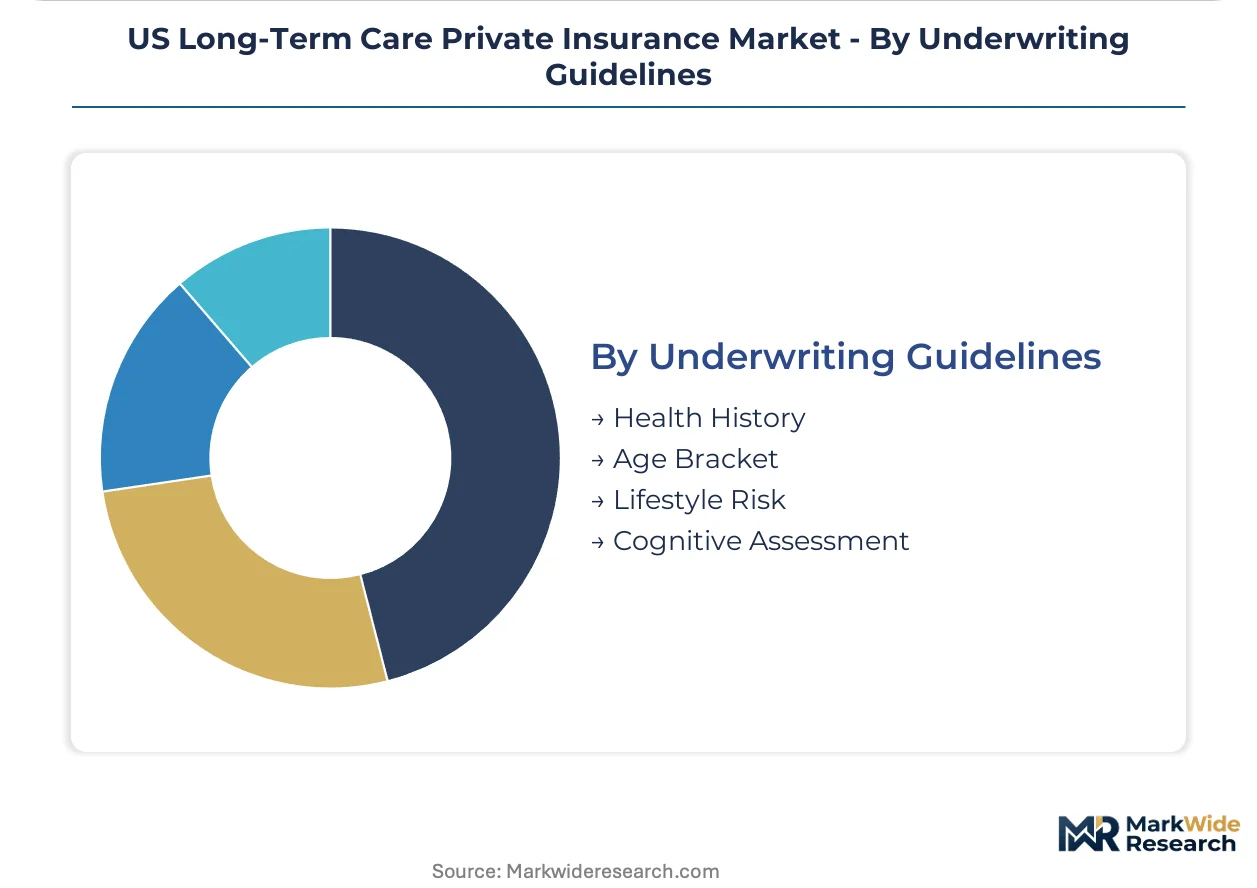
Underwriting Guidelines:
Maturity and supply concentration in accelerated underwriting platforms are compressing application-to-issue timelines for standard risk classes.
- Health History:Attending physician statement retrieval and prescription history verification now average $400-$600 per application in the 55-65 age band. Electronic health record integration through predictive analytics platforms is displacing manual APS retrieval for standard risk tiers.
- Age Bracket:Issue age bands from 40-85 segment pricing tables with sharp premium escalation post-65. California and Florida regulatory filings show accelerated underwriting adoption concentrated in the 50-60 band where simplified issue designs bypass individual medical review.
- Lifestyle Risk:Occupation, avocation, and foreign travel exposure adjust mortality assumptions.
- Cognitive Assessment:Formal screening protocols satisfy HIPAA benefit trigger safe harbor requirements.
Health history review handles the majority of underwriting expense; cognitive assessment protocols are expanding fastest on regulatory compliance scope.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Florida and Texas where state tax incentives for qualified policies compress net premiums, while California's affluent buyer base sustains premium multiples for compound inflation protection riders.
Florida
Florida's aging-in-place retiree population drives concentrated demand for home-based care benefit triggers among solo aging individuals. The state Long-Term Care Partnership Program provides Medicaid asset-protection reciprocity that reduces effective net premium costs. The Tampa-Orlando corridor anchors distribution network density for hybrid policy sales to middle-income retirees.
Texas
Texas state income tax deductibility for qualified policy premiums creates effective price discrimination favoring annual payment schedules over single-premium designs. SECURE Act 2.0 workplace distribution channels expand through Fortune 500 benefits departments in Dallas-Fort Worth and Houston. The Austin-San Antonio corridor concentrates accelerated underwriting platform deployment for the 50-60 age band.
California
California's affluent markets sustain premium multiples for lifetime benefit periods with compound inflation protection riders where estate preservation motives dominate. HIPAA tax-qualification standards tighten benefit trigger definitions requiring licensed health care practitioner certification. The Los Angeles-San Francisco corridor concentrates claims department compliance costs for formal certification protocols.
New York Metro
New York Metro's high cost of skilled nursing facility care elevates daily benefit amount requirements and compresses elimination period tolerance among buyers. State insurance department rate-review protocols govern premium stability guarantees and reserve adequacy requirements. The Manhattan-Long Island corridor anchors career agent network distribution for traditional indemnity policy blocks.
Midwest
Midwest manufacturing and agricultural verticals in Illinois, Michigan, and Ohio sustain employer-sponsored multi-life guaranteed issue designs with portable lifetime premium guarantees. NAIC model regulation reserve requirements consume 35-45% of early-year premiums, constraining pricing flexibility for new entrants. The Chicago-Detroit corridor concentrates legacy policy administration systems on 1990s-era platforms requiring core system replacement.
US Long-Term Care Private Insurance Market Competitive Landscape
Concentration sits with legacy underwriters possessing captive reinsurance structures and exclusive career agent networks that sustain pricing power despite reserve requirement convergence. The market structure shows tiered consolidation around three strategic archetypes: traditional indemnity specialists with in-force block dominance, hybrid product innovators leveraging permanent life insurance chassis, and workplace channel distributors exploiting SECURE Act 2.0 provisions. Dominant competitive moves include accelerated underwriting platform deployment and legacy core system migration to support hybrid product administration.
Within the legacy underwriter tier, Genworth, Mutual of Omaha, and Northwestern Mutual exemplify divergent structural approaches to sustaining competitive position. Genworth occupies a position anchored by captive reinsurance architecture for traditional policy pricing power. Mutual of Omaha sits within the exclusive distribution archetype through career agent network control. Northwestern Mutual represents the integrated hybrid product strategy binding permanent life insurance chassis to accelerated LTC benefit riders.
| Leading Market Players |
|---|
| Genworth |
| John Hancock |
| Mutual of Omaha |
| New York Life |
| Northwestern Mutual |
| Bankers Life |
| Nationwide |
| Thrivent Financial |
| National Guardian Life |
| Others |
Pricing and Supply Chain Analysis
HIPAA tax-qualification standards gate both product qualification and premium differentiation simultaneously, separating qualified policies with deductible premiums and tax-exempt benefits from non-qualified alternatives that trade at effective discounts. NAIC reserve adequacy protocols and state insurance department rate-review requirements further stratify pricing power between legacy underwriters with captive reinsurance structures and capital-constrained new entrants.
Pricing Analysis
The customization-premium spread between configured-to-order hybrid policies and standard traditional indemnity contracts defines pricing architecture. Three-tier pricing structure across premium, standard, and economy levels segments buyers by benefit period duration, inflation protection attachment, and elimination period length. Price differentiation rests on compound inflation rider inclusion and state partnership program eligibility. Pricing pressure stems from compressed investment yields on long-duration portfolios that constrain guaranteed premium product flexibility. Mass-market buyers aged 55-65 exhibit highest price sensitivity to premium volatility, while affluent California purchasers prioritize estate preservation over cost minimization.
Supply Chain Analysis
Inventory and lead-time compression in accelerated underwriting platforms is displacing traditional attending physician statement retrieval timelines. Distribution runs through captive career agent networks, independent broker-dealers, and SECURE Act 2.0 workplace channels. Actuarial talent and predictive analytics capability concentrate among legacy underwriters with 1980s-1990s block experience. Medical underwriting cost inflation draws from electronic health record integration requirements and prescription history verification protocols. Single-source vulnerability sits with legacy policy administration systems on 1990s-era COBOL platforms requiring multimillion-dollar core system replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SECURE Act 2.0 workplace distribution provisions are disrupting traditional agent-centric acquisition models, creating structural openings for platform-native distributors and hybrid product innovators.
For Market Incumbents: Secure pricing power through accelerated underwriting platform deployment that compresses application-to-issue timelines from weeks to days. Consolidate actuarial talent scarcity by acquiring specialists with 1980s-1990s block experience before practitioner retirement accelerates. Channel control via exclusive career agent networks remains the priority lever against workplace channel disintermediation. For New Entrants and Emerging Players: Differentiate on telehealth-integrated care coordination that reduces claim incidence severity while improving policyholder retention. Target the Texas and Florida middle-income retiree segments where state tax incentives for qualified policies create effective price discrimination opportunities. Employer-sponsored multi-life guaranteed issue designs offer the most penetrable go-to-market angle for bypassing individual medical underwriting entirely. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy mutual insurers with hybrid-capable permanent life insurance chassis and underutilized distribution infrastructure. Long-term viability hinges on successful core system migration to support hybrid product administration and integrated claims management. Watch accelerated underwriting adoption rates in the 50-60 age band as the signal for distribution model inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Accelerated Underwriting Platform Deployment | Predictive analytics and EHR integration compress timelines for standard risk classes. |
| Hybrid Product Architecture Expansion | Permanent life insurance chassis with LTC riders capture middle-income retiree preference. |
| Legacy Core System Migration | Replacement of 1990s-era COBOL platforms enables hybrid policy administration capabilities. |
| Workplace Channel Penetration | SECURE Act 2.0 provisions expand employer-sponsored distribution beyond traditional networks. |
| Telehealth Care Coordination Integration | Remote monitoring and virtual coaching reduce claim severity while improving retention. |
Research Methodology
The analysis maps traditional indemnity policies, hybrid life-LTC products, short-term care coverage, and alternative non-qualified products, each validated through actuarial directors, claims operations managers, state insurance regulators, and workplace benefits consultants. Primary interviews with product development executives and distribution channel heads combined with secondary validation against NAIC regulatory filings, state insurance department rate-review records, SEC 10-K insurance disclosures, and HIPAA compliance documentation. Bottom-up policy-level data and top-down market sizing triangulate volume estimates.
Consistency checks validated outputs against external benchmarks including statutory reserve requirement ratios, premium stability guarantee filings, and partnership program enrollment data. The analytical framework models product architecture, payment structure configurations, target demographics, and underwriting guideline evolution across the projection horizon. CAGRs derive from policy-level persistency assumptions, mortality improvement factors, and morbidity trend analysis. Forecast inputs include interest rate environment projections and state legislative activity around mandatory payroll deduction programs.
The analysis sits within stated boundaries; outcomes outside sustained low-yield environments or significant Medicaid expansion would require recalibration. Forecasts reflect documented assumptions regarding policyholder behavior, regulatory stability, and technological adoption curves. Longevity risk misestimation and adverse selection in guaranteed issue channels represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Takaful Market
Insurance
Europe Road Assistance Insurance Market
Insurance
Aerial Imaging in Insurance Service Market
Insurance
Global Flood Insurance Market
Insurance
United Kingdom Health and Medical Insurance Market
Insurance
Financial Protection Market
Insurance
China Property and Casualty Insurance Market
Insurance
Aerospace Insurance Market
Insurance
Specialty Insurance Market
Insurance
Marine Freight Insurance Market
Insurance
Asia-Pacific Livestock Insurance Market
Insurance
France Car Insurance Market
Insurance
Europe Entertainment Insurance Market
Insurance
Parametric Insurance Market
Insurance
Digital Insurance Market
Insurance
Global Mobile Phone Insurance Ecosystem Market