
 France Liability Insurance Market | 2026-2036
France Liability Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
France Liability Insurance Market Insights
The French technology and professional services sector is repositioning liability coverage priorities as cyber exposure and director indemnity risks intensify. AXA France leverages its commercial lines infrastructure to dominate metropolitan corporate accounts. Allianz France anchors its position through specialized engineering and construction liability units. Macif competes aggressively in the mutualist segment, extending coverage to mid-sized cooperatives and regional enterprises.
France liability insurance encompasses contractual risk transfer instruments that indemnify policyholders against third-party claims for bodily injury, property damage, or financial loss arising from negligence, defective products, or professional errors. Policies incorporate claims-made or occurrence triggers, retroactive dates, and aggregate limits calibrated to sector-specific exposure profiles. Professional liability leads premium generation among coverage types, reflecting elevated litigation frequency against consultants, architects, and healthcare providers. The broker channel controls distribution of complex multi-line programmes for large corporations, while direct sales and online platforms gain traction among SMEs seeking standardized general liability contracts. Annual policy duration remains predominant, though multi-year structures emerge in construction and infrastructure sectors seeking rate certainty.
ACPR, the French prudential regulator, mandates solvency capital requirements and conduct standards that shape product design and pricing transparency across domestic underwriters. EU Green Deal disclosure obligations and CSRD reporting standards force corporations to evidence environmental liability coverage adequacy in annual filings. ANSM oversight of healthcare product safety generates parallel demand for product liability extensions among pharmaceutical distributors. Stakeholders must monitor how ACPR's anticipated climate stress-testing framework for insurers will recalibrate capital charges and premium adequacy across pollution and environmental impairment lines.
Market Dynamics
CSRD disclosure mandates are compressing procurement cycles for environmental liability coverage as French corporations scramble to evidence insurance adequacy in sustainability filings ahead of statutory deadlines.
Growth Catalysts
- CSRD Reporting Mandates:EU-wide sustainability disclosure rules force French corporations to document environmental liability coverage adequacy, accelerating policy purchases across construction and manufacturing verticals.
- Cyber Exposure Intensification:Technology and professional services firms in Île-de-France are expanding directors and officers coverage as ransomware litigation against corporate boards escalates.
- Healthcare Product Safety Oversight:ANSM enforcement actions against pharmaceutical distributors drive demand for product liability extensions with retroactive date provisions.
Market Restraints
- Capital Charge Volatility:ACPR's anticipated climate stress-testing framework threatens to recalibrate solvency requirements for pollution and environmental impairment lines, constraining capacity.
- Litigation Frequency Concentration:Professional liability claims against architects and healthcare providers cluster disproportionately in Paris courts, creating geographic loss-cost spikes.
- Long-Tail Reserve Uncertainty:Construction sector occurrence-trigger policies with multi-decade tail exposure strain actuarial modeling precision for domestic underwriters.
Strategic Opportunities
- Mutualist Segment Expansion:Mid-sized cooperatives in Auvergne-Rhône-Alpes and Occitanie remain underpenetrated relative to corporate headquarters concentration in Île-de-France.
- Parametric Climate Products:Convergence of satellite-based weather monitoring with automated claims settlement creates white space for drought and flood liability coverage in agricultural cooperatives.
- Online Platform Distribution:Direct digital sales channels gain traction among SMEs seeking standardized general liability contracts without broker intermediation.
Industry Challenges
- Actuarial Talent Scarcity:Climate risk modeling expertise remains concentrated among a handful of Paris-based actuarial consultancies, constraining product development velocity for regional insurers.
- Legacy System Integration:Mutual insurers with decades-old policy administration platforms struggle to embed real-time CSRD compliance reporting into client dashboards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Liability Insurance Market |
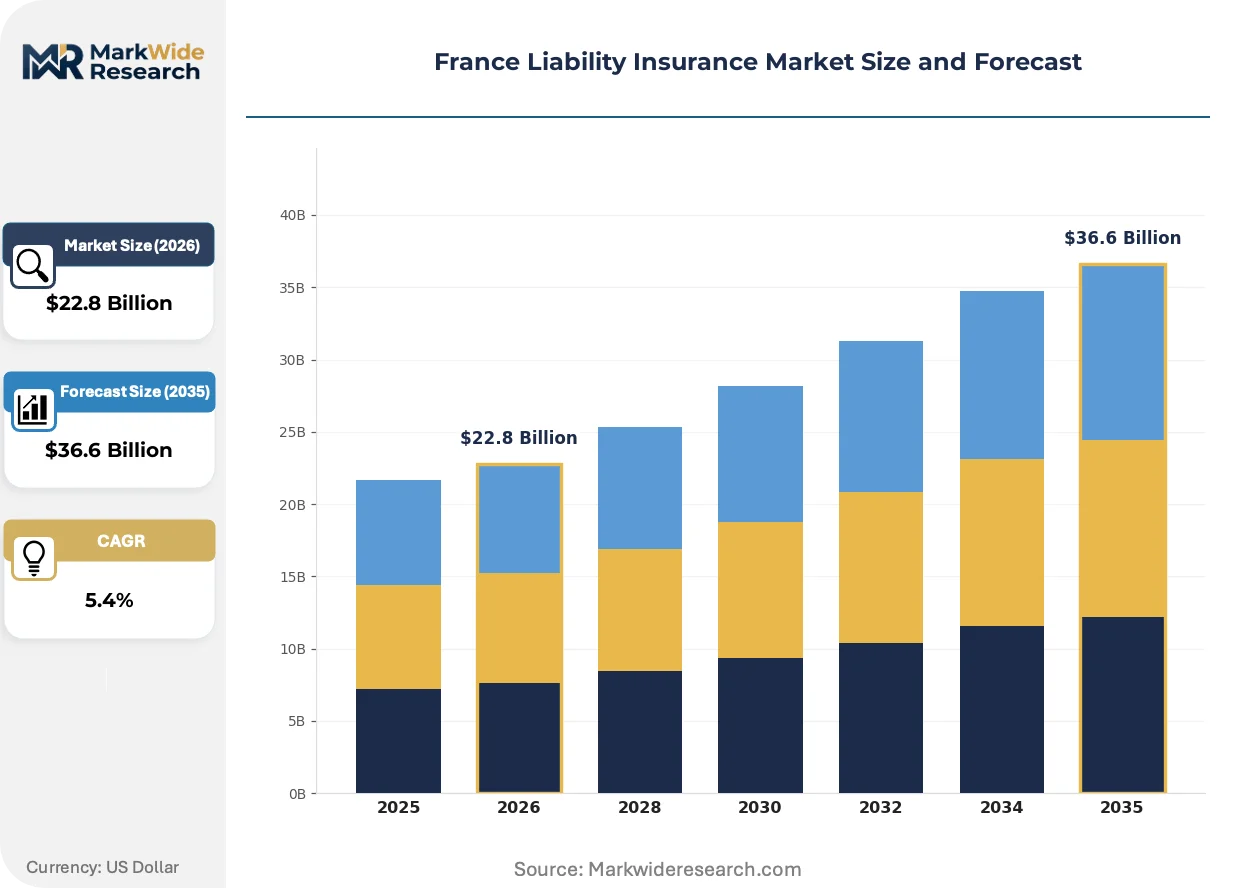
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $36.6 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Professional Liability, General Liability, Product Liability, Employers' Liability Client Type: SMEs, Large Corporations, Nonprofits, Public Sector Policy Duration: Annual, Multi-Year, Short-Term, Long-Term Distribution Channel: Brokers, Direct Sales, Online Platforms, Agents |
| Companies Covered | Allianz France, Macif, AXA France, CNP Assurances, Crédit Agricole Assurances, Covéa, Crédit Mutuel Assurances, Aéma Groupe, Groupama, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Liability Insurance Market Trends and Innovations
Artificial intelligence is compressing claims settlement timelines while embedded insurance models and climate risk quantification tools reshape how French corporations procure and manage liability protection.
Algorithmic claims triage is overtaking manual loss-adjustment workflows in property and casualty lines. AXA France and Allianz France have deployed natural language processing systems to parse bodily injury demand letters, reducing settlement negotiation cycles from weeks to days. This automation is compressing loss-adjustment expense ratios and enabling premium adequacy recalibration in high-frequency professional liability segments.
CSRD disclosure standards are mandating granular environmental liability coverage documentation in annual corporate sustainability reports. French construction firms must now evidence pollution impairment limits and retroactive date continuity to satisfy auditor scrutiny. Healthcare and pharmaceutical distributors face parallel pressure under ANSM product safety oversight to maintain product liability extensions with adequate aggregate limits.
Corporate risk managers are consolidating multi-line programmes under single-carrier arrangements to streamline CSRD compliance reporting. Broker channel dominance in complex corporate accounts is yielding to direct negotiation with insurers offering integrated cyber, D&O, and environmental liability packages. This concentration is most visible among CAC 40 constituents headquartered in La Défense and central Paris districts.
France Liability Insurance Market Segmentation
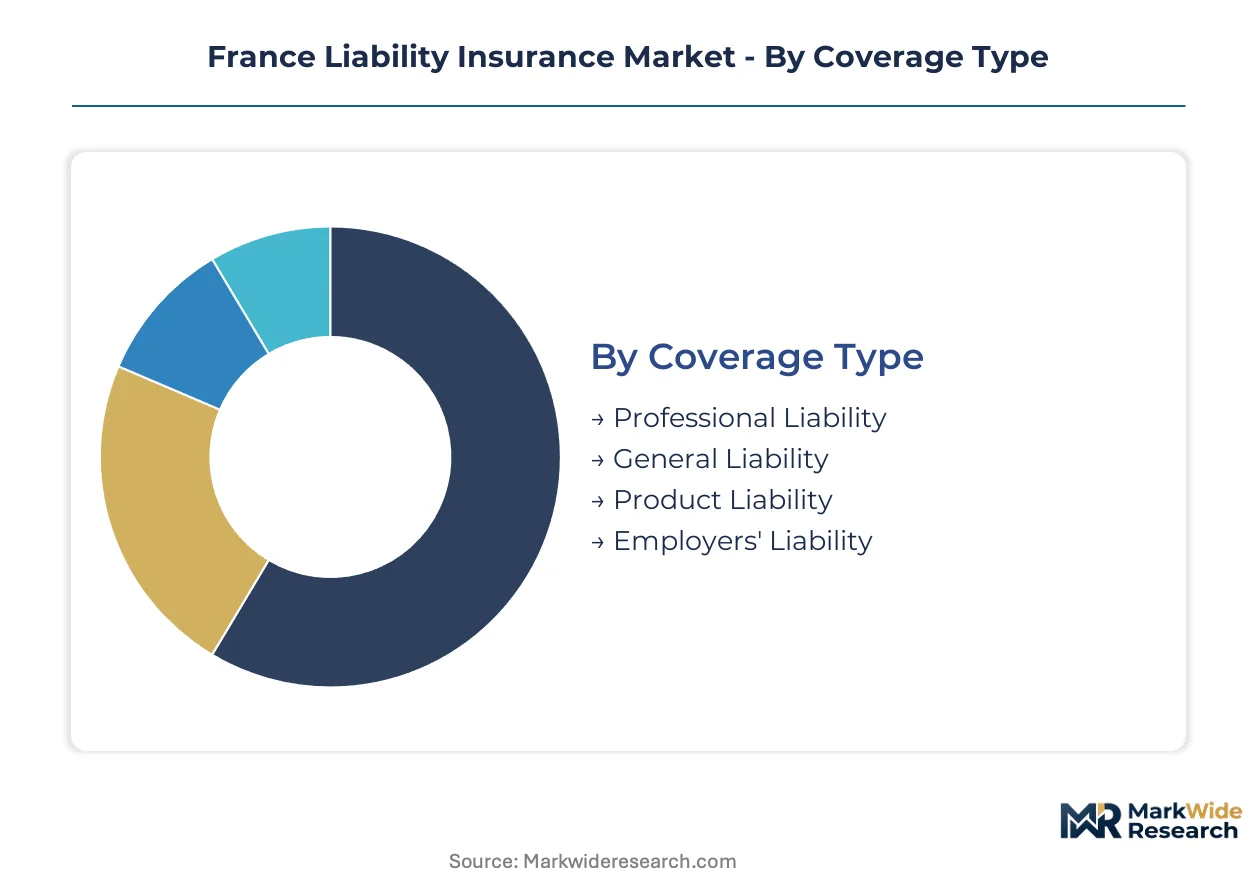
Segmentation in the France liability insurance market reveals how coverage design, client scale, and distribution economics create distinct competitive arenas. Underwriters calibrate capital deployment, pricing models, and service intensity differently across each dimension, shaping profitability profiles and market access strategies.
Coverage Type:
Professional liability operates as a standalone specialty line with dedicated underwriting teams and claims expertise, while general liability typically embeds within broader commercial packages.
- Professional Liability:Claims-made policies covering negligence, errors, and omissions against consultants, architects, and healthcare providers. Demand clusters among Île-de-France professional services firms facing elevated litigation frequency in Paris commercial courts. Premium adequacy depends on retroactive date continuity and aggregate limit structures.
- General Liability:Occurrence-triggered coverage for third-party bodily injury and property damage, often bundled with property and business interruption lines. SMEs in Auvergne-Rhône-Alpes manufacturing corridors purchase standardized contracts through direct channels.
- Product Liability:Extensions covering defective goods and downstream harm, critical for pharmaceutical distributors under ANSM enforcement pressure. Policies incorporate batch-specific retroactive dates and recall cost sublimits.
- Employers' Liability:Mandatory coverage for workplace injury claims, embedded within statutory social security contributions for most French enterprises. Standalone supplementation occurs in high-hazard construction and industrial sectors.
Volume placements concentrate in general liability; the faster expansion belongs to professional liability.
Client Type:
Premium economics diverge sharply between price-sensitive smaller accounts and complex corporate programmes requiring bespoke structuring.
- SMEs:Standardized coverage with limited customization, purchased through direct sales and online platforms. Occitanie agricultural cooperatives and Provence-Alpes-Côte d'Azur tourism operators drive regional premium pools.
- Large Corporations:Multi-line programmes with dedicated claims handling and captive participation options. CAC 40 constituents headquartered in La Défense negotiate integrated cyber, D&O, and environmental liability packages.
- Nonprofits:Volunteer liability and directors indemnity coverage with constrained premium budgets. Regional mutual insurers like Macif dominate this segment through cooperative membership structures.
- Public Sector:State guarantee-backed coverage for hospitals, municipalities, and transport authorities. Procurement follows centralized tender processes with extended placement timelines.
Revenue concentration sits with large corporations; nonprofits are climbing the fastest.
Policy Duration:
Construction sector rate certainty demands are stretching contract tenors beyond traditional annual cycles.
- Annual:Dominant structure for professional liability and general liability, enabling annual rate review and coverage adequacy reassessment. Renegotiation cycles align with fiscal year-ends.
- Multi-Year:Three-to-five year terms emerging in infrastructure and construction to lock pricing amid capital charge volatility. Grand Paris Express contractors seek cost predictability across decade-long project horizons.
- Short-Term:Event-specific coverage for exhibitions, construction phases, and project-based professional services. Premium density remains low relative to administrative burden.
- Long-Term:Decade-plus occurrence-trigger policies with extended reporting provisions for environmental impairment and asbestos exposure. Reserve uncertainty constrains underwriter appetite.
Annual placements retain volume dominance; multi-year structures are gaining share fastest.
Distribution Channel:
Channel economics determine service intensity, price transparency, and client retention mechanics across the client lifecycle.
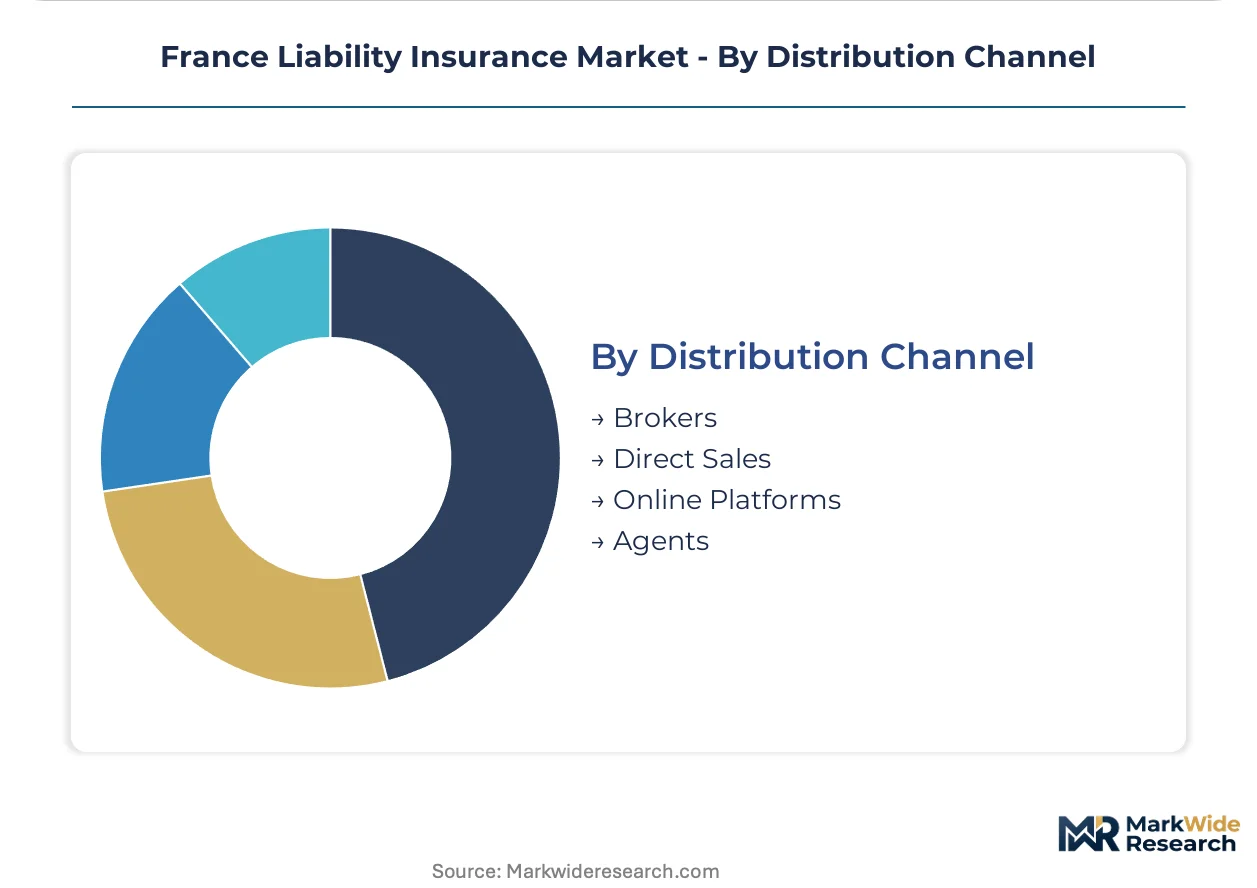
- Brokers:Control complex multi-line programmes for large corporations, providing coverage adequacy benchmarking and claims advocacy. Willis Towers Watson and Aon dominate CAC 40 account placements.
- Direct Sales:AXA France and Allianz France maintain captive salesforces for mid-market commercial accounts, capturing margin otherwise paid to intermediaries.
- Online Platforms:Automated quotation and policy issuance for standardized general liability, gaining traction among Normandy and Brittany SMEs with straightforward risk profiles.
- Agents:Tied distribution for mutual insurers serving regional cooperatives and agricultural enterprises, emphasizing relationship continuity over price competition.
Broker placements command premium volume; online platforms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France concentrates liability insurance consumption in corporate headquarters clusters while underwriting capacity distributes across regional mutual networks. Premium generation tilts toward Île-de-France, yet policy issuance infrastructure reaches into peripheral agricultural and industrial zones.
Île-de-France
Paris and La Défense host CAC 40 headquarters driving professional liability and D&O premium volumes. CSRD disclosure mandates compel corporations to document environmental liability coverage adequacy in sustainability filings. The concentration of technology and professional services firms intensifies cyber exposure procurement cycles.
Auvergne-Rhône-Alpes
Mid-sized manufacturing cooperatives in Lyon and Grenoble corridors expand general liability purchases through mutual channels. ACPR solvency requirements shape product design for regional underwriters serving industrial clients. Engineering clusters around Saint-Étienne generate construction liability demand for infrastructure contractors.
Provence-Alpes-Côte d'Azur
Tourism operators and port logistics firms in Marseille and Nice purchase standardized general liability through direct digital platforms. EU Green Deal disclosure obligations extend to maritime environmental liability coverage. The region's agricultural cooperatives remain underpenetrated relative to metropolitan corporate accounts.
Occitanie
Agricultural cooperatives in Toulouse and Montpellier zones drive demand for parametric climate liability products. ANSM oversight of pharmaceutical distribution creates product liability extensions among regional healthcare suppliers. Mutual insurers like Macif extend coverage through cooperative membership structures.
Hauts-de-France
Industrial manufacturing in Lille and Dunkirk corridors generates employers' liability supplementation beyond statutory coverage. Construction firms bidding on cross-border infrastructure projects seek multi-year policy structures for rate certainty. The region's logistics hubs concentrate cargo liability exposure for freight operators.
France Liability Insurance Market Competitive Landscape
Top-tier vendors anchor metropolitan corporate accounts, while mutual networks and cooperative structures occupy the mid-market tier. The market presents a consolidated structure at the premium end with fragmentation among regional mutuals serving specialized segments. Three archetypes dominate: integrated commercial lines insurers, mutualist cooperatives, and bancassurance distributors. Competitive moves center on multi-line programme consolidation and digital platform deployment for SME acquisition.
Among integrated commercial lines specialists, AXA France and Allianz France occupy positions exemplifying the premium-tier archetype through dedicated underwriting infrastructure. Macif represents the mutualist cooperative model, extending coverage through membership-based structures to mid-sized enterprises and agricultural cooperatives. These three anchors illustrate how geographic concentration in Île-de-France combines with regional mutual penetration to shape competitive dynamics across coverage segments and client scales.
| Leading Market Players |
|---|
| Allianz France |
| Macif |
| AXA France |
| CNP Assurances |
| Crédit Agricole Assurances |
| Covéa |
| Crédit Mutuel Assurances |
| Aéma Groupe |
| Groupama |
| Others |
Pricing and Supply Chain Analysis
Mutualist cooperative ownership structures across Auvergne-Rhône-Alpes and Occitanie constrain pricing discipline, as member-owned insurers prioritize coverage accessibility over margin extraction while competing against shareholder-backed commercial lines specialists in Île-de-France.
Pricing Analysis
Margin tightening in SME general liability traces to direct digital platform proliferation, compressing acquisition costs and policy servicing overhead. Three-tier pricing structure across premium, standard, and economy levels separates CAC 40 multi-line programmes from mid-market packaged coverage and bare-bones online contracts. Price differentiation hinges on retroactive date continuity and claims-handling service tiers. SMEs in Normandy and Brittany exhibit highest price sensitivity; large corporations in La Défense prioritize coverage adequacy over premium minimization.
Supply Chain Analysis
Reverse-logistics flows for policy documentation and claims evidence are minimal in liability insurance, though digital claims triage systems at AXA France and Allianz France compress settlement cycles from weeks to days. Capital provision concentrates in France, Germany, and Switzerland through reinsurance treaties and captive participation structures. Raw material dependencies include actuarial talent pools, regulatory compliance infrastructure, and climate risk modeling capabilities. Single-source vulnerability sits with Paris-based actuarial consultancies for climate risk quantification. Distribution runs through broker channels for complex corporate accounts, direct salesforces for mid-market capture, and online platforms for SME standardization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into climate risk modeling capabilities is accelerating as ACPR stress-testing mandates force insurers to build in-house actuarial capacity rather than outsource to concentrated Paris consultancies.
For Market Incumbents: Acquire specialized climate risk modeling teams to reduce dependency on external actuarial consultancies. Consolidate multi-line programme offerings into integrated cyber, D&O, and environmental liability packages to defend against broker disintermediation. Embed real-time CSRD compliance dashboards into client portals to counter mutualist competitors' relationship-based retention. For New Entrants and Emerging Players: AI-powered claims triage platforms offer entry wedge against legacy manual adjustment workflows. Target parametric climate liability coverage for Occitanie agricultural cooperatives, a segment underpenetrated by incumbent mutual networks. Pursue direct digital distribution partnerships with regional banking cooperatives to bypass established broker relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional mutual insurers with outdated policy administration platforms in Hauts-de-France and Provence-Alpes-Côte d'Azur. Long-term viability rests on conversion cost of legacy system modernization against digital-native competitor threat. Monitor ACPR climate stress-testing framework implementation timeline as capital charge recalibration inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Climate Risk Modeling Acquisition | Reduces dependency on concentrated Paris actuarial consultancies as ACPR mandates tighten. |
| CSRD Compliance Dashboard Integration | Enables real-time coverage adequacy documentation for auditor scrutiny under EU disclosure rules. |
| Parametric Climate Product Development | Creates white-space coverage for drought and flood exposure in Occitanie agricultural cooperatives. |
| Direct Digital Platform Expansion | Captures SME general liability volume in Normandy and Brittany with streamlined quotation workflows. |
| Multi-Year Policy Structure Offering | Locks pricing for Grand Paris Express contractors seeking cost predictability across decade-long horizons. |
Research Methodology
Multi-period observation of premium volume trajectories, policy duration trends, and distribution channel shifts anchored the trend analysis, supplemented by interviews with underwriting directors at integrated commercial lines insurers, mutual cooperative executives, broker placement specialists, ACPR regulatory affairs officers, and corporate risk managers at CAC 40 constituents. Secondary validation drew from ACPR solvency filings, EU CSRD implementation guidance, ANSM enforcement action records, and French insurance federation statistical bulletins. Bottom-up policy issuance data triangulated against top-down premium pool estimates.
Input-output matrices modeled demand drivers across coverage type, client scale, policy duration, and distribution channel dimensions throughout the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market trajectory. Industry-specific forecast inputs included CSRD compliance deadline phasing, ACPR climate stress-testing implementation schedule, and cyber litigation frequency trends in Paris commercial courts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated ACPR capital charge recalibration or abrupt CSRD enforcement tightening. Practitioners should monitor ACPR climate stress-testing framework publication and CSRD audit finding severity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Auto Compulsory Insurance Market
Insurance
United Kingdom Car Insurance Market
Insurance
Asia-Pacific AI in Insurance Market
Insurance
Horse Insurance Market
Insurance
AI in Insurance Market
Insurance
Saudi Arabia Health Insurance Market
Insurance
Small Business Insurance Market
Insurance
Asia-Pacific Usage-Based Insurance Market
Insurance
Usage-Based Insurance for Automotive Market
Insurance
North America Liability Insurance Market
Insurance
Asia-Pacific Surety Market
Insurance
India Dental Insurance Market
Insurance
Social Media Analytics-Based Insurance Market
Insurance
Europe Car Insurance Market
Insurance
Art Insurance Market
Insurance
Asia-Pacific Extended Warranty Market